
 Nitro-Infused Cola Market | 2026-2036
Nitro-Infused Cola Market Size, Share, and Industry Trends Forecast 2026-2036
Nitro-Infused Cola Market Analytics
Beverage-grade nitrogen supply infrastructure in the United States is hardening as regional gas distributors expand production capabilities to serve the growing nitro-infused drinks category. The Coca-Cola Company leverages its fountain equipment network to trial nitrogen-dispensing systems in select foodservice accounts. PepsiCo anchors its position through captive R&D on cold-brew nitrogenation protocols adapted for cola bases. Rise Brewing Co. competes by specializing in organic-certified nitro formulations that command premium placement in natural grocery channels.
Nitro-infused cola denotes a carbonated soft drink wherein food-grade nitrogen gas replaces or supplements traditional carbon dioxide, producing smaller bubbles, a denser foam head, and a smoother mouthfeel at pressures typically between 30 and 40 psi. Manufacturers force-nitrogenate the liquid through in-line injection or tank sparging prior to canning with widget technology or draft dispensing. The canned format dominates current volume due to widget-enabled home consumption, while draft systems capture the highest per-unit margins through on-premise accounts. Online sales channels represent the fastest-growing vector as direct-to-consumer subscription models reduce retailer slotting fee burdens for emerging brands.
The FDA exercises jurisdiction over nitrogen labeling and GRAS status for gas additives in beverages, while state-level alcohol beverage control agencies in jurisdictions like California and Texas regulate cross-contamination protocols when nitro equipment serves both soft drinks and alcoholic products. The EPA monitors wastewater discharge from nitrogen generation facilities that supply the foodservice sector. Stakeholders must track evolving state-by-state equipment sanitation mandates and anticipate whether FDA will mandate explicit nitrogen content disclosure on nutrition panels.
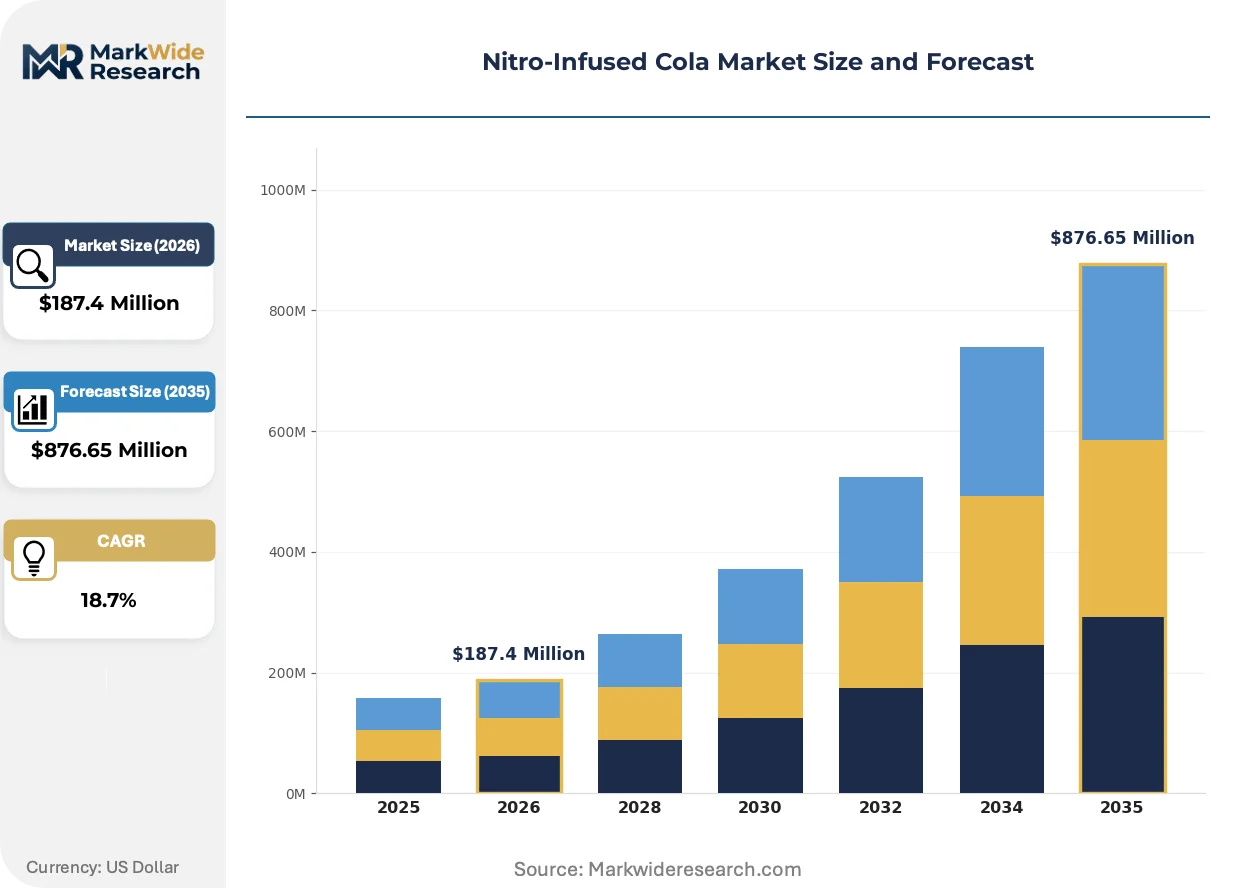
Market Dynamics
Widget-enabled canning technology is compressing capital barriers for nitro-infused cola entrants, allowing regional craft producers to replicate the nitrogenation protocols historically controlled by fountain equipment networks.
Growth Catalysts
- California craft beverage incubators:Los Angeles and San Francisco clusters accelerate formulation talent density and cross-pollination with cold-brew nitrogenation expertise.
- FDA GRAS pathway for food-grade nitrogen:Streamlined additive clearance reduces regulatory uncertainty for new market entrants versus novel ingredient categories.
- Subscription commerce infrastructure:Direct-to-consumer platforms bypass slotting fee structures that disadvantage emerging brands in conventional retail.
Market Restraints
- Beverage-grade nitrogen supply concentration:Regional gas distributor consolidation in Texas and California creates input vulnerability for producers outside major metro corridors.
- Widget patent thickets:Proprietary ball-and-chamber designs controlled by packaging equipment licensors limit formulation flexibility for independent canners.
- Cross-contamination protocols:State alcohol beverage control agencies in California and Texas impose equipment sanitation mandates that raise compliance costs for multi-beverage producers.
Strategic Opportunities
- Texas metropolitan expansion:Austin and Dallas incubator density remains underpenetrated relative to California, offering first-mover positioning for regional nitrogenation specialists.
- Natural grocery channel premium placement:Organic-certified formulations command shelf space differentiation in chains prioritizing clean-label beverage portfolios.
- EPA wastewater discharge incentives:Nitrogen generation facility upgrades eligible for environmental compliance credits reduce operational cost structures for captive gas production.
Industry Challenges
- Nitrogenation technician scarcity:Specialized expertise in pressure-system calibration and in-line injection timing exceeds current vocational training pipeline output.
- Multi-jurisdiction equipment certification:State-by-state sanitation mandates fragment compliance timelines for draft system deployments across California and Texas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitro-Infused Cola Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned, Bottled, Draft, Fountain Sales Channel: Online, Supermarkets, Convenience Stores, Wholesale Flavor Profile: Vanilla, Chocolate, Original, Citrus Consumer Demographic: Young Adults, Health Conscious, Athletes, Casual Drinkers |
| Companies Covered | Rise Brewing Co., Nitro Beverage Co., The Coca-Cola Company, Lucky Jack, Cruise Beverages, PepsiCo, Left Hand Brewing Co., Califia Farms, Monster Energy Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitro-Infused Cola Market Evolving Landscape
Packaging technology and regulatory disclosure requirements are reshaping competitive positioning in nitro-infused cola, while procurement patterns in foodservice channels compress traditional distribution hierarchies.
Widget-enabled nitrogen release systems are decentralizing production geography by eliminating dependency on draft-dispensing infrastructure. Smaller canning operations in Texas and California adopt portable nitrogen injection skids at accelerating rates. This technology diffusion is decentralizing market entry away from fountain-equipment incumbents toward regional craft producers.
FDA labeling scrutiny over nitrogen content disclosure is intensifying reformulation investments by domestic producers. Draft guidance on explicit gas additive notation threatens competitive opacity for brands marketing "smoothness" without ingredient transparency. California-based natural grocery channels are responding fastest, pressuring suppliers for pre-emptive panel compliance.
Foodservice procurement is consolidating around equipment-lease bundling that ties nitrogen-dispensing systems to exclusive beverage supply agreements. Independent restaurants in Austin and Dallas face compressed vendor choice as fountain network operators consolidate account control. This channel capture is most visible in Texas metropolitan corridors where equipment subsidy programs accelerate lock-in dynamics.
Nitro-Infused Cola Market Segmentation
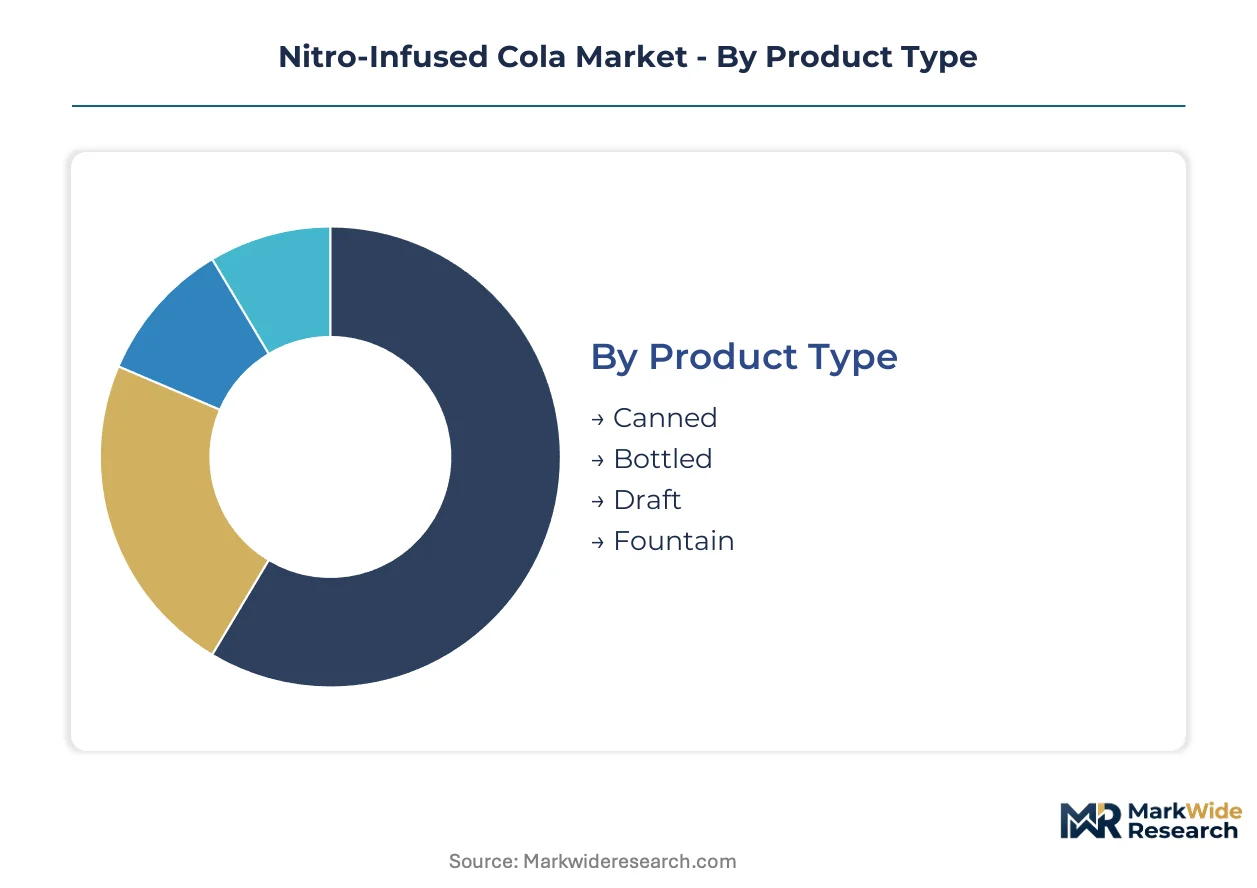
Segmentation in nitro-infused cola reveals how widget technology, channel access, and formulation certification create divergent margin structures. Each dimension carries distinct FDA labeling obligations and equipment compliance burdens that reshape competitive entry costs.
Product Type:
FDA GRAS clearance for food-grade nitrogen applies uniformly, yet equipment certification requirements fragment across packaging formats. Widget-enabled formats face distinct EPA wastewater scrutiny at generation facilities.
- Canned:Widget-integrated aluminum containers deploy nitrogen-release chambers activated upon opening, producing the dense foam head consumers associate with draft quality. Demand concentrates in California natural grocery channels where subscription models bypass slotting fees; organic-certified variants command premium placement against conventional formulations.
- Draft:On-premise dispensing through pressurized stainless systems captures the highest per-unit margins in Austin and Dallas foodservice accounts. Equipment-lease bundling by fountain network operators compresses vendor choice for independent restaurants.
- Bottled:PET and glass formats with nitrogen barrier layers remain secondary due to headspace limitations and oxidation sensitivity during shelf storage.
- Fountain:Coca-Cola's equipment network trials nitrogen-dispensing protocols in select accounts, leveraging existing infrastructure for rapid market testing.
Leading the category by volume: Canned. Growing fastest: Draft.
Sales Channel:
Channel selection determines working capital intensity and regulatory touchpoint density. Direct-to-consumer models minimize FDA nutrition panel exposure while wholesale contracts trigger batch-level documentation requirements.
- Online:Subscription commerce infrastructure enables emerging brands to circumvent retailer slotting fees that disadvantage regional craft producers. California-based incubators leverage DTC platforms for rapid formulation iteration before retail expansion.
- Convenience Stores:United States chains are expanding shelf space for nitrogenated soft drinks as younger consumers seek differentiated carbonation experiences. Texas metropolitan corridors show accelerating placement velocity.
- Supermarkets:Natural grocery channels in Los Angeles and San Francisco pressure suppliers for pre-emptive nitrogen content disclosure compliance ahead of FDA draft guidance finalization.
- Wholesale:Foodservice procurement consolidation around equipment-lease bundling ties nitrogen-dispensing systems to exclusive supply agreements, particularly visible in Austin and Dallas.
Channel commanding highest margins: Draft foodservice. Expanding most quickly: Online subscription.
Flavor Profile:
Flavor formulation intersects with nitrogen solubility chemistry, as certain compounds alter bubble nucleation patterns and foam stability. Clean-label positioning drives certification requirements for natural flavor additives.
- Original:Unflavored cola bases adapted from cold-brew nitrogenation protocols dominate current production volume. PepsiCo's captive R&D focuses here for scale economies.
- Vanilla:Cream-flavored variants show strongest velocity in natural grocery channels where organic-certified positioning commands shelf differentiation.
- Chocolate:Cocoa-derived formulations face additional FDA scrutiny for allergen cross-contamination in shared nitrogenation equipment.
- Citrus:Acidic flavor profiles require reformulation to maintain nitrogen solubility at standard dispensing pressures between 30 and 40 psi.
Highest volume position: Original. Steepest expansion trajectory: Vanilla.
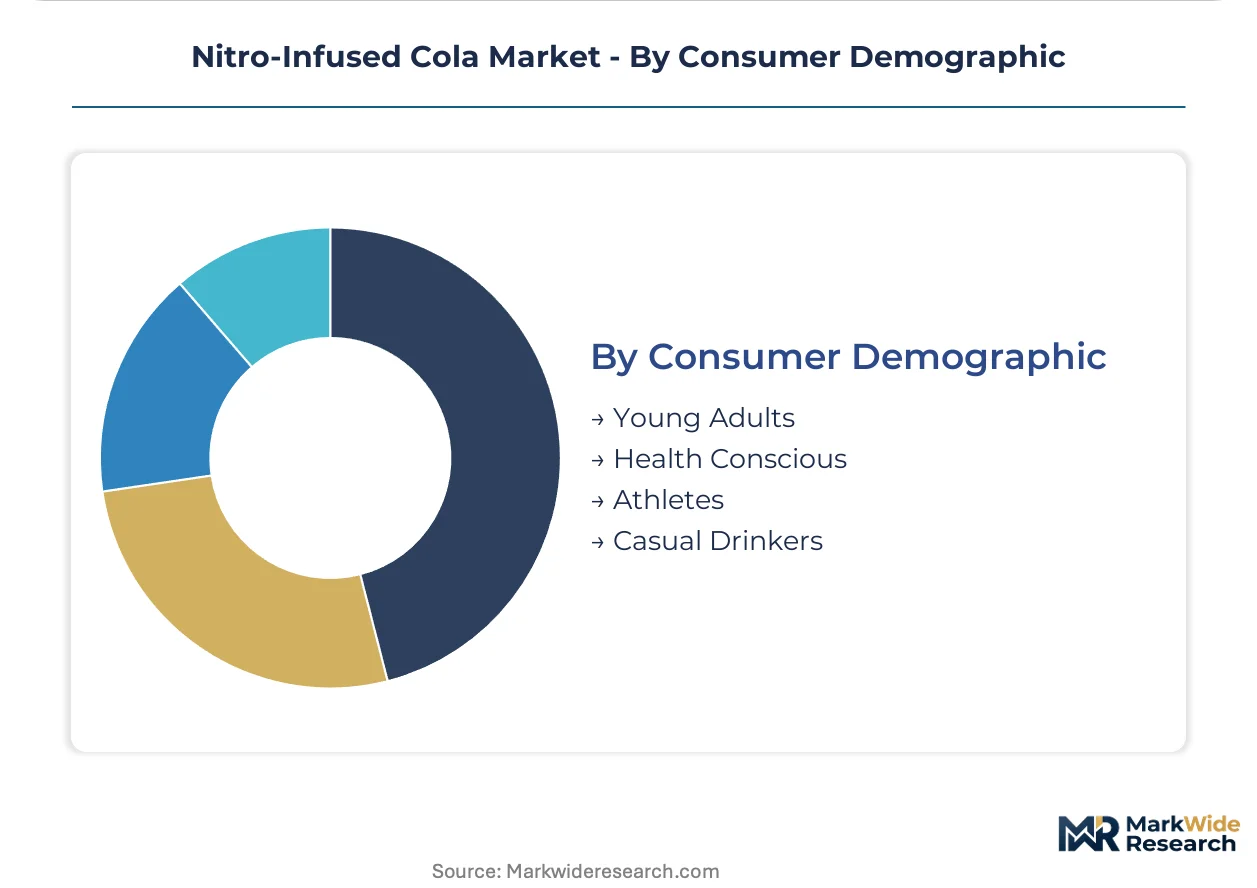
Consumer Demographic:
Demographic targeting shapes both formulation strategy and channel prioritization. Health-conscious segments drive organic certification investment, while athlete positioning requires sports-nutrition labeling compliance.
- Young Adults:Consumers aged 21-34 in California and Texas metropolitan clusters demonstrate highest trial rates for novel carbonation formats. Los Angeles and San Francisco incubator density accelerates trend adoption.
- Health Conscious:Organic-certified demand concentrates in natural grocery channels where Rise Brewing Co. competes through premium placement. Clean-label requirements pressure conventional formulation suppliers.
- Athletes:Sports-positioned variants require navigation of FDA structure-function claim boundaries for nitrogen's purported recovery benefits.
- Casual Drinkers:Mainstream convenience store purchasers in Texas show price sensitivity that favors widget-enabled cans over draft premium pricing.
Largest addressable base: Young Adults. Gaining share fastest: Health Conscious.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food-grade nitrogen generation capacity clusters near metropolitan beverage production corridors, with industrial gas infrastructure expansion tracking nitro-infused cola formulation density across key state markets.
California
Los Angeles and San Francisco incubator clusters accelerate formulation talent density and cross-pollination with cold-brew nitrogenation expertise. The state's Department of Public Health enforces equipment sanitation mandates for draft systems serving both soft drinks and alcoholic beverages. Natural grocery channels in Los Angeles pressure suppliers for pre-emptive nitrogen content disclosure compliance ahead of federal guidance finalization.
Texas
Austin and Dallas metropolitan corridors show accelerating convenience store placement velocity as younger consumers seek differentiated carbonation experiences. The Texas Alcoholic Beverage Commission regulates cross-contamination protocols when nitro equipment serves multiple beverage categories. Regional gas distributor consolidation creates input vulnerability for producers outside Dallas-Fort Worth and Austin metro corridors.
New York
Metropolitan New York's foodservice procurement consolidation around equipment-lease bundling compresses vendor choice for independent restaurants. The state's Department of Agriculture and Markets oversees food-grade gas additive labeling requirements for retail distribution. Brooklyn-based craft beverage startups leverage subscription commerce infrastructure to circumvent traditional retailer slotting fees.
Illinois
Chicago's fountain equipment network trials accelerate nitrogen-dispensing protocol testing in select foodservice accounts. The Illinois Environmental Protection Agency monitors wastewater discharge from nitrogen generation facilities supplying the foodservice sector. Regional craft producers adopt portable nitrogen injection skids to decentralize production geography away from draft-dispensing infrastructure dependency.
Florida
Miami-Dade and Tampa Bay metropolitan areas demonstrate rising trial rates for novel carbonation formats among young adult demographics. The Florida Department of Business and Professional Regulation coordinates with FDA on GRAS status enforcement for food-grade nitrogen additives. Orlando's tourism-dependent foodservice sector attracts equipment subsidy programs that accelerate vendor lock-in dynamics for fountain network operators.
Nitro-Infused Cola Market Competitive Landscape
Global majors compete with regional champions across equipment networks and formulation specialization, creating a tiered structure where fountain infrastructure incumbents face pressure from widget-enabled craft entrants. Market concentration splits between captive R&D divisions of diversified beverage conglomerates and independent nitrogenation specialists. Three archetypes dominate: equipment-leasing fountain operators, organic-certified craft formulators, and diversified energy drink portfolio owners. Competitive moves center on subscription commerce platform development and natural grocery channel premium placement capture.
Within the diversified beverage conglomerate tier, The Coca-Cola Company and PepsiCo occupy positions anchored by fountain equipment networks and captive R&D protocols. Among craft nitrogenation specialists, Rise Brewing Co. exemplifies the organic-certified formulation archetype targeting natural grocery differentiation. These named entities represent strategic positioning vectors rather than exhaustive market coverage, with each anchoring distinct competitive approaches to channel access and consumer segmentation.
| Leading Market Players |
|---|
| Rise Brewing Co. |
| Nitro Beverage Co. |
| The Coca-Cola Company |
| Lucky Jack |
| Cruise Beverages |
| PepsiCo |
| Left Hand Brewing Co. |
| Califia Farms |
| Monster Energy Company |
| Others |
Value Network & Pricing Analysis
Convenience store chain procurement consolidation across Texas and California is forcing nitrogen gas distributors to expand regional production capacity, compressing input costs for widget-enabled canners while draft system operators absorb equipment-lease premium pricing. This buyer-side concentration is reshaping margin structures across packaging formats.
Pricing Analysis
Equipment-lease bundling by fountain network operators in Austin and Dallas foodservice accounts packages nitrogen-dispensing systems with exclusive beverage supply agreements, obscuring true per-unit costs. Three-tier pricing structure across premium organic-certified, standard conventional, and economy private-label levels differentiates by certification grade and after-sales service inclusion. Pricing pressure stems from subscription commerce models that bypass retailer slotting fees, forcing wholesale channel repricing. Casual drinkers in Texas metropolitan corridors show highest price sensitivity, while health-conscious segments in California natural grocery channels accept premium positioning.
Supply Chain Analysis
Dual-sourcing requirements for food-grade nitrogen generation equipment mandate multi-supplier qualification by California and Texas beverage producers, reducing single-source vulnerability. Supply concentrates in United States regional gas distributor networks, with secondary sourcing from Canadian industrial gas producers and Mexican border-state generation facilities. Raw material dependencies span beverage-grade nitrogen, widget-integrated aluminum can substrates, and stainless steel pressure-system components. Tariff exposure on imported packaging equipment creates supply chain risk for independent canners. Distribution runs through direct-to-consumer subscription platforms, convenience store chains, and foodservice equipment-lease networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Widget patent thickets and equipment-lease bundling are accelerating consolidation, forcing independent nitrogenation specialists toward acquisition or exit as capital barriers rise.
For Market Incumbents: Acquire portable nitrogen injection skid technology to decentralize production geography away from fountain-equipment dependency. PepsiCo's captive R&D on cold-brew nitrogenation protocols demonstrates how backward integration into formulation expertise defends against craft entrant displacement. Lock in exclusive equipment-lease agreements with Austin and Dallas foodservice accounts before regional gas distributor consolidation completes. For New Entrants and Emerging Players: Independent restaurants in Texas metropolitan corridors facing compressed vendor choice from equipment-lease bundling represent the most penetrable buyer archetype. Target these accounts with unbundled nitrogen-dispensing system sales that break fountain network lock-in. Natural grocery channel premium placement in California offers white-space positioning for organic-certified formulations without slotting fee burdens. For Investors and Strategic Acquirers: Re-rating potential sits with organic-certified craft nitrogenation specialists given FDA labeling scrutiny over nitrogen content disclosure forcing pre-emptive compliance investments. Long-term viability over a multi-year window favors targets with captive gas production capabilities and EPA wastewater discharge credit eligibility. Monitor FDA draft guidance finalization on explicit gas additive notation as the signal indicating margin compression for non-compliant formulation suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Widget Technology Licensing | Patent access enables regional craft producers to replicate nitrogenation protocols historically controlled by fountain networks. |
| Captive Nitrogen Generation | EPA wastewater discharge credits reduce operational cost structures for producers with in-house gas production. |
| Direct-to-Consumer Platform Launch | Subscription models bypass retailer slotting fees that disadvantage emerging brands in California natural grocery channels. |
| Organic Certification Investment | Clean-label positioning commands shelf differentiation in Los Angeles and San Francisco incubator clusters. |
| Equipment-Lease Bundling Expansion | Fountain network operators consolidate account control in Austin and Dallas foodservice procurement. |
Research Methodology
Multi-period observation of FDA labeling guidance evolution, nitrogen generation facility expansion patterns, and widget patent filing trajectories anchored the trend analysis, supplemented by interviews with beverage formulation chemists, draft system equipment manufacturers, convenience store category buyers, and regional gas distributor operations managers. Secondary validation drew from FDA GRAS notices, EPA wastewater discharge permits, state alcohol beverage control agency sanitation mandates, and trade customs data on nitrogen generation equipment imports. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Input-output matrices mapped nitrogen gas supply volumes to finished beverage production across canned, draft, bottled, and fountain formats, with value flows tracked through subscription commerce, convenience retail, supermarket, and wholesale channels. Segmentation dimensions modeled include packaging format, sales channel, flavor profile, and consumer demographic. CAGRs were derived from regression analysis of historical volume trajectories against projected nitrogenation technology adoption curves and regulatory compliance cost impacts.
Revisions become necessary when FDA finalizes explicit nitrogen content disclosure requirements, EPA modifies wastewater discharge standards for generation facilities, or state alcohol beverage control agencies harmonize equipment sanitation mandates across California and Texas. Deviation in widget patent enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Powdered Beverages Market
Beverages
Morocco Bottled Water Market
Beverages
Hot Chocolate Market
Beverages
Water Bottle Market
Beverages
Blenders Market
Beverages
Gluten Free Beverages Market
Beverages
Bottled Beverages Market
Beverages
Sarsaparilla Market
Beverages
Ready to Drink Shakes Market
Beverages
GCC Coconut Water Market
Beverages
Ready-To-Drink (RTD) Beverages Market
Beverages
Pineapple Juice Market
Beverages
Extra Virgin Olive Oil Market
Beverages
Beverage Cooler Market
Beverages
Peanut Oil Market
Beverages
Collagen-Infused Water Market