
 Bangladesh Energy Drinks Market | 2026-2036
Bangladesh Energy Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Bangladesh Energy Drinks Market Outlook
The gap between premium imported formulations and locally manufactured commodity energy drinks is realigning shelf dynamics across Bangladeshi retail. Akij Food & Beverage Ltd leverages its domestic manufacturing footprint to control pricing in tier-two cities, while Red Bull GMBH anchors the premium segment through specialized channel partnerships in Dhaka's upscale convenience networks. PRAN-RFL Group Ltd competes aggressively on volume, extending distribution into rural haats and small-format kiranas that multinational brands rarely penetrate.
Energy drinks are non-alcoholic beverages containing caffeine, taurine, B-vitamins, and carbohydrates, formulated to reduce fatigue and enhance mental alertness through stimulant action on the central nervous system. Carbonated variants dominate current volume due to established consumer preference for crisp mouthfeel in tropical climates, while sugar-free formulations represent the fastest-expanding margin pool as health consciousness rises among urban professionals. Young adults and working professionals constitute the core demand base, though athlete-targeted SKUs remain underdeveloped relative to regional peers.
The Bangladesh Standards and Testing Institution mandates caffeine content disclosure and permissible limits, while the Bangladesh Food Safety Authority enforces additive compliance that shapes reformulation priorities for both domestic blenders and importers. The Drug Administration Directorate monitors stimulant thresholds, creating compliance complexity for brands sourcing concentrate from multiple jurisdictions. Stakeholders must track evolving enforcement intensity around sugar taxation proposals and the potential harmonization of local standards with ASEAN food safety protocols.
Market Dynamics
The Bangladesh energy drinks market is compressing around regulatory scrutiny of stimulant content and the geographic concentration of demand in Dhaka and Chittagong's industrial corridors. Manufacturers face simultaneous pressure to reformulate for compliance while extending distribution into secondary urban centers where per-capita consumption remains nascent.
Growth Catalysts
- Extended Work Hours:Garment factory shifts and IT service operations in Dhaka's export processing zones sustain demand for alertness-enhancing beverages among wage workers and salaried professionals alike.
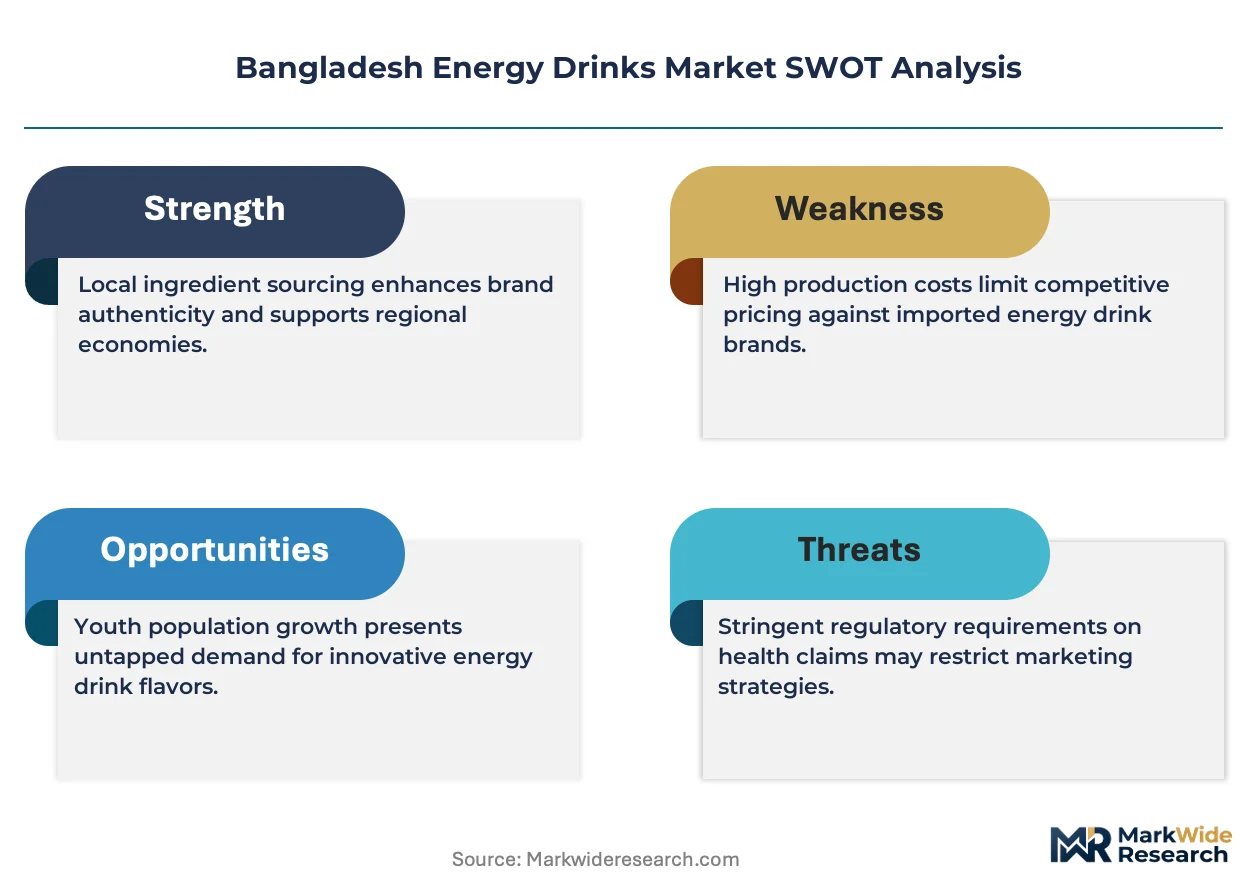
- Bangladesh Food Safety Authority Enforcement:Tighter additive compliance standards are accelerating product standardization, reducing informal sector competition and creating shelf space for compliant branded formulations.
- Carbonated Preference:Tropical climate conditions reinforce consumer attachment to crisp, chilled carbonated variants over still alternatives, locking in established production infrastructure and distribution economics.
Market Restraints
- Caffeine Concentrate Import Dependency:Domestic blenders rely on imported active ingredients, exposing margin structures to currency volatility and international shipping disruptions through Chittagong port.
- Sugar Tax Proposals:Pending fiscal measures targeting sweetened beverages threaten volume-driven business models, particularly for standard-tier products where price elasticity is highest.
- Functional Water Substitution:Electrolyte-enhanced still beverages and vitamin-fortified juices are capturing health-conscious consumers seeking hydration without stimulant load.
Strategic Opportunities
- Sylhet and Rajshahi Expansion:Tier-two urban centers with growing student populations and emerging service economies offer underexploited distribution territory beyond saturated Dhaka-Chittagong corridors.
- Sugar-Free Formulation:Health-conscious urban professionals represent an expanding margin pool for reduced-calorie SKUs, particularly in upscale convenience networks near corporate districts.
- Direct-to-Retailer Digital Platforms:B2B ordering applications are bypassing traditional distributor layers, enabling faster inventory turns and real-time demand sensing in fragmented kirana channels.
Industry Challenges
- Reformulation Timeline Compression:Bangladesh Standards and Testing Institution label disclosure mandates require rapid recipe adjustments and packaging redesigns, straining R&D bandwidth at smaller domestic blenders.
- Cold Chain Fragmentation:Inconsistent refrigeration infrastructure across rural haats and small-format retail limits shelf-life confidence for preservative-free premium variants targeting health-positioned segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bangladesh Energy Drinks Market |
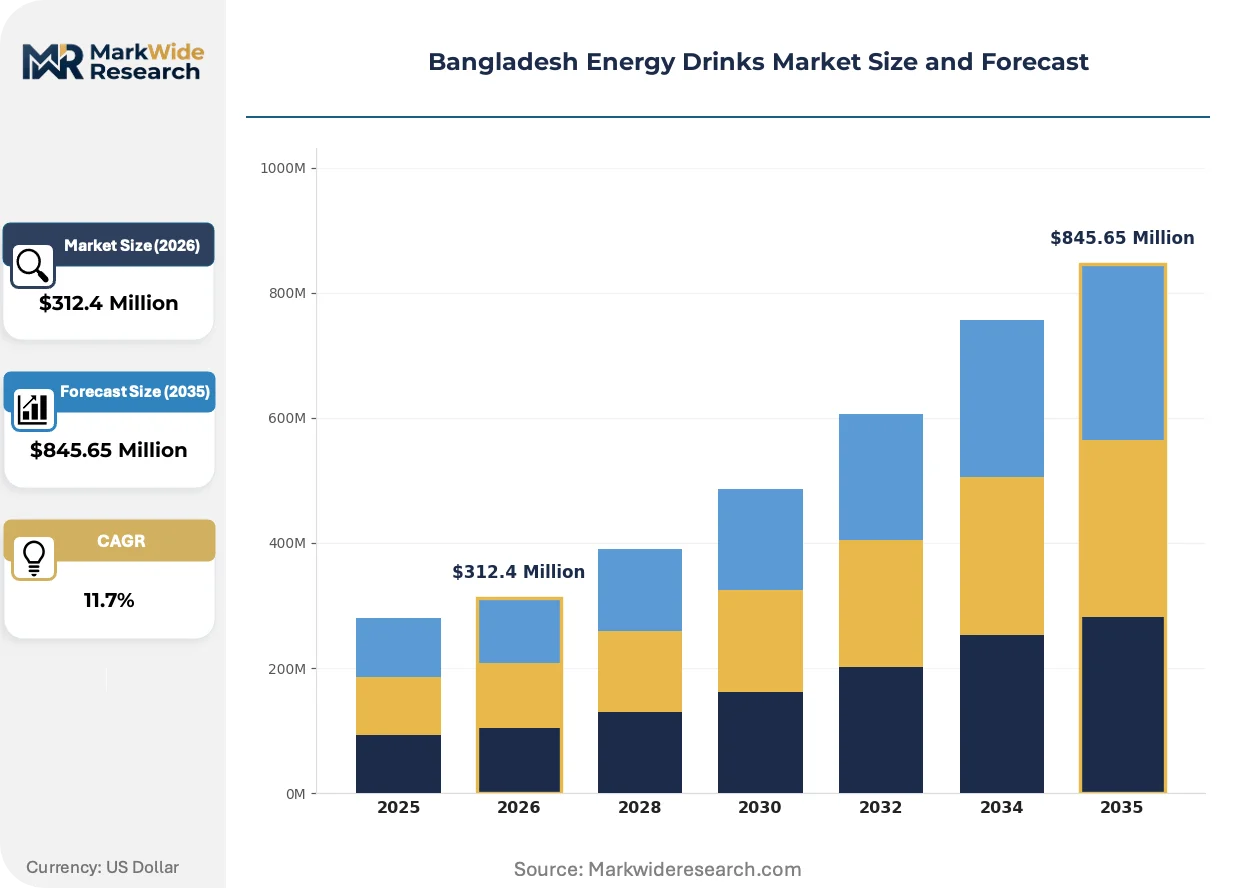
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-carbonated, Sugar-free, Herbal End User: Teens, Young Adults, Working Professionals, Athletes Distribution Channel: Supermarkets, Convenience Stores, Online, Vending Machines Packaging Type: Cans, Bottles, Tetra Packs, Pouches |
| Companies Covered | Akij Food & Beverage Ltd, Osotspa Co Ltd, PRAN-RFL Group Ltd, PepsiCo Bangladesh, Zisan Food & Beverage Ltd, Red Bull GMBH, Globe Soft Drinks & AST Beverage Ltd, Coca-Cola Bangladesh Beverages Ltd, Deshbandhu Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bangladesh Energy Drinks Market Strategic Shifts
Automation and regulatory digitization are reshaping how Bangladeshi energy drink manufacturers manage compliance and production workflows. Three converging developments are redefining competitive capability requirements across the value chain.
Aseptic filling technology with integrated quality sensing is automating contamination detection and fill-level precision in high-speed bottling lines. Domestic manufacturers in Gazipur and Narayanganj industrial zones are retrofitting existing carbonated beverage plants to accommodate energy drink SKUs with minimal capital outlay. This equipment convergence is compressing time-to-market for new formulations while reducing manual intervention points that previously generated batch inconsistencies.
The Bangladesh Food Safety Authority's phased implementation of digital product registration portals is accelerating compliance documentation requirements. Manufacturers must now submit real-time batch records and ingredient traceability data through centralized systems rather than paper-based filings. Small and mid-sized domestic blenders with limited IT infrastructure face disproportionate adaptation costs, creating structural advantage for organized players with dedicated regulatory affairs functions.
Convenience store operators in Dhaka's upscale neighborhoods are consolidating supplier relationships around fewer, larger beverage distributors capable of integrated category management. This buyer concentration is displacing fragmented multi-brand wholesaler networks that historically dominated urban replenishment. The shift is most visible in Gulshan and Banani commercial districts, where chain convenience formats now demand single-point accountability for planogram execution and promotional funding.
Bangladesh Energy Drinks Market Segmentation
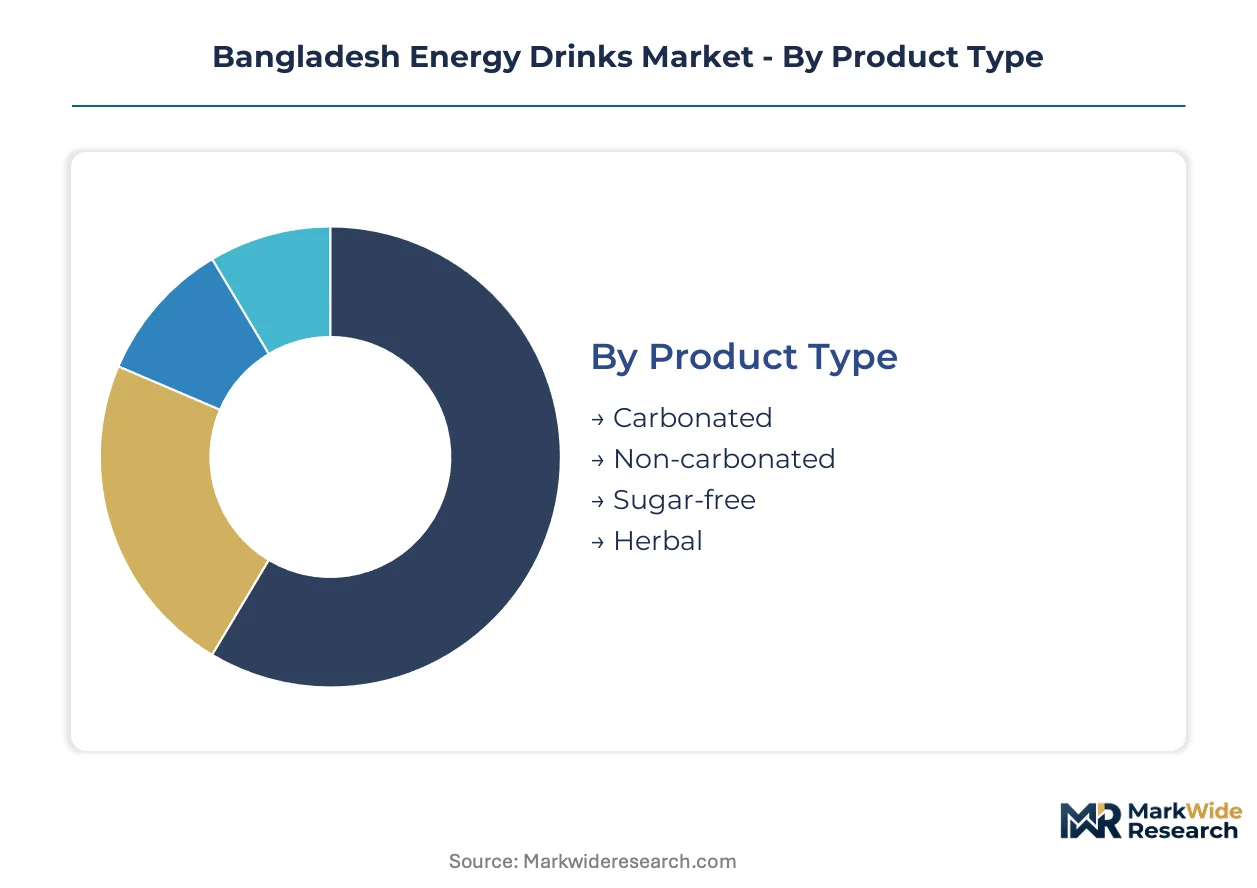
Segmentation in the Bangladesh energy drinks market reveals how regulatory pressure, climate preference, and channel fragmentation create distinct competitive arenas. Manufacturers must align formulation, packaging, and route-to-market strategies against specific consumption moments rather than pursuing undifferentiated mass penetration.
Product Type:
Carbonation technology and sweetener systems differentiate manufacturing investment and margin profiles across Bangladesh's energy drink portfolio.
- Carbonated:Pressurized CO2 infusion creates the crisp mouthfeel preferred in tropical heat, with established filling lines in Gazipur and Narayanganj industrial zones serving Dhaka garment corridors and Chittagong port logistics hubs. Demand concentrates near factory zones where chilled availability sustains shift-work consumption.
- Sugar-free:Artificial sweetener formulations using sucralose or stevia blends target health-conscious professionals in Gulshan and Banani corporate districts, commanding premium shelf positioning in upscale convenience networks where reduced-calorie claims drive basket margin.
- Non-carbonated:Still formulations with taurine-caffeine bases suit consumers avoiding bloating, finding niche placement in university canteens and long-distance transport terminals.
- Herbal:Botanical extracts including ginseng and ashwagandha appeal to traditional medicine-inclined segments in Sylhet and rural Rajshahi, though caffeine standardization by Bangladesh Standards and Testing Institution limits functional claim differentiation.
Mature deployment sits with Carbonated variants. Newer deployment is concentrated in Sugar-free formulations.
End User:
Consumption intensity and purchase autonomy vary sharply across demographic cohorts, dictating channel access and price-point tolerance.
- Working Professionals:Salaried employees in Dhaka's export processing zones and IT corridors sustain the highest per-capita consumption, purchasing single-serve cans during commute breaks and overtime shifts with limited price sensitivity for convenience.
- Young Adults:University students in Chittagong and Dhaka exhibit brand-switching behavior driven by promotional pricing, generating volume concentration near campus-adjacent kirana stores and chain convenience formats.
- Teens:Under-18 consumption faces Bangladesh Food Safety Authority scrutiny around caffeine limits, restricting explicit marketing and pushing informal acquisition through peer networks.
- Athletes:Fitness-oriented users remain underdeveloped relative to regional peers, with limited specialized SKUs targeting gym channels or sports nutrition positioning.
Volume leadership sits with Working Professionals. Steepest expansion trajectory is concentrated in Young Adults as student populations grow in tier-two urban centers.
Distribution Channel:
Channel economics determine cold chain requirements, working capital intensity, and promotional mechanics for energy drink suppliers.
- Convenience Stores:Small-format urban outlets in Dhaka's upscale neighborhoods and garment zone periphery dominate single-serve impulse purchases, with consolidated distributor relationships displacing fragmented wholesaler networks.
- Supermarkets:Organized retail in Chittagong and Dhaka offers multi-pack bundling and promotional display space, serving stock-up behavior among middle-income households.
- Online:E-commerce platforms and direct-to-retailer B2B applications are gaining traction for bulk procurement by small kirana operators, bypassing traditional distributor markups.
- Vending Machines:Automated dispensing remains nascent, limited by electricity reliability and coin-handling infrastructure in public spaces.
Transaction density sits with Convenience Stores. Digital channel development is concentrated in Online platforms serving fragmented rural retail.
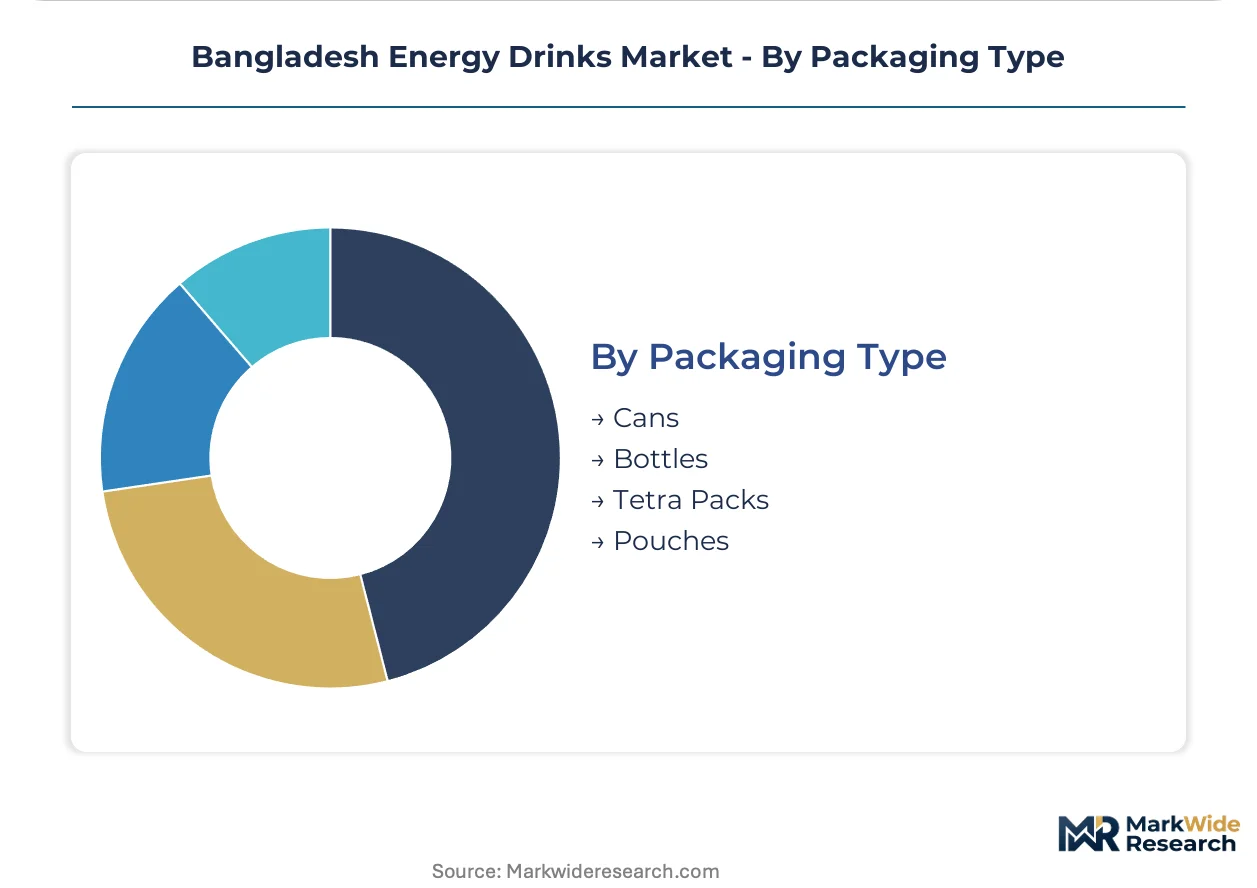
Packaging Type:
Material selection governs shelf stability, chilling performance, and logistics economics across Bangladesh's distribution network.
- Cans:Aluminum vessels deliver superior chilling retention and premium perception, dominating urban convenience and supermarket channels where cold-chain confidence supports higher price realization.
- Bottles:PET formats offer resealability for extended consumption, finding preference in long-haul transport and workplace desk consumption among professionals.
- Tetra Packs:Aseptic cartons reduce refrigeration dependency, enabling rural haat penetration where cold infrastructure is inconsistent.
- Pouches:Flexible sachets target extreme price-sensitive segments with single-use portions, though regulatory labeling requirements complicate small-format compliance.
Urban premium positioning sits with Cans. Cost-driven expansion is concentrated in Tetra Packs for secondary city and rural distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dhaka dominates Bangladesh's energy drink consumption through its garment export processing zones and IT service corridors, where extended shift work sustains stimulant beverage demand. The market's geographic concentration creates distinct competitive dynamics across the country's major urban centers.
Dhaka Division
Garment factory clusters in Gazipur and Narayanganj industrial zones drive volume consumption among wage workers operating 12-hour shifts. Bangladesh Standards and Testing Institution caffeine disclosure mandates force rapid label redesigns for products distributed through these corridors. Upscale neighborhoods including Gulshan and Banani concentrate premium-tier sales near corporate offices and chain convenience formats.
Chittagong Division
Port logistics operations and shipyard maintenance schedules create demand among dock workers and maritime contractors working irregular hours. Bangladesh Food Safety Authority enforcement intensifies around import documentation for caffeine concentrate entering through Chittagong port. The city's university corridors generate brand-switching volume among students sensitive to promotional pricing.
Sylhet Division
Emerging service sector employment and growing private university enrollments expand the addressable consumer base beyond traditional industrial demand. Local distributors face cold-chain limitations extending premium chilled products into rural haats. Tea garden worker communities present untapped potential for functional beverage positioning adapted to shift-work patterns.
Rajshahi Division
Agricultural processing and emerging textile investments diversify demand beyond pure manufacturing consumption. Sugar-free formulations gain traction among health-conscious professionals in the divisional city center. Distribution infrastructure gaps favor tetra-pack formats with reduced refrigeration dependency for rural penetration.
Khulna Division
Shrimp processing export zones and jute mill operations sustain industrial demand patterns similar to Dhaka's garment corridors. Limited organized retail presence channels volume through traditional kirana networks with minimal promotional support. B2B digital ordering platforms show early adoption among urban retailers seeking inventory efficiency.
Bangladesh Energy Drinks Market Competitive Environment
Capital-heavy domestic bottlers compete with asset-light brand licensors for shelf positioning across Bangladesh's fragmented retail network. The market structure tiers around manufacturing scale, with integrated beverage conglomerates controlling tier-two distribution while premium importers anchor upscale urban channels. Three archetypes dominate: domestic manufacturing specialists with backward integration into sweetener and packaging supply; multinational brand licensors relying on local bottling partnerships; and regional Southeast Asian exporters targeting price-sensitive volume segments. Competitive moves concentrate on distributor consolidation and sugar-free portfolio expansion ahead of anticipated fiscal measures.
Among domestic manufacturing conglomerates, Akij Food & Beverage Ltd and PRAN-RFL Group Ltd occupy positions defined by captive production infrastructure and rural distribution depth. Red Bull GMBH anchors the premium-imported archetype through specialized channel partnerships. These three represent the competitive spectrum from commodity volume through brand-premium positioning, with each exemplifying distinct responses to Bangladesh Standards and Testing Institution compliance pressures and cold-chain infrastructure constraints.
| Leading Market Players |
|---|
| Akij Food & Beverage Ltd |
| Osotspa Co Ltd |
| PRAN-RFL Group Ltd |
| PepsiCo Bangladesh |
| Zisan Food & Beverage Ltd |
| Red Bull GMBH |
| Globe Soft Drinks & AST Beverage Ltd |
| Coca-Cola Bangladesh Beverages Ltd |
| Deshbandhu Group |
| Others |
Value Chain & Pricing Dynamics
Backward integration into domestic sweetener and packaging supply anchors Akij Food & Beverage Ltd and PRAN-RFL Group Ltd with cost advantages that translate into pricing flexibility across tier-two urban centers. This captive production structure insulates organized players from currency-driven input volatility while compressing procurement cycles for caffeine concentrate imports through Chittagong port.
Pricing Analysis
Value-based pricing tied to alertness duration and shift-work productivity anchors the Bangladesh energy drinks market. Three-tier pricing structure across premium, standard, and economy levels separates Red Bull GMBH's import-dependent positioning from Akij's domestic manufacturing scale and PRAN-RFL's rural volume penetration. Cost compression in standard-tier products intensifies as sugar tax proposals advance through parliamentary committees. Young adults in university corridors exhibit highest price sensitivity, while garment zone working professionals prioritize convenience over per-unit cost.
Supply Chain Analysis
Single-source vulnerability sits with caffeine concentrate imports from India, Thailand, and Vietnam that feed domestic blending operations in Gazipur and Narayanganj industrial zones. Raw material dependencies extend to aluminum can sheet, high-fructose corn syrup, and aseptic carton laminate. Tariff exposure on ASEAN-sourced active ingredients compounds margin pressure during taka depreciation cycles. Distribution runs through consolidated beverage distributors serving chain convenience formats in Dhaka and Chittagong, with fragmented kirana networks in secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bangladesh energy drinks market functions as a supply-constrained environment where cold chain infrastructure gaps prop pricing power for shelf-stable formats. Tetra-pack capacity expansion remains the binding bottleneck limiting rural penetration.
For Market Incumbents: Anchor Dhaka-Chittagong corridor dominance through exclusive convenience store partnerships that lock out multinational challengers. Defend against functional water substitution by accelerating sugar-free SKU registration with Bangladesh Food Safety Authority ahead of fiscal tightening. Prioritize captive can manufacturing to reduce aluminum import dependency. For New Entrants and Emerging Players: Launch via B2B digital ordering platforms targeting kirana operators in Sylhet and Rajshahi where distributor consolidation has not yet occurred. White space concentrates in herbal-positioned variants for traditional medicine-inclined consumers in tea garden communities. Bypass established wholesaler networks through direct-to-retailer inventory management applications. For Investors and Strategic Acquirers: Exit pathways concentrate in domestic manufacturing specialists with regulatory compliance infrastructure and backward-integrated packaging supply. Long-term viability hinges on adaptation to Bangladesh Standards and Testing Institution digitization mandates. Monitor Bangladesh Food Safety Authority enforcement intensity around sugar taxation implementation as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sugar-Free Formulation Expansion | Captures health-conscious professionals in Gulshan corporate districts ahead of fiscal tightening. |
| Tetra-Pack Capacity Buildout | Enables rural haat penetration in Rajshahi where refrigeration infrastructure remains inconsistent. |
| Direct-to-Retailer Digital Platform | Bypasses fragmented wholesaler markups through B2B ordering applications serving kirana channels. |
| Regulatory Compliance Digitization | Aligns batch record submission with Bangladesh Food Safety Authority centralized portal requirements. |
| Backward Integration into Packaging | Reduces aluminum can sheet import exposure and compresses procurement cycles for domestic blenders. |
Study Parameters
Multi-period observation of caffeine concentrate import volumes, cold chain infrastructure deployment, and regulatory enforcement intensity anchored the trend analysis, supplemented by interviews with brand managers at domestic beverage conglomerates, category buyers at Dhaka chain convenience operators, supply planners managing Chittagong port logistics, and regulatory affairs leads navigating Bangladesh Food Safety Authority digitization. Secondary validation drew from Bangladesh Standards and Testing Institution disclosure filings, customs records tracking ASEAN ingredient imports, and retail audit data from Nielsen covering organized trade in major urban centers. Bottom-up channel sizing triangulated against top-down macroeconomic consumption elasticity estimates.
Segment-weighting across carbonation technology, end-user consumption intensity, distribution channel cold chain requirements, and packaging material economics structured the analytical framework throughout the projection horizon. CAGRs were derived from elasticity-adjusted per-capita consumption trajectories within each urban demographic cluster. Forecast inputs incorporated garment sector shift-hour patterns, student population growth in tier-two cities, and Bangladesh Food Safety Authority compliance cost pass-through assumptions.
The model assumes a particular technology adoption path for aseptic filling automation; alternative pathways for cold chain infrastructure buildout would alter the outlook for premium can-dependent SKUs. Forecasts reflect assumptions around regulatory enforcement continuity and import tariff stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Wellness Water Market
Beverages
Orange Juice Market
Beverages
Nitro-Infused Cola Market
Beverages
Blackstrap Molasses Market
Beverages
Breakfast Drink Market
Beverages
Global Fruit Juice Concentrate Market
Beverages
Hot Beverages Market
Beverages
North America Dairy Beverages Market
Beverages
Sports Drink Market
Beverages
Aloe Vera Juice Market
Beverages
Apple Juice Concentrate Market
Beverages
Nitro-Infused Beverages Market
Beverages
Still Drinks Market
Beverages
Global Squash Drinks Market
Beverages
Relaxation Beverages Market
Beverages
Global Soft Drinks Concentrate Market