
 Fermented Drinks Market | 2026-2036
Fermented Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Drinks Market Analysis
The capital-intensity gap between craft-scale fermenters and multinational brewers is collapsing as automated bioreactor systems democratize production. Anheuser-Busch InBev leverages its global distribution infrastructure to push hard kombucha into conventional retail. GT's Living Foods anchors the premium probiotic segment through raw, unpasteurized positioning. PepsiCo extends its beverage portfolio into functional fermented sodas via established convenience store networks.
Fermented drinks comprise beverages produced through controlled microbial metabolism of sugars, yielding alcohol, organic acids, carbon dioxide, or probiotic cultures in finished products with defined pH ranges and live culture counts. These products serve commercial purposes spanning refreshment, digestive health support, alcohol delivery, and functional nutrition in both on-premise and retail channels. Kombucha and kefir capture disproportionate margin pools as consumers prioritize gut-health claims over conventional refreshment. Mead and kvass occupy smaller volume positions but sustain pricing power through heritage positioning and regional authenticity narratives. Bottles and cans dominate packaging type dynamics, with draft systems expanding in foodservice as operators seek differentiated beverage programs.
FDA oversees probiotic structure-function claims and acidified food safety requirements, while EFSA evaluates health claim substantiation for European market access. USDA organic certification and EU organic regulation create parallel compliance tracks that influence ingredient sourcing and labeling strategies. Stakeholders must monitor evolving live-culture count thresholds and sugar-content disclosure mandates as regulators tighten functional beverage oversight.
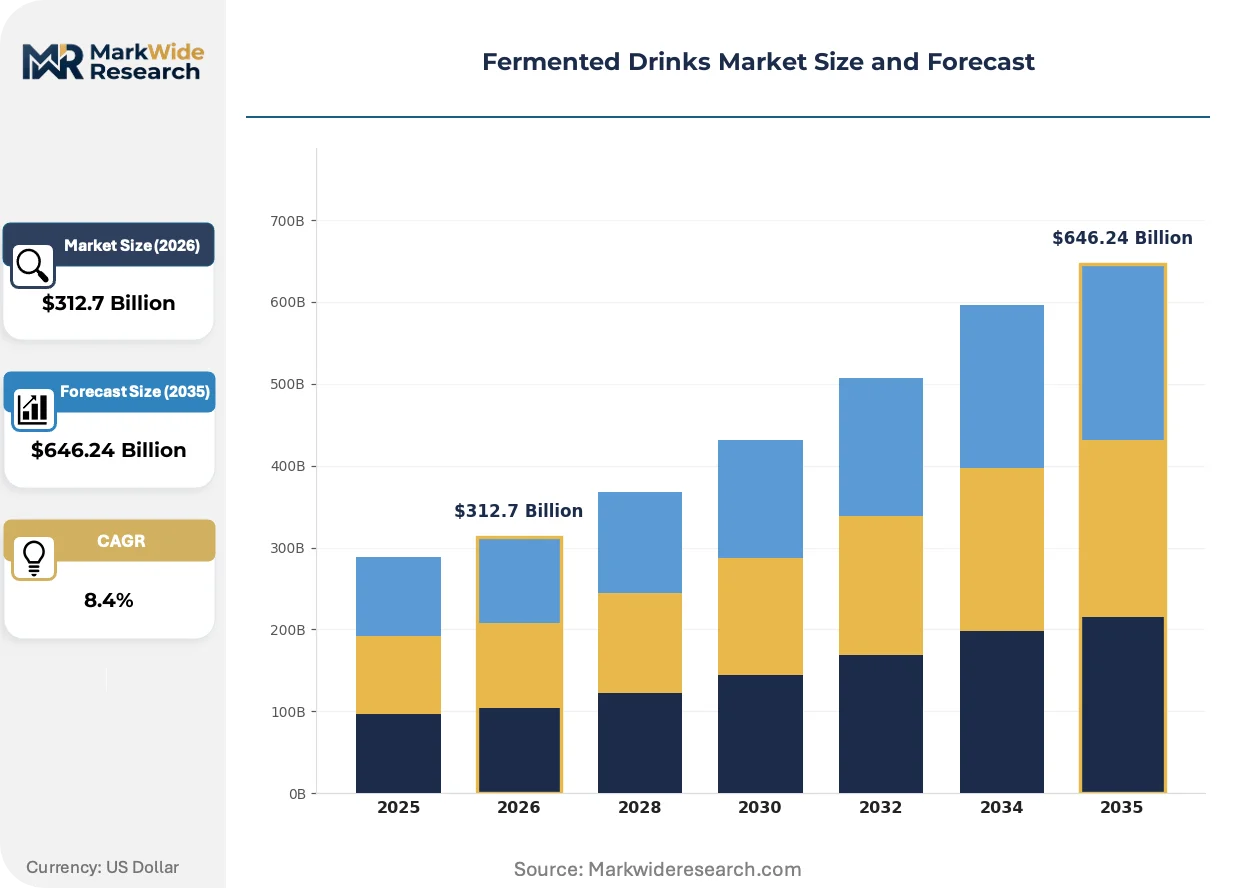
Market Dynamics
Automated bioreactor systems are collapsing the capital-intensity gap between craft-scale fermenters and multinational brewers, redistributing production capacity across tier-1 and tier-2 cities while compressing batch-to-market timelines from months to weeks.
Growth Catalysts
- Probiotic Labeling Standards:EFSA health claim substantiation requirements and FDA structure-function claim pathways create compliant formulation roadmaps that premium brands exploit for shelf differentiation.
- Portland-Denver-Brooklyn Corridor:Concentrated craft beverage infrastructure in these three US cities generates knowledge spillovers and supplier clustering that accelerates product iteration cycles.
- Hard Kombucha:Alcohol delivery through fermented substrates captures crossover demand from beer-avoiding millennials seeking sessionable alternatives with functional positioning.
Market Restraints
- Live-Culture Volatility:Unpasteurized products face spoilage rates exceeding conventional beverages, constraining distribution radius and cold-chain infrastructure investment.
- Sugar Disclosure Mandates:Pending FDA added-sugar line-item requirements threaten formulation secrecy and competitive positioning for heritage recipes.
- Glass Supply Concentration:Premium bottle sourcing clusters in select European and Mexican manufacturing hubs, exposing brands to freight cost spikes and capacity constraints.
Strategic Opportunities
- Convenience Store Networks:Functional fermented sodas penetrate C-store channels previously closed to alcohol-adjacent products, unlocking impulse purchase occasions.
- EU Organic Regulation:Parallel compliance tracks with USDA organic certification enable dual-market product architecture with minimal reformulation overhead.
- Draft Systems:Foodservice operators deploy keg-based fermented programs to differentiate beverage menus without bottle inventory complexity.
Industry Challenges
- Microbiology Talent Scarcity:Commercial-scale fermentation science expertise concentrates in legacy brewing regions, forcing brands to recruit from pharmaceutical bioprocessing or academic labs.
- Acidified Food Safety Compliance:FDA 21 CFR Part 114 requirements impose scheduled process validation costs that strain emerging brand cash flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Drinks Market |
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $646.24 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kombucha, Kefir, Kvass, Mead End User: Health Enthusiasts, Millennials, Seniors, Fitness Buffs Flavor Profile: Fruity, Spicy, Herbal, Earthy Packaging Type: Bottles, Cans, Draft, Tetra Packs |
| Companies Covered | The Boston Beer Company, PepsiCo, Anheuser-Busch InBev, KeVita, GT's Living Foods, Heineken, Danone, Health-Ade, Carlsberg Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Drinks Market Emerging Trajectories
Controlled microbial metabolism technologies are fragmenting production hierarchies while live-culture verification methods and channel-specific formulation strategies reshape competitive boundaries across refreshment and functional nutrition categories.
Precision fermentation platforms is bifurcating the ingredient supply base. Synthetic biology startups engineer tailored yeast strains for specific organic acid profiles. Large beverage conglomerates adopt these inputs to standardize batch consistency. The technology is bifurcating margin capture between biotech licensors and finished-goods manufacturers.
EFSA health claim substantiation protocols are tightening evidentiary thresholds for gut-health marketing. Brands must now fund human intervention studies to retain premium positioning. European kombucha and kefir exporters face reformulation or label revision to maintain market access.
Millennial procurement patterns favor subscription-based replenishment over conventional retail discovery. Direct-to-consumer channels capture recurring revenue while specialty retailers lose foot traffic. Portland and Brooklyn demonstrate the highest subscription penetration, with Denver operators now piloting similar models.
Fermented Drinks Market Segmentation
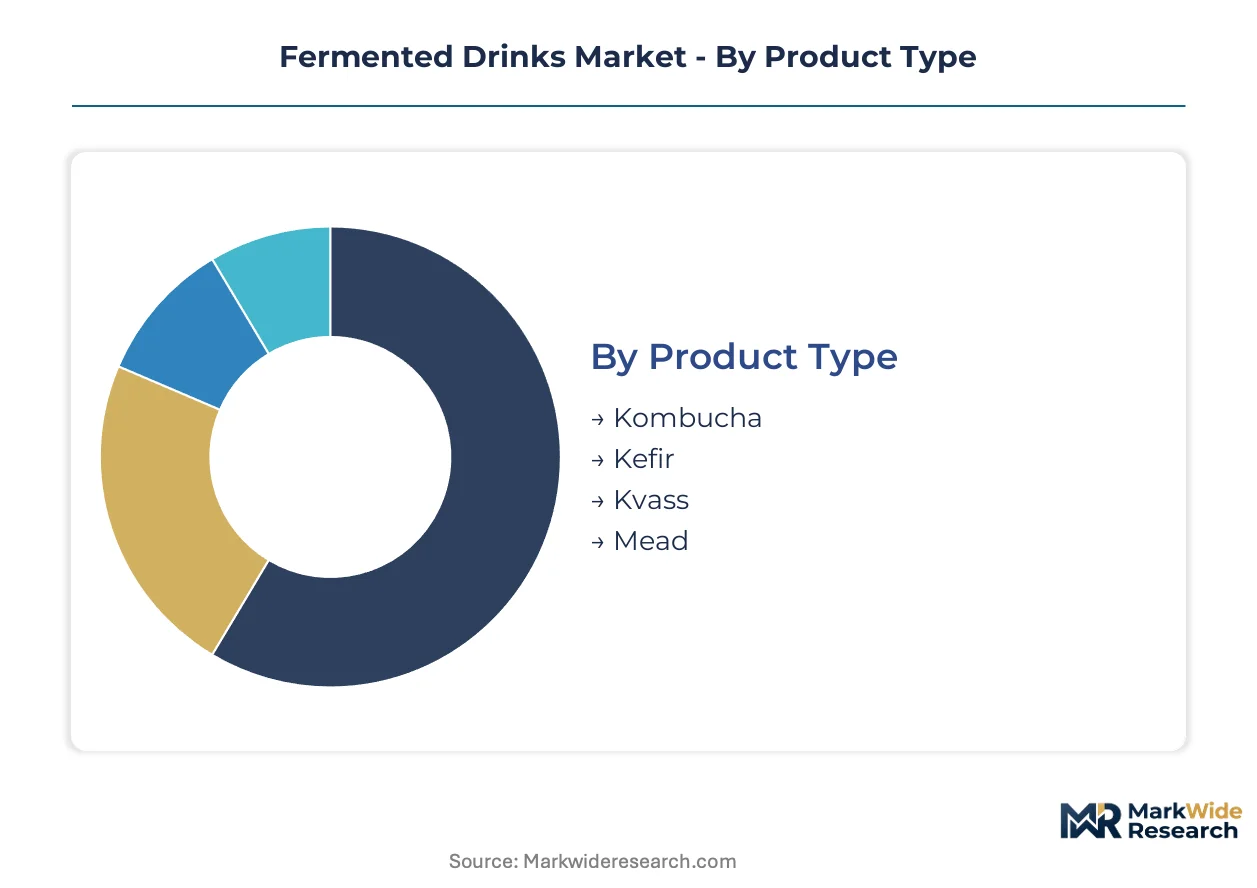
Segmentation in fermented drinks reveals how gut-health positioning, alcohol content, and packaging convenience create distinct competitive arenas with divergent margin profiles and channel requirements.
Product Type:
Kombucha faces the most intense substitute pressure from functional waters and probiotic supplements, while heritage categories defend through authenticity claims that resist commoditization.
- Kombucha:Tea-based fermentation yielding acetic acid and live cultures in effervescent finished products with pH below 4.6. Demand concentrates in Portland and Brooklyn specialty retail where EFSA-compliant probiotic labeling commands shelf premiums. GT's Living Foods anchors raw unpasteurized positioning against pasteurized mass-market entrants.
- Kefir:Dairy or water-based fermentation using kefir grains producing diverse yeast-bacterial consortia with higher culture counts than yogurt. Seniors and fitness buffs drive refrigerated dairy-aisle placement in Denver's natural grocery corridor. EFSA health claim substantiation requirements force reformulation for European export.
- Kvass:Slavic rye bread fermentation yielding low-alcohol (0.5-1.0% ABV) beverages with distinct malt character. Regional authenticity narratives sustain pricing in Eastern European heritage communities.
- Mead:Honey-wine fermentation spanning sessionable to fortified alcohol levels. Craft beverage tourism in the US mountain west supports small-batch premium positioning.
Kombucha anchors the volume base while kefir gains share at the steepest rate as dairy-alternative formulations expand addressable demand.
End User:
Cost-tier segmentation separates subscription-driven premium purchasers from price-sensitive mass-market trialists with divergent channel expectations.
- Health Enthusiasts:Early adopters prioritizing live-culture count verification and organic certification. This segment tolerates higher price points for raw unpasteurized products with transparent supply chains.
- Millennials:Largest cohort driving hard kombucha adoption as beer alternatives. Portland-Denver-Brooklyn corridor shows highest subscription penetration for direct-to-consumer replenishment.
- Seniors:Growing segment attracted to digestive health claims with established medical credibility. Pharmacy and natural grocery channels capture this demand.
- Fitness Buffs:Post-workout recovery positioning drives kefir and low-sugar kombucha selection. Protein-fortified variants target this application-specific occasion.
Millennials generate the highest per-capita spend while seniors expand the fastest as aging populations seek functional nutrition alternatives.
Flavor Profile:
Application-based segmentation maps flavor intensity to consumption occasion and food pairing compatibility.
- Fruity:Berry and citrus profiles dominate mainstream kombucha and kefir. These formulations face the strongest pressure from conventional juice and soda substitutes.
- Spicy:Ginger and pepper variants differentiate premium positioning. Heat intensity creates cocktail-mixing applications in foodservice draft systems.
- Herbal:Adaptogen and botanical infusions target stress-reduction positioning. FDA structure-function claim pathways govern marketing language.
- Earthy:Beet, turmeric, and root-vegetable profiles appeal to cleanse and detox positioning. Lower sweetness aligns with pending FDA added-sugar disclosure mandates.
Fruity formulations maintain volume leadership while earthy profiles climb fastest as sugar-content scrutiny intensifies.
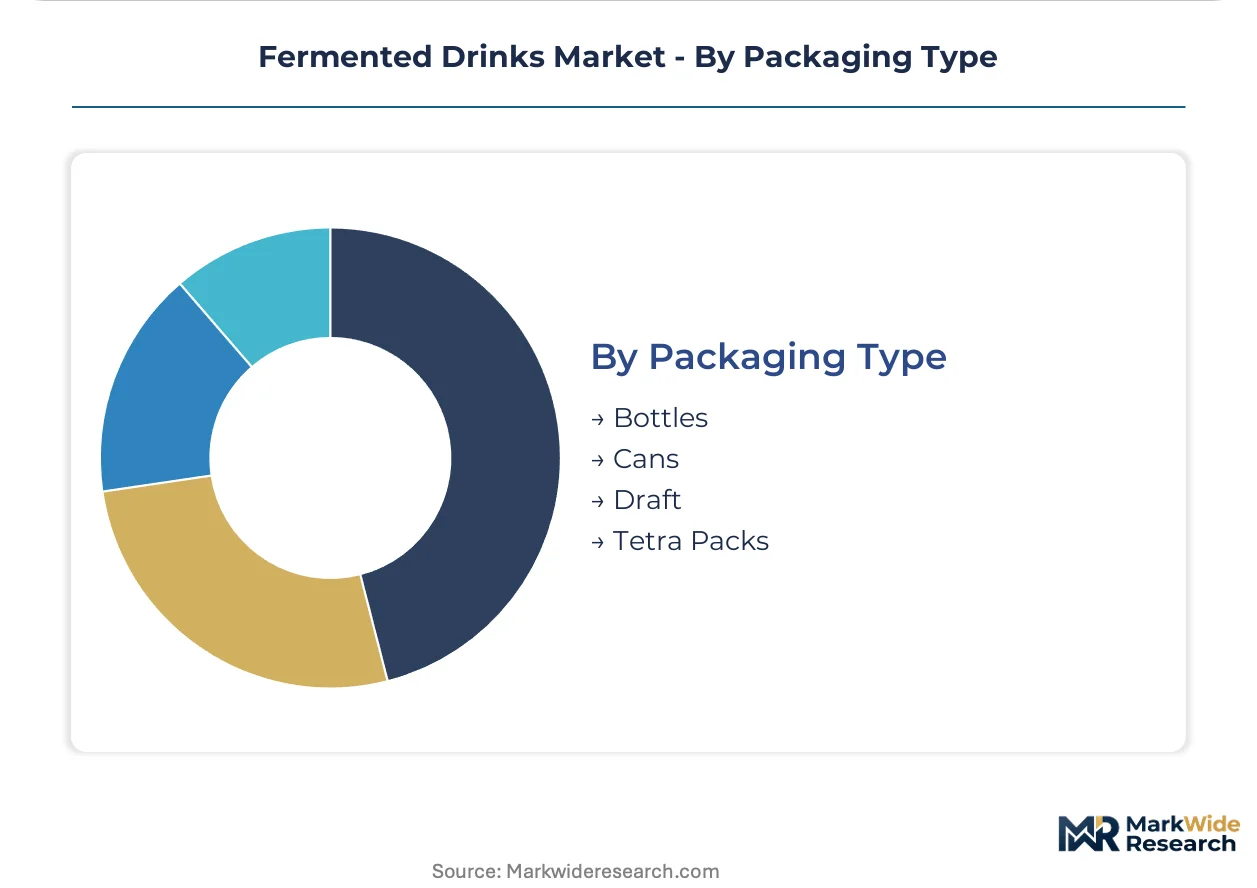
Packaging Type:
Supply concentration in glass manufacturing shapes packaging economics and distribution radius constraints.
- Bottles:Premium glass and PET formats dominate refrigerated probiotic segments. European and Mexican glass supply concentration exposes brands to freight cost volatility.
- Cans:Aluminum formats enable ambient distribution and outdoor consumption occasions. Hard kombucha and sessionable mead adopt canning for conventional retail penetration.
- Draft:Keg-based systems expand in foodservice as operators seek differentiated beverage programs without bottle inventory complexity.
- Tetra Packs:Aseptic cartons capture ambient shelf-stable kefir in European and Asian retail channels with extended distribution reach.
Bottles retain volume dominance while draft systems expand most quickly as on-premise operators rebuild post-pandemic beverage programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in fermented beverages tilt toward import dependence in emerging consumption hubs while established production centers defend export positions through heritage branding and probiotic certification advantages.
United States
Hard kombucha and craft kefir drive import substitution as domestic fermentation capacity expands. FDA acidified food safety requirements under 21 CFR Part 114 impose scheduled process validation costs on entrants. The Portland-Denver-Brooklyn corridor clusters supplier networks and accelerates product iteration through knowledge spillovers.
Germany
EFSA health claim substantiation protocols tighten evidentiary thresholds for gut-health marketing, forcing reformulation investments. Kvass heritage positioning sustains regional authenticity premiums in Eastern European export markets. Bavaria anchors traditional brewing expertise that transfers to non-alcoholic fermented beverage innovation.
Japan
Aging demographics expand demand for functional digestive health products with established medical credibility. METI standards govern probiotic labeling and live-culture count verification. Tokyo and Osaka concentrate retail distribution infrastructure for premium fermented dairy and tea-based products.
Australia
Subscription-based direct-to-consumer channels capture recurring revenue from health-conscious millennials. TGA oversight of therapeutic claims shapes marketing language for probiotic positioning. Melbourne and Sydney demonstrate highest penetration of craft kombucha taprooms and specialty retail.
Brazil
ANVISA registration requirements for novel probiotic strains delay market entry for imported functional beverages. São Paulo and Rio de Janeiro concentrate urban demand for premium positioning. Local sugarcane fermentation expertise transfers to emerging kombucha and kefir production.
Fermented Drinks Market Vendor Landscape
Concentration sits with multinational beverage conglomerates leveraging global distribution infrastructure to push functional fermented products into conventional retail channels. Craft-scale specialists defend margin pools through raw unpasteurized positioning and subscription-based direct relationships. Three archetypes dominate: legacy brewers diversifying into alcohol-adjacent segments, dairy multinationals extending probiotic portfolios, and independent fermenters exploiting regional authenticity narratives. Competitive moves center on automated bioreactor technology licensing and strategic partnerships with synthetic biology inputs suppliers.
Within the multinational tier, Anheuser-Busch InBev and PepsiCo exemplify scale-driven distribution plays, while GT's Living Foods anchors the premium independent segment. Boston Beer Company occupies a hybrid position bridging craft credibility with national retail penetration. These three entities represent the dominant strategic vectors: infrastructure leverage, premium positioning, and portfolio diversification.
| Leading Market Players |
|---|
| The Boston Beer Company |
| PepsiCo |
| Anheuser-Busch InBev |
| KeVita |
| GT's Living Foods |
| Heineken |
| Danone |
| Health-Ade |
| Carlsberg Group |
| Others |
Supply Flow & Price Mechanics
Automated bioreactor capacity utilization above 80% in tier-1 US cities compresses per-unit production costs and establishes price floors that craft-scale fermenters in tier-2 markets struggle to undercut without sacrificing live-culture viability or organic certification compliance.
Pricing Analysis
Health enthusiasts anchor premium pricing for raw unpasteurized kombucha and kefir through subscription-based replenishment models. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-compliant probiotic-labeled products from conventional fermented sodas and mass-market pasteurized entrants. Price differentiation hinges on organic certification tier and live-culture count verification, with cost compression in the standard tier intensifying due to automated production scaling. Millennials demonstrate lowest price sensitivity for hard kombucha, while seniors in pharmacy channels drive economy-tier volume.
Supply Chain Analysis
Finished-goods inventory turns slowest for glass-bottled refrigerated products due to cold-chain lead-time requirements and spoilage risk windows. Glass manufacturing concentrates in Mexico and select European hubs, while aluminum can sourcing draws from domestic US and Canadian smelters. Raw material dependencies center on organic tea substrates, honey varietals, and dairy cultures. Single-source vulnerability in European glass supply exposes brands to freight cost spikes. Distribution runs through direct-to-consumer subscription platforms, specialty retail, and conventional grocery with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated bioreactor technology represents a high-growth disruption as FDA acidified food safety requirements under 21 CFR Part 114 reshape compliance cost structures and consolidate production among scaled operators.
For Market Incumbents: Secure microbiology talent pipelines through pharmaceutical bioprocessing recruitment and academic lab partnerships to defend against craft-scale competitors exploiting regional authenticity narratives. Invest in backward integration into organic substrate sourcing to control input cost volatility and certification compliance.
For New Entrants and Emerging Players: Anchor in the convenience store channel for functional fermented sodas, exploiting the white-space opportunity in impulse purchase occasions previously closed to alcohol-adjacent products. Target seniors through pharmacy and natural grocery channels with digestive health positioning backed by transparent live-culture verification.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-based direct-to-consumer operators with Portland and Brooklyn customer density. Long-term viability favors craft-scale specialists with automated bioreactor licensing agreements and EFSA-compliant formulation capabilities. Watch for FDA added-sugar disclosure mandate implementation as an inflection indicator for reformulation-driven M&A activity.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Bioreactor Licensing | Democratizes production capacity for tier-2 city craft fermenters seeking scale. |
| EFSA Health Claim Substantiation | Enables premium shelf positioning in European markets with verified gut-health marketing. |
| Direct-to-Consumer Subscription Launch | Captures recurring revenue from millennials in Portland-Denver-Brooklyn corridor. |
| Organic Certification Investment | Unlocks dual-market architecture under USDA and EU organic regulation compliance tracks. |
| Draft System Foodservice Partnership | Differentiates on-premise beverage programs without bottle inventory complexity. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fermentation science directors, specialty retail category buyers, convenience store procurement managers, and foodservice beverage program directors. Secondary validation drew from FDA 21 CFR Part 114 filings, EFSA health claim substantiation databases, USDA organic certification records, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down category spend estimates.
Across the analysis window, forecasts segmented by product type, end-user cohort, flavor profile, and packaging format with regional regulatory cluster overlays. CAGRs derived from historical growth trajectory analysis and category penetration rate modeling. Industry-specific inputs included live-culture count threshold evolution and cold-chain infrastructure expansion rates.
Material uncertainties — regulatory revision to probiotic labeling standards, glass supply disruption, and sugar-content disclosure mandate timing — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
GCC Sports and Energy Drinks Market
Beverages
Germany Probiotic Drinks Market
Beverages
United States Smoothie Market
Beverages
Spring Water Market
Beverages
Smart Home-Based Beverage Machine Market
Beverages
North America Fruit Juice Market
Beverages
GCC Fruit Juice Market
Beverages
Packaged Coconut Water Market
Beverages
GCC Coconut Water Market
Beverages
Europe Yerba Mate Market
Beverages
Asia Pacific Fermented Drinks Market
Beverages
Europe Animal-Based Food and Beverage Market
Beverages
Europe Beverage Market
Beverages
Bottled Water Processing Market
Beverages
Fiber Fortified Beverages Market
Beverages
Birch Water Market