
 Asia Pacific Dairy Based Beverages Market | 2026-2036
Asia Pacific Dairy Based Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Dairy Based Beverages Market Outlook
India's dairy processing corridor from Gujarat to Uttar Pradesh is narrowing the cold-chain gap between rural milk collection and urban consumption. Fonterra Co-operative Group anchors its ingredient supply model across Southeast Asian manufacturing hubs. Yili Group extends its probiotic R&D platform into ambient-stable yogurt drink formats for tropical climates. Meiji Holdings Company, Ltd. dominates Japan's functional dairy beverage shelf with precision-fermented lactic acid strains.
Asia Pacific dairy based beverages comprise heat-treated or fermented liquid products containing minimum milk solids, processed through UHT pasteurization, aseptic filling, or controlled fermentation at specific pH thresholds, serving as portable nutrition delivery systems for protein, calcium, and live cultures. Flavored milk occupies the largest volume share as price-accessible entry points in Indonesia and the Philippines, while kefir generates premium margin pools among health food store channels in Australia and South Korea. Tetra Pak aseptic cartons sustain the dominant packaging position for ambient distribution, though pouches are gaining fastest in India's kirana-led convenience segment.
FSSAI's progressive enforcement of microbiological standards for ready-to-drink dairy in India, Japan's FOSHU approval pathway for functional claims under the Ministry of Health, and China's GB 19302 fermented milk standard collectively elevate formulation costs while blocking substandard imports. Australia's FSANZ nutrition labeling requirements shape export-ready product development across Oceania. Stakeholders must monitor divergence between ASEAN harmonization talks and national dairy safety regimes when allocating regulatory compliance budgets.
Market Dynamics
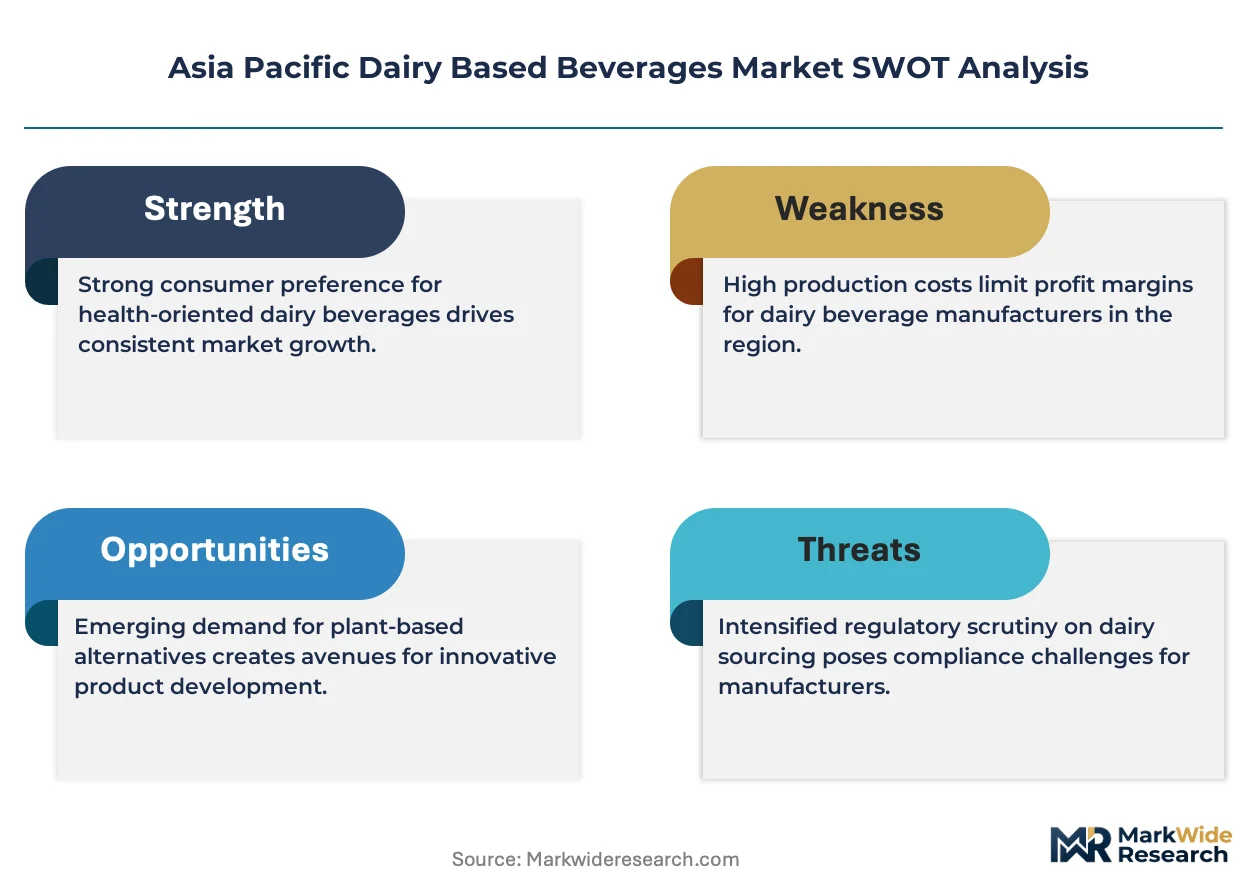
China's GB 19302 fermented milk standard revision is compressing formulation flexibility across Asia Pacific, forcing manufacturers to rebuild supply chains around stricter microbiological thresholds and documented culture strain provenance.
Growth Catalysts
- Protein fortification protocols:Young adult consumers in India and Indonesia are adopting ready-to-drink formats as meal replacements, pulling whey protein concentrate demand through Southeast Asian compounding facilities.
- FSSAI microbiological enforcement:India's progressive tightening of standards for ambient dairy beverages is clearing substandard regional competitors from shelf space in tier-two cities.
- Chilled distribution expansion:Gujarat-based cooperatives are extending cold-chain infrastructure into Uttar Pradesh, narrowing collection-to-consumption time windows for fermented products.
Market Restraints
- Skim milk powder volatility:Oceania drought cycles and New Zealand auction price swings transmit directly into Southeast Asian reconstituted milk cost structures.
- Single-origin culture dependence:Precision-fermented lactic acid strain supply concentrates in Japanese and Danish biotech facilities, creating chokepoint risk for functional claim products.
- Substitution by plant-based analogues:Oat and soy protein isolates from Australian and Chinese extrusion plants are capturing price-sensitive convenience channel volume in Indonesia and the Philippines.
Strategic Opportunities
- Ambient-stable probiotic formats:Yili Group's microencapsulation R&D platform enables shelf-stable yogurt drinks for tropical Southeast Asian climates without refrigeration.
- Kirana channel pouch penetration:India's fragmented convenience retail network favors flexible packaging over aseptic cartons for single-serve price points below ten rupees.
- FOSHU pathway exploitation:Japan's Ministry of Health approval framework for functional claims creates premium pricing headroom for precision-fermented lactic acid products targeting gut health positioning.
Industry Challenges
- Culture strain documentation:China's GB 19302 provenance requirements demand multi-year fermentation logs that most Southeast Asian contract manufacturers lack the laboratory infrastructure to maintain.
- Cold-chain capex intensity:India's tier-two city expansion requires refrigerated last-mile vehicles and hub storage that cooperatives must finance against thin fluid milk margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Dairy Based Beverages Market |
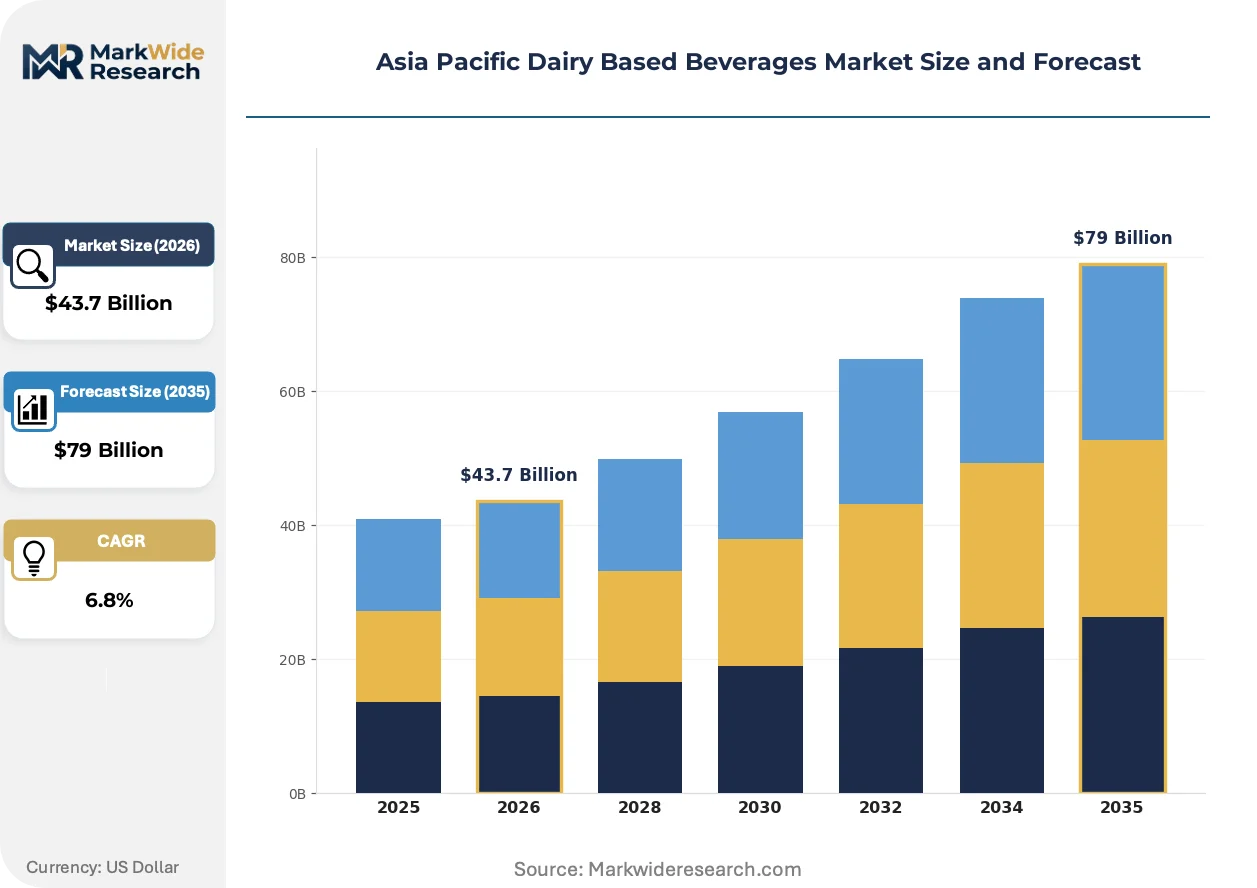
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored Milk, Yogurt Drinks, Kefir, Buttermilk Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Health Food Stores End User: Children, Young Adults, Adults, Seniors Packaging Type: Cartons, Bottles, Pouches, Tetra Packs |
| Companies Covered | GCMMF (Amul), Fonterra Co-operative Group, Bright Dairy & Food Co., Ltd., Yakult Honsha Co., Ltd., Mother Dairy Fruit & Vegetable Pvt. Ltd., Yili Group, Nestle SA, Meiji Holdings Company, Ltd., China Mengniu Dairy Company Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Dairy Based Beverages Market Strategic Shifts
Digital traceability infrastructure is penetrating dairy processing at the fermentation stage, with blockchain-enabled culture strain documentation becoming a compliance differentiator for China-bound exports.
Blockchain-based provenance tracking is digitizing supply chain verification for live culture products. Australian and New Zealand ingredient suppliers are adopting distributed ledger systems to satisfy Chinese GB 19302 documentation requirements. This technology is digitizing audit costs downward while compressing time-to-market for new strain introductions by eliminating manual chain-of-custody paperwork.
Japan's FOSHU regulatory pathway is tightening evidentiary standards for functional dairy claims. The Ministry of Health now requires human clinical trial data for gut health positioning, elevating R&D spend for market access. Precision-fermented lactic acid beverage developers in Tokyo and Osaka are responding by partnering with university medical centers for trial design.
Urban young adults across India and Indonesia are displacing traditional unpackaged lassi and dahi consumption with branded ready-to-drink formats. Kirana stores and quick-commerce platforms are capturing this volume shift through chilled dark-store networks in Bangalore, Mumbai, and Jakarta. This behavioral rotation is most visible in India's tier-one cities where single-serve protein-fortified products now occupy expanded refrigerator shelf space.
Asia Pacific Dairy Based Beverages Market Segmentation
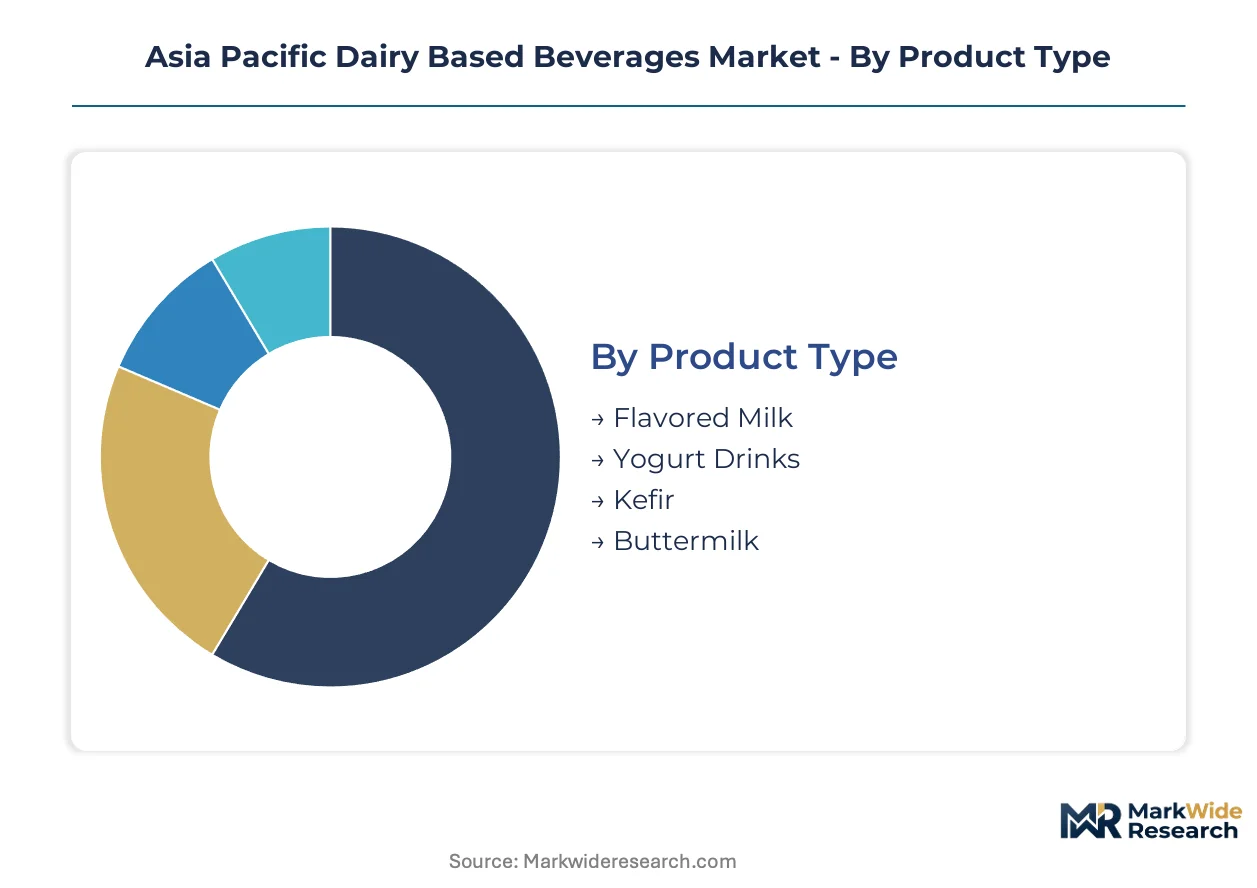
Segmentation reveals how Asia Pacific dairy based beverages fragment across price tiers, channel access, and nutritional positioning. Each dimension carries distinct margin profiles and regulatory exposure that shape portfolio allocation decisions.
Product Type:
After-sales intensity varies sharply across formats, with ambient-stable products requiring minimal cold-chain support while live-culture items demand temperature-controlled logistics infrastructure.
- Flavored Milk:Heat-treated or UHT-processed liquid milk with added sugars, cocoa, or fruit essences. Demand concentrates in Indonesia and the Philippines where single-serve sachets and pouches dominate kirana store shelves, constrained by skim milk powder price volatility from Oceania auction cycles.
- Yogurt Drinks:Fermented dairy beverages with controlled pH between 4.0-4.6, containing live or heat-treated cultures. Young adults across India's tier-one cities are displacing traditional unpackaged lassi consumption, pulling chilled dark-store expansion through quick-commerce platforms in Bangalore and Mumbai.
- Kefir:Effervescent fermented milk with complex polysaccharide kefiran and diverse yeast-bacterial symbiosis. Australian and South Korean health food store channels generate premium margin pools for organic-certified variants.
- Buttermilk:Traditional acidified dairy beverage from butter churning or culture inoculation. India's Gujarat-to-Uttar Pradesh processing corridor sustains regional cooperative volume through extended cold-chain networks.
Flavored milk holds the largest share; momentum sits with yogurt drinks.
Distribution Channel:
Channel cost structures stratify by refrigeration requirements and last-mile density, with urban convenience networks commanding premium slotting fees against thin rural margins.
- Supermarkets:Modern trade formats with dedicated chilled dairy sections and controlled cold-chain integrity. China's revised GB 19302 standards elevate compliance costs for fermented product listings, compressing SKU breadth for smaller suppliers.
- Convenience Stores:Small-format urban retail with limited refrigeration capacity and rapid inventory turns. Indonesia and the Philippines favor ambient-stable flavored milk pouches at sub-premium price points.
- Online Retailers:Quick-commerce and e-grocery platforms with dark-store chilled fulfillment networks. India's tier-one city young adults drive protein-fortified ready-to-drink volume through this channel.
- Health Food Stores:Specialty retail targeting functional positioning and premium pricing. Japan's FOSHU approval pathway creates regulatory moats for precision-fermented lactic acid products in Tokyo and Osaka.
Supermarkets retain volume concentration; online retailers are expanding most quickly.
End User:
User segments diverge by nutritional literacy, price sensitivity, and occasion-based consumption patterns that dictate formulation and packaging specifications.
- Children:Calcium and vitamin D fortified formats with controlled sugar profiles. Flavored milk dominates as parental entry-point purchases in price-accessible Southeast Asian markets.
- Young Adults:Protein-enriched ready-to-drink consumers treating beverages as meal replacements. This cohort drives fastest expansion across India and Indonesia through chilled convenience channels.
- Adults:Functional positioning around gut health and immunity support. Japan's clinical trial requirements for FOSHU claims elevate R&D spend for this demographic.
- Seniors:Bone health and digestibility-focused formulations with reduced lactose content. Australia's FSANZ labeling requirements shape export-ready product development for this segment.
Young adults hold the steepest expansion trajectory; children retain the largest volume base.
Packaging Type:
Packaging economics hinge on aseptic filling capital requirements versus flexible material flexibility, with ambient distribution favoring cartons and price-sensitive channels favoring pouches.
- Cartons:Paperboard-based aseptic containers with aluminum foil barriers for oxygen and light protection. Tetra Pak systems sustain dominant ambient distribution positions across Southeast Asian manufacturing hubs.
- Bottles:PET or HDPE formats for chilled distribution with resealability advantages. China's dairy processors favor this format for premium yogurt drink positioning in urban supermarkets.
- Pouches:Flexible multilayer films with spout or tear-notch configurations for single-serve price points. India's kirana-led convenience segment favors pouches below ten rupees against aseptic carton premiums.
- Tetra Packs:Brick-shaped aseptic cartons with standardized filling equipment ecosystems. Fonterra's ingredient supply model leverages this format consistency across regional manufacturing partners.
Cartons command the largest installed base; pouches are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy processing capacity clusters along three distinct corridors across the region, with chilled distribution networks determining competitive reach into tier-two urban markets. China's GB 19302 standard revision is forcing supply chain reconfiguration for fermented products bound for cross-border trade.
China
Urban young adults in Shanghai and Beijing are displacing traditional unpackaged yogurt consumption with branded ready-to-drink formats. GB 19302 fermented milk standards now mandate documented culture strain provenance, elevating laboratory infrastructure requirements for domestic processors. Yangtze River Delta manufacturing hubs are absorbing compliance costs through consolidated fermentation facilities.
India
Gujarat-based cooperatives are extending cold-chain infrastructure into Uttar Pradesh, narrowing collection-to-consumption windows for fermented products. FSSAI progressive enforcement of microbiological standards for ambient dairy beverages is clearing substandard regional competitors from tier-two city shelf space. The Gujarat-Uttar Pradesh processing corridor now anchors national fluid milk distribution.
Japan
Functional beverage positioning around gut health claims drives premium pricing in Tokyo and Osaka metropolitan markets. FOSHU approval pathway under the Ministry of Health now requires human clinical trial data, elevating R&D spend for market access. Kansai region precision-fermentation facilities concentrate lactic acid strain development for export-ready formulations.
Indonesia
Price-accessible flavored milk in single-serve pouches dominates kirana store channels across Jakarta and Surabaya urban corridors. Ambient-stable formulations bypass chilled infrastructure constraints in archipelago distribution. Local processors leverage skim milk powder reconstitution to manage Oceania auction price volatility exposure.
Australia
Organic-certified kefir generates premium margin pools through health food store channels in Sydney and Melbourne. FSANZ nutrition labeling requirements shape export-ready product development for regional trade. Blockchain-enabled culture strain documentation is penetrating fermentation-stage processing to satisfy Chinese GB 19302 documentation requirements.
Asia Pacific Dairy Based Beverages Market Competitive Environment
Vertically integrated cooperatives and multinational ingredient suppliers split the market between domestic cold-chain dominance and cross-border formulation technology. Three archetypes define competitive positioning: national cooperative networks with chilled distribution control, Asian dairy conglomerates with probiotic R&D platforms, and Oceania-based ingredient suppliers with standardized format ecosystems. Capacity expansion in tier-two city cold storage and strategic partnerships for culture strain documentation represent the dominant competitive moves.
Within the cooperative network archetype, GCMMF anchors Indian market presence through Gujarat-based chilled infrastructure extension. Among Asian dairy conglomerates, Yili Group and Meiji Holdings exemplify precision-fermentation capabilities targeting tropical climate stability and FOSHU functional claims respectively. Fonterra Co-operative Group occupies the ingredient supply tier, leveraging standardized Tetra Pak format consistency across Southeast Asian manufacturing partnerships.
| Leading Market Players |
|---|
| GCMMF (Amul) |
| Fonterra Co-operative Group |
| Bright Dairy & Food Co., Ltd. |
| Yakult Honsha Co., Ltd. |
| Mother Dairy Fruit & Vegetable Pvt. Ltd. |
| Yili Group |
| Nestle SA |
| Meiji Holdings Company, Ltd. |
| China Mengniu Dairy Company Limited |
| Others |
Value Chain & Pricing Dynamics
Oceania skim milk powder auction volatility compresses margin spreads across Southeast Asian reconstituted milk tiers while simultaneously forcing supply chain consolidation toward integrated powder-to-beverage processing corridors. GB 19302 culture strain documentation requirements in China further bifurcate pricing architecture between compliant premium formats and undocumented economy substitutes.
Pricing Analysis
FSSAI microbiological enforcement dictates the pricing tier structure across Indian ambient dairy beverages, separating FSSAI-certified premium SKUs from substandard regional economy products in tier-two city retail. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and cold-chain integrity rather than formulation differentiation alone. Cost compression in economy flavored milk pouches intensifies because Oceania drought cycles transmit directly into reconstituted milk input costs. Kirana channel buyers in Indonesia and the Philippines exhibit highest price sensitivity, while Japan's FOSHU-approved functional positioning commands least elastic demand.
Supply Chain Analysis
Contract manufacturing capacity concentrates in Yangtze River Delta fermentation facilities and Gujarat-based cooperative processing hubs. Raw material dependencies center on Oceania skim milk powder, Japanese precision-fermented lactic acid strains, and Danish biotech culture supplies. Single-origin strain vulnerability creates chokepoint exposure for functional claim products targeting Chinese and Japanese regulatory pathways. Distribution runs through Tetra Pak aseptic carton networks for ambient-stable formats, with chilled last-mile cooperatives dominating Indian tier-two expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific dairy based beverages present a service-attach opportunity where cold-chain logistics contracts and culture strain documentation services expand faster than base beverage manufacturing. Recurring revenue from compliance-as-a-service layers for GB 19302 and FOSHU documentation outpaces hardware margins on ambient carton filling equipment.
For Market Incumbents: Harden fermentation facility consolidation in Yangtze River Delta and Gujarat corridors to capture scale efficiencies against powder price volatility. Defend margin position by locking multi-year culture strain supply agreements with Japanese and Danish biotech facilities before provenance documentation requirements tighten further. Prioritize backward integration into chilled last-mile distribution in Indian tier-two cities where FSSAI enforcement is clearing substandard competitors. For New Entrants and Emerging Players: Build out ambient-stable probiotic formats for Indonesian and Philippine kirana channels where refrigeration infrastructure remains underdeveloped. Target India's quick-commerce dark-store networks with protein-fortified single-serve pouches priced below ten rupees. Lead with blockchain-enabled culture strain documentation as a compliance differentiator for China-bound export positioning. For Investors and Strategic Acquirers: China's GB 19302 revision reshapes the acquisition landscape toward fermentation facilities with existing laboratory infrastructure and documented strain libraries. Five-to-ten year viability favors precision-fermentation capabilities over commodity reconstitution capacity. Watch FSSAI enforcement intensity in Indian tier-two cities as inflection indicator for cooperative consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | GCMMF's Uttar Pradesh corridor extension narrows collection-to-consumption windows for fermented products. |
| Precision-Fermentation R&D Platform | Yili Group's microencapsulation enables tropical climate stability without refrigeration dependency. |
| Blockchain Provenance Integration | Australian suppliers adopt distributed ledgers to satisfy Chinese GB 19302 documentation requirements. |
| FOSHU Clinical Trial Investment | Meiji Holdings partners with university medical centers for gut health claim evidentiary standards. |
| Kirana Channel Pouch Penetration | Flexible packaging below ten rupees captures India's fragmented convenience retail price sensitivity. |
Study Parameters
Operator-level perspectives from dairy processing plant managers, cooperative supply chain directors, FSSAI regulatory affairs leads, Tetra Pak filling equipment technicians, and quick-commerce dark-store operators anchored the qualitative base. Primary fieldwork combined with secondary validation from FSSAI enforcement circulars, GB 19302 standard revision drafts, Japanese Ministry of Health FOSHU approval databases, and Oceania dairy auction price series. Bottom-up volume modeling across product type, distribution channel, end user, and packaging format segments triangulated against top-down regional consumption aggregates.
Scenario-bracketing around Oceania drought frequency, FSSAI enforcement intensity gradients, and GB 19302 implementation timelines bounded projection uncertainty across the analysis window. Segmentation dimensions modeled include product type, distribution channel, end user demographic, packaging format, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for structural shift inflection points in cold-chain penetration and functional claim regulatory pathways. Forecast inputs incorporated powder-to-fluid milk conversion ratios and live culture viability decay curves in tropical climate distribution.
Stress conditions across Oceania auction price spikes, FSSAI enforcement acceleration, and Chinese import documentation rejection rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about cooperative credit access for refrigerated vehicle fleets and biotech strain licensing cost trajectories. Quarterly review of FSSAI tier-two city inspection frequency and Yangtze River Delta fermentation facility utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Root Beer Market
Beverages
GCC Fruit Juice Market
Beverages
North America Fruit Juice Market
Beverages
Milk Tea Powder Market
Beverages
Hot Chocolate Market
Beverages
Relaxation Beverages Market
Beverages
Reconstituted Juice Market
Beverages
Ginger Beer Market
Beverages
Fruit Juice Market
Beverages
Growlers Market
Beverages
Caffeine-Based Drinks Market
Beverages
Beverages Market
Beverages
Asia Pacific Soy Beverages Market
Beverages
Cactus Water Market
Beverages
Whole Grain Drinks Market
Beverages
Beverage Premix Market