
 Indonesia Bottled Water Market | 2026-2036
Indonesia Bottled Water Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Bottled Water Market Outlook
Indonesia is rewriting competitive dynamics in Southeast Asian packaged beverages through aggressive production expansion across Java and Sulawesi. Danone SA leverages its Aqua brand heritage to dominate Java's retail channels. PT Sariguna Primatirta Tbk sustains cost leadership through captive spring access in Central Java. Nestle SA differentiates via mineral fortification protocols that exceed baseline national standards.
Bottled water comprises potable water sourced from springs, wells, or municipal supplies, then treated through reverse osmosis, ultraviolet sterilization, or ozonation to achieve microbiological safety and mineral stability for commercial consumption. Still water occupies the volume core across Indonesian retail, while flavored water captures premium margin pools in urban convenience stores. PET Bottles lead packaging economics due to lightweight logistics, though Reusable Containers gain traction in office and HoReCa channels where deposit-return systems reduce per-unit waste costs.
Indonesia's Ministry of Health and BIS enforce drinking water quality standards that mandate periodic testing for heavy metals, bacterial contamination, and pH stability, raising compliance costs for smaller packagers. BPOM registration requirements for flavored variants add formulation disclosure burdens that favor established players with regulatory affairs capacity. Stakeholders must monitor groundwater extraction licensing reforms and plastic waste reduction mandates that could reshape sourcing economics and packaging obligations across the archipelago.
Market Dynamics
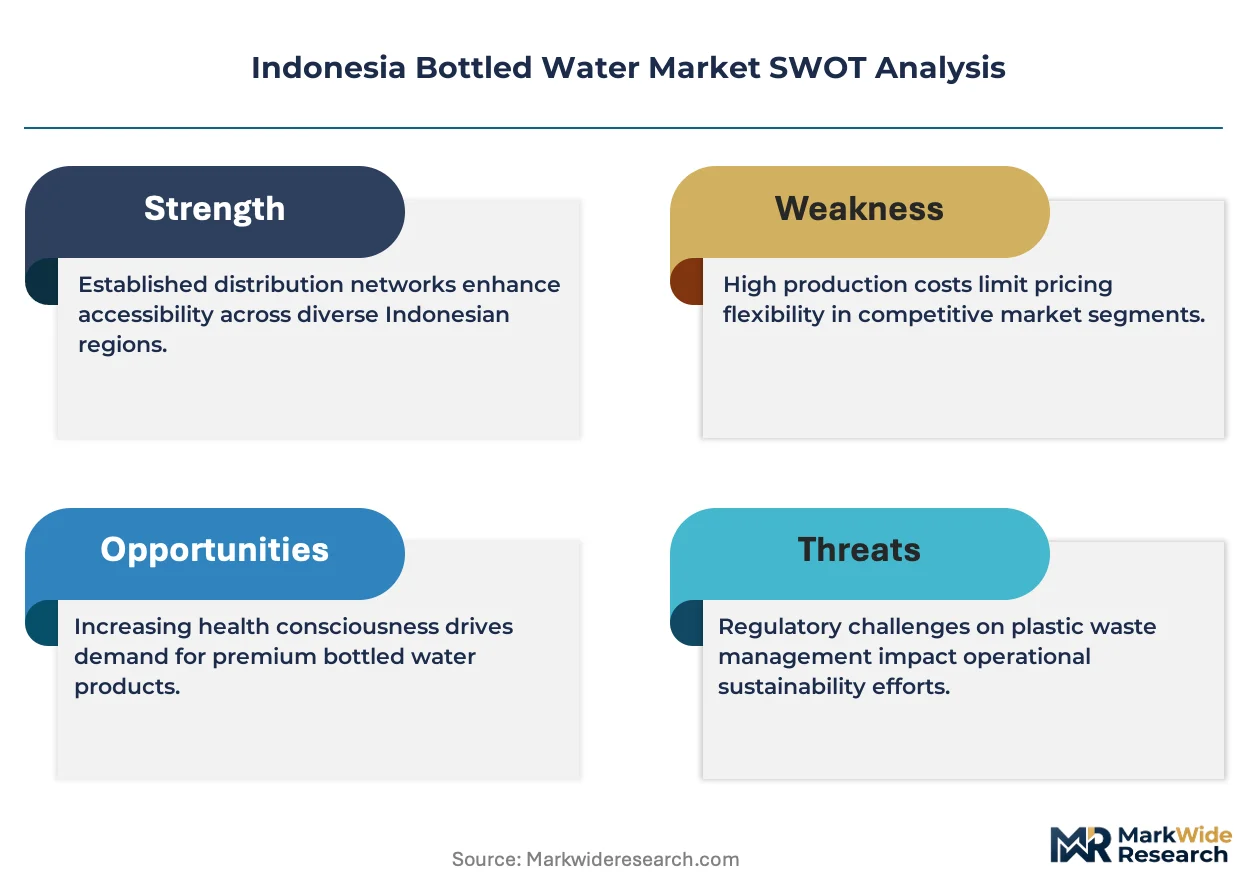
Groundwater extraction licensing reforms and single-use plastic reduction mandates are restructuring sourcing economics and packaging obligations across the Indonesian archipelago, forcing producers to recalibrate spring access and material substitution strategies.
Growth Catalysts
- HoReCa Channel Expansion:Tourism corridors in Bali and Yogyakarta drive premium volume as hotels and restaurants upgrade beverage programs beyond basic hydration to branded table water.
- BIS Quality Enforcement:Mandatory periodic testing for heavy metals and bacterial contamination elevates compliance barriers that cull informal packagers and consolidate share among certified operators.
- Reverse Osmosis Advancement:Municipal water treatment upgrades in Surabaya and Bandung reduce raw material variability, enabling consistent production scaling for mid-tier brands.
Market Restraints
- PET Resin Import Dependency:Packaging material costs fluctuate with rupiah-dollar volatility and regional polymer supply tightness, compressing margin buffers for volume-focused producers.
- Spring Site Concentration:Captive access to verified groundwater reserves clusters in Central Java and West Java highlands, creating extraction queue bottlenecks for new entrants.
- Household Filtration Substitution:Countertop UV and ceramic filter adoption in Jakarta middle-class apartments displaces daily purchase frequency for 19-liter gallon formats.
Strategic Opportunities
- Eastern Indonesia Penetration:Sulawesi and Papua retail infrastructure gaps present first-mover terrain for regional bottlers with localized distribution partnerships.
- Deposit-Return System Pilots:Reusable glass bottle programs in Bali hospitality clusters demonstrate operational viability for waste reduction compliance ahead of national mandates.
- Flavored Functional Positioning:Electrolyte and vitamin-fortified variants target post-exercise consumption in Jakarta fitness studio channels, capturing premium price multiples.
Industry Challenges
- BPOM Registration Timelines:Flavored water formulation disclosure requirements extend product launch cycles, demanding dedicated regulatory affairs capacity that strains mid-tier operators.
- Cold Chain Last-Mile Gaps:Temperature-controlled delivery to convenience stores in secondary cities requires fleet investment that conflicts with asset-light expansion models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Bottled Water Market |
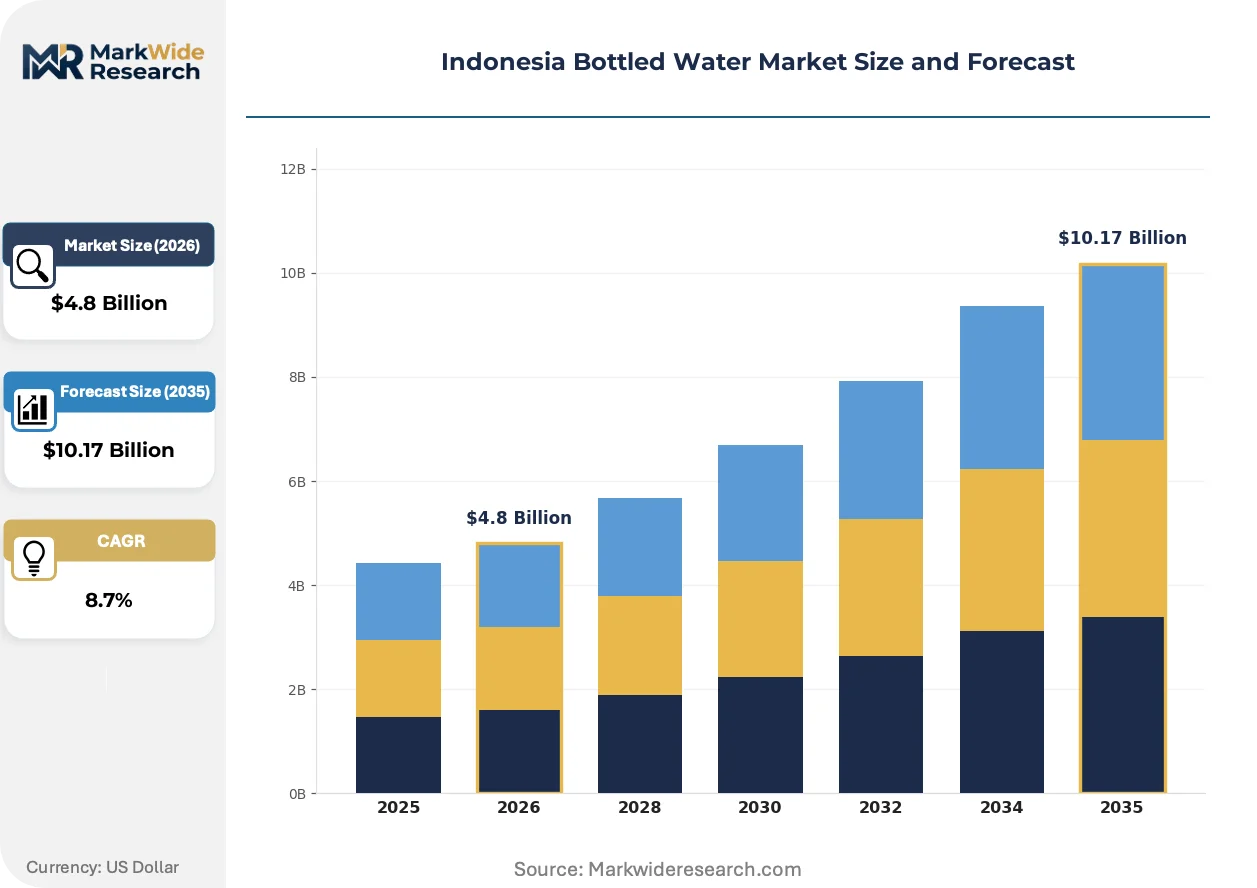
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Still Water, Sparkling Water, Flavored Water, Mineral Water Distribution Channel: Supermarkets, Convenience Stores, Online Retail, HoReCa Packaging Type: PET Bottles, Glass Bottles, Tetra Packs, Reusable Containers End User: Residential, Office, Restaurants, Cafes |
| Companies Covered | Danone SA, The Coca-Cola Company, Nestle SA, PT Mayora Indah Tbk, PT Sariguna Primatirta Tbk, PT Indofood CBP Sukses Makmur Tbk, Fraser & Neave Ltd, PT Pristine Prima Indonesia, PT Tirta Fresindo Jaya, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Bottled Water Market Strategic Shifts
Packaging material science and retail channel digitization are converging to redefine how Indonesian consumers access, purchase, and consume packaged hydration across urban and tourism-dense environments.
Ozonation-UV tandem treatment systems are hybridizing conventional purification workflows, enabling smaller packagers to achieve BIS microbiological standards without capital-intensive reverse osmosis infrastructure. Regional cooperatives in East Java deploy these compact units to enter formal retail distribution. The technology compresses the minimum efficient scale for certified production, fragmenting supply concentration in secondary cities.
Indonesia's Ministry of Environment and Forestry advances extended producer responsibility frameworks that mandate post-consumer packaging collection quotas. Brand owners must finance reverse logistics networks or face escalating waste levies. Premium segment operators respond by piloting refill station partnerships with convenience chains in Jakarta.
Subscription-based home and office delivery platforms displace traditional trade intermediation, compressing distributor margins while capturing recurring revenue streams. Direct-to-consumer apps in Surabaya and Medan bundle gallon refills with filtration equipment leases. This channel rotation concentrates most visibly in upper-middle residential clusters where smartphone penetration enables route optimization.
Indonesia Bottled Water Market Segmentation
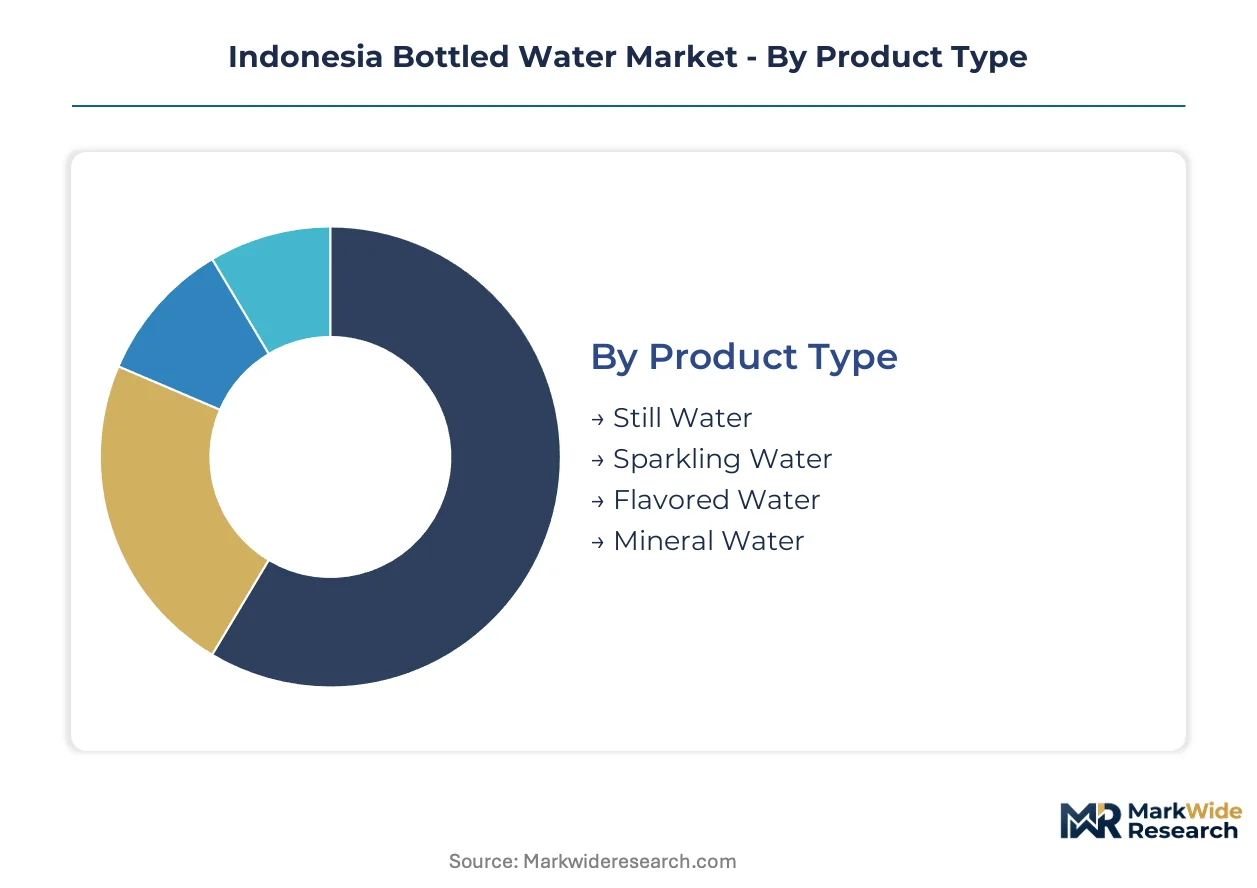
Segmentation in Indonesia's bottled water market reveals distinct service and logistics requirements across product formats and delivery channels. Understanding these divides allows producers to align purification investment, packaging procurement, and route density with margin profiles.
Product Type:
After-sales service intensity varies sharply across product categories, with mineral water demanding spring stewardship programs and flavored variants requiring formulation stability monitoring.
- Still Water:Un-carbonated potable water treated through reverse osmosis or UV sterilization dominates household consumption. Demand concentrates in Jakarta and Surabaya apartment complexes where daily delivery subscriptions sustain volume. Municipal tap water reliability concerns in these cities drive habitual purchase frequency.
- Mineral Water:Naturally sourced water retaining dissolved minerals like calcium and magnesium commands premium positioning. Hotels in Bali tourism corridors specify certified mineral content for guest dining programs, linking sourcing provenance to hospitality brand standards.
- Sparkling Water:Carbonated variants produced through forced CO2 injection target café and restaurant channels in Yogyakarta.
- Flavored Water:Fruit-infused or electrolyte-enhanced formulations capture fitness studio demand in Jakarta.
By volume, still water leads. By growth pace, flavored water is ahead.
Distribution Channel:
Cost tier separation across channels determines margin retention, with direct-to-premium HoReCa yielding multiples above mass retail.
- HoReCa:Hotels, restaurants, and cafés in Java and Bali tourism corridors drive branded table water specifications. Properties in Ubud and Seminyak negotiate exclusive supply agreements that lock in volume commitments and customization services.
- Convenience Stores:24-hour retail networks in Jakarta and Bandung prioritize chilled single-serve formats with rapid inventory turnover. Store clusters near transit hubs capture impulse hydration purchases from commuters.
- Supermarkets:Hypermarket chains in Surabaya and Medan stock multi-pack gallon formats for household stockpiling.
- Online Retail:E-commerce platforms in Jakarta residential zones bundle subscription refills with filtration equipment leases.
HoReCa commands highest per-unit margins. Online retail is expanding most quickly.
Packaging Type:
Application context dictates material selection, with deposit-return systems in hospitality settings diverging from disposable retail economics.
- PET Bottles:Lightweight polyethylene terephthalate containers dominate retail logistics across Indonesian archipelago shipping routes. The material's cost efficiency supports volume-focused producers serving convenience store networks in secondary cities.
- Reusable Containers:19-liter polycarbonate gallons with deposit-return mechanics sustain office and residential delivery subscriptions. Jakarta co-working spaces specify these formats to meet corporate waste reduction targets.
- Glass Bottles:Premium hospitality venues in Bali mandate glass for table service aesthetics.
- Tetra Packs:Aseptic cartons target school and institutional channels in East Java.
PET bottles lead by shipment volume. Reusable containers gain share fastest in compliance-driven segments.
End User:
Customer type segmentation aligns purification certification levels with consumption setting requirements, from residential BIS compliance to restaurant food safety protocols.
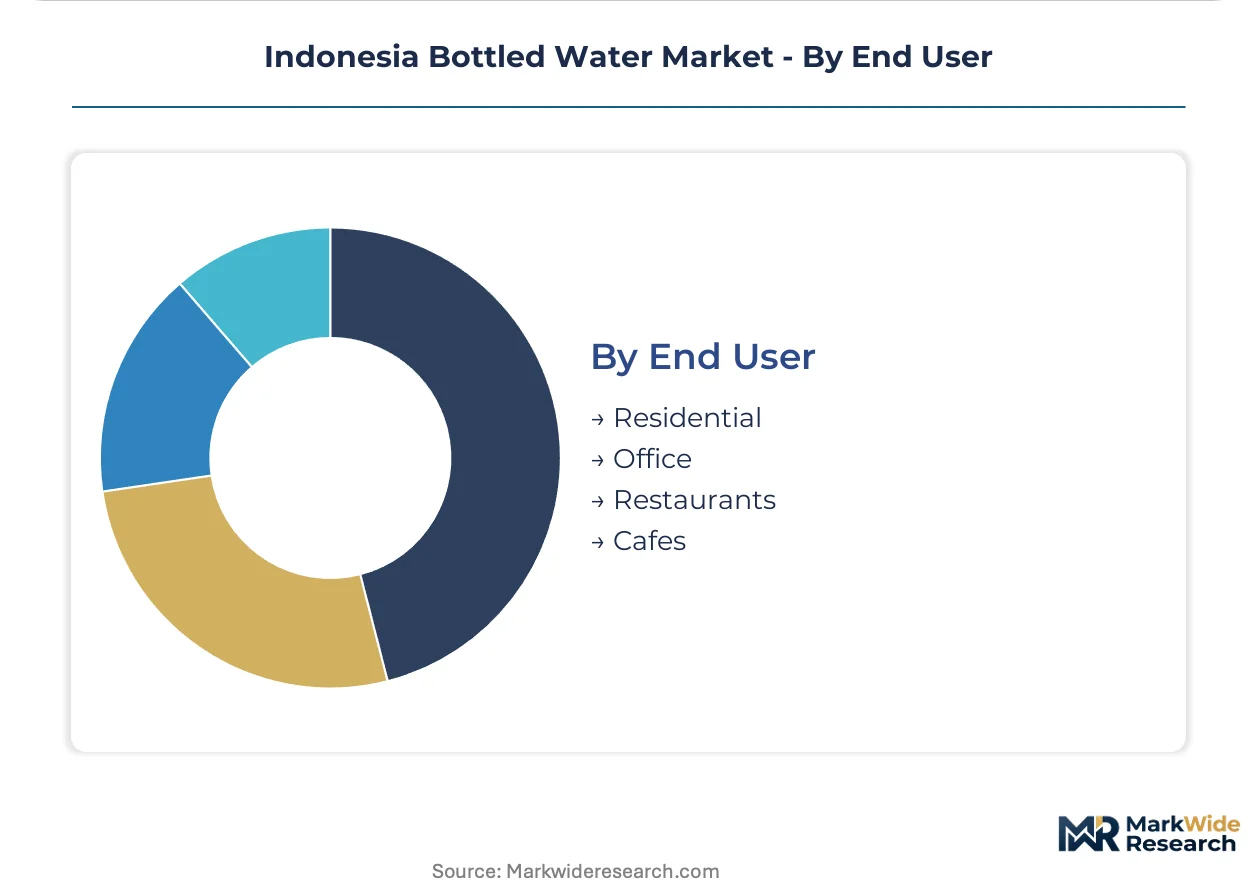
- Residential:Household consumption across Jakarta middle-class apartments sustains gallon refill subscriptions and countertop filtration alternatives. Family units prioritize cost-per-liter economics over premium positioning.
- Restaurants:Dining establishments in Surabaya and Bandung require BIS-certified supply with documented chain of custody for health inspection compliance. Menu-integrated water programs upgrade basic hydration to margin-contributing beverage categories.
- Office:Corporate facilities in Jakarta CBD clusters specify bulk delivery with dispenser maintenance contracts.
- Cafes:Independent coffee shops in Yogyakarta source sparkling variants for menu differentiation.
Residential segment leads by unit volume. Restaurants show steepest expansion trajectory amid tourism recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spring access concentrates in Central Java and West Java highlands, while consumption clusters form around Jakarta, Surabaya, and Bali tourism corridors. Provincial licensing regimes and municipal water reliability gaps create divergent operating conditions across the archipelago.
Java
Jakarta's apartment complexes sustain gallon subscription volumes amid persistent tap water quality concerns. BIS mandates periodic heavy metal and bacterial testing that raises compliance costs for packagers serving Greater Jakarta. Bandung and Surabaya host mid-tier production facilities leveraging municipal RO treatment upgrades to scale consistent output.
Bali
Ubud and Seminyak hospitality venues drive premium mineral water specifications through exclusive supply agreements. The Ministry of Environment and Forestry's extended producer responsibility pilots pressure brand owners to finance reverse logistics for post-consumer packaging collection. Deposit-return glass bottle programs demonstrate operational viability ahead of national waste reduction mandates.
Sulawesi
Makassar and Manado retail infrastructure gaps present first-mover terrain for regional bottlers with localized distribution partnerships. Groundwater extraction licensing reforms are restructuring sourcing economics as provincial authorities tighten spring site allocations. Cold chain last-mile gaps in secondary cities demand fleet investment that conflicts with asset-light expansion models.
Sumatra
Medan's direct-to-consumer apps bundle gallon refills with filtration equipment leases, capturing recurring revenue in upper-middle residential clusters. BPOM registration timelines for flavored variants extend product launch cycles, favoring established players with regulatory affairs capacity. Palembang and Padang convenience store networks prioritize chilled single-serve formats with rapid inventory turnover.
Papua
Jayapura and Sorong distribution partnerships remain underdeveloped relative to eastern Indonesia penetration opportunities. Provincial health authorities enforce BIS-certified supply documentation for institutional channels including schools and government facilities. Limited PET resin import logistics amplify packaging cost volatility in this frontier market.
Indonesia Bottled Water Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. Danone SA leverages its Aqua brand heritage to dominate Java's retail channels through decades of distribution infrastructure investment. PT Sariguna Primatirta Tbk sustains cost leadership through captive spring access in Central Java. Nestle SA differentiates via mineral fortification protocols that exceed baseline national standards. Competitive moves concentrate on capacity expansion in Sulawesi and strategic partnerships with HoReCa channels in Bali.
Among multinational CPG conglomerates, Danone SA and Nestle SA occupy positions as platform integrators with end-to-end control over purification, packaging, and route density. PT Sariguna Primatirta Tbk represents the domestic specialist archetype, anchoring cost-efficient production through geographic concentration in verified groundwater territories. These three players exemplify the market's tripartite structure: global brand equity, regional scale efficiency, and local resource access.
| Leading Market Players |
|---|
| Danone SA |
| The Coca-Cola Company |
| Nestle SA |
| PT Mayora Indah Tbk |
| PT Sariguna Primatirta Tbk |
| PT Indofood CBP Sukses Makmur Tbk |
| Fraser & Neave Ltd |
| PT Pristine Prima Indonesia |
| PT Tirta Fresindo Jaya |
| Others |
Value Chain & Pricing Dynamics
Central Java's captive spring clusters concentrate extraction rights among established packagers, translating geographic resource control into pricing power over Jakarta and Surabaya distribution networks. Cost compression in PET resin sourcing feeds through to margin pressure for volume-focused operators serving convenience store channels.
Pricing Analysis
BIS certification mandates dictate the pricing tier structure across Indonesian bottled water, separating premium mineral grades from standard purified formats through documented heavy metal testing protocols. Three-tier pricing structure across premium, standard, and economy levels reflects brand heritage, spring provenance, and distribution channel exclusivity. Price differentiation centers on HoReCa table water specifications versus retail gallon subscriptions. Household residential segments exhibit highest price sensitivity, while Bali hospitality venues absorb premium multiples for certified mineral content.
Supply Chain Analysis
Extended payment terms from PET resin suppliers strain working capital for mid-tier packagers navigating rupiah-dollar volatility. Raw material sourcing draws from regional polymer producers in Thailand and Singapore, plus domestic recycled flake processors. Groundwater extraction licensing reforms in Central Java and West Java create single-source vulnerability for spring-dependent operators. Distribution runs through layered distributor networks to convenience stores, with direct-to-consumer apps disintermediating traditional trade in Jakarta upper-middle clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Verified spring access functions as the scarcest capability in Indonesian bottled water, with extraction queue bottlenecks culling new entrants regardless of capital availability. Regulatory affairs capacity for BPOM flavored variant registration represents a secondary competency gap favoring established operators.
For Market Incumbents: Pre-empt household filtration substitution by bundling dispenser maintenance contracts with gallon subscription platforms in Jakarta residential towers. Lock exclusive supply agreements with Ubud and Seminyak hospitality properties before deposit-return mandates reshape packaging obligations. Vertical integration into captive spring stewardship programs in Central Java highlands defends cost position against PET resin volatility. For New Entrants and Emerging Players: Establish a beachhead in Sulawesi retail infrastructure gaps through localized distribution partnerships with Makassar and Manado wholesalers. Target Papua institutional channels where BIS-certified supply documentation requirements filter out informal competitors. Lead with ozonation-UV tandem treatment systems to achieve certification without capital-intensive reverse osmosis infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because extended producer responsibility frameworks will escalate waste levies on sub-scale operators lacking reverse logistics financing capacity. Acquisition candidates combine captive spring access with regulatory affairs teams capable of navigating BPOM registration timelines. Monitor groundwater extraction licensing reform implementation as the inflection signal for spring asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Spring Acquisition | Central Java highland extraction rights anchor cost leadership against resin-dependent competitors. |
| Deposit-Return System Pilot | Bali hospitality cluster programs demonstrate compliance viability ahead of national waste mandates. |
| Direct-to-Consumer Platform Launch | Jakarta subscription apps capture recurring revenue while compressing traditional distributor margins. |
| Flavored Functional Line Extension | Electrolyte variants target Jakarta fitness studios with premium price multiples over still water. |
| Eastern Indonesia Distribution Partnership | Sulawesi and Papua localized networks unlock first-mover terrain in underserved retail corridors. |
Study Parameters
Cross-validation between primary interviews with plant managers, procurement leads at HoReCa chains, BIS regulatory officers, and distribution channel partners anchors the qualitative findings. Secondary validation draws from BPOM registration databases, BIS testing protocols, customs import records for PET resin, and Nielsen retail audit data. Bottom-up production capacity modeling triangulates against top-down consumption estimates across the analysis window.
Calibration against historical volume trajectories and documented spring extraction allocations shapes the analytical framework. Segmentation dimensions span product type, distribution channel, packaging format, and end-user category throughout the forecast period. CAGRs derive from trend extrapolation moderated by regulatory inflection points and channel substitution dynamics. Forecast inputs incorporate groundwater licensing reform timelines and extended producer responsibility implementation schedules.
Sensitivities concentrate around rupiah depreciation accelerating PET resin cost pressure, household filtration adoption rates in Jakarta middle-class apartments, and provincial enforcement variance in BIS certification compliance. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Ginger Beer Market
Beverages
Hydrogen Water Bottle Market
Beverages
Plant Based Protein Beverages Market
Beverages
Botanical Infused Beverages Market
Beverages
North America Energy Drink Market
Beverages
Beverage Premix Market
Beverages
Sports Drink Market
Beverages
Smoothies Market
Beverages
Saudi Arabia Retail Bubble Tea Kits Market
Beverages
China Orange Juice Market
Beverages
Crystal Boba Market
Beverages
Dairy Based Beverages Market
Beverages
Carbonated Beverages Market
Beverages
Soft Serve Premix Market
Beverages
Freezer & Beverage and Wine Cooler Market
Beverages
Sparkling Bottled Water Market