
 Glazes Market | 2026-2036
Glazes Market Size, Share, and Industry Trends Forecast 2026-2036
Glazes Market Foresight
Italian ceramic glaze production is consolidating as energy-intensive kiln operations face natural gas cost pressures. Saint-Gobain leverages its fused mineral technology leadership to supply high-performance architectural glazes across Southern Europe. AGC Inc. anchors specialty glass glaze output for photovoltaic and display applications in East Asia. Kerry Group plc competes in the food-grade glaze segment with controlled-release coating systems for confectionery and pharmaceutical tablets.
Glazes are thin, vitreous coatings applied to ceramic, glass, or metal substrates through firing, spraying, or dipping, typically containing silica, fluxes, and colorants that melt between 900°C and 1300°C to form a durable, decorative, or protective surface layer. Their primary purpose spans aesthetic enhancement, chemical resistance, and surface hardening across manufactured goods. Ceramic glazes dominate value in the product type dimension, sustained by construction sector specification for architectural surfaces requiring frost resistance and stain immunity. Liquid formulations lead the form category due to spray application efficiency in automated tile production lines, while powder glazes retain cost advantages in artisanal craft and small-batch pottery operations where manual mixing persists.
EPA air quality standards and OSHA silica exposure limits constrain raw material handling and dry processing operations in United States glaze manufacturing facilities. REACH registration requirements in Europe govern the import and formulation of metal oxide colorants, particularly cobalt and chromium compounds used in specialty pigment glazes. China's GB standards for ceramic product safety set migration limits for lead and cadmium in tableware glazes, directly shaping export-oriented production decisions. Stakeholders must monitor evolving chemical restriction lists across these jurisdictions to anticipate reformulation costs and supply chain qualification requirements.
Market Dynamics
LEED certification tightening across United States commercial construction is forcing ceramic manufacturers to source specification-grade glazes with verified low-VOC and recycled content credentials, compressing supplier qualification timelines and raising technical barriers to contract participation.
Growth Catalysts
- EPA air quality standards:United States facilities must retrofit dry processing lines with dust capture systems, accelerating demand for pre-mixed liquid glaze formulations that eliminate silica handling risks.
- Photovoltaic manufacturing expansion:East Asian solar panel producers specify high-transmission glass glazes for anti-reflective coating substrates, pulling specialty formulation capacity toward energy sector applications.
- Artisanal pottery resurgence:Small-batch ceramic studios across North America and Western Europe sustain powder glaze demand through direct-to-craftsperson e-commerce channels bypassing traditional distributor networks.
Market Restraints
- Natural gas cost volatility:Italian and Spanish ceramic districts face kiln operation cost spikes as European energy markets destabilize, eroding margin buffers for mid-tier glaze producers.
- REACH registration friction:Cobalt and chromium oxide colorants require costly toxicity dossiers for European import, delaying new pigment launches and consolidating formulation choices among incumbent suppliers.
- Technical substitution threat:Digital ceramic printing systems bypass glaze layers entirely for surface decoration, threatening volume in commodity tile segments where pattern fidelity requirements are moderate.
Strategic Opportunities
- India construction acceleration:Bureau of Indian Standards certification for frost-resistant architectural ceramics remains underpenetrated, creating first-mover advantage for glaze suppliers establishing local technical service presence.
- Confectionery coating convergence:Controlled-release food-grade glaze technology from pharmaceutical tablet coating is migrating into premium chocolate and nut applications, opening cross-sector formulation licensing.
- China dual carbon policy:National mandates for industrial energy efficiency favor low-temperature glaze formulations firing below 1000°C, rewarding R&D investment in flux chemistry optimization.
Industry Challenges
- Pyrometric cone calibration expertise:Automated production lines still require skilled technicians to interpret firing curve variations, and demographic shifts in ceramic engineering programs constrain talent pipelines.
- Cross-border formulation reconciliation:Glaze recipes compliant with China GB standards for lead migration often fail United States FDA food-contact thresholds, forcing parallel product line maintenance and inventory duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glazes Market |
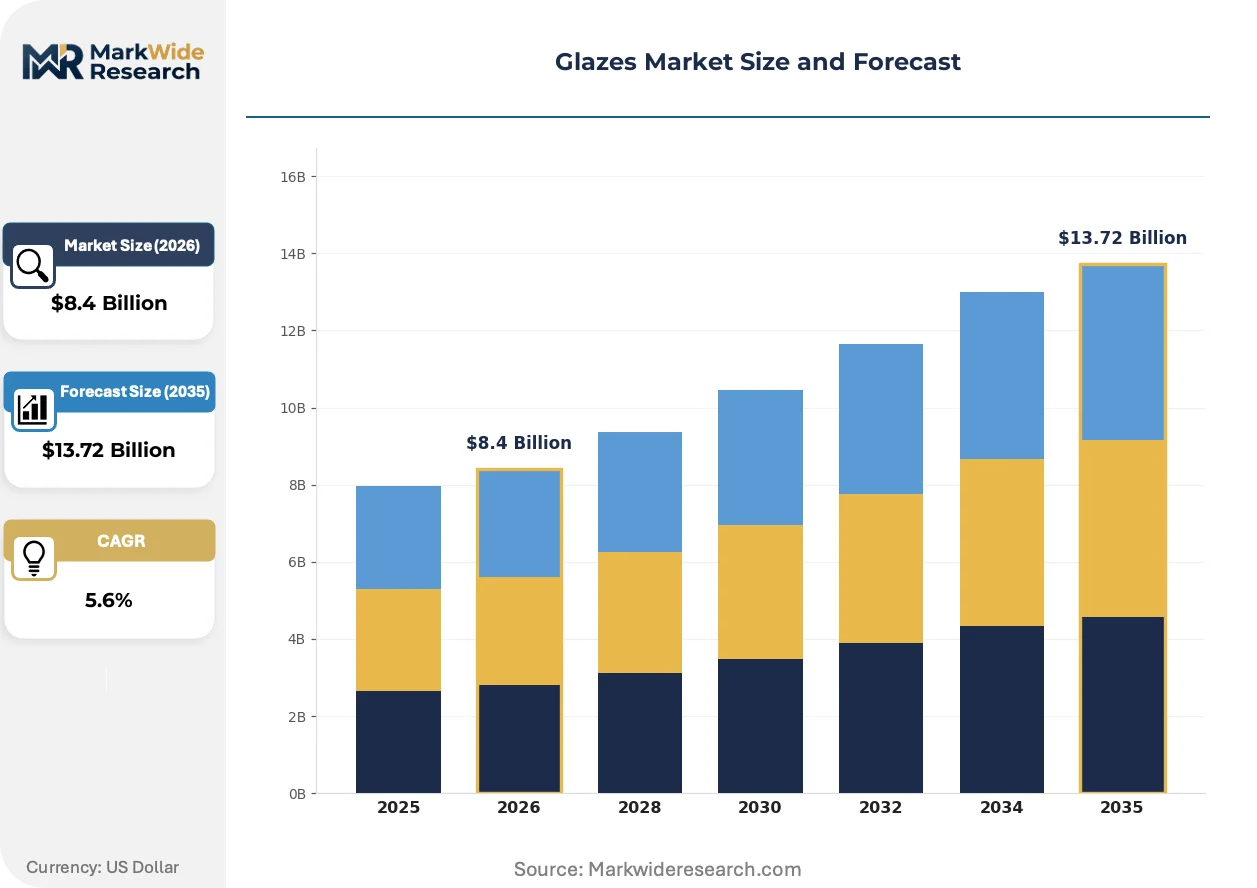
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.72 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
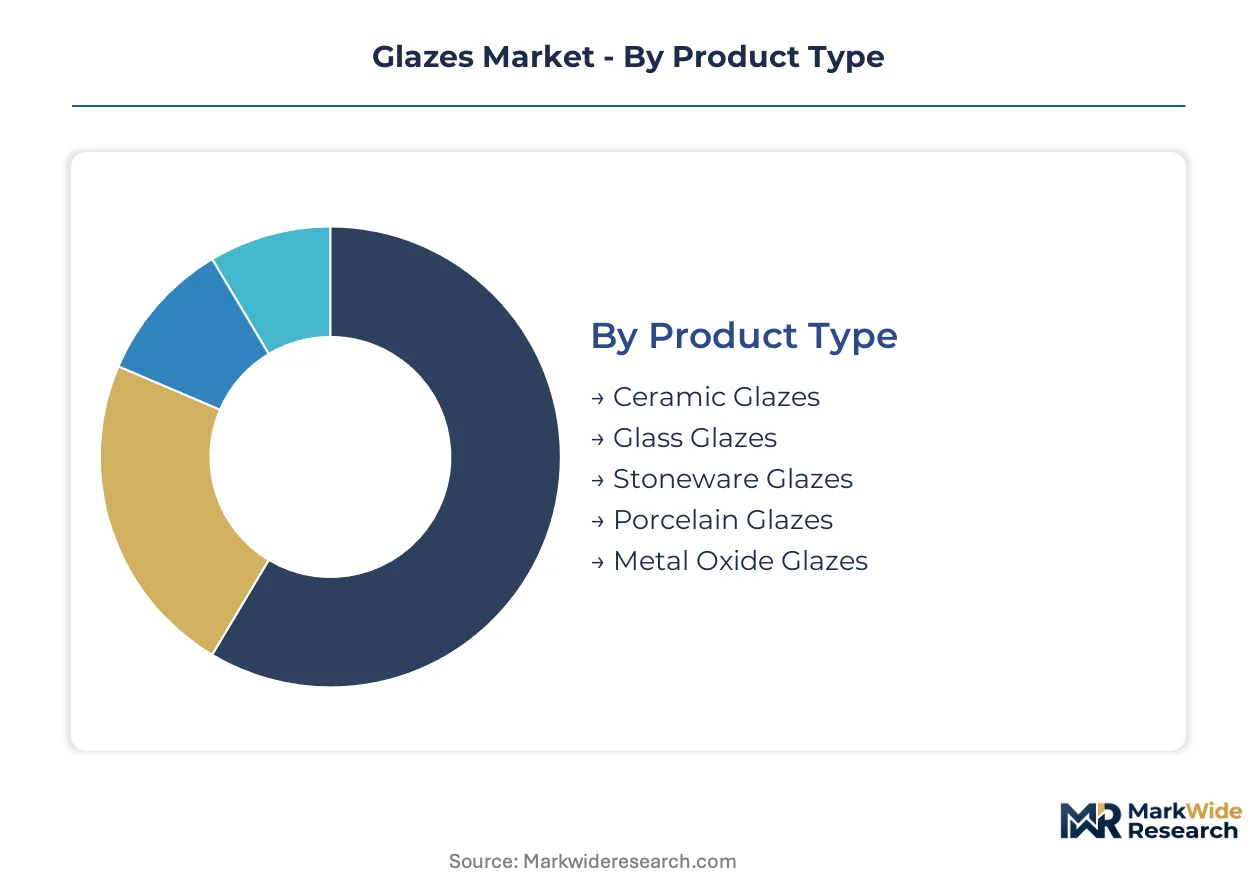
| Segmentation | Product Type: Ceramic Glazes, Glass Glazes, Stoneware Glazes, Porcelain Glazes, Metal Oxide Glazes Application: Architectural Surfaces, Pottery, Tableware, Decorative Tiles, Artisanal Craft End User: Ceramic Manufacturers, Construction Firms, Interior Designers, Artisans, Craft Studios Form: Powder, Liquid, Spray, Paste, Granular |
| Companies Covered | Saint-Gobain, AGC Inc., NSG Group, Guardian Industries, Corning Incorporated, Harmon Inc., Enclos Corp., Kerry Group plc, Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glazes Market Shifts & Advancements
Formulation chemistry and application automation are converging to reduce firing temperatures and material waste, while regulatory pressure on heavy metal content forces systematic reformulation of legacy colorant systems across all producing regions.
Water-based glaze suspensions with nano-scale particle distribution are overtaking solvent-based alternatives in automated spray lines. Italian tile manufacturers adopt these systems to eliminate volatile organic compound emissions during drying. The shift is overtaking conventional acrylic binder formulations in specification-grade architectural contracts where LEED points determine vendor selection.
China's GB standards for ceramic tableware safety impose tightening cadmium and lead migration limits that exceed prior export thresholds. Manufacturers serving European and North American markets must maintain dual inventory streams or accept reformulation costs. Small-batch pottery exporters in Fujian and Guangdong provinces face disproportionate compliance burdens as testing frequency increases.
Direct specification relationships between glaze suppliers and large construction firms are displacing traditional distributor intermediaries in commercial tile procurement. Contractors with multi-project portfolios negotiate volume commitments and technical service embeds directly with Saint-Gobain and comparable producers. This channel compression is most visible in United States healthcare and hospitality verticals where surface performance warranties carry liability weight.
Glazes Market Segmentation
Glaze procurement patterns diverge sharply across buyer archetypes, with construction firms prioritizing specification-grade certification while craft studios optimize for batch flexibility and color range. Understanding these segment boundaries clarifies where formulation R&D investments generate returns versus where cost-efficient supply consolidation wins.
Product Type:
Ceramic manufacturers select glaze chemistry based on firing temperature compatibility and surface performance warranties demanded by their end markets.
- Ceramic Glazes:Silica-flux formulations firing between 900°C and 1300°C create vitreous seals on earthenware and stoneware bodies. Construction firms in the United States drive specification-grade demand for architectural surfaces requiring frost resistance and stain immunity under LEED procurement protocols.
- Glass Glazes:Low-expansion borosilicate systems bond to float glass substrates for photovoltaic panel anti-reflective coatings and display cover applications. East Asian solar manufacturers anchor volume as module production capacity expands.
- Stoneware Glazes:High-flux feldspathic compositions vitrify at cone 6-10 temperatures for dense, durable tableware finishes. Small-batch pottery operations in North America sustain demand through direct e-commerce channels.
- Porcelain Glazes:Ultra-white, low-iron formulations achieve translucency in fine china and technical ceramic applications. European luxury tableware producers maintain premium positioning through cobalt-free blue colorant systems.
- Metal Oxide Glazes:Specialty pigment systems incorporating cobalt, chromium, and rare earth compounds deliver iridescent and crystalline surface effects. REACH registration requirements constrain European import and consolidate supply among incumbent dossier holders.
Ceramic glazes lead volumes today; glass glazes are gaining share fastest.
Application:
End-use specifications determine whether buyers prioritize chemical migration compliance, aesthetic customization, or mechanical durability.
- Architectural Surfaces:Large-format tile and facade panel producers require glazes with verified low-VOC credentials and recycled content percentages for LEED certification compliance. United States healthcare and hospitality verticals specify direct supplier relationships with embedded technical service.
- Tableware:Food-contact applications demand lead and cadmium migration testing under FDA thresholds in the United States and GB standards in China. Dual inventory maintenance burdens exporters serving multiple regulatory jurisdictions.
- Decorative Tiles:Pattern fidelity requirements moderate in commodity segments where digital ceramic printing systems threaten traditional glaze layer volumes. Italian manufacturers defend position through water-based nano-suspension formulations eliminating solvent emissions.
- Pottery:Functional ware and sculptural applications sustain powder glaze demand through manual mixing flexibility. Artisanal craft resurgence across Western Europe and North America bypasses traditional distributor networks.
- Artisanal Craft:Small-batch studios prioritize color range breadth and low minimum order quantities over unit economics. E-commerce platforms connect Fujian and Guangdong province exporters directly to individual craftspersons.
Architectural surfaces dominate revenue; artisanal craft is climbing the fastest.
End User:
Procurement scale and technical sophistication separate volume contract negotiators from spot purchasers.
- Ceramic Manufacturers:Automated tile production lines demand liquid glaze formulations compatible with spray application systems and rapid firing curves. Energy cost volatility in Italian ceramic districts erodes margin buffers for mid-tier producers.
- Construction Firms:Multi-project portfolio holders negotiate direct specification relationships with Saint-Gobain and comparable suppliers, compressing traditional distributor channels. Surface performance warranties carry liability weight in commercial contracts.
- Interior Designers:Specification influence concentrates in premium residential and boutique hospitality projects where custom color matching differentiates outcomes. Small order volumes limit supplier prioritization.
- Artisans:Individual craftspersons source powder glazes through direct-to-consumer channels for hand-building and wheel-throwing applications. Price sensitivity competes with colorant purity preferences.
- Craft Studios:Cooperative purchasing arrangements aggregate demand for shared kiln facilities and bulk glaze procurement. Community-based technical knowledge substitutes for formal ceramic engineering training.
Ceramic manufacturers lead volumes today; construction firms are gaining share fastest.
Form:
Material handling economics and application automation compatibility drive format selection.
- Liquid:Pre-mixed suspensions with nano-scale particle distribution enable spray line efficiency and eliminate silica dust exposure. Italian manufacturers adopt water-based systems to comply with tightening EPA air quality standards.
- Powder:Dry formulations retain cost advantages where manual mixing persists and automated lines remain uneconomical. China's construction sector drives specification-grade demand for decorative tile finishes.
- Spray:Aerosolized application systems dominate high-volume architectural tile production. OSHA silica exposure limits accelerate retrofit demand for pre-mixed alternatives.
- Paste:High-viscosity formulations support brush and dip application in studio pottery contexts. Limited shelf stability constrains distribution reach.
- Granular:Controlled particle size distributions enable specific surface texture effects in specialty architectural applications. Niche demand from restoration and heritage replication projects.
Liquid formulations lead volumes today; spray applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping glaze production geography as manufacturers relocate to jurisdictions with lower compliance burdens for heavy metal colorants and kiln emissions. Energy cost differentials and REACH registration friction in Europe accelerate capacity migration toward Asia-Pacific and North American production bases.
United States
LEED certification tightening drives specification-grade demand for low-VOC architectural glazes across commercial construction. EPA air quality standards and OSHA silica exposure limits force dry processing line retrofits, accelerating pre-mixed liquid formulation adoption. Italian and Spanish glaze exporters face margin compression serving this market amid transatlantic shipping cost volatility.
China
Construction firms in the Yangtze River Delta and Pearl River Delta drive volume demand for powder formulations in decorative tile finishes. GB standards for ceramic tableware safety impose tightening lead and cadmium migration limits that exceed prior export thresholds, forcing dual inventory maintenance for manufacturers serving European and North American markets. National dual carbon policy mandates favor low-temperature glaze formulations firing below 1000°C.
Italy
Energy-intensive kiln operations in the Sassuolo ceramic district confront natural gas cost spikes as European energy markets destabilize. REACH registration requirements for cobalt and chromium oxide colorants consolidate formulation choices among incumbent dossier holders. Water-based nano-suspension systems are displacing solvent-based alternatives in automated spray lines serving specification-grade architectural contracts.
India
Bureau of Indian Standards certification for frost-resistant architectural ceramics remains underpenetrated, creating first-mover advantage for glaze suppliers establishing local technical service presence. Construction acceleration in Maharashtra and Gujarat pulls demand for specification-grade surface finishes. Domestic ceramic manufacturers face raw material qualification gaps that favor imported formulation partnerships.
Japan
Photovoltaic manufacturing expansion across Kyushu and Kansai regions pulls specialty glass glaze capacity toward anti-reflective coating substrates for solar panel applications. METI industrial efficiency guidelines favor precision formulation control in automated production environments. Technical ceramic producers in the Nagoya corridor maintain premium positioning through ultra-low-iron porcelain glaze systems.
Glazes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent coating technologies and cross-sector formulation licensing. The vendor base stratifies across multinational mineral technology groups, regional ceramic specialists, and food-grade coating system providers. Three archetypes dominate: fused mineral technology leaders, photovoltaic glass glaze specialists, and controlled-release food coating innovators. Competitive moves concentrate on direct specification relationships with construction firms and cross-border technical service embeds.
Within the mineral technology tier, Saint-Gobain anchors European architectural glaze supply through fused mineral capabilities, while AGC Inc. represents East Asian specialization in photovoltaic and display glass applications. Kerry Group plc occupies the food-grade segment with controlled-release coating systems. These three exemplify how geographic origin and sector focus determine competitive positioning without requiring identical scale or integration depth.
| Leading Market Players |
|---|
| Saint-Gobain |
| AGC Inc. |
| NSG Group |
| Guardian Industries |
| Corning Incorporated |
| Harmon Inc. |
| Enclos Corp. |
| Kerry Group plc |
| Cargill, Incorporated |
| Others |
Supply & Pricing Matrix
LEED certification tightening across United States commercial construction is compressing supplier qualification timelines and forcing glaze manufacturers to absorb compliance costs or risk contract exclusion, which in turn concentrates pricing power among incumbent dossier holders with verified low-VOC credentials.
Pricing Analysis
Distributor margin compression dominates as construction firms with multi-project portfolios negotiate direct specification relationships with Saint-Gobain and comparable mineral technology groups. Three-tier pricing structure across specification-grade, standard commercial, and economy levels reflects certification burden and technical service embed intensity. Cost compression in mid-tier ceramic glaze production is intensifying because Italian and Spanish manufacturers face natural gas cost spikes without pricing power to pass through energy volatility. Artisanal craft studios exhibit highest price sensitivity due to small-batch economics, while photovoltaic glass glaze buyers prioritize transmission performance over unit cost.
Supply Chain Analysis
Demographic shifts in ceramic engineering programs constrain skilled technician availability for pyrometric cone calibration across Italian Sassuolo and Spanish Castellón manufacturing clusters. Supply concentrates in China, Italy, and Spain for ceramic glazes, with East Asian capacity expanding fastest for photovoltaic glass applications. Raw material sourcing draws from feldspathic mineral deposits, cobalt and chromium oxide colorant suppliers, and borosilicate glass precursor streams. Single-source vulnerability sits with REACH-registered cobalt compound dossier holders in Europe. Distribution runs through direct specification channels in United States healthcare and hospitality verticals, traditional distributor networks in artisanal craft segments, and e-commerce platforms connecting Fujian exporters to individual craftspersons.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on flux chemistry optimization enabling low-temperature firing below 1000°C under China's dual carbon mandates, plus premium-tier positioning through cobalt-free colorant systems in European luxury tableware.
For Market Incumbents: Extend technical service embeds into United States healthcare and hospitality construction firms to defend against channel compression, while accelerating backward integration into feldspathic mineral sourcing to offset raw material qualification gaps in emerging markets. Digital ceramic printing systems threaten commodity tile glaze volumes; counter through water-based nano-suspension formulation leadership that eliminates VOC emissions and captures LEED-driven specification demand. For New Entrants and Emerging Players: Direct-to-craftsperson e-commerce routes offer lowest barrier entry into North American and Western European artisanal pottery segments, where powder glaze demand sustains through manual mixing flexibility. Target India construction acceleration by establishing local technical service presence ahead of Bureau of Indian Standards certification penetration for frost-resistant architectural ceramics. Cross-sector licensing of controlled-release coating technology from pharmaceutical into premium confectionery applications opens adjacent revenue streams without capital-intensive kiln infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with regional ceramic specialists possessing REACH-registered colorant dossiers and established distributor relationships in underpenetrated certification markets. Long-term viability favors assets with demonstrated flux chemistry R&D pipelines capable of sub-1000°C formulations. Acquisition target archetype: mid-tier Italian or Spanish producers with energy-efficient kiln retrofit plans and existing specification-grade customer relationships. The inflection signal to watch is Bureau of Indian Standards enforcement acceleration triggering import substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Temperature Formulation R&D | Dual carbon policy compliance in China rewards sub-1000°C firing chemistry investments. |
| Direct Specification Relationships | Construction firm channel compression in United States healthcare verticals eliminates distributor margin capture. |
| REACH Dossier Acquisition | Cobalt and chromium oxide registration consolidation protects European market access against new entrant competition. |
| Technical Service Localization | India frost-resistant certification gaps favor first-mover embeds in Maharashtra and Gujarat construction clusters. |
| Cross-Sector Coating Licensing | Pharmaceutical controlled-release technology migration into confectionery opens premium food-grade glaze revenue. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ceramic plant managers, construction firm procurement leads, artisan studio owners, and specialty chemical distribution channel partners with secondary validation through customs trade data, SEC filings from listed mineral technology groups, Italian ceramic district association reports, and China GB standards documentation. Bottom-up demand modeling across tile production volumes and top-down macroeconomic triangulation anchored value estimates.
Segment-weighting approaches distributed projections across product type, application, end user, and form dimensions, with additional granularity for firing temperature tier and certification level. CAGRs were derived through regression analysis of historical production data against construction sector output indicators and photovoltaic manufacturing capacity announcements across the analysis window. Key inputs included natural gas price volatility assumptions for European kiln operations and REACH registration timeline friction for cobalt compound imports.
The model assumes a particular technology adoption path; alternative pathways for digital ceramic printing surface decoration would alter the outlook by compressing traditional glaze layer demand in commodity tile segments. Forecasts reflect underlying assumptions about LEED certification penetration rates, dual carbon policy enforcement intensity, and artisanal craft e-commerce channel expansion. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Wood Protection Coating Market
Coatings
Global Anti-Corrosion Coating Market
Coatings
Textile Coatings Market
Coatings
Marine Nanocoating Market
Coatings
Water Based Enamel Market
Coatings
Hydrophilic Coatings Market
Coatings
Fluid Bed and Coating System Market
Coatings
Packaging Coatings Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Self-Healing Microcapsule Systems for Protective Coatings Market
Coatings
Global Cellulosic Fire Protection Intumescent Coatings Market
Coatings
Leisure Boat Marine Coatings Market
Coatings
Diamond-Like Carbon Coatings Market
Coatings
Acrylic Coating Market
Coatings
Ultraviolet (UV) Coatings Market
Coatings
Electrocoat Market