
 North America Anti-Friction Coatings Market | 2026-2036
North America Anti-Friction Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
North America Anti-Friction Coatings Market Analytics
EPA Tier 3 vehicle emission standards is rebalancing the cost-of-entry calculus for coating suppliers serving powertrain applications. DuPont leverages its fluoropolymer heritage to sustain formulation leadership in high-temperature engine environments. PPG Industries anchors North American supply through integrated resin-to-coating manufacturing networks. Axalta Coating Systems competes on automotive OEM channel control with dedicated technical service laboratories across the Midwest and Ontario.
North America anti-friction coatings comprise bonded solid lubricant films—typically PTFE, molybdenum disulfide, or graphite dispersed in thermosetting resin matrices at film thicknesses of 5–50 micrometers—engineered to reduce coefficient of friction below 0.10 in metal-to-metal contact zones without liquid lubrication. Dry film formulations dominate aerospace landing gear and fastener applications where vacuum stability and extreme temperature cycling prevent oil-based alternatives. Liquid coating technology leads industrial machinery maintenance channels due to brush and spray retrofit accessibility, while powder coating gains share in automotive OEM lines seeking zero-VOC compliance and automated reclaim systems.
EPA, NHTSA, and OSHA collectively shape product chemistry, application safety protocols, and end-use qualification pathways across the United States. Canada’s PMRA and Environment and Climate Change Canada impose parallel substance restrictions that force cross-border formulation harmonization. Stakeholders must monitor evolving PFAS regulatory thresholds in both jurisdictions to anticipate reformulation timelines and raw material substitution requirements.
Market Dynamics
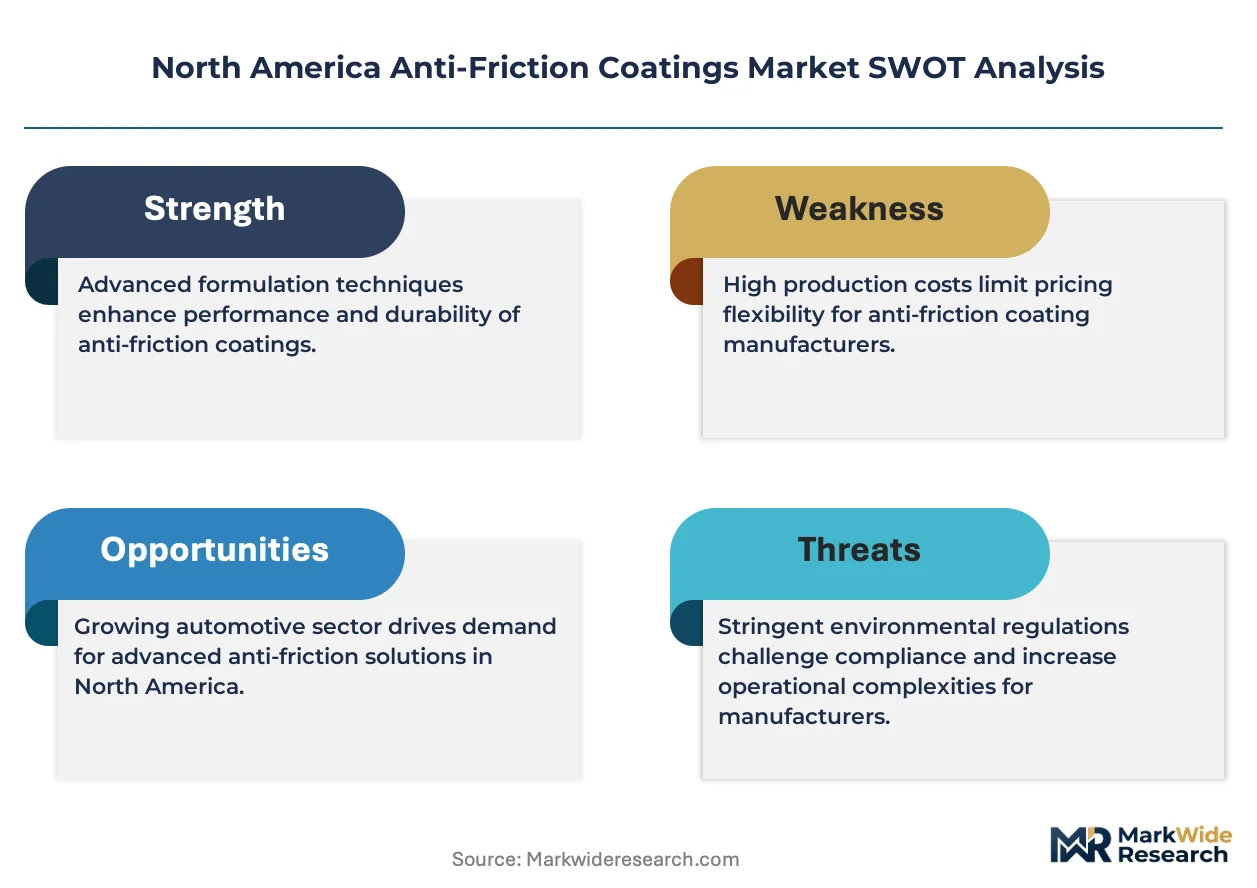
PFAS regulatory thresholds in the United States and Canada are forcing simultaneous reformulation across bonded solid lubricant portfolios, compressing supplier R&D timelines while expanding qualification requirements for powertrain and aerospace applications.
Growth Catalysts
- EPA Tier 3 Emission Standards:Tightening lubrication system requirements for fuel economy are expanding dry film coating specifications across Michigan and Ohio automotive OEM supply chains.
- Graphite-Molybdenum Disulfide Hybrids:Next-generation solid lubricant dispersions are penetrating aerospace fastener applications where vacuum stability and thermal cycling resistance outperform legacy PTFE formulations.
- Great Lakes Manufacturing Corridor:Concentrated demand from Ontario, Michigan, and Ohio powertrain assembly plants is creating procurement scale sufficient to justify dedicated coating facility investments.
Market Restraints
- Fluoropolymer Feedstock Concentration:Limited domestic production of high-purity PTFE resins creates import dependency on Asian fluorochemical suppliers, exposing formulators to tariff and shipping cost volatility.
- PFAS Regulatory Friction:Evolving EPA and PMRA substance restriction thresholds force parallel compliance investments without harmonized testing protocols, duplicating certification expenditures.
- Ceramic Coating Substitution:Thermal spray ceramic alternatives are capturing select high-temperature engine applications where dry film thickness limitations compromise durability.
Strategic Opportunities
- Mexico Automotive Assembly Expansion:OEM plant construction in Guanajuato and Nuevo León is extending the Great Lakes supply chain southward, creating demand for localized coating application services.
- OSHA Process Safety Modernization:Updated workplace exposure standards for hexavalent chromium and volatile organic compounds are accelerating zero-VOC powder coating adoption in maintenance channels.
- Digital-Physical Convergence:Integration of automated spray robotics with real-time film thickness monitoring is enabling closed-loop quality control in high-volume OEM lines.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in thermosetting resin matrix optimization and solid lubricant dispersion stability is concentrated among retiring practitioners with limited pipeline replacement.
- Dual-Jurisdiction Certification Burden:Separate EPA and PMRA approval pathways for new coating chemistries extend commercialization timelines by 18-24 months versus single-market launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Anti-Friction Coatings Market |
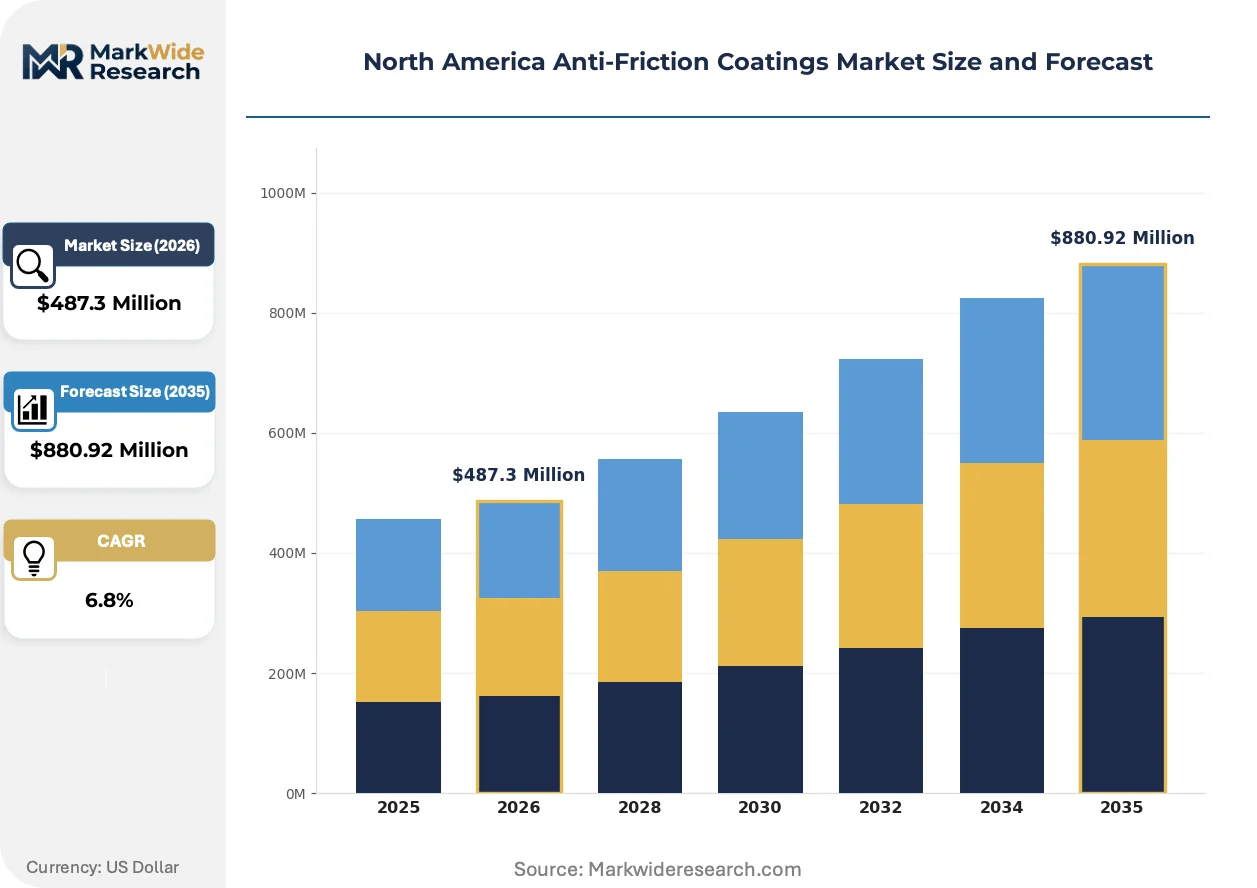
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Film, Liquid Coating, Powder Coating, Solid Film End User: Aerospace, Automotive OEMs, Marine, Industrial Machinery Application: Bearings, Gears, Cylinders, Sliding Surfaces Technology: Spray Coating, Electroplating, Dip Coating, Brush Application |
| Companies Covered | DuPont, PPG Industries, The Sherwin-Williams Company, Axalta Coating Systems, 3M Company, Akzo Nobel, Endura Coatings, Carl Bechem GmbH, Whitford Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Anti-Friction Coatings Market Evolving Landscape
Active reformulation of fluoropolymer-based coatings is compressing product development cycles while expanding the addressable application set beyond traditional aerospace and automotive boundaries.
Thermal-cured PTFE-molybdenum disulfide composite films are electrifying powertrain assembly specifications. Tier 1 suppliers in Michigan and Ohio are adopting these hybrids for transmission synchronizer rings and piston skirt applications at accelerated qualification pace. This convergence of solid lubricant technologies is electrifying supplier technical service requirements, forcing coating formulators to embed application engineering teams directly within OEM manufacturing facilities.
EPA's evolving PFAS reporting obligations under TSCA Section 8(a)(7) are reshaping raw material sourcing protocols. Industrial coating formulators must now document fluoropolymer content across supply tiers, triggering pre-emptive substitution of PTFE with graphite-ceramic alternatives in select industrial maintenance channels. The impact concentrates in Ohio and Ontario machinery rebuild shops where legacy inventory faces accelerated write-down risk.
Specification consolidation among Detroit Three automakers is narrowing approved coating vendor lists. Tier 1 powertrain suppliers now face consolidated procurement through centralized commodity managers, displacing fragmented plant-level purchasing. This concentration is most visible in southeastern Michigan, where transmission and engine assembly plants have standardized on two primary dry film specifications across all platforms.
North America Anti-Friction Coatings Market Segmentation
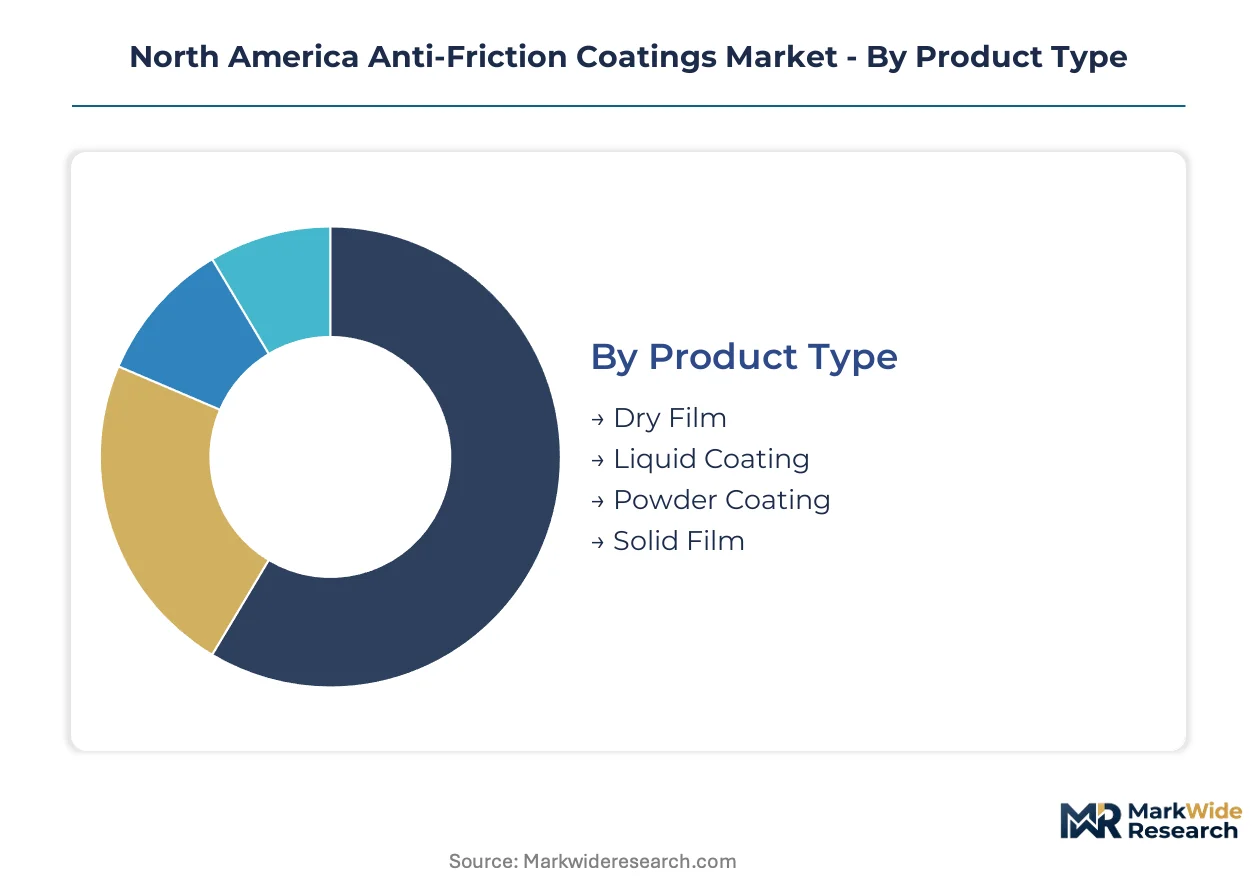
Segmentation in the North America anti-friction coatings market reveals distinct technology-performance tradeoffs across formulation chemistries, application methods, and end-use specifications. Understanding these divides enables suppliers to align R&D investments with the tightening regulatory and qualification requirements shaping procurement decisions in Michigan, Ohio, and Ontario manufacturing corridors.
Product Type:
Formulation chemistry dictates thermal ceiling, film thickness range, and VOC compliance profile across bonded solid lubricant portfolios.
- Dry Film:PTFE, molybdenum disulfide, or graphite dispersions in thermosetting resin matrices cure to 5–50 micrometer films with coefficients of friction below 0.10. Demand concentrates in aerospace landing gear and powertrain assemblies across Ohio and Michigan where vacuum stability and extreme temperature cycling prevent liquid lubrication alternatives.
- Liquid Coating:Solvent-borne and water-borne formulations enable brush and spray retrofit accessibility in industrial machinery maintenance channels. Ohio and Ontario machinery rebuild shops favor these for field application flexibility, though EPA VOC regulations and OSHA hexavalent chromium exposure standards are accelerating substitution toward compliant alternatives.
- Powder Coating:Zero-VOC thermoset powders with integrated solid lubricants support automated reclaim systems in high-volume automotive OEM lines. NHTSA fuel economy rules tightening lubrication system requirements are expanding specifications for transmission and engine components in southeastern Michigan assembly plants.
- Solid Film:Pre-cured bonded lubricant tapes and sheets provide precise thickness control for specialty fastener and bearing applications where spray application is impractical.
Dry film leads on scale; powder coating leads on momentum.
End User:
Customer concentration patterns follow the Great Lakes manufacturing corridor's industrial geography and regulatory exposure profile.
- Automotive OEMs:Detroit Three powertrain specifications dominate procurement volume, with Tier 1 suppliers in Michigan and Ohio consolidating vendor lists around two primary dry film standards. EPA Tier 3 emission standards and NHTSA fuel economy rules are expanding coating specifications for transmission synchronizer rings and piston skirt applications.
- Aerospace:Landing gear, fastener, and actuator applications demand vacuum-stable formulations resistant to extreme temperature cycling. Graphite-molybdenum disulfide hybrids are penetrating this segment where thermal performance requirements exceed legacy PTFE capabilities.
- Industrial Machinery:Maintenance and rebuild channels across Ohio and Ontario favor liquid coating accessibility, though PMRA and EPA PFAS reporting obligations are triggering pre-emptive reformulation away from fluoropolymer-based inventories.
- Marine:Corrosion-resistant solid lubricant specifications address saltwater exposure in propulsion and deck equipment, with procurement concentrated in Gulf Coast and Atlantic seaboard shipyards.
Automotive OEMs anchor volume concentration; aerospace commands premium qualification requirements.
Application:
Component geometry and contact mechanics determine film thickness specifications and lubrication regime selection.
- Bearings:Rolling and sliding contact applications require sub-10 micrometer films with embedded solid lubricant particles to prevent cage wear and reduce starting torque in Michigan and Ohio transmission assembly plants.
- Gears:Mesh contact zones demand thicker films with enhanced wear debris entrapment, particularly in aerospace gearbox applications where maintenance access is limited.
- Cylinders:Piston skirt and liner coatings in internal combustion engines balance scuff resistance with oil retention compatibility; thermal-cured PTFE-molybdenum disulfide composites are electrifying specifications here.
- Sliding Surfaces:Linear guide and cam follower applications prioritize low breakaway friction and stick-slip elimination in automated manufacturing equipment across Ontario precision machining facilities.
Bearings represent the dominant addressable surface area; cylinders exhibit the steepest specification upgrade trajectory.
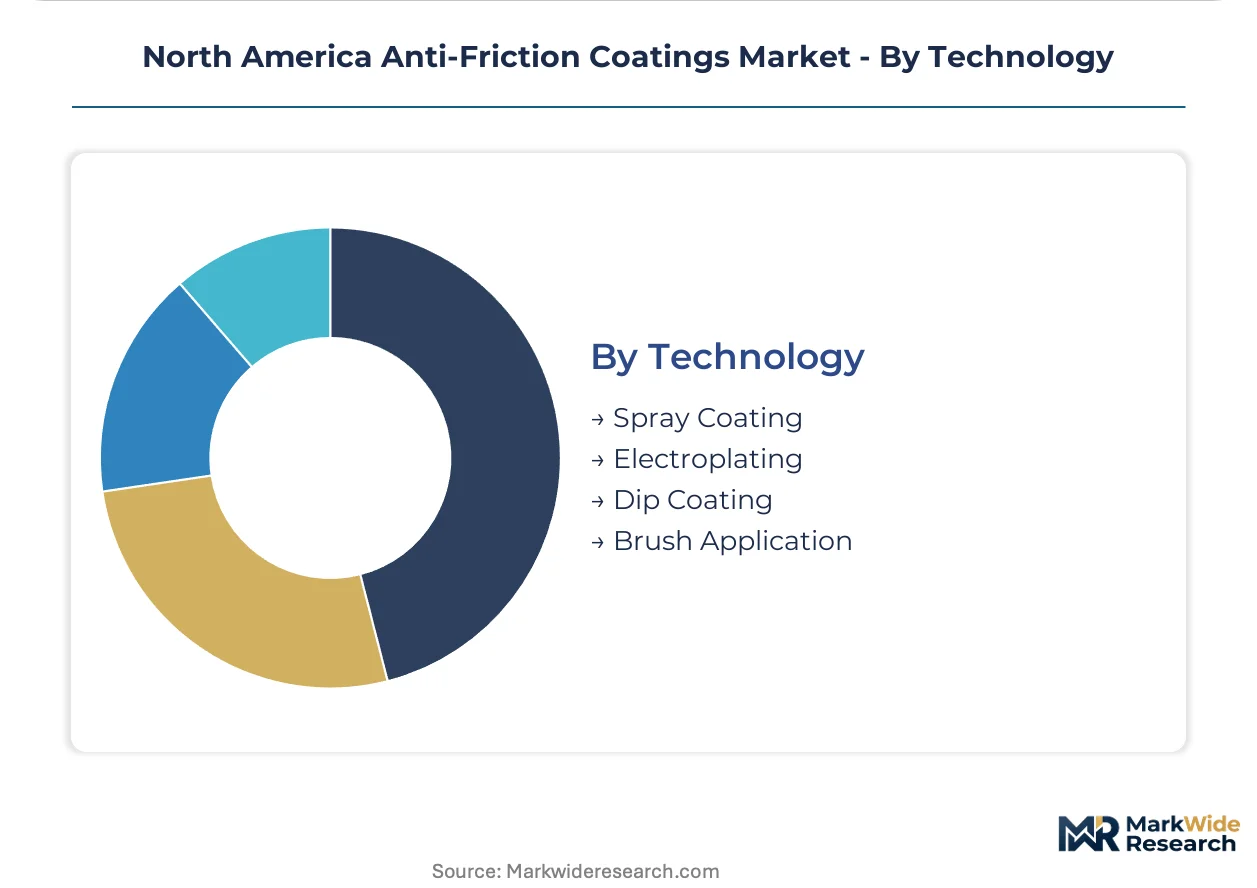
Technology:
Application method selection hinges on part geometry complexity, volume scale, and regulatory constraints on workplace exposure.
- Spray Coating:Airless and electrostatic spray systems dominate OEM production lines, with automated robotics integration enabling real-time film thickness monitoring for closed-loop quality control in high-volume Michigan transmission plants.
- Dip Coating:Immersion methods ensure complete coverage of complex geometries like bearing cages and gear interiors, with drain-controlled film thickness management.
- Brush Application:Manual methods persist in maintenance channels and prototype development, constrained by OSHA process safety modernization requirements for hexavalent chromium and VOC exposure.
- Electroplating:Composite plating with co-deposited solid lubricant particles addresses extreme load-bearing requirements in aerospace fastener specifications where bonded films would delaminate.
Spray coating commands production volume leadership; electroplating holds the most defensible niche in extreme-duty specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists with expertise in thermosetting resin matrix optimization cluster in the Great Lakes industrial corridor, anchoring North American technical capability for bonded solid lubricant development.
United States
EPA Tier 3 emission standards and NHTSA fuel economy rules are tightening lubrication system specifications for Michigan and Ohio powertrain assembly plants. OSHA process safety modernization for hexavalent chromium exposure accelerates zero-VOC powder coating adoption in maintenance channels. Southeastern Michigan transmission and engine plants have consolidated procurement around two primary dry film specifications across all platforms.
Canada
PMRA substance restrictions and Environment and Climate Change Canada PFAS thresholds force cross-border formulation harmonization with US suppliers. Ontario machinery rebuild shops face accelerated inventory write-down risk as fluoropolymer-based coatings trigger pre-emptive substitution. The Windsor-Toronto manufacturing corridor concentrates aerospace fastener demand requiring vacuum-stable formulations.
Mexico
OEM plant construction in Guanajuato and Nuevo León extends the Great Lakes supply chain southward, creating demand for localized coating application services. Mexican federal environmental regulations under SEMARNAT align with US EPA VOC standards for automotive production facilities. The Bajío region's expanding transmission assembly capacity requires technical service laboratory proximity for qualification support.
North America Anti-Friction Coatings Market Competitive Landscape
The competitive structure tilts toward integrated resin-to-coating manufacturers with captive fluoropolymer supply chains. Three to five multinational chemical conglomerates dominate high-volume automotive OEM specifications through centralized commodity management, while specialized dry film formulators defend niche aerospace and industrial maintenance positions. Strategic archetypes include integrated chemical majors, dedicated coating systems specialists, and regional application service providers. Capacity expansion in Mexico and portfolio diversification away from PTFE-based formulations represent the dominant competitive moves.
Within the integrated chemical major tier, DuPont leverages its fluoropolymer heritage to sustain formulation leadership, while PPG Industries anchors North American supply through resin-to-coating manufacturing networks. Axalta Coating Systems occupies a position competing on automotive OEM channel control with dedicated technical service laboratories across the Midwest and Ontario. These three exemplify the scale and qualification depth required for Tier 1 powertrain procurement consolidation.
| Leading Market Players |
|---|
| DuPont |
| PPG Industries |
| The Sherwin-Williams Company |
| Axalta Coating Systems |
| 3M Company |
| Akzo Nobel |
| Endura Coatings |
| Carl Bechem GmbH |
| Whitford Corporation |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up coating specialists have consolidated regional application service networks across the Great Lakes corridor, tightening pricing discipline while locking in multi-year procurement contracts with Detroit Three powertrain suppliers. This ownership concentration feeds directly into supply behavior: captive resin-to-coating manufacturing networks anchor cost structures, while centralized commodity management at Tier 1 suppliers limits spot-market pricing volatility.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning across the North American anti-friction coatings market. Three-tier pricing structure across premium, standard, and economy levels reflects qualification depth: aerospace-grade PTFE-molybdenum disulfide composites command premium positioning due to NADCAP certification requirements, while industrial maintenance channels compete on per-liter transactional pricing for liquid formulations. Cost compression in standard-tier powder coatings is intensifying because Mexican OEM plant construction is extending qualified supplier lists southward. Automotive OEM procurement teams exhibit the highest price sensitivity, driven by consolidated vendor lists and platform standardization mandates, whereas aerospace fastener specifications tolerate premium pricing for vacuum-stable formulations.
Supply Chain Analysis
Dual-sourcing requirements mandated by Detroit Three powertrain procurement teams have reshaped supplier qualification protocols across Michigan and Ohio assembly plants. High-purity PTFE resin supply concentrates in China, Japan, and the United States, with limited domestic fluoropolymer production creating import dependency for specialized formulations. Raw material portfolios draw from fluorochemical feedstocks, thermosetting resin matrices, and solid lubricant dispersions including graphite and molybdenum disulfide. Tariff exposure on Asian fluorochemical imports represents the dominant structural risk, compounded by EPA PFAS reporting obligations under TSCA Section 8(a)(7) that trigger pre-emptive inventory substitution. Distribution runs through integrated coating systems specialists with captive technical service laboratories, direct OEM supply agreements, and regional application service providers serving maintenance channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on reformulation-driven cost reduction: graphite-ceramic alternatives to PTFE-based systems are collapsing raw material input costs while maintaining qualification thresholds for select industrial applications.
For Market Incumbents: Extend formulation leadership into PFAS-compliant chemistries before regulatory thresholds harden, locking in requalification timelines with Detroit Three powertrain procurement teams. Backward integration into fluoropolymer resin production—where feasible—defends margin position against Asian feedstock tariff volatility. Prioritize technical service laboratory expansion in Guanajuato to capture Mexican automotive assembly demand.
For New Entrants and Emerging Players: The price-point gap between premium aerospace-grade specifications and economy-tier industrial maintenance coatings offers white-space entry. Target Ohio and Ontario machinery rebuild shops facing accelerated fluoropolymer inventory write-down risk, where brush-applied liquid coating substitution demand is concentrating. Pursue private-label partnerships with regional distribution networks rather than direct OEM qualification.
For Investors and Strategic Acquirers: Integrated chemical majors are the most active acquirer in this space, seeking captive fluoropolymer supply and automotive OEM channel control. The five-to-ten-year viability window favors targets with established PMRA-EPA dual-jurisdiction certification pathways and embedded technical service teams. Monitor PFAS regulatory threshold evolution as the critical inflection signal: accelerated restriction timelines would compress valuation multiples for PTFE-dependent portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Compliant Reformulation | EPA and PMRA substance restrictions are forcing pre-emptive chemistry substitution across bonded solid lubricant portfolios. |
| Technical Service Laboratory Expansion | Mexican OEM plant construction in Guanajuato requires localized qualification support for transmission assembly applications. |
| Backward Integration into Resin Production | Captive fluoropolymer supply reduces tariff exposure on Asian high-purity PTFE feedstock imports. |
| Automated Spray Robotics Deployment | Real-time film thickness monitoring enables closed-loop quality control in high-volume Michigan powertrain lines. |
| Dual-Jurisdiction Certification Investment | Parallel EPA and PMRA approval pathways extend commercialization timelines by 18-24 months without harmonized investment. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national regulatory jurisdiction and manufacturing cluster. The analysis combines structured interviews with coating formulator R&D directors, Tier 1 automotive supplier procurement leads, aerospace fastener specification engineers, and industrial machinery maintenance channel distributors with secondary validation. Data sources include EPA TSCA filings, PMRA substance restriction notices, SEC 10-K disclosures from integrated chemical majors, customs trade data on fluoropolymer resin imports, and automotive production databases tracking Michigan and Ohio assembly plant volumes. Bottom-up coating consumption estimates triangulate against top-down market sizing derived from resin production and application equipment deployment patterns.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including formulation chemistry, application method, end-use industry, and regional production hub. CAGRs derive from fitted growth curves calibrated to historical qualification timelines, regulatory implementation schedules, and OEM platform lifecycle transitions. Industry-specific inputs include PFAS regulatory threshold evolution scenarios and Detroit Three powertrain specification consolidation patterns.
The model assumes a particular technology adoption path; alternative pathways for graphite-ceramic substitution would alter the outlook if qualification pace accelerates beyond baseline assumptions. Deviation in EPA PFAS restriction timelines or NHTSA fuel economy rule implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Compound Coating Market
Coatings
Global Solar Panel Coatings Market
Coatings
Japan Automotive OEM Coatings Market
Coatings
North America Coil Coatings Market
Coatings
Global Radiation Cured Coatings Market
Coatings
PU Coatings Market
Coatings
Global Wood Protection Coating Market
Coatings
Electrical Appliance Coatings Market
Coatings
Thermal Barrier Coatings Market
Coatings
Mexico Protective Coatings Market
Coatings
Mexico Floor Coatings Market
Coatings
Wood Preservative Coatings Market
Coatings
Coating Market
Coatings
Global Fluorinated Ethylene Propylene (FEP) Coatings Market
Coatings
Global Low Friction Coatings Market
Coatings
Extrusion Coating Market