
 Global Flat Steel Market | 2026-2036
Global Flat Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flat Steel Market Foresight
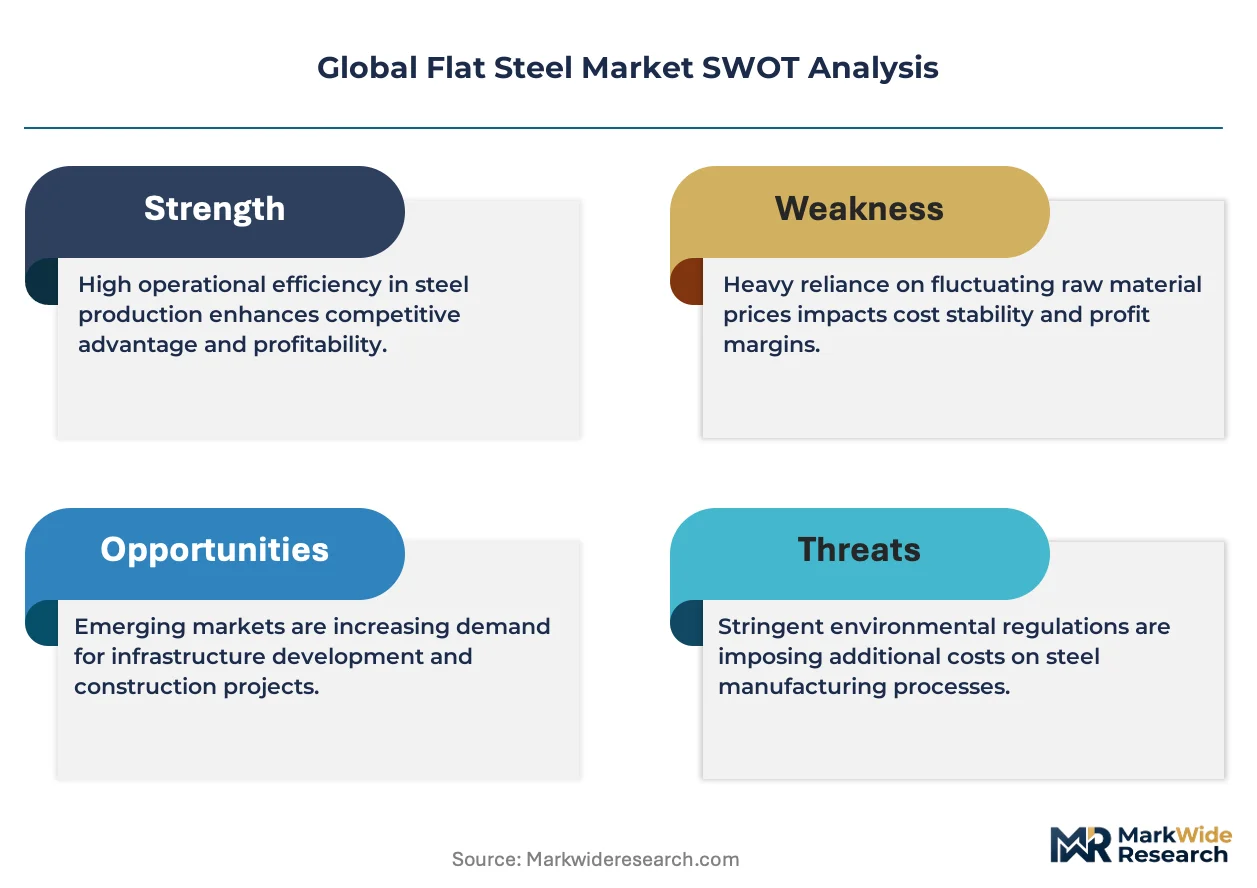
Project finance tied to green hydrogen-ready blast furnace retrofits is tilting capital requirements toward integrated producers with balance-sheet depth. ArcelorMittal leverages its European green steel project pipeline to anchor low-carbon flat product supply. POSCO sustains dominance in advanced high-strength automotive grades through dedicated R&D centers in South Korea. China Baowu Group controls the largest crude steel capacity globally and extends this into captive hot-rolled coil supply for domestic appliance manufacturers.
Flat steel comprises rolled sheet and plate products typically under 6 mm thickness, produced through continuous casting followed by hot or cold reduction, with surface finishes including galvanization or pre-painting for corrosion resistance. Its primary purpose spans structural fabrication, automotive body-in-white assemblies, and appliance enclosures where dimensional precision and surface quality govern performance. Hot rolled coil occupies the volume base across construction and heavy machinery, while cold rolled and galvanized grades command margin concentration in automotive OEM and premium appliance contracts. The electric arc furnace segment is gaining structural share as scrap availability improves and carbon accounting tightens, though blast furnace-basic oxygen furnace routes still lead in ultra-low-carbon steel for automotive exposed panels.
The US EPA and OSHA frameworks govern emissions and workplace exposure limits at integrated mills, while the EU Green Deal and F-Gas Regulation shape product-level carbon intensity thresholds that determine market access for imported coil. China's MEE enforces dual carbon compliance timelines that are forcing capacity consolidation and process switching. Stakeholders must monitor hydrogen-based direct reduction pilot outcomes and their implications for capital allocation across integrated versus mini-mill configurations.
Market Dynamics
China's MIIT dual carbon enforcement is forcing a process switch from blast furnace-basic oxygen furnace routes toward scrap-fed electric arc furnaces, rewiring capital allocation and supplier qualification criteria across the value chain.
Growth Catalysts
- Automotive lightweighting mandates:Germany and Japan OEMs are accelerating advanced high-strength steel consumption in body-in-white assemblies to meet fleet emission standards.
- India's PLI scheme for specialty steel:Domestic procurement patterns are redirecting toward local mills, creating captive demand for flat products in infrastructure and appliance manufacturing.
- Green hydrogen pilot scaling:Direct reduction iron trials using hydrogen feedstock are attracting project finance for blast furnace retrofits in European integrated mills.
Market Restraints
- Iron ore and coking coal price volatility:Input cost swings compress margin predictability for blast furnace operators, favoring scrap-based producers where feasible.
- Chinese capacity concentration risk:China Baowu Group and state-controlled mills control dominant crude steel output, creating supply-side leverage over global hot-rolled coil pricing.
- Aluminum substitution in automotive panels:Premium EV architectures are specifying aluminum for hood and door skins, displacing ultra-low-carbon exposed steel grades in certain OEM programs.
Strategic Opportunities
- Underpenetrated Indian flat steel per capita consumption:Infrastructure build-out and urban housing stock expansion offer structural volume growth for domestic and import supply.
- EU Green Deal carbon border adjustment mechanism:Embedded emissions accounting creates a regulatory tailwind for low-carbon steel producers qualifying for premium import access.
- Pre-painted coil direct-to-appliance OEM supply:Bypassing traditional service center intermediaries shortens lead times and captures margin in refrigerator and washing machine enclosure contracts.
Industry Challenges
- Electric arc furnace metallurgical skill scarcity:Scrap chemistry control and residual element management require specialized furnace operators, constraining workforce scalability for route conversions.
- Blast furnace retrofit capex intensity:Hydrogen-ready tuyere injection and carbon capture integration demand balance-sheet depth that fragments project execution capability among integrated producers.
- Automotive OEM qualification timeline compression:Advanced high-strength grade approval cycles stretch 18-24 months, mismatching capital deployment with contract award windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flat Steel Market |
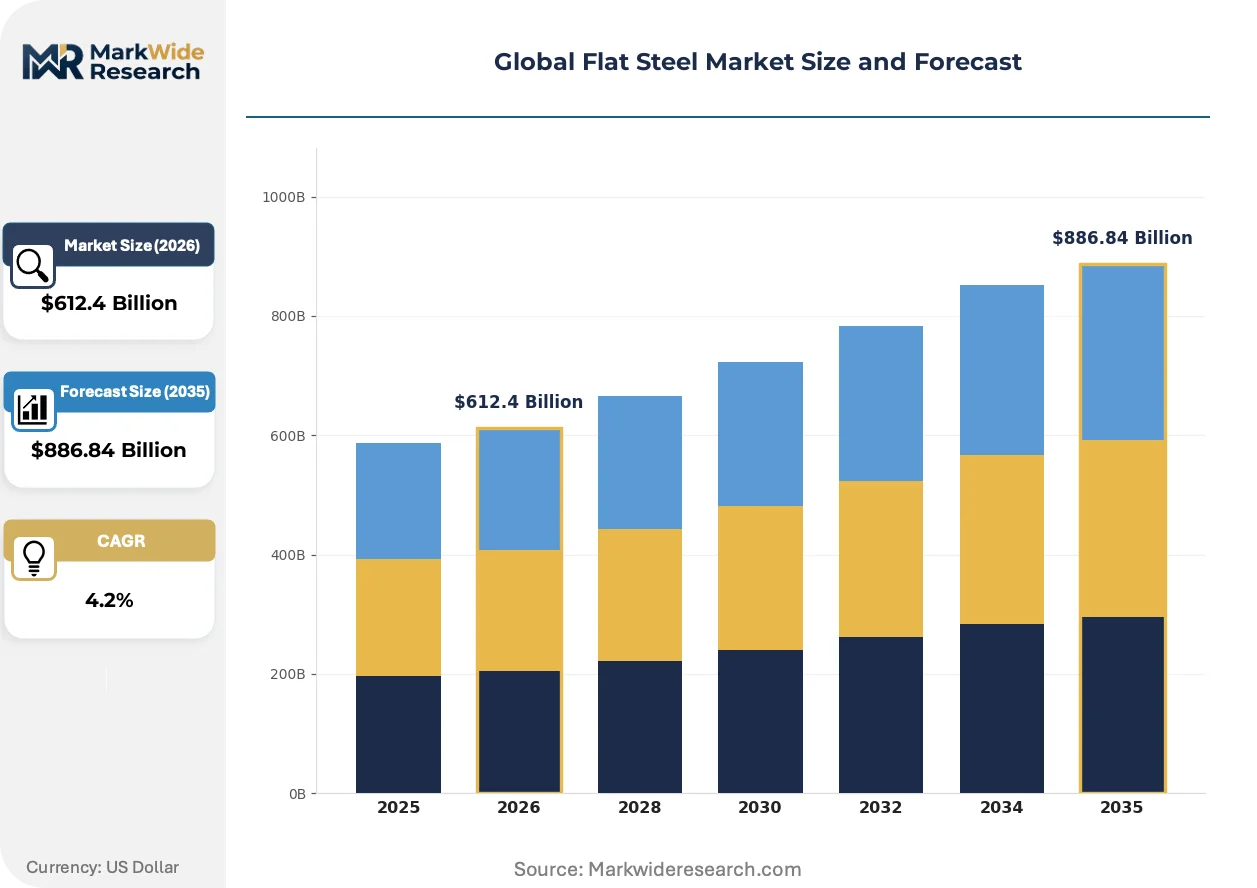
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $886.84 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Rolled, Cold Rolled, Galvanized, Electrolytic, Pre-painted Application: Construction, Shipbuilding, Household Appliances, Packaging, Transportation End User Industry: Aerospace, Heavy Machinery, Electrical, Consumer Electronics, Infrastructure Manufacturing Process: Continuous Casting, Blast Furnace, Electric Arc Furnace, Basic Oxygen Furnace |
| Companies Covered | Tata Steel Limited, JFE Steel Corporation, ArcelorMittal, United States Steel Corporation, ThyssenKrupp AG, Nippon Steel Corporation, China Baowu Group, Ansteel Group Corporation, POSCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flat Steel Market Shifts & Advancements
Hydrogen-based direct reduction and digital twin process control are collapsing the cost gap between low-carbon and conventional steel production, while regulatory carbon accounting is embedding emissions transparency into procurement specifications.
Direct reduction iron using green hydrogen feedstock is collapsing the carbon intensity differential between scrap-based electric arc furnace output and traditional blast furnace routes. Automotive OEMs in Germany are qualifying these grades for body-in-white exposed panels at accelerated timelines. The technology is collapsing legacy assumptions that ultra-low-carbon steel requires premium pricing tiers.
The EU F-Gas Regulation and embedded carbon intensity thresholds are reshaping import eligibility for hot-rolled coil into European fabrication markets. Mills without verified emissions disclosure face exclusion from public infrastructure tender participation. Automotive stamping plants in the Czech Republic and Slovakia are now requiring supplier EPD certification for coil procurement.
Long-term offtake contracting with fixed carbon premiums is displacing spot market purchasing for automotive and appliance OEMs. Tier-1 stamping operations in Japan are locking in five-year supply agreements with embedded green steel volume commitments. This pattern is most visible in South Korea, where POSCO and Hyundai Steel are structuring take-or-pay contracts with domestic appliance manufacturers.
Global Flat Steel Market Segmentation
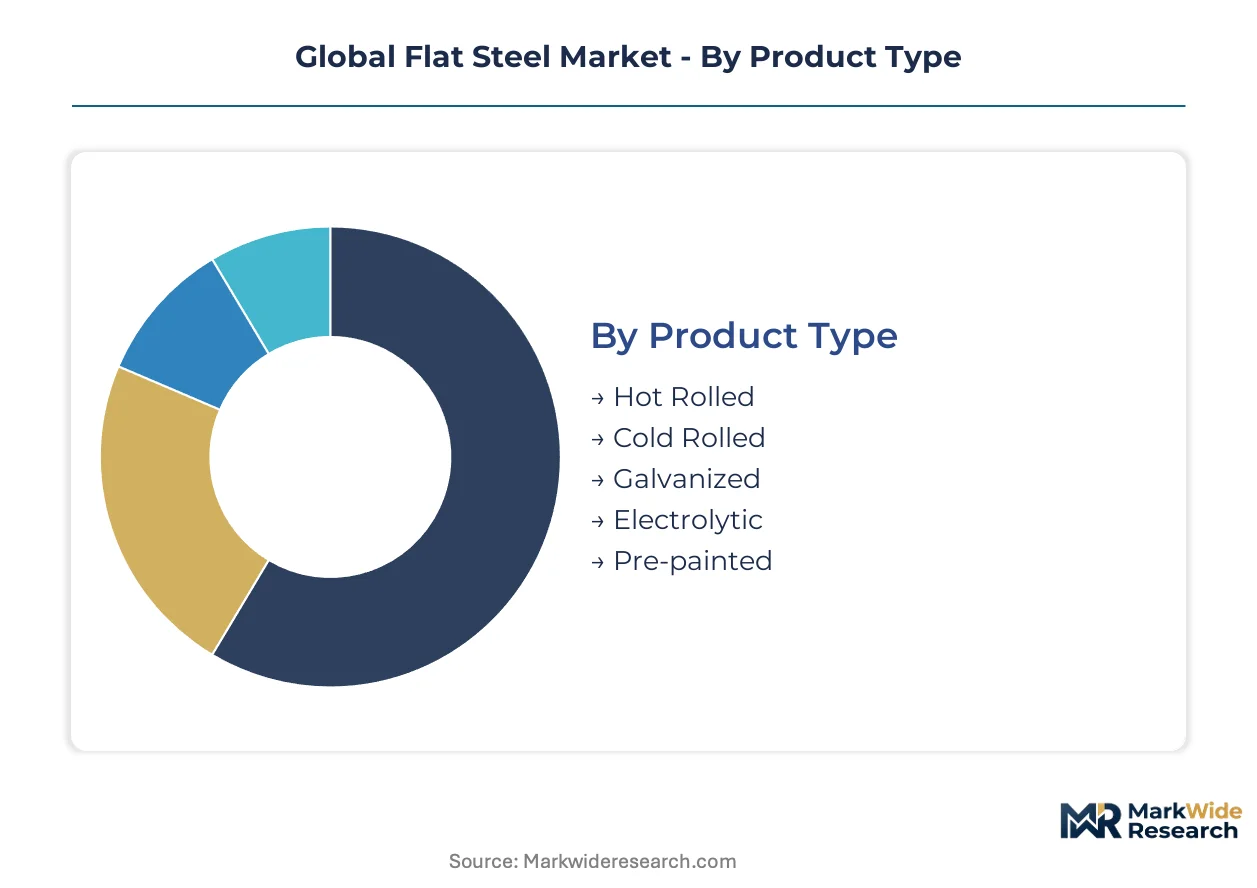
Flat steel segmentation reveals divergent margin profiles across product grades and process routes. Procurement specifications from automotive OEMs and appliance manufacturers are fragmenting demand into increasingly specialized tiers with distinct qualification barriers.
Product Type:
Cost tier differentiation separates commodity-grade volume products from surface-finished premium grades with coating value-add.
- Hot Rolled:Continuously cast slabs reduced above recrystallization temperature yield oxidized scale surfaces suited to structural fabrication. Construction demand in India and heavy machinery build-out in China absorb the majority of global tonnage.
- Cold Rolled:Subsequent cold reduction below recrystallization temperature delivers tighter dimensional tolerances and superior surface finish for automotive body panels. German and Japanese OEM qualification programs for advanced high-strength variants are compressing approval timelines.
- Galvanized:Zinc coating provides sacrificial corrosion protection for outdoor structural applications and appliance enclosures.
- Electrolytic:Electro-deposited zinc or tin coatings serve precision electronic component shielding and food-grade packaging.
- Pre-painted:Coil coating with polymer films eliminates downstream painting steps for refrigerator and washing machine OEMs in South Korea.
Hot Rolled holds installed capacity. Cold Rolled is rotating up the share rankings.
Application:
End-use fragmentation reflects divergent performance requirements across load-bearing, aesthetic, and protective functions.
- Construction:Hot-rolled sections and plates form the structural backbone of commercial and residential building frames. India's infrastructure build-out and urban housing stock expansion are concentrating demand growth in this segment.
- Transportation:Cold-rolled and coated grades serve automotive body-in-white assemblies, rail car fabrication, and truck trailer construction. Fleet emission mandates in Germany are accelerating advanced high-strength steel penetration.
- Shipbuilding:Heavy plate and bulb flats for hull construction require certified toughness grades for marine classification societies.
- Household Appliances:Pre-painted and galvanized coils for refrigerator, washing machine, and HVAC enclosures prioritize surface cosmetic quality.
- Packaging:Tinplate and electrolytic chromium-coated steel for food and beverage can stock demands ultra-low residual elements.
Construction absorbs the highest tonnage. Transportation is climbing the fastest on value-per-ton metrics.
End User Industry:
Customer type concentration varies from project-driven infrastructure procurement to continuous-flow manufacturing contracts.
- Infrastructure:Public and private construction projects specify grade-certified structural sections with traceable mill documentation. India's PLI scheme for specialty steel is redirecting procurement toward domestic qualified suppliers.
- Heavy Machinery:Mining equipment, agricultural implements, and industrial presses require abrasion-resistant plate grades with through-thickness properties.
- Aerospace:Precision-rolled thin strip for aircraft structural components demands vacuum-degassed ultra-low inclusion steel.
- Electrical:Grain-oriented silicon steel for transformer cores and non-oriented grades for electric motor laminations.
- Consumer Electronics:Cold-rolled thin sheet for laptop chassis and smartphone components requires tight thickness tolerances.
Infrastructure commands the volume base. Aerospace sits at the premium margin extreme.
Manufacturing Process:
Process route selection determines carbon intensity, raw material flexibility, and product metallurgical capability.
- Blast Furnace:Iron ore reduction with coke produces virgin iron with ultra-low residual elements essential for automotive exposed panels. China's MIIT dual carbon enforcement is forcing retrofits and capacity consolidation among state-controlled mills.
- Electric Arc Furnace:Scrap melting enables lower carbon intensity output where scrap chemistry and residual element control meet specification. European integrated producers are balancing EAF expansion against retained blast furnace capacity for premium grades.
- Continuous Casting:Liquid steel solidification into semi-finished slabs, blooms, or billets precedes all flat rolling operations.
- Basic Oxygen Furnace:Molten pig iron refining with oxygen injection converts blast furnace output into steel with precise carbon control.
Blast Furnace retains installed capacity dominance. Electric Arc Furnace is gaining share fastest on carbon accounting tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances vary sharply across major steel-consuming economies, with integrated producers in East Asia and Europe tilting toward carbon-accounted premium grades while import-dependent markets absorb commodity tonnage for infrastructure build-out.
China
Blast furnace retrofits and scrap-fed electric arc furnace expansion dominate capital allocation under MIIT dual carbon enforcement timelines. The MEE mandates emissions disclosure for all crude steel output above threshold volumes. Tangshan and Baoshan industrial clusters concentrate hydrogen-ready tuyere injection pilot programs.
India
Infrastructure build-out and urban housing stock expansion drive hot-rolled coil absorption at per-capita consumption levels below regional peers. The PLI scheme for specialty steel redirects procurement toward domestic qualified suppliers. Jamshedpur and Hazira clusters anchor integrated mill capacity serving automotive and appliance OEM contracts.
Germany
Automotive lightweighting mandates accelerate advanced high-strength steel consumption in body-in-white assemblies for fleet emission compliance. The EU Green Deal carbon border adjustment mechanism shapes import eligibility for hot-rolled coil into European fabrication markets. Ruhr Valley and Salzgitter industrial zones concentrate hydrogen-based direct reduction pilot scaling.
Japan
OEM qualification programs for advanced high-strength variants compress approval timelines for exposed panel grades. METI frameworks govern process efficiency benchmarks at integrated mills. Chiba and Kimitsu coastal clusters sustain dominance in automotive-grade cold-rolled output through dedicated R&D center proximity.
United States
Scrap availability improvements and carbon accounting tightening favor electric arc furnace share gains in flat product output. EPA and OSHA frameworks govern emissions and workplace exposure limits at integrated mills. Great Lakes and Southern mini-mill corridors concentrate capacity serving construction and appliance manufacturing demand.
Global Flat Steel Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in narrow grade categories. The vendor base clusters around three concentration nodes: state-controlled Chinese mills with captive raw material access, European-Japanese integrated producers with automotive qualification depth, and North American mini-mill operators with scrap-fed cost structures. Strategic archetypes include carbon-transition leaders anchoring green hydrogen project finance, automotive-grade specialists occupying qualification-intensive premium tiers, and scale-driven commodity producers defending volume positions. Dominant competitive moves comprise blast furnace retrofit partnerships with equipment licensors and long-term offtake contracting with fixed carbon premiums.
Within the integrated multinational tier, ArcelorMittal and POSCO occupy positions defined by geographic diversification and automotive-grade specialization respectively. Among East Asian state-controlled producers, China Baowu Group exemplifies scale-driven capacity concentration with captive hot-rolled coil supply relationships. Tata Steel Limited represents the emerging market integrated archetype with domestic infrastructure and automotive exposure.
| Leading Market Players |
|---|
| Tata Steel Limited |
| JFE Steel Corporation |
| ArcelorMittal |
| United States Steel Corporation |
| ThyssenKrupp AG |
| Nippon Steel Corporation |
| China Baowu Group |
| Ansteel Group Corporation |
| POSCO |
| Others |
Supply & Pricing Matrix
Iron ore and coking coal supply concentration in Australia and Brazil funnels pricing power toward integrated producers with captive mining assets, compressing margin pools for service-center-dependent fabricators in import-dependent markets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing with embedded carbon premiums for low-carbon grades. Price differentiation rests on certification level—EPD-verified low-carbon steel commands premiums against commodity hot-rolled coil—and volume scale commitments. Cost compression in commodity-grade hot-rolled coil is intensifying because Chinese state-controlled mills leverage captive raw material access. Tier-2 stamping operations exhibit highest price sensitivity, while automotive OEMs with qualification-locked supply chains show lowest.
Supply Chain Analysis
Tariff exposure between China and major import markets dominates supply chain risk calculus for flat steel distributors. Raw material sourcing draws from Australian iron ore, Mongolian coking coal, and US scrap flows. Single-source vulnerability concentrates in hydrogen-ready direct reduction iron pilot supply from European integrated mills. Distribution runs through mill-direct contracts to large OEMs, with service centers filling spot demand for smaller fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized metallurgical expertise for scrap chemistry control and residual element management in electric arc furnace operations represents the critical capability gap constraining route conversion timelines.
For Market Incumbents: Insulate automotive-grade qualification positions by accelerating hydrogen-based direct reduction pilot output ahead of EU Green Deal carbon border adjustment enforcement. Deepen backward integration into captive green hydrogen supply to defend margin structure against emerging low-carbon import competition. Lock in five-year offtake contracts with fixed carbon premiums to reduce spot market exposure. For New Entrants and Emerging Players: India's underpenetrated per-capita flat steel consumption offers structural volume growth for scrap-fed electric arc furnace operators with localized melt shop capacity. Target infrastructure-grade hot-rolled coil supply to state-level housing development authorities under PLI scheme procurement redirection. Pursue direct-to-appliance OEM pre-painted coil contracts bypassing traditional service center intermediaries. For Investors and Strategic Acquirers: Capital is best deployed toward integrated producers with balance-sheet depth for blast furnace retrofit capex and hydrogen-ready tuyere injection capability. Long-term viability over the coming decade hinges on qualifying low-carbon steel grades for automotive exposed panel contracts. Monitor EU carbon border adjustment mechanism implementation scope as the critical inflection signal for import-competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Blast Furnace Hydrogen Retrofit | Enables ArcelorMittal and Salzgitter to supply EPD-certified coil for German automotive OEM qualification programs. |
| Scrap-Fed Electric Arc Furnace Expansion | Allows US mini-mill corridors to capture construction demand under tightening EPA emissions frameworks. |
| Long-Term Green Steel Offtake Contracting | Locks in POSCO and Hyundai Steel volume commitments with South Korean appliance manufacturers at fixed carbon premiums. |
| Direct-to-Appliance Pre-Painted Coil Supply | Shortens lead times for refrigerator and washing machine OEMs in India's Hazira industrial cluster. |
| Automotive Grade Qualification Investment | Compresses 18-24 month approval cycles for advanced high-strength steel body-in-white panel specifications. |
Research Methodology
Initial hypotheses were tested against primary input from melt shop operations managers, automotive OEM procurement directors, service center distribution heads, and EPC contractors executing blast furnace retrofits and refined through secondary validation against customs trade data, SEC 10-K filings from listed steel producers, MIIT capacity disclosure filings, and EU ETS emissions registry records. Bottom-up demand modeling across construction, automotive, and appliance end-uses was triangulated against top-down crude steel capacity assessments.
Demand-supply-balance dynamics across the analysis window were modeled through segmented projections by product grade, manufacturing process route, and regional production hub. CAGRs were derived from fitted growth curves calibrated to infrastructure build-out trajectories, automotive lightweighting penetration rates, and electric arc furnace share shift assumptions. Industry-specific forecast inputs included hydrogen direct reduction iron pilot scale-up timelines and PLI scheme procurement redirection velocity.
Practitioners should monitor iron ore and coking coal price volatility, Chinese MIIT dual carbon enforcement acceleration, and automotive aluminum substitution rates for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Precious Metal Market
Metals
Hafnium Foil Market
Metals
Copper Chromium Black Market
Metals
Battery Metals Market
Metals
Titanium Sponge Market
Metals
Aluminum Fluoride Market
Metals
Global Galvanized Steel Wire Market
Metals
Bismuth Oxide Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
Weathering Steel Market
Metals
Flat-Rolled Stainless Steel Market
Metals
Metal Injection Molding (MIM) Parts Market
Metals
Ferrite Market
Metals
Asia-Pacific Aluminum Casting Market
Metals
Liquid Metal Thermal Pad Market
Metals
Europe Metal Casting Market