
 Ferrosilicon Market | 2026-2036
Ferrosilicon Market Size, Share, and Industry Trends Forecast 2026-2036
Ferrosilicon Market Intelligence
ISO 9001 quality management certification is bifurcating the competitive landscape into qualified suppliers and marginal producers. Elkem ASA leverages its Norwegian smelting heritage and captive hydropower to sustain cost leadership in European deliveries. Ferroglobe anchors its position through Spanish and American furnace assets that compete on energy arbitrage across Atlantic markets.
Ferrosilicon denotes an iron-silicon alloy typically containing 15-90% silicon by weight, produced via carbothermic reduction of quartz with iron in submerged arc furnaces at temperatures exceeding 1,800°C; its primary function is deoxidation and alloying in steelmaking and cast iron production. The steel production segment dominates volume offtake as electric arc furnace operators prioritize consistent silicon recovery rates for rebar and flat-rolled products. Foundry alloys represent a concentrated margin pool where automotive casting specifications reward narrow chemistry tolerances and low-aluminum grades.
China's MIIT enforces GB standards on alloy chemistry and energy consumption intensity, while the EU F-Gas Regulation and REACH framework constrain fluorinated process inputs and trace element disclosures for European-sourced material. India's BIS certification mandates IS 1550 compliance for ferrosilicon used in government infrastructure steel, creating a non-tariff barrier for uncertified imports. Stakeholders must monitor divergence between Chinese national standards and evolving EU carbon border adjustment mechanisms to anticipate procurement qualification costs.
Market Dynamics
China's MIIT enforcement of GB standards on energy consumption intensity and alloy chemistry is compressing marginal smelter capacity while redirecting procurement toward certified producers with captive hydropower or furnace modernization programs.
Growth Catalysts
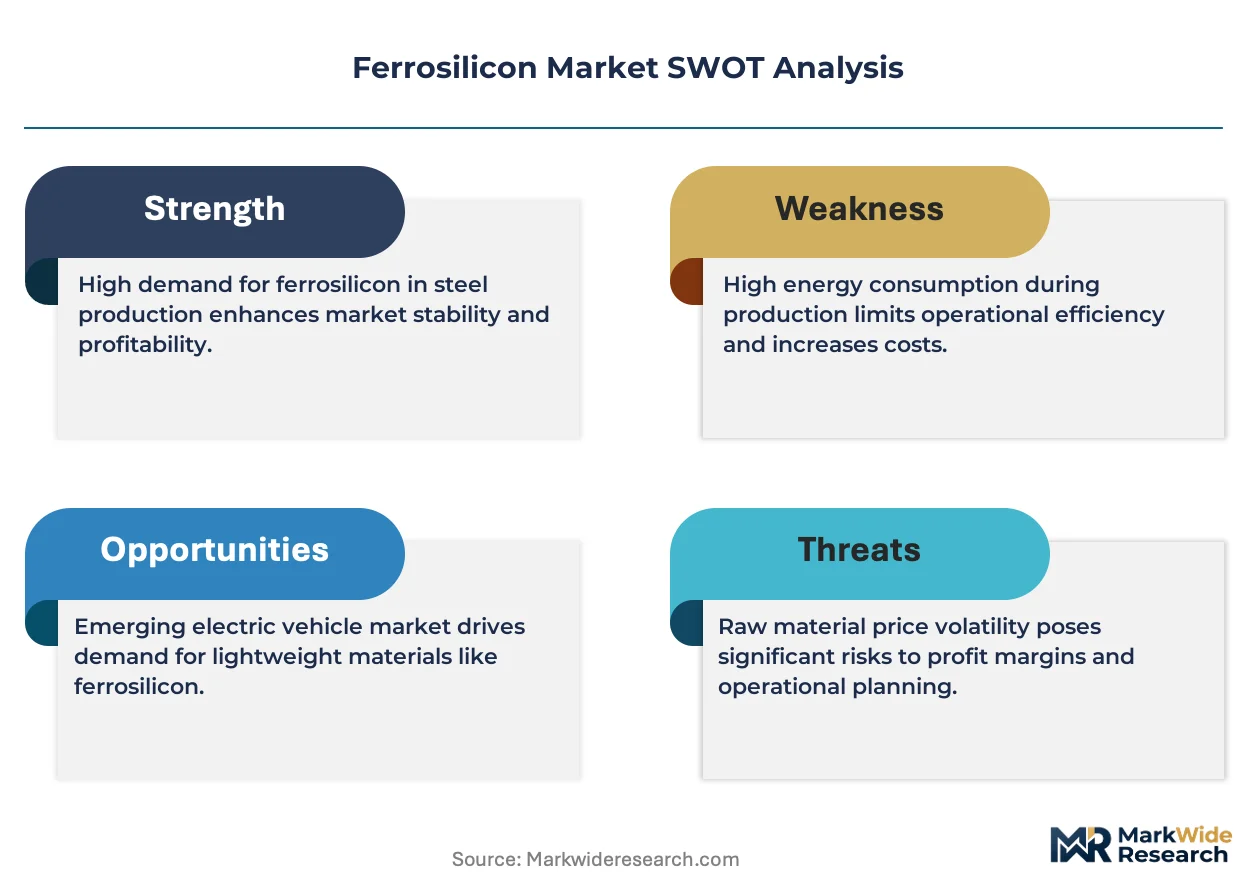
- Electric arc furnace expansion:Steel producers in India, Brazil, and South Africa prioritize consistent silicon recovery rates for rebar and flat-rolled products, sustaining alloy offtake volumes.
- REACH framework compliance:EU F-Gas Regulation constraints on fluorinated process inputs create qualification premiums for European-sourced material with trace element disclosures.
- Dual carbon goals:China's emissions standards enforcement accelerates furnace upgrades and consolidates output among low-carbon intensity operators.
Market Restraints
- Quartz supply concentration:High-purity silica deposits cluster in specific mining jurisdictions, exposing smelters to freight cost volatility and geological depletion risks.
- Carbothermic reduction energy intensity:Submerged arc furnace operations exceeding 1,800°C require baseload power contracts that face carbon pricing exposure under EU CBAM mechanisms.
- Aluminum ferrosilicon substitution:Foundry operators in cost-sensitive segments trial synthetic graphite and calcium-silicon alloys for specific deoxidation applications.
Strategic Opportunities
- Automotive casting specifications:Narrow chemistry tolerances and low-aluminum grades for powertrain components command concentrated margin pools in European and Japanese supply chains.
- Indian government infrastructure steel:BIS certification mandates IS 1550 compliance, creating non-tariff barriers that reward early qualification investments by certified importers.
- Hydrogen-reduction pilot programs:Norwegian and Icelandic smelters test renewable hydrogen injection to displace metallurgical coke in carbothermic reduction reactions.
Industry Challenges
- ISO 9001 certification timeline:Quality management system audits and documentation requirements delay supplier qualification by 12-18 months for government steel procurement contracts.
- Furnace rebuild capex cycles:Submerged arc furnace lining replacement and electrode systems require capital deployment that conflicts with carbon border adjustment uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferrosilicon Market |
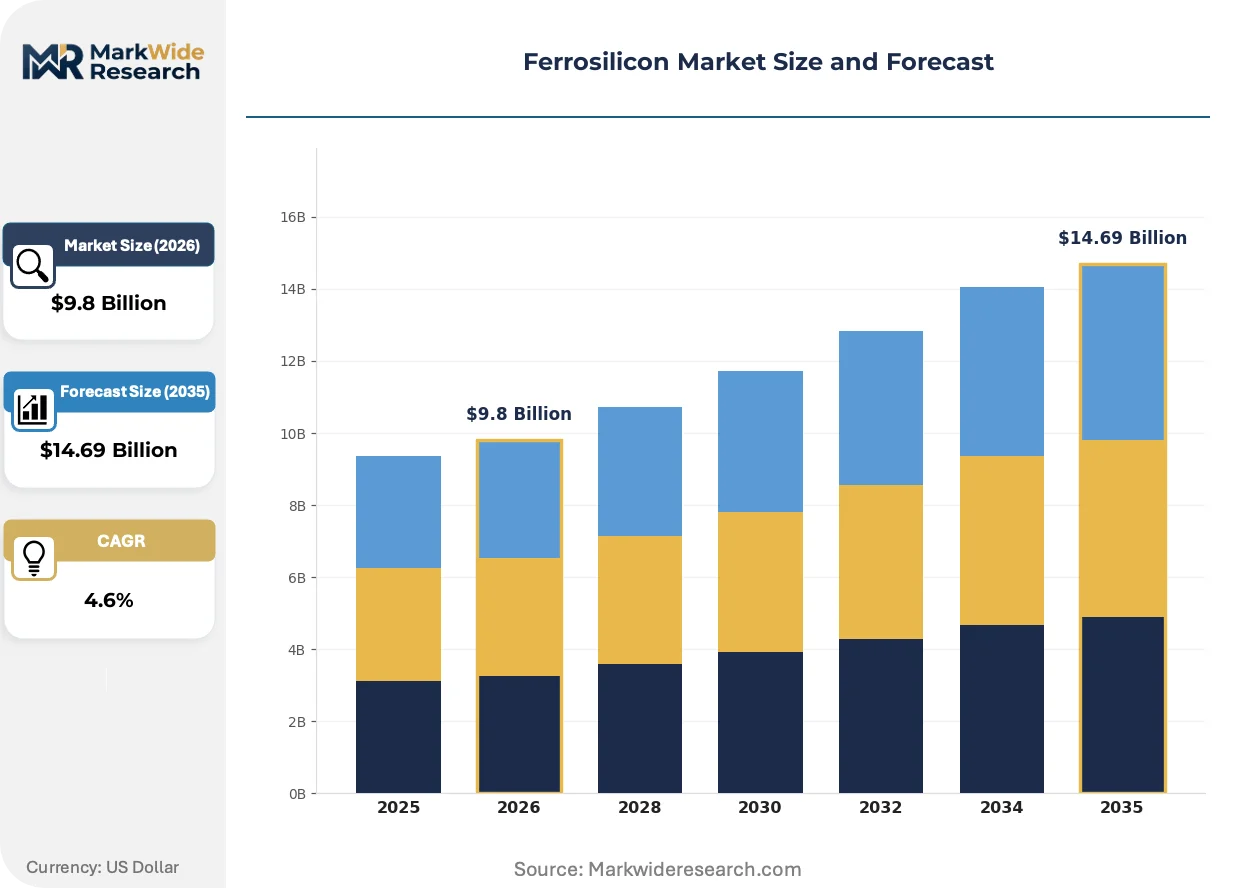
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferroalloys, Silicon Alloys, Foundry Alloys, Master Alloys End Use Industry: Steel Production, Automotive Components, Electrical Equipment, Construction Materials Form: Powder, Granules, Crystals, Ingots Distribution Channel: Direct Sales, Online Retail, Distributors, Traders |
| Companies Covered | Finnfjord AS, Russian Ferro-Alloys Inc., Elkem ASA, DMS Powders, China Minmetals Corporation, Ferroglobe, OM Holdings Ltd., Mechel PAO, Eurasian Resources Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferrosilicon Market Strategic Shifts & Innovations
Smelting technology is compressing energy intensity thresholds while regulatory frameworks fragment procurement qualification requirements across major steel-producing jurisdictions.
Advanced electrode paste formulations with modified pitch-binder ratios are miniaturizing specific energy consumption per ton of ferrosilicon output. European producers with hydropower integration adopt these formulations fastest, achieving 8-12% efficiency gains. This technology is miniaturizing the cost gap between Nordic smelters and coal-dependent competitors in carbon-adjusted markets.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon process inputs constrain fluorinated slag conditioner availability. Smelters must reformulate slag chemistry or source alternative mineralizers, raising batch consistency costs. Foundry alloy segments with strict aluminum specifications face the tightest reformulation timelines.
Steel mills now unbundle ferrosilicon procurement from long-term oxide supplier contracts, creating spot-market exposure for alloy chemistry premiums. Tier-one automotive steel producers in Germany and South Korea lead this shift, negotiating quarterly silicon recovery rate guarantees rather than annual volume commitments. This pattern concentrates price volatility risk on smelters without captive steel mill relationships.
Ferrosilicon Market Segmentation
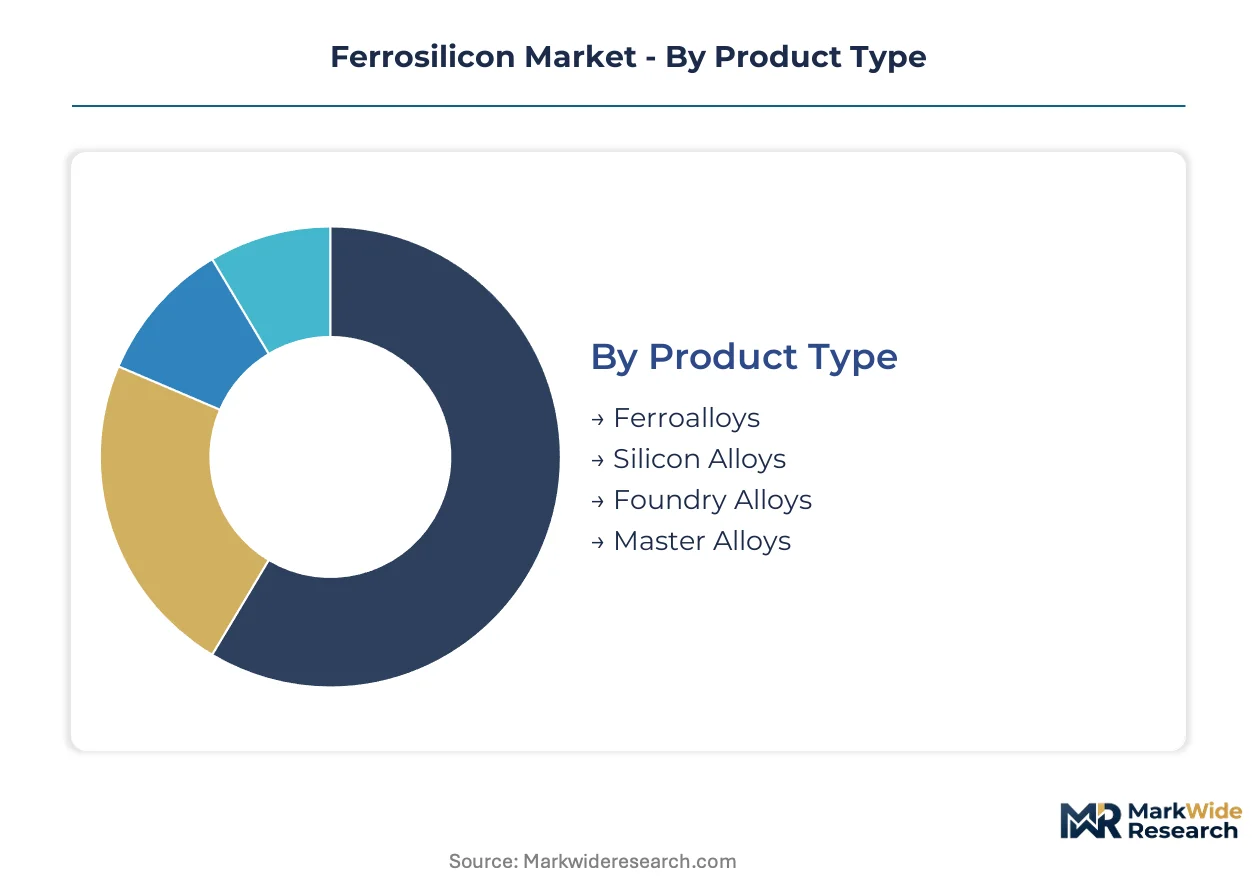
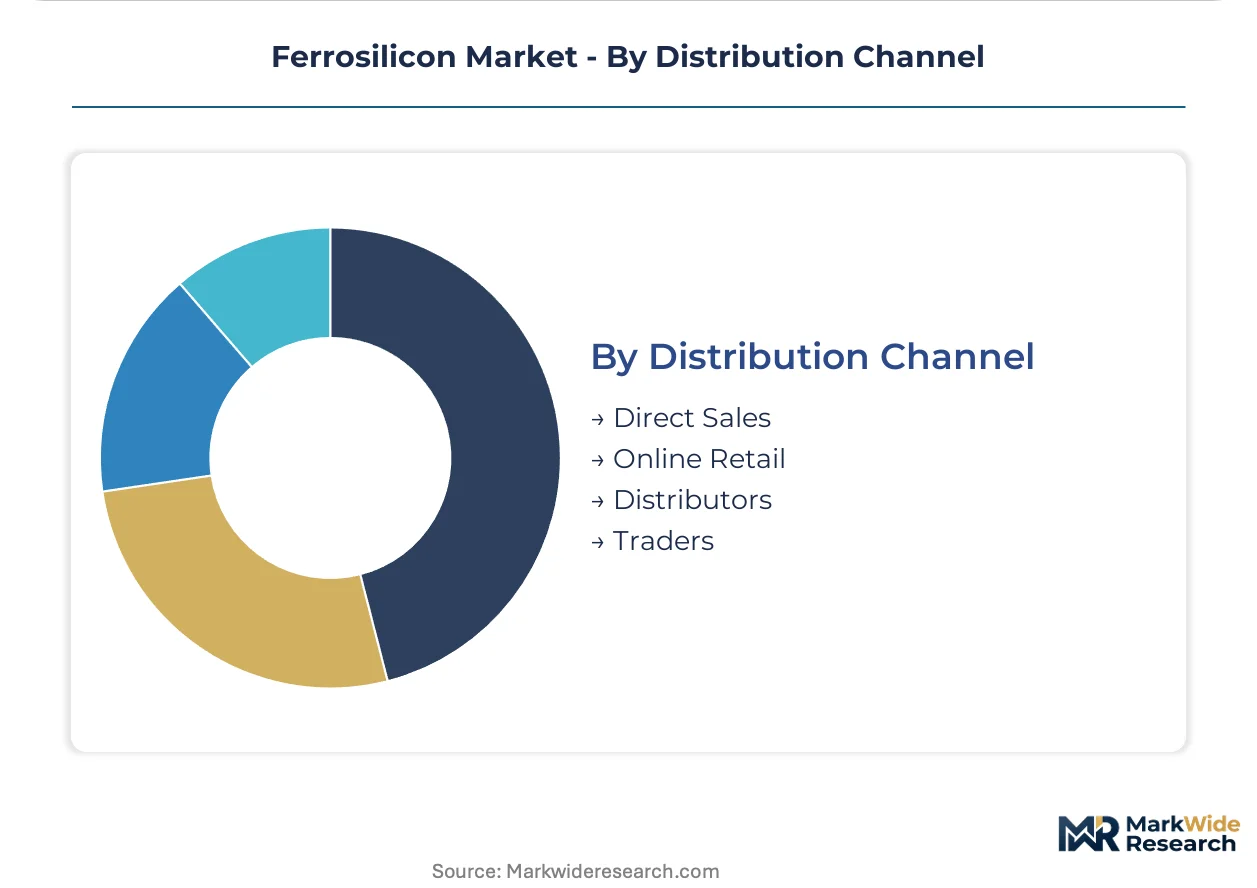
Segmentation in ferrosilicon markets reveals where chemistry specifications command premium pricing and where commoditized grades compete on logistics efficiency. Steel mill procurement unbundling has intensified granularity in contract structures across product forms and distribution channels.
Product Type:
Margin pools concentrate in foundry alloys where narrow chemistry tolerances for automotive castings resist price compression.
- Ferroalloys:Standard deoxidation grades with 15-90% silicon content serve bulk steelmaking operations. Demand clusters in electric arc furnace facilities across India, Brazil, and South Africa where consistent silicon recovery rates govern rebar quality.
- Silicon Alloys:Higher-purity formulations with controlled aluminum and calcium traces target specialty steel applications. German and South Korean automotive steel producers negotiate quarterly silicon recovery guarantees rather than annual volume commitments, concentrating volatility risk on smelters.
- Foundry Alloys:Low-aluminum specifications for powertrain castings.
- Master Alloys:Precision additions for exotic steel grades.
Ferroalloys hold installed capacity. Silicon Alloys is rotating up the share rankings.
End Use Industry:
Volume concentration tracks steel production geography while margin expansion follows automotive specification tightening.
- Steel Production:Electric arc furnace operators prioritize deoxidation efficiency in rebar and flat-rolled output. China's MIIT enforcement of GB standards on energy consumption intensity redirects procurement toward certified producers with furnace modernization programs or captive hydropower.
- Automotive Components:Powertrain casting specifications demand narrow chemistry tolerances and low-aluminum grades. European and Japanese supply chains reward early qualification investments with concentrated margin pools unavailable in commodity grades.
- Electrical Equipment:Transformer core and motor lamination specifications.
- Construction Materials:Infrastructure rebar and structural steel applications.
Steel Production anchors volume throughput. Automotive Components is climbing the fastest on value per ton metrics.
Form:
Physical configuration determines handling economics and dissolution kinetics in specific furnace types.
- Granules:Intermediate sizing optimizes dissolution rates in electric arc furnaces while minimizing dust generation during pneumatic injection. Steel mills in India and Brazil specify granule size distributions that align with their automated alloy addition systems.
- Ingots:Dense cast blocks suit foundry cupola operations where controlled melt rates prevent thermal shock. Japanese automotive casting facilities specify ingot chemistry certifications that trace back to individual furnace batches.
- Powder:Fine particle size for specialized injection metallurgy.
- Crystals:High-purity monocrystalline forms for semiconductor-grade applications.
Granules dominate shipment volumes. Ingots maintain pricing power in premium foundry segments.
Distribution Channel:
Channel selection reflects procurement scale and certification documentation requirements.
- Direct Sales:Long-term offtake agreements with integrated steel mills specify chemistry tolerances and carbon intensity disclosures. Tier-one producers in Germany and South Korea unbundle ferrosilicon from oxide supplier contracts, creating quarterly price renegotiation exposure.
- Distributors:Regional inventory positioning serves mid-size foundries and specialty steel producers. Indian government infrastructure steel mandates BIS certification and IS 1550 compliance, creating non-tariff barriers that qualified distributors exploit.
- Traders:Spot market liquidity for specification deviations and geographic arbitrage.
- Online Retail:Emerging platform for small-batch foundry procurement.
Direct Sales captures contract value. Distributors are gaining share fastest in fragmented foundry supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated steel mills and electric arc furnace operators concentrate procurement power across four distinct national markets where furnace technology and regulatory compliance reshape supplier qualification requirements.
China
Steel producers in Hebei and Jiangsu provinces drive ferrosilicon consumption as MIIT enforces GB standards on energy consumption intensity and alloy chemistry. The dual carbon goals accelerate furnace upgrades among state-owned mills, consolidating procurement toward certified producers with captive hydropower or modernization programs. Tangshan steel clusters redirect alloy sourcing as emissions inspections disqualify marginal smelters.
India
Electric arc furnace expansion in Gujarat and Maharashtra sustains alloy offtake volumes for rebar and structural steel production. BIS certification mandates IS 1550 compliance for government infrastructure projects, creating non-tariff barriers that reward early qualification investments. The Delhi-Mumbai Industrial Corridor concentrates demand from integrated steel plants upgrading deoxidation specifications.
Germany
Automotive steel producers in the Ruhr region and Bavaria negotiate quarterly silicon recovery rate guarantees rather than annual volume commitments. EU F-Gas Regulation constraints on fluorinated process inputs create qualification premiums for European-sourced material with full trace element disclosures. ThyssenKrupp and Salzgitter operations anchor demand for narrow-tolerance foundry alloys.
Brazil
CSN and Gerdau electric arc furnace networks in Minas Gerais prioritize consistent silicon recovery rates for flat-rolled and long steel products. ANVISA-aligned import documentation requirements intersect with customs valuation protocols, extending clearance timelines for uncertified material. The Ipatinga steel valley concentrates specification-intensive procurement from qualified distributors.
South Africa
Scaw Metals and Columbus Stainless operations in Gauteng and Mpumalanga sustain alloy demand despite baseload power contract volatility from Eskom. The country's national standards regulator enforces SABS certification for infrastructure steel, creating procurement friction for uncertified imports. The Vaal Triangle industrial cluster maintains foundry alloy specifications for mining equipment castings.
Ferrosilicon Market Key Industry Players
Player mix skews toward integrated alloy producers with captive energy assets and furnace modernization programs. Market structure exhibits moderate consolidation around Nordic hydropower-integrated smelters and diversified mining conglomerates with ferroalloy divisions. Two strategic archetypes dominate: low-carbon intensity operators leveraging renewable power contracts, and diversified resource groups bundling ferrosilicon with manganese and chrome alloys. Capacity expansion and strategic partnerships constitute the dominant competitive moves as carbon border adjustment mechanisms reshape procurement geography.
Within the hydropower-integrated tier, Elkem ASA and Finnfjord ASA exemplify Nordic smelters achieving cost leadership through captive renewable energy and Norwegian smelting heritage. Ferroglobe occupies a position spanning Spanish and American furnace assets that compete on energy arbitrage across Atlantic markets. Among diversified resource groups, China Minmetals Corporation and Eurasian Resources Group represent mining conglomerates bundling ferrosilicon within broader ferroalloy portfolios. Russian Ferro-Alloys Inc. and Mechel PAO sit within the vertically integrated steel-and-alloy complex archetype, serving captive demand from affiliated mill operations. OM Holdings Ltd. and DMS Powders exemplify regional specialists concentrating on specific alloy grades and distribution channels.
| Leading Market Players |
|---|
| Finnfjord AS |
| Russian Ferro-Alloys Inc. |
| Elkem ASA |
| DMS Powders |
| China Minmetals Corporation |
| Ferroglobe |
| OM Holdings Ltd. |
| Mechel PAO |
| Eurasian Resources Group |
| Others |
Cost & Logistics Intelligence
ISO 9001 quality management certification gates both supplier qualification and price differentiation simultaneously, bifurcating the competitive landscape into certified producers commanding premium contract terms and marginal operators competing on spot-market discounts. Steel mills in Germany and South Korea unbundle ferrosilicon procurement from long-term oxide supplier contracts, creating quarterly price renegotiation exposure that concentrates volatility risk on smelters without captive relationships.
Pricing Analysis
Cost-plus contracts indexed to metallurgical coke and high-purity quartz benchmarks dominate long-term offtake agreements between integrated steel mills and certified producers. Three-tier pricing structure across premium, standard, and economy levels separates foundry alloys with narrow automotive specifications from bulk deoxidation grades. Cost compression in standard ferroalloys is intensifying because electric arc furnace operators in India and Brazil prioritize silicon recovery consistency over brand premiums. Mid-size foundries exhibit highest price sensitivity, while tier-one automotive steel producers in Japan and Germany accept chemistry premiums for batch-traceable material.
Supply Chain Analysis
Inventory positioning and lead-time compression favor distributors serving fragmented foundry supply chains over direct sales to integrated mills. High-purity quartz deposits cluster in Brazil, Norway, and Australia, exposing smelters to freight cost volatility and geological depletion risks. Carbothermic reduction rests on metallurgical coke, electrodes, and slag conditioners constrained by EU F-Gas Regulation phase-down schedules. Single-source vulnerability concentrates in electrode paste formulations with modified pitch-binder ratios. Distribution runs through regional distributors with BIS-certified inventory for Indian government infrastructure steel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement power is shifting toward electric arc furnace operators in India, Brazil, and South Africa as steel mill consolidation accelerates contract renegotiation frequency and chemistry specification unbundling.
For Market Incumbents: Secure captive hydropower contracts or furnace modernization certifications ahead of EU carbon border adjustment mechanism expansion. Defensive consolidation moves include backward integration into high-purity quartz mining in Norway or Brazil, and channel control through exclusive distributor relationships in India's BIS-mandated infrastructure steel segment. Synthetic graphite substitution in foundry deoxidation applications threatens margin pools in standard grades. For New Entrants and Emerging Players: After-sales technical service for silicon recovery rate optimization represents a service-layer gap where incumbents under-serve mid-size electric arc furnace operators. White-space targets include spot-market liquidity provision for specification deviations, and BIS certification facilitation for uncertified imports into Indian government steel projects. A go-to-market angle anchored in quarterly chemistry guarantees rather than annual volume commitments penetrates German and South Korean automotive steel supply chains fastest. For Investors and Strategic Acquirers: EU carbon border adjustment mechanism implementation reshapes the acquisition landscape toward low-carbon intensity smelters with hydropower integration. Long-term viability over a multi-year horizon favors Nordic operators with renewable energy contracts and furnace modernization programs already deployed. Acquisition target archetype: mid-cap specialists with ISO 9001 certification and underutilized capacity in Atlantic-adjacent geographies. The signal to watch is divergence between Chinese GB standard enforcement and EU trace element disclosure requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quartz Mining | Captive high-purity silica supply from Norwegian or Brazilian deposits insulates against freight volatility. |
| Furnace Modernization Program | Submerged arc furnace electrode system upgrades achieve 8-12% energy efficiency gains under EU carbon pricing. |
| BIS Certification Investment | IS 1550 compliance creates non-tariff barrier exploitation for Indian government infrastructure steel procurement. |
| Long-term Supply Agreement | Quarterly silicon recovery rate guarantees with German automotive steel producers concentrate contract value. |
| Joint Venture | Partnerships with Eskom-stabilized South African smelters secure baseload power for alloy export capacity. |
Research Approach
The analysis maps ferroalloy grade tiers, silicon alloy purity specifications, foundry alloy chemistry tolerances, and master alloy precision categories, each validated through plant managers at submerged arc furnace operations, procurement leads at electric arc furnace steel mills, distribution channel partners in Indian and Brazilian markets, and technical R&D directors at electrode paste suppliers. Primary interview data triangulates against customs and trade data from major exporting jurisdictions, SEC 10-K filings from diversified mining conglomerates, national standards body certification registries, and industry association production statistics. Bottom-up capacity assessments and top-down demand modeling from steel production forecasts converge through iterative reconciliation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models segmentation across product chemistry grade, end-use industry application, physical form configuration, and distribution channel structure, with regional regulatory clusters as an additional industry-specific dimension. CAGRs derive from curve-fitting historical production trends against electric arc furnace capacity expansion schedules and carbon intensity compliance timelines. Key forecast inputs include Chinese MIIT enforcement patterns for GB standards and EU F-Gas Regulation phase-down schedules for fluorinated process inputs.
Material uncertainties — abrupt shifts in Chinese dual carbon goal enforcement, Eskom power contract volatility in South Africa, or synthetic graphite substitution acceleration in foundry applications — sit outside the modeled envelope. Forecasts reflect assumptions about furnace modernization deployment rates and certification timeline completion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
High Purity Base Metals Market
Metals
Aluminium Forging Market
Metals
Crude Steel Market
Metals
Motor Lamination Material Market
Metals
Lanthanum Market
Metals
Global Steel Market
Metals
Qatar Metalworking Market
Metals
Shipbuilding Steel Plate Market
Metals
Reconditioned Steel Drums Market
Metals
Barium Market
Metals
United States Metal Casting Market
Metals
Platinum Group Metals Market
Metals
Aluminum Casting Market
Metals
Lithium Foil Market
Metals
Neodymium Market
Metals
Copper and Copper Alloy Scrap and Recycling Market