
 Asia Pacific Plant-Based Milk Market | 2026-2036
Asia Pacific Plant-Based Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Plant-Based Milk Market Outlook
Clean-label certification tiers is unwinding conventional commodity positioning across the Asia Pacific Plant-Based Milk Market. Oatly Group AB leverages its barista-series formulation expertise to anchor premium placement in specialty coffee channels. Danone SA sustains broad retail penetration through multi-brand portfolios spanning soy and almond segments. Vitasoy International Holdings Ltd dominates heritage soy milk positioning while extending into oat-based lines for younger demographics.
Plant-based milk denotes aqueous emulsions extracted from oilseeds, cereals, or nuts, typically containing two to twelve percent solids with protein contents ranging from 0.5 to 4.0 grams per 100 milliliters depending on source material, produced through wet milling, enzymatic hydrolysis, and ultra-high temperature processing to achieve microbial stability and sensory acceptance as dairy alternatives in beverages and food manufacturing. Oat milk leads volume momentum among product types due to neutral flavor compatibility and lower allergenicity profiles, while soy milk retains margin density through established fortification infrastructure and institutional supply contracts. Supermarkets and online retailers capture diverging growth vectors in distribution channels, with the former consolidating shelf-space negotiations and the latter enabling direct-to-consumer subscription models for niche formulations.
FSSAI fortification rules in India, China's GB standards for plant protein beverages, and Australia's Food Standards Code collectively tighten compositional thresholds and labeling protocols across the region. These frameworks elevate compliance costs for new entrants while rewarding manufacturers with existing analytical laboratories and regulatory affairs capabilities. Stakeholders must monitor pending ASEAN harmonization proposals for pre-packaged food standards, as unified rules would reshape cross-border manufacturing location decisions and regional brand consolidation timelines.
Market Dynamics
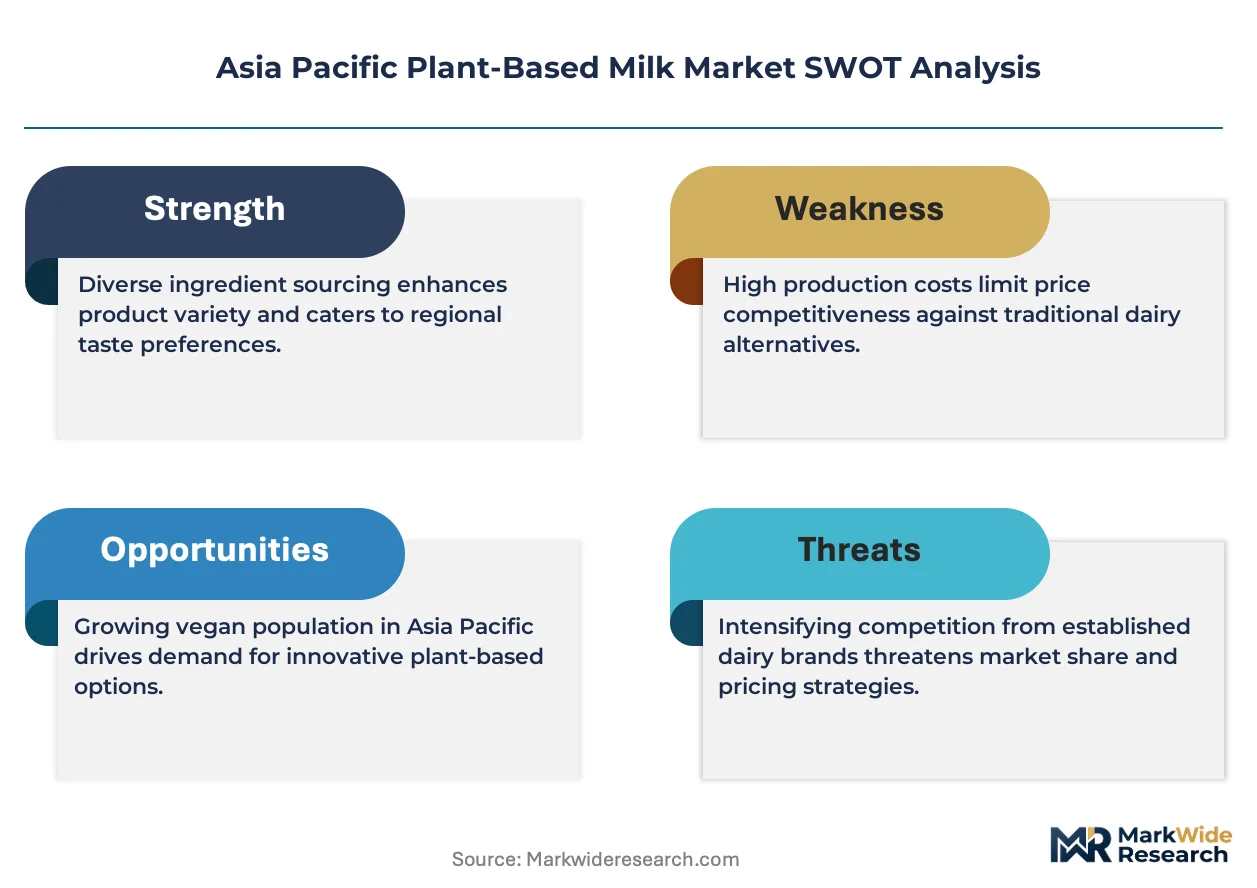
Clean-label certification tiers are unwinding conventional commodity positioning across the Asia Pacific Plant-Based Milk Market as FSSAI fortification mandates in India and China's GB standards force reformulation investments that favor established laboratory networks.
Growth Catalysts
- FSSAI Fortification Mandates:India's calcium and vitamin D requirements for dairy alternatives are reshaping product formulations and rewarding manufacturers with existing analytical capabilities.
- Specialty Coffee Channel Expansion:Barista-grade oat and almond formulations in Australian and South Korean cafés are creating premium placement anchors for neutral-flavor, low-allergenicity products.
- Cold-Chain Infrastructure Maturation:China's tier-one cities now support refrigerated plant-based milk distribution at scale, enabling fresh-format competition against ambient-stable imports.
Market Restraints
- Input Cost Volatility:Australian oat supply concentration exposes processors to drought-induced price swings and quality inconsistency in beta-glucan content.
- Technical Limitation:Protein extraction efficiency from rice and coconut sources remains below 60%, compressing margin structures for Southeast Asian originators.
- Regulatory Friction:Pending ASEAN harmonization proposals for pre-packaged food standards create compliance uncertainty for cross-border manufacturing location decisions.
Strategic Opportunities
- Underpenetrated Geography:Indonesia's halal certification infrastructure for plant-based dairy alternatives remains nascent, creating first-mover positioning for compliant entrants.
- Regulatory Tailwind:Australia's Food Standards Code tightening on compositional thresholds elevates local manufacturers with existing regulatory affairs capabilities above import competitors.
- Distribution Innovation:Direct-to-consumer subscription models for niche formulations are capturing younger demographics in China's tier-two cities bypassing supermarket slotting fee barriers.
Industry Challenges
- Enzymatic Hydrolysis Talent Gap:Southeast Asian processors face scarcity of food biochemists capable of optimizing lipase and protease protocols for sensory-matched oat milk production.
- Ultra-High Temperature Capex Burden:Aseptic filling line investments exceeding $15 million per installation constrain mid-tier entrants from achieving microbial stability parity with Danone and Vitasoy networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Plant-Based Milk Market |
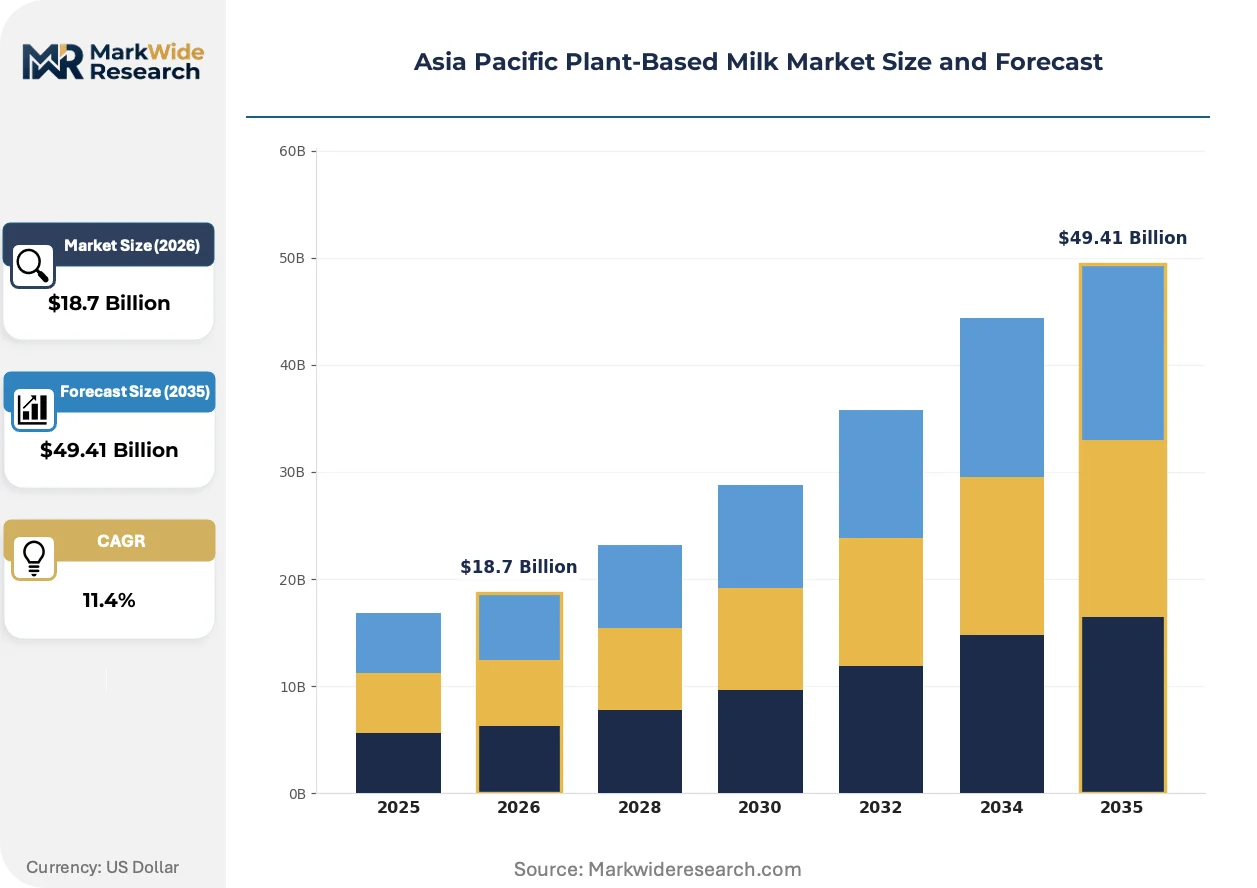
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Cashew Milk End User: Households, Cafés, Restaurants, Health Clubs Distribution Channel: Supermarkets, Health Stores, Online Retailers, Convenience Stores Packaging Type: Cartons, Bottles, Pouches, Tetra Packs |
| Companies Covered | Oatly Group AB, Danone SA, Vitasoy International Holdings Ltd, Califia Farms, Blue Diamond Growers, Oatside, The Hain Celestial Group Inc, SunOpta Inc, Sanitarium Health and Wellbeing Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Plant-Based Milk Market Strategic Shifts
Enzymatic processing advances and barista-specific formulation science are fragmenting traditional sensory benchmarks while regulatory tightening across India, China, and Australia compresses compliance timelines for new entrants.
High-pressure homogenization paired with cellulase pre-treatment is fragmenting conventional oat milk texture standards. Specialty roasters in Melbourne and Seoul are adopting these formulations for microfoam stability within eighteen-month procurement cycles. The technology is fragmenting legacy equipment depreciation schedules as processors face premature obsolescence of standard wet-milling configurations.
China's GB standards for plant protein beverages are tightening protein minimums and additive disclosure requirements. Manufacturers must now submit batch-level analytical documentation to provincial SAMR offices before shelf placement. Soy milk heritage brands with established laboratory networks are absorbing these compliance costs more efficiently than oat-focused entrants.
Café procurement committees now specify barista-grade certification as a mandatory tender requirement rather than optional premium tier. Independent roasters in Sydney and Busan are displacing conventional wholesale arrangements with direct processor contracts specifying viscosity and foam retention parameters. This specification intensity concentrates most visibly in Australia's specialty coffee channel where latte art consistency drives repeat purchase loyalty.
Asia Pacific Plant-Based Milk Market Segmentation
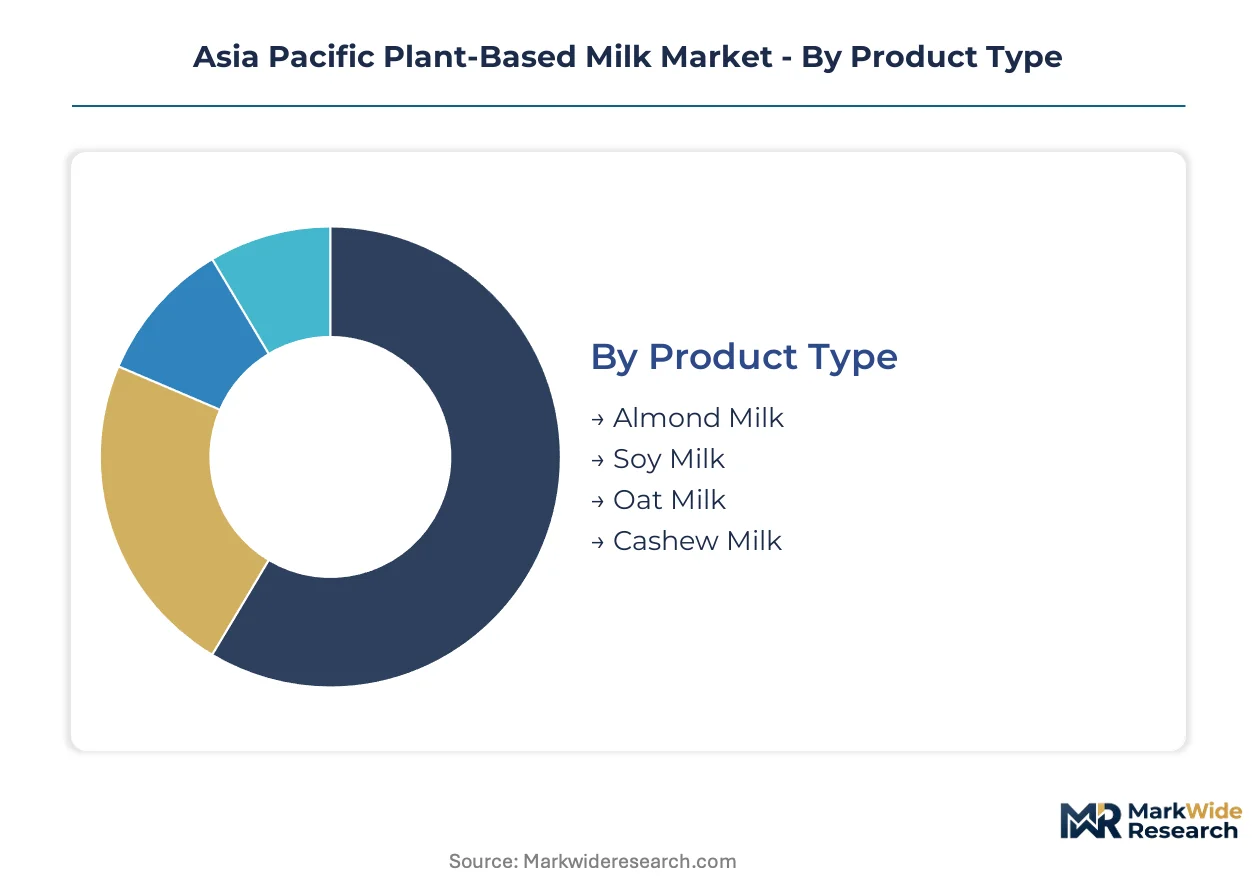
Segmentation in the Asia Pacific Plant-Based Milk Market reflects divergent compliance burdens and channel economics. India's FSSAI fortification mandates and China's GB standards for plant protein beverages create asymmetric cost structures across product formulations and packaging formats.
Product Type:
Regulatory differentiation across India, China, and Australia reshapes competitive viability by source material, with protein minimums and additive disclosure rules favoring established laboratory networks.
- Oat Milk:Aqueous emulsion from oat groats containing 2-4% solids with beta-glucan content driving viscosity specifications. Australian and South Korean specialty cafés specify barista-grade formulations for microfoam stability, though drought-induced supply concentration exposes processors to price volatility.
- Soy Milk:Heritage positioning with established fortification infrastructure meeting India's calcium and vitamin D mandates. China's tier-one cities concentrate institutional supply contracts for this segment, with heritage brands absorbing batch-level analytical documentation costs more efficiently than oat-focused entrants.
- Almond Milk:Lower protein content (0.5-1.5g per 100ml) positions this as a flavor-forward option in health-conscious households across Australia's metropolitan clusters.
- Cashew Milk:Premium creaminess profile targets niche formulations in direct-to-consumer subscription channels, with limited scale due to input cost structures.
Soy milk handles the majority of throughput; oat milk is expanding most quickly on share.
End User:
Application intensity varies sharply by procurement sophistication, with specification-heavy channels commanding premium placement while volume channels prioritize shelf stability.
- Cafés:Procurement committees in Melbourne, Sydney, and Busan now mandate barista-grade certification with viscosity and foam retention parameters specified in direct processor contracts. Latte art consistency drives repeat purchase loyalty in this channel.
- Households:China's tier-two cities are bypassing supermarket slotting fees through online subscription models for niche formulations, capturing younger demographics with flavor experimentation.
- Restaurants:Bulk procurement favors ambient-stable imports with extended shelf life, though cold-chain maturation in tier-one Chinese cities enables fresh-format competition.
- Health Clubs:Fortification claims align with post-workout recovery positioning, particularly in South Korean fitness chains where protein content verification is standard tender requirement.
Households absorb the largest volume base; cafés are climbing the fastest on margin contribution.
Distribution Channel:
Channel economics fragment by working capital intensity and regulatory touchpoint density, with diverging growth vectors between consolidated shelf-space negotiations and direct-to-consumer agility.
- Supermarkets:Consolidated shelf-space negotiations in Australia and China favor multi-brand portfolios with established slotting fee structures. Retailers capture margin through private-label placement alongside premium imports.
- Online Retailers:Direct-to-consumer subscription models for niche formulations bypass traditional distribution markups, with China's tier-two cities showing strongest adoption velocity for oat-based lines targeting younger demographics.
- Health Stores:Clean-label certification tiers command premium positioning, with India's FSSAI fortification mandates reshaping product formulations available in this channel.
- Convenience Stores:Ambient-stable SKUs dominate due to refrigeration constraints, though South Korean CU and GS25 chains are testing chilled plant-based milk in Seoul metro locations.
Supermarkets move the highest absolute volume; online retailers are gaining share fastest through demographic bypass strategies.
Packaging Type:
Packaging selection concentrates by shelf-life requirements and cold-chain availability, with aseptic technology investments creating tiered entry barriers.
- Tetra Packs:Ultra-high temperature processing compatibility enables ambient distribution without refrigeration, critical for Southeast Asian markets with intermittent cold-chain coverage. Aseptic filling line investments exceeding $15 million per installation constrain mid-tier entrants.
- Cartons:Standard gable-top formats dominate refrigerated segments in China's tier-one cities where cold-chain logistics now support distribution at scale.
- Bottles:Premium visual differentiation targets health club and café channels, with PET and glass variants segmented by price tier.
- Pouches:Flexible format reduces shipping cube for online retail channels, though limited structural integrity constrains premium positioning.
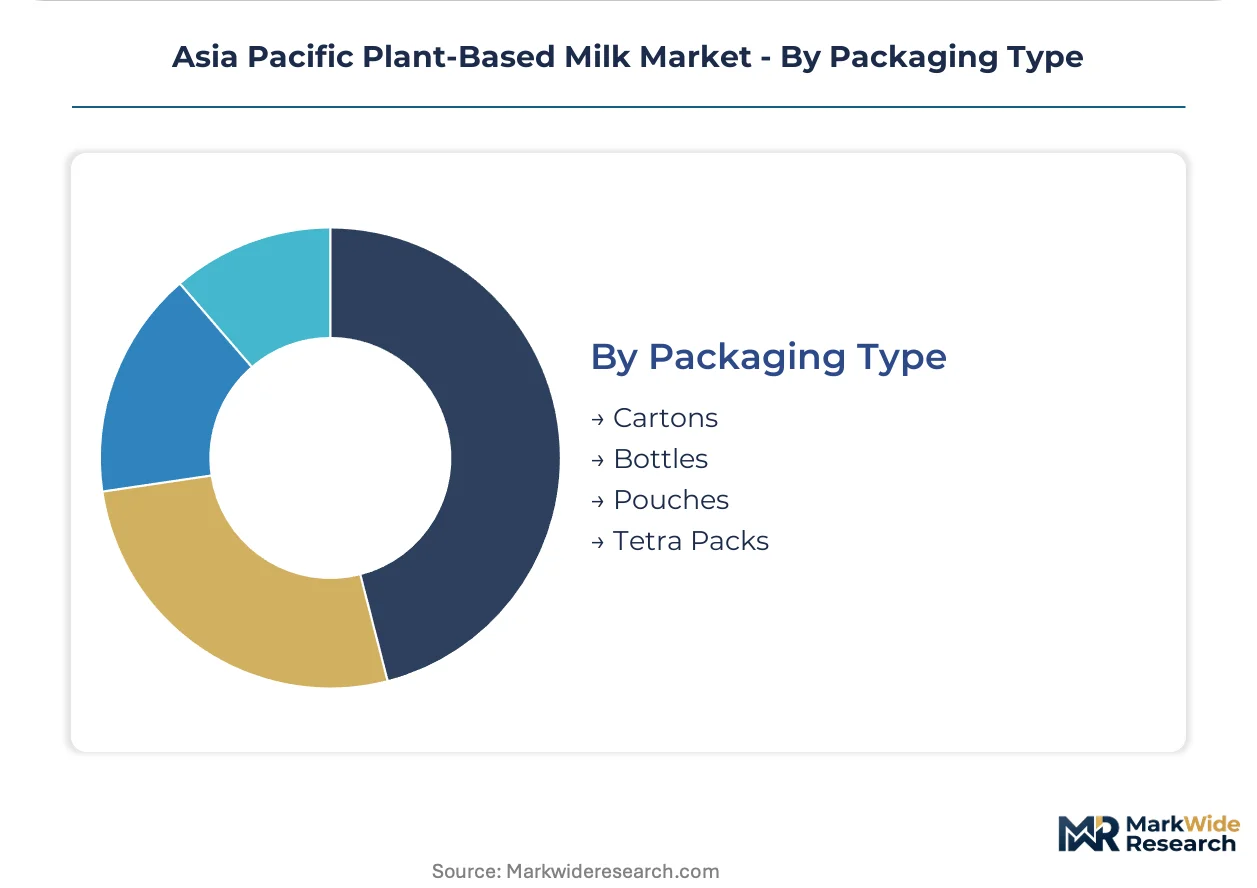
Tetra packs handle the majority of throughput; cartons are expanding most quickly in refrigerated segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian oat processors dominate raw material supply for barista-grade formulations, though manufacturing capacity distributes across South Korea, China, and India to serve divergent regulatory environments. Cold-chain maturation in select metropolitan clusters is enabling fresh-format competition against ambient-stable imports.
China
GB standards for plant protein beverages mandate protein minimums and additive disclosure requirements that favor heritage soy milk brands with established laboratory networks. SAMR batch-level documentation requirements apply before provincial shelf placement. Shanghai and Beijing concentrate refrigerated distribution infrastructure that supports fresh-format oat milk competition against imports.
India
FSSAI fortification mandates for calcium and vitamin D reshape product formulations and reward manufacturers with existing analytical capabilities. Heritage soy milk infrastructure absorbs compliance costs more efficiently than oat-focused entrants. Maharashtra and Karnataka host the primary processing clusters where reformulation investments concentrate.
Australia
Food Standards Code tightening on compositional thresholds elevates local manufacturers with regulatory affairs capabilities above import competitors. Drought-induced oat supply concentration exposes processors to price volatility and beta-glucan quality inconsistency. Melbourne and Sydney specialty cafés mandate barista-grade certification with specified viscosity parameters.
South Korea
MFDS oversight aligns with specialty coffee channel expansion where procurement committees specify foam retention parameters in direct processor contracts. Busan roasters displace conventional wholesale arrangements with technical specification intensity. Seoul metro convenience chains test chilled plant-based milk in limited refrigeration deployments.
Indonesia
Halal certification infrastructure for plant-based dairy alternatives remains nascent, creating first-mover positioning for compliant entrants. Rice and coconut source materials face protein extraction efficiency below 60%, compressing margin structures for originators. Java-based processors concentrate where enzymatic hydrolysis talent scarcity constrains oat milk sensory matching.
Asia Pacific Plant-Based Milk Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia Pacific Plant-Based Milk Market. Barista-grade formulation expertise and aseptic processing capability define the technology tier, while multi-brand portfolio scale and heritage distribution networks anchor the cost-efficient tier. Three archetypes dominate: specialty formulation specialists, diversified nutrition conglomerates, and heritage beverage brands extending into adjacent categories. Competitive moves concentrate on direct café procurement contracts and cold-chain infrastructure partnerships that bypass traditional retail slotting structures.
Among the diversified nutrition conglomerates, Danone SA occupies a position exemplifying multi-brand portfolio breadth across soy and almond segments. Vitasoy International Holdings Ltd anchors heritage soy milk positioning while extending into oat-based lines for younger demographics. Oatly Group AB represents the specialty formulation archetype through barista-series expertise that secures premium placement in Australian and South Korean coffee channels.
| Leading Market Players |
|---|
| Oatly Group AB |
| Danone SA |
| Vitasoy International Holdings Ltd |
| Califia Farms |
| Blue Diamond Growers |
| Oatside |
| The Hain Celestial Group Inc |
| SunOpta Inc |
| Sanitarium Health and Wellbeing Company |
| Others |
Value Chain & Pricing Dynamics
Barista-grade oat milk substitution for conventional soy formulations simultaneously shifts raw material sourcing toward Australian oat belt concentration and compresses margin structures for processors lacking enzymatic hydrolysis capabilities. This substitution dynamic fragments established pricing benchmarks as FSSAI fortification mandates and China's GB standards impose asymmetric compliance cost burdens across source materials.
Pricing Analysis
FSSAI fortification mandates dictate the pricing tier structure across the Asia Pacific Plant-Based Milk Market by imposing batch-level analytical documentation costs that heritage soy milk brands absorb more efficiently than oat-focused entrants. Three-tier pricing structure across premium barista-grade, standard retail, and economy ambient-stable levels separates formulations by certification intensity and cold-chain dependency. Pricing pressure stems from drought-induced Australian oat supply volatility and beta-glucan quality inconsistency. Health clubs and specialty cafés demonstrate lowest price sensitivity due to specification-intensive procurement, while bulk restaurant channels prioritize economy tiers with extended shelf-life requirements.
Supply Chain Analysis
Just-in-time inventory preferences dominate fresh-format refrigerated segments in China's tier-one cities, while strategic stockpiling of ambient-stable Tetra Pack inventories protects against Australian oat harvest variability. Raw material sourcing draws from Australian oat processors, Indian soy protein concentrate suppliers, and Southeast Asian coconut cream originators. Single-source vulnerability concentrates in Australian oat belt drought exposure, with beta-glucan content inconsistency disrupting viscosity specifications. Distribution runs through supermarket slotting fee negotiations for volume channels and direct-to-consumer subscription platforms for niche formulations in China's tier-two cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment defensive moat where FSSAI fortification mandates and China's GB standards create switching costs for institutional buyers through batch-level analytical documentation requirements. Heritage laboratory networks and established SAMR filing capabilities constitute structural advantages that new entrants cannot replicate without multi-year investment horizons.
For Market Incumbents: Fortify barista-grade formulation capabilities through enzymatic hydrolysis talent acquisition in Melbourne and Seoul procurement corridors, while expanding aseptic filling capacity to defend against fresh-format refrigerated competition from cold-chain maturation in Chinese tier-one cities. Direct processor contracts with independent roasters displace conventional wholesale arrangements and anchor premium placement against oat-focused challengers. For New Entrants and Emerging Players: Halal certification fast-track for Indonesia's nascent plant-based dairy alternative infrastructure creates first-mover positioning before ASEAN harmonization proposals solidify compliance frameworks. Target underpenetrated tier-two Chinese cities through subscription-based oat milk delivery bypassing supermarket slotting fee barriers, with flavor experimentation angles capturing younger demographic conversion from heritage soy milk. For Investors and Strategic Acquirers: Capital is best deployed toward specialty formulation specialists possessing barista-grade certification and established direct café procurement relationships rather than commodity-scale ambient-stable processors facing margin compression. Long-term viability across the projection horizon hinges on enzymatic processing capability and regulatory affairs infrastructure. Watch for MFDS alignment with China's GB standards as inflection indicator for regional consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Barista-Grade Certification Investment | Melbourne and Seoul specialty roasters now mandate viscosity parameters in direct contracts. |
| Cold-Chain Infrastructure Partnership | Refrigerated distribution scale in Shanghai and Beijing enables fresh-format competition against imports. |
| Halal Certification Fast-Track | Indonesia's nascent infrastructure creates first-mover positioning for compliant entrants before harmonization. |
| Enzymatic Hydrolysis Capability Buildout | Southeast Asian processors face talent scarcity for sensory-matched oat milk production protocols. |
| Direct-to-Consumer Subscription Launch | China's tier-two cities bypass supermarket slotting fees through online niche formulation channels. |
Study Parameters
Initial hypotheses were tested against primary input from plant-based milk R&D directors, regulatory affairs managers at heritage beverage brands, specialty café procurement committees, cold-chain logistics operators, and FSSAI compliance consultants, then refined through secondary validation against SAMR batch documentation filings, Australian Food Standards Code amendments, FSSAI fortification circulars, and Nielsen retail audit data. Bottom-up volume triangulation across product type and distribution channel segments converged with top-down market sizing from processor capacity utilization and import customs records.
Variance decomposition across the projection horizon isolates volume drivers by source material substitution rates, regulatory compliance cost absorption differentials, and cold-chain penetration velocity in metropolitan clusters. Segmentation dimensions modeled include product type, end-user application intensity, distribution channel economics, and packaging format shelf-life requirements. CAGRs derive from processor capacity expansion announcements, café procurement cycle documentation, and SAMR provincial placement approvals. Industry-specific forecast inputs incorporate beta-glucan content variability from Australian harvest data and enzymatic hydrolysis yield improvements from patent filings.
Underlying assumptions cover FSSAI fortification mandate enforcement consistency, Australian oat supply stabilization, and ASEAN harmonization proposal timelines, with deviation risk concentrated in drought-induced raw material price volatility and enzymatic processing talent scarcity in Southeast Asian manufacturing clusters. Revision becomes warranted when MFDS regulatory alignment with China's GB standards crosses implementation thresholds or when cold-chain penetration in Chinese tier-two cities accelerates beyond modeled infrastructure deployment rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
China Rice Protein Market
Plant Based Food
Global Organic Soy Protein Market
Plant Based Food
Plant-Based Margarine Market
Plant Based Food
Vegan Flavor Market
Plant Based Food
Europe Plant-Based Food and Beverage Market
Plant Based Food
Europe Meat Substitutes Market
Plant Based Food
Global Plant Based Milk Market
Plant Based Food
Europe Textured Vegetable Protein Market
Plant Based Food
New Jersey Vegan Products Market
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Plant-Based Tzatziki and Labneh Ferment Bases Market
Plant Based Food
Plant-Based Protein Food Market
Plant Based Food
Yellow Pea Protein Market
Plant Based Food
Global Plant Protein Market
Plant Based Food
United States Plant Protein Market
Plant Based Food
India Meat Substitutes Market