
 Germany Soy Protein Market | 2026-2036
Germany Soy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Soy Protein Market Foresight
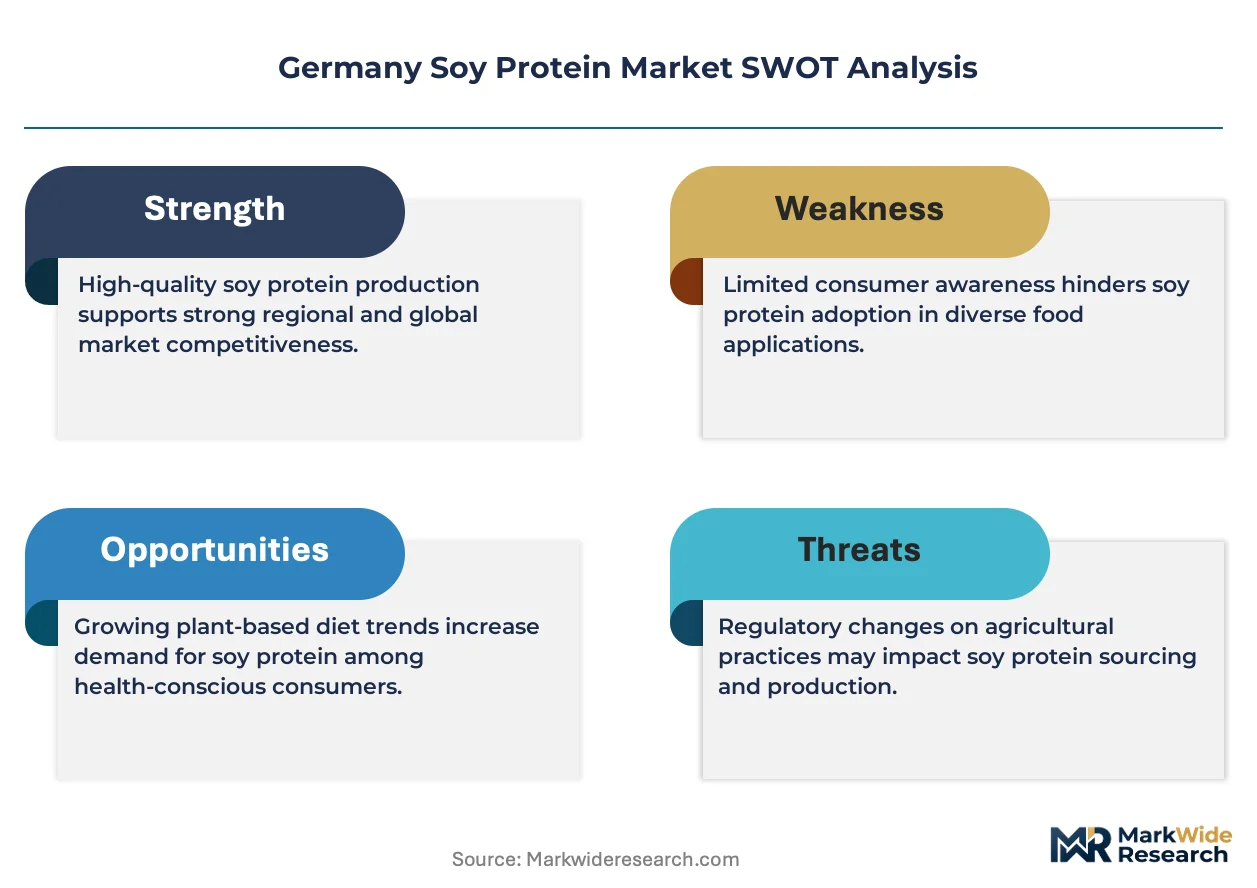
Organic and non-GMO specification tiers is rotating toward the center of German procurement decisions as retailers tighten clean-label requirements. Archer Daniels Midland Company leverages its European crushing footprint to secure identity-preserved soybean flows into Cologne and Hamburg processing nodes. Kerry Group PLC differentiates through customized hydrolysate systems for sports nutrition brands operating out of Bavaria. Brenntag SE controls distribution density across Mittelstand food manufacturers seeking smaller-batch isolate deliveries.
Soy protein comprises refined or minimally processed protein fractions extracted from dehulled, defatted soybeans, typically achieving isolate purities above 90% protein content on a dry basis through alkaline extraction and isoelectric precipitation. Its primary commercial purpose centers on emulsification, gelation, and water-binding in formulated foods where animal protein replacement or cost reduction is sought. Isolate commands the deepest margin pools in pharmaceutical and infant nutrition applications where endotoxin thresholds are most stringent. Textured soy protein competes on throughput economics in industrial meat analogue lines serving German discount retail channels. Hydrolysate occupies the fastest-expanding niche among allergen-reduced pediatric and geriatric nutritional formulations.
German soy protein formulations fall under EFSA novel food assessments for emerging hydrolysate grades and must comply with EU Regulation 1169/2011 on allergen labeling, while BfR evaluates maximum residue limits for processing aids. The EU Deforestation Regulation tightens traceability requirements for imported soybean origins, pushing processors toward certified sustainable supply chains. Stakeholders must monitor how Germany's forthcoming national protein strategy allocates public R&D funding between domestic legume cultivation and imported soy refining infrastructure.
Market Dynamics
The EU Deforestation Regulation is forcing German soy protein processors to rebuild traceability infrastructure from farm gate to isolate output, compressing margins for traders lacking certified supply chain documentation while advantaging identity-preserved operators in Hamburg and Cologne.
Growth Catalysts
- EU Green Deal protein transition targets:Institutional catering contracts in Berlin and Munich now mandate plant protein quotas, pulling isolate volumes into school and hospital nutrition programs.
- Precision fermentation cluster maturation:Baden-Württemberg's biotech corridor is converting soy hydrolysate into recombinant protein precursors, expanding addressable demand beyond traditional food applications.
- Meat analogue line expansion:Bavarian and North Rhine-Westphalian food processors are commissioning textured soy protein extrusion capacity to supply discount retail private-label analogue programs.
Market Restraints
- Import dependency concentration:German crushing capacity relies on Brazilian and Argentine soybean origins, exposing processors to port congestion at Rotterdam and Hamburg.
- Allergen labeling friction:EU Regulation 1169/2011 mandates prominent soy disclosure, limiting formulation flexibility in clean-label product development for pediatric and senior nutrition segments.
- Pulse protein substitution:Pea and fava isolates from Nordic suppliers are capturing share in sports nutrition applications where amino acid completeness is less critical.
Strategic Opportunities
- East German institutional channel:Saxony and Thuringia school catering systems remain underpenetrated by isolate suppliers, presenting volume consolidation potential for regional distributors.
- Emerging pharmaceutical-grade endotoxin thresholds:BfR guidance on parenteral nutrition purity is opening margin pools for processors capable of sub-0.25 EU/g endotoxin certification.
- Hybrid extrusion-convergence:Combining high-moisture extrusion with precision fermentation biomass is enabling next-generation whole-muscle analogue textures for foodservice channels.
Industry Challenges
- Protein separation engineering talent scarcity:German universities produce insufficient isoelectric precipitation specialists, forcing processors to recruit from Dutch and Danish food technology programs.
- EFSA novel food assessment timelines:Emerging hydrolysate grades face 18-24 month authorization delays, freezing product pipeline advancement for startups in the Berlin-Brandenburg corridor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Soy Protein Market |
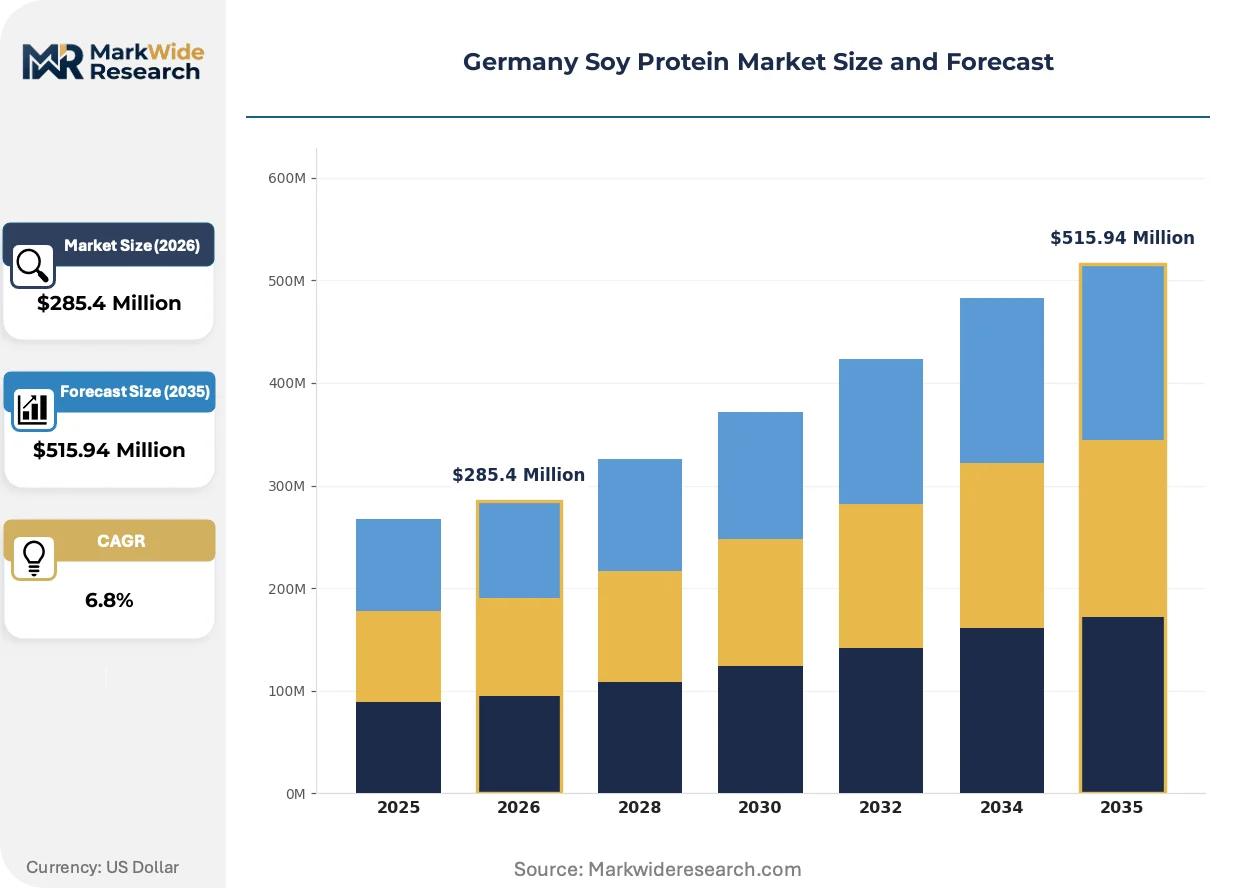
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Textured, Flour, Hydrolysate Application: Bakery, Beverages, Meat Analogues, Dairy Alternatives, Nutritional Supplements End User Industry: Food Processing, Animal Nutrition, Cosmetics, Pharmaceuticals, Personal Care Form: Powder, Liquid, Granules, Fiber, Extrudate |
| Companies Covered | Archer Daniels Midland Company, CHS Inc., International Flavors & Fragrances Inc., Kerry Group PLC, Wilmar International Ltd, Brenntag SE, Costantino & C. SpA, Fuji Oil Group, The Scoular Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Soy Protein Market Shifts & Advancements
Processing technology and regulatory architecture are simultaneously compressing commodity margins and opening premium niches, splitting competitive focus between throughput scale and certification depth.
High-moisture extrusion systems for whole-muscle analogue production are bifurcating the textured soy protein category. Industrial meat processors in North Rhine-Westphalia are adopting twin-screw extruders capable of 80% moisture content, while legacy dry-textured operations serving discount channels defend on kilogram economics. The technology is compressing price realization for standard-grade chunks while enabling premium positioning for fibrous cuts in foodservice.
The EU Deforestation Regulation traceability mandate is restructuring procurement documentation requirements. German processors must now geolocate every soybean plot to GPS coordinates, invalidating traditional paper-based chain-of-custody systems. Small-batch Mittelstand manufacturers lacking blockchain-enabled supplier portals face exclusion from retail contracts with EDEKA and REWE sustainability specifications.
Clean-label preference rotation is altering isolate specification hierarchies. German retailers are tightening non-GMO and organic certification requirements, displacing conventional isolate in branded consumer goods. Bavarian sports nutrition formulators are switching to identity-preserved organic hydrolysate despite 15-20% cost premiums, with the shift most visible in direct-to-consumer channels serving performance-oriented demographics.
Germany Soy Protein Market Segmentation
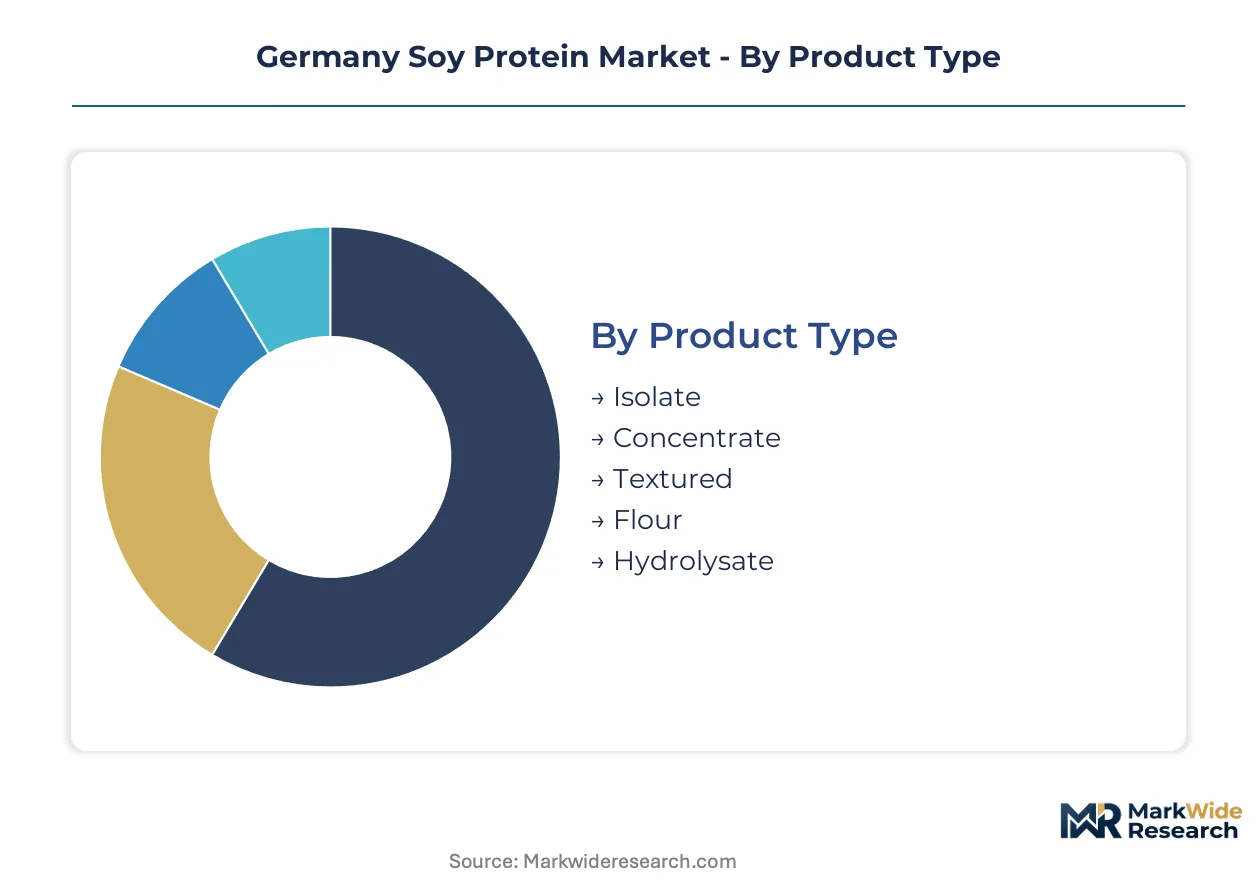
German soy protein procurement stratifies across purity grades, application intensities, and regulatory thresholds that determine margin capture. Each segment tier responds differently to EFSA novel food assessments and the EU Deforestation Regulation's traceability mandates.
Product Type:
Pulse protein substitution pressure concentrates most acutely in lower-purity fractions where amino acid completeness matters less, while pharmaceutical-grade isolates defend position through endotoxin certification barriers.
- Isolate:Achieves above 90% protein content on a dry basis through alkaline extraction and isoelectric precipitation. Demand concentrates in Baden-Württemberg's precision fermentation cluster where recombinant protein precursors require ultra-pure hydrolysate feedstocks, though BfR's tightening endotoxin thresholds for parenteral nutrition are compressing qualified supplier pools.
- Hydrolysate:Enzymatically predigested fractions with reduced allergenicity and faster absorption kinetics. Bavarian sports nutrition formulators are switching to identity-preserved organic grades despite 15-20% cost premiums, with EFSA novel food assessments for emerging grades freezing pipeline advancement for Berlin-Brandenburg startups.
- Textured:Extruded fibrous structures mimicking meat muscle architecture. Bavarian and North Rhine-Westphalian processors are commissioning high-moisture extrusion capacity to supply discount retail private-label analogue programs.
- Concentrate:Intermediate purity fraction retaining more soluble carbohydrates and fiber. Mittelstand bakery manufacturers in Saxony favor concentrate for cost-sensitive applications where emulsification dominates over gelation.
- Flour:Minimally processed full-fat or defatted ground soybean. Organic flour volumes are rising in Thuringia's artisanal baking sector as clean-label preferences displace conventional isolates.
Isolate anchors the volume base while hydrolysate gains share at the steepest rate.
Application:
Cost tier stratification separates premium-positioned categories commanding formulation flexibility from commodity segments defending on kilogram economics.
- Meat Analogues:Industrial extrusion of textured soy protein into fibrous whole-muscle structures. North Rhine-Westphalian food processors are adopting twin-screw systems capable of 80% moisture content, enabling premium positioning in foodservice channels while compressing margins for standard-grade chunks.
- Nutritional Supplements:Sports nutrition, pediatric, and geriatric formulations demanding allergen-reduced or organic-certified inputs. Bavarian direct-to-consumer brands are absorbing identity-preserved organic hydrolysate premiums to serve performance-oriented demographics.
- Bakery:Emulsification and water-binding in bread, pastries, and industrial baked goods. EDEKA and REWE clean-label specifications are displacing conventional isolate in branded consumer goods.
- Beverages:Plant-based milk alternatives and protein-fortified drinks. Berlin-Brandenburg alt-protein startups are targeting ready-to-drink formats with novel hydrolysate grades.
- Dairy Alternatives:Yogurt, cheese analogues, and frozen desserts requiring gelation and fat mimetic properties. Thuringia's underpenetrated institutional channels present consolidation potential for regional distributors.
Meat analogues dominate current procurement volumes while nutritional supplements expand most quickly.
End User Industry:
Customer type maturity separates established food processing incumbents with integrated procurement systems from emerging pharmaceutical buyers demanding documentation depth.
- Food Processing:Mittelstand manufacturers across Bavaria and North Rhine-Westphalia sourcing isolate, concentrate, and textured grades for meat analogue and bakery applications. Brenntag SE controls distribution density for smaller-batch deliveries lacking blockchain-enabled supplier portals.
- Pharmaceuticals:Parenteral and enteral nutrition formulations requiring sub-0.25 EU/g endotoxin certification. BfR guidance is opening margin pools for processors capable of pharmaceutical-grade purification.
- Animal Nutrition:Feed-grade soy protein for aquaculture and livestock. Import dependency on Brazilian and Argentine origins exposes compounders to Rotterdam and Hamburg port congestion.
- Cosmetics:Hair and skin conditioning applications leveraging soy protein film-forming properties. Smaller-batch organic specifications are rising among regional formulators.
- Personal Care:Cleansing and moisturizing products utilizing soy-derived amino acid profiles. Niche demand concentrates in certified natural and organic product lines.
Food processing anchors the volume base while pharmaceuticals climbs the fastest.
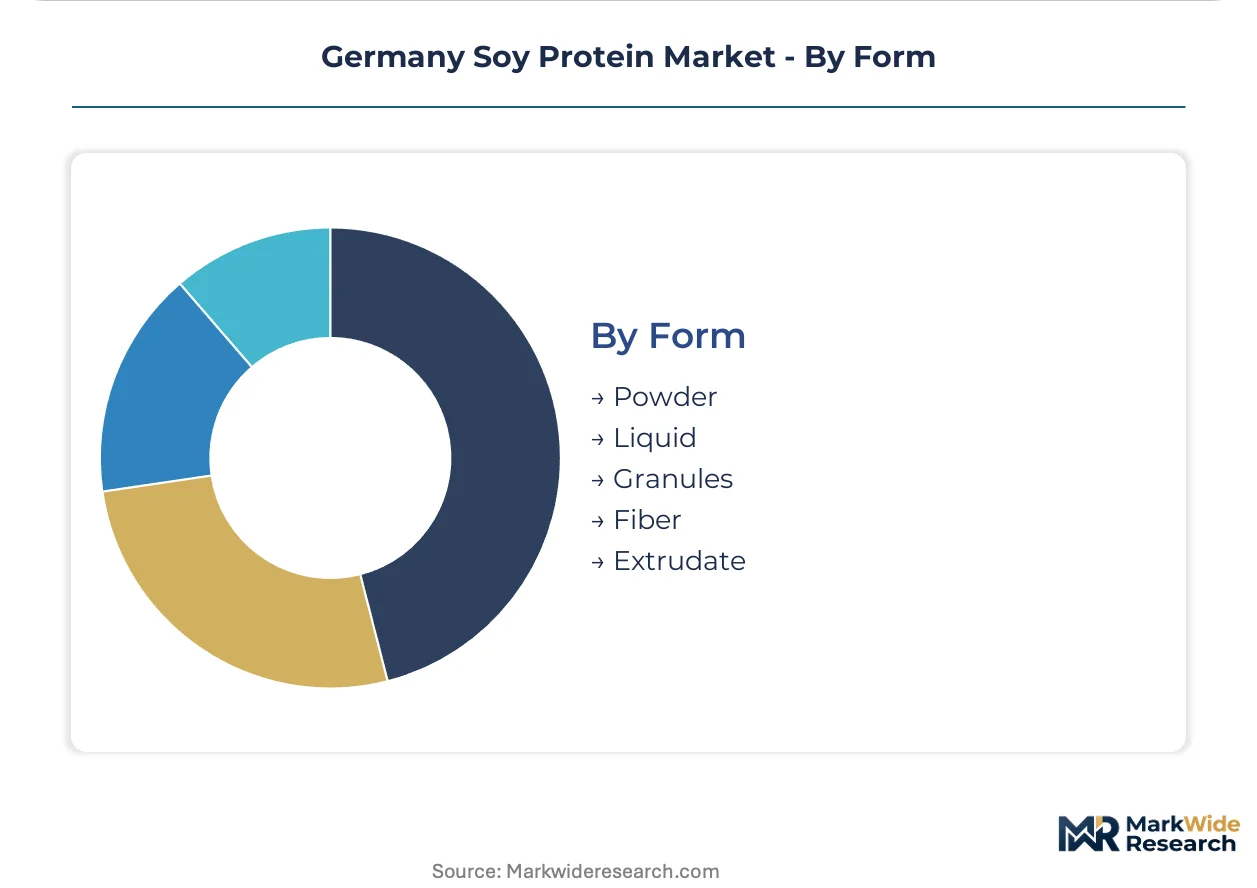
Form:
Supply concentration in powder processing infrastructure leaves liquid and specialized formats dependent on smaller-scale toll manufacturing networks.
- Powder:Spray-dried isolates and concentrates dominating bulk procurement. Archer Daniels Midland Company's European crushing footprint secures identity-preserved flows into Cologne and Hamburg processing nodes.
- Liquid:Pre-hydrated suspensions for beverage and dairy alternative applications. Kerry Group PLC differentiates through customized hydrolysate systems for sports nutrition brands.
- Granules:Agglomerated particles improving dispersibility in instant applications. Bakery manufacturers favor granules for reduced dusting during high-speed mixing operations.
- Fiber:Insoluble carbohydrate fractions for digestive health positioning. Emerging demand in functional food formulations remains constrained by EFSA health claim authorization timelines.
- Extrudate:Direct-expanded or high-moisture extruded structures for meat analogue applications. Hybrid extrusion-precision fermentation convergence is enabling next-generation whole-muscle textures.
Powder anchors the volume base while extrudate gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's soy protein trade balance tilts toward import dependency, with crushing capacity concentrated at Hamburg and Cologne processing nodes drawing Brazilian and Argentine feedstock. Regional demand clusters reflect distinct application intensities across federal states.
Bavaria
Meat analogue manufacturers in Bavaria are commissioning high-moisture extrusion lines to supply discount retail private-label programs. The state's National Nutrition Strategy implementation mandates plant protein quotas in Munich institutional catering. Food processors around Nuremberg and Augsburg are absorbing identity-preserved organic hydrolysate premiums for sports nutrition formulations.
North Rhine-Westphalia
Industrial extrusion capacity for textured soy protein is expanding across the Ruhr industrial corridor to serve EDEKA and REWE sustainability specifications. The EU Deforestation Regulation's geolocation requirements are forcing processors to rebuild blockchain-enabled supplier portals. Cologne anchors crushing infrastructure for Archer Daniels Midland Company's European footprint.
Baden-Württemberg
Precision fermentation startups in the Stuttgart biotech corridor are converting soy hydrolysate into recombinant protein precursors. BfR guidance on parenteral nutrition purity is opening margin pools for pharmaceutical-grade endotoxin certification. The cluster draws ultra-pure isolate feedstocks from specialized toll manufacturers.
Berlin-Brandenburg
Alt-protein startups in the Berlin corridor face EFSA novel food assessment timelines of 18-24 months for emerging hydrolysate grades. Clean-label preference rotation is displacing conventional isolate in direct-to-consumer channels. Regional distributors are consolidating underpenetrated school catering systems in surrounding federal states.
Hamburg
Port congestion at Hamburg exposes crushing operations to supply chain volatility from Brazilian soybean origins. The EU Deforestation Regulation traceability mandate is invalidating traditional paper-based chain-of-custody systems. Identity-preserved operators are securing retail contracts through certified sustainable supply chain documentation.
Germany Soy Protein Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and supply chain traceability capabilities. The vendor base stratifies between multinational traders with integrated crushing infrastructure and regional distributors serving Mittelstand batch requirements. Three archetypes dominate: identity-preserved supply chain operators, customized hydrolysate formulators, and distribution-density controllers. Competitive moves concentrate on M&A for traceability technology and capacity expansion for high-moisture extrusion systems.
Within the integrated supply chain tier, Archer Daniels Midland Company and Wilmar International Ltd represent crushing-footprint operators securing feedstock flows into European processing nodes. Kerry Group PLC exemplifies the formulation-specialist archetype, occupying a position among customized hydrolysate providers. Brenntag SE anchors the distribution-density vector, sitting within the regional logistics tier controlling smaller-batch isolate deliveries to Mittelstand manufacturers.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| CHS Inc. |
| International Flavors & Fragrances Inc. |
| Kerry Group PLC |
| Wilmar International Ltd |
| Brenntag SE |
| Costantino & C. SpA |
| Fuji Oil Group |
| The Scoular Company |
| Others |
Supply & Pricing Matrix
The EU Deforestation Regulation gates both supply qualification and price differentiation simultaneously, forcing German processors to absorb blockchain-enabled traceability costs while retailers tier contracts around certified sustainable documentation.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command spreads through identity-preserved organic certification and sub-0.25 EU/g endotoxin thresholds, while discount retail channels defend on kilogram economics for conventional textured grades. Cost compression in standard isolates is intensifying because Brazilian and Argentine import dependency exposes processors to Rotterdam and Hamburg port congestion volatility. Mittelstand bakery manufacturers in Saxony exhibit highest price sensitivity, whereas Bavarian sports nutrition formulators absorb 15-20% organic hydrolysate premiums for clean-label positioning.
Supply Chain Analysis
Inventory buffers at Cologne and Hamburg processing nodes stretch lead times when Brazilian soybean arrivals face documentation delays under geolocation mandates. German crushing capacity draws from Brazilian and Argentine origins, with specialized toll manufacturers in Baden-Württemberg feeding ultra-pure isolates to precision fermentation clusters. Single-source vulnerability concentrates in Rotterdam-Hamburg port corridors, where congestion cascades through Mittelstand just-in-time systems. Distribution runs through Brenntag SE's regional logistics density for smaller-batch isolate deliveries, while Archer Daniels Midland Company's European footprint secures bulk flows into major processing nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German soy protein procurement is approaching a platform-economics inflection where EFSA novel food assessment interoperability will determine which hydrolysate grades achieve cross-border formulation acceptance.
For Market Incumbents: Consolidate traceability infrastructure investments to defend against identity-preserved operators capturing EDEKA and REWE sustainability contracts. Deepen backward integration into certified South American crushing assets to hedge EU Deforestation Regulation documentation requirements. Prioritize high-moisture extrusion capacity additions in North Rhine-Westphalia to serve discount retail private-label expansion. For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade endotoxin certification where BfR guidance is compressing qualified supplier pools. Target Thuringia and Saxony institutional catering systems as underpenetrated volume consolidation opportunities. Pursue direct-to-consumer sports nutrition channels with identity-preserved organic hydrolysate formulations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed precision fermentation toll manufacturers in Baden-Württemberg seeking exit liquidity. Five-to-ten year viability hinges on EFSA novel food assessment pipeline throughput rather than commodity margin recovery. Monitor Berlin-Brandenburg startup authorization timelines as inflection indicator for emerging hydrolysate grade commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Enabled Traceability Deployment | EU Deforestation Regulation compliance secures EDEKA and REWE retail contract eligibility. |
| High-Moisture Extrusion Capacity Expansion | Ruhr corridor processors capture discount retail private-label analogue program volumes. |
| Pharmaceutical-Grade Endotoxin Certification | BfR parenteral nutrition guidance opens margin pools for qualified isolate suppliers. |
| Precision Fermentation Feedstock Partnership | Baden-Württemberg biotech corridor converts soy hydrolysate into recombinant protein precursors. |
| East German Institutional Channel Consolidation | Saxony and Thuringia school catering systems present volume aggregation opportunities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of BfR guidance documents, EFSA novel food registers, EU trade flow databases, and industry association procurement surveys. Interviews conducted with soy protein plant managers, Mittelstand food manufacturer procurement leads, distribution channel partners, and precision fermentation R&D directors informed demand-side validation. Secondary sources included customs and trade data, SEC filings of listed processors, and EDEKA and REWE sustainability specification disclosures. Bottom-up volume modeling triangulated against top-down protein transition target allocations.
Segmentation dimensions modeled span purity grade tier, application intensity, end-use industry, and regional production cluster across the analysis window. CAGRs derived from elasticity-adjusted demand projections incorporating EU Green Deal protein transition mandates and institutional catering contract volumes. Forecast inputs included precision fermentation cluster maturation rates and EFSA novel food assessment pipeline throughput assumptions.
The analysis sits within stated boundaries; outcomes outside sustained EU Deforestation Regulation enforcement intensity or accelerated EFSA authorization timelines would require recalibration. Forecasts reflect documented assumptions around Brazilian and Argentine supply continuity and German institutional procurement mandate implementation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Flavor Market
Plant Based Food
Meatless Meat Market
Plant Based Food
Vegan Noodles Market
Plant Based Food
Veggie Meals Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Vegan Chocolate Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Fermented Plant Extracts Market
Plant Based Food
China Pea Protein Market
Plant Based Food
Oat Protein Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Global Plant Based Milk Market
Plant Based Food
Europe Tofu Market
Plant Based Food
Chicory Roots Market