
 South America Rice Protein Market | 2026-2036
South America Rice Protein Market Size, Share, and Industry Trends Forecast 2026-2036
South America Rice Protein Market Analytics
Asset-light contract manufacturing is reconfiguring competitive entry in South America rice protein, allowing regional brands to bypass capital-intensive extraction facilities. Axiom Foods leverages its proprietary hexane-free processing to sustain quality differentiation across Brazilian nutrition channels. Golden Grain Group Limited anchors supply reliability through backward integration into rice milling operations in Asia that feed South American distribution. BENEO GmbH competes on clean-label positioning, extending its regulatory dossier depth into Mercosur markets.
Rice protein denotes the concentrated protein fraction extracted from rice bran or brown rice through enzymatic or alkaline processing, typically yielding 80-90% protein content with a balanced amino acid profile including methionine and cysteine. The ingredient serves primarily as a hypoallergenic alternative to soy and whey in human nutrition and specialized animal feed formulations. Isolate commands premium positioning due to superior protein concentration and minimal carbohydrate carryover, while hydrolysate gains traction in rapid-absorption sports nutrition applications. Powder dominates form preferences for industrial blending flexibility, though liquid concentrates penetrate beverage manufacturing for ready-to-drink protein products.
ANVISA governs food supplement registration and ingredient safety assessments in Brazil, directly influencing product formulation standards and import clearance timelines for rice protein suppliers. Argentina's national food code and Mercosur harmonization protocols shape cross-border trade conditions and labeling requirements across the Southern Cone. ISO 22000 and HACCP certification operate as baseline market access credentials for ingredient suppliers serving multinational food manufacturers. Stakeholders must track evolving novel food consultations in Chile and Peru, where regulatory precedents for plant protein claims remain unsettled and create first-mover certification advantages.
Market Dynamics
ANVISA's updated food supplement labeling rules are tightening ingredient transparency requirements across Brazilian nutrition channels, forcing suppliers to reconfigure compliance infrastructure and documentation workflows.
Growth Catalysts
- ANVISA Labeling Mandates:Brazil's food supplement regulator now demands granular protein source disclosure, creating first-mover advantages for suppliers with pre-built dossier depth.
- Sports Nutrition Formulation:Brazilian athletic nutrition brands are accelerating isolate adoption for rapid-absorption protein products targeting endurance and strength segments.
- Enzymatic Extraction Methods:Hexane-free processing advances are lowering residual solvent risk profiles and opening Mercosur market access for premium-positioned suppliers.
Market Restraints
- Input Cost Volatility:Brown rice bran supply fluctuations in Asian milling operations transmit price instability into South American ingredient costs.
- Supply Concentration Risk:Backward-integrated Asian rice processors control upstream raw material flows, creating single-source dependencies for regional distributors.
- Technical Limitation:Rice protein's incomplete amino acid profile relative to whey requires costly blending with pea or pumpkin proteins to achieve PDCAAS parity.
Strategic Opportunities
- Underpenetrated Geography:Chile's novel food consultation pathway remains unsettled, offering certification-first suppliers a window to establish regulatory precedent.
- Regulatory Tailwind:Argentina's national food code harmonization with Mercosur protocols is streamlining cross-border labeling and reducing duplicate compliance burdens.
- Emerging Application:Ready-to-drink beverage manufacturing in São Paulo and Buenos Aires is creating pull for liquid concentrate formats with extended shelf stability.
Industry Challenges
- Certification Timeline Compression:ISO 22000 and HACCP audits for multinational food manufacturers are extending lead times by four to six months, straining working capital cycles.
- Capex Intensity:Dedicated enzymatic processing lines for isolate production require seven-figure equipment commitments that regional contract manufacturers struggle to finance.
- Skill Gap in Regulatory Affairs:Mercosur technical barrier navigation expertise remains scarce in São Paulo and Buenos Aires talent pools, inflating specialist compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Rice Protein Market |
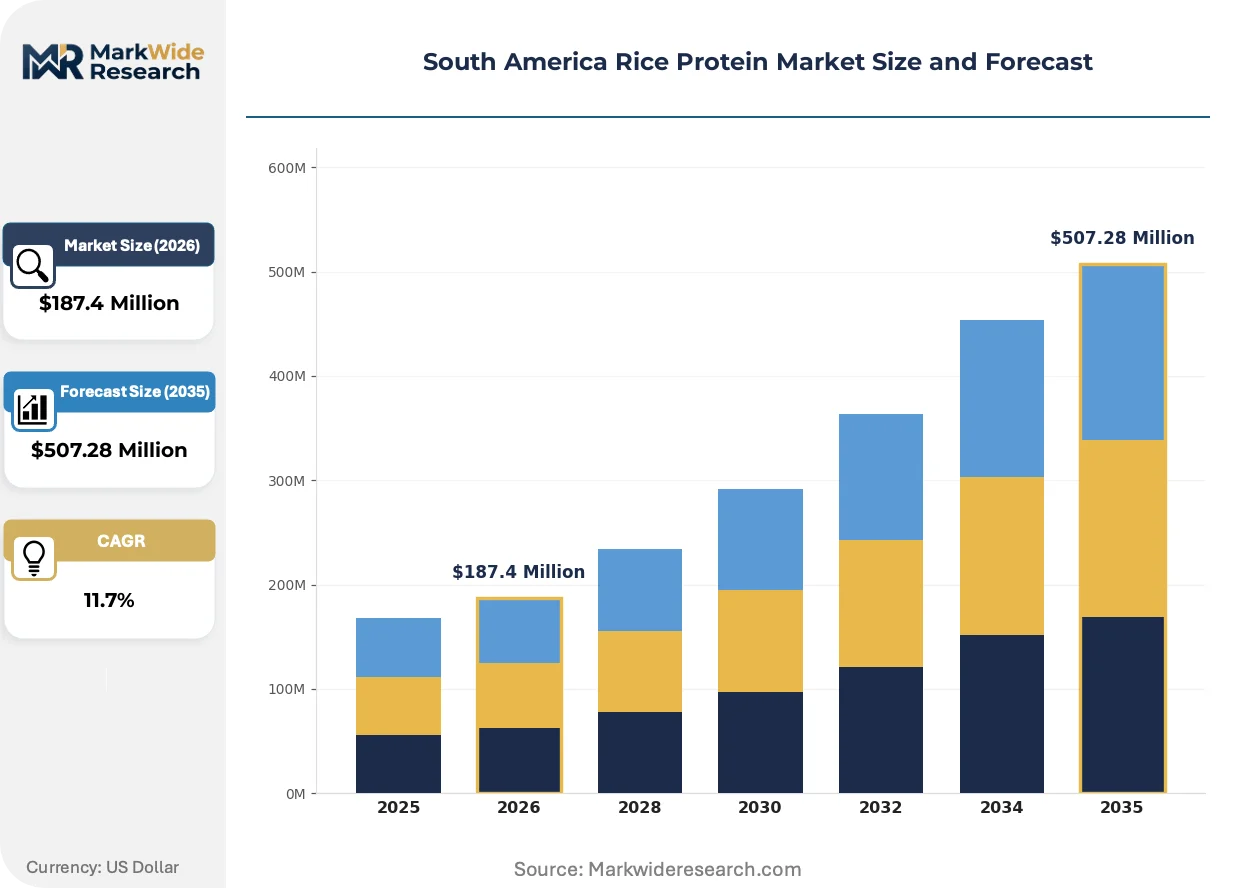
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Hydrolysate, Blend End User: Nutrition Supplements, Food & Beverages, Animal Feed, Bakery Products Form: Powder, Liquid, Granules, Capsules Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | RiceBran Technologies, Axiom Foods, BENEO GmbH, Pure Foods Company, NutriBiotic, AIDP Inc., Golden Grain Group Limited, Shafi Gluco-Chem, Ribus Inc., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Rice Protein Market Evolving Landscape
Processing technology convergence and regulatory disclosure requirements are reshaping competitive positioning in South American rice protein, with suppliers racing to build compliance infrastructure ahead of enforcement deadlines.
Enzymatic hydrolysis systems are hybridizing with traditional alkaline extraction to produce rapid-absorption isolates with improved solubility profiles. Brazilian sports nutrition formulators are adopting these hybrid-processed ingredients at twice the pace of standard isolates. The technology is hybridizing quality tiers, compressing the performance gap between premium hydrolysates and mid-market concentrates.
ANVISA's updated food supplement labeling rules now mandate protein source traceability down to the extraction method. This regulatory shift is forcing importers to rebuild documentation chains and reject non-compliant Asian suppliers. Brazilian contract manufacturers with pre-positioned dossiers are capturing shelf space from competitors scrambling to retrofit compliance.
Buyer concentration among São Paulo-based sports nutrition brands is consolidating procurement decisions into fewer technical gatekeepers. Direct supplier relationships are displacing traditional ingredient distributor networks for volume commitments above twenty metric tons annually. This pattern is most visible in isolate purchasing for premium whey-alternative formulations.
South America Rice Protein Market Segmentation
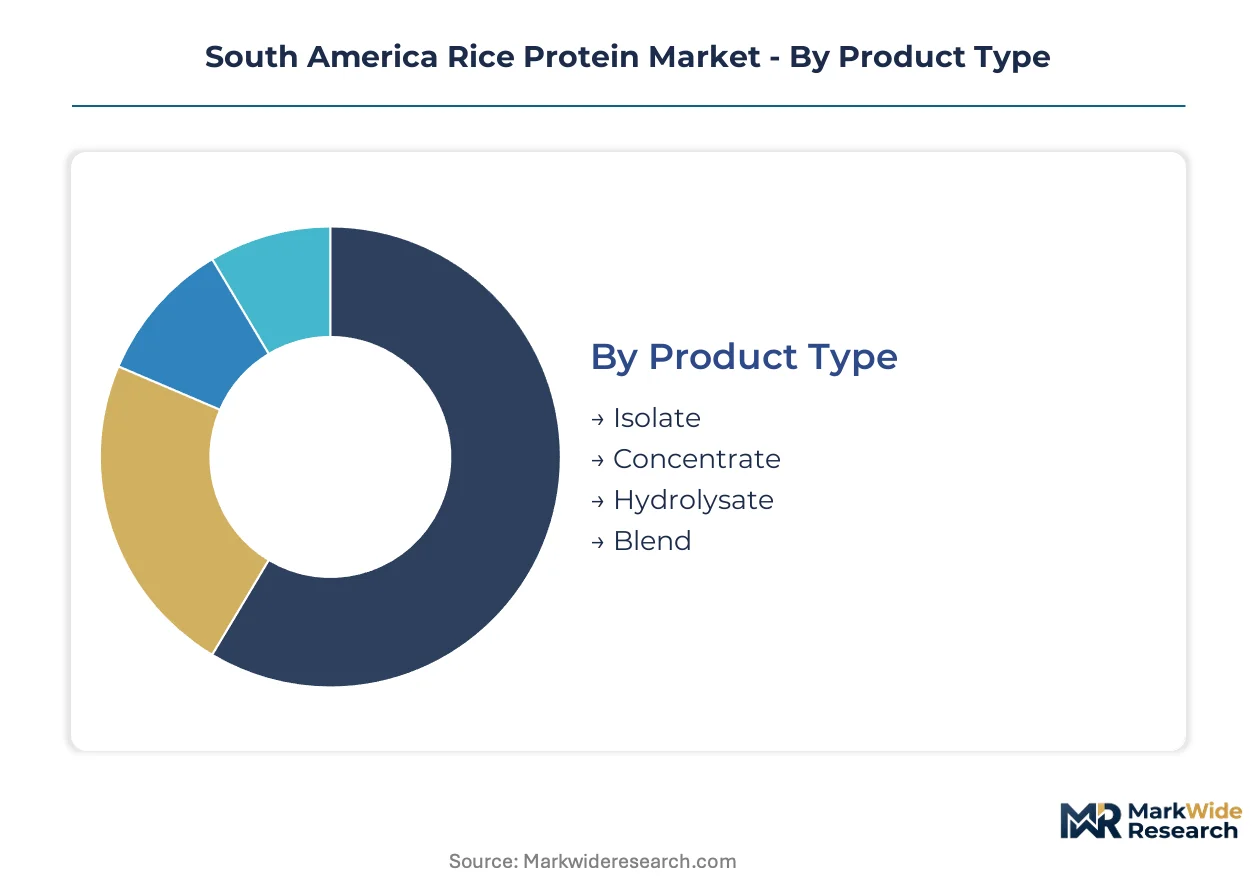
Rice protein suppliers in South America configure their service models around segment-specific technical support demands. Isolate buyers require extensive formulation assistance, while commodity concentrate purchasers prioritize logistics reliability over laboratory collaboration.
Product Type:
After-sales service intensity varies sharply across protein grades, with isolate commanding dedicated technical account management and hydrolysate requiring rapid troubleshooting for enzymatic stability issues.
- Isolate:Enzymatic or alkaline extraction yields 80-90% protein with minimal carbohydrate carryover. Brazilian sports nutrition brands in São Paulo concentrate procurement here for premium whey-alternative positioning, though ANVISA dossier requirements extend onboarding timelines.
- Concentrate:Lower protein fraction retains more fiber and starch, suitable for cost-sensitive applications. Argentine food manufacturers drive volume absorption for plant-based meat extenders where protein purity matters less than emulsification performance.
- Hydrolysate:Pre-digested peptides enable rapid absorption profiles. Chilean novel food consultations create regulatory uncertainty for this advanced grade.
- Blend:Combined rice-pea or rice-pumpkin formulations address PDCAAS limitations. Brazilian contract manufacturers favor these for turnkey sports nutrition solutions.
By volume, Concentrate leads. By growth pace, Hydrolysate is ahead.
End User:
Cost tier stratification separates premium-positioned nutrition supplements from commodity-driven animal feed applications, with food and beverages occupying the contested middle ground.
- Nutrition Supplements:Sports nutrition and wellness brands in Brazil formulate protein powders, bars, and recovery drinks. ANVISA labeling mandates force granular protein source disclosure, advantaging suppliers with pre-built compliance infrastructure.
- Food & Beverages:Plant-based dairy alternatives and functional beverages incorporate rice protein for clean-label positioning. Buenos Aires-based ready-to-drink manufacturers are expanding liquid concentrate offtake.
- Animal Feed:Hypoallergenic protein source for specialized pet nutrition and aquaculture. Argentine soy belt proximity creates price competition pressure.
- Bakery Products:Gluten-free bread and pastry applications leverage rice protein for structure and moisture retention. Brazilian industrial bakeries in Minas Gerais test isolate enrichment for protein claims.
By volume, Animal Feed leads. By margin capture, Nutrition Supplements is ahead.
Form:
Customer type determines packaging and handling requirements, with industrial manufacturers preferring bulk powder and retail-channel suppliers needing consumer-ready unitization.
- Powder:Dominant industrial format for blending flexibility across applications. Brazilian contract manufacturers in São Paulo state standardize on 20-kilogram bags for sports nutrition production.
- Liquid:Concentrated suspensions for ready-to-drink beverage manufacturing. Extended shelf stability requirements favor aseptic processing investments by Buenos Aires suppliers.
- Granules:Intermediate flowability for tableting operations. Argentine supplement compressors favor this format for capsule filling efficiency.
- Capsules:Pre-dosed unitization for direct-to-consumer wellness brands. Online retail channel growth in Chile drives small-batch demand.
By volume, Powder leads. By value per kilogram, Capsules is ahead.
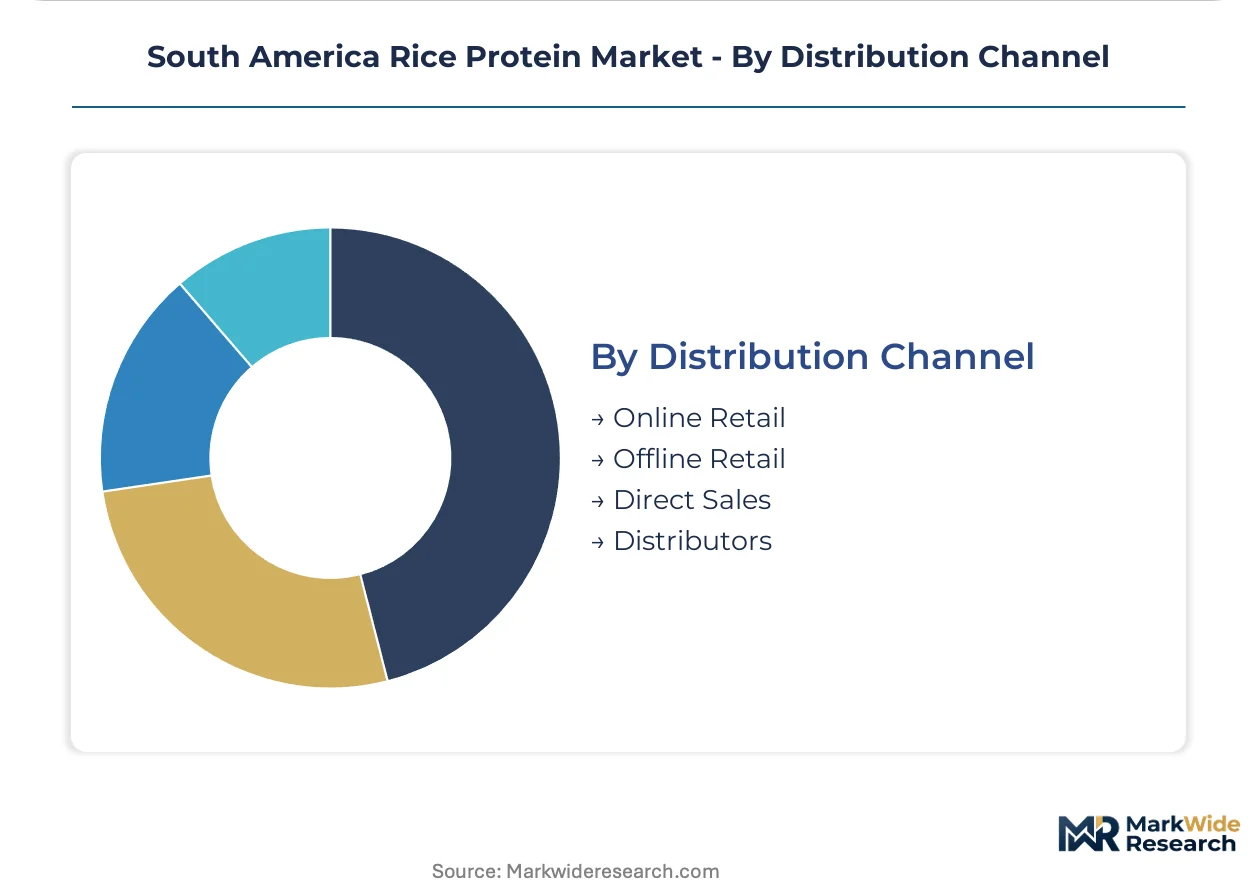
Distribution Channel:
Supply concentration in Asian upstream milling shapes channel economics, with direct sales capturing volume commitments above twenty metric tons and distributor networks serving fragmented regional buyers.
- Online Retail:E-commerce platforms serve Brazilian and Argentine direct-to-consumer brands with small-batch flexibility. Logistics complexity limits isolate availability through this channel.
- Offline Retail:Traditional ingredient distributors maintain regional warehouse stocks for mid-size manufacturers. Mercosur cross-border harmonization reduces duplicate inventory requirements.
- Direct Sales:Volume buyers above twenty metric tons annually negotiate direct supplier relationships. São Paulo-based sports nutrition brands consolidate procurement through this channel.
- Distributors:Specialist food ingredient networks provide technical support and credit terms. Working capital cycles extend by four to six months for ISO 22000-certified multinational suppliers.
By volume, Direct Sales leads. By customer reach expansion, Online Retail is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's updated labeling mandates and Mercosur harmonization protocols are redrawing competitive access across South American rice protein markets, with regulatory dossier depth becoming the decisive market entry credential.
Brazil
São Paulo-based sports nutrition brands concentrate procurement for isolate grades, while ANVISA's granular protein source disclosure rules extend supplier onboarding timelines. Brazilian contract manufacturers with pre-positioned compliance infrastructure capture shelf space from competitors scrambling to retrofit documentation chains.
Argentina
Buenos Aires ready-to-drink manufacturers expand liquid concentrate offtake as plant-based food sector demand anchors isolate absorption. National food code harmonization with Mercosur protocols streamlines cross-border labeling and reduces duplicate compliance burdens for regional distributors.
Chile
Novel food consultation pathways remain unsettled for hydrolysate grades, creating certification-first windows for suppliers establishing regulatory precedent. Santiago and Valparaíso industrial clusters test small-batch capsule demand driven by online retail channel expansion.
Peru
Evolving novel food consultations for plant protein claims generate first-mover certification advantages for prepared suppliers. Lima-based ingredient importers rebuild documentation chains to meet emerging traceability requirements for extraction method disclosure.
Colombia
Bogotá and Medellín nutrition supplement distributors develop regional warehouse networks as Mercosur cross-border harmonization reduces inventory duplication. Mid-size manufacturers prioritize logistics reliability over laboratory collaboration for concentrate procurement.
South America Rice Protein Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure shaped by Asian upstream concentration and regional compliance fragmentation. Three to five backward-integrated Asian rice processors dominate raw material flows, while Brazilian contract manufacturers and Mercosur-focused ingredient distributors occupy midstream positions. Strategic archetypes separate hexane-free processing specialists, clean-label positioning players, and supply reliability anchors. Competitive moves concentrate on regulatory dossier depth expansion and direct supplier relationship consolidation above twenty metric ton annual commitments.
Among Asia-Pacific-based upstream controllers, Golden Grain Group Limited and Shafi Gluco-Chem represent supply reliability archetypes through backward integration into rice milling operations. Axiom Foods exemplifies the processing-specialist tier with proprietary hexane-free extraction positioning. BENEO GmbH occupies the clean-label regulatory depth segment, extending dossier infrastructure into Mercosur markets. These three anchors illustrate how quality differentiation, supply security, and compliance infrastructure define competitive positioning in South American rice protein channels.
| Leading Market Players |
|---|
| RiceBran Technologies |
| Axiom Foods |
| BENEO GmbH |
| Pure Foods Company |
| NutriBiotic |
| AIDP Inc. |
| Golden Grain Group Limited |
| Shafi Gluco-Chem |
| Ribus Inc. |
| Others |
Value Network & Pricing Analysis
Jiangsu and Zhejiang province milling clusters in eastern China control enzymatic extraction capacity that feeds South American isolate demand, with their output fluctuations transmitting directly into Brazilian sports nutrition procurement costs. ANVISA's traceability mandates force importers to absorb documentation overhead that compresses distributor margins on concentrate grades.
Pricing Analysis
Certification level creates the primary spread between ISO 22000-certified isolates and uncertified concentrates, with HACCP dossier depth commanding fifteen to twenty percent premiums in São Paulo contract manufacturing channels. Three-tier pricing structure across premium hydrolysate, standard isolate, and economy concentrate segments stratifies buyer access. Pricing pressure stems from Asian brown rice bran supply tightening, which compresses margins on mid-grade offerings. Animal feed purchasers exhibit highest price sensitivity, while Brazilian sports nutrition brands prioritize certification tier over unit cost.
Supply Chain Analysis
Tariff exposure between China and Brazil dominates upstream risk calculus for regional distributors dependent on Jiangsu-origin isolate shipments. Supply concentrates in China, Thailand, and Vietnam, with enzymatic processing equipment and food-grade rice bran as critical input dependencies. Single-source vulnerability pervades the channel, as three to five backward-integrated Asian processors control raw material flows into Mercosur markets. Distribution runs through direct supplier relationships for volume commitments above twenty metric tons, while specialist ingredient networks serve fragmented mid-size manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's traceability mandates and enzymatic extraction advances are disrupting incumbent positioning, creating windows for compliance-first suppliers to capture shelf space from documentation-scrambled competitors.
For Market Incumbents: Entrench regulatory dossier depth as the primary defensive moat, accelerating ISO 22000 audit completion ahead of enforcement deadlines to deny oxygen to retrofitting rivals. Deepen backward integration into Asian rice milling operations to secure captive supply of food-grade bran against input cost volatility threatening margin stability. For New Entrants and Emerging Players: Chile's unsettled novel food consultation pathway offers first-mover certification advantages for hydrolysate-grade suppliers establishing regulatory precedent before competitors. Target Buenos Aires ready-to-drink manufacturers with liquid concentrate formats, leveraging aseptic processing partnerships as the go-to-market angle to bypass powder-dominated incumbent relationships. For Investors and Strategic Acquirers: Long-term, this sits as a clean-label ingredient consolidation play because ANVISA's transparency mandates will structurally favor scaled suppliers with pre-built compliance infrastructure over fragmented regional traders. Watch enzymatic hydrolysis patent filings as the signal indicating processing technology inflection and quality tier compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Expansion | ANVISA traceability mandates reward pre-positioned ISO 22000 documentation with faster market access. |
| Backward Integration into Rice Milling | Captive supply of food-grade bran insulates against Asian input cost volatility hitting concentrate margins. |
| Enzymatic Hydrolysis Patent Development | Hybrid processing patents compress performance gaps between hydrolysate and isolate quality tiers. |
| Liquid Concentrate Format Launch | Buenos Aires and São Paulo beverage manufacturers pull for extended-shelf-stability aseptic suspensions. |
| Direct Supplier Relationship Consolidation | São Paulo sports nutrition brands displace distributor networks for volume commitments above twenty metric tons. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANVISA regulatory filings, Mercosur trade databases, and Asian rice milling export records, combining structured interviews with Brazilian contract manufacturing procurement leads, Argentine food formulation R&D directors, and Chilean supplement regulatory consultants with bottom-up and top-down triangulation validation.
Forecast inputs span protein grade tier, end-use application intensity, form factor preference, and distribution channel concentration across the analysis window, with CAGRs derived from segment-level volume trajectories and price elasticity modeling. Enzymatic extraction capacity expansion timelines and ANVISA enforcement schedule phasing served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates or Asian rice harvest yields would shift the trajectory of import cost structures and isolate affordability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Africa Soy Beverages Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
United States Rice Protein Market
Plant Based Food
Plant-Based Waters Market
Plant Based Food
Vegan Pizza Crust Market
Plant Based Food
Faba Bean Protein Market
Plant Based Food
Rice Protein Market
Plant Based Food
Plant-Based Food Ingredients Market
Plant Based Food
Global Plant Based Food Market
Plant Based Food
Plant-Based Beef Market
Plant Based Food
Plant-Based Wafer Biscuits Market
Plant Based Food
Fractionated Pulses Market
Plant Based Food
Kava Root Extract Market
Plant Based Food
Soy Food Products Market
Plant Based Food
United Kingdom Tofu Market
Plant Based Food
China Pea Protein Market