
 Fermented Protein Market | 2026-2036
Fermented Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Protein Market Foresight
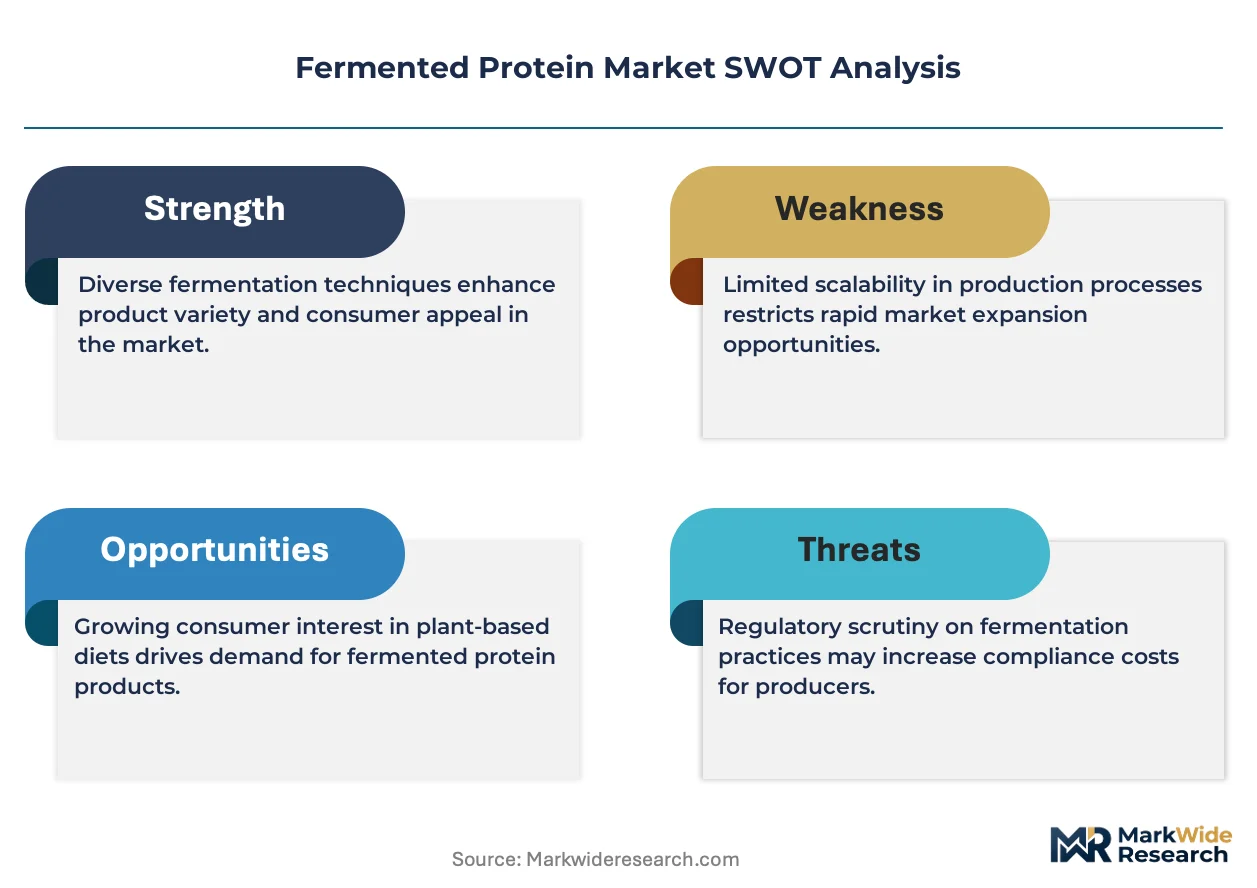
Premium isolate grades are unwinding commodity pricing structures as manufacturers command higher unit economics for ultra-pure fermented proteins. Perfect Day, Inc. leverages precision fermentation infrastructure to supply animal-free dairy proteins at commercial scale. Cargill, Incorporated anchors global distribution networks that connect bioreactor outputs to CPG formulators across multiple continents. Koninklijke DSM N.V. dominates strain development and bioprocess engineering, supplying the enzymatic backbone that powers competitor manufacturing lines.
Fermented protein denotes biomass or precision-fermented protein products cultivated via microbial hosts in controlled bioreactor environments, typically achieving protein concentrations exceeding 70% dry weight with complete amino acid profiles comparable to animal-derived equivalents. These ingredients serve as functional replacements for conventional dairy, egg, and plant proteins across sports nutrition, clinical nutrition, and alternative dairy applications. Whey protein and casein protein variants lead current revenue pools due to their direct substitutability in existing food processing lines, while pea protein fermentation is expanding fastest as manufacturers seek to bypass agricultural yield volatility and allergen concerns. The isolate formulation tier captures the dominant margin pool because downstream brands pay premiums for neutral flavor profiles and minimal carbohydrate carryover.
The FDA GRAS notification pathway and EU Novel Food Regulation govern market access for fermented protein ingredients in North America and Europe, with EFSA safety evaluations creating de facto approval timelines that shape capital deployment decisions. BIS food safety standards and FSSAI ingredient classifications in India add compliance layers for exporters targeting emerging nutrition markets. Stakeholders must monitor evolving precision fermentation carbon accounting methodologies, as lifecycle assessments will soon determine which production platforms qualify for green procurement mandates and sustainability-linked financing.
Market Dynamics
Precision fermentation infrastructure is concentrating manufacturing capacity among bioreactor operators with validated strain libraries, creating a supply bottleneck that favors early movers with de-risked production pathways.
Growth Catalysts
- FDA GRAS Pathway:The streamlined notification process accelerates commercial entry for novel dairy proteins, reducing time-to-market versus traditional food additive petitions.
- Sports Nutrition Formulation:Clean-label protein powders drive ingredient substitution as brands remove artificial sweeteners and synthetic additives from recovery products.
- EU Novel Food Regulation:Centralized EFSA safety assessments create predictable approval timelines that attract venture capital into European precision fermentation scale-ups.
Market Restraints
- Feedstock Cost Volatility:Glucose and nitrogen source prices fluctuate with agricultural commodity cycles, compressing margins for continuous fermentation operations.
- Bioreactor Supply Concentration:Stainless steel vessel fabrication concentrates among German and Swiss engineering firms, extending equipment lead times to 18-24 months.
- Downstream Processing Bottleneck:Membrane filtration and chromatography capacity limits isolate purity grades achievable at commercial tonnage.
Strategic Opportunities
- Clinical Nutrition Expansion:Medical foods for renal and metabolic disorders seek hypoallergenic protein sources with complete amino acid profiles.
- Carbon Accounting Integration:Lifecycle assessment methodologies emerging under EU Green Deal framework differentiate low-emission fermentation platforms in green procurement tenders.
- Hybrid Product Architectures:Blended fermented-animal dairy proteins bridge taste acceptance gaps in premium ice cream and fresh cheese categories.
Industry Challenges
- Strain Optimization Talent Scarcity:Metabolic engineering and synthetic biology expertise concentrates among academic spinouts, constraining in-house R&D buildout.
- Scale-Up Validation Timelines:Demonstrating batch-to-batch consistency for regulatory dossiers demands 12-18 months of continuous production data.
- Legacy Equipment Retrofit Complexity:Conventional dairy processing lines require stainless steel compatibility verification and CIP protocol redesign for microbial protein handling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Protein Market |
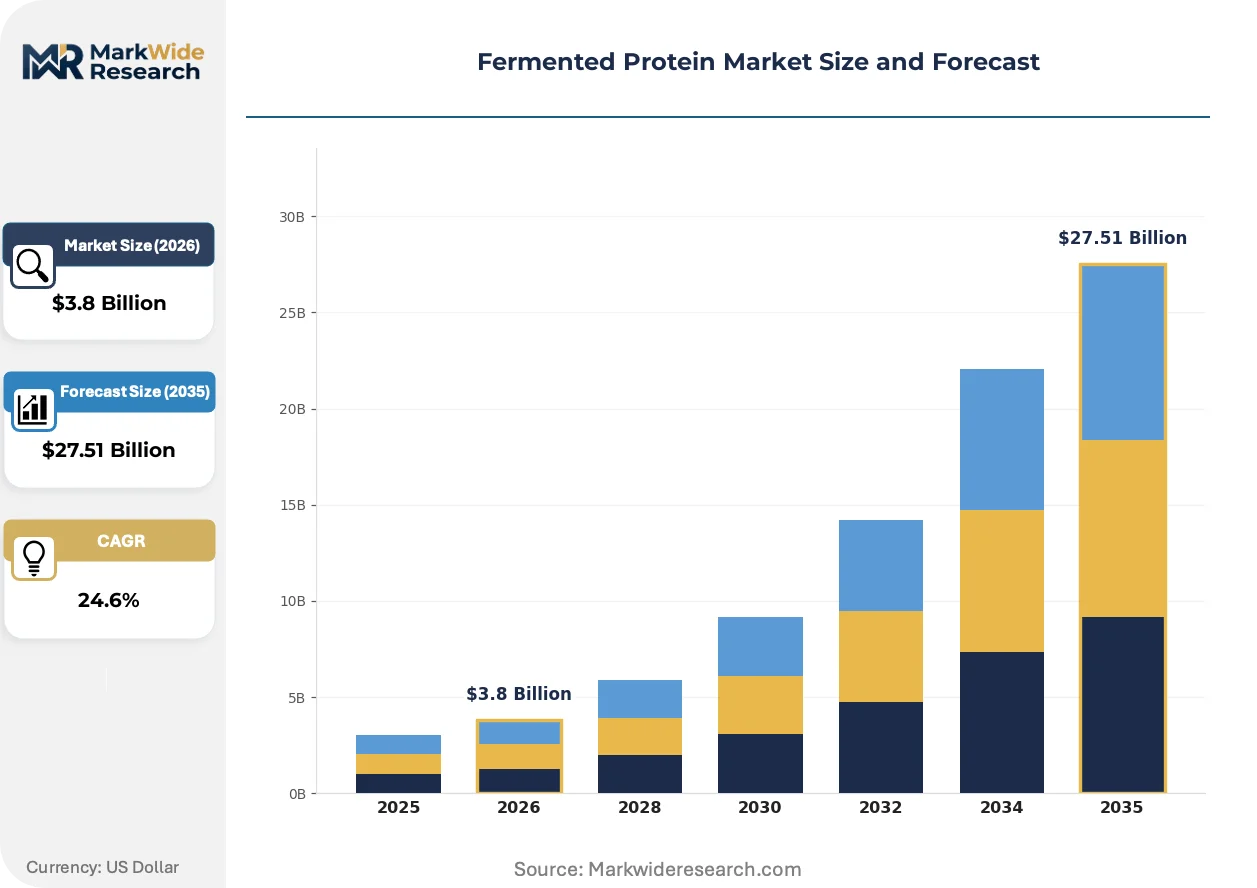
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Soy Protein, Pea Protein, Casein Protein End User: Fitness Enthusiasts, Athletes, Health-Conscious Consumers, Vegans Delivery Mode: Powder, Bars, Ready-to-Drink, Capsules Formulation: Isolate, Concentrate, Hydrolysate, Blends |
| Companies Covered | ImaginDairy Ltd., Cargill, Incorporated, Perfect Day, Inc., TurtleTree, Koninklijke DSM N.V., Remilk Ltd., Geltor, Inc., Evonik Industries AG, The EVERY Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Protein Market Shifts & Advancements
Continuous processing architectures and AI-driven bioprocess control are compressing unit economics for precision-fermented proteins, enabling price parity with commodity whey in select applications.
Single-use bioreactor systems are decomposing the capital barrier that historically protected incumbent dairy processors. Mid-size ingredient suppliers in the Netherlands and Denmark adopt 5,000-liter disposable vessels for rapid product iteration without stainless steel fabrication delays. This technology is decomposing the scale advantages of legacy dairy infrastructure, allowing biotech entrants to achieve viable unit costs at one-tenth traditional dairy plant capacity.
EU F-Gas Regulation phase-down schedules accelerate adoption of mechanical vapor recompression and ammonia-based cooling in fermentation facilities. Industrial consequence includes redesigned heat exchange networks that recover energy from exothermic microbial growth. German and Danish operators lead retrofit deployment, securing operating permits ahead of 2030 refrigerant quota reductions.
Direct procurement contracts between CPG formulators and fermentation operators displace traditional ingredient distributor intermediaries. Sports nutrition brands in California and Bavaria negotiate multi-year offtake agreements with dedicated bioreactor capacity, securing supply visibility while accepting price escalation clauses tied to agricultural input indices. This channel restructuring concentrates in North American and German markets where buyer scale justifies bilateral contract complexity.
Fermented Protein Market Segmentation
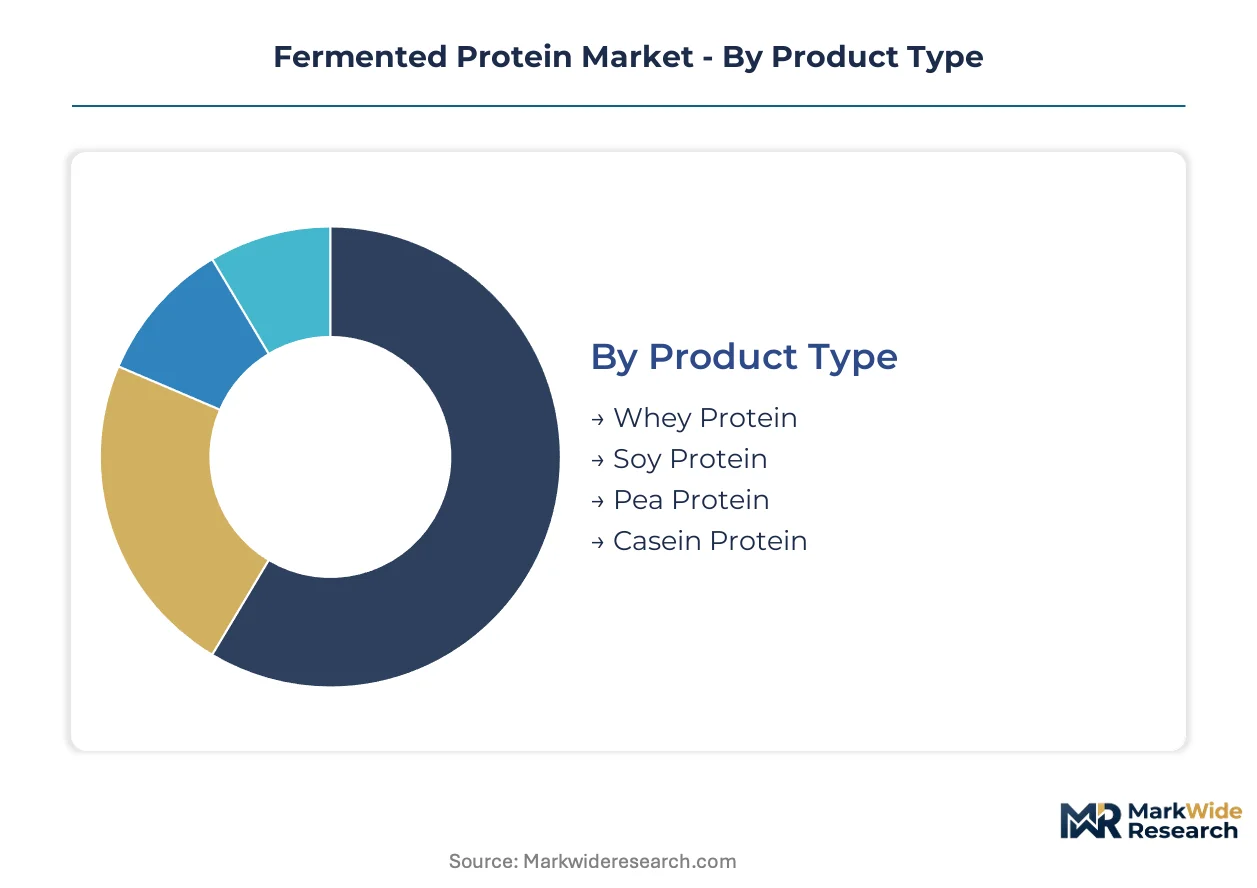
Fermented protein manufacturers calibrate R&D investment and capacity planning against four distinct segmentation axes. Product type and formulation tiers determine margin capture, while end-user targeting and delivery mode selection shape channel economics and brand positioning.
Product Type:
Whey and casein variants face the most acute substitution pressure from precision-fermented alternatives, given their entrenched dominance in conventional dairy processing lines.
- Whey Protein:Precision-fermented whey achieves functional equivalence to dairy-derived isolates with complete amino acid profiles and superior batch consistency. Sports nutrition formulators in Germany and California are locking in multi-year supply contracts to secure volume visibility. Whey protein retains volume leadership; pea protein holds the steepest expansion curve.
- Casein Protein:Slow-release micellar structures from fermentation deliver sustained amino acid availability valued in overnight recovery formulations. Clinical nutrition applications for metabolic disorder management are concentrating demand in Danish and Dutch markets where EFSA approval pathways are most mature.
- Soy Protein:Fermented soy isolates bypass agricultural allergen variability while meeting BIS food safety standards for Indian export markets.
- Pea Protein:Microbial cultivation eliminates crop yield volatility and off-flavor challenges that constrain conventional pea protein adoption.
Cost tier separation runs deepest in this category, with precision-fermented dairy proteins commanding premium positioning against commodity plant inputs.
Formulation:
Downstream processing intensity creates sharp margin stratification across purity grades, with isolate production requiring substantially greater capital commitment.
- Isolate:Ultra-pure grades exceeding 90% protein content capture the dominant margin pool through neutral flavor profiles and minimal carbohydrate carryover. Premium sports nutrition brands in Bavaria and California specify isolate grades for clean-label positioning. Isolate formulations retain volume leadership; hydrolysate holds the steepest expansion curve.
- Concentrate:Lower processing intensity suits mass-market applications where cost sensitivity outweighs purity requirements. Emerging market distributors in India leverage concentrate grades to hit FSSAI-compliant price points.
- Hydrolysate:Pre-digested peptide structures accelerate gastric emptying for clinical nutrition and elite athletic applications.
- Blends:Custom amino acid profiling allows formulators to optimize cost-performance ratios across specific end-use scenarios.
Application-driven demand concentration favors isolate for premium positioning and hydrolysate for specialized medical nutrition.
End User:
Customer type segmentation reveals divergent purchasing behaviors, with institutional buyers commanding substantially different contract structures than individual consumers.
- Athletes:Performance-verified protein specifications with batch-level amino acid analysis support doping-compliant nutrition programs. Olympic training facilities in Germany and professional sports franchises in California drive volume through certified supplier programs. Athletes retain volume leadership; vegans hold the steepest expansion curve.
- Fitness Enthusiasts:Mid-tier pricing sensitivity favors concentrate grades and blended formulations in club-channel distribution.
- Health-Conscious Consumers:Clean-label demands push toward isolate grades with minimal ingredient lists and transparent fermentation sourcing.
- Vegans:Ethical positioning premiums support price acceptance for precision-fermented dairy proteins that bypass animal agriculture entirely.
Volume concentration clusters with athletic institutional procurement; vegan adoption is climbing the fastest as ethical positioning penetrates mainstream retail.
Delivery Mode:
Manufacturing asset requirements vary substantially across format types, with powder production favoring continuous processing and ready-to-drink demanding aseptic filling infrastructure.
- Powder:Bulk handling efficiency and extended shelf stability make powder the default format for ingredient suppliers and private-label manufacturers. German and Danish fermentation operators optimize spray-drying capacity for powder output. Powder retains volume leadership; ready-to-drink holds the steepest expansion curve.
- Ready-to-Drink:Convenience positioning commands substantial retail price premiums in North American convenience channels. Aseptic filling partnerships with established beverage co-manufacturers reduce capital barriers for fermentation entrants.
- Bars:Extrusion and enrobing compatibility requirements favor blended protein inputs with specific water-binding characteristics.
- Capsules:Clinical nutrition and precise dosing applications drive demand for compact delivery in medical food contexts.
Supply concentration in powder reflects fermentation infrastructure optimization; ready-to-drink is gaining share fastest through convenience-channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioreactor fabrication concentrates among German and Swiss engineering firms, creating equipment bottlenecks that favor early-movers with installed capacity. Venture capital deployment tracks regulatory approval maturity, clustering in jurisdictions with validated GRAS or Novel Food pathways. Demand formation diverges between athletic institutional procurement in North America and clean-label consumer positioning in Northern Europe.
United States
Sports nutrition brands in California negotiate multi-year offtake agreements with dedicated bioreactor capacity, securing supply visibility for isolate grades. FDA GRAS notifications for precision-fermented dairy proteins accelerate commercial entry versus traditional food additive petitions. The San Francisco Bay Area anchors strain development activity, with academic spinouts concentrating metabolic engineering expertise.
Germany
Ingredient buyers in Bavaria integrate fermented dairy proteins into clean-label formulations, commanding premium positioning through transparent sourcing. EU Novel Food Regulation and EFSA safety assessments create predictable approval timelines that attract fermentation scale-up investment. The Munich biotech corridor hosts downstream processing partnerships linking bioreactor outputs to CPG formulators.
Netherlands
Mid-size suppliers adopt single-use bioreactor systems for rapid product iteration without stainless steel fabrication delays. The country's national food safety authority aligns with EFSA frameworks, streamlining Novel Food dossier preparation. The Randstad cluster concentrates spray-drying capacity optimization for powder output destined for European distribution.
Denmark
Clinical nutrition applications for metabolic disorder management concentrate demand where EFSA approval pathways are most mature. EU F-Gas Regulation phase-down schedules accelerate mechanical vapor recompression adoption in fermentation facilities. Copenhagen-area operators lead retrofit deployment, securing operating permits ahead of refrigerant quota reductions.
India
Emerging nutrition markets drive concentrate-grade demand as distributors leverage FSSAI-compliant price points for mass-market penetration. BIS food safety standards and FSSAI ingredient classifications add compliance layers for precision-fermented protein exporters. Maharashtra-based formulators pilot blended fermented-animal dairy proteins for premium ice cream categories.
Fermented Protein Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with strain development specialists commanding premium positioning against scale-oriented bioreactor operators. The market structure fragments across three tiers: integrated biotechnology platforms with validated production pathways, ingredient distributors anchoring global supply chains, and synthetic biology service providers licensing enzymatic backbones. Dominant competitive moves include strategic partnerships between fermentation operators and CPG formulators, plus capacity expansion through single-use bioreactor deployment to bypass stainless steel fabrication delays.
Among precision-fermented dairy specialists, Perfect Day, Inc. and Remilk Ltd. exemplify the commercial-scale archetype, while Koninklijke DSM N.V. occupies a position as the enzymatic backbone supplier powering competitor manufacturing lines. Cargill, Incorporated anchors global distribution networks connecting bioreactor outputs to CPG formulators across multiple continents. These three represent distinct strategic positions: direct-to-brand supply, ingredient platform licensing, and commodity distribution infrastructure.
| Leading Market Players |
|---|
| ImaginDairy Ltd. |
| Cargill, Incorporated |
| Perfect Day, Inc. |
| TurtleTree |
| Koninklijke DSM N.V. |
| Remilk Ltd. |
| Geltor, Inc. |
| Evonik Industries AG |
| The EVERY Company |
| Others |
Supply & Pricing Matrix
Single-use bioreactor systems replacing stainless steel vessels simultaneously shift manufacturing geography toward Netherlands and Denmark contract operators while compressing capital barriers that historically protected incumbent dairy processors. This substitution dynamic enables mid-size fermentation entrants to achieve viable unit costs at reduced scale, fragmenting pricing power across a broader supplier base and forcing legacy operators to defend margins through isolate-grade purity premiums rather than volume leverage.
Pricing Analysis
EU Novel Food Regulation dictates the pricing tier structure by creating compliance cost stratification across approval maturity levels. Three-tier pricing structure across premium isolate, standard concentrate, and economy-grade biomass separates EFSA-validated suppliers from pre-approval aspirants and commodity plant protein alternatives. Price differentiation rests on certification tier and volume scale, with Bavarian sports nutrition brands paying premiums for batch-level amino acid documentation. Cost compression in concentrate grades is intensifying because Indian distributors leverage FSSAI-compliant price points for mass-market penetration. Fitness enthusiasts exhibit highest price sensitivity, while clinical nutrition procurement shows lowest elasticity due to hypoallergenic performance requirements.
Supply Chain Analysis
Bioreactor vessel inventory lead times extending to 18-24 months concentrate supply risk among German and Swiss engineering fabricators. Manufacturing capacity clusters in Germany, Netherlands, and Denmark where EFSA approval pathways attract venture deployment. Raw material dependencies draw from agricultural glucose streams, nitrogen sources, and chromatography resins. Single-source vulnerability concentrates in stainless steel fabrication, with tariff exposure on Chinese-sourced engineering components amplifying cost uncertainty. Distribution runs through direct procurement contracts between CPG formulators and fermentation operators, displacing traditional ingredient distributor intermediaries in California and Bavaria markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermented protein represents an early-cycle expansion story where FDA GRAS pathway maturation accelerates commercial entry timelines and unlocks institutional capital deployment previously constrained by regulatory uncertainty.
For Market Incumbents: Fortify strain library depth and validated production pathways against synthetic biology spinouts threatening technical differentiation. Secure dedicated bioreactor capacity through multi-year offtake agreements with California and Bavarian sports nutrition brands to lock in volume visibility. Invest in EFSA Novel Food dossier preparation ahead of competitor submissions to capture premium positioning in EU clinical nutrition procurement. For New Entrants and Emerging Players: Lead with clinical nutrition applications for metabolic disorder management where EFSA approval pathways in Denmark and Netherlands create addressable white space. Target Indian concentrate-grade demand through FSSAI-compliant formulations that bypass premium isolate competition. Deploy single-use bioreactor systems for rapid product iteration without stainless steel fabrication delays, enabling speed-to-market against capital-intensive incumbents. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down schedules reshape the acquisition landscape by favoring operators with mechanical vapor recompression retrofit completion ahead of 2030 refrigerant quota reductions. Long-term viability over a 5-10 year window hinges on carbon accounting integration and green procurement qualification. Prioritize acquisition targets with validated strain libraries and continuous production data for regulatory dossiers. Monitor EFSA safety evaluation timelines as the critical inflection signal for capital deployment velocity into European scale-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EFSA Novel Food validation unlocks EU clinical nutrition procurement and attracts venture capital deployment. |
| Manufacturing Scale-Up | Single-use bioreactor adoption bypasses German stainless steel fabrication bottlenecks and compresses lead times. |
| Backward Integration | Captive glucose supply hedges agricultural commodity volatility affecting continuous fermentation margins. |
| Long-term Supply Agreement | Direct procurement contracts with California sports nutrition brands secure volume visibility and price escalation clauses. |
| Green Certification Program | EU Green Deal lifecycle assessment qualification differentiates platforms in sustainability-linked financing tenders. |
Research Methodology
Cross-validation between primary interviews with bioprocess engineers, strain development scientists, sports nutrition formulators, and EFSA regulatory consultants anchors the qualitative findings against secondary validation from FDA GRAS notifications, EFSA scientific opinions, FSSAI ingredient classifications, and BIS food safety standards. Bottom-up capacity modeling triangulates against top-down venture capital deployment tracking across precision fermentation scale-ups. This dual approach captures both technical feasibility constraints and capital formation dynamics shaping commercialization timelines.
Sensitivity analysis across feedstock cost scenarios, approval timeline distributions, and bioreactor utilization rates informs the analytical framework. Segmentation dimensions span product type, formulation grade, end-user archetype, and delivery mode across the projection horizon. CAGRs derive from installed capacity buildout curves, regulatory approval velocity, and substitution elasticity estimates against conventional dairy and plant proteins. Industry-specific inputs include strain optimization timelines, downstream processing yield curves, and carbon intensity differentials under emerging EU Green Deal methodologies.
The analysis sits within stated boundaries; outcomes outside sustained FDA GRAS notification velocity, EFSA evaluation throughput maintenance, or agricultural input price stability would require recalibration. Forecasts reflect assumptions on regulatory pathway efficiency and capital availability for scale-up infrastructure. Specific risk factors include bioreactor fabrication delays, metabolic engineering talent scarcity, and evolving carbon accounting standards that could revise platform competitiveness. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
RTD Protein Beverages Market
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
North America Probiotic Drinks Market
Functional Food and Beverage
South America Functional Beverages Market
Functional Food and Beverage
Global Functional Proteins Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Mediterranean Healthy-Aging Beverage Ingredients Market
Functional Food and Beverage
Very Low Calorie Desserts Market
Functional Food and Beverage
Marine Functional Ingredients Market
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
Oat Beta-Glucan Market
Functional Food and Beverage
Low-Fat and Low Protein Diet Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Low Fat Product Market
Functional Food and Beverage
Low Fat Smoothies Market