
 Europe Fats and Oil Market | 2026-2036
Europe Fats and Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fats and Oil Market Foresight
Foodservice distribution networks across Northern Europe are rewriting procurement patterns for bulk oils and tailored fat blends. Cargill Incorporated leverages its integrated crush and refining footprint to secure supply contracts with industrial bakeries. AAK AB specializes in confectionery fats and bakery solutions, sustaining premium positioning through technical application centers in Sweden and the Netherlands. Bunge Limited anchors its European operations through port-based crushing assets in Germany and Poland, competing on origination scale and logistics efficiency.
Europe fats and oils comprise triglyceride-based lipid matrices derived from oilseed crushing, animal rendering, or fractionation processes, with fatty acid profiles and melting points engineered for specific functional performance in food matrices, oleochemical derivatives, or fuel applications. Vegetable oils dominate volume flows through the region's crush and refinery infrastructure, while demand for tailored shortenings and confectionery fats concentrates margin pools in technical specialty segments. The food industry application channel absorbs the largest share of refined output, though biodiesel production acts as a structural price floor for lower-grade oil streams during periods of energy policy support.
EMA, EFSA, and REACH frameworks govern ingredient safety assessments, novel food approvals, and chemical substance registration across European fat and oil value chains. EFSA's ongoing evaluations of 3-MCPD esters and glycidyl esters in refined vegetable oils are tightening process standards and forcing capital deployment toward modified deodorization systems. Stakeholders must monitor the EU Deforestation Regulation's traceability mandates, which will reshape sourcing geography and supplier qualification protocols for palm and soy derivatives entering European refineries.
Market Dynamics
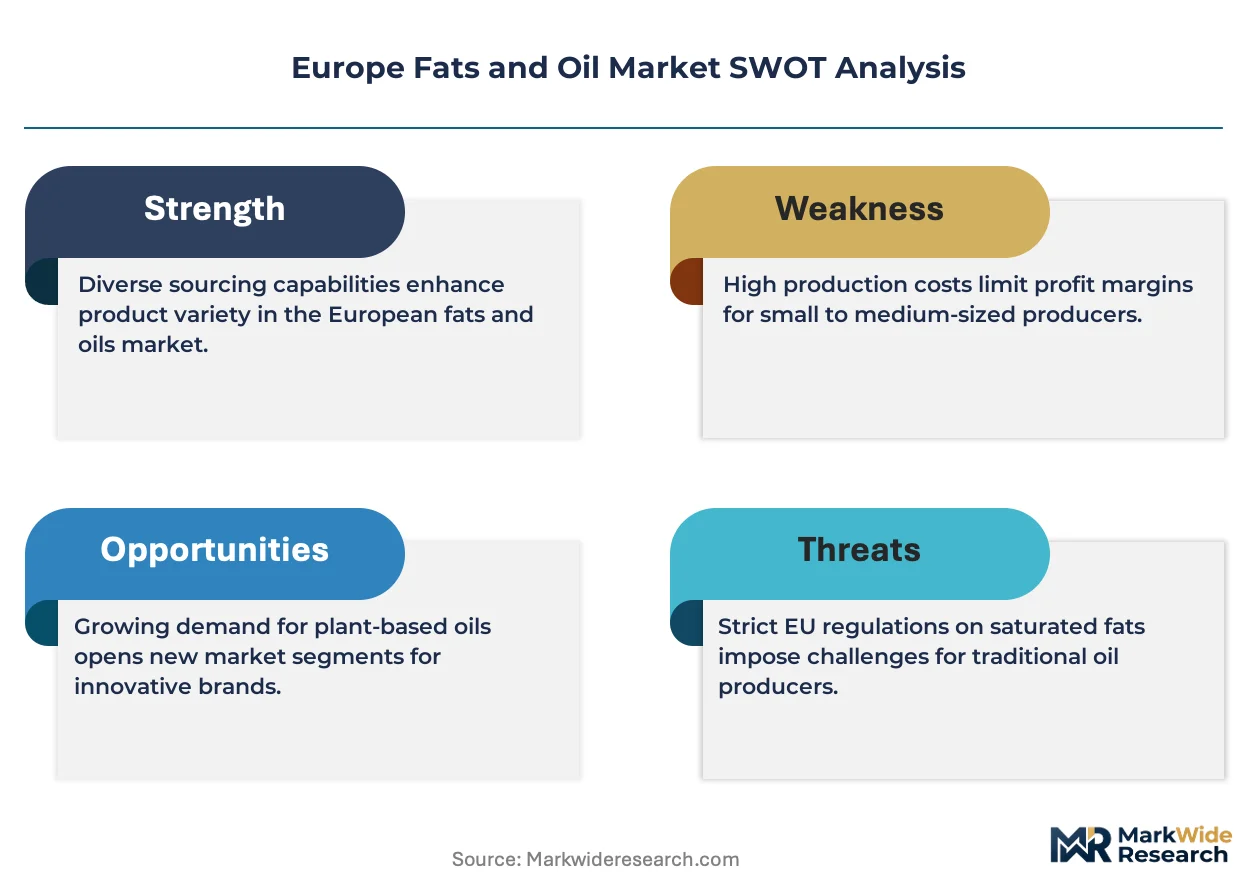
EU Deforestation Regulation traceability mandates are forcing refiners to rebuild supplier qualification protocols and invest in chain-of-custody verification systems across palm and soy sourcing networks. This regulatory pressure compounds with EFSA's tightening limits on 3-MCPD esters, creating dual compliance burdens that favor capital-heavy operators capable of deploying modified deodorization and molecular distillation assets.
Growth Catalysts
- Bio-based feedstock mandates:The EU Green Deal and F-Gas Regulation accelerate refinery conversions to renewable processing routes, pulling investment into enzymatic interesterification and supercritical fluid extraction systems for specialty fat production.
- Germany's industrial food processing corridor:Concentrated demand from pan-European packaged food brands in the Rhine-Ruhr and Bavaria clusters sustains offtake volumes for tailored shortenings and confectionery fat blends.
- REACH chemical registration frameworks:Streamlined novel ingredient approvals enable faster commercialization of structured lipids and modified triglycerides for nutraceutical and infant formula applications.
Market Restraints
- Black Sea origination concentration:Sunflower oil supply disruptions from Ukraine and Russia expose European crushers to raw material volatility and force costly alternative sourcing from Argentina and Turkey.
- Energy cost asymmetry:Natural gas-intensive hydrogenation and refining processes in the Netherlands and Germany face margin compression against Middle Eastern and Southeast Asian competitors with subsidized feedstock energy.
- Plant protein substitution:Pea and fava protein isolates displace functional roles of emulsified fats in meat analog formulations, constraining volume growth in certain bakery and prepared food segments.
Strategic Opportunities
- Poland's underdeveloped specialty fat sector:Limited domestic confectionery fat refining capacity creates white space for technical application centers serving Central European chocolate and bakery manufacturers.
- CSRD sustainability reporting mandates:Mandatory Scope 3 emissions disclosure drives demand for verified deforestation-free and regenerative agriculture-certified oil streams, enabling premium positioning for compliant suppliers.
- Precision fermentation lipids:Convergence of synthetic biology and lipid chemistry opens routes to tailored fatty acid profiles without agricultural land use, attracting venture funding for pilot-scale production in Denmark and the Netherlands.
Industry Challenges
- Process analytical chemistry talent scarcity:Refiners struggle to recruit specialists capable of operating real-time 3-MCPD and glycidyl ester monitoring systems required under EFSA's evolving guidance.
- Legacy ERP integration with traceability platforms:EU Deforestation Regulation geolocation data requirements force expensive middleware development to connect farm-level GPS verification with enterprise resource planning systems.
- Fractionation train retrofit complexity:Dry fractionation assets designed for palm oil require substantial reconfiguration to handle high-oleic sunflower and high-stearic rapeseed varieties, extending capital deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fats and Oil Market |
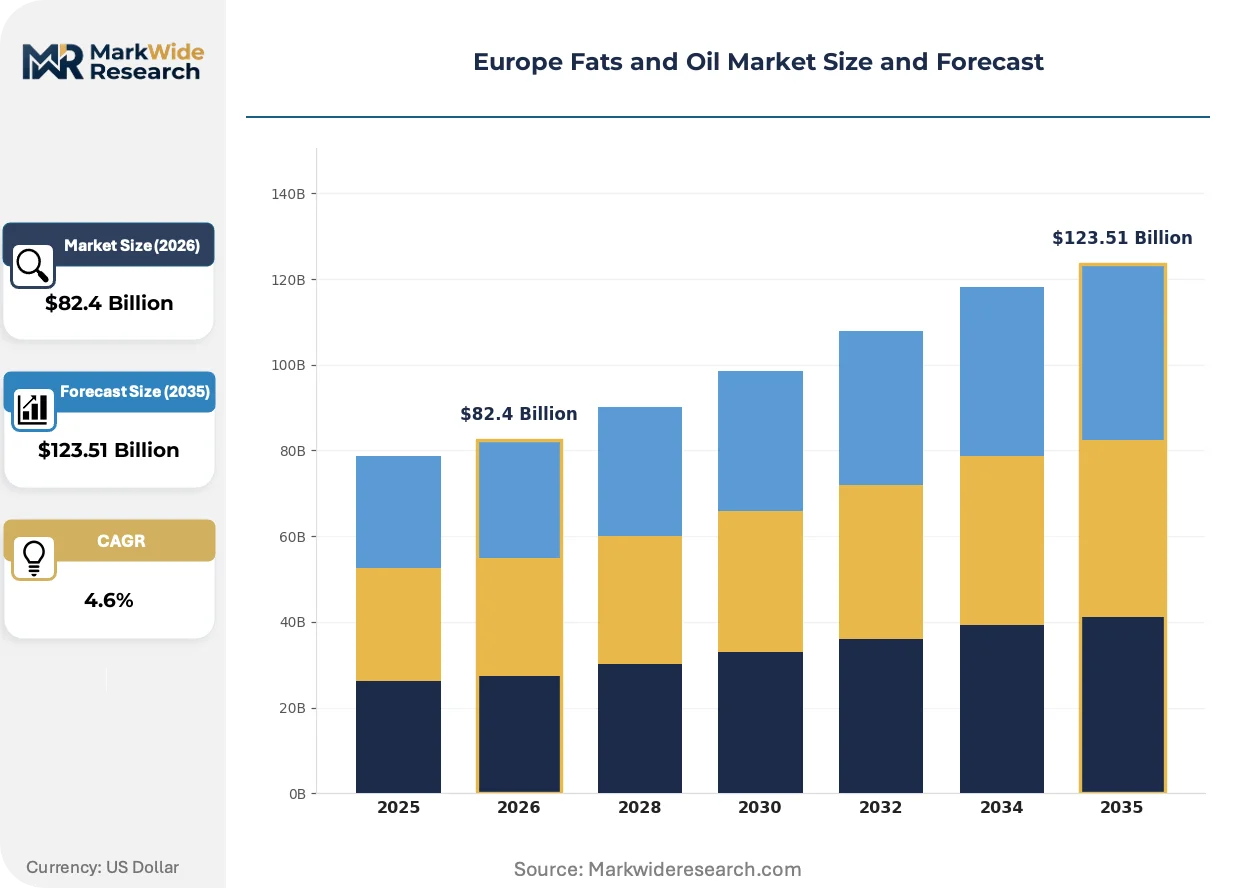
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $123.51 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
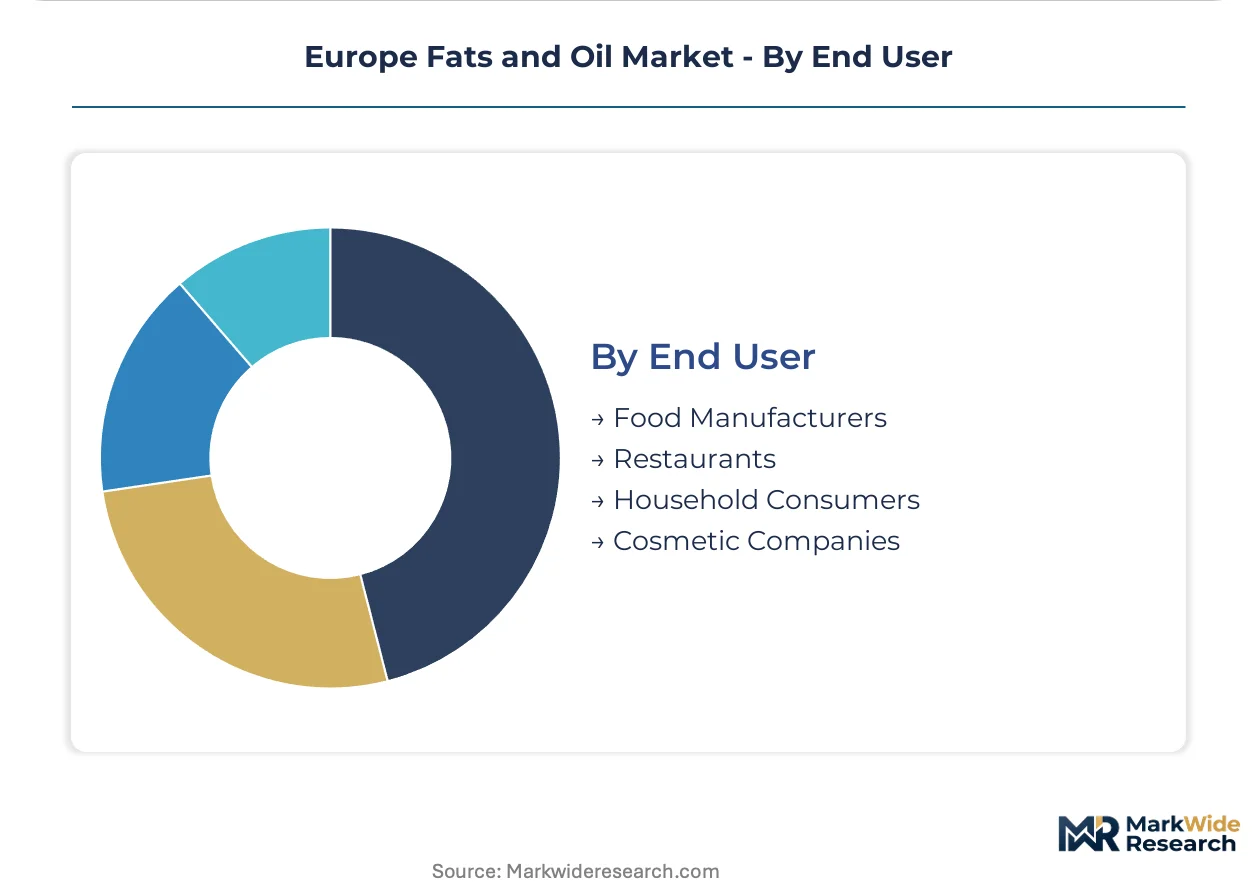
| Segmentation | Product Type: Vegetable Oils, Animal Fats, Margarine, Shortening Application: Food Industry, Personal Care Products, Biodiesel Production, Industrial Uses Distribution Channel: Wholesale, Retail, Online, Direct Sales End User: Food Manufacturers, Restaurants, Household Consumers, Cosmetic Companies |
| Companies Covered | Wilmar International Limited, Olam International Ltd., Cargill Incorporated, Louis Dreyfus Company, AAK AB, Bunge Limited, Associated British Foods, Fuji Oil Holdings Inc., Archer Daniels Midland Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fats and Oil Market Shifts & Advancements
Digital twin technology is virtualizing process control across European oilseed crushing and refining operations, compressing commissioning cycles for new product specifications. These virtualized workflows reshape how technical teams collaborate across geographically distributed facilities.
Enzymatic interesterification is virtualizing the functional performance of traditional chemical interesterification without trans-fat formation, enabling clean-label claims for bakery shortenings. Industrial bakeries in France and Germany are adopting this biocatalytic route at accelerated pace to meet retailer clean-label requirements. The technology is virtualizing capital allocation decisions, as smaller-batch flexible systems displace large-scale chemical reactors.
REACH authorization requirements for nickel catalysts used in hydrogenation are tightening process standards and forcing refiners toward precious metal alternatives or enzymatic routes. The industrial consequence is elevated capital intensity for hydrogenation assets and accelerated depreciation of legacy nickel-based systems. Margarine and spread manufacturers in Benelux and Scandinavia are most affected, responding with reformulation toward non-hydrogenated fat bases.
Food manufacturers are consolidating supplier relationships around integrated crush-to-specialty-fat providers capable of delivering tailored melting profiles and fatty acid specifications from single-source accountability. This buying-pattern change disrupts traditional merchant oil traders and elevates technical service capabilities as a selection criterion. The shift is most visible in Germany's industrial bakery sector, where procurement teams prioritize application laboratories over commodity pricing in tender evaluations.
Europe Fats and Oil Market Segmentation
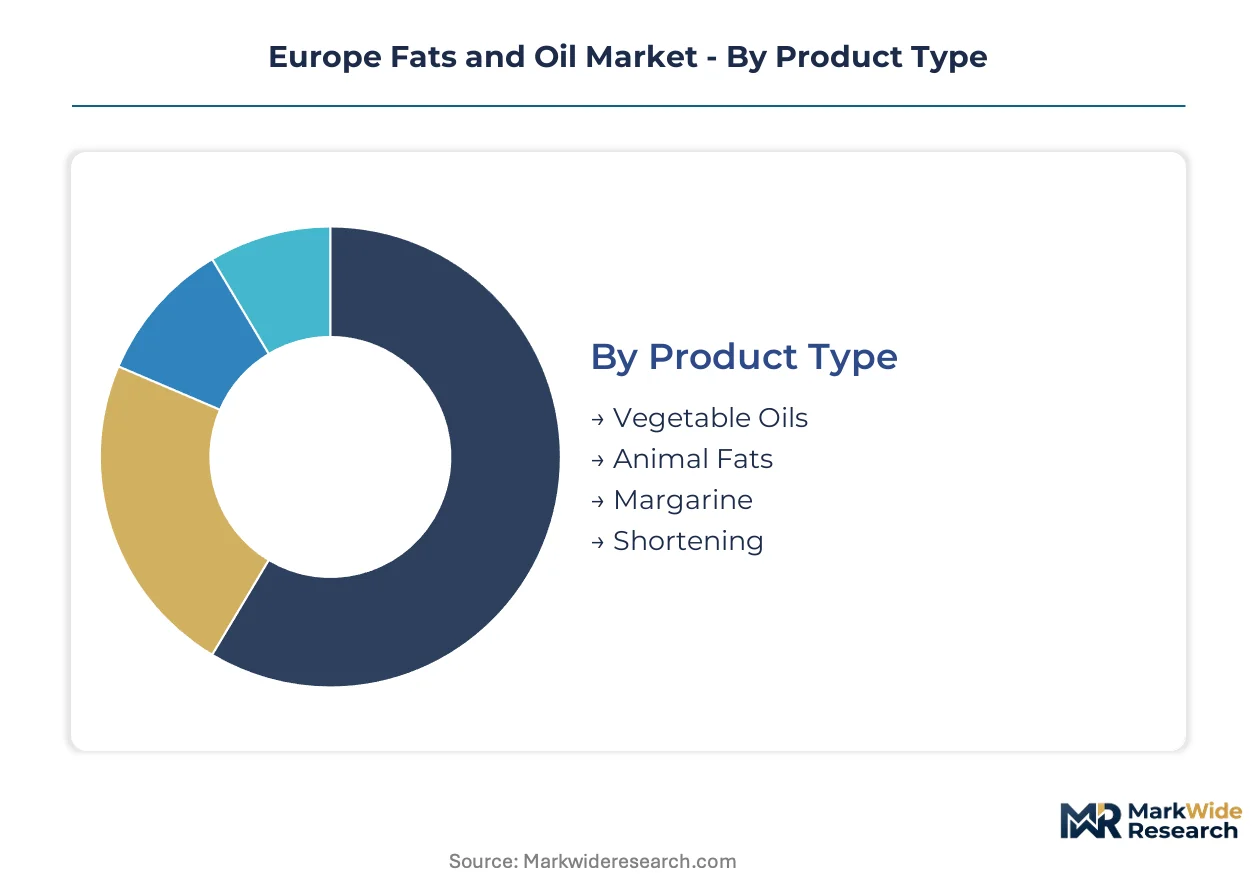
Segmentation in the European fats and oils market reveals how divergent technical specifications, regulatory exposure, and channel economics create distinct competitive arenas. Each dimension—product chemistry, application function, distribution logistics, and end-user scale—demands specialized capabilities that reshape margin capture and capital deployment priorities across the value chain.
Product Type:
Cost tier structures diverge sharply across lipid sources, with vegetable-origin feedstocks commanding volume flows while animal-derived and formulated products concentrate value pools in technical specialty segments.
- Vegetable Oils:Triglyceride matrices derived from rapeseed, sunflower, and palm crushing dominate refinery throughput across Germany, Poland, and the Netherlands. Rhine-Ruhr industrial bakeries and Benelux biodiesel producers absorb the largest offtake volumes, though Black Sea sunflower disruptions have forced costly alternative sourcing from Argentina.
- Animal Fats:Rendered tallow and lard supply saturated fatty acid profiles for oleochemical derivatives and pet food formulations. Demand concentrates in Northern France and Denmark where integrated rendering operations serve pan-European soap and lubricant manufacturers facing REACH registration burdens for synthetic alternatives.
- Margarine:Water-in-fat emulsions formulated for spreadability and shelf stability serve retail and foodservice channels across Scandinavia and the UK. Reformulation pressures from EFSA trans-fat limits and nickel catalyst restrictions are accelerating enzymatic interesterification adoption.
- Shortening:Plasticized fat blends engineered for aeration and creaming performance in bakery applications. German industrial bakeries drive specification development, with clean-label demands pulling investment toward enzymatic rather than chemical modification routes.
Vegetable oils command the established base. The steepest expansion runs through shortening as clean-label bakery reformulation accelerates.
Application:
Application-driven demand splits between food matrices requiring precise functional performance and non-food channels where energy policy and chemical substitution create alternative value anchors.
- Food Industry:The largest absorption channel spanning confectionery fats, frying oils, and tailored shortenings for industrial bakeries. Germany's packaged food corridor and Italian pasta manufacturers sustain offtake, with EFSA's 3-MCPD ester limits forcing capital deployment toward modified deodorization systems.
- Personal Care Products:Cosmetic-grade oils and emollients for skincare and haircare formulations. France's beauty cluster around Paris and Lyon drives specification stringency, with CSRD sustainability mandates pushing demand for certified deforestation-free shea and coconut derivatives.
- Biodiesel Production:Lower-grade oil streams and fatty acid methyl esters serving renewable fuel mandates under the EU Green Deal. German and Dutch refiners face margin compression when energy policy support fluctuates, creating structural price floor effects for feedstock procurement.
- Industrial Uses:Lubricants, metalworking fluids, and surfactant feedstocks derived from oleochemical processing. REACH authorization requirements for petrochemical alternatives sustain niche demand for plant-derived base stocks in precision manufacturing.
Food industry applications anchor volume throughput. Personal care products are climbing the fastest as sustainability certification becomes a non-negotiable selection criterion.
Distribution Channel:
Channel economics reflect customer scale and specification complexity, with direct relationships capturing tailored formulations while arms-length channels handle standardized commodity flows.
- Wholesale:Bulk tanker and flexitank deliveries to industrial food manufacturers and biodiesel refiners. Rotterdam and Hamburg port infrastructure enables efficient aggregation of pan-European demand, though EU Deforestation Regulation traceability mandates are forcing middleware investments to connect farm-level GPS data with enterprise systems.
- Retail:Branded bottled oils and spreads through supermarket chains across France, Germany, and Italy. Private label concentration in Benelux and Scandinavia pressures margin pools, with clean-label claims driving premium positioning for enzymatically interesterified products.
- Online:Direct-to-consumer specialty oils and niche cosmetic ingredients. Danish and Dutch precision fermentation startups leverage digital channels to bypass traditional distribution layers for novel lipid products.
- Direct Sales:Technical service-intensive relationships for confectionery fat blends and structured lipids. AAK AB and integrated crush-to-specialty providers anchor this channel through application laboratories in Sweden and the Netherlands.
Wholesale channels command the established base. Direct sales are expanding most quickly as food manufacturers consolidate supplier relationships around single-source accountability.
End User:
End-user scale and technical sophistication determine service intensity, with large-scale manufacturers driving specification development while fragmented operators prioritize cost and availability.
- Food Manufacturers:Industrial bakeries, confectioners, and prepared food processors across Germany, France, and Italy. Procurement teams in the Rhine-Ruhr corridor increasingly prioritize application laboratory capabilities over commodity pricing in tender evaluations.
- Restaurants:Foodservice operators from independent establishments to chain networks. Northern European distribution networks are consolidating procurement patterns for bulk frying oils and tailored fat blends.
- Household Consumers:Retail purchasers of cooking oils and spreads. Health and wellness positioning around omega fatty acid profiles and clean-label claims drives brand switching in UK and Scandinavian markets.
- Cosmetic Companies:Formulators of skincare, haircare, and color cosmetics. L'Oréal and Unilever supply chains in France and the Netherlands are demanding verified regenerative agriculture certification for botanical oil inputs.
Food manufacturers command the established base. Cosmetic companies are gaining share fastest as CSRD Scope 3 disclosure mandates intensify supply chain scrutiny.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural gas-intensive refiners in the Netherlands and Germany face margin compression against Turkish and Black Sea competitors with subsidized energy inputs. This pricing-power asymmetry is reshaping procurement patterns across Northern European food manufacturers. The Rhine-Ruhr industrial corridor sustains concentrated demand for tailored fat blends serving pan-European packaged food brands.
Germany
Industrial bakeries in the Rhine-Ruhr and Bavaria clusters drive specification development for confectionery fats and shortenings. EFSA's tightening limits on 3-MCPD esters force capital deployment toward modified deodorization systems. Hamburg anchors port-based crushing infrastructure serving pan-European oil flows.
Netherlands
Rotterdam's port infrastructure enables efficient aggregation of palm and soy imports for refinery processing. The EU Deforestation Regulation mandates geolocation data integration with enterprise ERP systems. Benelux margarine manufacturers face reformulation pressures from nickel catalyst restrictions under REACH authorization.
France
Paris and Lyon beauty clusters demand certified deforestation-free shea and coconut derivatives for cosmetic formulations. CSRD sustainability reporting mandates intensify Scope 3 emissions disclosure requirements. Northern France's integrated rendering operations supply tallow for oleochemical derivatives.
Poland
Limited domestic confectionery fat refining capacity creates white space for technical application centers. Gdansk port crushing assets compete on origination scale and logistics efficiency. Central European chocolate manufacturers seek localized specialty fat supply.
Sweden
Application laboratories in Stockholm serve Nordic bakery and confectionery technical service requirements. Precision fermentation lipid startups attract venture funding for pilot-scale production. Clean-label demands accelerate enzymatic interesterification adoption across Scandinavian margarine formulations.
Europe Fats and Oil Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient technology. The vendor base concentrates around integrated crush-to-specialty providers capable of delivering tailored melting profiles from single-source accountability. Three archetypes dominate: origination-scale traders with port-based assets, technical specialists with application laboratories, and sustainability-certified niche operators. Competitive moves center on M&A for traceability platform integration and capacity expansion in enzymatic processing.
Within the integrated trading tier, Cargill Incorporated and Bunge Limited exemplify origination-scale operators with European port infrastructure. AAK AB occupies a position among technical specialists, anchoring the confectionery fat segment through application-centered service models. Wilmar International Limited represents the sustainability-certified archetype, leveraging integrated plantation-to-refinery traceability for EU Deforestation Regulation compliance.
| Leading Market Players |
|---|
| Wilmar International Limited |
| Olam International Ltd. |
| Cargill Incorporated |
| Louis Dreyfus Company |
| AAK AB |
| Bunge Limited |
| Associated British Foods |
| Fuji Oil Holdings Inc. |
| Archer Daniels Midland Company |
| Others |
Supply & Pricing Matrix
Rotterdam-Hamburg maritime corridors transmit freight cost volatility directly into refined fat and oil pricing tiers, concentrating margin pressure on Dutch and German refiners while enabling Black Sea and Turkish operators to capture share through subsidized energy inputs. This logistics-cost asymmetry forces downstream price differentiation between configured-to-order specialty fats and standard bulk oils.
Pricing Analysis
The customization-premium spread separates enzymatically interesterified bakery shortenings from commodity vegetable oil flows, with clean-label certification and tailored melting profiles commanding substantial markups over standard refined products. Pricing stratifies across premium, standard, and economy tiers based on functional performance specifications and CSRD-compliant sustainability verification. Cost compression in standard-grade oils is intensifying because Black Sea sunflower disruptions force alternative sourcing from Argentina and Turkey. Industrial bakeries in Germany's Rhine-Ruhr corridor demonstrate lowest price sensitivity, prioritizing application laboratory capabilities and single-source accountability over commodity benchmarking.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from integrated crush-to-specialty providers are displacing traditional merchant traders, tightening working capital requirements for smaller refiners competing on origination scale. Supply concentrates in Germany, the Netherlands, and Poland where port-based crushing infrastructure anchors European oilseed processing. Raw material dependencies rest on Ukrainian and Russian sunflower seeds, Indonesian and Malaysian palm oil, and South American soybeans. Single-source vulnerability from Black Sea origination concentration exposes crushers to geopolitical disruption. Distribution runs through Rotterdam and Hamburg port aggregation hubs serving pan-European wholesale tanker deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges across Central European specialty fat supply as CSRD traceability mandates and EFSA process standards disqualify commodity traders from premium tender evaluations. Clean-label reformulation and sustainability certification are creating addressable niches for technical specialists with application laboratory capabilities.
For Market Incumbents: Entrench competitive position by deploying modified deodorization assets to meet EFSA's tightening 3-MCPD ester limits, locking out capital-constrained competitors. Deepen backward integration into certified deforestation-free palm and regenerative agriculture oilseed sourcing to satisfy EU Deforestation Regulation geolocation requirements. Prioritize capacity expansion in Poland's underdeveloped confectionery fat sector to preempt emerging technical service demand from Central European chocolate manufacturers.
For New Entrants and Emerging Players: Poland's limited domestic confectionery fat refining capacity represents the most penetrable entry point for technical application centers serving Central European bakery and chocolate manufacturers. Precision fermentation lipid production in Denmark and the Netherlands offers white-space positioning beyond agricultural land-use constraints. Pursue direct sales channel development targeting cosmetic companies in France's Paris and Lyon beauty clusters demanding verified regenerative agriculture certification.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated agribusiness conglomerates with underutilized European crush assets and stranded refinery capacity lacking enzymatic processing capabilities. Long-term viability over a five-to-ten year window favors operators with traceability platform integration and CSRD-compliant Scope 3 emissions disclosure infrastructure. Monitor EFSA guidance evolution on glycidyl ester limits as inflection indicator for accelerated capital deployment toward molecular distillation assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Capacity Expansion | Enables clean-label claims for bakery shortenings under EFSA trans-fat restrictions. |
| Backward Integration into Certified Feedstock | Secures EU Deforestation Regulation compliance for palm and soy sourcing networks. |
| Traceability Platform Integration | Connects farm-level GPS verification with enterprise ERP systems for CSRD disclosure. |
| Technical Application Center Establishment | Positions suppliers for consolidated procurement from Germany's industrial bakeries. |
| Precision Fermentation Pilot Scale-Up | Opens routes to tailored fatty acid profiles without agricultural land use constraints. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with refinery operations managers, procurement leads at industrial bakeries, sustainability officers at cosmetic manufacturers, and technical R&D directors at specialty fat formulators. Secondary validation drew from EFSA guidance documents, EU Deforestation Regulation implementation texts, REACH authorization databases, customs trade flows through Rotterdam and Hamburg, and SEC filings from listed agribusiness conglomerates. Bottom-up volume modeling across crushing capacity and refinery throughput was triangulated against top-down macroeconomic demand projections.
Calibration against historical price spreads between standard and specialty fat grades anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, application function, distribution channel scale, and end-user technical sophistication. CAGRs were derived from trend extrapolation of procurement pattern shifts and capacity expansion announcements. Industry-specific forecast inputs incorporated EFSA regulatory timeline assumptions and EU Green Deal bio-based feedstock mandate implementation trajectories.
Practitioners should monitor EFSA guidance evolution, Black Sea supply disruption persistence, and CSRD enforcement intensity for early signals of forecast deviation. The analysis reflects assumptions about regulatory implementation schedules and energy cost trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Textured Soy Flour Market
Ingredients
Feed Premix Market
Ingredients
Injection Grade Soybean Oil Market
Ingredients
Global Dietary Fibers Market
Ingredients
North America Dairy Protein Market
Ingredients
Meat Tenderizer Powder Market
Ingredients
North America Carrageenan Market
Ingredients
Salt Market
Ingredients
North America Cocoa Products Market
Ingredients
Vitamin and Mineral Premixes Market
Ingredients
Yeast Flakes Market
Ingredients
Global Malt Extracts and Ingredients Market
Ingredients
Tannin Market
Ingredients
Proteose Peptone Market
Ingredients
Potato Starch Market
Ingredients
Cocoa Butter Market