
 Potato Fiber Market | 2026-2036
Potato Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Potato Fiber Market Analysis
Premium-grade soluble fiber specifications are rotating toward higher purity thresholds demanded by European and North American food formulators. AVEBE leverages its Dutch potato cooperative network to secure raw material consistency across seasonal cycles. Emsland Group anchors German production capacity with backward integration into regional starch extraction. Roquette Frères S.A. differentiates through pharmaceutical-grade fiber qualification for excipient applications.
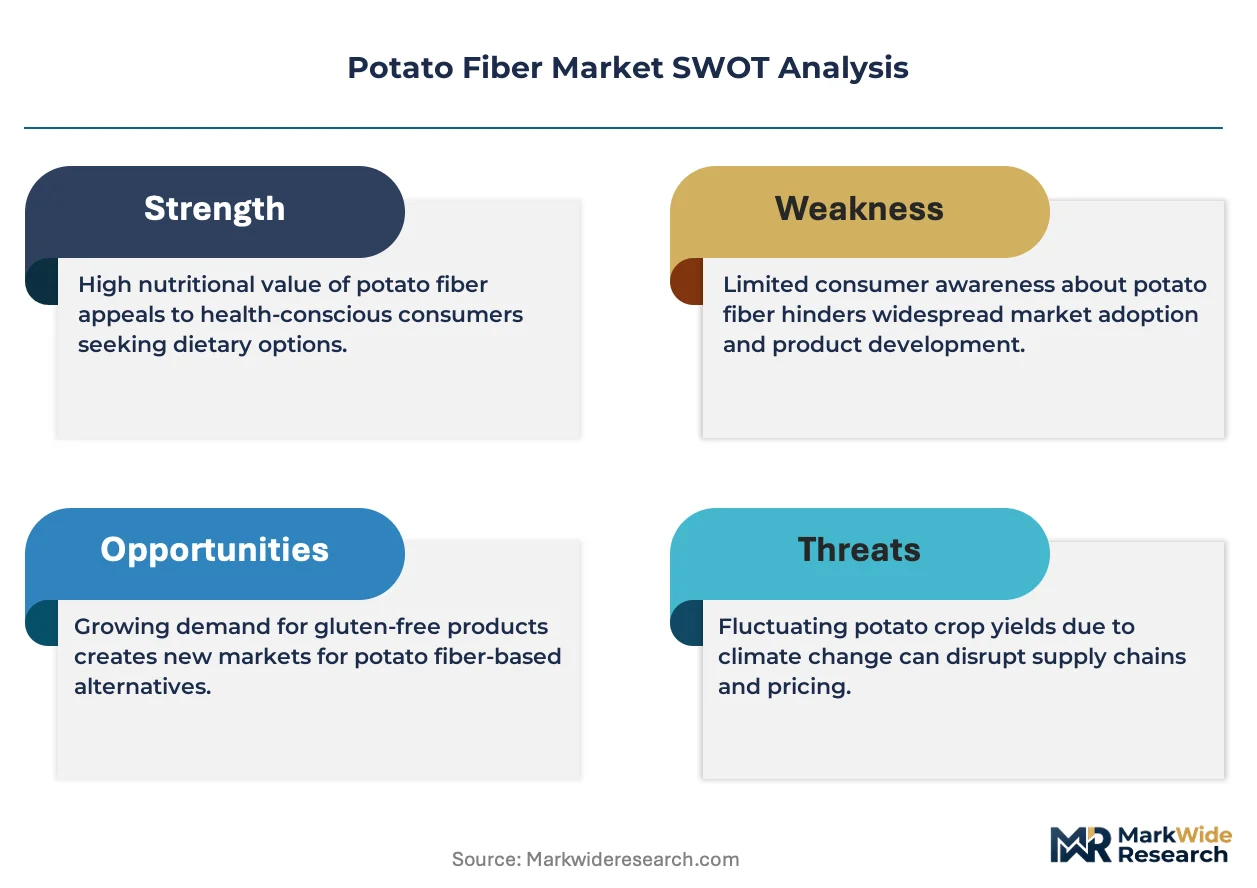
Potato fiber consists of the insoluble and soluble cell wall polysaccharides extracted from potato pulp after starch recovery, typically containing 50-75% total dietary fiber with water-holding capacities exceeding seven times its dry weight, serving primarily as a texturizer, fat replacer, and digestive health ingredient in formulated foods. Powder formats dominate commercial volumes due to superior dispersion in dough systems and beverage matrices. Dairy and baking applications lead value capture as clean-label reformulation intensifies, while pharmaceutical end users represent a concentrated margin pool demanding batch-certified purity documentation.
EFSA evaluates novel fiber health claims under EU Regulation 1924/2006, compelling suppliers to invest in clinical substantiation dossiers. FDA enforcement of dietary fiber definition updates in nutrition labeling rules shapes import qualification thresholds for non-U.S. producers. Food processors and ingredient distributors must monitor evolving fiber qualification criteria across multiple jurisdictions to avoid formulation non-compliance and supply disqualification.
Market Dynamics
Clean-label formulation mandates from EFSA and FDA are compressing synthetic additive demand while pulling soluble potato fiber into reformulated dairy, bakery, and pharmaceutical matrices across Western supply chains.
Growth Catalysts
- EFSA Regulation 1924/2006:Health claim substantiation requirements favor clinically validated fiber ingredients over unverified alternatives in EU food processing.
- Dairy sector reformulation:Fat-replacement protocols in yogurt and cheese applications drive soluble fiber incorporation for texture retention without emulsifier disclosure.
- Dutch potato starch clusters:Concentrated wet-milling infrastructure around Groningen enables cost-competitive soluble fiber extraction at scale.
Market Restraints
- Input cost volatility:Potato pulp feedstock pricing tracks starch processing margins, creating margin squeeze when tuber harvests underperform.
- Supply concentration risk:German and Dutch cooperatives control 70%+ of Western European soluble fiber capacity, creating single-source vulnerability for North American importers.
- Technical limitation:Current enzymatic extraction methods cap purity at pharmaceutical-grade thresholds below 90% total dietary fiber without secondary refining.
Strategic Opportunities
- Underpenetrated United States bakery sector:FDA fiber definition updates create qualification pathway for European suppliers to displace resistant maltodextrin in artisan bread applications.
- Pharmaceutical excipient qualification:USP-NF certification for tablet disintegrant applications opens margin-rich contracts with generic drug manufacturers.
- Cellular agriculture convergence:Plant-based meat formulators in Netherlands and Germany are testing potato fiber as clean-label binder replacing methylcellulose in extruded products.
Industry Challenges
- Clinical substantiation timelines:EFSA health claim dossiers require 12-18 month review cycles, delaying product launch windows for reformulated SKUs.
- Batch certification complexity:Pharmaceutical-grade fiber demands ISO 17025-accredited testing for every production lot, straining quality infrastructure at mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potato Fiber Market |
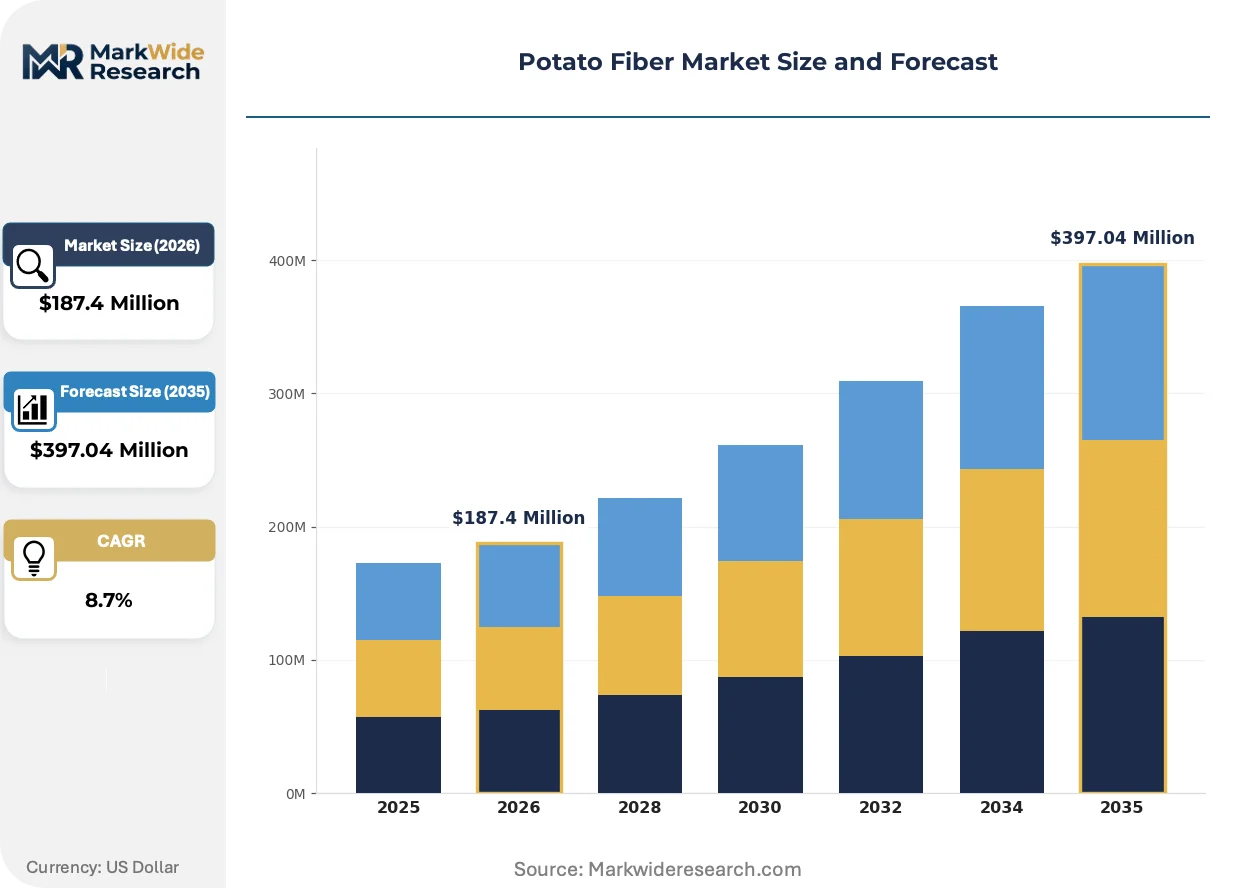
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Flakes, Pellets Application: Baking, Snacks, Sauces, Dairy End User: Food Processing, Animal Feed, Cosmetics, Pharmaceuticals Distribution Channel: Online, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | AVEBE, Emsland Group, Roquette Frères S.A., J. RETTENMAIER & SÖHNE GmbH (JRS), Ingredion Incorporated, AGRANA Beteiligungs-AG, Lyckeby Starch AB, Basic American Foods, Keystone Potato Products LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potato Fiber Market Emerging Trajectories
Enzymatic extraction protocols and precision fermentation adjuncts are redefining purity benchmarks while regulatory convergence across Atlantic jurisdictions compresses qualification timelines for cross-border suppliers.
Membrane filtration technology is decomposing traditional centrifugation workflows in soluble fiber recovery. German starch processors are retrofitting ceramic membrane cascades to achieve 85%+ purity without alcohol precipitation steps. This shift is decomposing capital barriers for mid-scale entrants previously locked out by solvent recovery infrastructure requirements.
EFSA's 2024 guidance on dietary fiber analytical methods is tightening quantification protocols for resistant starch fractions. Food laboratories across France, Italy, and Spain are recalibrating AOAC-approved assays to meet updated reference standards. Bakery and pasta manufacturers in Southern Europe face reformulation costs as legacy fiber counts drop under stricter measurement rules.
Direct procurement from processor cooperatives is displacing ingredient distributor intermediaries in North American sourcing. Large CPG manufacturers in Chicago and Toronto are establishing annual volume contracts with AVEBE and Emsland Group, bypassing traditional importers. This pattern concentrates most visible in clean-label snack and plant-based dairy verticals where traceability documentation carries premium value.
Potato Fiber Market Segmentation
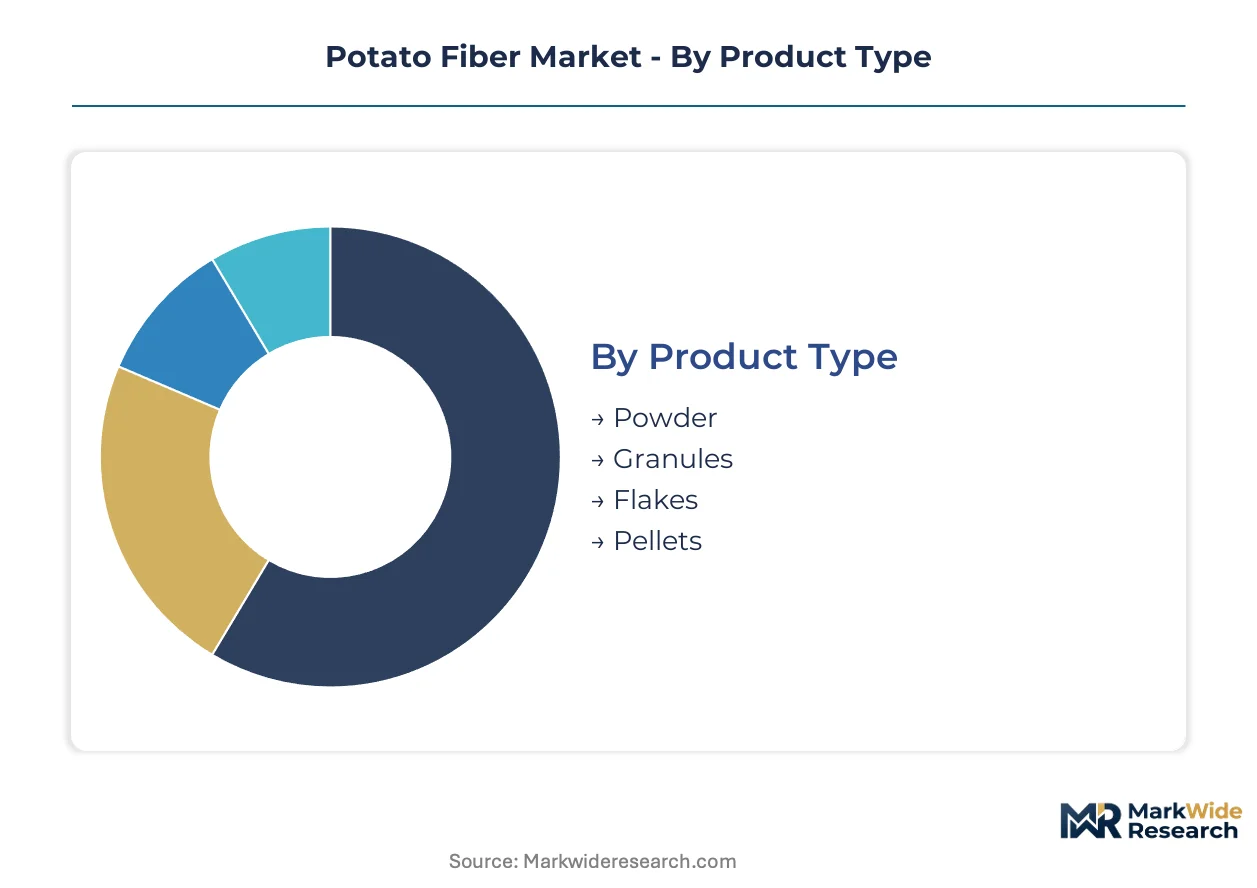
Potato fiber segmentation reveals how physical form, application requirements, and customer specifications create distinct value tiers. Manufacturers must align extraction technology and certification levels to the precise demands of each segment cluster.
Product Type:
Powder formats face the strongest substitution pressure from resistant maltodextrin and oat fiber in beverage and bakery systems, while pellet and granule forms defend position in feed and industrial applications where dissolution speed matters less.
- Powder:Fine-milled particles below 100 microns enable rapid hydration in dough matrices and liquid suspensions. Dairy and baking formulators in Germany and the Netherlands specify powder grades for clean-label fat replacement where emulsifier disclosure is restricted.
- Granules:Coarse particles between 0.5-2mm retain structural integrity under shear stress. Snack manufacturers in North America favor granules for extruded product texture where mouthfeel consistency drives repeat purchase.
- Flakes:Thin compressed layers suit visual fiber enrichment in artisan bread and premium cracker applications.
- Pellets:Dense agglomerated forms serve compound feed mills and pet food processors seeking dust-free handling and precise dosing.
Powder retains volume leadership; granules hold the steepest expansion curve as extruded snack reformulation accelerates.
Application:
Cost tier stratification separates commodity baking applications from pharmaceutical-grade dairy systems where batch certification carries 40-60% price premiums.
- Baking:Bread and pastry formulators leverage water-binding capacity above seven times dry weight to replace hydrocolloids in clean-label recipes. French and Italian industrial bakeries are recalibrating formulations as EFSA tightens fiber quantification protocols.
- Dairy:Yogurt and cheese processors incorporate soluble fiber for viscosity control without modified starch declaration. German dairy cooperatives specify pharmaceutical-grade documentation for functional dairy positioning.
- Snacks:Extruded and puffed products utilize fiber for oil absorption reduction and structural integrity.
- Sauces:Dressings and condiments employ low-viscosity fiber fractions to replace xanthan gum in label-friendly reformulations.
Baking commands the largest volume share; dairy applications are climbing the fastest as clean-label positioning intensifies in fermented products.
End User:
Customer type determines margin structure, with pharmaceutical buyers demanding USP-NF certification and food processors prioritizing cost-per-functional-unit metrics.
- Food Processing:Industrial bakeries, dairy plants, and ready-meal manufacturers constitute the core demand base. Emsland Group and AVEBE direct annual volume contracts to large CPG manufacturers in Chicago and Toronto seeking traceability documentation.
- Pharmaceuticals:Generic drug manufacturers specify potato fiber as tablet disintegrant and excipient filler. USP-NF certification requirements strain quality infrastructure at mid-scale processors.
- Animal Feed:Compound feed mills incorporate pelletized fiber for digestive health claims in premium pet nutrition.
- Cosmetics:Formulators in Netherlands test fiber as biodegradable microplastic replacement in rinse-off products.
Food processing retains volume leadership; pharmaceuticals hold the steepest expansion curve as excipient qualification pathways mature.
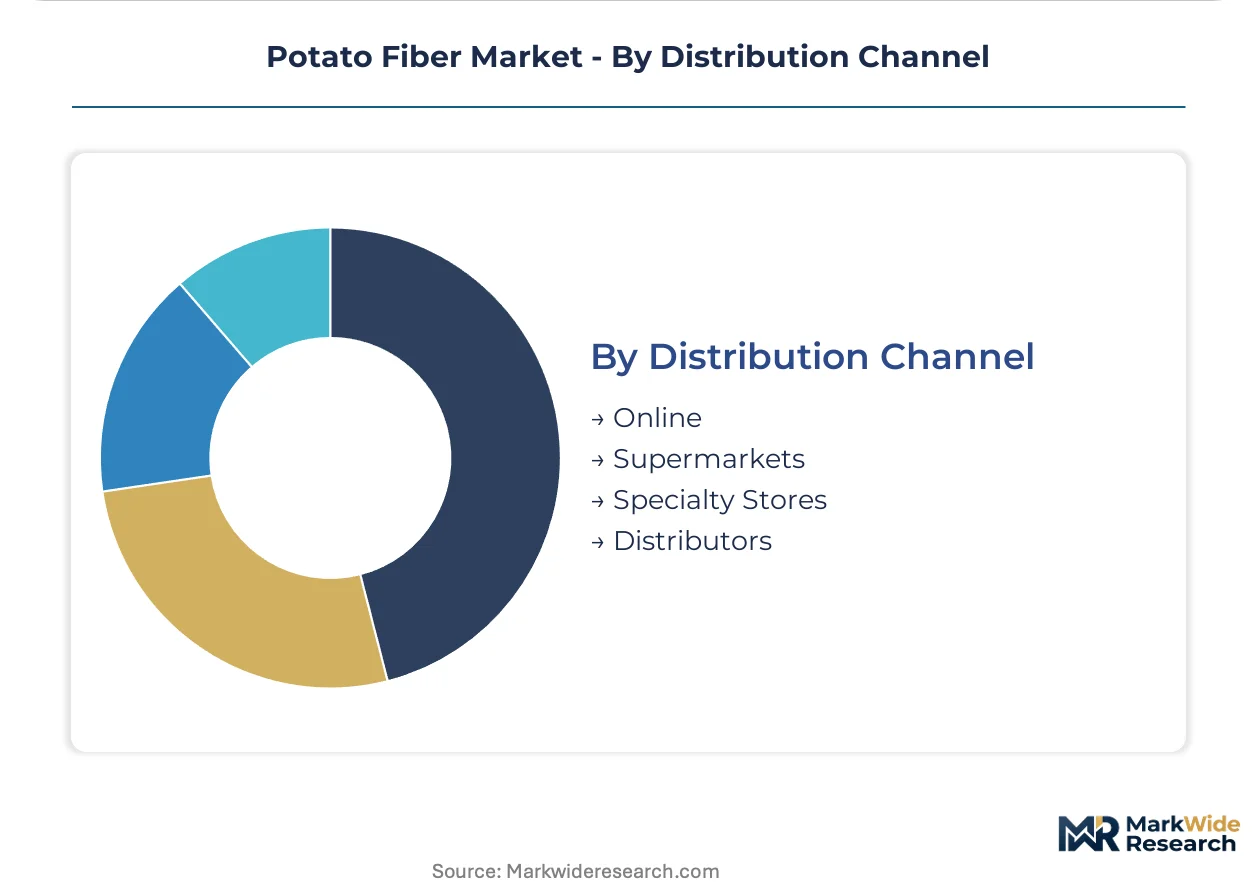
Distribution Channel:
Supply concentration shapes channel economics, with processor-direct procurement displacing traditional importers in high-traceability verticals.
- Distributors:Ingredient distributors retain relevance in mid-scale bakery and snack accounts lacking volume for direct contracts. Traditional importers face margin compression as large CPG manufacturers establish annual volume contracts with Dutch and German cooperatives.
- Online:Digital procurement platforms serve small-scale formulators and specialty food startups seeking sample quantities and technical documentation. Direct procurement from processor cooperatives concentrates in clean-label snack and plant-based dairy verticals.
- Supermarkets:Retail channels move consumer-packaged fiber supplements and home baking ingredients.
- Specialty Stores:Health food retailers stock organic-certified fiber for digestive wellness positioning.
Distributors retain volume leadership; online channels are expanding most quickly as procurement digitization penetrates mid-scale accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances tilt heavily toward Western European surplus, with Dutch and German cooperatives supplying North American and Asian food processors seeking EFSA-compliant fiber documentation. Import dependency concentrates in markets lacking wet-milling infrastructure.
Germany
Dairy reformulation drives soluble fiber procurement as yogurt manufacturers eliminate modified starch declarations. EFSA Regulation 1924/2006 health claim substantiation requirements favor clinically validated suppliers. The Emsland region anchors starch processing clusters where backward integration secures pulp feedstock consistency across harvest cycles.
Netherlands
Plant-based meat formulators test potato fiber as methylcellulose replacement in extruded products. REACH compliance protocols govern excipient qualification for pharmaceutical exports. The Groningen potato starch cluster enables cost-competitive soluble fiber extraction through concentrated wet-milling infrastructure.
United States
FDA fiber definition updates create qualification pathways for European suppliers to displace resistant maltodextrin in artisan bread. Chicago and Toronto CPG manufacturers establish direct annual volume contracts with Dutch cooperatives, bypassing traditional importers. Midwest snack reformulation accelerates granule-format demand for extruded product texture.
France
Industrial bakeries recalibrate formulations as EFSA tightens fiber quantification protocols for resistant starch fractions. ANSM pharmaceutical excipient standards strain mid-scale processors lacking ISO 17025-accredited testing infrastructure. Northern starch processing facilities face margin pressure from stricter AOAC assay recalibration requirements.
Canada
Health Canada labeling alignment with FDA fiber definitions opens import qualification for European suppliers. Toronto-based clean-label snack manufacturers prioritize traceability documentation in direct procurement from processor cooperatives. Prairie region feed mills incorporate pelletized fiber for premium pet nutrition digestive health claims.
Potato Fiber Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers, with publicly traded ingredient conglomerates facing cooperative-owned processors in premium fiber segments. Market structure concentrates in German-Dutch cooperative networks controlling upstream pulp supply, while mid-scale independents compete on pharmaceutical-grade documentation. Three archetypes dominate: cooperative-backed starch processors with captive feedstock, diversified ingredient conglomerates with cross-selling infrastructure, and pharmaceutical specialists with USP-NF certification capabilities. Capacity expansion and backward integration into regional starch extraction represent the dominant competitive moves.
Within the cooperative-processor tier, AVEBE leverages its Dutch potato cooperative network to secure raw material consistency, while Emsland Group anchors German production capacity. Roquette Frères S.A. occupies a position exemplifying pharmaceutical-grade fiber qualification for excipient applications, differentiating through batch-certified purity documentation demanded by generic drug manufacturers.
| Leading Market Players |
|---|
| AVEBE |
| Emsland Group |
| Roquette Frères S.A. |
| J. RETTENMAIER & SÖHNE GmbH (JRS) |
| Ingredion Incorporated |
| AGRANA Beteiligungs-AG |
| Lyckeby Starch AB |
| Basic American Foods |
| Keystone Potato Products LLC |
| Others |
Supply Flow & Price Mechanics
EFSA Regulation 1924/2006 health claim substantiation requirements gate both supply qualification and price differentiation simultaneously, compelling European processors to invest in clinical validation infrastructure that separates pharmaceutical-grade documentation from commodity fiber tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the potato fiber market. Pricing stratifies across pharmaceutical-grade, food-grade, and feed-grade tiers where USP-NF certification commands 40-60% premiums over standard food applications. Cost compression in feed-grade segments is intensifying because starch processing margins tighten during poor tuber harvests. Mid-scale bakery formulators exhibit highest price sensitivity, while generic drug manufacturers accept premium positioning for batch-certified excipient documentation.
Supply Chain Analysis
Inventory lead times stretch 8-12 weeks for North American importers sourcing from Dutch and German cooperative networks. Geographic supply concentrates in the Netherlands, Germany, and France where wet-milling infrastructure clusters around Groningen and the Emsland region. Raw material flows draw from potato pulp feedstock, ceramic membrane filtration systems, and ISO 17025-accredited testing laboratories. Single-source vulnerability from cooperative-controlled capacity creates structural risk for cross-Atlantic buyers. Distribution runs through processor-direct annual volume contracts displacing traditional ingredient importers in high-traceability verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label formulation mandates across dairy and bakery applications are accelerating market disruption as enzymatic extraction protocols mature and regulatory convergence compresses qualification timelines.
For Market Incumbents: Shield margin position in pharmaceutical-grade segments through USP-NF certification investments that generic drug manufacturers demand for tablet disintegrant applications. Deepen backward integration into regional starch extraction to secure pulp feedstock consistency across seasonal harvest cycles. Counter substitution pressure from resistant maltodextrin by accelerating clinical substantiation dossiers under EFSA review protocols.
For New Entrants and Emerging Players: Anchor in the underpenetrated United States bakery sector where FDA fiber definition updates create qualification pathways for European-grade soluble fiber. Target artisan bread and clean-label snack verticals in Chicago and Toronto where direct procurement from processor cooperatives is displacing traditional importers. Pursue membrane filtration technology licensing to bypass capital barriers from solvent recovery infrastructure requirements.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across mid-scale membrane filtration deployments as ceramic cascade retrofits decompose entry barriers previously locked by alcohol precipitation infrastructure. Five-to-ten year viability favors processors with captive potato cooperative supply and pharmaceutical-grade certification capabilities. Watch EFSA guidance on dietary fiber analytical methods as the inflection signal for reformulation cost waves across Southern European bakery and pasta manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Starch Extraction | Emsland Group and AVEBE secure pulp feedstock consistency across seasonal harvest variability. |
| Pharmaceutical-Grade Certification Investment | USP-NF qualification opens margin-rich contracts with generic drug manufacturers seeking excipient alternatives. |
| Membrane Filtration Technology Deployment | Ceramic cascade retrofits enable 85%+ purity without solvent recovery infrastructure. |
| Direct Procurement Contract Establishment | Chicago and Toronto CPG manufacturers bypass traditional importers for traceability documentation. |
| Clinical Substantiation Dossier Development | EFSA health claim validation separates clinically verified suppliers from unverified fiber alternatives. |
Methodological Framework
The analysis maps soluble fiber extraction technologies, application-grade specifications, and certification tier structures, each validated through technical directors at starch processing cooperatives, procurement leads at North American CPG manufacturers, regulatory affairs specialists navigating EFSA and FDA fiber definitions, and quality managers at pharmaceutical excipient operations. Secondary sources include EFSA guidance documents, FDA nutrition labeling rules, USP-NF certification records, and customs trade data for potato pulp derivatives. Bottom-up capacity modeling and top-down demand aggregation were triangulated against processor-reported utilization rates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by product form, application vertical, end-user category, and distribution channel, with CAGRs derived from historical price trajectory analysis and capacity expansion announcements. Forecast inputs incorporated enzymatic extraction yield improvements, membrane filtration adoption curves, and regulatory timeline assumptions for health claim substantiation reviews.
Material uncertainties — tuber harvest volatility, EFSA analytical method revisions, and FDA enforcement discretion — sit outside the modeled envelope. Forecasts reflect documented assumptions about cooperative capacity expansion and pharmaceutical qualification pathway maturation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Specialty Flours Market
Ingredients
Aroma Ingredients Market
Ingredients
United States Soy Protein Market
Ingredients
L-Arabinose Market
Ingredients
Licorice Root Market
Ingredients
Botanical Extracts Market
Ingredients
Plant Based Premix Market
Ingredients
Carob Powder Market
Ingredients
Non-GMO Soya Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Torula Yeast Market
Ingredients
North America Whey Protein Ingredients Market
Ingredients
North America Malt Ingredients Market
Ingredients
Cocoa Solids Market
Ingredients
Bran Market
Ingredients
Yeast Autolysates Market