
 Mexico Food Acidulants Market | 2026-2036
Mexico Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Food Acidulants Market Foresight
COFEPRIS food additive registration is collapsing the vendor qualification cycle, forcing distributors to pre-validate acidulant purity before import. Archer Daniels Midland Company leverages its captive citric acid fermentation capacity to bypass third-party bottlenecks. Cargill, Incorporated anchors its position through backward integration into corn-derived feedstock supply. Jungbunzlauer Holding AG differentiates via specialized lactic acid grades for dairy pH stabilization.
Food acidulants comprise organic acids—citric, lactic, acetic, and malic—typically supplied at 50-99% concentration purity for pH reduction, microbial inhibition, and flavor modulation in processed foods. Industrial users specify acidulant blends by titratable acidity and buffering capacity to match heat-process tolerance in retort applications. Citric acid occupies the largest volume share due to its GRAS status and versatility across beverage acidification and antioxidant synergy. Lactic acid represents the fastest-expanding category, propelled by clean-label fermentation-derived positioning in dairy and plant-based alternatives. pH Control applications command premium pricing relative to flavoring agents, reflecting tighter specification windows and batch certification requirements.
COFEPRIS maintains the primary registration pathway for acidulant import and use, while NOM-051 nutritional labeling standards shape formulation disclosure requirements that cascade into acidulant selection criteria. The Secretaría de Economía monitors anti-dumping measures on Chinese citric acid imports, directly affecting domestic pricing benchmarks and sourcing strategy. Stakeholders must track regulatory alignment between Mexican additive standards and US FDA GRAS determinations, as cross-border supply agreements increasingly predicate compliance on dual-jurisdiction recognition.
Market Dynamics
COFEPRIS registration timelines are compressing vendor qualification cycles, forcing distributors to pre-validate acidulant purity certificates before cargo departs foreign ports. This procedural tightening redistributes margin from traders to vertically integrated suppliers with captive laboratory certification capacity.
Growth Catalysts
- NOM-051 nutritional labeling standards:Reformulation disclosure requirements are cascading into acidulant selection criteria, pulling fermentation-derived lactic acid into clean-label dairy applications.
- Beverage processing corridor concentration:Central Mexico's cluster of carbonated and juice manufacturers generates concentrated demand for citric acid with specified titratable acidity ranges.
- Retort application expansion:Heat-process tolerance specifications for shelf-stable prepared meals are expanding the addressable market for buffered acidulant blends.
Market Restraints
- Chinese citric acid anti-dumping measures:Secretaría de Economía monitoring of import pricing creates supply uncertainty and pushes buyers toward higher-cost Western Hemisphere sourcing.
- Corn feedstock price volatility:Drought conditions in Sinaloa and Tamaulipas generate input cost instability for fermentation-based acidulant production.
- COFEPRIS batch certification delays:Laboratory backlog extends qualification timelines from 90 to 180 days for new supplier entrants.
Strategic Opportunities
- Guadalajara dairy processing expansion:Jalisco's cheese and yogurt manufacturing base remains underpenetrated for specialized lactic acid grades with defined optical purity.
- Plant-based alternative formulation:Oat and almond milk processors require pH stabilization systems distinct from traditional dairy applications.
- Dual-jurisdiction compliance services:Cross-border suppliers are bundling COFEPRIS registration with US FDA GRAS documentation to capture maquiladora beverage exporters.
Industry Challenges
- Analytical chemistry talent scarcity:Qualified personnel for titratable acidity and buffering capacity testing are concentrated in Mexico City, constraining regional laboratory expansion.
- Legacy ERP integration:Batch certification tracking systems from COFEPRIS require middleware development to connect with established inventory management platforms.
- Refrigerated logistics fragmentation:Temperature-controlled distribution for high-purity liquid acidulants lacks consolidated carrier networks outside the central corridor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Food Acidulants Market |
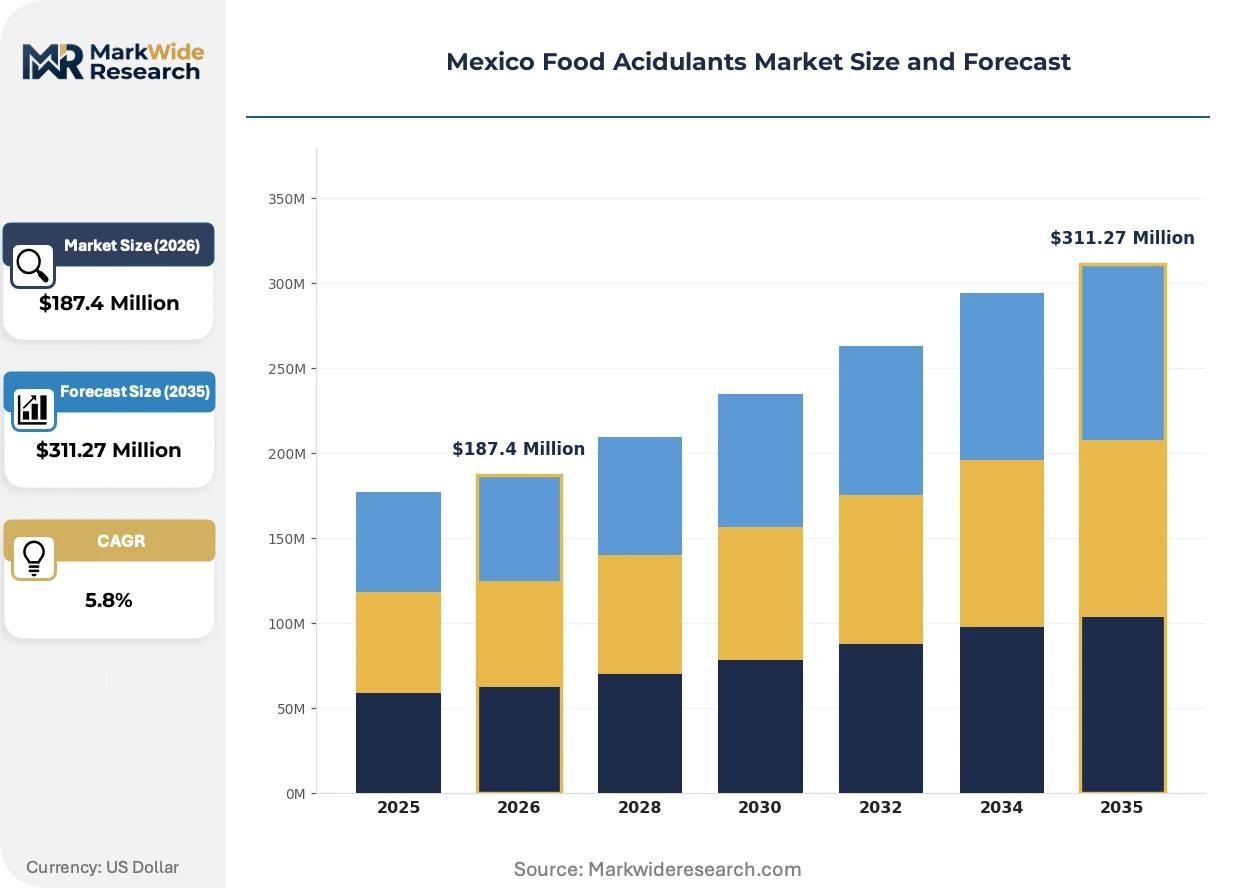
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Lactic Acid, Acetic Acid, Malic Acid End User: Food & Beverage, Dairy Products, Bakery, Confectionery Application: Flavoring Agent, pH Control, Preservative, Texturizer Distribution Channel: Supermarket, Online Retail, Specialty Stores, Wholesalers |
| Companies Covered | Archer Daniels Midland Company, Tate & Lyle PLC, Brenntag AG, Corbion N.V., Jungbunzlauer Holding AG, Bartek Ingredients Inc, Cargill, Incorporated, Ingredion, Univar Solutions LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Food Acidulants Market Shifts & Advancements
Fermentation-derived acidulant production is fragmenting traditional petrochemical supply relationships, while regulatory disclosure requirements and procurement model evolution are compressing supplier-buyer contracting cycles.
Biotechnological fermentation platforms for lactic acid production are fragmenting the historical dominance of synthetic chemical routes. Dairy processors in Querétaro and Aguascalientes are adopting these grades at contract volumes that now rival citric acid offtake in beverage applications. This shift is fragmenting supplier portfolios, forcing distributors to maintain dual sourcing relationships across synthetic and biotech production bases.
COFEPRIS has tightened contaminant threshold specifications for imported acidulants, aligning with US FDA Food Safety Modernization Act preventive control frameworks. Industrial users must now submit batch-specific heavy metal and microbial certificates prior to customs release. The beverage sector, particularly carbonated soft drink bottlers in Estado de México, is responding by consolidating supplier relationships with integrated manufacturers possessing captive laboratory infrastructure.
Direct mill relationships are displacing layered distribution networks for high-volume acidulant consumers. Tortilla and bakery manufacturers in Puebla and Veracruz are negotiating annual contracts with fermentation facilities rather than regional chemical distributors. This pattern concentrates procurement leverage among processors with sufficient volume to justify dedicated tanker logistics, compressing margin capture for intermediary trading houses.
Mexico Food Acidulants Market Segmentation
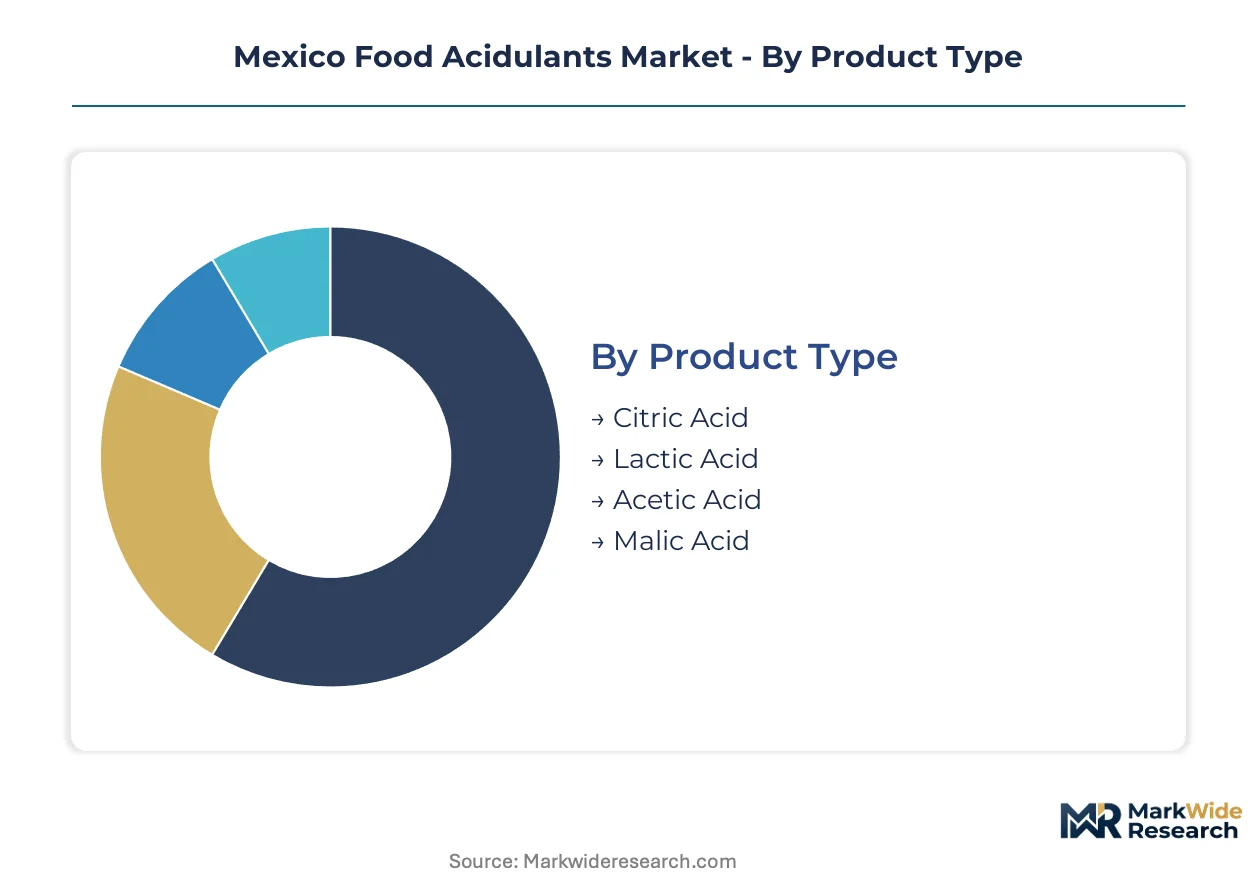
Mexico's food acidulant demand fragments across distinct technical specifications and end-use tolerances. Each segment carries unique COFEPRIS certification requirements that reshape supplier qualification economics.
Product Type:
Domestic fermentation capacity concentrates citric and lactic acid production near Guadalajara and central Mexico, while acetic and malic acid supplies depend heavily on import flows through Veracruz port.
- Citric Acid:GRAS-status organic acid supplied at 50-99% concentration purity for beverage acidification and antioxidant synergy. Demand clusters among carbonated soft drink bottlers in Estado de México seeking specified titratable acidity ranges for heat-process tolerance. COFEPRIS batch certification delays favor integrated manufacturers with captive laboratory infrastructure.
- Lactic Acid:Fermentation-derived grades with defined optical purity for dairy pH stabilization. Querétaro and Aguascalientes cheese processors now contract volumes rivaling citric acid offtake in beverages. Clean-label positioning accelerates substitution away from synthetic chemical routes.
- Acetic Acid:Vinegar-derived and synthetic grades for pickling and sauce applications. Import dependency creates pricing exposure to peso-dollar volatility.
- Malic Acid:Tartness enhancement specialist for confectionery and fruit-flavored beverages. Lower volume segment with concentrated demand among candy manufacturers in Mexico City metropolitan area.
Citric acid commands the established base. The steepest expansion runs through lactic acid.
End User:
Cost-tier differentiation separates high-volume beverage processors with dedicated tanker logistics from smaller bakery and confectionery operations purchasing through distributors.
- Food & Beverage:Carbonated and juice manufacturers in central Mexico generate concentrated demand for citric acid with tight titratable acidity specifications. Direct mill relationships displace layered distribution networks for annual contract volumes.
- Dairy Products:Jalisco's cheese and yogurt manufacturing base drives specialized lactic acid grades with defined optical purity requirements. Guadalajara processing expansion remains underpenetrated for fermentation-derived positioning.
- Bakery:Tortilla and bread manufacturers in Puebla negotiate supply agreements with fermentation facilities rather than regional chemical distributors. Volume thresholds determine procurement leverage.
- Confectionery:Candy producers in Mexico City metropolitan area specify malic acid for tartness modulation in fruit-flavored applications. Smaller batch sizes sustain distributor relationships.
Food & beverage anchors volume concentration. Dairy products are climbing the fastest.
Application:
Specification windows tighten from flavor modulation through pH control to preservative functions, with corresponding margin阶梯 across certification requirements.
- Flavoring Agent:Acidulant blends selected for sensory impact in beverages and confectionery. Relaxed specification tolerances relative to functional applications.
- pH Control:Tight specification windows and batch certification requirements command premium pricing. Dairy processors in Aguascalientes require precise buffering capacity matching for retort applications.
- Preservative:Microbial inhibition functionality drives concentration purity requirements. COFEPRIS contaminant thresholds align with US FDA preventive control frameworks.
- Texturizer:Acidulant-protein interactions in dairy and plant-based alternatives. Oat and almond milk processors demand pH stabilization systems distinct from traditional dairy.
pH control captures margin premiums. Texturizer functions are gaining share fastest.
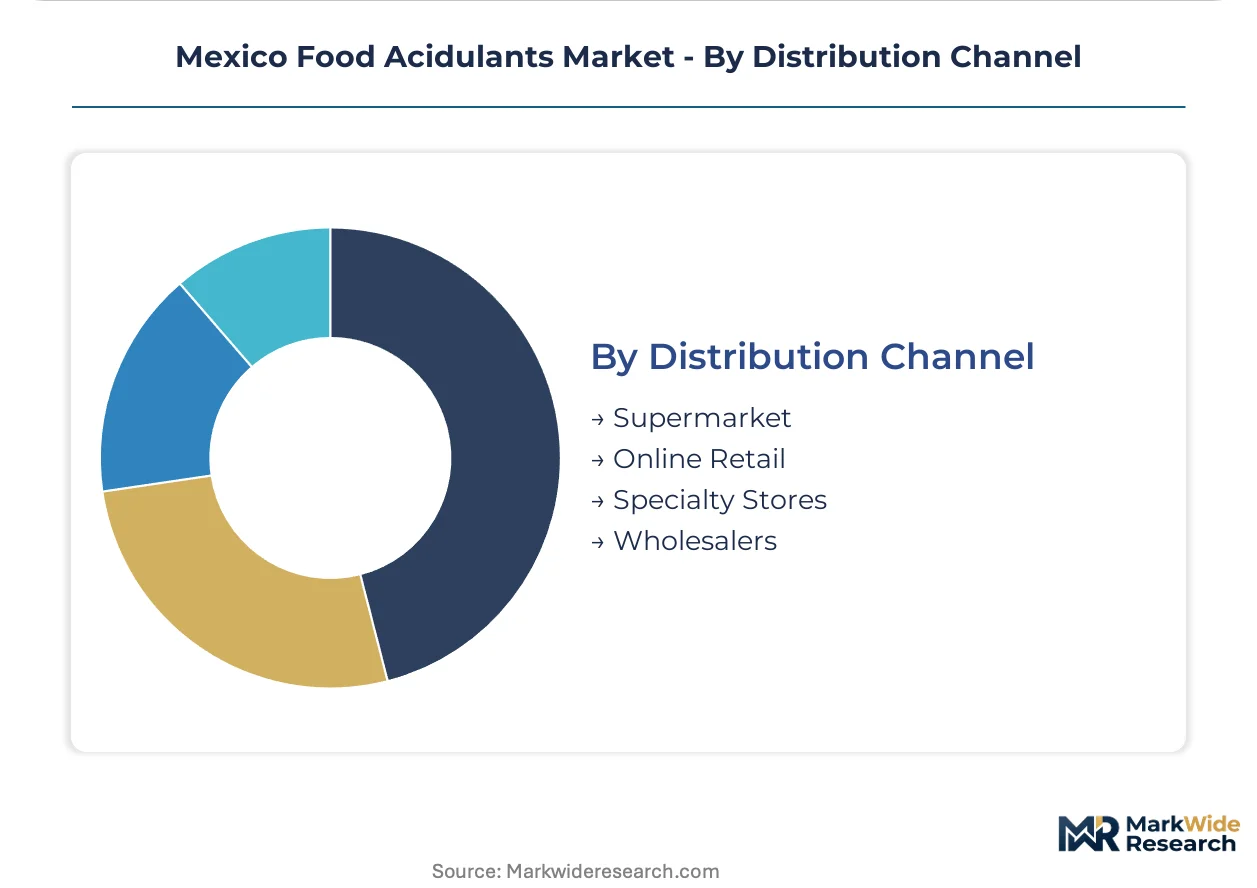
Distribution Channel:
Channel selection correlates with buyer scale, with high-volume processors bypassing intermediaries while smaller operators depend on fragmented refrigerated logistics networks.
- Supermarket:Retail-packaged acidulant sales for small-scale food processors and institutional kitchens. Limited volume relative to industrial channels.
- Online Retail:Emerging channel for specialty acidulant grades and technical documentation access. COFEPRIS certificate verification remains a friction point.
- Specialty Stores:Regional chemical distributors serving Puebla and Veracruz tortilla manufacturers. Margin compression from direct mill relationships.
- Wholesalers:Layered distribution networks for medium-volume buyers lacking dedicated tanker logistics. Temperature-controlled fragmentation constrains regional expansion outside central corridor.
Wholesalers retain the established base. Online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
COFEPRIS registration timelines and NOM-051 labeling standards are redistributing acidulant procurement leverage across Mexican sub-regions, favoring processors with captive laboratory infrastructure and direct fermentation facility relationships.
Mexico City Metro
Carbonated soft drink bottlers in Estado de México specify citric acid with tight titratable acidity ranges for heat-process tolerance. COFEPRIS batch certification requirements concentrate procurement among integrated manufacturers with captive laboratory infrastructure. The metropolitan confectionery cluster generates specialized malic acid demand for tartness modulation in fruit-flavored applications.
Jalisco
Guadalajara's cheese and yogurt manufacturing base drives fermentation-derived lactic acid grades with defined optical purity requirements. The state's dairy processing expansion remains underpenetrated for clean-label acidulant positioning. NOM-051 reformulation disclosure requirements pull biotechnological lactic acid into premium dairy applications.
Bajío Region
Querétaro and Aguascalientes processors contract lactic acid volumes now rivaling citric acid offtake in beverages. Retort application specifications for shelf-stable prepared meals expand demand for buffered acidulant blends. COFEPRIS contaminant threshold tightening aligns procurement with US FDA preventive control frameworks for cross-border suppliers.
Nuevo León
Monterrey-based food manufacturers negotiate direct mill relationships with fermentation facilities rather than regional chemical distributors. Corn feedstock price volatility from Sinaloa and Tamaulipas drought conditions generates input cost instability for acidulant production. Dedicated tanker logistics justify annual contract volumes that compress intermediary trading house margins.
Puebla and Veracruz
Tortilla and bakery manufacturers in this corridor bypass layered distribution networks for supply agreements with fermentation facilities. Temperature-controlled distribution fragmentation constrains high-purity liquid acidulant logistics outside the central corridor. Secretaría de Economía anti-dumping monitoring on Chinese citric acid pushes buyers toward Western Hemisphere sourcing alternatives.
Mexico Food Acidulants Market Competitive Landscape
Player mix skews toward integrated fermentation specialists with captive corn-derived feedstock supply and laboratory certification capacity. Market structure concentrates procurement leverage among processors with sufficient volume to justify dedicated logistics, compressing margin capture for intermediary distributors. Strategic archetypes include backward-integrated agricultural processors, specialized organic acid fermentation houses, and chemical distribution networks with regional refrigerated infrastructure. Dominant competitive moves encompass direct mill relationship cultivation and dual-jurisdiction compliance service bundling for maquiladora exporters.
Among North American agricultural processors, Archer Daniels Midland Company and Cargill, Incorporated occupy positions exemplifying feedstock-integrated fermentation capacity. Swiss-based Jungbunzlauer Holding AG represents the specialized organic acid tier with defined optical purity positioning. These three anchors illustrate the strategic divide between commodity-scale citric acid supply and differentiated lactic acid grades for dairy pH stabilization.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Brenntag AG |
| Corbion N.V. |
| Jungbunzlauer Holding AG |
| Bartek Ingredients Inc |
| Cargill, Incorporated |
| Ingredion |
| Univar Solutions LLC |
| Others |
Supply & Pricing Matrix
Ninety-day pre-validation windows for COFEPRIS batch certification now govern inventory planning, compressing margin capture for distributors lacking captive laboratory infrastructure while amplifying pricing power for integrated fermentation houses with in-house analytical capacity. This lead-time compression reshapes procurement economics across Mexico's central beverage corridor and Jalisco dairy belt.
Pricing Analysis
Certification grade creates the primary spread between commodity citric acid and pharmaceutical-grade lactic acid tiers. Three-tier pricing structure across premium, standard, and economy levels reflects COFEPRIS contaminant thresholds, titratable acidity precision, and optical purity specifications. Cost compression in standard-grade citric acid is intensifying because Secretaría de Economía anti-dumping monitoring constrains Chinese import flows. Small-scale tortilla manufacturers in Puebla exhibit highest price sensitivity, while carbonated beverage bottlers in Estado de México absorb premiums for heat-process tolerance certification.
Supply Chain Analysis
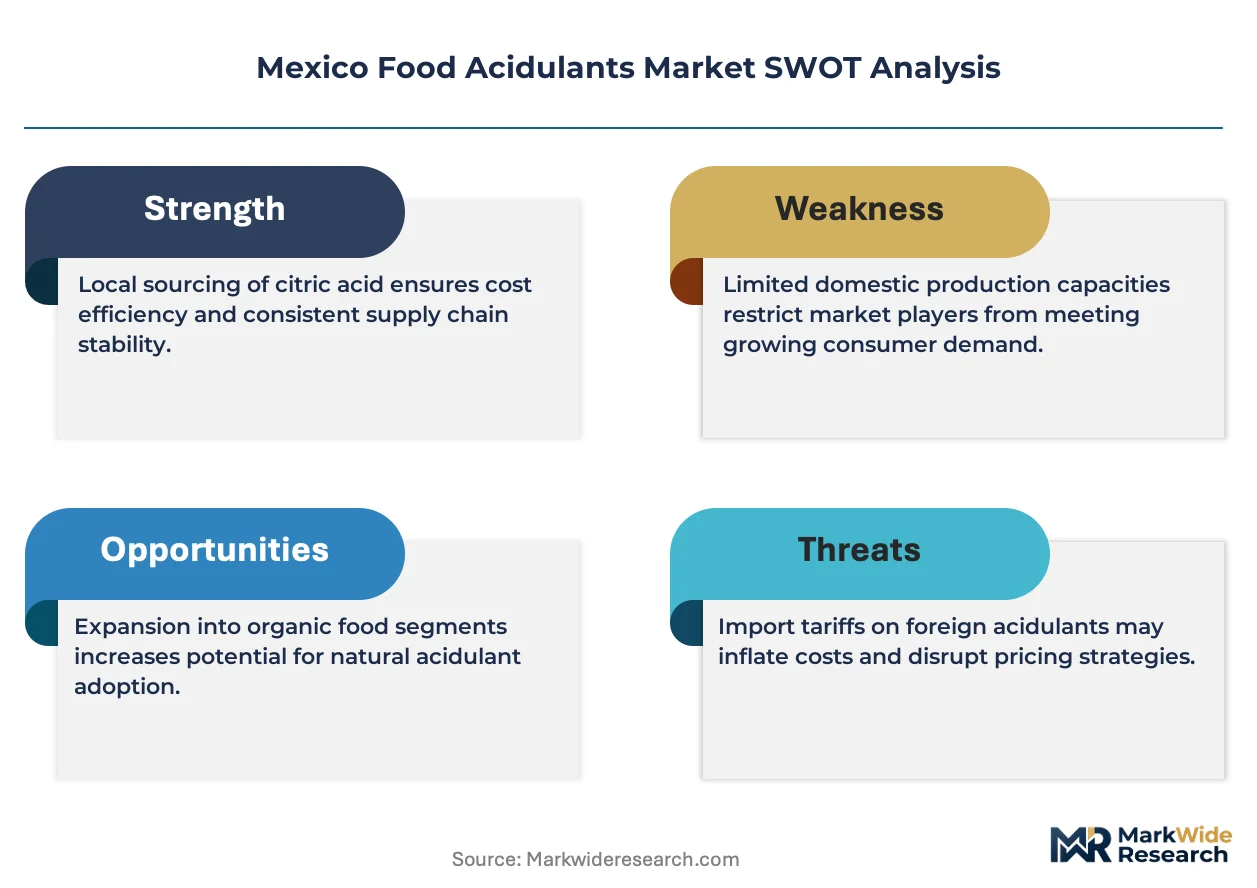
Strategic stockpile preferences dominate among integrated manufacturers buffering against Sinaloa and Tamaulipas corn feedstock volatility, while just-in-tanker delivery governs high-volume beverage processors with dedicated logistics. Supply concentrates in domestic fermentation capacity near Guadalajara and central Mexico, with acetic and malic acid sourcing drawing from Chinese and US import flows through Veracruz port. Raw material dependencies center on corn-derived glucose feedstock, laboratory reagents for batch certification, and refrigerated transport capacity. Single-source vulnerability runs through COFEPRIS-registered laboratory infrastructure concentrated in Mexico City. Distribution runs through direct mill relationships for annual contract volumes above tanker thresholds, with regional chemical distributors serving fragmented smaller buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food acidulant demand cycles track corn harvest volatility and COFEPRIS regulatory enforcement waves, with current conditions favoring processors that secured feedstock contracts ahead of drought-driven input cost spikes.
For Market Incumbents: Consolidate procurement leverage through captive corn-derived feedstock supply in Guadalajara fermentation corridors, while deepening laboratory certification capacity to compress rival qualification timelines. Biotechnological lactic acid entrants threaten premium dairy positioning; defend through optical purity specialization and NOM-051 clean-label certification bundling. For New Entrants and Emerging Players: COFEPRIS fast-track registration for US FDA-GRAS pre-cleared acidulant grades opens immediate access to maquiladora beverage exporters. Guadalajara dairy processing expansion remains the most penetrable geography, with undercontracted cheese and yogurt manufacturers seeking fermentation-derived lactic acid alternatives. Lead with dual-jurisdiction compliance documentation as the go-to-market wedge. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biotechnological lactic acid production as optical purity specifications tighten. Five-to-ten-year viability favors backward-integrated fermentation specialists with captive corn supply and laboratory infrastructure. Target acquisition archetype: mid-scale organic acid houses with COFEPRIS registration track records and underutilized capacity in central Mexico. Watch for inflection when NOM-051 disclosure requirements expand to plant-based alternative categories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Feedstock Supply | Cargill and ADM anchor cost stability through captive Sinaloa and Tamaulipas sourcing. |
| Dual-Jurisdiction Compliance Bundling | COFEPRIS registration paired with US FDA GRAS documentation captures maquiladora exporters. |
| Specialized Lactic Acid Grade Development | Jungbunzlauer targets Querétaro and Aguascalientes dairy processors with defined optical purity. |
| Direct Mill Relationship Cultivation | Puebla tortilla manufacturers bypass distributors for fermentation facility annual contracts. |
| Laboratory Certification Capacity Expansion | Integrated manufacturers compress rival qualification timelines from 180 to 90 days. |
Research Methodology
A spread of perspectives from fermentation plant managers, procurement leads at carbonated beverage bottlers, COFEPRIS regulatory affairs specialists, and dairy processing technical directors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs/trade data, COFEPRIS registration databases, and SEC 10-K filings of North American agricultural processors. Bottom-up acidulant volume estimates triangulated against top-down macroeconomic consumption models.
Segmentation dimensions modeled include acidulant type, end-use industry tier, application function, and distribution channel scale across the analysis window. CAGRs derived from historical trajectory analysis adjusted for regulatory enforcement intensity and feedstock cost inflection points. Forecast inputs incorporated NOM-051 reformulation disclosure timelines and anti-dumping measure probability assessments.
Decision-makers should treat outputs as directional under sustained COFEPRIS batch certification backlog assumptions; material deviation would warrant model refresh. Forecasts reflect corn yield volatility and peso-dollar exchange rate trajectories as primary revision triggers. Revision becomes warranted when Secretaría de Economía anti-dumping enforcement crosses threshold intensity sufficient to restructure Chinese import flows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
United States Food Preservatives Market
Food Additives and Ingredients
Carrageenan Gum Market
Food Additives and Ingredients
Sri Lanka Starch and Starch Derivative Market
Food Additives and Ingredients
United States Feed Additives Market
Food Additives and Ingredients
Quillaja Saponaria Ingredient Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
Germany Food Additives Market
Food Additives and Ingredients
Anti-Caking Market
Food Additives and Ingredients
Brazil Food Additives Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Salatrim Market
Food Additives and Ingredients
Asia-Pacific Food Preservatives Market
Food Additives and Ingredients
Australia Food Additives Market
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
Microencapsulated Food Ingredient Market
Food Additives and Ingredients
Global Baking Powder Market