
 Flavophospholipol Market | 2026-2036
Flavophospholipol Market Size, Share, and Industry Trends Forecast 2026-2036
Flavophospholipol Market Analytics
China is tilting global flavophospholipol supply dynamics through expanded fermentation capacity and phospholipid extraction infrastructure. Huvepharma leverages its integrated veterinary pharmaceutical platform to anchor European distribution networks for feed-grade additives. Jiangsu SEL Biochem dominates domestic Chinese output through captive raw material sourcing and specialized bacterial strain development. BASF SE extends its synthetic chemistry expertise into phospholipol derivatives for high-specification animal nutrition applications.
Flavophospholipol is a phosphoglycolipid antibiotic produced by Streptomyces species, functioning as a coccidiostat and growth promoter in animal feed through membrane-active antibacterial properties at concentrations typically ranging from 1 to 20 ppm. The compound serves primarily as a feed additive for improving feed conversion efficiency and controlling enteric pathogens in monogastric livestock. Powder formulations lead volume demand due to stability in premix blending operations and compatibility with standard feed mill equipment, while liquid concentrates capture margin pools in automated dosing systems for large-scale integrated poultry operations. Animal feed applications structurally anchor revenue, though nutraceutical and pharmaceutical segments attract R&D investment for human-grade phospholipid derivatives.
EFSA feed additive authorization protocols and REACH chemical registration requirements govern European market access, while China's Ministry of Agriculture and Rural Affairs oversees domestic feed additive production licensing and residue limit enforcement. The US FDA Center for Veterinary Medicine regulates import tolerances and new animal drug applications for phospholipol-based products entering American livestock supply chains. Stakeholders must monitor evolving regulatory divergence between antibiotic growth promoter restrictions in Europe and sustained permissive frameworks in major Asian production markets to calibrate portfolio and geographic prioritization decisions.
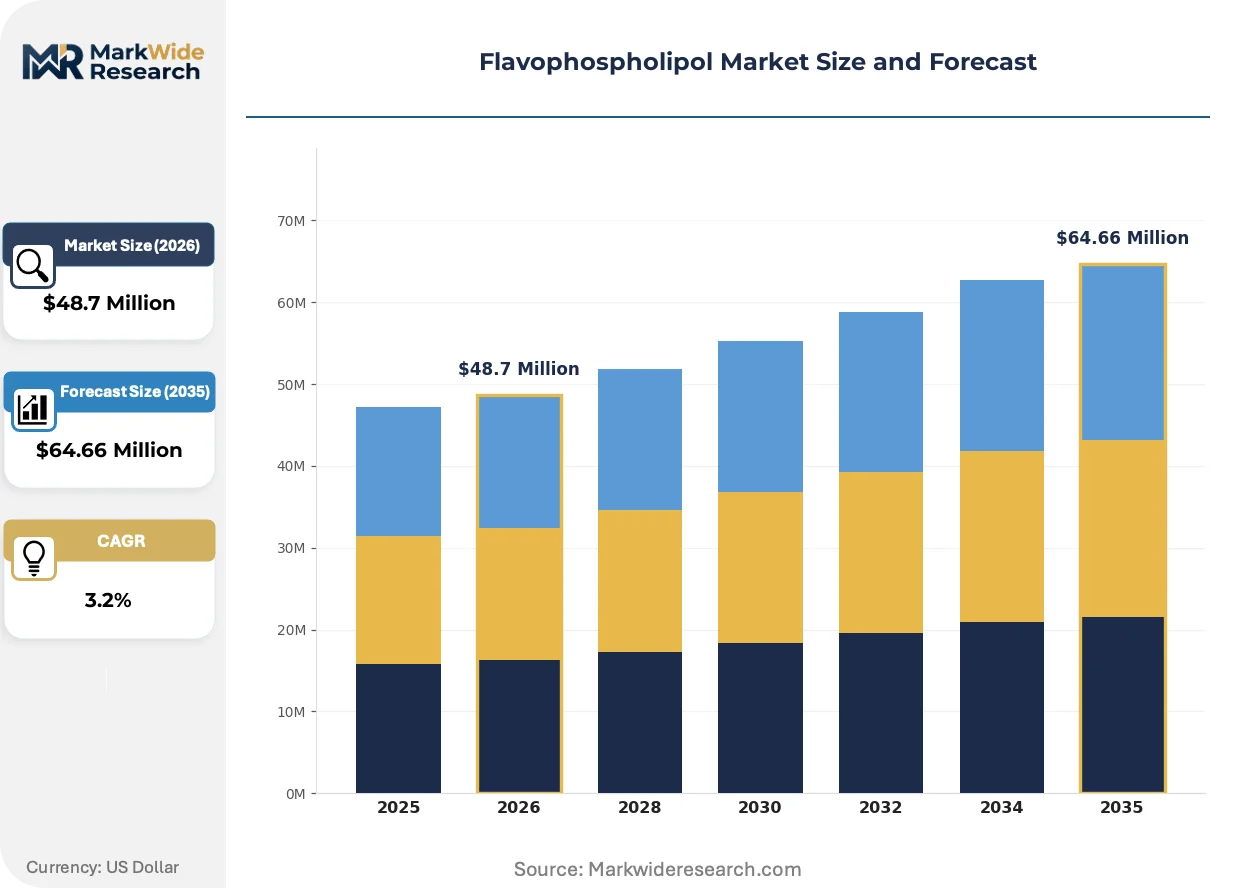
Market Dynamics
Antibiotic-free livestock production mandates across multiple jurisdictions are restructuring flavophospholipol demand patterns, forcing feed additive suppliers to reposition growth-promoter claims within coccidiostat-only regulatory frameworks while fermentation capacity races to meet residual therapeutic demand.
Growth Catalysts
- EFSA feed additive reauthorization:The European Food Safety Authority's streamlined technical dossier pathways accelerate market access for phosphoglycolipid-based coccidiostats in poultry and swine operations.
- Monogastric feed conversion efficiency:Broiler integrators deploy flavophospholipol at 5-10 ppm inclusion rates to suppress Clostridium perfringens and improve weight gain metrics in antibiotic-free production systems.
- Fermentation infrastructure expansion:China's Ministry of Agriculture and Rural Affairs licensing surge supports domestic Streptomyces strain optimization and phospholipid extraction capacity scaling.
Market Restraints
- Soybean oil feedstock volatility:Phospholipid precursor costs fluctuate with Chicago Board of Trade soybean futures, compressing margin structures for fermentation-derived glycerophospholipids.
- Regulatory fragmentation:Divergent residue limit standards between EU MRL regulations and China's GB 31650-2019 create compliance complexity for cross-border feed additive shipments.
- Organic acid substitution:Formic acid and propionic acid blends displace phosphoglycolipid growth promoters in certain European swine nursery diets under cost-pressure scenarios.
Strategic Opportunities
- Brazilian poultry export compliance:ANVISA's alignment with Codex Alimentarius coccidiostat standards creates regulatory runway for flavophospholipol penetration into integrated broiler operations supplying EU-bound chicken.
- Precision dosing automation:Liquid concentrate formulations integrate with automated feed mill systems at large-scale operations, capturing service revenue pools beyond commodity powder sales.
- Human-grade phospholipid derivatives:Nutraceutical applications for membrane-active phosphoglycolipids in cognitive health supplements attract R&D investment from fermentation specialists.
Industry Challenges
- Streptomyces strain optimization expertise:Industrial microbiology talent scarcity constrains yield improvements in phosphoglycolipid titer rates for fermentation facilities.
- EFSA technical dossier compilation:Efficacy study requirements for coccidiostat authorization demand 12-18 month regulatory timelines with substantial toxicology investment.
- Legacy premix equipment compatibility:Powder formulation flowability specifications must align with existing feed mill pneumatic conveying infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavophospholipol Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $64.66 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granule, Concentrate Application: Animal Feed, Nutraceuticals, Pharmaceuticals, Dietary Supplements End User: Livestock, Poultry, Aquaculture, Companion Animals Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Best Veterinary Solutions, Huvepharma, Jiangsu SEL Biochem, Hainan Zhongxin Chemical, Shandong Shengli Corporation, Fengchen Group, BASF SE, Kemin Industries, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavophospholipol Market Evolving Landscape
Digital process control systems are penetrating fermentation operations, while regulatory data submission protocols harden and buyer procurement models consolidate toward direct manufacturer relationships.
Automated bioreactor monitoring platforms is digitizing flavophospholipol production workflows through real-time dissolved oxygen and pH telemetry. Contract fermentation facilities in Jiangsu and Shandong provinces deploy these systems to reduce batch-to-batch titer variation. The technology is compressing quality assurance labor costs while enabling continuous manufacturing transitions away from batch fermentation paradigms.
REACH chemical registration requirements now mandate extended environmental fate studies for phosphoglycolipid metabolites in soil and aquatic systems. Industrial feed additive manufacturers must submit dossiers addressing persistence, bioaccumulation, and toxicity endpoints for authorization renewal. Poultry-focused coccidiostat suppliers face the steepest compliance burden as ECHA scrutiny intensifies for membrane-active compounds.
Integrated broiler operations now contract directly with fermentation manufacturers, bypassing traditional distribution intermediaries. Large-scale poultry processors in Thailand and Vietnam negotiate volume-based supply agreements with phosphoglycolipol producers, securing price stability and technical support access. This channel consolidation concentrates procurement leverage among the top ten global broiler integrators.
Flavophospholipol Market Segmentation
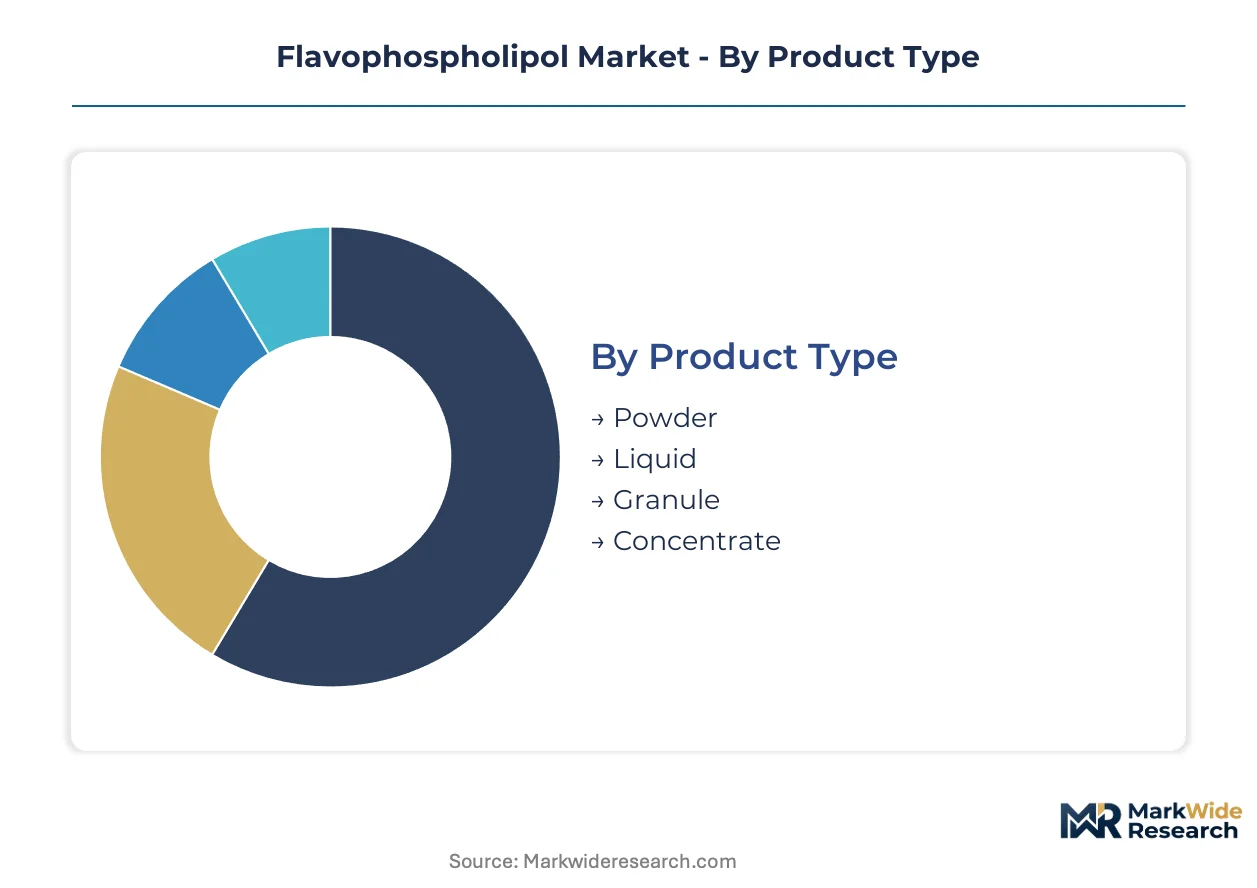
Segmentation in the flavophospholipol market reveals how formulation chemistry, regulatory pathways, and procurement economics intersect. Manufacturers calibrate production mixes across powder, liquid, and concentrate grades to match feed mill infrastructure and veterinary prescribing patterns.
Product Type:
Cost tier differentiation across powder, liquid, granule, and concentrate formats determines margin capture and customer lock-in intensity.
- Powder:Spray-dried formulations with standardized particle size distribution dominate premix blending operations. Broiler integrators in Thailand and Vietnam specify powder grades for pneumatic conveying compatibility in legacy feed mill infrastructure.
- Liquid:Aqueous suspensions enable precision dosing through automated injection systems at large-scale poultry operations. Integrated operations in Brazil's southern states are rotating toward liquid procurement to reduce dust exposure and improve worker safety compliance.
- Granule:Extruded carriers with controlled release properties suit aquaculture feed applications requiring water stability.
- Concentrate:High-potency formulations reduce freight costs for export shipments to distant production markets.
Powder holds installed capacity. Liquid is rotating up the share rankings.
Application:
Application scope spans veterinary coccidiostasis, human nutraceuticals, and pharmaceutical development pipelines with divergent regulatory burdens.
- Animal Feed:Coccidiostat and growth promoter claims at 1-20 ppm inclusion rates anchor commercial volume. EFSA's streamlined technical dossier pathways for feed additive reauthorization are accelerating access for phosphoglycolipid-based poultry and swine applications.
- Nutraceuticals:Membrane-active phospholipid derivatives for cognitive health supplements attract fermentation specialist R&D investment. China's NMPA dietary supplement registration requirements create compliance complexity for cross-border nutraceutical shipments.
- Pharmaceuticals:Investigational drug applications for antibacterial membrane disruptors face extended toxicology study timelines.
- Dietary Supplements:Human-grade phospholipid extraction requires GMP certification upgrades beyond feed-grade production standards.
Animal Feed commands production allocation. Nutraceuticals is climbing the fastest as margin pools deepen.
End User:
Customer type segmentation tracks species-specific pharmacokinetics, residue limit regimes, and veterinary prescribing authority structures.
- Livestock:Swine and cattle operations deploy flavophospholipol for enteric pathogen suppression in antibiotic-free production systems. China's Ministry of Agriculture and Rural Affairs residue limit enforcement under GB 31650-2019 shapes domestic livestock application rates.
- Poultry:Broiler and layer operations represent the dominant commercial demand concentration. EFSA coccidiostat authorization protocols specifically target poultry pathogen control efficacy endpoints.
- Aquaculture:Shrimp and finfish applications require specialized formulation stability for aqueous feed environments.
- Companion Animals:Pet food additive applications face restrictive veterinary prescription frameworks in European markets.
Poultry dominates capacity deployment. Aquaculture is gaining share fastest as marine protein demand intensifies.
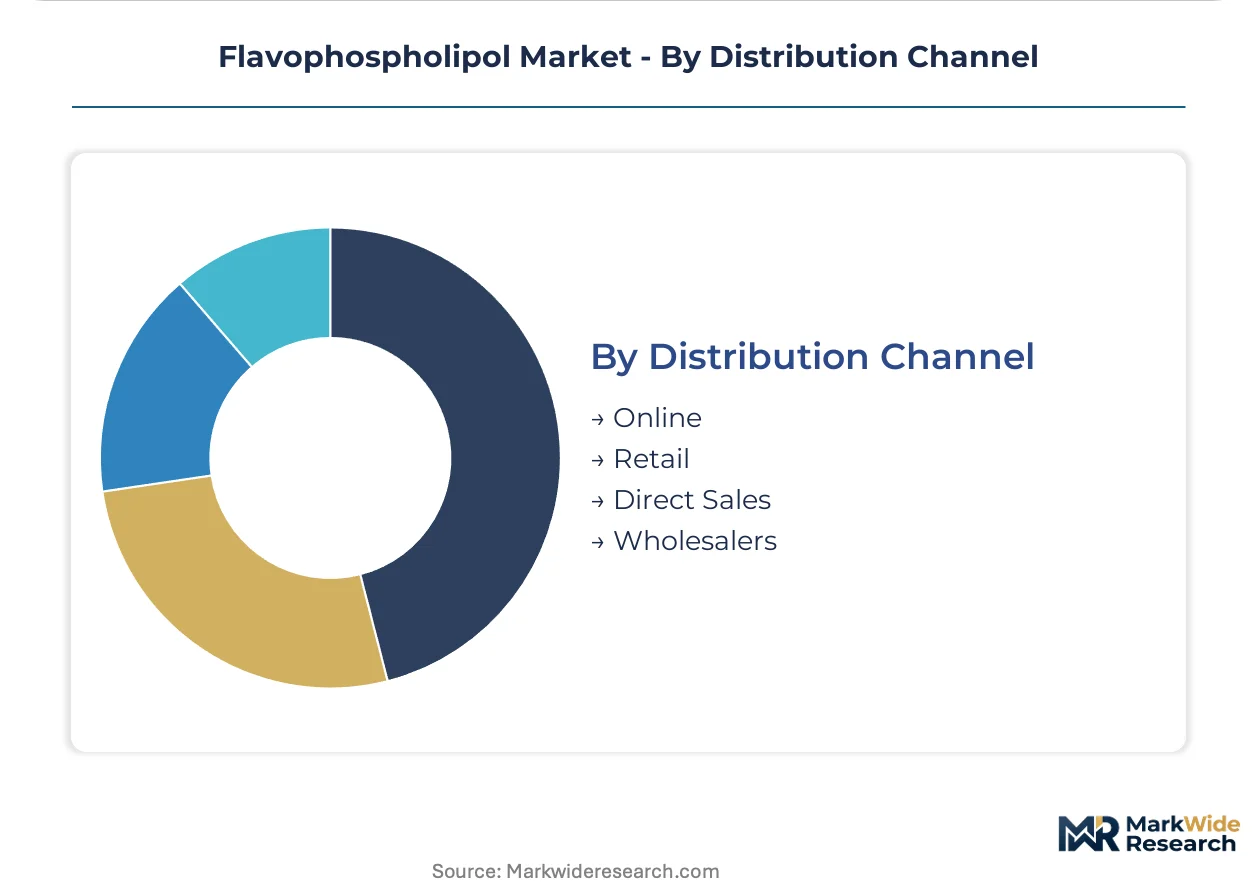
Distribution Channel:
Channel structure reflects procurement consolidation trends and technical service requirements for fermentation-derived additives.
- Direct Sales:Volume-based supply agreements between manufacturers and integrated broiler operations eliminate distributor margins. Thailand's Charoen Pokphand and Brazil's JBS negotiate direct contracts with Jiangsu SEL Biochem and Huvepharma for price stability.
- Online:B2B procurement platforms serve small and mid-size feed compounders with standardized powder grades. Alibaba's agricultural inputs marketplace connects Chinese fermentation facilities with Southeast Asian buyers.
- Retail:Veterinary clinic and farm supply store channels serve companion animal and hobby farmer segments.
- Wholesalers:Regional distributors maintain inventory positions for just-in-time delivery to independent feed mills.
Direct Sales holds procurement leverage. Online is expanding most quickly as digital platforms penetrate mid-tier customer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across production geographies. Chinese integrators deploy flavophospholipol primarily as growth promoters at 10-20 ppm, while European poultry operations restrict usage to coccidiostat-only frameworks at 5-10 ppm under antibiotic-free mandates.
China
Domestic broiler and swine operations consume the majority of fermentation output. The Ministry of Agriculture and Rural Affairs enforces residue limits under GB 31650-2019, tightening enforcement since 2023. Jiangsu and Shandong provinces host expanded Streptomyces fermentation capacity with automated bioreactor installations.
Brazil
Integrated poultry exporters drive demand for EU-compliant coccidiostat applications. ANVISA alignment with Codex Alimentarius standards streamlines regulatory access for phosphoglycolipid feed additives. Southern states including Paraná and Rio Grande do Sul concentrate automated dosing system adoption at large-scale broiler facilities.
United States
Import tolerance frameworks govern phospholipol-based product entry into livestock supply chains. The FDA Center for Veterinary Medicine oversees new animal drug applications and residue monitoring programs. Midwestern feed compounding clusters in Iowa and Illinois maintain powder formulation demand for legacy premix infrastructure.
Germany
EFSA feed additive reauthorization protocols shape coccidiostat market access for poultry operations. REACH chemical registration mandates extended environmental fate studies for phosphoglycolipid metabolites. Bavaria and Lower Saxony concentrate integrated pork production deploying membrane-active additives in antibiotic-free nursery systems.
Thailand
Charoen Pokphand and other integrated poultry processors negotiate direct supply agreements with fermentation manufacturers. The country's national agricultural regulator enforces feed additive safety standards aligned with export market requirements. Eastern seaboard industrial zones concentrate automated feed mill infrastructure compatible with liquid concentrate dosing systems.
Flavophospholipol Market Competitive Landscape
Capability concentration sits with fermentation specialists mastering Streptomyces strain optimization; scale advantage sits with integrated veterinary pharmaceutical platforms controlling distribution networks. The market structures around three tiers: captive raw material producers, diversified chemical conglomerates, and contract fermentation facilities. Two dominant competitive moves define positioning: backward integration into phospholipid precursor supply and direct contracting with integrated poultry operations bypassing distribution intermediaries.
Within the fermentation specialist tier, Jiangsu SEL Biochem and Huvepharma exemplify contrasting geographic anchoring strategies. BASF SE occupies a position bridging synthetic chemistry expertise with animal nutrition applications. Chinese producers including Shandong Shengli Corporation and Hainan Zhongxin Chemical represent the contract manufacturing concentration in coastal industrial zones. Kemin Industries and Cargill sit within diversified agricultural input portfolios where phosphoglycolipid additives complement broader feed additive ranges. Best Veterinary Solutions and Fengchen Group exemplify regional distribution-focused positioning.
| Leading Market Players |
|---|
| Best Veterinary Solutions |
| Huvepharma |
| Jiangsu SEL Biochem |
| Hainan Zhongxin Chemical |
| Shandong Shengli Corporation |
| Fengchen Group |
| BASF SE |
| Kemin Industries |
| Cargill |
| Others |
Value Network & Pricing Analysis
Overcapacity in Jiangsu and Shandong fermentation corridors is compressing supplier pricing power while forcing integrated poultry processors toward volume-based contract structures that lock in cost stability. Chinese producers with captive phospholipid precursor supply command margin buffers unavailable to toll fermentation operators dependent on spot soybean oil feedstock markets.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between integrated broiler operations and fermentation manufacturers, displacing spot powder purchases as buyers seek price stability. Price differentiation hinges on certification grade—EFSA-authorized coccidiostat tiers command premiums over feed-grade growth promoter formulations—and volume scale, with direct manufacturer contracts eliminating distributor markups. Cost compression in standard powder grades is intensifying because toll fermentation operators lack backward integration into phospholipid precursor supply. Small and mid-size feed compounders exhibit highest price sensitivity, while Charoen Pokphand and JBS negotiate least sensitive positions through dedicated supply agreements.
Supply Chain Analysis
Extended payment terms from integrated poultry processors are squeezing working capital at contract fermentation facilities, accelerating consolidation toward producers with balance-sheet depth. Supply concentrates in China, Brazil, and Germany, with Jiangsu province anchoring Streptomyces fermentation capacity and Paraná state hosting automated dosing system adoption. Raw material dependencies rest on soybean oil phospholipid precursors, specialized bacterial strain inventories, and automated bioreactor telemetry systems. Single-source vulnerability in Streptomyces strain optimization expertise constrains yield improvements. Distribution runs through direct manufacturer relationships with integrated broiler operations, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial microbiology talent scarcity is tightening around Streptomyces strain optimization expertise, creating asymmetric returns for producers that internalize yield improvement capabilities and phospholipid precursor supply.
For Market Incumbents: Insulate margin position through captive phospholipid precursor supply and EFSA technical dossier pre-positioning ahead of reauthorization windows. Organic acid substitution in European swine diets threatens growth promoter claim viability; counter by accelerating coccidiostat-only regulatory positioning. Backward integration into soybean oil processing secures cost buffers against Chicago Board of Trade volatility. For New Entrants and Emerging Players: Pursue Brazilian poultry export compliance as the most penetrable geographic entry point, where ANVISA alignment with Codex Alimentarius standards reduces regulatory friction. Aquaculture formulation stability represents underserved white-space, with shrimp and finfish applications requiring specialized water-stable granule formats. Go-to-market through B2B procurement platforms serving Southeast Asian mid-tier feed compounders bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation specialists with integrated phospholipid precursor supply and direct contracting relationships with top-ten global broiler integrators. Long-term viability over the five-to-ten year horizon rests on regulatory positioning durability as antibiotic-free mandates expand. Target acquisition archetype: Chinese producers with automated bioreactor installations and EFSA dossier progress. Signal to watch: EFSA coccidiostat reauthorization timeline acceleration as inflection indicator for European market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phospholipid Precursor Supply | Captive soybean oil processing insulates margin structures against commodity futures volatility. |
| EFSA Technical Dossier Pre-Positioning | Early toxicology investment accelerates coccidiostat reauthorization access ahead of competitors. |
| Automated Bioreactor Installation | Real-time dissolved oxygen telemetry reduces batch-to-batch titer variation and labor costs. |
| Direct Manufacturer Contracting | Volume-based agreements with Charoen Pokphand and JBS eliminate distributor margins and secure price stability. |
| Aquaculture Formulation Development | Water-stable granule formats for shrimp and finfish applications access faster-growing marine protein demand. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation plant managers, poultry procurement leads at integrated operations, regulatory affairs specialists navigating EFSA protocols, and feed mill technical directors, then refined through secondary validation. Bottom-up capacity assessments triangulated with top-down consumption estimates. Secondary sources included customs and trade data on phosphoglycolipid shipments, EFSA feed additive authorization databases, SEC filings from diversified agricultural input portfolios, and Chinese Ministry of Agriculture production licensing records.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation dimensions spanning formulation chemistry (powder, liquid, concentrate), application (animal feed, nutraceutical, pharmaceutical), and end-user species (poultry, livestock, aquaculture). CAGRs derived from production capacity expansion trajectories, regulatory authorization timelines, and substitution elasticity estimates for organic acid alternatives. Industry-specific inputs incorporated Streptomyces strain optimization yield curves and EFSA environmental fate study completion rates.
Macroeconomic conditions sit as an overlay; deviation in soybean oil futures, exchange rate volatility affecting Chinese export competitiveness, or accelerated antibiotic-free mandate adoption would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory divergence persistence and fermentation technology diffusion rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Leavening Acids Market
Food Additives and Ingredients
Food Grade Calcium Lactate Market
Food Additives and Ingredients
Japan Food Emulsifiers Market
Food Additives and Ingredients
Europe Food Enzymes Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Nanoencapsulated Food Additives Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
Canada Food Enzymes Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
Global Crystalline Maltitol Market
Food Additives and Ingredients
Food Grade Calcium Hydroxide Market
Food Additives and Ingredients
Germany Food Additives Market
Food Additives and Ingredients
Canada Food Preservatives Market
Food Additives and Ingredients
Food Emulsifiers Market
Food Additives and Ingredients
Food Grade Sodium Citrate Market
Food Additives and Ingredients
Potassium Lactate Market