
 Natural Food Preservatives Market | 2026-2036
Natural Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Food Preservatives Market Analysis
Plant-based bakery goods is expanding as a primary end-use vertical for natural preservatives, displacing conventional applications in shelf-stable sauces. Kemin Industries leverages vertically integrated botanical extraction to sustain supply security for rosemary-derived antioxidants. Corbion N.V. anchors its position through fermented ingredient technology leadership, while Kerry Group plc competes on clean-label formulation services that integrate preservation with flavor masking.
Natural food preservatives comprise antimicrobial and antioxidant compounds derived from botanical, microbial, or mineral sources, typically functioning at concentrations between 0.01% and 1.0% by weight to inhibit spoilage organisms or oxidative rancidity without synthetic chemical labeling. Essential oils supply the highest-margin preservation platform due to concentrated bioactive potency and premium positioning in organic product lines, whereas fermented ingredients represent the fastest-growing category as bioprocess engineering reduces unit costs. Herbal extracts occupy mature demand territory in meat products, where regulatory familiarity supports steady procurement volumes from established processors.
EU EFSA standards, FDA GRAS determinations, and USDA organic certification collectively govern ingredient approval pathways and label claim permissibility, with EFSA novel food assessments creating particular bottlenecks for emerging botanical extracts. The EU Green Deal chemical sustainability targets are accelerating synthetic-to-natural substitution mandates that reshape supplier qualification requirements. Stakeholders must monitor regulatory divergence between jurisdictions where preservative maximum permitted levels and clean-label definitions lack harmonization.
Market Dynamics
Clean-label reformulation mandates from EU Green Deal compliance are forcing processors to abandon synthetic benzoates and sorbates, compressing substitution timelines from five-year cycles to eighteen-month procurement windows.
Growth Catalysts
- EU Green Deal chemical sustainability targets:REACH restrictions on synthetic additives accelerate natural preservative qualification across German, French, and Italian processing facilities.
- Plant-based bakery goods:Clean-label bread and pastry applications displace conventional shelf-stable sauces as the primary demand vertical for rosemary-derived antioxidants.
- Fermented ingredient bioprocess engineering:Unit cost reductions in microbial cultivation expand addressable market share for mid-tier processors previously priced out of natural solutions.
Market Restraints
- Botanical raw material volatility:Mediterranean rosemary harvest fluctuations concentrate supply risk with Spanish and Moroccan extractors.
- EFSA novel food assessment bottlenecks:Emerging botanical extracts face eighteen-to-thirty-six month approval timelines that freeze commercialization pipelines.
- Performance gap in high-moisture applications:Natural antimicrobials fail to match synthetic efficacy in ready-to-eat deli meats above sixty-five percent water activity.
Strategic Opportunities
- India FSSAI clean-label adoption:Urban packaged food processors in Mumbai and Bangalore represent underpenetrated demand for fermented preservation cultures.
- Precision fermentation convergence with enzymology:Engineered microbial strains producing targeted antimicrobial peptides open pharmaceutical-grade food safety applications.
- Direct-to-manufacturer digital procurement platforms:Bypassing traditional ingredient distributors reduces qualification friction for small-batch natural preservative suppliers.
Industry Challenges
- Cross-jurisdictional label claim harmonization:Divergent clean-label definitions between FDA GRAS determinations and EU EFSA standards fragment formulation strategies.
- Integration complexity with legacy thermal processing:Natural preservatives requiring modified heat treatment protocols demand capital retooling at established canning facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Food Preservatives Market |
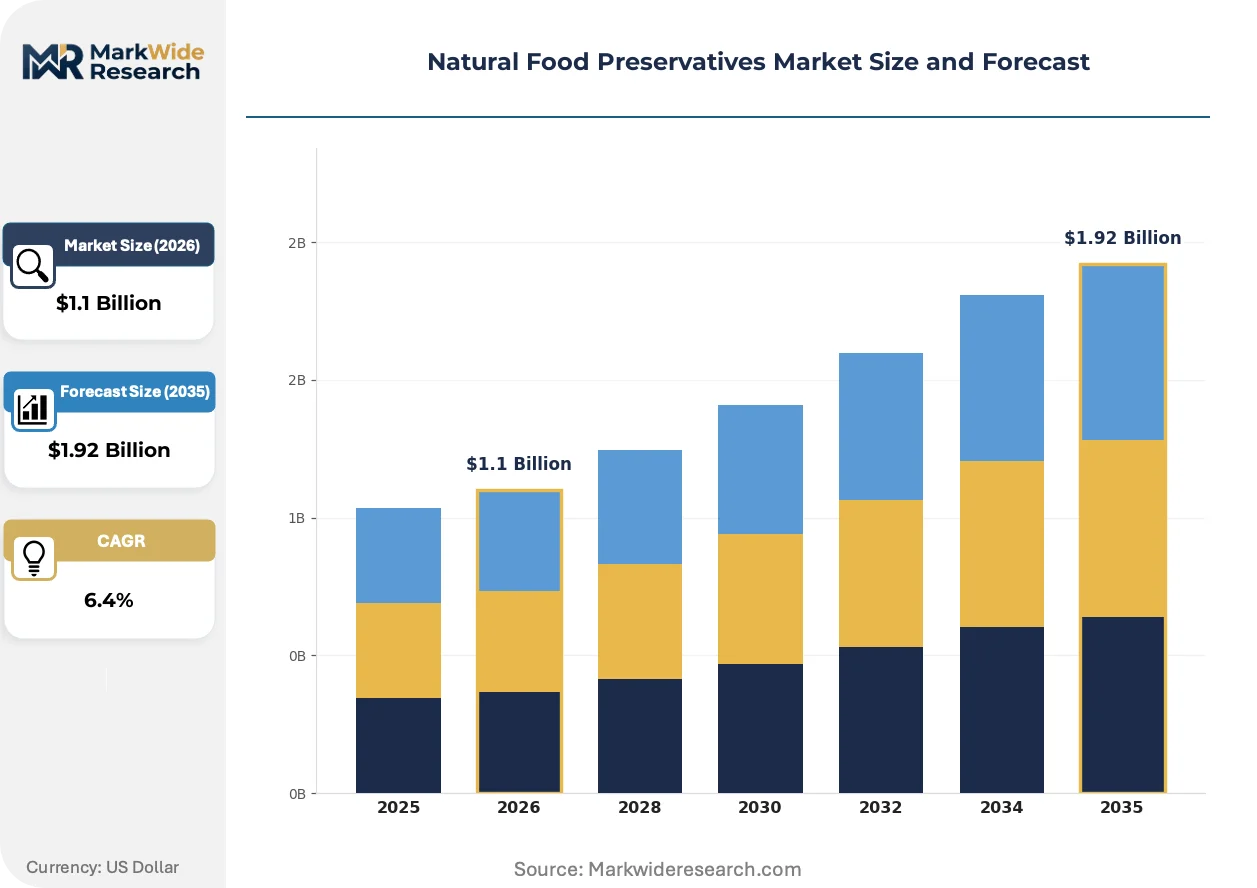
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $1.92 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Herbal Extracts, Fermented Ingredients, Natural Antioxidants Application: Dairy Products, Sauces, Meat Products, Bakery Goods End User: Food Manufacturers, Restaurants, Retailers, Home Cooks Form: Liquids, Powders, Capsules, Granules |
| Companies Covered | Kemin Industries, Inc., Corbion N.V., Cargill, Incorporated, Naturex S.A., Archer Daniels Midland Company, Kerry Group plc, Tate & Lyle PLC, Handary S.A., Koninklijke DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Food Preservatives Market Emerging Trajectories
Bioprocess engineering and extraction technology advances are compressing cost curves for natural preservation systems while regulatory divergence between jurisdictions fragments standardization pathways.
Encapsulation technology using lipid-based delivery systems is integrating essential oil actives into water-soluble matrices. Bakery manufacturers in Germany and the Netherlands adopt these systems at accelerated procurement cycles. This integration enables sub-zero storage distribution without flavor degradation, collapsing previous cold-chain requirements that excluded natural alternatives from frozen dough applications.
REACH authorization sunset clauses for synthetic biocides tighten substitution deadlines across European compound feed and pet food processing. Industrial consequence forces reformulation commitments before 2027 authorization reviews. Meat alternative processors in Denmark and Sweden face compressed timelines, accelerating partnerships with fermented ingredient suppliers to secure compliant preservation pathways.
Certification-driven procurement now prioritizes USDA organic and EU organic label alignment over unit cost minimization. Mid-tier co-manufacturers serving private-label retailers replace synthetic preservative inventories to meet retailer sustainability scorecards. This behavioral shift concentrates demand in California and Pacific Northwest processing clusters where organic certification density supports supplier qualification efficiency.
Natural Food Preservatives Market Segmentation
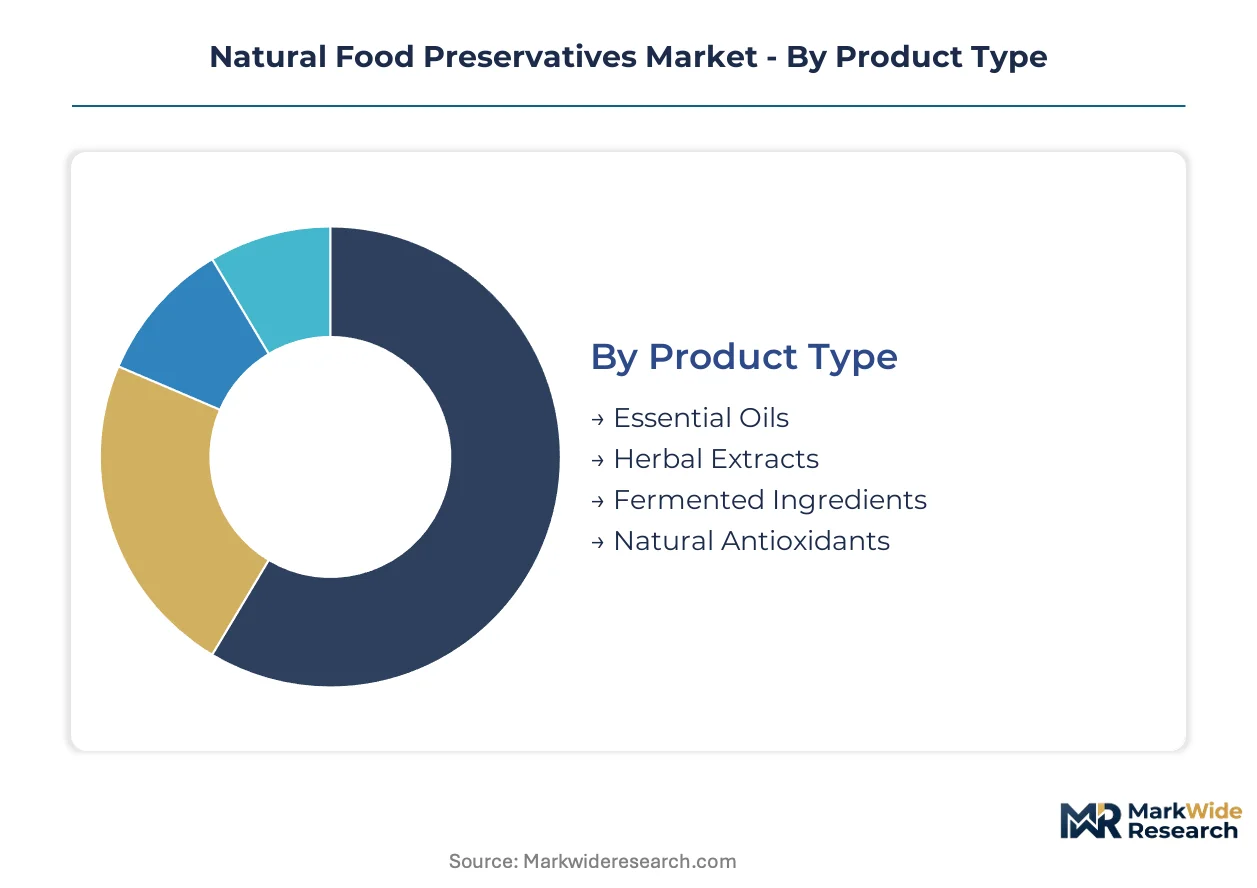
Natural food preservatives exhibit distinct performance profiles across product chemistry, application requirements, and delivery formats. Procurement patterns diverge sharply between commodity-scale dairy processors and specialty bakery formulators seeking clean-label certification.
Product Type:
Technology differentiation separates concentrated bioactives from fermentation-derived alternatives on cost curves and regulatory pathways.
- Essential Oils:Terpene-rich concentrates from rosemary, oregano, and thyme deliver antimicrobial potency at 0.05-0.3% inclusion rates. German organic meat processors absorb premium pricing to secure EU organic label alignment.
- Herbal Extracts:Standardized polyphenol fractions from green tea and grape seed stabilize lipid oxidation in refrigerated sausages. Italian charcuterie specialists drive steady procurement volumes through established EFSA safety dossiers.
- Fermented Ingredients:Bacteriocin-producing cultures and organic acid blends from controlled bioprocessing.
- Natural Antioxidants:Tocopherol and ascorbic acid derivatives from vegetable oil refining byproducts.
Essential oils lead on scale; fermented ingredients lead on momentum.
Application:
Moisture content and thermal processing intensity dictate preservative selection and dosage economics.
- Bakery Goods:Encapsulated rosemary extracts in par-baked frozen doughs leverage lipid-delivery systems to survive sub-zero distribution. Dutch and German manufacturers compress substitution timelines under retailer sustainability mandates.
- Meat Products:Fermented celery powder and vinegar-derived clean-label curing alternatives replace synthetic nitrites in deli applications. Danish processors face compressed reformulation deadlines ahead of REACH biocide reviews.
- Dairy Products:Nisin and natamycin cultures for cheese surface protection and yogurt shelf-life extension.
- Sauces:Acetic acid blends and cultured dextrose for ambient-stable emulsions and dressings.
Bakery goods command the steepest expansion trajectory; meat products retain the largest absolute volume.
End User:
Scale and certification requirements fragment procurement behavior across the value chain.
- Food Manufacturers:Industrial processors with reformulation teams and regulatory affairs capacity.
- Restaurants:Clean-label positioning for chain menu transparency initiatives.
- Retailers:Private-label sustainability scorecards driving co-manufacturer specification changes.
- Home Cooks:Niche organic and natural product enthusiasts.
Food manufacturers dominate absolute demand; retailers are gaining procurement influence fastest.
Form:
Physical state determines integration compatibility with existing production infrastructure.
- Powders:Spray-dried extracts and microencapsulated actives for dry-mix applications. California organic baking clusters favor powder formats for blending efficiency with flour and leavening systems.
- Liquids:Oil-soluble and water-dispersible concentrates for liquid processing lines. French sauce manufacturers prefer liquid formats for emulsion incorporation without hydration steps.
- Granules:Agglomerated powders for controlled dissolution in high-shear mixing.
- Capsules:Pre-measured unit doses for small-batch and artisanal applications.
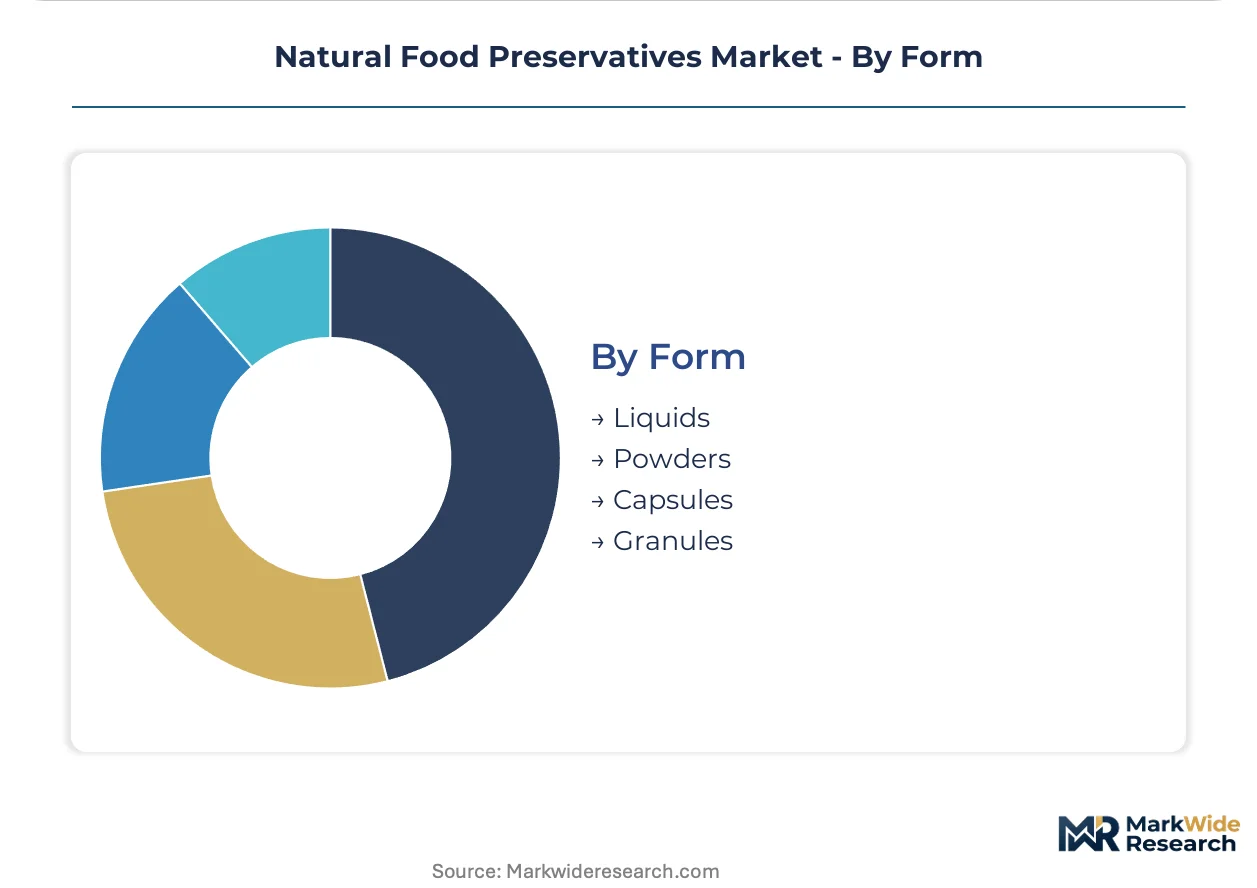
Powders lead on manufacturing throughput; liquids lead on formulation flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting natural preservative production toward jurisdictions where REACH compliance costs and EU Green Deal timelines compress faster than competitors can adapt. German processors absorb premium ingredient pricing to secure supply security ahead of authorization deadlines.
Germany
Reformulation investments by meat and bakery processors outpace European peers as REACH biocide reviews approach. The EU Green Deal chemical sustainability targets force substitution of synthetic benzoates by 2027. The Baden-Württemberg organic meat processing cluster accelerates partnerships with fermented ingredient suppliers.
United States
USDA organic certification density in California and the Pacific Northwest concentrates demand for rosemary-derived antioxidants. FDA GRAS determinations for novel botanical extracts lag EFSA timelines, creating regulatory uncertainty for emerging suppliers. Midwest dairy processors in Wisconsin and Minnesota expand nisin and natamycin procurement for cheese surface protection.
India
Urban packaged food processors in Mumbai and Bangalore represent underpenetrated demand for fermented preservation cultures. FSSAI clean-label adoption lags Western regulatory stringency, opening qualification windows for mid-tier suppliers. The Maharashtra and Gujarat bakery manufacturing corridors expand encapsulated extract trials for par-baked frozen dough applications.
Denmark
Meat alternative processors face compressed reformulation timelines ahead of REACH authorization reviews. EFSA novel food assessment bottlenecks freeze commercialization pipelines for emerging botanical actives. The Copenhagen-Skåne cross-border food tech cluster accelerates precision fermentation partnerships for antimicrobial peptide development.
Netherlands
Dutch bakery manufacturers compress substitution cycles under retailer sustainability mandates. Encapsulation technology adoption for lipid-delivery systems concentrates in Amsterdam-Rotterdam processing corridors. The Wageningen food innovation ecosystem anchors bioprocess engineering collaborations that reduce unit costs for microbial cultivation.
Natural Food Preservatives Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with ingredient technology leaders commanding premium positioning in bakery and meat applications while toll processors capture volume in commodity dairy. Market structure tilts toward consolidation among fermentation-derived specialists, whereas botanical extract supply fragments across Mediterranean and North African harvest zones. Three archetypes dominate: vertically integrated agricultural processors controlling raw material sourcing, biotechnology platforms leveraging precision fermentation, and formulation service providers integrating preservation with sensory masking. Capacity expansion and strategic partnerships represent the dominant competitive moves, with substitution timeline compression favoring suppliers with existing EFSA safety dossiers.
Within the biotechnology platform tier, Corbion N.V. and Koninklijke DSM N.V. exemplify fermentation-derived antimicrobial leadership, while Kerry Group plc occupies a position bridging formulation services with clean-label integration. Kemin Industries anchors the vertically integrated archetype through captive botanical extraction infrastructure. These three entities represent distinct strategic postures: microbial cultivation scale, end-to-end formulation capability, and agricultural supply chain control.
| Leading Market Players |
|---|
| Kemin Industries, Inc. |
| Corbion N.V. |
| Cargill, Incorporated |
| Naturex S.A. |
| Archer Daniels Midland Company |
| Kerry Group plc |
| Tate & Lyle PLC |
| Handary S.A. |
| Koninklijke DSM N.V. |
| Others |
Supply Flow & Price Mechanics
Captive botanical extraction infrastructure in Spanish and Moroccan rosemary cultivation zones anchors supply security for antioxidant suppliers while compressing procurement premiums for German meat processors facing REACH substitution deadlines. This backward integration into Mediterranean agricultural assets simultaneously secures raw material throughput and transfers margin capture upstream from toll processors to integrated extractors.
Pricing Analysis
Distributor margins for essential oil concentrates absorb substantial markup before reaching mid-tier bakery manufacturers, whereas direct-to-manufacturer digital procurement platforms collapse these layers for fermented ingredient cultures. Three-tier pricing structure across premium organic-certified, standard food-grade, and economy technical-grade levels stratifies according to EU organic label alignment and EFSA safety dossier completeness. Pricing pressure stems from bioprocess engineering advances in microbial cultivation that expand supply availability for nisin and natamycin alternatives. Mid-tier co-manufacturers serving private-label retailers exhibit highest price sensitivity as sustainability scorecard compliance forces inventory replacement without pass-through pricing power.
Supply Chain Analysis
EU Green Deal domestic-content mandates for chemical sustainability compliance are reshaping sourcing patterns toward European Union-based fermentation capacity and away from third-country botanical extract dependence. Supply concentration clusters in Spain and Morocco for rosemary-derived antioxidants, India for acetic acid precursors, and the Netherlands for precision-cultured bacteriocins. Raw material dependencies include Mediterranean herbal biomass, corn-derived dextrose fermentation feedstock, and vegetable oil refining byproducts for tocopherol extraction. Single-source vulnerability concentrates in Spanish rosemary harvest zones exposed to climate volatility. Distribution runs through specialty ingredient distributors with regulatory affairs capabilities serving reformulation-intensive processors in Germany and Denmark.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage economics favor locating fermentation capacity in India to exploit FSSAI qualification windows and lower bioprocess engineering costs against European regulatory compliance premiums.
For Market Incumbents: Cement supply security through captive rosemary cultivation partnerships in Morocco and Spain before REACH authorization reviews compress substitution timelines to eighteen-month procurement windows. Expand Wageningen-area precision fermentation collaborations to lock in antimicrobial peptide development pipelines against emerging biotechnology platforms. Vertical integration into Mediterranean agricultural assets represents the critical defensive lever against botanical raw material volatility. For New Entrants and Emerging Players: Direct-to-manufacturer digital procurement platforms bypass established distributor relationships to reach mid-tier bakery processors in Maharashtra and Gujarat with encapsulated extract trials. Target underpenetrated fermented preservation culture demand among Mumbai and Bangalore urban packaged food processors where FSSAI clean-label adoption lags Western stringency. White-space opportunity concentrates in par-baked frozen dough applications requiring lipid-delivery system compatibility. For Investors and Strategic Acquirers: Roll-up economics work for fermentation-derived antimicrobial specialists because EFSA novel food assessment bottlenecks create durable competitive moats around existing safety dossiers. Long-term viability hinges on precision fermentation convergence with enzymology opening pharmaceutical-grade applications. Watch for REACH biocide authorization sunset clauses forcing meat alternative processor partnerships as the inflection signal for accelerated category consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mediterranean Cultivation | Captive rosemary supply secures German processor relationships ahead of REACH deadlines. |
| Precision Fermentation Partnership | Wageningen ecosystem collaborations reduce unit costs for antimicrobial peptide manufacturing. |
| Digital Procurement Platform Launch | Direct channels collapse distributor margins for small-batch natural preservative suppliers. |
| EFSA Safety Dossier Investment | Novel food assessment completion unlocks eighteen-to-thirty-six month commercialization pipelines. |
| India FSSAI Qualification Expansion | Mumbai and Bangalore processor penetration captures clean-label adoption lag windows. |
Methodological Framework
Bottom-up bakery and meat processor modeling reconciled against top-down botanical extraction and fermentation capacity tracking forms the analytical core. Primary interviews with regulatory affairs directors at German and Danish meat processors, procurement leads at Dutch bakery manufacturers, and technical R&D heads at Mediterranean extractors combined with secondary validation from EFSA novel food registers, REACH authorization databases, FSSAI clean-label guidance documents, and EU Green Deal chemical sustainability target disclosures. Triangulation across supply-side capacity announcements and demand-side reformulation timelines ensures cross-verified volume and value estimates.
Input-output matrices map preservative inclusion rates by application moisture content and thermal processing intensity against segmented production volumes across the projection horizon. Segmentation dimensions modeled include product chemistry platform, application moisture regime, end-user scale and certification requirements, and physical delivery format. CAGRs derive from processor substitution timeline compression analysis and bioprocess engineering cost curve trajectories. Industry-specific forecast inputs incorporate REACH authorization sunset clause scheduling and retailer sustainability scorecard adoption curves.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation antimicrobial peptides would alter the outlook if pharmaceutical-grade food safety applications accelerate ahead of projected commercialization timelines. Forecasts reflect assumptions regarding EFSA assessment throughput rates, Mediterranean climate stability for rosemary harvests, and FSSAI regulatory stringency convergence with Western standards. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
China Anti-Caking Market
Food Additives and Ingredients
Sucroglycerides Market
Food Additives and Ingredients
Starch-Based Texturizing Agents Market
Food Additives and Ingredients
Gelatin Films Market
Food Additives and Ingredients
Food Grade Phosphates Market
Food Additives and Ingredients
Fruit and Vegetable Processing Enzymes Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
Soft Drink Ingredients Market
Food Additives and Ingredients
United Kingdom Food Colorants Market
Food Additives and Ingredients
Non-PHO Emulsifiers Market
Food Additives and Ingredients
Quillaja Saponaria Ingredient Market
Food Additives and Ingredients
Agar Agar Gum Market
Food Additives and Ingredients
South America Brewing Enzymes Market
Food Additives and Ingredients
North America Dehydrated Onion Market
Food Additives and Ingredients
Potassium Lactate Market
Food Additives and Ingredients
Egg Wash Substitute Market