
 Australia Food Colorants Market | 2026-2036
Australia Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Food Colorants Market Outlook
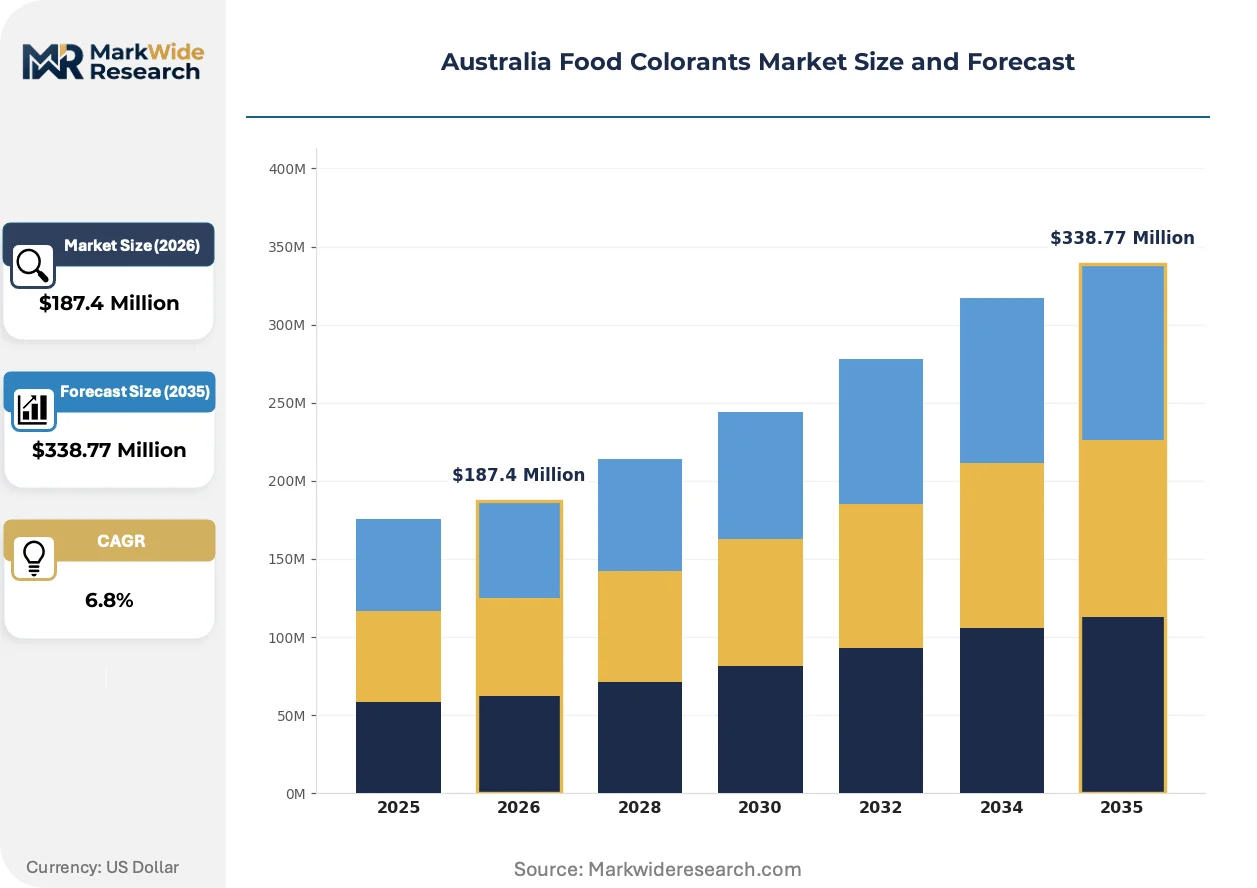
Asset-light contract manufacturing and toll-processing arrangements are reshaping competitive dynamics in Australian food colorants, lowering capital barriers for mid-tier entrants. Chr. Hansen Holding A/S leverages its microbial fermentation expertise to dominate natural colorant supply for dairy applications. Cargill, Inc. anchors its position through backward integration into agricultural feedstocks across Australian grain belts. Sensient Technologies Corporation specializes in customized color systems for confectionery clients seeking precise shade matching.
Food colorants comprise dyes, pigments, and lakes that impart, preserve, or enhance visual appeal in edible products, typically formulated to withstand thermal processing between pH 3.0 and 8.0 while maintaining light stability over shelf life. Their primary commercial purpose centers on consumer acceptance, brand differentiation, and perceived freshness signaling across packaged goods. Natural colors command premium positioning as clean-label formulations displace synthetic alternatives in beverages and dairy products. Powder forms retain logistical advantages for large-scale food manufacturers operating high-throughput blending lines, while liquid formats gain traction in artisanal bakery and restaurant segments requiring volumetric dosing precision.
FSANZ governs permitted colorant species and maximum usage levels through the Australia New Zealand Food Standards Code, directly determining which formulations achieve market access. The ACCC monitors labeling representations under consumer protection frameworks, penalizing misleading natural claims that influence purchaser decisions. Stakeholders must track pending FSANZ proposals on novel extraction technologies and monitor state-level environmental compliance for botanical sourcing operations.
Market Dynamics
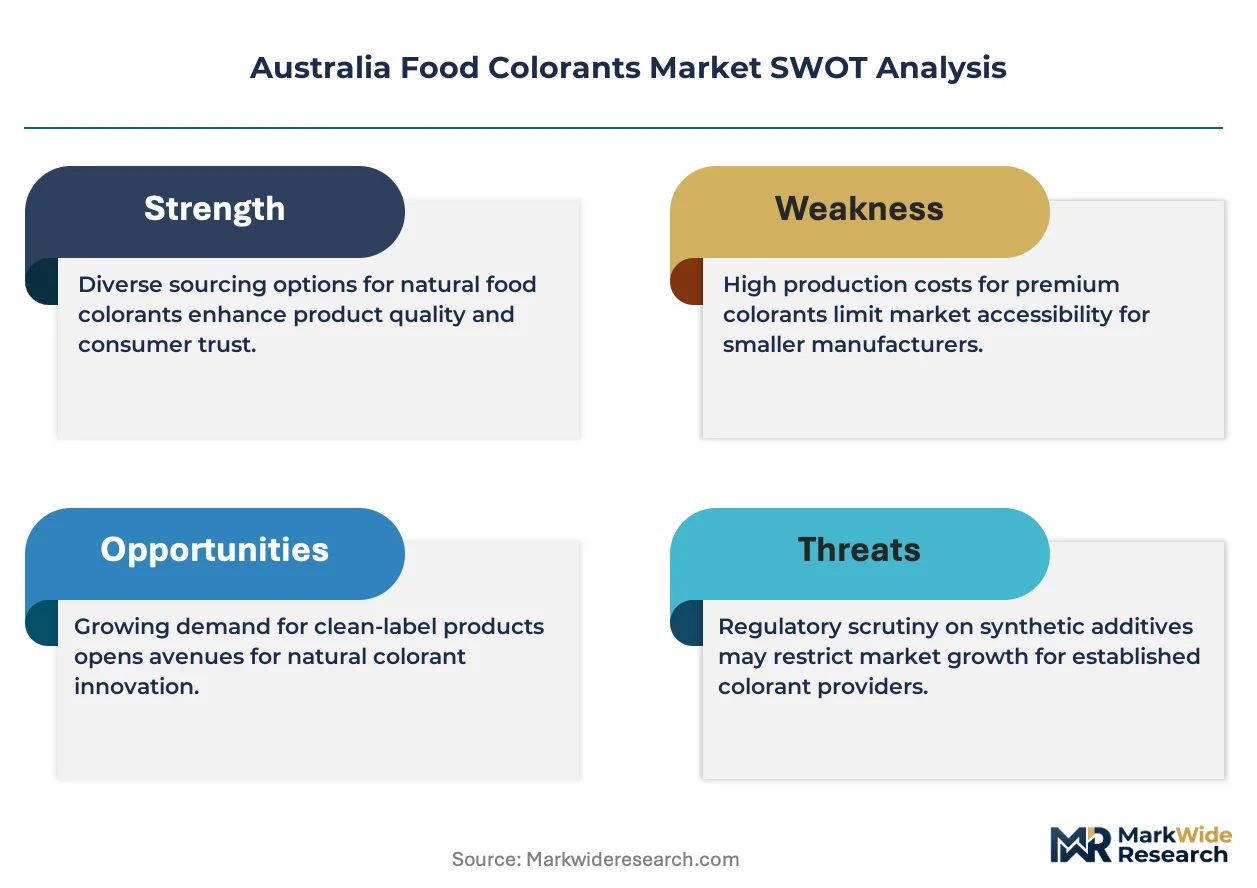
FSANZ's tightening review of additive permissions is compressing the regulatory runway for synthetic colorants while beverage manufacturers accelerate plant-derived reformulations. This structural pivot favors suppliers with captive fermentation and botanical extraction capabilities.
Growth Catalysts
- Clean-label beverage reformulation:Functional drink producers are replacing synthetic dyes with anthocyanin and carotenoid extracts to meet retailer clean-label mandates.
- FSANZ Code amendments:Pending approvals for novel extraction methods are expanding the permitted natural colorant palette for dairy applications.
- Victoria manufacturing concentration:Melbourne's food processing corridor offers co-location advantages for colorant suppliers serving national brands.
Market Restraints
- Botanical input volatility:Beetroot and spirulina supply fluctuates with seasonal conditions across Riverina and Queensland growing regions.
- Synthetic colorant substitution ceiling:Heat-stable bakery applications lack viable natural alternatives at commercial scale.
- Import dependency for specialty lakes:Aluminum lake production concentrates with Asian chemical processors outside Australian tariff preferences.
Strategic Opportunities
- Tasmanian organic botanical sourcing:Premium cold-pressed extraction from pesticide-free growing regions commands price premiums in export markets.
- Cell-cultured pigment fermentation:Precision biotechnology converges with traditional food processing to produce standardized betalain yields independent of agricultural cycles.
- Direct-to-artisan distribution:Specialty baking supply channels bypass conventional ingredient distributors for small-batch colorant sales.
Industry Challenges
- Natural colorant stability expertise:Formulation chemists capable of optimizing light and pH stability across beverage matrices remain scarce in Australian labor markets.
- FSANZ novel food approval timelines:Eighteen-to-twenty-four month assessment windows delay commercialization of emerging fermentation-derived pigments.
- Legacy blending equipment retrofit costs:Powder-to-liquid conversion lines require capital outlay that mid-tier manufacturers defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Food Colorants Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colors, Synthetic Colors, Caramel Colors, Anthocyanins Application: Beverages, Bakery Products, Dairy Products, Confectionery Form: Powder, Liquid, Gel, Granular End User: Food Manufacturers, Beverage Producers, Retail, Restaurants |
| Companies Covered | Sensient Technologies Corporation, Chr. Hansen Holding A/S, Cargill, Inc., Naturex S.A, Döhler GmbH, Kerry Group, Symrise AG, BASF SE, Tate & Lyle PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Food Colorants Market Strategic Shifts
Microbial fermentation and precision extraction technologies are collapsing cost premiums that historically separated natural from synthetic colorants. Regulatory stringency and buyer procurement evolution are synchronizing to accelerate this transition.
Cell-cultured pigment production via microbial fermentation is collapsing the yield gap between agricultural extraction and petrochemical synthesis. Chr. Hansen and specialty biotech suppliers are scaling betalain and carotenoid production in controlled bioreactor environments. Beverage formulators in Sydney and Melbourne are adopting these inputs at contract volumes that match synthetic pricing tiers.
FSANZ's systematic review of Schedule 15 permissions is narrowing the approved synthetic colorant list while expanding natural source documentation requirements. Food Standards Code amendments now mandate quantitative declaration of certain azo dyes in children's products. Confectionery and snack manufacturers are preemptively reformulating to avoid labeling liabilities.
Buyer consolidation among national retail chains is compressing supplier qualification cycles and unbundling technical service from ingredient supply contracts. Coles and Woolworths procurement teams now mandate stability documentation and shelf-life modeling as pre-qualification gates. This pattern concentrates contract awards with colorant houses offering integrated application laboratories.
Australia Food Colorants Market Segmentation
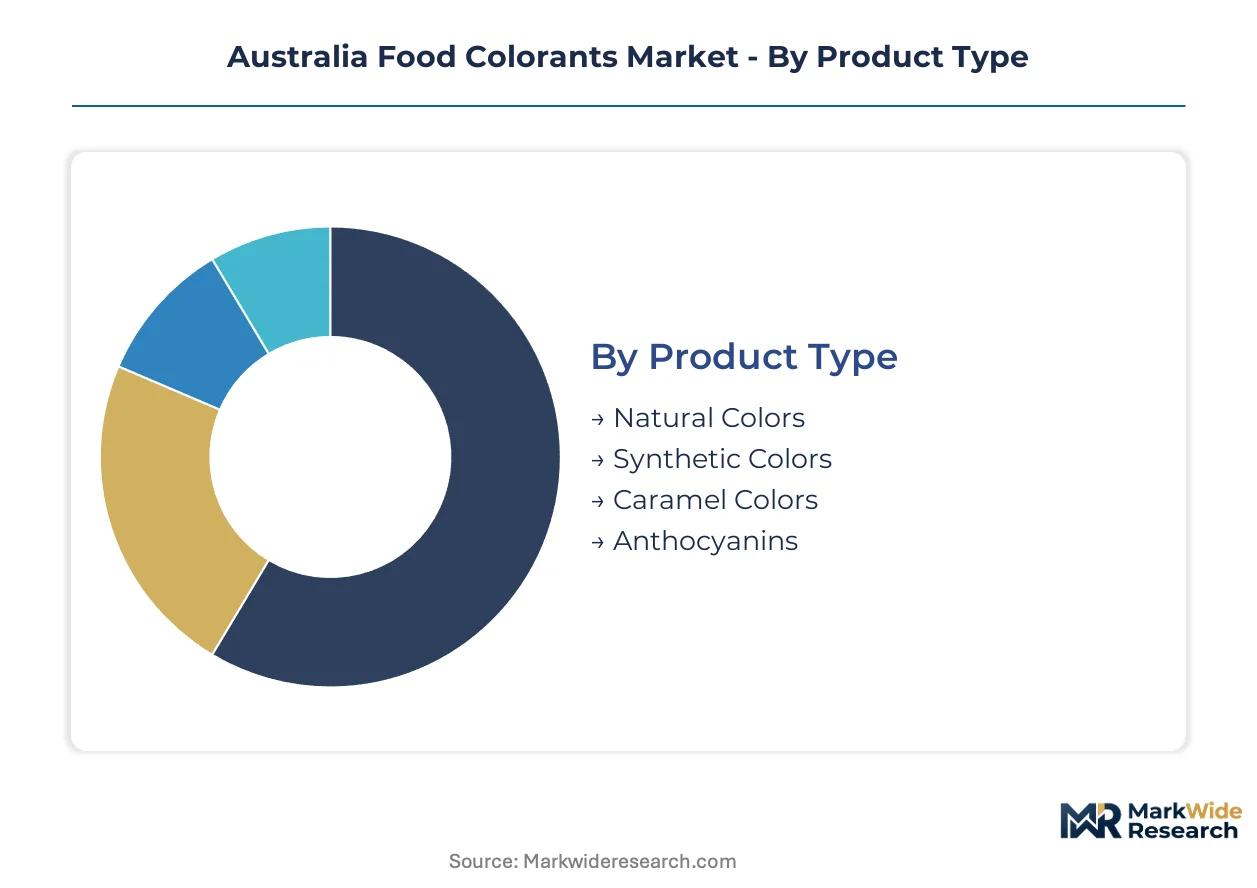
Colorant selection in Australian food manufacturing tracks directly to processing constraints, label positioning, and FSANZ compliance requirements. Each segmentation dimension reveals distinct procurement patterns and supplier qualification criteria that determine commercial outcomes.
Product Type:
Cost tier positioning separates commodity synthetics from premium natural extracts and specialized fermentation-derived pigments.
- Natural Colors:Anthocyanin, carotenoid, and betalain extracts from botanical sources dominate clean-label beverage and dairy reformulations. Victoria-based manufacturers source heavily from Tasmanian organic growing regions to meet export certification requirements.
- Synthetic Colors:Petroleum-derived azo dyes and triphenylmethane compounds retain cost advantages in heat-stable bakery applications. FSANZ's tightening Schedule 15 review is compressing permissible species and accelerating substitution timelines.
- Caramel Colors:Heat-treated carbohydrates classified by color intensity and negative charge characteristics serve cola and sauce applications across New South Wales processing corridors.
- Anthocyanins:Grape skin and blackcurrant extracts deliver pH-dependent color shifts prized in functional drink positioning.
Natural Colors holds installed capacity. Anthocyanins is rotating up the share rankings.
Application:
End-use thermal processing requirements and shelf-life specifications dictate colorant formulation choices and supplier technical service intensity.
- Beverages:Acid-stable anthocyanins and light-fast carotenoids predominate in functional drink and juice applications. Melbourne formulators prioritize cold-pressed extracts to avoid heat degradation during pasteurization.
- Bakery Products:Heat-stable caramel colors and encapsulated natural pigments address Maillard reaction temperatures exceeding 180°C. Queensland manufacturers report persistent natural alternative gaps for red velvet and chocolate shade matching.
- Dairy Products:Fat-compatible carotenoid emulsions and microbial-derived riboflavin serve yogurt and cheese applications. FSANZ's expanded natural colorant permissions for dairy are unlocking new formulation palettes.
- Confectionery:Surface-deposited lakes and panned coating colors demand precise particle size distribution for gloss uniformity.
Beverages commands the deepest supplier technical engagement. Dairy Products is climbing the fastest as natural permissions expand.
Form:
Volume throughput and dosing precision requirements separate industrial-scale powder handling from artisanal liquid measurement protocols.
- Powder:Spray-dried and agglomerated formats optimize freight economics and storage stability for high-volume blending operations. National manufacturers along Victoria's Hume Highway corridor specify powder for automated dosing systems.
- Liquid:Pre-dispersed colloidal suspensions eliminate dust handling and enable volumetric pump dosing. Sydney artisanal bakeries and restaurant chains specify liquid for small-batch flexibility.
- Gel:High-viscosity concentrates target precise portion control in decorative icing and fondant applications.
- Granular:Free-flowing particulates bridge powder and liquid handling characteristics for mid-scale operations.
Powder maintains dominant throughput volumes. Liquid is gaining share fastest through foodservice channel expansion.
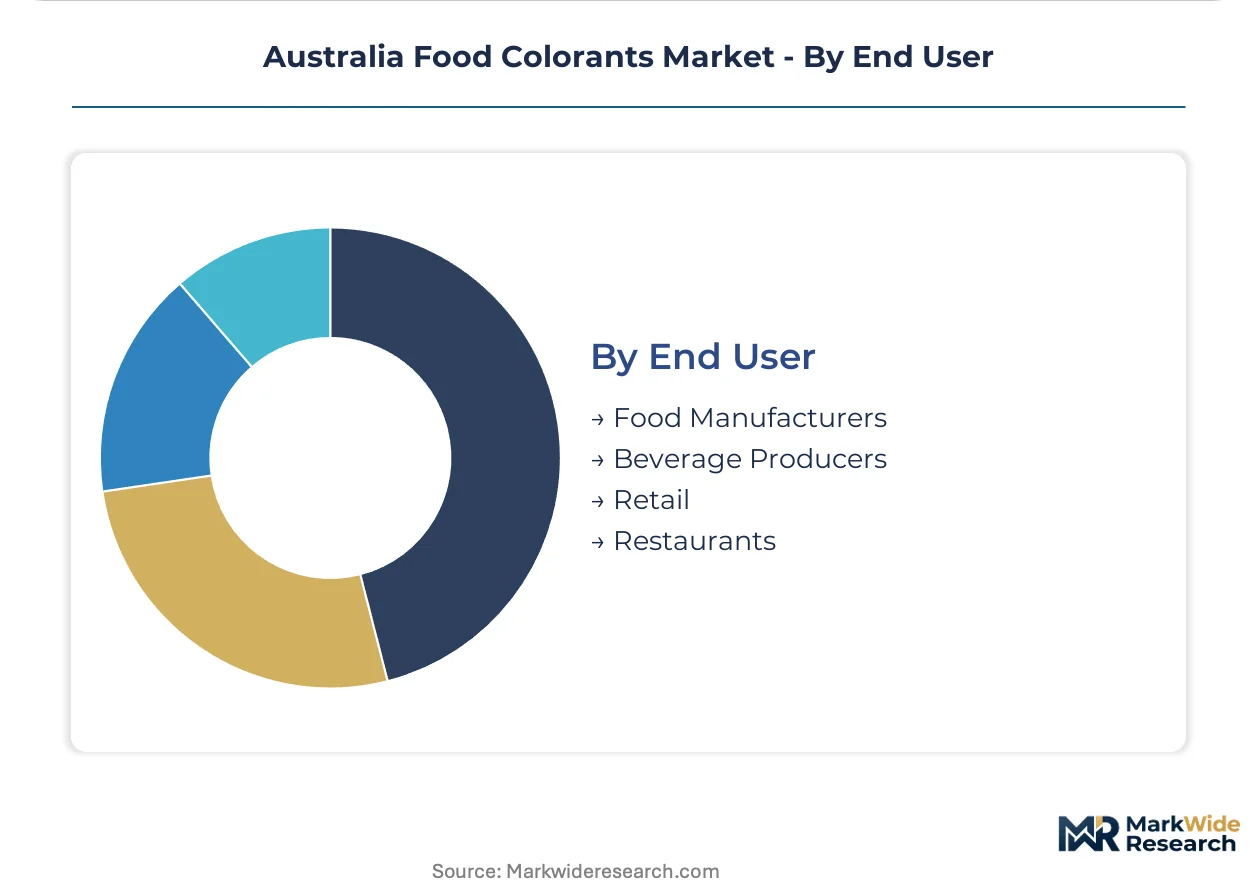
End User:
Customer scale and technical capability determine whether procurement emphasizes commodity pricing or integrated formulation support.
- Food Manufacturers:Large-scale processors demand batch-to-batch consistency documentation and stability modeling across shelf-life testing. Coles and Woolworths private-label suppliers face mandatory colorant pre-qualification gates.
- Beverage Producers:Functional drink specialists prioritize anthocyanin sourcing with verified polyphenol content for dual color-antioxidant label claims. Contract manufacturers in Sydney's western suburbs concentrate procurement volumes.
- Retail:Packaged consumer colorant kits for home baking represent marginal volume with premium pricing tolerance.
- Restaurants:Direct procurement from specialty distributors bypasses conventional ingredient channels for small-batch plating colors.
Food Manufacturers anchors procurement volumes. Beverage Producers is rotating up the share rankings through clean-label reformulation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price premiums in New South Wales and Victoria exceed Queensland benchmarks by double-digit margins, reflecting manufacturing concentration effects and transport cost asymmetries across Australian state boundaries.
New South Wales
Sydney's western suburbs host concentrated contract beverage manufacturing, driving anthocyanin procurement volumes for functional drink reformulations. FSANZ's Schedule 15 tightening directly impacts formulation approvals for processors operating in this corridor. The Parramatta-to-Penrith industrial belt anchors national distribution logistics for colorant suppliers.
Victoria
Melbourne's food processing corridor generates the deepest demand for dairy-compatible carotenoids and microbial-derived pigments. State-level environmental compliance frameworks govern botanical extraction operations in surrounding agricultural zones. The Hume Highway manufacturing cluster offers co-location advantages for suppliers serving national retail private-label programs.
Queensland
Spirulina cultivation in Riverina-adjacent growing regions supplies concentrated betalain feedstocks for natural colorant extraction. Seasonal weather volatility creates input price fluctuations that compress margins for regional processors. Brisbane's emerging food-tech incubators are piloting fermentation-derived pigment alternatives.
South Australia
Adelaide's mid-scale baking sector sustains demand for heat-stable caramel colors in sauce and confectionery applications. Interstate freight differentials disadvantage local processors relative to eastern seaboard competitors. The Barossa Valley's premium food positioning drives niche procurement for artisanal plating colors.
Tasmania
Organic-certified growing regions command export price premiums for cold-pressed anthocyanin extracts. Pesticide-free certification requirements align with Japanese and European import standards. Hobart-based extraction facilities serve specialty dairy exporters targeting Asian clean-label markets.
Australia Food Colorants Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the supply architecture. The Australian food colorants sector exhibits tiered concentration, with global ingredient houses anchoring premium supply and regional distributors filling volume gaps. Three strategic archetypes dominate: fermentation-derived pigment specialists, agricultural backward-integrated traders, and application-technical service integrators. Capacity expansion in botanical extraction and strategic partnerships with contract manufacturers represent the primary competitive vectors.
Within the fermentation-specialist tier, Chr. Hansen Holding A/S and Sensient Technologies Corporation exemplify divergent positioning strategies. Cargill, Inc. anchors the agricultural-integration archetype through its grain-belt supply control. These three entities occupy distinct competitive spaces rather than direct overlap, with each representing a viable template for market participation.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| Chr. Hansen Holding A/S |
| Cargill, Inc. |
| Naturex S.A |
| Döhler GmbH |
| Kerry Group |
| Symrise AG |
| BASF SE |
| Tate & Lyle PLC |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Victorian extraction facilities is compressing supplier margins while simultaneously amplifying pricing leverage for buyers with long-term offtake commitments. FSANZ's tightening additive permissions are accelerating synthetic-to-natural reformulations, redirecting procurement volumes toward fermentation-derived pigments and Tasmanian botanical sources.
Pricing Analysis
Configured-to-order pricing for customized shade-matched color systems commands spreads of 40-60% above standard catalog grades. The dominant pricing structure stratifies across premium, standard, and economy tiers, with differentiation driven by organic certification status and stability documentation depth. Cost compression in commodity synthetics is intensifying because FSANZ's Schedule 15 review is narrowing permissible species. Beverage producers exhibit the lowest price sensitivity due to clean-label mandate compliance costs, while mid-tier bakery manufacturers face acute margin pressure.
Supply Chain Analysis
Extended payment terms from national retail chains are forcing colorant suppliers to absorb working capital burdens or access supply-chain finance facilities. Geographic concentration centers on China for specialty aluminum lakes, India for concentrated botanical extracts, and domestic Victorian facilities for dairy-compatible carotenoids. Raw material dependencies include Riverina spirulina, Tasmanian blackcurrant, and Queensland beetroot feedstocks. Single-source vulnerability runs through Chinese lake processors outside Australian tariff preferences. Distribution runs through Melbourne's Hume Highway corridor for national reach, with Sydney's Parramatta-Penrith belt anchoring beverage sector logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as cell-cultured fermentation pigments threaten incumbent agricultural extraction models. Incumbents must navigate biotechnology-enabled competitors achieving synthetic-comparable yields.
For Market Incumbents: Harden formulation expertise moats by embedding application laboratories within Victoria's Hume Highway manufacturing cluster. Secure captive spirulina supply through backward integration into Riverina growing contracts before fermentation alternatives achieve cost parity. FSANZ approval timeline compression for novel pigments threatens first-mover advantages in dairy applications.
For New Entrants and Emerging Players: Establish a beachhead in direct-to-artisan distribution channels serving Sydney's specialty baking supply market. Target white-space in Tasmanian organic-certified extraction for export-grade anthocyanin production. The most penetrable entry vector combines cold-pressed processing credentials with Japanese and European import compliance documentation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across microbial fermentation pigment production as bioreactor scale economies mature. Long-term viability favors platforms integrating fermentation capability with existing botanical extraction infrastructure. Acquisition targets should exhibit dual-source supply resilience across agricultural and biotechnological inputs. Watch FSANZ novel food approval velocity as the critical inflection signal for fermentation-derived pigment commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Feedstocks | Captive spirulina and beetroot supply from Riverina insulates margins against seasonal volatility. |
| Fermentation-Derived Pigment Scale-Up | Chr. Hansen-style bioreactor capacity addresses FSANZ's tightening synthetic permissions with standardized yields. |
| Application Laboratory Co-Location | Melbourne corridor presence meets Coles and Woolworths stability documentation mandates for private-label suppliers. |
| Tasmanian Organic Certification Investment | Pesticide-free credentials unlock Japanese and European export premiums for cold-pressed anthocyanins. |
| Direct-to-Artisan Distribution Buildout | Bypassing conventional ingredient distributors captures margin in Sydney's specialty baking supply channel. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with formulation chemists at Victorian dairy processors, procurement leads at Sydney beverage contract manufacturers, FSANZ regulatory affairs specialists, and botanical extraction facility operators in Tasmania. Secondary validation drew from FSANZ Schedule 15 amendment proposals, ACCC consumer protection rulings on natural claims, Australian Bureau of Agricultural and Resource Economics crop forecasts, and customs records tracking aluminum lake imports. Bottom-up volume modeling across extraction facilities and top-down expenditure analysis from national food manufacturers were triangulated to establish market sizing.
Calibration against historical FSANZ approval timelines and reformulation cycle data from major beverage brands anchored projection reliability. Segmentation dimensions modeled include colorant source type, thermal processing application, physical form factor, and end-user scale category across the analysis window. CAGRs were derived from elasticity-adjusted demand curves incorporating clean-label procurement mandate diffusion rates. Forecast inputs weighted spirulina cultivation yield variability and fermentation facility commissioning schedules.
Sensitivities concentrate around FSANZ novel extraction method approvals and Riverina climate volatility affecting botanical input availability. Forecasts reflect documented assumptions regarding regulatory trajectory and agricultural productivity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Monk Fruit Ingredient Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
Asia-Pacific Food Emulsifier Market
Food Additives and Ingredients
Food Grade Potassium Sorbate Market
Food Additives and Ingredients
Global Wood-Derived Food Additives Market
Food Additives and Ingredients
Hydrocolloid Carrier Market
Food Additives and Ingredients
Middle East and Africa Clean Label Ingredients Market
Food Additives and Ingredients
Natural Food Color Ingredients Market
Food Additives and Ingredients
Aluminum-Free Natural Food Color Market
Food Additives and Ingredients
Seitan Powder Market
Food Additives and Ingredients
Oxygen Absorbers Market
Food Additives and Ingredients
Neohesperidin Market
Food Additives and Ingredients
Australia Food Acidulants Market
Food Additives and Ingredients
Vietnam Food Additives Market
Food Additives and Ingredients
Global Flaked Shortenings Market
Food Additives and Ingredients
Neohesperidine DC Market