
 Tax Advisory Services Market | 2026-2036
Tax Advisory Services Market Size, Share, and Industry Trends Forecast 2026-2036
Tax Advisory Services Market Analysis
OECD Pillar Two is repositioning the cost-of-entry calculus for tax advisory firms serving multinational clients. Deloitte Touche Tohmatsu Limited leverages its global transfer pricing network to anchor complex implementation work across jurisdictions. Ernst & Young (EY) specializes in building country-by-country reporting systems that navigate the new 15% effective minimum rate mechanics. KPMG International Limited competes through technology-led compliance platforms that automate substance requirements and safe harbor calculations.
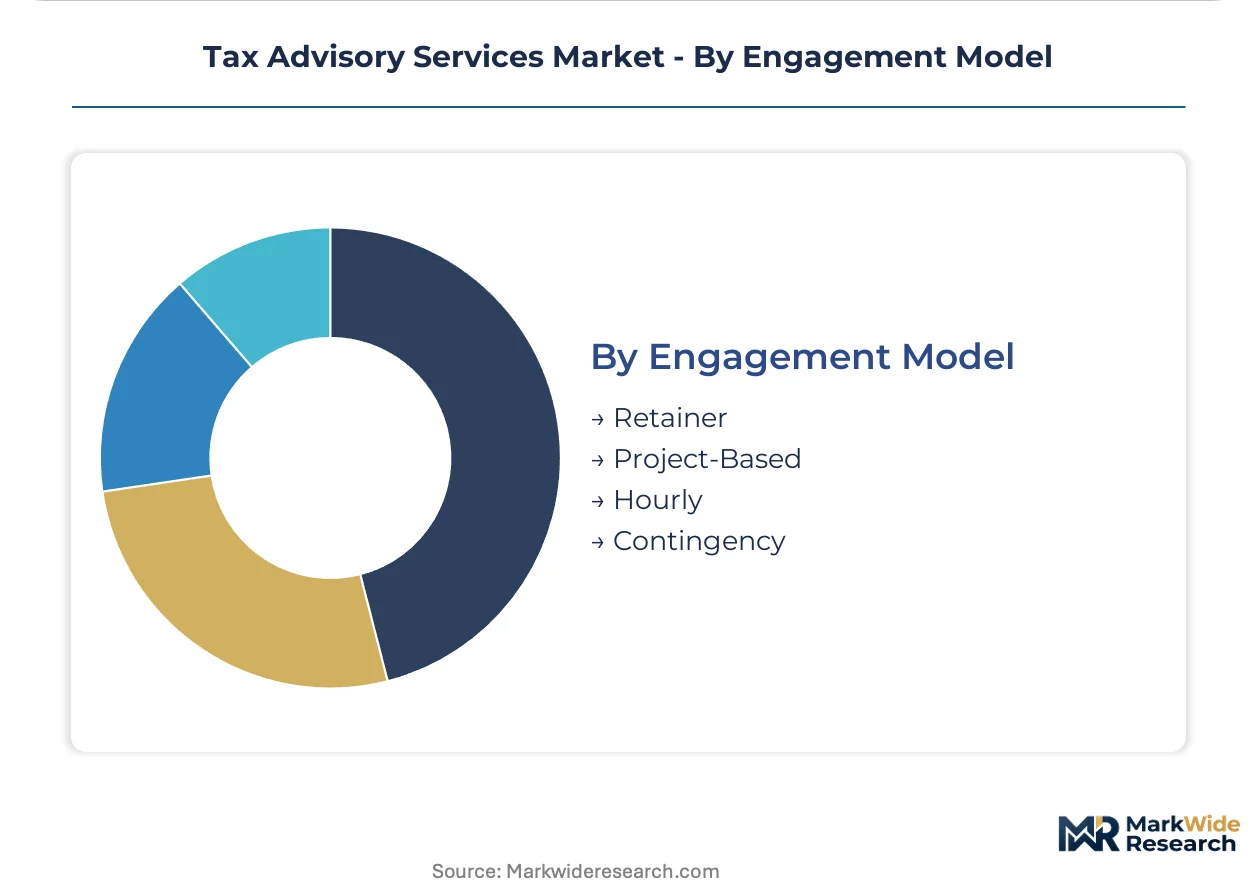
Tax advisory services encompass professional guidance on tax law interpretation, liability optimization, and regulatory compliance across corporate, individual, and institutional clients. Practitioners apply statutory codes, bilateral treaty networks, and administrative rulings to minimize legal tax exposure while satisfying disclosure obligations to revenue authorities. The compliance segment dominates current revenue as mandatory Pillar Two filings and enhanced transfer pricing documentation multiply filing burdens. Consulting and tax planning categories capture expanding margin pools as enterprises restructure supply chains and intellectual property holdings to align with new global minimum tax architecture. The engagement model dimension shows retainer relationships deepening as clients seek continuous monitoring rather than episodic project support.
The US Treasury Department and Internal Revenue Service shape domestic demand through detailed Pillar Two regulations and foreign tax credit modifications. The OECD's Inclusive Framework coordinates multilateral implementation, while EU member states transpose the directive through national legislation with varying effective dates. Stakeholders must monitor divergence between model rules and local enforcement postures to anticipate where advisory complexity will intensify most acutely.
Market Dynamics
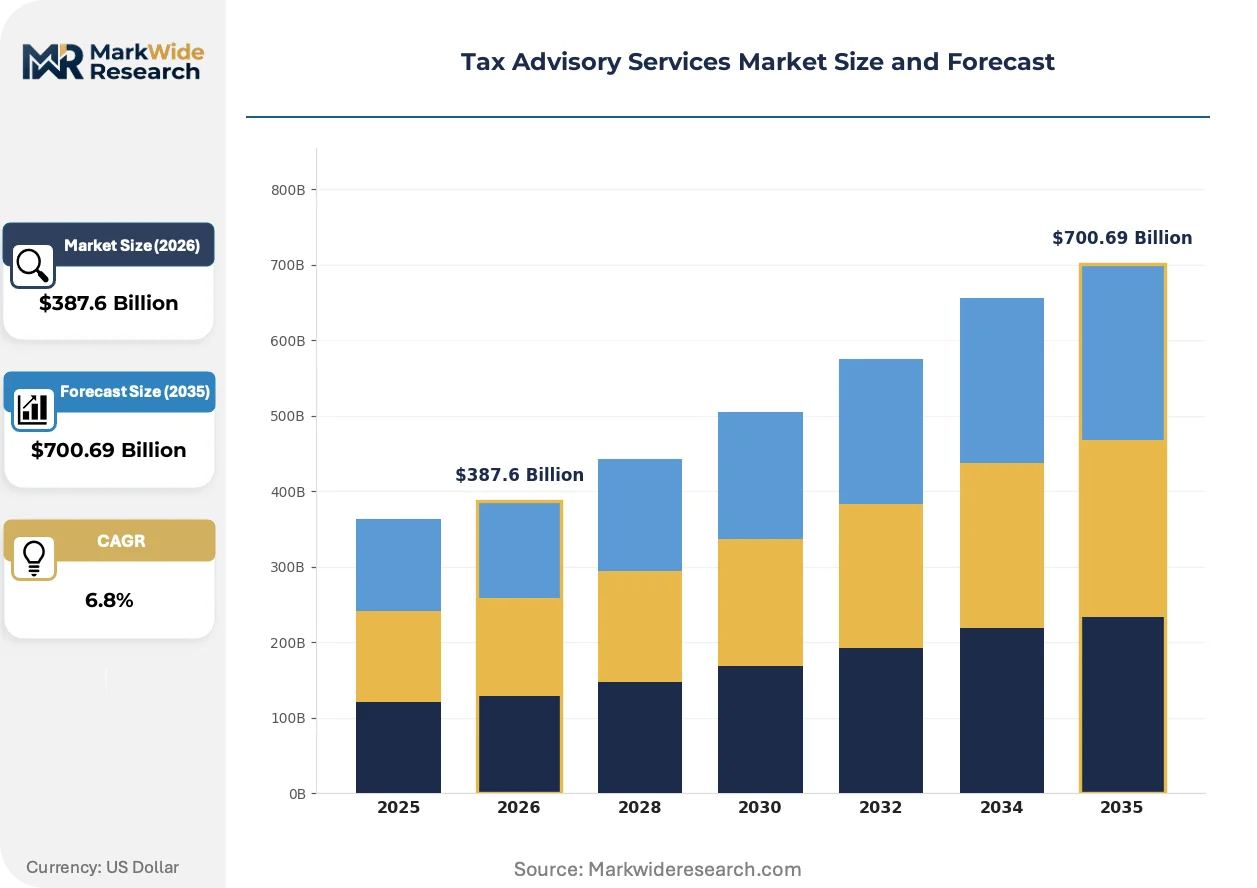
The OECD's Pillar Two global minimum tax framework is compressing multinational tax planning horizons and forcing enterprises to rebuild compliance infrastructure from transfer pricing through entity rationalization. Advisory firms must now embed continuous monitoring capabilities rather than delivering episodic project support.
Growth Catalysts
- Pillar Two Implementation:The OECD's 15% effective minimum rate mechanics mandate new country-by-country reporting systems across jurisdictions, expanding mandatory filing burdens and advisory engagement scope.
- Supply Chain Restructuring:Multinational corporations are relocating intellectual property holdings and substance operations to align with qualified domestic minimum top-up tax safe harbors, creating sustained restructuring demand.
- United States:Treasury Department rulemaking on foreign tax credit modifications and transfer pricing documentation requirements is reshaping international tax planning complexity for US-headquartered enterprises.
Market Restraints
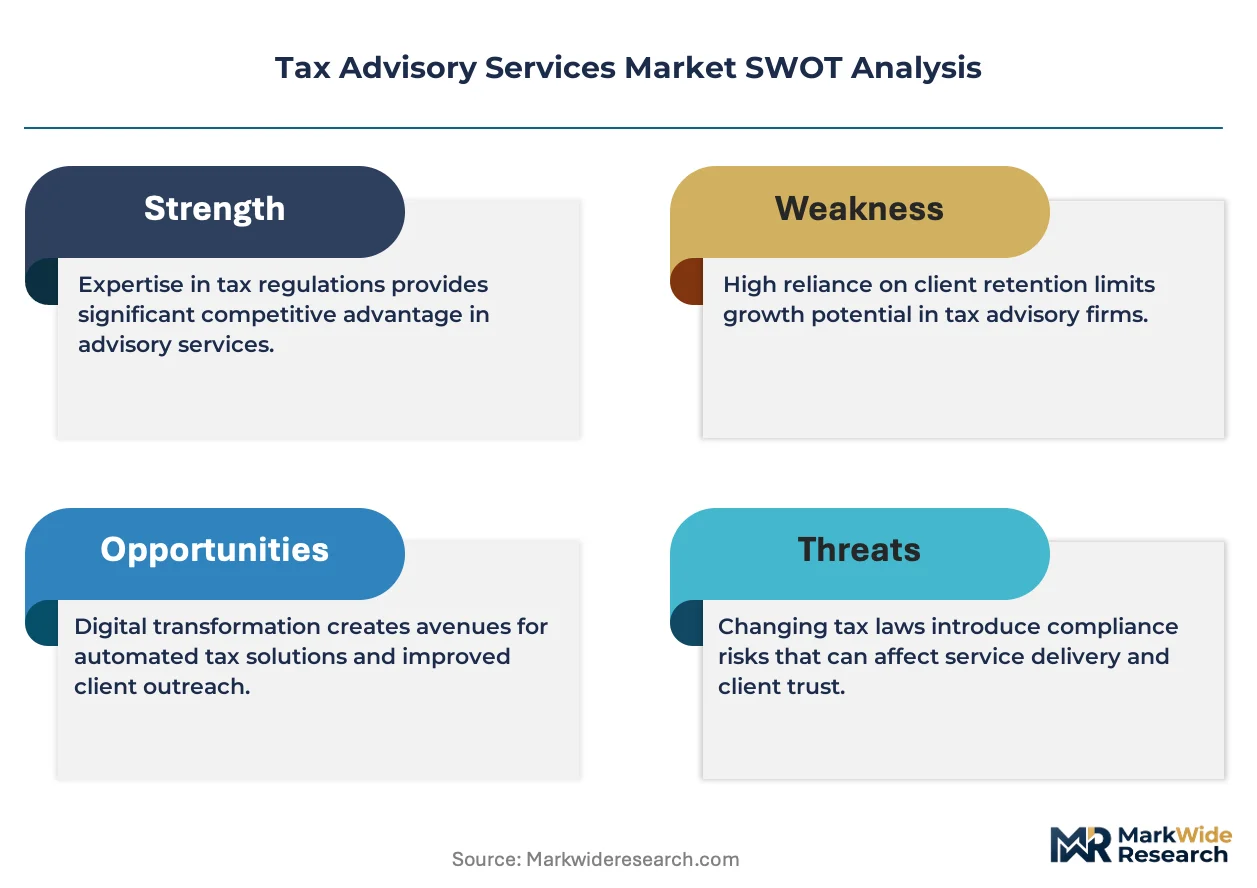
- Talent Concentration:Deep technical expertise in Pillar Two mechanics concentrates among senior professionals at major advisory networks, limiting scalable service delivery.
- Technology Investment Burden:Automated compliance platforms require substantial capital deployment for substance tracking and safe harbor calculation engines, raising barriers for mid-tier competitors.
- Regulatory Divergence:EU member states are transposing the directive through national legislation with varying effective dates, fragmenting implementation timelines and advisory workload predictability.
Strategic Opportunities
- Technology Convergence:Artificial intelligence tools combined with entity management software are enabling real-time effective tax rate monitoring and scenario modeling for enterprise clients.
- Retainer Model Expansion:Continuous monitoring relationships are displacing project-based engagements, locking in recurring revenue and deepening client advisory penetration.
- Emerging Jurisdictions:Developing economies adopting Pillar Two frameworks present first-mover advisory opportunities before local expertise matures.
Industry Challenges
- Skill Scarcity:Cross-border tax technologists capable of integrating Pillar Two mechanics with legacy transfer pricing systems command premium compensation and limited availability.
- Integration Complexity:New compliance platforms must interface with enterprise ERP systems housing decades of historical tax positions without disrupting ongoing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tax Advisory Services Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Compliance, Consulting, Dispute Resolution, Tax Planning Client Type: Corporates, High-Net-Worth Individuals, SMEs, Non-Profit Organizations Industry Vertical: Financial Services, Real Estate, Technology, Manufacturing Engagement Model: Retainer, Project-Based, Hourly, Contingency |
| Companies Covered | PricewaterhouseCoopers (PwC), Deloitte Touche Tohmatsu Limited, Ernst & Young (EY), KPMG International Limited, BDO International Limited, Grant Thornton International Ltd., RSM International, Baker Tilly International, Crowe Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tax Advisory Services Market Emerging Trajectories
Tax advisory delivery is pivoting from manual interpretation toward algorithmic compliance and predictive scenario modeling. The profession is absorbing automation tools that compress traditional research and documentation timelines while elevating strategic advisory value.
Generative AI is absorbing routine statutory research and documentation drafting functions previously executed by junior professionals. Mid-market enterprises are adopting these tools fastest, drawn by cost predictability and turnaround compression. The technology is absorbing lower-margin compliance work and pushing advisory firms toward higher-value restructuring and controversy support.
The EU's Corporate Sustainability Reporting Directive intersects with tax transparency mandates, requiring integrated disclosure of effective tax rates by jurisdiction. This regulatory layering is forcing advisory firms to build cross-functional teams combining tax technical and ESG reporting expertise. Financial services and extractive industries face the steepest compliance ramps.
Enterprise procurement of tax advisory is consolidating around integrated platform providers capable of spanning compliance, planning, and controversy. Retainer relationships with quarterly business reviews are replacing discrete project scoping. This shift is most visible among Fortune 500 enterprises with operations across 20-plus jurisdictions.
Tax Advisory Services Market Segmentation
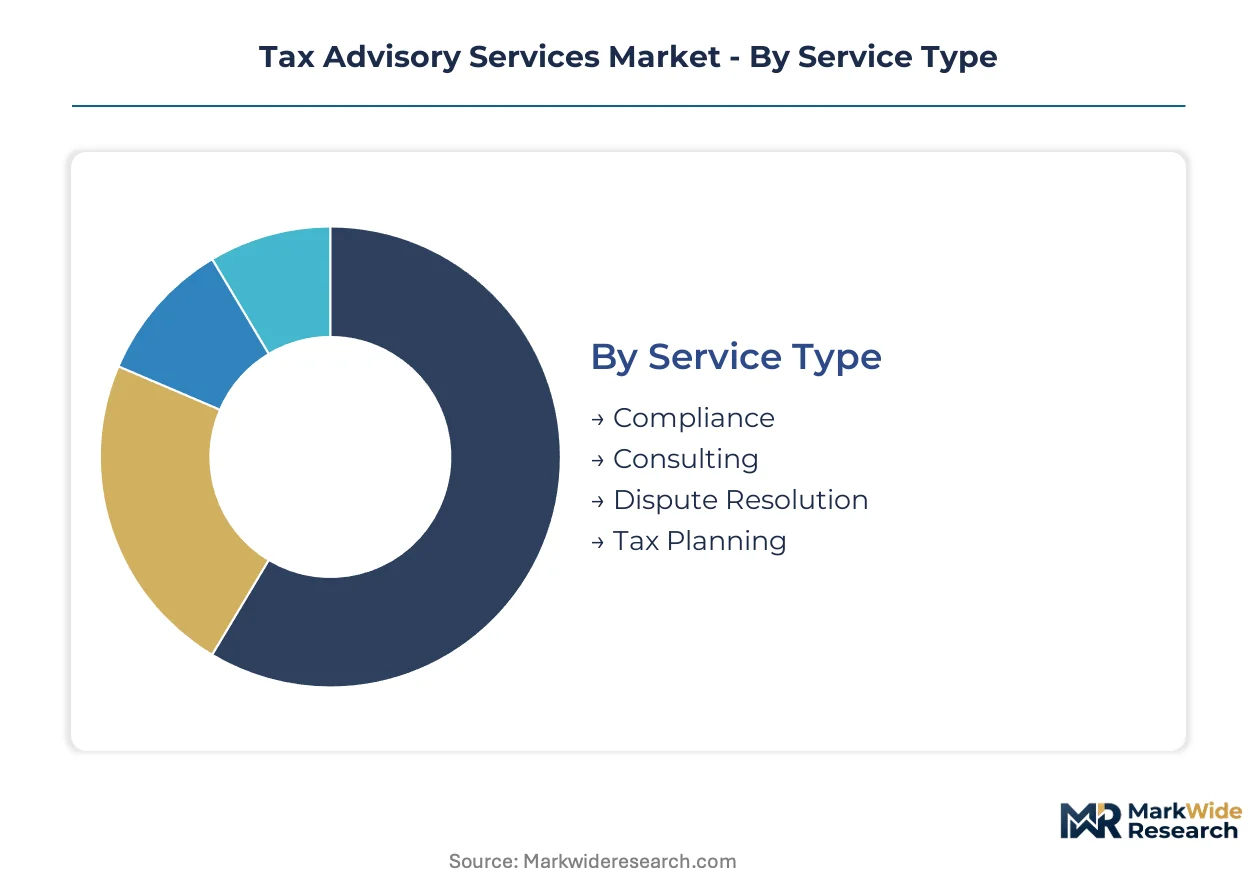
Tax advisory services fragment across service delivery modes, client sophistication levels, and regulatory complexity tiers. Each segmentation axis carries distinct margin profiles and capital requirements that reshape competitive positioning across the advisory landscape.
Service Type:
Capital intensity concentrates in technology infrastructure for automated compliance platforms and scenario modeling engines rather than physical assets.
- Compliance:Mandatory Pillar Two filings and enhanced transfer pricing documentation multiply filing burdens across jurisdictions. Demand concentrates among Fortune 500 enterprises with operations spanning 20-plus countries, driven by OECD's 15% effective minimum rate mechanics and country-by-country reporting requirements.
- Consulting:Supply chain restructuring and intellectual property relocation advisory commands premium pricing. Technology and manufacturing verticals in the United States dominate demand as Treasury Department rulemaking reshapes international tax planning complexity.
- Dispute Resolution:Controversy support during revenue authority examinations and mutual agreement procedures.
- Tax Planning:Strategic liability optimization across bilateral treaty networks and safe harbor calculations.
Most installed capacity flows through Compliance. Expansion is steepest in Consulting.
Client Type:
Service delivery economics vary sharply by client scale, with enterprise retainers subsidizing compliance platform development for mid-market deployment.
- Corporates:Multinational enterprises require integrated compliance, planning, and controversy capabilities across multiple jurisdictions. Demand clusters in the United States and EU member states transposing Pillar Two directives through national legislation with varying effective dates.
- High-Net-Worth Individuals:Cross-border wealth structuring and succession planning for globally mobile capital.
- SMEs:Generative AI tools are absorbing routine statutory research, compressing turnaround times and cost predictability for mid-market adoption.
- Non-Profit Organizations:Unrelated business income tax and international grant structuring compliance.
Revenue concentration sits with Corporates. Fastest share gains are occurring among SMEs.
Industry Vertical:
Regulatory layering intensity determines advisory penetration depth, with financial services facing overlapping tax transparency and ESG disclosure mandates.
- Financial Services:EU's Corporate Sustainability Reporting Directive intersects with tax transparency requirements, demanding integrated effective tax rate disclosure by jurisdiction. The steepest compliance ramps confront banking and insurance groups with cross-border operations.
- Technology:Intellectual property holding company restructuring dominates as enterprises relocate substance operations to align with qualified domestic minimum top-up tax safe harbors.
- Real Estate:Partnership structuring and passive activity loss limitation planning.
- Manufacturing:Supply chain rationalization and customs-tariff coordination.
Advisory complexity peaks in Financial Services. Technology verticals are expanding engagement scope most quickly.
Engagement Model:
Contract structure determines revenue predictability and client switching costs across the advisory relationship lifecycle.
- Retainer:Continuous monitoring relationships with quarterly business reviews are displacing discrete project scoping. Fortune 500 enterprises lock in recurring revenue arrangements that deepen advisory penetration and reduce procurement friction.
- Project-Based:Episodic restructuring and controversy support engagements.
- Hourly:Time-based billing for discrete technical opinions and ruling requests.
- Contingency:Success-fee structures for tax authority settlement negotiations and refund claims.
Contract volume concentrates in Retainer arrangements. Contingency structures are gaining traction in dispute resolution contexts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Senior tax technologists cluster disproportionately in London, New York, and Singapore, anchoring advisory capacity for cross-border implementation work. This talent concentration shapes where multinational enterprises source Pillar Two compliance architecture and transfer pricing restructuring expertise.
United States
Fortune 500 enterprises headquartered across the United States drive sustained demand for international tax planning and foreign tax credit optimization. Treasury Department rulemaking on Pillar Two implementation and transfer pricing documentation requirements reshapes compliance complexity quarterly. The New York and Washington D.C. metro areas concentrate Big Four advisory capacity serving cross-border restructuring mandates.
Germany
Industrial conglomerates with manufacturing footprints spanning Central and Eastern Europe require integrated substance planning and qualified domestic minimum top-up tax navigation. The country's federal finance ministry transposes EU Pillar Two directives through national legislation with phased effective dates. Frankfurt and Munich anchor advisory clusters serving automotive and machinery verticals restructuring intellectual property holdings.
United Kingdom
Financial services groups with operations across Commonwealth and offshore jurisdictions demand integrated effective tax rate disclosure and controversy support. HM Treasury and HMRC coordinate Pillar Two implementation timelines diverging from EU member state schedules. The City of London concentrates advisory capacity for banking and insurance groups navigating regulatory layering with ESG disclosure mandates.
Japan
Trading houses and automotive manufacturers with Southeast Asian supply chains require country-by-country reporting systems and safe harbor calculation support. METI coordinates with the National Tax Agency on Pillar Two administrative guidance affecting regional headquarters structures. Tokyo anchors advisory capacity for keiretsu groups rationalizing cross-border intellectual property arrangements.
Singapore
Regional headquarters operations for technology and commodities trading firms drive demand for qualified domestic minimum top-up tax planning and substance requirement documentation. The Inland Revenue Authority of Singapore administers Pillar Two implementation alongside existing headquarters tax incentive frameworks. The city-state's advisory cluster serves as coordination hub for Asia-Pacific multinational restructuring mandates.
Tax Advisory Services Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service delivery models. The market structure concentrates advisory capacity among global networks with transfer pricing technical depth and jurisdictional coverage breadth. Three archetypes dominate: integrated platform providers spanning compliance through controversy; technology-led specialists automating safe harbor calculations; and boutique practices serving single-jurisdiction complexity. Competitive moves center on retainer relationship expansion and AI-enabled compliance platform deployment.
Within the integrated platform tier, Deloitte Touche Tohmatsu Limited and Ernst & Young exemplify archetypes anchoring complex Pillar Two implementation work across multiple jurisdictions. These structures represent the scale-driven end where global transfer pricing networks and country-by-country reporting system capabilities concentrate senior technical expertise.
| Leading Market Players |
|---|
| PricewaterhouseCoopers (PwC) |
| Deloitte Touche Tohmatsu Limited |
| Ernst & Young (EY) |
| KPMG International Limited |
| BDO International Limited |
| Grant Thornton International Ltd. |
| RSM International |
| Baker Tilly International |
| Crowe Global |
| Others |
Supply Flow & Price Mechanics
Retainer-premium divergence between continuous monitoring contracts and episodic project engagements reshapes both pricing architecture and talent deployment across advisory networks. The bundled service tier anchors recurring revenue through integrated compliance platforms, while unbundled hourly arrangements concentrate in discrete controversy support, creating parallel supply chains for senior technologists versus automated tooling infrastructure.
Pricing Analysis
Retainer versus project-based service splits dominate pricing architecture across the advisory landscape. Three-tier pricing structure across premium, standard, and economy levels aligns with client complexity tiers, with Fortune 500 enterprises locking in premium continuous monitoring while mid-market adopters select standard automated compliance tiers. Pricing pressure stems from generative AI absorption of routine statutory research, compressing margins in economy-tier compliance documentation. SMEs exhibit highest price sensitivity, gravitating toward predictable SaaS-tiered automation tools, while multinational corporates demonstrate lowest sensitivity given mandatory Pillar Two filing exposure.
Supply Chain Analysis
Reverse-logistics flows for advisory service delivery center on knowledge asset recycling and methodology reuse across client engagements. Senior tax technologists concentrate in London, New York, and Singapore, drawing from these talent clusters for cross-border implementation work. Technology infrastructure draws from cloud computing providers and specialized entity management software vendors, with compliance platform development resting on substantial capital deployment. Single-source vulnerability concentrates in senior Pillar Two technical expertise, where limited practitioner availability creates bottleneck risk. Distribution runs through direct enterprise sales relationships and channel partnerships with law firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in technology-enabled compliance automation and retainer relationship deepening, with AI tooling deployment driving cost compression in routine advisory delivery.
For Market Incumbents: Deploy AI-augmented compliance platforms to absorb lower-margin statutory research functions while elevating strategic advisory penetration. Big Four networks should anchor continuous monitoring relationships through integrated entity management software, defending against pure-play technology specialists. Vertical integration into proprietary safe harbor calculation engines creates differentiation against mid-tier competitors lacking capital depth. For New Entrants and Emerging Players: Digital-channel routes through generative AI tooling present the most penetrable entry vector for mid-market SME segments underserved by retainer-heavy incumbent models. White-space targets concentrate in developing economies adopting Pillar Two frameworks before local expertise matures. Cloud-native compliance platforms with transparent per-jurisdiction pricing offer the strongest go-to-market angle against bundled enterprise offerings. For Investors and Strategic Acquirers: Consolidation pressure builds where technology investment burdens exceed mid-tier capital access, creating acquisition opportunities for automated compliance platform specialists. Long-term viability favors advisory networks with demonstrated AI integration and recurring revenue depth over project-dependent boutiques. The signal to watch is regulatory divergence intensity between EU member state implementation timelines, which accelerates demand for multi-jurisdictional coordination capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Compliance Platform Deployment | Automates Pillar Two safe harbor calculations, reducing junior practitioner headcount requirements. |
| Retainer Relationship Expansion | Locks in recurring revenue through quarterly business reviews replacing discrete project scoping. |
| Cross-Functional Team Building | Integrates tax technical and ESG reporting expertise for EU Corporate Sustainability Reporting Directive compliance. |
| Geographic Advisory Cluster Expansion | Establishes presence in Singapore and Frankfurt to capture Asia-Pacific and Central European restructuring demand. |
| Generative AI Research Tool Integration | Compresses statutory interpretation timelines while elevating senior practitioner strategic advisory value. |
Methodological Framework
Multiple input streams — primary interviews with tax advisory partners, regulatory affairs directors, and enterprise tax directors, alongside secondary validation through OECD implementation guidance, EU directive transposition documents, and Treasury Department rulemaking releases — were reconciled through bottom-up and top-down triangulation. Cross-functional perspectives from Big Four network leaders, mid-tier firm managing partners, and multinational corporate tax executives informed service delivery model assessments. Secondary sources included SEC 10-K disclosures of advisory revenue concentration, professional services trade association reports, and jurisdictional regulatory filings.
Historical revenue trajectory patterns were cross-referenced against panel input from senior practitioners to establish projection parameters across the analysis window. Segmentation dimensions modeled encompass service type, client sophistication tier, industry vertical, and engagement model complexity. CAGRs were derived through regression analysis of advisory fee growth correlated with Pillar Two implementation phase timing. Forecast inputs incorporated regulatory divergence scenarios between EU member states and US Treasury coordination postures.
The model assumes a particular technology adoption path; alternative pathways for generative AI integration would alter the outlook for junior practitioner demand and compliance margin structure. Forecasts reflect assumptions regarding OECD Inclusive Framework cohesion and uniform Pillar Two enforcement intensity. Practitioners should monitor regulatory divergence triggers and AI tooling commoditization velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Saudi Arabia Forensic Accounting Market
Accounting and Taxation Services
Small Business Accounting Software Market
Accounting and Taxation Services
Accounting and Budgeting Software Market
Accounting and Taxation Services
Accounting Software Market
Accounting and Taxation Services
Construction Accounting Software Market
Accounting and Taxation Services
Global Fund Accounting Software Market
Accounting and Taxation Services
Hydrocarbons Accounting Solution Market
Accounting and Taxation Services
Canada Forensic Accounting Market
Accounting and Taxation Services
Tax Preparation Services Market
Accounting and Taxation Services
Japan Accounting Software Market
Accounting and Taxation Services
UAE Accounting Software Market
Accounting and Taxation Services
Tax Management Market
Accounting and Taxation Services
Tax Management Software Market
Accounting and Taxation Services
Europe Accounting Software Market
Accounting and Taxation Services
India Accounting Software Market
Accounting and Taxation Services
UK Forensic Accounting Market