
 Smart Wealth Management Market | 2026-2036
Smart Wealth Management Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Wealth Management Market Insights
The capability gap between cloud-native architecture and legacy mainframe infrastructure is rotating competitive dynamics across the sector. SS&C Technologies Holdings, Inc. leverages its vertical software stack to dominate back-office custody and portfolio accounting workflows. Temenos Headquarters SA anchors its position through scalable core banking integration that extends into wealth modules. Fiserv, Inc. competes by embedding advisory tools within its broader financial services ecosystem, reducing client switching costs.
Smart wealth management denotes the algorithmic and data-driven automation of investment advisory, portfolio construction, and client servicing functions through digital platforms that process real-time market feeds, risk tolerance inputs, and regulatory compliance parameters. These systems execute rebalancing, tax-loss harvesting, and goal-based planning across fragmented asset classes to reduce advisory costs and democratize access to institutional-grade strategies. Robo-advisory platforms currently lead service type deployment due to lower marginal cost per account, while artificial intelligence and machine learning capabilities within the technology segment capture disproportionate R&D investment as firms differentiate through predictive analytics and natural language processing for client interaction. Blockchain applications in investment strategy verification and settlement remain nascent but attract specialized development from vendors seeking to occupy trust and transparency layers.
The SEC enforces fiduciary standards under the Investment Advisers Act that shape product suitability algorithms and fee disclosure requirements across US-deployed platforms. The EU's MiFID II and GDPR frameworks, alongside the UK's FCA Consumer Duty rules, impose cross-border data governance and best-execution obligations that vendors must navigate for international expansion. Stakeholders should monitor how generative AI regulatory proposals from multiple jurisdictions will force redesigns of automated advice engines and client consent architectures before compliance deadlines crystallize.
Market Dynamics
The SEC's fiduciary rule evolution is compressing fee structures across advisory channels while simultaneously forcing platform providers to rebuild compliance architectures around real-time suitability algorithms.
Growth Catalysts
- Generative AI integration:Natural language processing engines are reducing client onboarding friction by automating risk tolerance interviews and document parsing for registered investment advisors.
- IRA tax incentives:The Inflation Reduction Act's clean energy provisions are redirecting household capital toward ESG-aligned portfolio construction tools that automate carbon footprint tracking.
- Hybrid advisory models:High net worth individuals in the United States are demanding seamless handoffs between algorithmic portfolio management and human advisor intervention.
Market Restraints
- Legacy system integration costs:Mainframe-dependent custodians face prohibitive capital requirements to API-enable decades-old portfolio accounting databases.
- Data localization mandates:The EU's GDPR cross-border transfer restrictions fragment cloud infrastructure deployment and inflate compliance overhead for US-headquartered platforms.
- Human advisor substitution ceiling:Complex estate planning and concentrated stock management resist full automation, capping addressable market expansion.
Strategic Opportunities
- India's wealthtech penetration:SEBI's regulatory sandbox framework permits controlled experimentation with AI-driven advisory for the country's underbanked affluent segment.
- Blockchain settlement layers:Distributed ledger verification of investment strategy execution addresses transparency demands from institutional due diligence committees.
- Embedded finance distribution:Neobank partnerships allow wealth modules to surface within primary banking interfaces, capturing deposits before they migrate to standalone platforms.
Industry Challenges
- Quantitative risk modeling talent scarcity:Platforms compete for PhD-level expertise in stochastic calculus and alternative data signal extraction.
- Multi-jurisdiction compliance synchronization:Firms must maintain parallel audit trails satisfying SEC, FCA, and MiFID II record-keeping requirements simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Wealth Management Market |
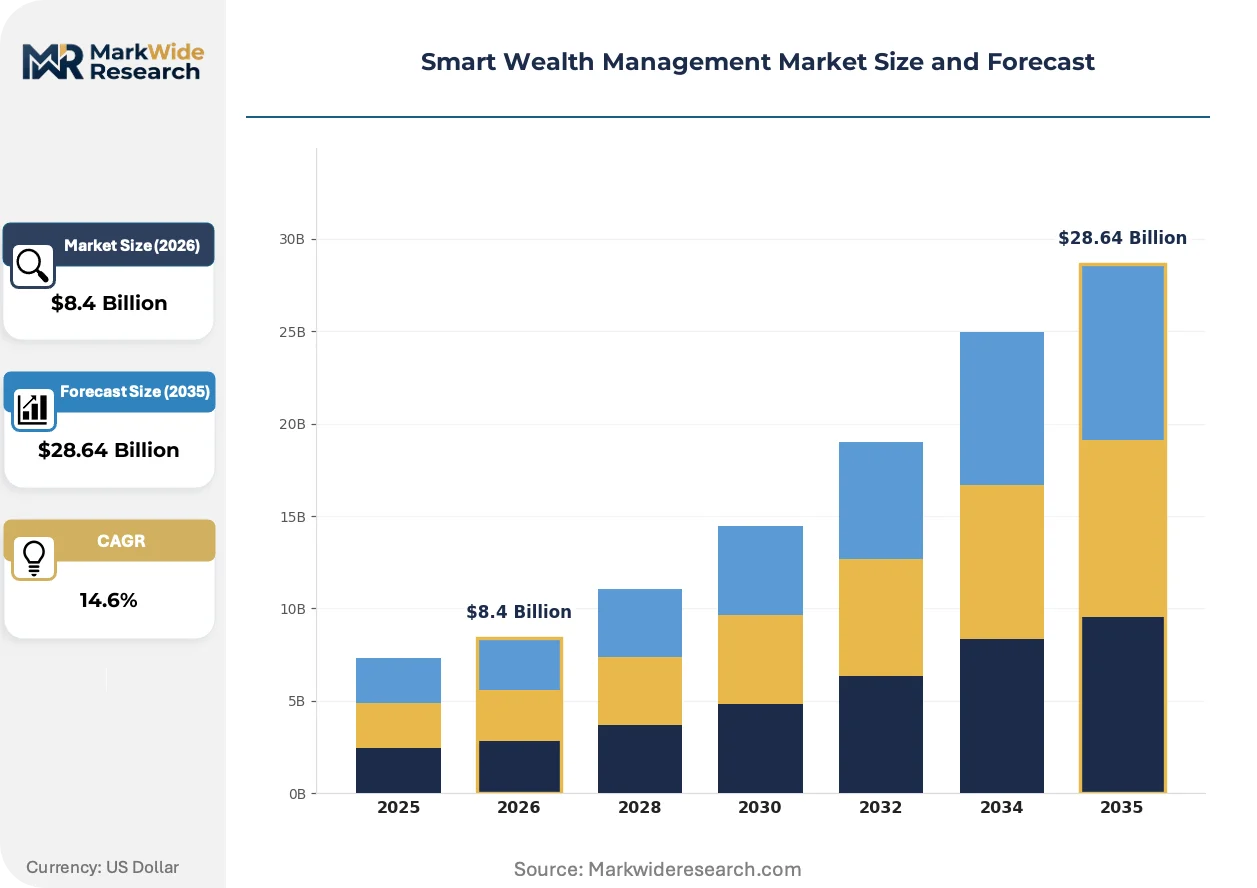
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $28.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Robo-Advisory, Financial Planning, Asset Allocation, Investment Management Client Type: High Net Worth Individuals, Millennials, Institutional Investors, Retail Investors Technology: Artificial Intelligence, Machine Learning, Big Data Analytics, Blockchain Investment Strategy: Value Investing, Growth Investing, Income Investing, Alternative Investments |
| Companies Covered | SS&C Technologies Holdings, Inc., Fiserv, Inc., Fidelity National Information Services, Inc., Temenos Headquarters SA, SEI Investments Company, Comarch SA, Dorsum Ltd., Profile Software, Objectway S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Wealth Management Market Trends and Innovations
Algorithmic decision-making is migrating from portfolio construction into client relationship management, compressing the traditional advisor-client interaction cycle and enabling predictive intervention before behavioral biases trigger withdrawals.
Natural language generation is fragmenting the content production economics of wealth management. GPT-class models now draft personalized market commentary, tax-loss harvesting alerts, and estate planning summaries at marginal cost near zero. Registered investment advisors with sub-$500 million AUM deploy these tools to match the communication frequency previously reserved for billion-dollar family offices. The technology is fragmenting competitive differentiation away from scale toward prompt engineering and data integration depth.
The EU AI Act's risk classification framework is forcing redesigns of automated advice engines deployed across European jurisdictions. High-risk system designations trigger mandatory human oversight, explainability requirements, and conformity assessment procedures. Vendors are responding by bifurcating product architectures—stripped-down European versions with manual checkpoints alongside fully automated US deployments.
Subscription pricing for advisory software is displacing traditional basis-point AUM fees among independent advisors. Monthly SaaS arrangements align vendor incentives with advisor growth rather than portfolio appreciation. The shift is most visible among solo practitioners and small ensembles in the United States seeking to decouple technology costs from market volatility.
Smart Wealth Management Market Segmentation
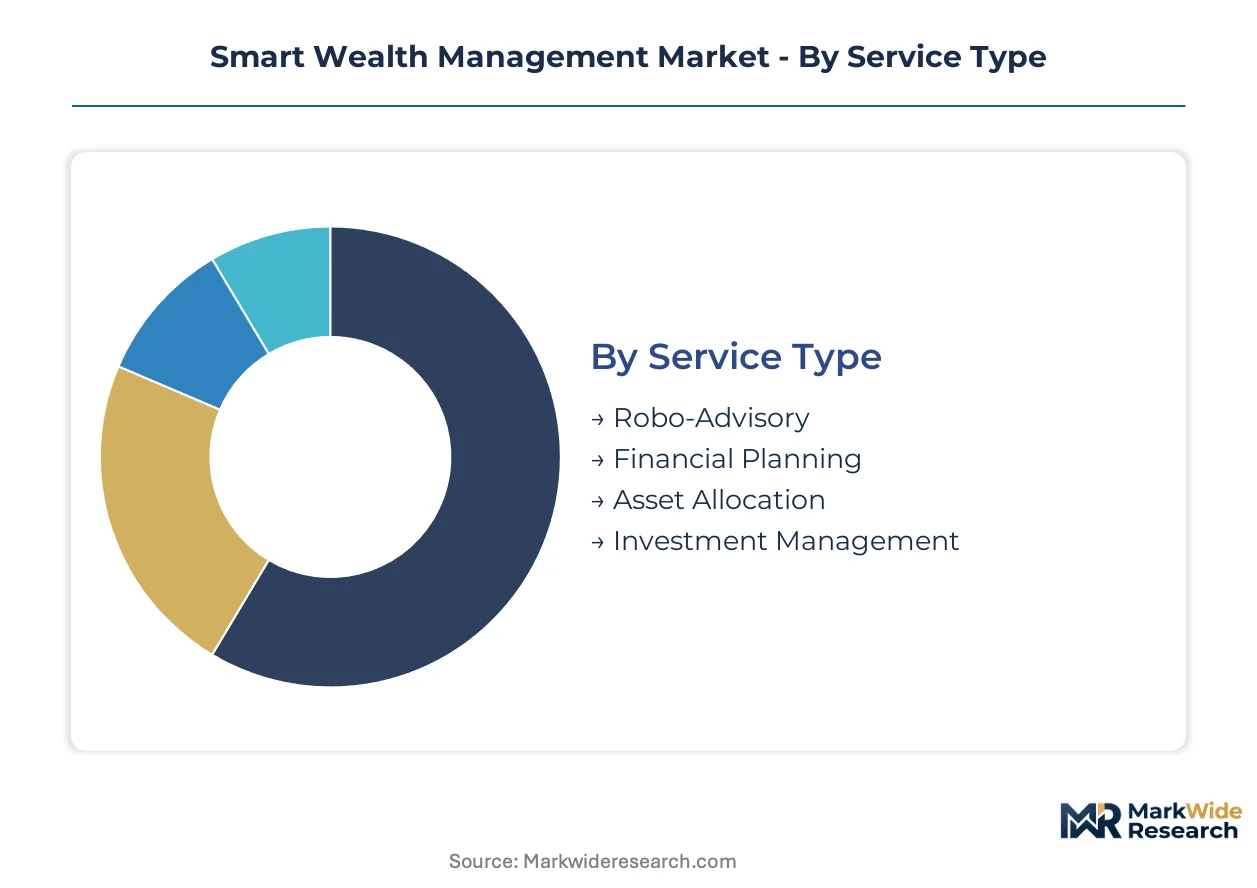
Smart wealth management platforms must align service architecture with distinct client sophistication levels and technology maturity. Segmentation reveals where algorithmic automation displaces human advisors versus where hybrid models dominate.
Service Type:
Domestic deployment concentrates in registered investment advisor channels within the United States, while export-led growth follows MiFID II compliance pathways into European wealth management subsidiaries.
- Robo-Advisory:Fully automated portfolio construction engines execute rebalancing and tax-loss harvesting through API connections to custodial accounts. Demand clusters among millennials in the United States seeking fee compression below traditional advisory rates, though human advisor substitution ceilings persist for complex estate scenarios.
- Financial Planning:Goal-based algorithms integrate cash flow modeling with liability-driven investment frameworks. High net worth individuals across North America drive adoption as platforms add generational wealth transfer modules and concentrated stock management tools.
- Asset Allocation:Strategic and tactical allocation engines process risk tolerance inputs across fragmented asset classes.
- Investment Management:Active and passive strategy implementation with real-time compliance monitoring.
Robo-advisory commands the established base. The steepest expansion runs through financial planning as goal-based modules penetrate mass-affluent segments.
Client Type:
Cost tier stratification separates white-glove human augmentation from self-service algorithmic interfaces, with fee sensitivity determining platform selection.
- High Net Worth Individuals:Clients with investable assets exceeding one million dollars demand seamless handoffs between automated portfolio management and dedicated advisor intervention. The United States registered investment advisor channel captures this segment through hybrid models that preserve relationship continuity during market volatility.
- Millennials:Digital-native investors prioritize mobile-first interfaces and ESG-aligned portfolio construction. IRA tax incentives redirect household capital toward platforms automating carbon footprint tracking and clean energy sector exposure.
- Institutional Investors:Pension funds and endowments require customized reporting and fiduciary audit trails.
- Retail Investors:Mass-market participants access entry-level robo-advisory through neobank partnerships and embedded finance distribution.
High net worth individuals anchor current revenue concentration. Millennial adoption is climbing the fastest as inheritance transfers and IRA contribution limits expand addressable accounts.
Technology:
Application maturity separates production-grade deployment from experimental sandbox environments, with regulatory classification determining geographic availability.
- Artificial Intelligence:Natural language processing engines automate risk tolerance interviews and document parsing, reducing onboarding friction for registered investment advisors. The EU AI Act's high-risk system designation forces bifurcated architectures—stripped-down European versions with mandatory human oversight alongside fully automated United States deployments.
- Machine Learning:Predictive analytics models extract signals from alternative data sources for dynamic portfolio adjustment. Quantitative risk modeling talent scarcity constrains vendor differentiation as PhD-level expertise in stochastic calculus commands premium compensation.
- Big Data Analytics:Real-time market feed processing and client behavioral pattern recognition enable predictive intervention.
- Blockchain:Distributed ledger verification of investment strategy execution addresses institutional transparency demands, though settlement layer applications remain nascent.
Artificial intelligence captures disproportionate R&D investment. Blockchain is gaining share fastest among vendors seeking to occupy trust and transparency layers for institutional due diligence committees.
Investment Strategy:
Customer type differentiation separates income-dependent retirees from accumulation-phase investors, with life cycle positioning driving module configuration.
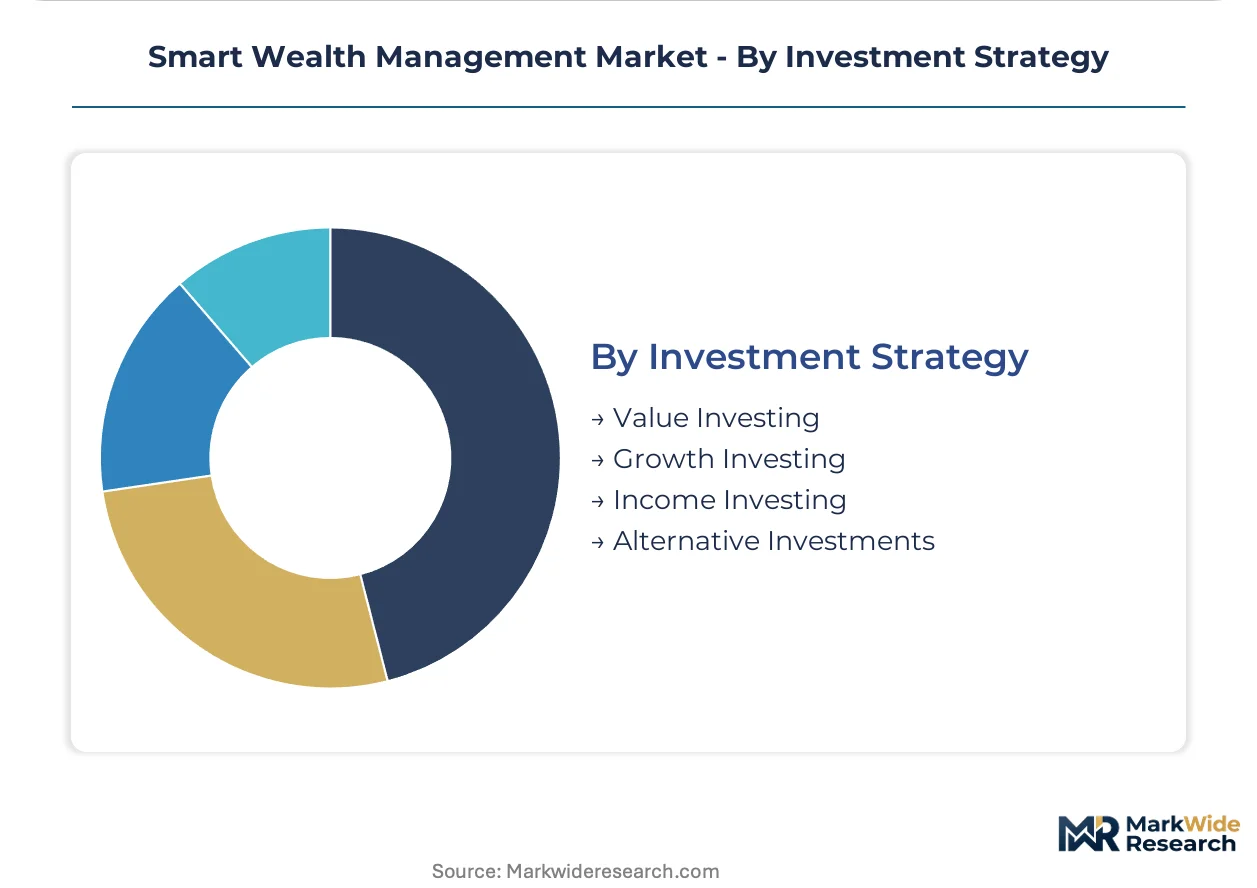
- Value Investing:Algorithmic screening of price-to-book and free cash flow metrics identifies undervalued equity positions. United States-based platforms automate Benjamin Graham-derived frameworks for retail investors seeking downside protection.
- Growth Investing:Momentum and earnings revision signals direct capital toward technology and healthcare sectors. Millennial demand concentrates here as platforms integrate thematic exposure to artificial intelligence and clean energy supply chains.
- Income Investing:Dividend sustainability algorithms and bond ladder construction serve retirement-phase clients.
- Alternative Investments:Private equity, hedge fund, and real estate exposure modules target accredited investor thresholds.
Value investing retains the largest automated AUM base. Growth investing is expanding most quickly as thematic sector ETFs integrate with goal-based planning interfaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across jurisdictions. United States buyers absorb premium advisory fees for hybrid human-digital service models. Indian and Southeast Asian markets demand fee compression below fifty basis points, compressing vendor margins and forcing cloud-native delivery architectures.
United States
Registered investment advisor channels and hybrid robo-advisory offerings drive platform demand. The SEC enforces fiduciary standards under the Investment Advisers Act that shape product suitability algorithms and fee disclosure requirements. Boston and New York metropolitan areas concentrate vendor development centers where SS&C Technologies and Fidelity National Information Services anchor custody and portfolio accounting workflows.
Germany
Private banking subsidiaries of universal banks seek MiFID II-compliant advisory automation. The EU AI Act's risk classification framework forces redesigns of automated advice engines with mandatory human oversight for high-risk system designations. Frankfurt's financial district hosts Temenos implementation partnerships for core banking integration extending into wealth modules.
United Kingdom
Wealth management subsidiaries of insurance groups demand goal-based planning modules for mass-affluent segments. The FCA Consumer Duty rules impose best-execution and fair value obligations that reshape platform compliance architectures. London's fintech cluster incubates AI-driven natural language processing tools for client onboarding automation.
Switzerland
Multi-family offices and external asset managers seek white-label advisory platforms for cross-border private clients. FINMA guidelines on digitalization of financial services create regulatory clarity for algorithmic portfolio construction. Zurich and Geneva private banking centers drive demand for tax-loss harvesting automation across fragmented cross-border asset holdings.
India
SEBI's regulatory sandbox framework permits controlled experimentation with AI-driven advisory for the country's underbanked affluent segment. The central bank's data localization requirements shape cloud infrastructure deployment decisions for foreign platform vendors. Mumbai and Bangalore wealthtech clusters develop mobile-first interfaces for millennial investors prioritizing ESG-aligned portfolio construction.
Smart Wealth Management Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the smart wealth management sector. Vertically integrated software vendors dominate custody and portfolio accounting through decades-old client relationships and high switching costs. Cloud-native challengers compete on implementation speed and API flexibility, winning new advisory firm formations. Strategic moves concentrate on embedding finance partnerships that capture deposits before capital migrates to standalone platforms, and on regulatory sandbox certifications that unlock emerging market entry.
Within the vertical software tier, SS&C Technologies Holdings, Inc. and Fiserv, Inc. occupy positions exemplifying back-office dominance through custody workflow integration. Temenos Headquarters SA represents the core banking extension archetype, leveraging scalable infrastructure into adjacent wealth modules. These three entities anchor competitive dynamics by reducing client switching costs through ecosystem breadth rather than point solution excellence.
| Leading Market Players |
|---|
| SS&C Technologies Holdings, Inc. |
| Fiserv, Inc. |
| Fidelity National Information Services, Inc. |
| Temenos Headquarters SA |
| SEI Investments Company |
| Comarch SA |
| Dorsum Ltd. |
| Profile Software |
| Objectway S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Cloud-native platform scale economies concentrate vendor profitability in subscription tiers above five hundred seats, compressing price floors for mid-market advisory firms while elevating switching costs through API ecosystem depth. This scale dynamic bifurcates supply concentration between vertically integrated custody incumbents and modular challengers competing on implementation velocity.
Pricing Analysis
Implementation services and ongoing platform support contracts generate lifetime value multiples exceeding pure software licensing by a factor of three among registered investment advisor deployments. Three-tier pricing structure across enterprise, professional, and essential levels segments by advisor headcount and custody integration complexity. Cost compression in the essential tier is intensifying because neobank partnerships embed wealth modules at marginal cost near zero. Solo practitioners and small ensembles exhibit acute price sensitivity, while billion-dollar family offices absorb premium fees for white-glove human augmentation layers.
Supply Chain Analysis
Trans-Pacific cable latency and Singapore hub congestion inflate data transfer costs for Asia-Pacific cloud deployments, forcing regional infrastructure replication. Core banking software supply concentrates in Switzerland, the United States, and India, with Temenos and SS&C anchoring custody workflow integration. Platform development draws from stochastic calculus talent pools, alternative data feeds, and regulatory compliance API libraries. Single-source vulnerability sits with concentrated PhD-level quantitative risk modeling expertise commanding premium compensation. Distribution runs through registered investment advisor channels, neobank embedded finance partnerships, and direct-to-advisor SaaS marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart wealth management market tracks a cyclical recovery pattern as interest rate normalization restores portfolio construction activity and advisory firm formation accelerates from depressed base-year levels.
For Market Incumbents: Fortify custody workflow integration through API ecosystem expansion that raises client switching costs against cloud-native challengers. Deepen vertical integration into alternative data signal extraction to offset quantitative modeling talent scarcity. Prioritize SEBI regulatory sandbox certification for India market entry before local wealthtech competitors consolidate advisory relationships.
For New Entrants and Emerging Players: Differentiate on generative AI prompt engineering depth for natural language client communication, displacing incumbents' scale advantages in content production. Target India's underbanked affluent segment through SEBI sandbox partnerships with mobile-first onboarding architectures. Pursue embedded finance distribution through neobank API integration to capture deposits before capital migrates to standalone platforms.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native challengers with demonstrated API flexibility and rapid implementation velocity over legacy mainframe-dependent vendors. Five-to-ten-year viability hinges on regulatory sandbox certifications unlocking emerging market entry and AI-driven advisory engine differentiation. Watch for SEC generative AI regulatory proposals as inflection signal forcing compliance architecture redesigns and vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API ecosystem depth raises switching costs for registered investment advisor custody relationships. |
| Regulatory Sandbox Certification | SEBI framework unlocks controlled AI-driven advisory experimentation for India's affluent segment. |
| Strategic Partnership | Neobank embedded finance distribution captures deposits before capital migrates to standalone platforms. |
| Acquisition of Specialist Firm | Alternative data signal extraction capabilities offset quantitative risk modeling talent scarcity. |
| Geographic Expansion | EU AI Act compliance bifurcation creates architecture differentiation between European and United States deployments. |
Research Methodology
A spread of perspectives from chief technology officers at registered investment advisors, platform integration specialists, quantitative risk modeling leads, and neobank partnership directors converged on the working assumptions driving this analysis. These primary insights combined with secondary validation from SEC regulatory filings, SEBI sandbox announcements, EU AI Act implementation guidance, and hyperscaler cloud infrastructure disclosures. Bottom-up triangulation across advisory firm technology budgets and top-down reconciliation with custody platform revenue disclosures anchored the market sizing framework.
Segmentation dimensions modeled include service type automation level, client sophistication tier, technology application maturity, and regional regulatory framework cluster across the projection horizon. CAGRs derived from advisor firm formation rates, AUM migration patterns, and platform subscription pricing trajectories. Forecast inputs incorporated IRA tax incentive flow-through effects on ESG-aligned portfolio construction demand and generative AI capability deployment timelines.
The analysis sits within stated boundaries; outcomes outside sustained interest rate normalization, stable SEC fiduciary rule evolution, and cloud infrastructure cost curves would require recalibration. Forecasts reflect assumptions regarding regulatory sandbox expansion timelines and AI advisory engine compliance redesign scope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
Family Office Software for Financial Management Market
Wealth Management and Private Banking
Private Banking Market
Wealth Management and Private Banking
Wealth Management Market
Wealth Management and Private Banking
High Net Worth (HNW) Offshore Investment Market
Wealth Management and Private Banking
UK Pension Fund Market
Wealth Management and Private Banking
Asia Pacific Private Banking Market
Wealth Management and Private Banking
India Private Banking Market
Wealth Management and Private Banking
Wealth Management Software Market
Wealth Management and Private Banking
Latin America Wealth Management Market
Wealth Management and Private Banking
United States Private Banking Market
Wealth Management and Private Banking
Global Wealth Management Platform Market
Wealth Management and Private Banking
Europe Wealth Management Market
Wealth Management and Private Banking
MENA Wealth Management Market
Wealth Management and Private Banking
Family Office Services Market
Wealth Management and Private Banking
Japan Private Banking Market
Wealth Management and Private Banking
Asia Pacific Wealth Management Market