
 Latin America Wealth Management Market | 2026-2036
Latin America Wealth Management Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Wealth Management Market Foresight
Unbundling of traditional bundled private banking packages is hardening across Latin America as affluent clients demand modular service components rather than all-inclusive retainer structures. BTG Pactual leverages its boutique investment banking heritage to anchor ultra-high-net-worth relationships in São Paulo and Rio de Janeiro. Itaú Private Bank sustains dominance through its captive retail-to-private wealth pipeline across Brazilian state capitals. Citi Wealth Management competes by extending its cross-border dollar-denominated platform to Latin American families with Miami and New York connectivity.
Wealth management encompasses the professional discipline of preserving, growing, and transferring financial assets through structured investment vehicles, fiduciary oversight, and tax-optimized vehicles across jurisdictions. Practitioners deploy portfolio construction models incorporating local currency hedging, offshore trust structures, and alternative asset allocation to shield purchasing power from regional inflation volatility. The client type dimension shows high net worth individuals generating the deepest revenue pools while robo-advisory within the delivery model segment captures the fastest client acquisition velocity among digitally native professionals. Portfolio management under service type commands premium pricing due to performance-linked fee structures, whereas hybrid services increasingly displace pure personal advisor relationships in Mexico City and Bogotá metropolitan corridors.
Brazil's Comissão de Valores Mobiliários and Mexico's Comisión Nacional Bancaria y de Valores enforce suitability standards and transparency mandates that elevate compliance costs for foreign entrants. The central bank of Brazil's open banking regulations and Mexico's fintech law reshape data portability and client onboarding protocols across digital and hybrid channels. Stakeholders must monitor how regulatory divergence between Mercosur and Pacific Alliance frameworks affects cross-border product passporting and custody arrangements.
Market Dynamics
Open banking frameworks across Brazil and Mexico are dissolving traditional custody monopolies and forcing wealth managers to rebuild client acquisition around data portability rather than branch networks.
Growth Catalysts
- Central Bank Open Banking Mandates:Brazil's regulatory modernization forces incumbent private banks to share client financial data through standardized APIs, lowering switching costs and enabling fintech wealth platforms to onboard affluent clients with pre-populated portfolio analytics.
- Multigenerational Wealth Transfer:Family offices across São Paulo and Mexico City are consolidating advisory relationships around platforms offering integrated succession planning, driving demand for fiduciary structures that span local and Miami-domiciled assets.
- Offshore Dollar Diversification:High net worth individuals in Buenos Aires and Santiago are accelerating allocations to dollar-denominated custody arrangements as local currency hedging becomes central to purchasing power preservation.
Market Restraints
- Compliance Cost Escalation:Brazil's Comissão de Valores Mobiliários suitability standards and Mexico's fintech law transparency mandates impose overlapping audit requirements that consume 15-20% of operating budgets for foreign entrants building hybrid advisory models.
- Custody Infrastructure Fragmentation:Mercosur and Pacific Alliance regulatory divergence prevents seamless cross-border product passporting, forcing wealth managers to maintain parallel custody arrangements in São Paulo, Mexico City, and Miami for the same client relationship.
- Local Currency Volatility:Argentine peso and Brazilian real depreciation cycles compress fee revenue when translated to dollar reporting, discouraging global platforms from pricing services in local currency.
Strategic Opportunities
- Robo-Advisory Penetration in Colombia:Bogotá's digitally native professional segment remains underserved by automated portfolio construction tools, creating white space for hybrid models combining algorithmic allocation with periodic human oversight.
- Alternative Asset Democratization:Regulatory sandboxes in Mexico's fintech law are enabling fractional private equity and real estate exposure for mass-affluent investors previously excluded from closed-end fund structures.
- Cross-Border Succession Structuring:Miami's trust law convergence with Latin American forced heirship regimes allows wealth managers to capture intergenerational relationships by unifying U.S. and local jurisdiction estate planning.
Industry Challenges
- Certified Fiduciary Talent Scarcity:Brazil's CVM and Mexico's CNBV licensing requirements for investment advisors create 18-24 month onboarding timelines, constraining headcount expansion at foreign platforms entering through acquisition.
- Legacy Core System Integration:Established private banks in São Paulo and Rio de Janeiro operate on 1990s-era custody platforms that resist API connectivity, delaying real-time portfolio rebalancing for clients demanding mobile-first experiences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Wealth Management Market |
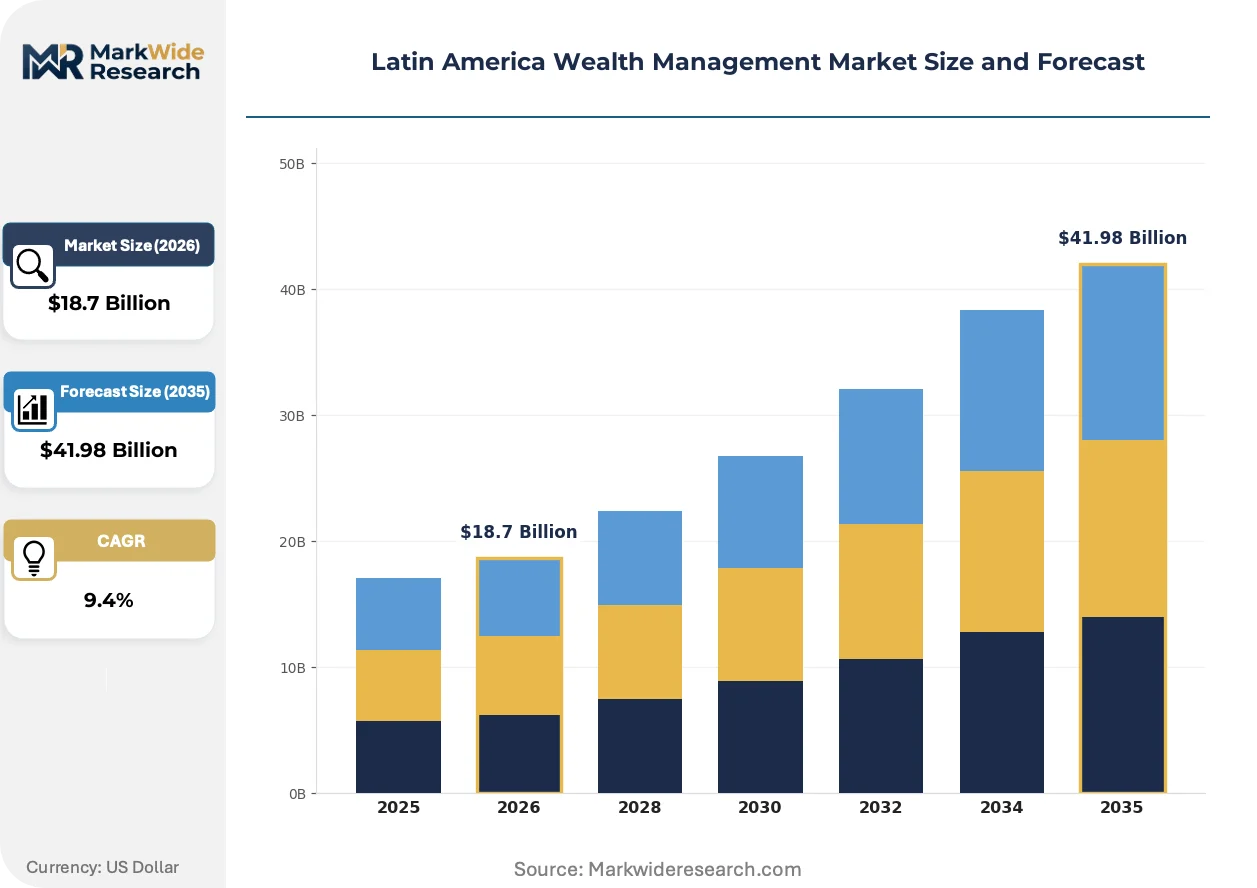
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Client Type: High Net Worth Individuals, Ultra High Net Worth Individuals, Corporations, Institutions Service Type: Investment Advisory, Estate Planning, Tax Consulting, Portfolio Management Delivery Model: Online Platforms, Personal Advisor, Robo-Advisors, Hybrid Services Investment Strategy: Alternative Investments, Equity Investments, Fixed Income Investments, Real Estate Investments |
| Companies Covered | Itaú Private Bank, UBS, BTG Pactual, BBVA Bancomer, Citi Wealth Management, Credit Suisse, Bradesco, 3G Capital, Morgan Stanley, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Wealth Management Market Shifts & Advancements
Digital onboarding protocols and modular service unbundling are compressing traditional relationship economics while elevating transparency as the primary competitive differentiator across Brazilian and Mexican wealth management.
Embedded finance architectures are electrifying client acquisition pathways by integrating investment account opening into payroll, lending, and insurance workflows. Retail banks across São Paulo and Mexico City are deploying white-labeled robo-advisory modules within existing mobile applications, collapsing the time from first login to first allocation from weeks to minutes. This convergence is compressing standalone wealth platform margins and forcing pure-play advisors to demonstrate performance alpha or migrate upmarket to ultra-high-net-worth segments.
Brazil's open banking regulations and Mexico's fintech law are mandating real-time data portability between financial institutions, eroding the information asymmetries that historically protected incumbent private banks. Wealth managers must now compete on algorithmic insight quality rather than exclusive access to client transaction histories. The regulatory pressure is most acute in São Paulo's metropolitan corridor, where digital-native competitors are leveraging standardized APIs to construct holistic financial pictures that span checking accounts, credit facilities, and investment holdings.
Affluent clients across Latin America are unbundling traditional all-inclusive retainer packages and purchasing portfolio management, tax optimization, and succession planning as discrete service modules. This procurement fragmentation rewards specialists with transparent fee schedules while penalizing bundled providers unable to demonstrate component-level value. The shift is most visible among family offices in Mexico City, where multigenerational wealth holders are retaining separate advisors for local custody, Miami trust structures, and alternative asset sourcing.
Latin America Wealth Management Market Segmentation
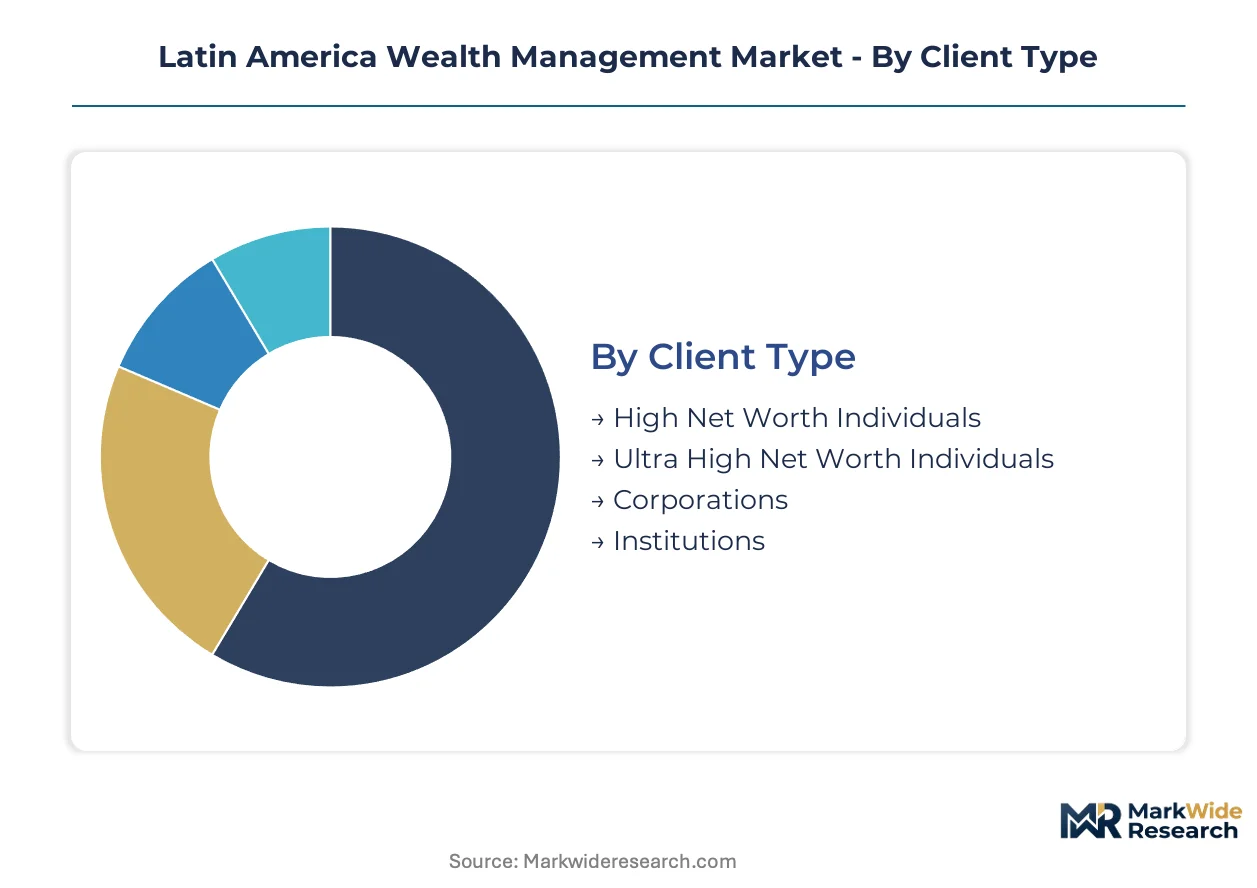
Segmentation in Latin American wealth management reveals how advisory services must adapt to divergent client sophistication levels, regulatory constraints, and digital readiness across São Paulo, Mexico City, and regional financial centers. Understanding these dimensions enables platforms to match service architecture with specific wealth holder expectations rather than deploying uniform offerings.
Client Type:
Wealth concentration and relationship complexity determine which client tiers absorb premium advisory capacity versus scalable digital solutions.
- High Net Worth Individuals:Clients with liquid assets between one million and thirty million dollars generate recurring revenue through multi-currency custody needs and Miami-connected trust structures. São Paulo's entrepreneurial class demands integrated local and offshore portfolio construction as currency hedging becomes central to wealth preservation.
- Ultra High Net Worth Individuals:Family offices and multigenerational wealth holders above thirty million dollars in assets command bespoke fiduciary oversight across forced heirship regimes and U.S. trust law convergence. Mexico City's established dynasties are consolidating relationships around platforms offering unified succession planning spanning local and Florida-domiciled assets.
- Corporations:Regional conglomerates and family-controlled enterprises require treasury management overlaying personal wealth with corporate liquidity optimization.
- Institutions:Pension funds, insurance carriers, and endowments seek institutional-grade custody with ESG integration and alternative asset access.
High Net Worth Individuals lead on scale; Ultra High Net Worth Individuals lead on momentum.
Service Type:
Fee structure transparency and performance attribution intensity separate commoditized offerings from premium advisory relationships.
- Portfolio Management:Active allocation across local and dollar-denominated instruments commands premium pricing through performance-linked fee structures. Brazil's CVM suitability standards elevate compliance costs for discretionary mandates, concentrating demand among São Paulo and Rio de Janeiro metropolitan corridors.
- Investment Advisory:Non-discretionary guidance on asset allocation and security selection serves clients retaining direct custody control. Mexico's fintech law transparency mandates are accelerating unbundling of advisory fees from product distribution commissions.
- Estate Planning:Succession structuring across local forced heirship and Miami trust jurisdictions captures intergenerational relationship value.
- Tax Consulting:Cross-border optimization between Latin American residence and U.S. or European domicile addresses reporting complexity.
Portfolio Management captures the steepest expansion trajectory as performance-linked pricing gains acceptance.
Delivery Model:
Digital onboarding velocity and human touch integration define competitive positioning across generational wealth holder preferences.
- Hybrid Services:Algorithmic portfolio construction combined with periodic human oversight is displacing pure personal advisor relationships in Mexico City and Bogotá metropolitan corridors. This model balances scalability with trust requirements for complex succession discussions.
- Robo-Advisors:Automated allocation engines with low minimums capture digitally native professionals previously excluded from private banking. Colombia's Bogotá corridor remains underserved, creating white space for platforms leveraging Brazil's open banking APIs for pre-populated onboarding.
- Personal Advisor:Dedicated relationship managers sustain dominance among Ultra High Net Worth Individuals requiring bespoke trust and alternative asset access.
- Online Platforms:Self-directed execution portals serve sophisticated investors with established allocation frameworks.
Hybrid Services lead on scale; Robo-Advisors are expanding most quickly among under-40 professionals.
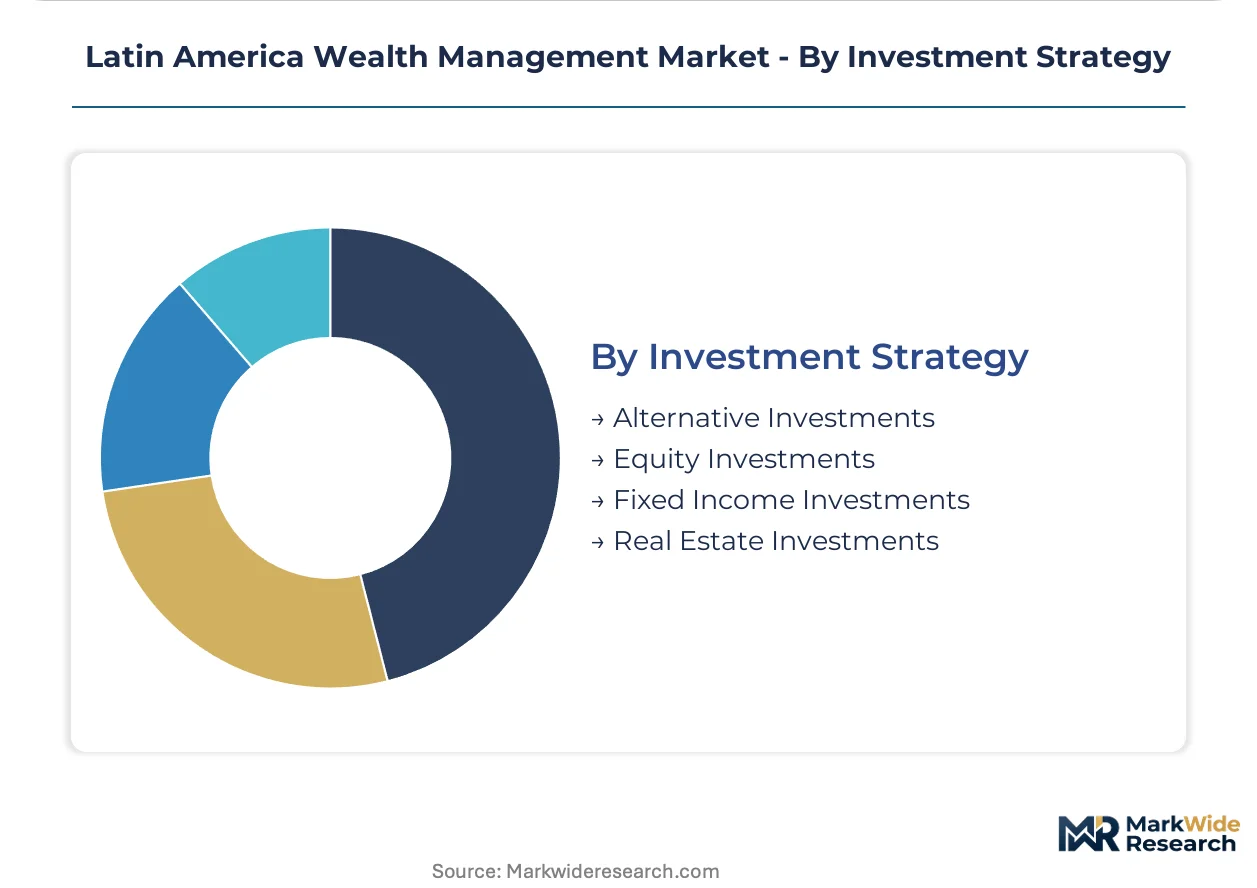
Investment Strategy:
Inflation hedging requirements and offshore diversification urgency reshape allocation preferences across local currency volatility cycles.
- Alternative Investments:Private equity, venture capital, and hedge fund exposure addresses return objectives unmet by public markets. Mexico's fintech law regulatory sandboxes are enabling fractional access for mass-affluent investors previously excluded from closed-end structures.
- Fixed Income Investments:Local currency sovereign and corporate debt requires active duration management as Brazilian real and Argentine peso depreciation cycles compress real returns. Dollar-denominated issuance from Latin American corporates concentrates demand in Miami custody arrangements.
- Equity Investments:Regional and U.S. listed securities form core liquid allocations for most advisory relationships.
- Real Estate Investments:Direct property and REIT exposure provides inflation linkage and local market familiarity.
Fixed Income Investments lead on scale; Alternative Investments gain share fastest as regulatory access barriers erode.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wealth management in Latin America traces its institutional roots to São Paulo's private banking expansion during Brazil's 1990s financial modernization, when international custody frameworks and dollar-denominated trust structures first scaled across the Southern Cone.
Brazil
Family offices and multigenerational wealth holders in São Paulo and Rio de Janeiro drive demand for integrated succession planning across local and Miami-domiciled assets. The Comissão de Valores Mobiliários enforces suitability standards that elevate compliance costs for discretionary mandates. BTG Pactual leverages its boutique investment banking heritage to anchor ultra-high-net-worth relationships in these metropolitan corridors.
Mexico
High net worth individuals in Mexico City deepen private banking penetration faster than elsewhere in the region, demanding modular service components rather than bundled retainer structures. The Comisión Nacional Bancaria y de Valores transparency mandates accelerate fee unbundling from product distribution commissions. BBVA Bancomer sustains market presence through its captive retail-to-private wealth pipeline across state capitals.
Argentina
Wealth holders in Buenos Aires accelerate allocations to dollar-denominated custody arrangements as peso depreciation cycles compress real returns on local currency holdings. The central bank's foreign exchange restrictions create parallel informal channels for offshore diversification. Family offices concentrate in Recoleta and Puerto Madero districts where Miami-connected trust structures dominate succession planning.
Chile
Santiago's entrepreneurial class demands currency hedging as central to purchasing power preservation amid real volatility. The country's pension fund regulator shapes institutional-grade custody standards that spill into private wealth infrastructure. Wealth managers cluster in Las Condes and Vitacura sub-markets serving families with cross-border succession requirements.
Colombia
Bogotá's digitally native professional segment remains underserved by automated portfolio construction tools, creating white space for hybrid advisory models. The financial superintendent's fintech sandbox provisions enable fractional alternative asset access for mass-affluent investors previously excluded from closed-end structures. Robo-advisory penetration lags regional peers, presenting acquisition opportunities for platforms leveraging Brazil's open banking APIs.
Latin America Wealth Management Market Competitive Landscape
Premium-margin players sit above commodity-margin players across advisory sophistication and cross-border structuring capability. Incumbent private banks defend position through captive retail pipelines and established custody relationships, while fintech platforms erode switching costs via open banking data portability. Three archetypes dominate: integrated universal banks with captive wealth divisions, boutique investment banking heritage firms, and international private banks with Miami-dollar connectivity. Competitive intensity concentrates on M&A to acquire licensed advisor headcount and technology licensing to modernize legacy core systems.
Within the integrated universal bank tier, Itaú Private Bank and Bradesco exemplify scale-driven positioning through retail-to-private wealth pipelines across Brazilian state capitals. BTG Pactual occupies a boutique specialist position anchored in São Paulo and Rio de Janeiro, leveraging investment banking heritage for ultra-high-net-worth relationships. On the international connectivity vector, Citi Wealth Management and UBS represent cross-border dollar-denominated platform providers serving Latin American families with Miami and New York custody arrangements.
| Leading Market Players |
|---|
| Itaú Private Bank |
| UBS |
| BTG Pactual |
| BBVA Bancomer |
| Citi Wealth Management |
| Credit Suisse |
| Bradesco |
| 3G Capital |
| Morgan Stanley |
| Others |
Supply & Pricing Matrix
Family offices and multigenerational wealth holders in São Paulo and Mexico City concentrate advisory purchasing power around performance-linked fee structures rather than traditional bundled retainers. This buyer archetype concentration elevates transparency demands and compresses margins for providers unable to demonstrate component-level value attribution.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Latin American wealth management. Premium tiers attach to ultra-high-net-worth relationships with bespoke fiduciary oversight and Miami-connected trust structures. Standard tiers serve high-net-worth individuals through hybrid advisory models. Economy tiers capture digitally native professionals via robo-advisory platforms. Price differentiation hinges on advisor certification level and cross-border structuring complexity. Pricing pressure stems from open banking mandates lowering client switching costs. Mass-affluent segments exhibit highest price sensitivity; family offices prioritize performance attribution over fee minimization.
Supply Chain Analysis
Licensed fiduciary talent supply rests on Brazilian and Mexican regulatory pipelines with 18-24 month onboarding timelines. Custody infrastructure draws from São Paulo, Mexico City, and Miami parallel arrangements necessitated by Mercosur-Pacific Alliance regulatory divergence. Technology inputs feed from open banking API providers and legacy core system modernizers. Single-source vulnerability concentrates in certified advisor headcount scarcity. Distribution runs through captive retail-to-private wealth pipelines, boutique investment banking heritage networks, and international private banking platforms with cross-border dollar connectivity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American wealth management represents a late-cycle quality story as affluent clients pivot toward modular service components with transparent performance attribution. This demand-shift favors platforms demonstrating algorithmic insight quality over information asymmetry advantages.
For Market Incumbents: Acquire licensed advisor headcount to offset CVM and CNBV onboarding bottlenecks constraining expansion velocity. Consolidate technology licensing partnerships to modernize 1990s-era custody platforms resisting API connectivity. Defensive positioning requires deepening captive retail pipelines against fintech platforms leveraging open banking data portability. Vertical integration into Miami trust law capabilities protects ultra-high-net-worth relationships from cross-border specialists. For New Entrants and Emerging Players: Enter via Bogotá's digitally native professional segment where robo-advisory penetration lags regional peers. Target Colombia's mass-affluent investors through hybrid models combining algorithmic allocation with periodic human oversight. Mexico's fintech law regulatory sandboxes enable fractional alternative asset access as a differentiated go-to-market angle. White space exists in cross-border succession structuring unifying local forced heirship with Florida trust jurisdictions. For Investors and Strategic Acquirers: Boutique investment banking heritage firms with São Paulo and Rio de Janeiro presence are the most active acquirer category in this space. Long-term viability over the coming decade depends on capturing intergenerational relationships through integrated succession planning capabilities. Acquisition target archetypes include hybrid advisory platforms with open banking API integration and licensed advisor teams. Watch regulatory divergence between Mercosur and Pacific Alliance frameworks as an inflection indicator for custody infrastructure consolidation needs.| Strategic Initiative | Industry Significance |
|---|---|
| Licensed Advisor Acquisition | Brazil's CVM and Mexico's CNBV onboarding timelines create scarcity value for credentialed headcount. |
| Open Banking API Integration | Real-time data portability erodes incumbent information asymmetries and elevates algorithmic competition. |
| Miami Trust Law Capability Buildout | Cross-border succession structuring captures intergenerational relationships from Latin American family offices. |
| Hybrid Advisory Model Launch | Algorithmic construction with human oversight penetrates Bogotá's underserved digitally native segment. |
| Legacy Core System Modernization | API connectivity enables real-time portfolio rebalancing demanded by mobile-first client experiences. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged private banking executives, wealth management technology officers, regulatory compliance leads at CVM and CNBV, and family office principals across São Paulo, Mexico City, and Bogotá. Secondary validation drew from central bank open banking disclosures, securities commission suitability filings, fintech law regulatory texts, and cross-border trust law documentation. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Historical reference periods anchored projections across the analysis window to establish baseline adoption curves for digital onboarding protocols and modular service unbundling. The analytical framework modeled client type, service type, delivery model, and investment strategy dimensions alongside regulatory framework clusters. CAGRs were derived from trajectory fitting across open banking penetration curves and wealth transfer velocity patterns. Forecast inputs incorporated central bank regulatory modernization timelines and multigenerational wealth holder behavioral shifts.
Inputs from primary stakeholder interviews and secondary regulatory filings were available through the study window; gaps in real-time custody infrastructure cost data introduce uncertainty bands around hybrid advisory platform margin projections. Forecasts reflect documented assumptions regarding open banking API standardization pace and Miami trust law convergence with Latin American forced heirship regimes. Regulatory divergence between Mercosur and Pacific Alliance frameworks, local currency depreciation cycle severity, and certified fiduciary talent pipeline expansion warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
Family Office Services Market
Wealth Management and Private Banking
Digital Wealth Management Market
Wealth Management and Private Banking
Europe Wealth Management Market
Wealth Management and Private Banking
Wealth Management Market
Wealth Management and Private Banking
Wealth Management Software Market
Wealth Management and Private Banking
India Private Banking Market
Wealth Management and Private Banking
Asia Pacific Private Banking Market
Wealth Management and Private Banking
Global Wealth Management Platform Market
Wealth Management and Private Banking
Asia Pacific Wealth Management Market
Wealth Management and Private Banking
Family Office Software for Financial Management Market
Wealth Management and Private Banking
United States Private Banking Market
Wealth Management and Private Banking
UK Pension Fund Market
Wealth Management and Private Banking
High Net Worth (HNW) Offshore Investment Market
Wealth Management and Private Banking
Private Banking Market
Wealth Management and Private Banking
Family Offices Market
Wealth Management and Private Banking
Smart Wealth Management Market