
 Tax Compliance Services Market | 2026-2036
Tax Compliance Services Market Size, Share, and Industry Trends Forecast 2026-2036
Tax Compliance Services Market Insights
Modular bundling of tax preparation with audit support and reporting management is realigning how enterprises procure compliance capabilities. Thomson Reuters leverages its information infrastructure to anchor premium positioning in integrated workflow solutions. Deloitte competes through deep specialization in cross-border transfer pricing and OECD Pillar Two implementation. Intuit sustains dominance among small businesses via intuitive cloud-based filing interfaces and embedded advisory tools.
Tax compliance services encompass the systematic preparation, validation, and submission of tax obligations to governmental authorities, incorporating automated data extraction from ERP systems, real-time jurisdiction rule updates, and defensible documentation for audit defense. Cloud-based deployment leads structural growth as enterprises prioritize scalable API connectivity with existing financial stacks, while subscription pricing captures the largest margin pool through predictable recurring revenue and lower customer acquisition costs. On-premise solutions retain traction among large corporations with stringent data residency requirements.
The OECD's Pillar Two framework, the US IRS digital reporting mandates, and the EU's DAC7 directive on platform taxation collectively expand compliance scope and service complexity for multinational enterprises. These regulatory layers elevate demand for real-time jurisdictional monitoring and automated nexus detection capabilities. Stakeholders must evaluate whether captive in-house tax technology investments or outsourced managed compliance partnerships offer superior risk-adjusted returns as rule velocity accelerates.
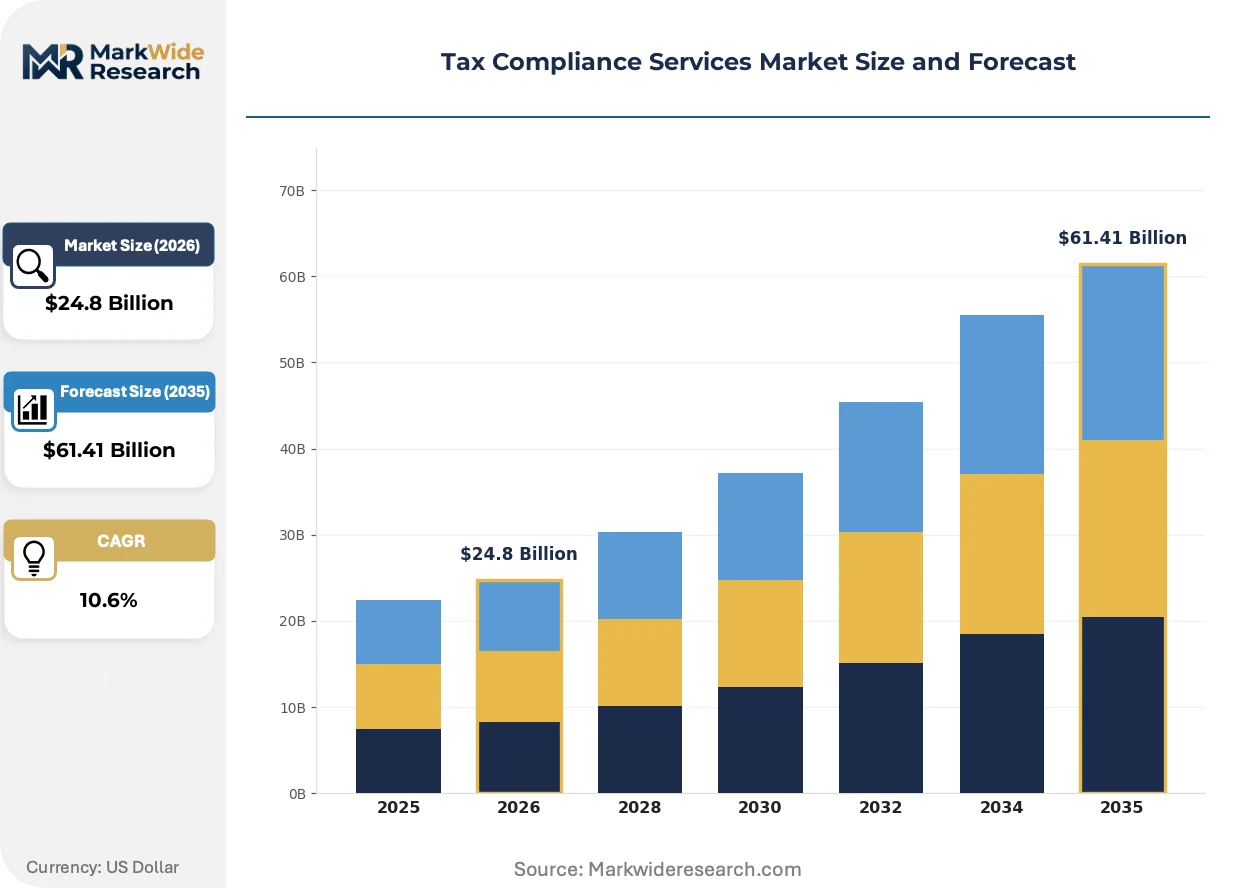
Market Dynamics
The OECD's Pillar Two global minimum tax framework is forcing multinational enterprises to reconstruct compliance architectures around real-time jurisdictional monitoring and automated nexus detection capabilities.
Growth Catalysts
- OECD Pillar Two Implementation:The global minimum tax framework mandates new calculation methodologies and disclosure requirements, expanding service scope for cross-border compliance providers.
- API-First Cloud Deployment:Scalable connectivity with ERP systems enables mid-sized enterprises to access enterprise-grade compliance infrastructure without captive technology investments.
- State Nexus Proliferation:US state-level economic nexus rules continue multiplying post-Wayfair, generating recurring demand for multi-jurisdictional filing automation.
Market Restraints
- Specialized Talent Scarcity:Cross-border tax technologists with both regulatory expertise and systems integration skills command premium compensation, compressing margins for service providers.
- Data Residency Requirements:Large corporations in Germany, France, and Switzerland maintain stringent on-premise mandates, limiting cloud-native vendor addressable markets.
- Regulatory Velocity:The EU's DAC7 directive and evolving US IRS digital reporting mandates force continuous platform reinvestment, shortening amortization periods for compliance technology.
Strategic Opportunities
- Mid-Market Penetration:Enterprises with 500-5,000 employees remain underserved by both Big Four advisory and basic software, creating white space for modular managed services.
- Embedded Advisory Convergence:Machine learning is automating anomaly detection within filing workflows, enabling real-time advisory insertion at transaction points rather than annual cycles.
- India Regulatory Expansion:The country's central bank and securities regulator are tightening cross-border transaction reporting, opening demand for localized compliance infrastructure.
Industry Challenges
- Legacy System Integration:ERP heterogeneity across client technology stacks fragments implementation pathways and extends deployment timelines.
- Certification Lag:Professional credentialing bodies have not standardized tax technology competencies, creating hiring friction and quality variance across delivery teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tax Compliance Services Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $61.41 Billion |
| CAGR (2026 – 2036) | 10.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Tax Preparation, Audit Support, Tax Filing, Consulting, Reporting Management End User: Small Businesses, Mid-Sized Enterprises, Large Corporations, Nonprofit Organizations, Government Agencies Deployment Model: Cloud-Based, On-Premise, Hybrid, Outsourced, In-House Pricing Model: Subscription, Per-Transaction, Fixed Fee, Usage-Based, Value-Based |
| Companies Covered | Avalara, Vertex, Wolters Kluwer, Thomson Reuters, ADP, Intuit, PwC, Deloitte, Ernst & Young, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tax Compliance Services Market Trends and Innovations
Computational tax engines are displacing manual interpretation workflows, while regulatory fragmentation accelerates demand for jurisdiction-agnostic platform architectures.
Machine learning is automating document classification and data extraction from unstructured source materials including invoices, contracts, and cross-border payment records. Mid-sized enterprises in the United States and United Kingdom are adopting these capabilities fastest, driven by IRS and HMRC digital filing mandates. The technology is automating routine preparation tasks and compressing headcount ratios within compliance functions.
The EU's DAC7 directive on platform taxation extends reporting obligations to digital marketplace operators, capturing seller transaction data previously outside tax authority visibility. This regulatory layer forces platform companies to build or acquire specialized compliance infrastructure. Marketplace operators in Germany, France, and the Netherlands are responding through partnerships with specialized tax technology vendors rather than captive development.
Subscription pricing models are displacing per-filing transaction structures across buyer segments. Large enterprises favor predictable annual commitments with embedded advisory hours, while mid-market buyers prefer modular tiered access scaled to entity count. This shift is most visible in the United States, where state filing volume variability makes fixed-cost structures attractive for multi-jurisdictional businesses.
Tax Compliance Services Market Segmentation
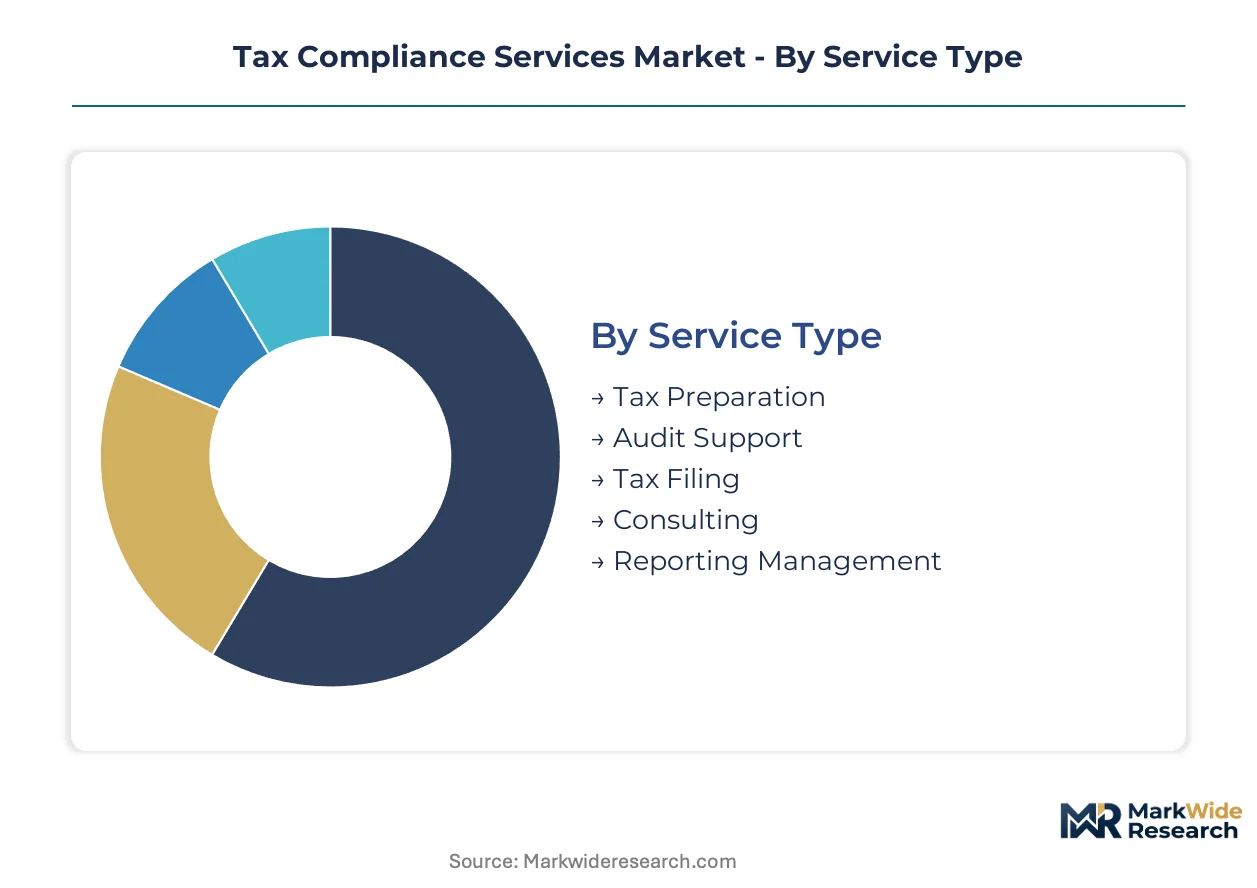
Tax compliance services fragment across service delivery modes, customer scale, and pricing architectures. Each segment carries distinct certification burdens and technology requirements that reshape procurement patterns.
Service Type:
Certification intensity varies sharply across service types, with audit defense and cross-border consulting demanding professional licensure that preparation and filing services often bypass.
- Tax Preparation:Automated data extraction from ERP systems and real-time rule updates dominate this segment. Small businesses in the United States concentrate demand here, driven by IRS digital filing mandates and penalty avoidance.
- Audit Support:Defensible documentation workflows and regulatory correspondence management define this high-stakes category. Large corporations facing OECD Pillar Two scrutiny are expanding audit defense retainers as jurisdictional complexity intensifies.
- Tax Filing:Multi-jurisdictional submission automation with jurisdiction-specific formatting requirements.
- Consulting:Strategic advisory on transfer pricing, nexus optimization, and regulatory change management.
- Reporting Management:Continuous disclosure obligations including DAC7 platform taxation and state-level economic nexus tracking.
Leading the category by volume: Tax Preparation. Growing fastest: Audit Support.
End User:
Customer scale determines service bundling depth, with mid-sized enterprises representing the most contested white space between basic software and Big Four advisory.
- Mid-Sized Enterprises:Organizations with 500-5,000 employees face acute talent scarcity for cross-border tax technologists. These buyers are adopting API-first cloud solutions fastest, prioritizing scalable connectivity without captive technology investments.
- Large Corporations:Stringent data residency requirements in Germany, France, and Switzerland sustain on-premise solution demand. These entities favor predictable annual subscriptions embedding advisory hours for OECD Pillar Two implementation.
- Small Businesses:Intuitive cloud-based interfaces with embedded advisory tools capture this price-sensitive segment.
- Nonprofit Organizations:Specialized exemption maintenance and unrelated business income tracking.
- Government Agencies:Public sector procurement of compliance infrastructure and audit capabilities.
Highest absolute spend: Large Corporations. Steepest expansion trajectory: Mid-Sized Enterprises.
Deployment Model:
Technology stack heterogeneity fragments implementation pathways, with ERP integration complexity extending deployment timelines for hybrid and on-premise configurations.
- Cloud-Based:Scalable API connectivity with existing financial stacks anchors this segment's structural growth. Mid-market buyers across the United States and United Kingdom are migrating here fastest, compelled by HMRC and IRS digital mandates.
- On-Premise:Captive infrastructure for stringent data residency requirements persists among German, French, and Swiss large corporations. Regulatory velocity around EU DAC7 and evolving IRS rules forces continuous platform reinvestment, shortening technology amortization periods.
- Hybrid:Sensitive data on-premise with scalable processing in cloud environments.
- Outsourced:Managed compliance partnerships transferring operational burden to specialized providers.
- In-House:Captive technology investments and dedicated tax technology teams.
Dominant architecture: Cloud-Based. Gaining share fastest: Hybrid.
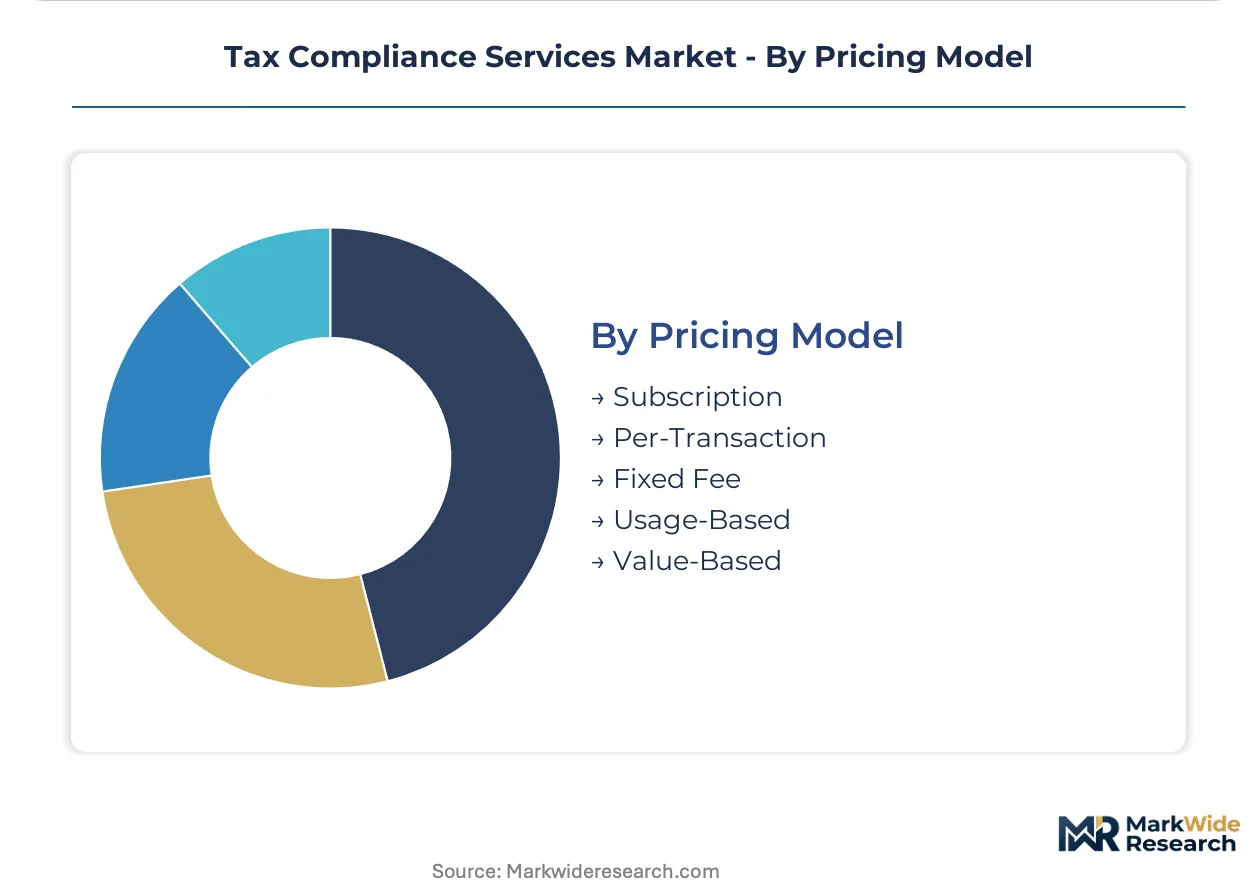
Pricing Model:
Revenue predictability and customer acquisition economics drive pricing architecture shifts, with subscription models capturing the largest margin pool through lower churn and embedded expansion revenue.
- Subscription:Predictable recurring revenue with modular tiered access scaled to entity count. This structure attracts multi-jurisdictional US businesses managing state filing volume variability through fixed-cost commitments.
- Value-Based:Outcome-linked fees tied to tax savings, penalty avoidance, or regulatory risk reduction. Sophisticated large corporations are piloting these arrangements for complex cross-border restructuring and OECD Pillar Two implementation projects.
- Per-Transaction:Filing-volume-linked pricing common in basic preparation services.
- Fixed Fee:Project-based engagements for discrete compliance events.
- Usage-Based:Consumption-metered access to computational tax engines and automated workflows.
Largest margin capture: Subscription. Expanding most quickly: Value-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tax compliance services concentrate consumption in the United States while production capabilities distribute across Western Europe and North American technology hubs. Service delivery models diverge sharply by jurisdiction, with cloud-native platforms dominating Anglo-Saxon markets and on-premise solutions persisting in continental European financial centers.
United States
State-level economic nexus proliferation post-Wayfair generates sustained demand for multi-jurisdictional filing automation. IRS digital reporting mandates accelerate cloud migration among mid-sized enterprises. New York and San Francisco anchor the largest concentrations of tax technology vendors and advisory practices.
Germany
Stringent data residency requirements sustain on-premise solution demand among large corporations in banking and automotive sectors. The Federal Financial Supervisory Authority enforces transaction reporting standards that elevate compliance complexity. Frankfurt and Munich host the densest clusters of specialized tax technology implementation firms.
United Kingdom
HMRC's Making Tax Digital initiative compels small and mid-sized enterprises toward API-first cloud compliance platforms. Post-Brexit regulatory divergence from EU frameworks creates parallel reporting obligations for cross-border traders. London concentrates both Big Four advisory presence and emerging fintech compliance challengers.
India
The Reserve Bank of India and Securities and Exchange Board of India tighten cross-border transaction reporting requirements for foreign portfolio investors. Goods and Services Tax complexity sustains demand for automated reconciliation and filing support. Mumbai and Bangalore emerge as primary hubs for compliance technology development and service delivery.
France
The country's national tax authority mandates real-time invoice reporting through the Chorus Pro platform, forcing enterprise system upgrades. DAC7 platform taxation rules capture marketplace operator data previously outside visibility. Paris anchors the largest concentration of EU-focused transfer pricing advisory capacity.
Tax Compliance Services Market Competitive Landscape
The competitive structure tilts toward information-anchored technology platforms with professional advisory networks layered atop. Consolidation pressures concentrate around workflow integration capabilities and jurisdictional rule update velocity. Three archetypes dominate: ERP-embedded calculation engines, standalone cloud compliance suites, and Big Four advisory technology hybrids. Strategic moves center on API ecosystem expansion and mid-market channel partnerships.
Within the information infrastructure tier, Thomson Reuters and Wolters Kluwer occupy positions defined by regulatory content depth and workflow integration. Deloitte and PwC exemplify the advisory-technology hybrid model, embedding proprietary calculation engines within client service relationships. Avalara and Vertex represent the cloud-native specialist archetype, anchoring subscription-based automation for multi-jurisdictional filers.
| Leading Market Players |
|---|
| Avalara |
| Vertex |
| Wolters Kluwer |
| Thomson Reuters |
| ADP |
| Intuit |
| PwC |
| Deloitte |
| Ernst & Young |
| Others |
Pricing and Supply Chain Analysis
Mid-sized enterprise procurement consolidation around API-first cloud platforms is compressing implementation timelines and forcing vendors to absorb upfront integration costs, which in turn compresses margin structures and accelerates subscription pricing adoption across the competitive landscape.
Pricing Analysis
Margin tightening in audit defense and cross-border consulting reflects specialized talent scarcity and OECD Pillar Two certification requirements. Pricing stratifies across premium advisory tiers anchored by Big Four firms, mid-market SaaS subscriptions, and economy self-service software for small businesses. Cost-down pressure on mid-market bundles accelerates because buyers demand predictable fixed-cost structures amid US state nexus proliferation. Small businesses exhibit highest price sensitivity, while large corporations facing Pillar Two scrutiny prioritize risk mitigation over cost minimization.
Supply Chain Analysis
Professional credentialing requirements for cross-border tax technologists create supply gating that fragments service delivery capacity across jurisdictions. Talent concentration rests on the United States, the United Kingdom, and India, with regulatory expertise clustering in New York, London, and Mumbai. Service delivery draws from cloud infrastructure providers, ERP integration specialists, and jurisdiction-specific content databases. Single-source vulnerability concentrates around real-time rule update engines for OECD and EU regulatory frameworks. Distribution runs through direct enterprise sales, channel partnerships with accounting firms, and API marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational tax engines are displacing manual interpretation workflows, creating a technology-transition phase where legacy service providers must rearchitect delivery models or surrender share to cloud-native automation platforms.
For Market Incumbents: Lock in mid-market relationships through embedded advisory convergence and API ecosystem expansion before specialized tax technology vendors capture workflow integration points. Deepen proprietary calculation engine development for OECD Pillar Two implementation to defend against Big Four advisory-technology hybrids. Prioritize certification investment in cross-border transfer pricing expertise as regulatory velocity accelerates.
For New Entrants and Emerging Players: Begin with modular managed services targeting the 500-5,000 employee white space between basic software and Big Four advisory, where talent scarcity creates acute buyer pain. Penetrate fastest through partnerships with regional accounting firms lacking in-house tax technology capabilities. Anchor go-to-market around real-time nexus detection for US state-level economic nexus proliferation.
For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native compliance platforms possessing jurisdiction-agnostic architectures given API-first deployment acceleration and subscription revenue predictability. Long-term viability favors vendors with embedded machine learning capabilities for anomaly detection and transaction-point advisory insertion. Monitor IRS digital reporting mandate enforcement velocity and EU DAC7 implementation timelines as inflection indicators for demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Enables seamless ERP connectivity for mid-market buyers facing state nexus complexity. |
| Machine Learning Platform Development | Automates anomaly detection and enables real-time advisory insertion at transaction points. |
| Regulatory Content Acquisition | Secures jurisdiction-specific rule update velocity critical for OECD Pillar Two compliance. |
| Mid-Market Channel Partnership | Penetrates the 500-5,000 employee segment through regional accounting firm alliances. |
| Hybrid Deployment Architecture | Addresses German, French, and Swiss data residency requirements while capturing cloud scalability. |
Research Methodology
Document review covered regulatory filings from the IRS, OECD, and EU tax authorities, complemented by interviews with tax technology vendors, Big Four advisory partners, and mid-market enterprise CFOs. Primary fieldwork engaged compliance officers at multinational corporations, implementation specialists at ERP providers, and procurement leads at accounting firms. Secondary sources included SEC filings from publicly traded compliance vendors, HMRC implementation guidance, and DAC7 technical specifications. Bottom-up sizing triangulated against top-down macroeconomic projections.
Cross-referencing historical adoption curves with expert panel input anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, customer scale, deployment architecture, and pricing structure. CAGRs derived from regression analysis against regulatory mandate timelines and cloud migration velocity. Industry-specific forecast inputs incorporated OECD Pillar Two implementation schedules and US state nexus rule proliferation rates.
Underlying measurement precision varies by segment; cloud-based deployment and subscription pricing carry tighter precision than on-premise and value-based arrangements due to vendor disclosure practices. Forecasts reflect assumptions around regulatory enforcement consistency and technology adoption curves. Stakeholders should weight assumptions against their own operating context and jurisdictional exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Accounting Software Market
Accounting and Taxation Services
Corporate Tax Service Market
Accounting and Taxation Services
Italy Forensic Accounting Market
Accounting and Taxation Services
South Africa Forensic Accounting Market
Accounting and Taxation Services
Italy Accounting Software Market
Accounting and Taxation Services
Europe Forensic Accounting Market
Accounting and Taxation Services
Tax Advisory Services Market
Accounting and Taxation Services
Europe Auditing Services Market
Accounting and Taxation Services
UK Forensic Accounting Market
Accounting and Taxation Services
Japan Accounting Software Market
Accounting and Taxation Services
South Korea Accounting Software Market
Accounting and Taxation Services
Sales Tax Software Market
Accounting and Taxation Services
Germany Forensic Accounting Market
Accounting and Taxation Services
France Accounting Software Market
Accounting and Taxation Services
Australia Accounting Software Market
Accounting and Taxation Services
Trust Accounting Software Market