
 Stacked CMOS Image Sensor Market | 2026-2036
Stacked CMOS Image Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Stacked CMOS Image Sensor Market Outlook
Japanese foundry capacity for backside-illuminated wafer processing is shifting toward 300mm lines dedicated to stacked architectures. Sony Semiconductor Solutions leverages captive fab capacity to sustain leadership in high-resolution mobile sensors. Samsung Electronics anchors supply for automotive-grade devices with in-house through-silicon via integration. OmniVision Technologies competes aggressively in the medical endoscopy segment through specialized low-noise pixel designs.
Stacked CMOS image sensors vertically integrate photodiode arrays atop logic wafers using copper-to-copper hybrid bonding, achieving pixel pitches below 0.7 micrometers with full-well capacities exceeding 30,000 electrons. This architecture enables simultaneous high-speed readout and advanced on-chip computational imaging for real-time scene analysis. Color sensors dominate volume shipments to consumer electronics OEMs, while Near Infrared variants capture expanding margin pools in biometric authentication and driver monitoring systems. Hybrid wafer bonding technology leads capital deployment as manufacturers push for sub-micron alignment precision at wafer scale.
FDA device classification rules for diagnostic imaging equipment shape pixel reliability standards and traceability requirements in medical applications. EPA hazardous substance restrictions influence material selection for sensor packaging and interconnect metallization. The EU AI Act's conformity assessment framework for high-risk embedded vision systems creates new compliance thresholds for automotive and surveillance deployments. Stakeholders must monitor evolving export control classifications for advanced packaging equipment and assess captive versus outsourced wafer bonding strategies before capacity commitments crystallize.
Market Dynamics
Hybrid wafer bonding equipment shortages are compressing capacity expansion timelines as automotive OEMs demand automotive-grade pixel reliability. South Korea's Pyeongtaek cluster concentrates advanced packaging investment while Japanese foundries retool 300mm lines.
Growth Catalysts
- EU AI Act conformity assessment:Embedded vision system certification creates dedicated demand for traceable sensor supply chains in autonomous vehicle programs.
- Through-silicon via integration:Copper-to-copper hybrid bonding enables sub-0.7 micrometer pixel pitches with full-well capacities exceeding 30,000 electrons.
- Medical endoscopy:FDA device classification rules for diagnostic imaging equipment mandate pixel reliability standards that favor stacked architectures.
Market Restraints
- Equipment concentration:Advanced wafer bonder supply concentrates among Japanese and Dutch capital equipment vendors, creating 18-24 month lead times.
- Copper interconnect volatility:Hybrid bonding metallization costs fluctuate with refined copper spot markets and specialized sputtering target availability.
- EPA hazardous substance restrictions:Sensor packaging material selection faces compliance constraints on lead-free solder alternatives and mold compound formulations.
Strategic Opportunities
- Near Infrared variants:Biometric authentication and driver monitoring systems capture expanding margin pools beyond commodity color sensors.
- India PLI scheme:Electronics manufacturing incentives attract camera module assembly investment for smartphone OEM supply diversification.
- Computational imaging convergence:On-chip AI acceleration merges with photodiode arrays to enable real-time scene analysis without external processing.
Industry Challenges
- Sub-micron alignment talent:Wafer-scale bonding precision requires specialized process engineers scarce outside established semiconductor clusters.
- Multi-jurisdiction certification:Simultaneous FDA, EU MDR, and NMPA device approvals extend time-to-revenue for medical imaging sensor launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stacked CMOS Image Sensor Market |
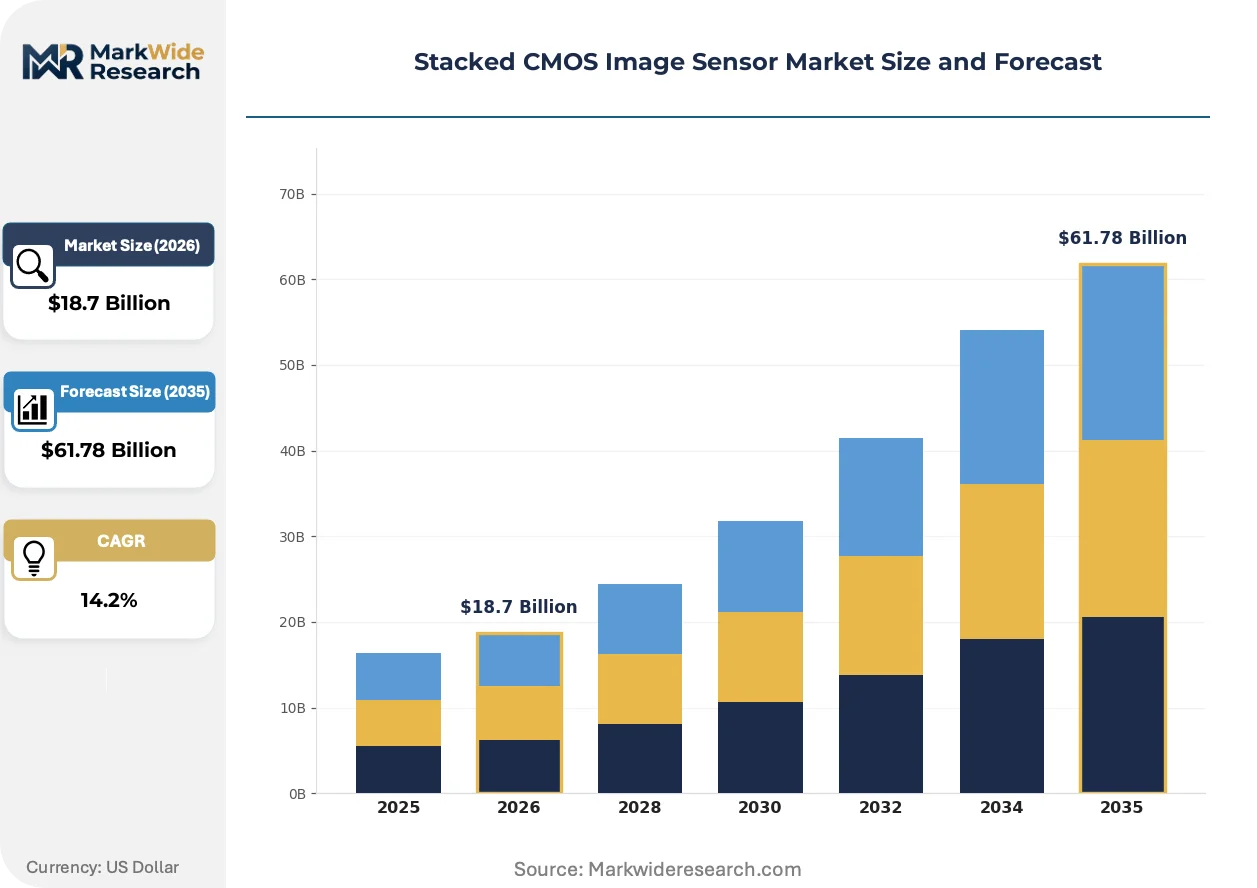
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monochrome, Color, Near Infrared, Thermal Application: Consumer Electronics, Automotive, Surveillance, Medical Imaging Technology: 3D Integration, Hybrid Wafer Bonding, Advanced Packaging, Dicing End User: OEMs, Tier-1 Suppliers, System Integrators, Aftermarket Providers |
| Companies Covered | SK Hynix, ON Semiconductor, Sony Semiconductor Solutions, GalaxyCore, Canon, Samsung Electronics, STMicroelectronics, Panasonic, OmniVision Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stacked CMOS Image Sensor Market Strategic Shifts
Copper-to-copper hybrid bonding is displacing conventional microbump interconnects as the dominant stacking methodology. This shift compresses pixel pitch limits while elevating capital intensity requirements across the supply base.
Hybrid bonding is expanding into automotive-grade sensor production as Tier-1 suppliers demand full-well capacity above 30,000 electrons for HDR scene capture. German and Japanese automotive OEMs specify this architecture for next-generation surround-view camera modules. The technology is expanding into foundry service offerings previously reserved for captive integrated device manufacturers.
The EU AI Act's algorithmic transparency requirements are reshaping sensor certification protocols for high-risk embedded vision deployments. Conformity assessment frameworks now mandate documented pixel-to-decision traceability in autonomous driving systems. Automotive suppliers in Germany and France are pre-qualifying sensor vendors against these thresholds ahead of mandatory enforcement.
Smartphone OEMs now specify outcome-based sensor performance guarantees rather than discrete component procurement. This compresses supplier margins while transferring yield risk to sensor vendors. South Korean and Chinese handset manufacturers lead this contractual evolution, with Apple and Google suppliers following in subsequent negotiation cycles.
Stacked CMOS Image Sensor Market Segmentation
Stacked CMOS image sensor procurement diverges sharply across end-use verticals, with automotive qualification cycles and consumer electronics refresh rates driving fundamentally different specification requirements. Understanding these segment boundaries clarifies where hybrid bonding investments concentrate versus where commodity color sensors dominate shipment volumes.
Product Type:
Upgrade cycles vary dramatically by spectral sensitivity, with monochrome and Near Infrared sensors demanding fresh capital equipment while color sensors ride existing mobile handset refresh patterns.
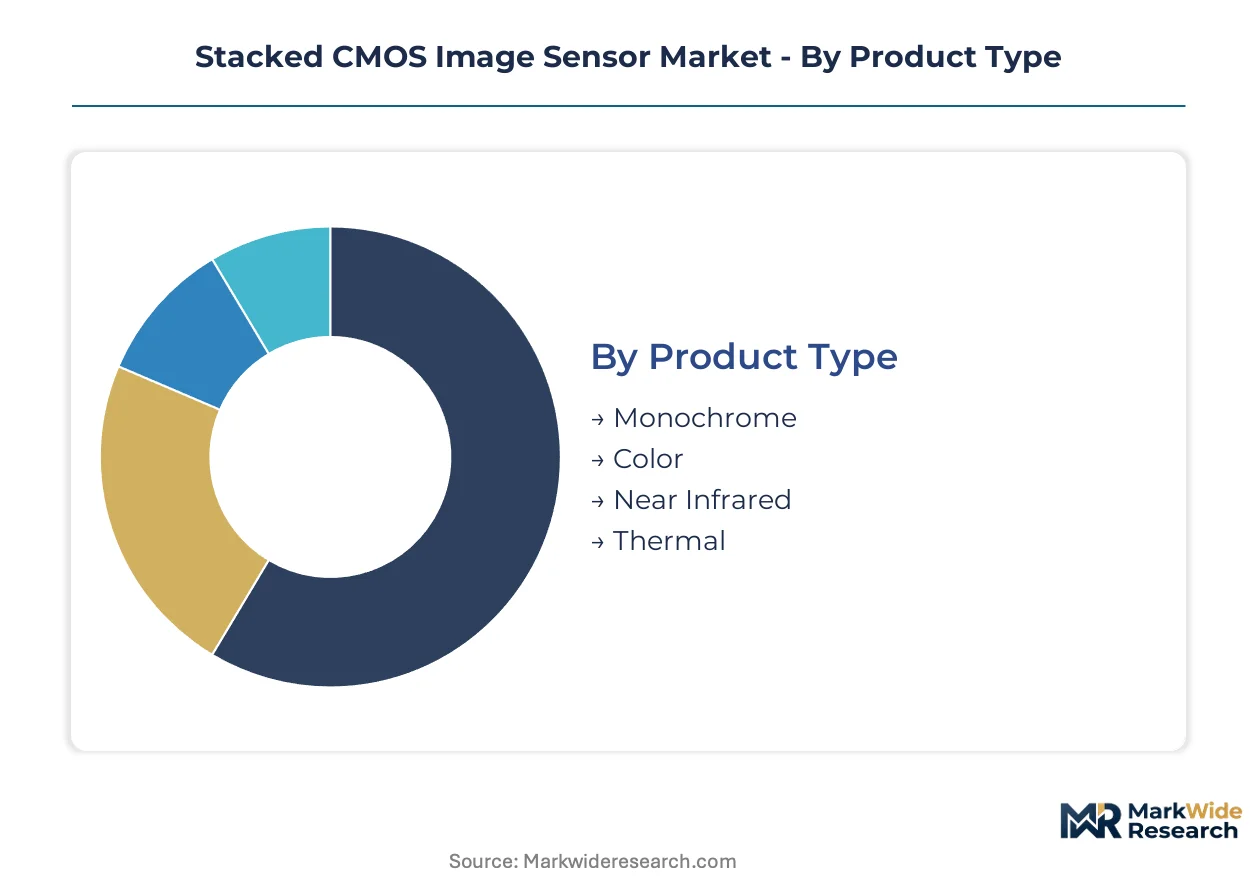
- Color:Dominates consumer electronics procurement through sub-0.7 micrometer pixel architectures with full-well capacities exceeding 30,000 electrons. South Korean smartphone OEMs anchor volume demand, though outcome-based performance guarantees now compress supplier margins.
- Near Infrared:Captures expanding margin pools in biometric authentication and driver monitoring systems with specialized photodiode arrays tuned for 700-1000 nanometer wavelengths. German automotive OEMs specify these for next-generation surround-view camera modules.
- Monochrome:Serves computational imaging pipelines requiring maximum quantum efficiency without Bayer filter attenuation.
- Thermal:Addresses radiometric measurement applications in industrial automation and fever screening deployments.
Color sits at the top of the volume ranking, with Near Infrared climbing the fastest.
Application:
Cost tiers separate automotive-grade qualification from consumer electronics procurement, with medical imaging commanding premium pricing for traceable pixel reliability.
- Automotive:Tier-1 suppliers demand copper-to-copper hybrid bonding for HDR scene capture above 30,000 electrons full-well capacity. EU AI Act conformity assessment mandates documented pixel-to-decision traceability for autonomous driving systems.
- Consumer Electronics:Smartphone OEMs specify outcome-based sensor performance guarantees rather than discrete component procurement, transferring yield risk to vendors.
- Surveillance:Requires continuous operation reliability with extended temperature tolerance for outdoor deployment.
- Medical Imaging:FDA device classification rules mandate pixel reliability standards and traceability requirements that favor stacked architectures in diagnostic equipment.
Consumer Electronics maintains volume leadership, while Automotive shows the steepest expansion trajectory.
Technology:
Supply concentration determines access, with hybrid wafer bonding equipment shortages compressing capacity expansion timelines across all end-use categories.
- Hybrid Wafer Bonding:Copper-to-copper interconnects achieve sub-micron alignment precision at wafer scale, displacing conventional microbump methodologies. Japanese and Dutch capital equipment vendors concentrate supply, creating 18-24 month lead times for new installations.
- 3D Integration:Vertically stacks photodiode arrays atop logic wafers to enable simultaneous high-speed readout and on-chip computational imaging.
- Advanced Packaging:Encompasses mold compound selection constrained by EPA hazardous substance restrictions on lead-free solder alternatives.
- Dicing:Separates bonded wafers into individual die with minimal edge chipping for high-yield module assembly.
Hybrid Wafer Bonding commands the dominant share of capital deployment, with 3D Integration gaining share fastest in automotive qualification programs.
End User:
Customer type dictates contract structure, with OEMs transferring yield risk downstream while Tier-1 suppliers absorb qualification costs for automotive-grade certification.
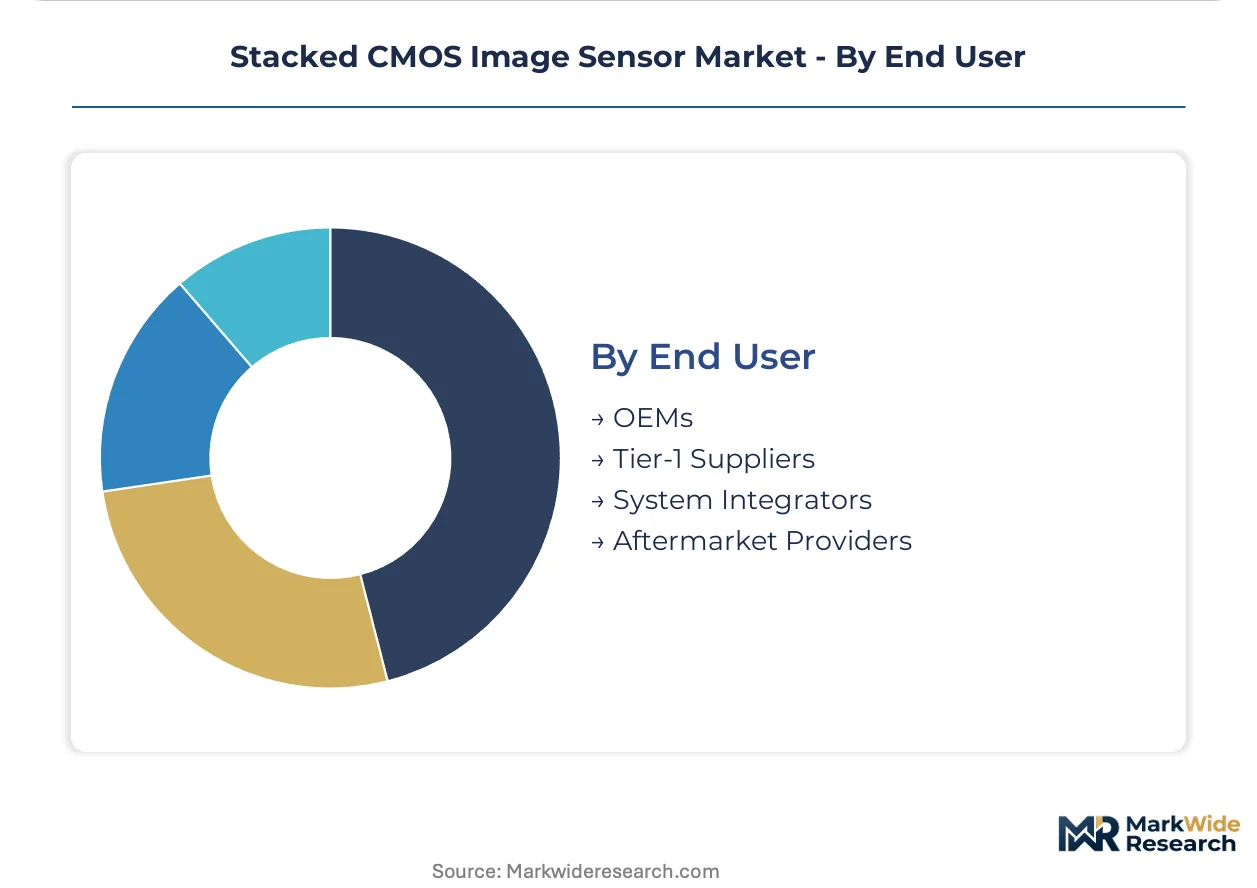
- OEMs:Smartphone manufacturers in South Korea and China lead outcome-based procurement evolution, with Apple and Google suppliers following in subsequent negotiation cycles.
- Tier-1 Suppliers:German and Japanese automotive component manufacturers pre-qualify sensor vendors against EU AI Act thresholds ahead of mandatory enforcement.
- System Integrators:Bundle sensors into complete vision systems for surveillance and industrial automation deployments.
- Aftermarket Providers:Serve replacement demand in legacy automotive camera modules and refurbished medical imaging equipment.
OEMs represent the largest addressable base, with Tier-1 Suppliers expanding most quickly through autonomous vehicle program wins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production toward jurisdictions with favorable compliance costs for advanced packaging. South Korea and Japan concentrate captive fab capacity, while China's domestic qualification programs and India's assembly incentives reshape regional competitive positioning.
South Korea
Automotive-grade sensor demand from Hyundai and Kia supply chains drives qualification investments. The Ministry of Trade, Industry and Energy (METI-equivalent industrial policy) channels subsidies through the K-Semiconductor Belt initiative. Pyeongtaek's semiconductor cluster hosts Samsung Electronics' expanded hybrid bonding lines for through-silicon via integration.
Japan
Mobile handset OEM procurement and medical imaging equipment exports sustain foundry utilization. The Ministry of Economy, Trade and Industry (METI) coordinates 300mm line retooling subsidies under the Semiconductor and Digital Industry Strategy. Kumamoto and Hiroshima prefectures concentrate Sony Semiconductor Solutions' backside-illuminated wafer processing capacity.
China
Domestic smartphone brands and surveillance system integrators absorb volume production from local packaging houses. The National Medical Products Administration (NMPA) device classification rules for diagnostic imaging equipment shape pixel reliability standards. Yangtze River Delta clusters in Shanghai and Suzhou concentrate GalaxyCore and emerging hybrid bonding foundry services.
United States
Automotive Tier-1 supplier qualification programs and medical device OEM procurement anchor demand for traceable supply chains. FDA device classification rules for diagnostic imaging equipment mandate pixel reliability documentation. Arizona and Texas semiconductor corridors attract ON Semiconductor and OmniVision Technologies packaging investments for proximity to North American OEMs.
Germany
BMW, Mercedes-Benz, and Volkswagen surround-view camera module specifications drive automotive-grade sensor procurement. The EU AI Act's conformity assessment framework for high-risk embedded vision systems mandates documented pixel-to-decision traceability. Bavaria's automotive electronics corridor hosts pre-qualification testing for sensor vendors targeting autonomous driving programs.
Stacked CMOS Image Sensor Market Competitive Environment
Japanese and South Korean producers anchor the premium-tier captive fab segment; Chinese specialists hold volume-driven foundry positions. Market structure tilts toward consolidation at the bleeding-edge node while mid-range color sensors fragment across second-tier packaging houses. Three archetypes dominate: vertically integrated IDMs with captive copper-to-copper bonding capacity, fabless designers outsourcing to hybrid wafer bonding foundries, and diversified conglomerates leveraging internal demand. Capacity expansion and strategic technology licensing represent the primary competitive vectors.
Within the IDM archetype, Sony Semiconductor Solutions and Samsung Electronics exemplify full-stack control from photodiode arrays through logic wafer integration. ON Semiconductor occupies a position bridging automotive qualification expertise with outsourced packaging partnerships. These three anchors demonstrate how geographic concentration in East Asian semiconductor clusters shapes competitive positioning without requiring identical business model configurations.
| Leading Market Players |
|---|
| SK Hynix |
| ON Semiconductor |
| Sony Semiconductor Solutions |
| GalaxyCore |
| Canon |
| Samsung Electronics |
| STMicroelectronics |
| Panasonic |
| OmniVision Technologies |
| Others |
Value Chain & Pricing Dynamics
Automotive-grade certification tiers bifurcate sharply from consumer electronics procurement, with EU AI Act conformity assessment costs propagating through Tier-1 supplier contracts while smartphone OEMs compress margins through outcome-based performance guarantees. This divergence concentrates premium pricing power among captive fab operators in South Korea and Japan, while commoditized color sensors fragment across second-tier packaging houses in China's Yangtze River Delta.
Pricing Analysis
Distributor margins on hybrid wafer bonding equipment compress as Japanese and Dutch capital equipment vendors enforce direct-to-fab procurement for 300mm line installations. Three-tier pricing stratifies across automotive-grade, medical-grade, and consumer-grade certification levels, with FDA and EU MDR traceability requirements commanding substantial premiums. Pricing pressure stems from copper interconnect volatility in refined spot markets and specialized sputtering target availability constraints. Smartphone OEMs in South Korea exhibit highest price sensitivity, while German automotive OEMs absorb qualification premiums for autonomous driving program compliance.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers, with backside-illumination processing chemicals drawing from concentrated Kyushu manufacturing corridors. Raw material dependencies span copper sputtering targets, high-purity silicon wafers, and lead-free solder alternatives constrained by EPA hazardous substance restrictions. Single-source vulnerability concentrates in advanced wafer bonder equipment from Japanese and Dutch vendors, creating procurement bottlenecks for capacity expansion. Distribution runs through direct OEM relationships for automotive and medical tiers, while consumer electronics channels leverage contract manufacturers in India PLI scheme zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stacked CMOS image sensor demand compounds steadily through automotive camera module proliferation and medical imaging equipment refresh cycles, with hybrid bonding technology diffusion sustaining multi-year expansion.
For Market Incumbents: To counter equipment concentration risk among Japanese and Dutch capital equipment vendors, Sony Semiconductor Solutions and Samsung Electronics should deepen captive fab utilization through 300mm line retooling subsidies coordinated with METI and K-Semiconductor Belt initiatives. Securing multi-year copper sputtering target offtake agreements insulates against refined spot market volatility.
For New Entrants and Emerging Players: Specialized low-noise pixel designs for medical endoscopy represent the most penetrable white-space target, with FDA device classification rules favoring stacked architectures that incumbent IDMs underweight. GalaxyCore and emerging Chinese foundries should leverage Yangtze River Delta packaging clusters to offer hybrid bonding services previously reserved for captive integrated device manufacturers, targeting domestic smartphone brands and surveillance system integrators with cost-competitive through-silicon via integration.
For Investors and Strategic Acquirers: Consolidation pressure builds where automotive-grade qualification expertise overlaps with outsourced packaging partnerships, creating acquisition opportunities for mid-cap specialists bridging Tier-1 supplier relationships with hybrid wafer bonding foundry access. The inflection signal to monitor is EU AI Act enforcement timing, which will accelerate pre-qualification investments and strand non-compliant vendor relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Wafer Bonding Capacity Expansion | Captive 300mm line investment in Pyeongtaek and Kumamoto secures sub-micron alignment precision for automotive qualification programs. |
| Copper Sputtering Target Backward Integration | Upstream control over refined copper supply chains mitigates hybrid bonding metallization cost volatility from spot market fluctuations. |
| EU AI Act Conformity Pre-Qualification | Documented pixel-to-decision traceability investment ahead of mandatory enforcement locks in German and French automotive OEM supply positions. |
| Near Infrared Spectral Variant Development | 700-1000 nanometer photodiode arrays capture biometric authentication and driver monitoring margin pools beyond commodity color sensors. |
| India PLI Scheme Camera Module Assembly | Electronics manufacturing incentives attract smartphone OEM supply diversification away from concentrated East Asian packaging corridors. |
Study Parameters
Coverage spans South Korea, Japan, China, the United States, and Germany, with primary inputs from each market triangulated against secondary validation. Semiconductor process engineers, Tier-1 supplier procurement directors, medical device regulatory affairs leads, and smartphone OEM component strategists contributed primary perspectives. Secondary sources include FDA device classification filings, EU AI Act conformity assessment documentation, METI and K-Semiconductor Belt policy disclosures, SEC 10-K filings from listed sensor vendors, and customs records for hybrid wafer bonding equipment imports. Bottom-up capacity and utilization estimates reconcile with top-down demand aggregation across automotive, consumer electronics, medical imaging, and surveillance end-use verticals.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon, with segmentation modeling across product type, application, technology, and end user dimensions. Automotive-grade pixel reliability standards, FDA traceability requirements, and EU AI Act algorithmic transparency thresholds inform qualification timeline assumptions. CAGRs derive from installed base growth, replacement cycle compression, and content-per-vehicle increases in surround-view camera modules. Copper spot market trajectories and advanced wafer bonder equipment lead times constitute industry-specific forecast inputs.
The model holds under stable regulatory enforcement timelines and continued hybrid bonding technology diffusion; deviation in EU AI Act implementation schedules or export control expansion for advanced packaging equipment would shift capacity expansion trajectories. A small set of triggers—automotive OEM platform standardization decisions, NMPA device approval reciprocity agreements, and India PLI scheme renewal terms—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
High-Resolution 3D X-Ray Microscopy Market
Imaging
Pico Projector Market
Imaging
Ent Cameras Market
Imaging
Event Camera Market
Imaging
Global CMOS Image Sensors Market
Imaging
Infrared Laser Night Vision Devices Market
Imaging
Industrial Machine Vision Market
Imaging
Photoconductor Drums Market
Imaging
Instant Digital Cameras Market
Imaging
Photoacoustic Tomography Market
Imaging
Computational Photography Market
Imaging
Pan-Tilt-Zoom (PTZ) Camera Market
Imaging
Machine Vision System Market
Imaging
Digital Image Processing Market
Imaging
Industrial X-Ray Inspection Equipment and Imaging Software Market
Imaging
X-Ray Market