
 Smart Thermometer Market | 2026-2036
Smart Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Thermometer Market Outlook
Clinical-grade accuracy certification is rotating toward the center of procurement decisions for connected temperature devices. Braun GmbH leverages its heritage in precision sensor engineering to sustain premium positioning across European hospital networks. Kinsa Inc. competes through population health data partnerships that anchor its public health surveillance footprint. Omron Corporation differentiates via integrated blood pressure-temperature ecosystems that extend its home diagnostics dominance.
A smart thermometer is a digital temperature measurement instrument incorporating wireless connectivity protocols, MEMS thermal sensors, and cloud-enabled data logging with precision typically within ±0.1°C. These devices transmit readings to mobile health platforms for trend analysis, medication timing, and caregiver alerts in both consumer wellness and clinical triage environments. Infrared product types lead volume due to non-contact hygiene protocols in hospital settings, while wearable segments capture the fastest expansion as continuous monitoring replaces episodic measurement. Bluetooth technology occupies the largest installed base, though cloud-based architectures are concentrating margin pools through recurring software subscription models.
FDA 510(k) clearance requirements and EU MDR conformity assessments shape product development timelines and channel access for smart thermometer manufacturers seeking clinical credibility. HIPAA in the United States and GDPR in Europe impose data governance obligations on cloud-connected temperature platforms that handle protected health information. Stakeholders must monitor evolving cybersecurity labeling requirements from regulators as connected diagnostic devices face heightened scrutiny over breach vulnerabilities and algorithmic transparency.
Market Dynamics
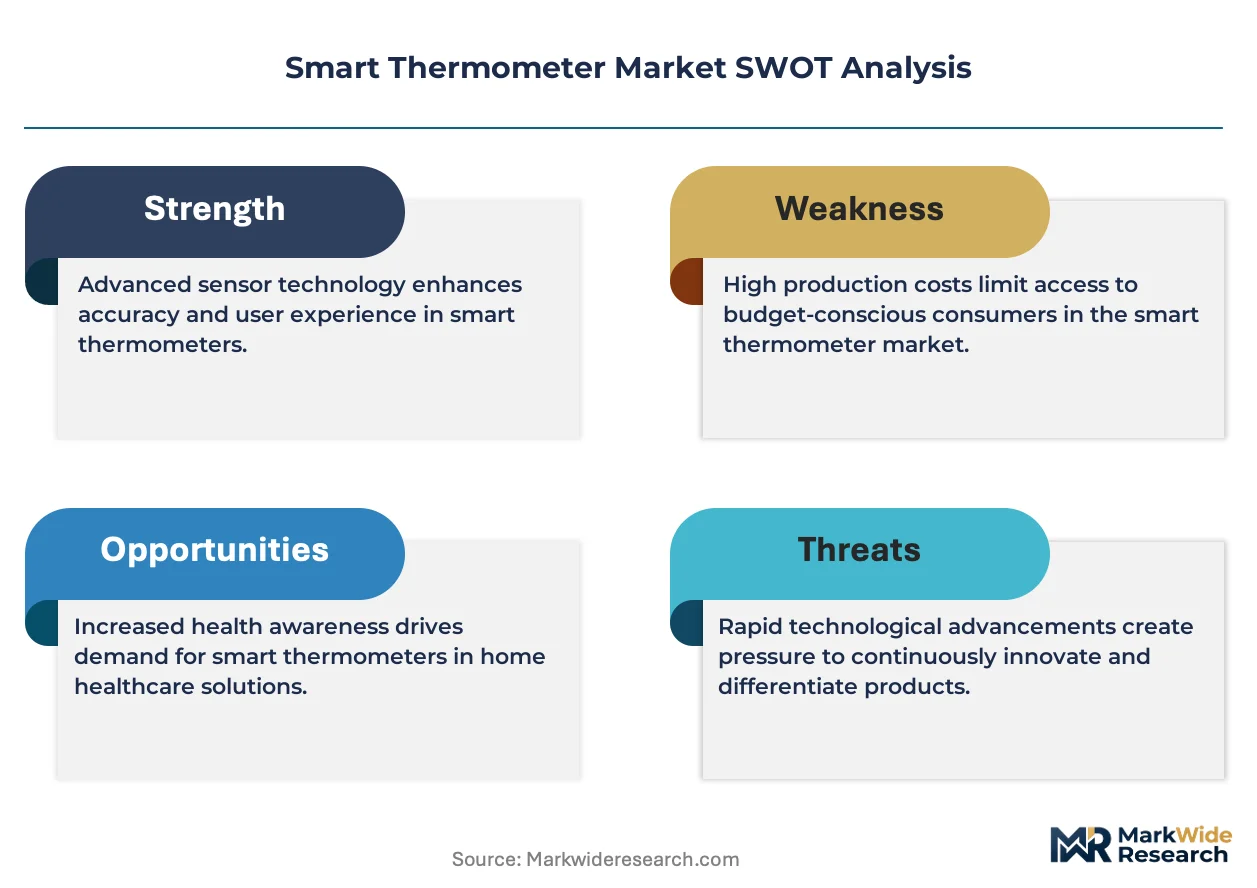
Clinical-grade accuracy requirements are tightening procurement specifications for connected temperature devices, forcing manufacturers to prioritize MEMS sensor calibration and wireless protocol certification over cost reduction.
Growth Catalysts
- Home-based patient monitoring:Chronic disease management programs in the United States, Germany, and Japan are digitizing temperature protocols, creating institutional demand for cloud-connected devices.
- FDA 510(k) streamlining:Expedited clearance pathways for connected health devices are compressing commercialization timelines and reducing regulatory friction for new entrants.
- Bluetooth Low Energy:This wireless protocol is anchoring the largest installed base of smart thermometers, enabling seamless mobile health platform integration without Wi-Fi dependency.
Market Restraints
- MEMS thermal sensor supply concentration:Precision sensor fabrication depends on a limited number of East Asian foundries, exposing manufacturers to geographic supply risk.
- GDPR compliance costs:European data governance obligations impose substantial infrastructure investments on cloud-connected platforms handling protected health information.
- Non-contact infrared accuracy limits:Ambient temperature interference and emissivity variation constrain clinical deployment of infrared devices in precision-critical settings.
Strategic Opportunities
- Wearable continuous monitoring:Episodic measurement replacement is accelerating in post-surgical recovery and pediatric sleep monitoring applications.
- EU MDR harmonization:Streamlined conformity assessments across European member states are reducing multi-market certification redundancy for connected diagnostic devices.
- Population health data partnerships:Aggregated anonymized temperature trend data is creating recurring revenue streams through public health surveillance contracts.
Industry Challenges
- Cybersecurity certification timelines:Evolving FDA and EMA labeling requirements for breach vulnerability disclosure are extending product launch schedules.
- Algorithmic transparency demands:Regulators in the United States and Europe are requiring explainable AI documentation for fever detection algorithms, complicating machine learning deployment.
- Legacy health system integration:Hospital IT infrastructure heterogeneity forces costly custom API development for electronic health record connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Thermometer Market |
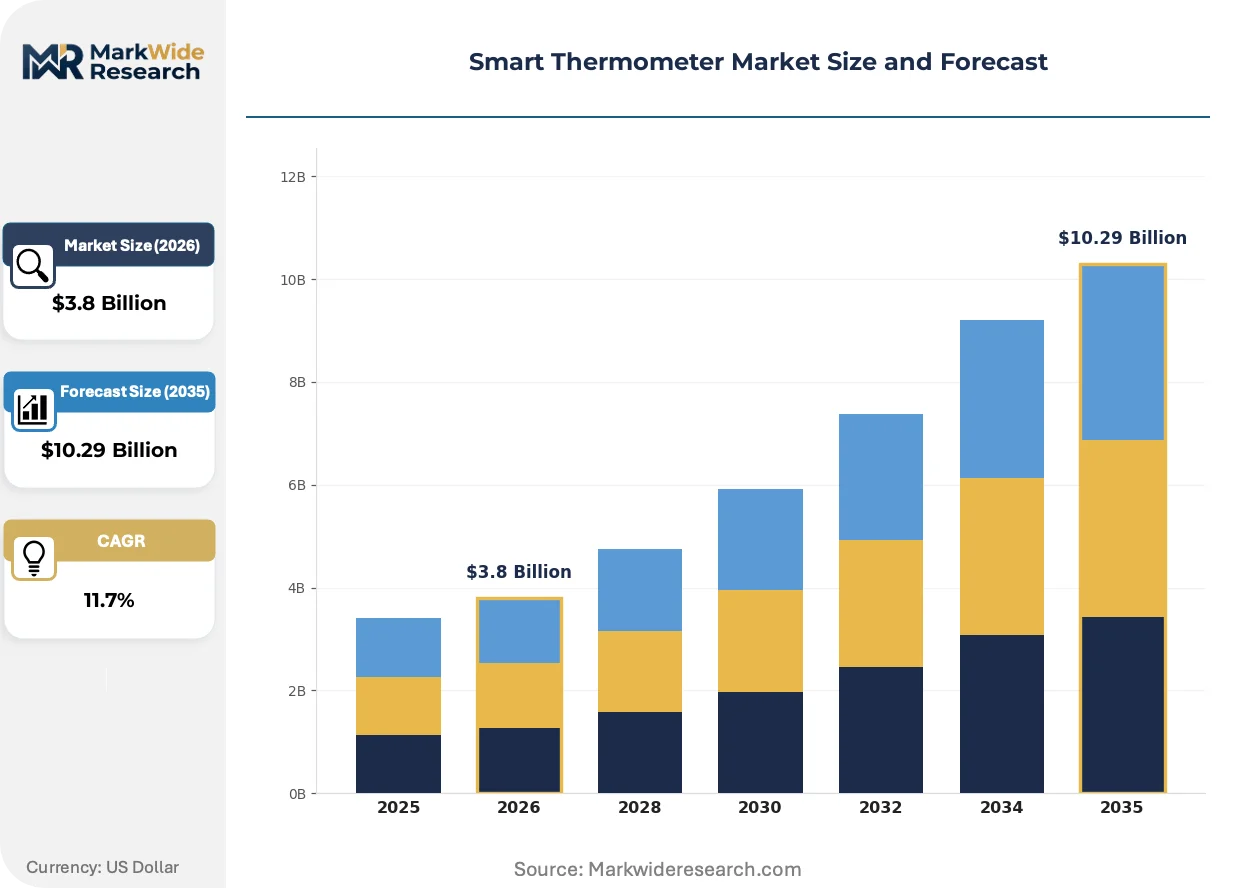
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared, Digital, Wearable, Smart Band End User: Home Users, Hospitals, Clinics, Laboratories Technology: Bluetooth, Wi-Fi, NFC, Cloud-Based Distribution Channel: Online Retail, Pharmacies, Supermarkets, Direct Sales |
| Companies Covered | Braun GmbH, iHealth Labs, Exergen Corporation, Withings, Microlife Corporation, Kinsa Inc., Omron Corporation, Welch Allyn, Testo SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Thermometer Market Strategic Shifts
Sensor miniaturization and edge computing are converging to enable continuous temperature monitoring without patient compliance friction, reshaping competitive differentiation around data analytics rather than hardware accuracy alone.
Multi-spectral infrared arrays are fragmenting the non-contact thermometer category. These sensors capture thermal radiation across multiple wavelengths to compensate for emissivity variation and ambient interference. Hospital infection control departments in the United States and Germany are piloting these devices for triage screening. The technology is fragmenting procurement decisions by introducing calibration complexity that favors vendors with in-house sensor engineering capabilities.
EU MDR Article 10 post-market surveillance requirements are mandating systematic clinical follow-up data collection for connected diagnostic devices. Manufacturers must now maintain active vigilance systems rather than passive complaint monitoring. Wearable thermometer segments face the steepest compliance burden, as continuous data generation multiplies adverse event reporting obligations.
Subscription-based software monetization is displacing hardware-centric revenue models. Cloud-enabled trend analysis, medication timing algorithms, and caregiver alert systems now generate recurring revenue streams that exceed device margins. This shift is most visible in United States consumer wellness channels, where direct-to-consumer brands bundle hardware with annual analytics subscriptions.
Smart Thermometer Market Segmentation
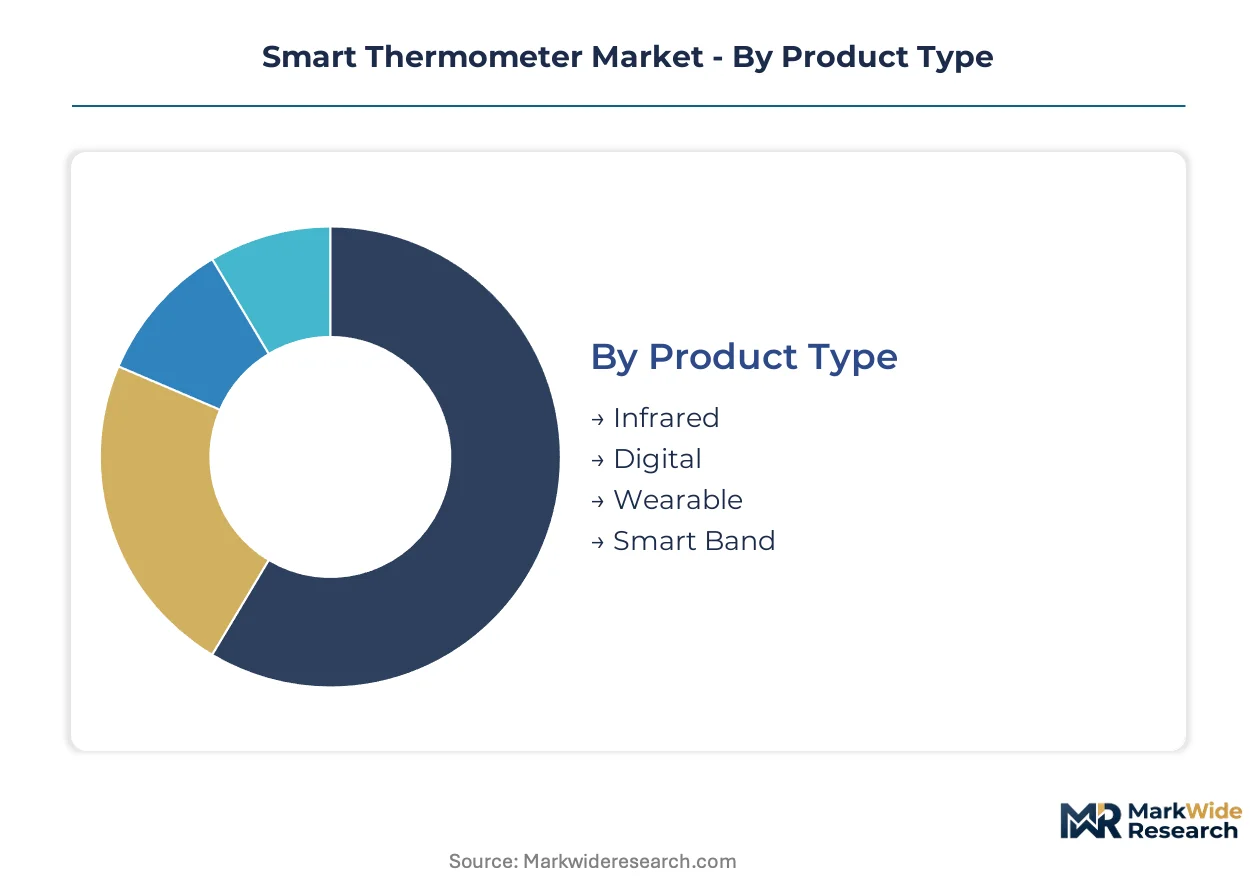
Smart thermometer segmentation reveals divergent channel strategies across product architectures. Infrared and wearable formats command premium positioning through hospital procurement, while Bluetooth-enabled devices saturate consumer retail. Technology choices determine margin structure, with cloud-based platforms capturing recurring software revenue against one-time hardware sales.
Product Type:
Hospital networks and direct-to-consumer channels split procurement flows across contact and non-contact formats, with infection control protocols driving institutional specification.
- Infrared:Non-contact thermal sensors measure surface radiation across multiple wavelengths, enabling triage screening without patient contact. Hospital infection control departments in the United States and Germany specify these for emergency department intake, though ambient temperature interference constrains precision-critical deployment.
- Wearable:Continuous skin-contact patches and adhesive sensors enable longitudinal temperature tracking without compliance friction. Post-surgical recovery programs and pediatric sleep monitoring in Japan concentrate demand, replacing episodic measurement with uninterrupted data streams.
- Digital:Traditional probe-based thermometers with wireless connectivity modules serve price-sensitive home diagnostics segments.
- Smart Band:Multi-sensor wrist-worn devices integrate temperature with activity and sleep metrics for wellness applications.
Infrared dominates installed base across clinical procurement. Wearable formats are where expansion concentrates.
End User:
Customer type determines regulatory burden and pricing power, with institutional buyers demanding FDA 510(k) clearance while consumers prioritize convenience.
- Home Users:Direct-to-consumer channels bundle hardware with subscription analytics, generating recurring revenue through medication timing algorithms and caregiver alert systems.
- Hospitals:Enterprise procurement specifications mandate MEMS sensor calibration certificates and wireless protocol compliance, anchoring premium pricing tiers.
- Clinics:Outpatient facilities balance accuracy requirements against capital constraints, favoring mid-range infrared devices with cloud connectivity.
- Laboratories:Research and reference laboratories require traceable calibration chains for protocol validation and regulatory submission support.
Hospitals anchor volume concentration. Home users are climbing the fastest.
Technology:
Wireless protocol selection shapes integration complexity and data governance obligations across deployment environments.
- Bluetooth:Low Energy protocols anchor the largest installed base, enabling seamless mobile health platform integration without Wi-Fi dependency in home and clinic settings.
- Cloud-Based:Architectures concentrate margin pools through recurring software subscriptions, with trend analysis and predictive fever detection generating revenue exceeding hardware margins.
- Wi-Fi:Direct internet connectivity supports hospital IT infrastructure integration, though cybersecurity certification timelines extend product launch schedules.
- NFC:Near-field pairing enables rapid device association for episodic measurement workflows in pharmacy and retail environments.
Bluetooth dominates installed base. Cloud-based architectures are gaining share fastest.
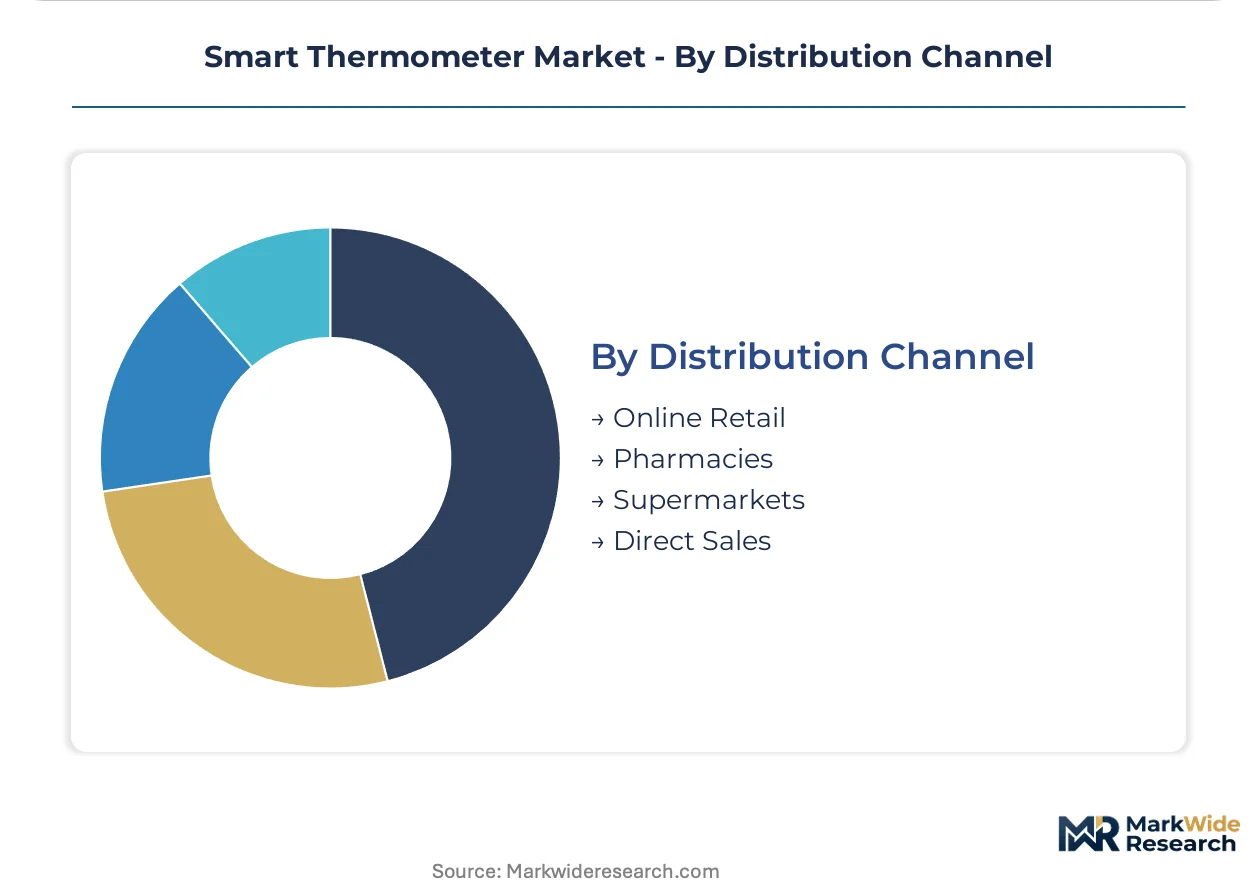
Distribution Channel:
Channel selection reflects customer acquisition cost tradeoffs and regulatory documentation requirements across geographic markets.
- Online Retail:Direct-to-consumer platforms enable subscription bundling and population health data partnerships, concentrating in United States wellness markets.
- Pharmacies:Brick-and-mortar drugstore chains provide clinical credibility and immediate availability for acute symptom management purchases.
- Supermarkets:Mass merchandisers capture price-sensitive demand through promotional placement and seasonal illness surge inventory.
- Direct Sales:Hospital and health system contracting teams negotiate enterprise procurement with custom API development for electronic health record connectivity.
Online retail dominates installed base. Direct sales is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor net importers in emerging markets while established manufacturing hubs in Germany and Japan sustain trade surpluses in precision sensor components. The United States absorbs the largest absolute import volume despite domestic assembly capacity. China serves as the dominant exporter of MEMS thermal sensor substrates.
United States
Hospital digitization programs and Medicare remote patient monitoring reimbursement codes drive institutional procurement. FDA 510(k) clearance pathways compress commercialization timelines for connected health devices. The Boston-Cambridge corridor concentrates digital health venture activity, with startups clustering near Massachusetts General Hospital's innovation network.
Germany
EU MDR harmonization and hospital infection control protocols sustain demand for clinical-grade infrared devices. EMA post-market surveillance requirements under Article 10 mandate systematic clinical follow-up data collection. Baden-Württemberg anchors precision sensor engineering, with Stuttgart-area firms supplying calibration-certified MEMS components to hospital networks.
Japan
Aging demographics and METI's Society 5.0 healthcare digitization agenda accelerate home-based patient monitoring adoption. PMDA streamlined approval pathways for Software as a Medical Device reduce regulatory friction. The Kansai region around Osaka concentrates wearable thermometer manufacturing, with firms integrating temperature sensors into adhesive patch formats for post-surgical recovery.
China
Domestic chronic disease management programs and NMPA's priority review channels for innovative medical devices expand market access. GB standards for wireless medical devices impose certification requirements that favor domestic cloud platform integration. Shenzhen's electronics manufacturing cluster dominates Bluetooth module assembly, supplying connectivity components to global thermometer brands.
India
CDSCO's relaxed import licensing for Class A medical devices and Ayushman Bharat digital health infrastructure investments open distribution channels. State-level telemedicine programs in Maharashtra and Karnataka pilot temperature monitoring for rural maternal health. Hyderabad's medical device manufacturing zone attracts contract assembly operations for export-oriented infrared thermometer production.
Smart Thermometer Market Competitive Environment
Listed leaders compete with private specialists across regulatory certification depth, with publicly traded electronics conglomerates leveraging balance sheet capacity for FDA 510(k) clearance investments while venture-backed startups prioritize software subscription monetization. The vendor base organizes into three tiers: precision sensor heritage firms, population health data platforms, and integrated home diagnostics ecosystems. Dominant competitive moves include strategic partnerships with hospital procurement consortia and backward integration into MEMS thermal sensor calibration capabilities.
Among precision engineering specialists, Braun GmbH and Testo SE & Co. KGaA exemplify the heritage sensor archetype, anchoring premium positioning through in-house calibration certification. Kinsa Inc. occupies a distinct position within the population health data tier, representing the venture-backed model that monetizes aggregated anonymized temperature trends through public health surveillance contracts. Omron Corporation exemplifies integrated ecosystem strategy, with its home diagnostics heritage extending into multi-parameter monitoring platforms that bundle temperature with blood pressure and pulse oximetry.
| Leading Market Players |
|---|
| Braun GmbH |
| iHealth Labs |
| Exergen Corporation |
| Withings |
| Microlife Corporation |
| Kinsa Inc. |
| Omron Corporation |
| Welch Allyn |
| Testo SE & Co. KGaA |
| Others |
Value Chain & Pricing Dynamics
MEMS thermal sensor substitution for traditional thermistor assemblies simultaneously shifts production gravity toward East Asian foundries and compresses margin capture for device integrators lacking in-house calibration capabilities. This input transition rewards manufacturers with captive sensor engineering while exposing pure-play assemblers to price volatility in precision fabrication.
Pricing Analysis
Hospital procurement committees anchor premium tier pricing through FDA 510(k) clearance requirements and MEMS calibration certificate specifications. Pricing stratifies across clinical-grade, consumer wellness, and economy tiers, with certification level and volume scale driving differentiation. Cost compression in consumer channels intensifies as direct-to-consumer brands bundle hardware with subscription analytics. Home users exhibit highest price sensitivity; hospital networks demonstrate lowest sensitivity due to infection control protocol mandates.
Supply Chain Analysis
China, Taiwan, and South Korea anchor MEMS thermal sensor fabrication and Bluetooth module assembly. Device manufacturing draws from precision sensor substrates, wireless connectivity components, and cloud infrastructure services. Single-source vulnerability concentrates in East Asian foundry capacity for clinical-grade thermal sensors. Distribution runs through hospital procurement consortia, direct-to-consumer platforms, and pharmacy retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
In-house MEMS calibration capabilities have become the decisive scarcity asset, separating margin-capturing integrated manufacturers from margin-compressed device assemblers dependent on external sensor supply.
For Market Incumbents: Compound defensive positioning through backward integration into MEMS thermal sensor calibration and exclusive hospital procurement consortia partnerships. Emerging direct-to-consumer subscription brands threaten premium positioning through software monetization models. Certification depth in FDA 510(k) and EU MDR pathways remains the critical lever for institutional channel control. For New Entrants and Emerging Players: FDA 510(k) streamlined pathways enable rapid clinical credibility acquisition for connected health device startups. Pediatric sleep monitoring and post-surgical recovery applications represent the most penetrable wearable segments. Population health data partnerships with municipal health departments offer a distinctive go-to-market angle against hardware-centric incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated sensor-device platforms with recurring software revenue components. Long-term viability across the analysis window hinges on regulatory certification depth and data monetization infrastructure. Watch for EU MDR Article 10 post-market surveillance compliance cost spikes as an inflection indicator for consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Sensor Backward Integration | Captive calibration capabilities defend margin position against East Asian foundry price volatility. |
| FDA 510(k) Streamlined Pathway | Expedited clearance compresses commercialization timelines for connected temperature devices. |
| Population Health Data Partnership | Aggregated anonymized temperature trends generate recurring revenue through surveillance contracts. |
| Wearable Continuous Monitoring Launch | Post-surgical and pediatric applications replace episodic measurement with uninterrupted data streams. |
| Hospital System API Integration | Custom electronic health record connectivity secures enterprise procurement lock-in. |
Study Parameters
A standing panel of biomedical engineers, hospital purchasing committee members, GPO contracts managers, and connected health platform executives provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR conformity assessment databases, hospital procurement records, and CMS remote patient monitoring reimbursement data. Bottom-up segment sizing triangulated against top-down market construction across product type, end user, technology, and distribution channel dimensions.
Consistency checks validated volume and value outputs against external benchmarks including regulatory submission databases and trade flow records. The analytical framework modeled demand drivers across the projection horizon through segmentation by product architecture, customer type, wireless protocol, and channel strategy. CAGRs derived from regression analysis of historical adoption curves and regulatory timeline compression effects, with inputs from MEMS sensor supply capacity and cloud platform subscription attach rates.
Underlying assumptions cover reimbursement code stability, MEMS foundry capacity expansion, and cybersecurity labeling timeline adherence, with deviation risk concentrated in supply chain geographic concentration and algorithmic transparency regulatory evolution. Recalibration cycles align with material shifts in FDA guidance documents, EU MDR enforcement patterns, and hospital digitization program accelerations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Inline Quality Control Sensors Market
Sensors and Controls
RFID Reader Market
Sensors and Controls
Current Calibrator Market
Sensors and Controls
Latin America Lidar Market
Sensors and Controls
Magnetic Field Sensor Market
Sensors and Controls
Home Automation Sensors Market
Sensors and Controls
Printed Antenna Market
Sensors and Controls
Digital Flow Meter Market
Sensors and Controls
Distributed Acoustic Sensing (DAS) Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
Global Pressure Calibrators Market
Sensors and Controls
Water Cut Monitor Market
Sensors and Controls
Air Particle Monitor System Market
Sensors and Controls
Temperature Transmitter Market
Sensors and Controls
North America Temperature Sensor Market