
 Consumer Grade Electrochemical CO Sensor Market | 2026-2036
Consumer Grade Electrochemical CO Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Grade Electrochemical CO Sensor Market Insights
Aftermarket calibration and sensor replacement revenue is rewriting margin economics for incumbent suppliers. City Technology leverages its UK manufacturing base to sustain premium positioning in reference-grade electrochemical cells. Alphasense anchors European demand through specialized low-concentration detection modules. Winsen Electronics competes aggressively on cost, dominating high-volume supply to Chinese detector OEMs.
Consumer grade electrochemical CO sensors employ porous working electrodes of platinum or gold deposited on polymer substrates, generating current proportional to carbon monoxide concentration through redox reactions at 0 to 500 ppm ranges. These devices primarily protect residential occupants from lethal exposure in sleeping environments. Portable detectors lead unit shipments due to landlord compliance mandates across rental housing markets, while smart home sensors represent the fastest-expanding margin pool as Wi-Fi and Matter protocol integration commands price premiums. Fixed mount sensors occupy a mature replacement cycle with lower growth but stable aftermarket attach rates for battery and electrode swaps.
UL 2034 in the United States and EN 50291 across Europe mandate minimum alarm thresholds and response times, directly dictating electrode sensitivity specifications and firmware validation protocols. China's GB standards, administered by the national standardization authority, require CCC certification for domestic sale, creating a parallel compliance track for manufacturers serving both export and local markets. Stakeholders must monitor evolving interoperability mandates as smart home ecosystems consolidate around unified protocols that could commoditize connectivity layers while preserving sensor performance as the primary differentiation axis.
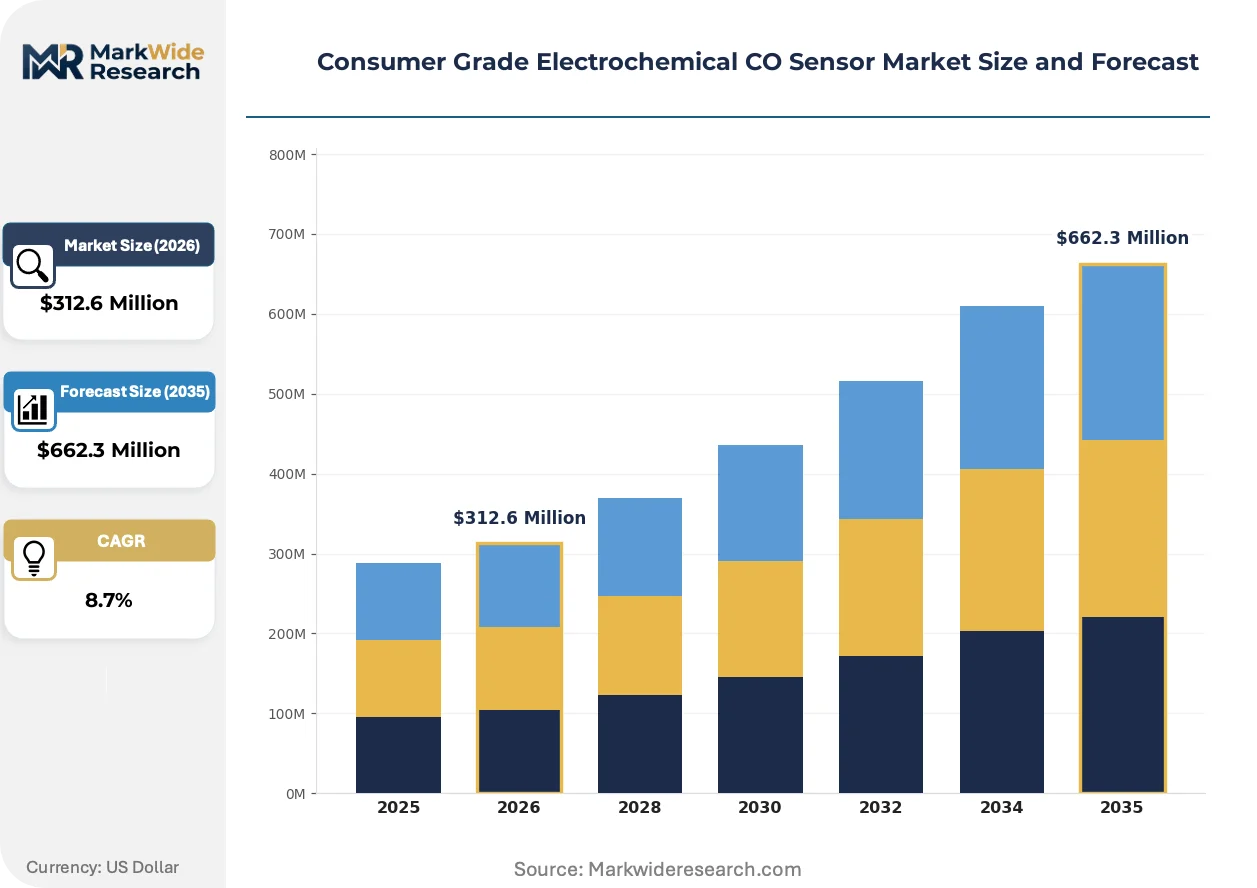
Market Dynamics
Smart home protocol consolidation around Matter is collapsing connectivity premiums while amplifying sensor performance as the sole differentiation axis for electrochemical CO detector suppliers.
Growth Catalysts
- UL 2034 Sensitivity Mandates:Tighter alarm thresholds in the United States are forcing electrode redesigns that extend replacement cycles and deepen aftermarket revenue pools for incumbent suppliers.
- Landlord Compliance Mandates:Rental housing regulations across multiple states now require portable CO detectors, concentrating unit shipments in the aftermarket channel.
- Platinum Working Electrode Advances:Porous deposition techniques on polymer substrates are improving redox reaction efficiency at sub-50 ppm detection levels.
Market Restraints
- Palladium Price Volatility:Working electrode materials face input cost swings that compress margins for non-integrated sensor manufacturers.
- Chinese Cell Concentration:Domestic electrochemical cell production in China creates supply dependency risk for European and North American detector OEMs.
- Optical Sensor Substitution:NDIR technology threatens premium positioning in commercial applications above 500 ppm detection ranges.
Strategic Opportunities
- India Residential Penetration:Low detector density in urban housing stock creates first-mover advantage for suppliers establishing local certification with BIS.
- Wi-Fi Matter Convergence:Unified smart home protocols enable cross-platform integration that commands hardware premiums from ecosystem-locked consumers.
- GB Standard Alignment:China's CCC certification pathway allows simultaneous export and domestic market access for dual-track manufacturers.
Industry Challenges
- Electrochemist Talent Scarcity:Specialized redox reaction expertise required for firmware validation protocols exceeds available labor supply in Western manufacturing bases.
- Multi-Regulatory Certification Timelines:Parallel UL 2034, EN 50291, and GB compliance tracks extend product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Grade Electrochemical CO Sensor Market |
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Portable Detectors, Fixed Mount Sensors, Plug-in Devices, Smart Home Sensors Technology: Electrochemical Cells, Solid Electrolyte, Metal Oxide Semiconductor, Optical Sensors, Photoacoustic Sensors Application: Fire Safety, Indoor Air Quality, Vehicular Emission Monitoring, Workplace Safety, HVAC Systems End User: Homeowners, Industrial Operators, Fire Departments, Facility Managers, Environmental Consultants |
| Companies Covered | City Technology, Alphasense, MEMBRAPOR, SGX Sensortech, Figaro Engineering, Dräger, Winsen Electronics, Hanwei Electronics, Nemoto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Grade Electrochemical CO Sensor Market Trends and Innovations
Electrochemical CO sensing is undergoing functional convergence with environmental monitoring suites, compressing standalone device economics while expanding total addressable value per installation.
Printed electrode manufacturing is collapsing traditional ceramic substrate costs. Roll-to-roll deposition of platinum nanoparticles onto flexible polymer films enables form factors that integrate into smoke detector housings and HVAC return vents. Residential smart home OEMs are adopting these substrates at scale, collapsing the cost gap between reference-grade and consumer-grade electrochemical performance.
REACH substance restrictions on lead-based solder materials are forcing electrode connection redesigns across European supply chains. The ECHA authorization process for alternative conductive adhesives adds six to nine months to product validation timelines. Detector manufacturers serving EU markets are responding by dual-sourcing electrode assemblies from UK and Southeast Asian facilities.
Subscription-based calibration services are unbundling from hardware sales in commercial property management channels. Facility operators now procure sensor hardware through capital budgets while routing ongoing accuracy verification through operational expenditure contracts. This bifurcation is most visible in United States multi-family housing portfolios, where property technology platforms bundle CO monitoring into broader indoor air quality dashboards.
Consumer Grade Electrochemical CO Sensor Market Segmentation
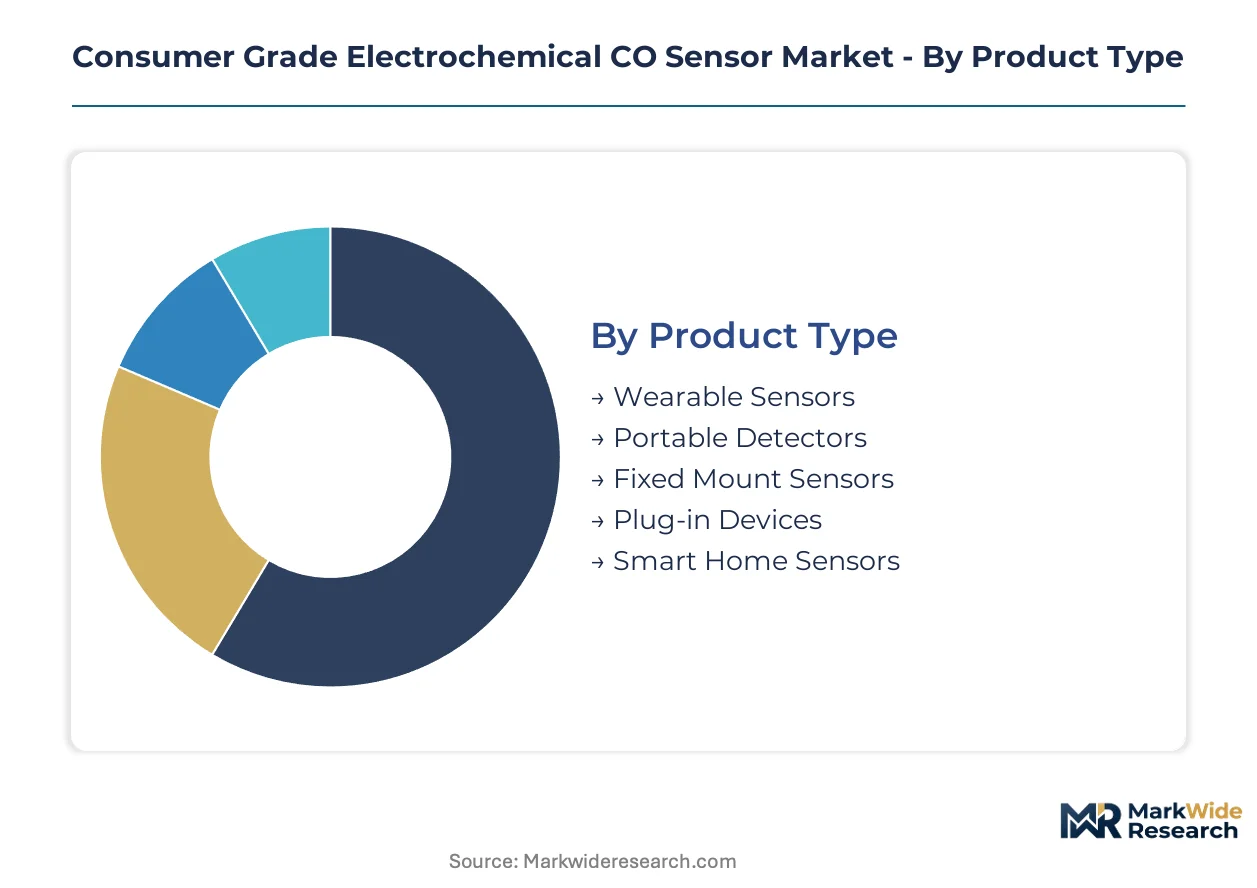
Segmentation in the Consumer Grade Electrochemical CO Sensor Market reveals divergent margin architectures across product tiers. Aftermarket calibration intensity varies dramatically by installation type, reshaping supplier revenue models and customer lifetime value calculations.
Product Type:
After-sales service intensity clusters around installation permanence and battery dependency, with portable units generating recurring replacement revenue while fixed systems anchor long-term calibration contracts.
- Smart Home Sensors:Wi-Fi and Matter protocol integration enables firmware-over-the-air updates and cloud-based accuracy monitoring. Demand concentrates in United States suburban housing developments where builder pre-installation mandates create volume anchors. Subscription calibration bundles command recurring revenue premiums from ecosystem-locked homeowners.
- Portable Detectors:Battery-powered units with electrochemical cells housed in plastic enclosures dominate landlord compliance procurement. Rental housing regulations across multiple United States states concentrate unit shipments in the aftermarket channel, with electrode replacement cycles driving repeat purchase intensity.
- Fixed Mount Sensors:Hardwired installations in commercial kitchens and parking structures require professional calibration servicing.
- Plug-in Devices:AC-powered residential units occupy a mid-tier price position with moderate replacement frequency.
- Wearable Sensors:Personal exposure monitors for industrial contractors integrate electrochemical cells into compact form factors.
Portable detectors hold the largest share; momentum sits with smart home sensors.
Technology:
Cost tier stratification separates reference-grade electrochemical performance from emerging solid-state alternatives, with platinum working electrode configurations defending premium positioning against price-aggressive metal oxide substitutes.
- Electrochemical Cells:Porous platinum or gold working electrodes deposited on polymer substrates generate current proportional to CO concentration through redox reactions. United States and European residential markets concentrate demand where UL 2034 and EN 50291 sensitivity mandates require proven reference-grade accuracy.
- Metal Oxide Semiconductor:Tin dioxide sensing layers offer lower unit costs but reduced selectivity against humidity and interfering gases. Chinese detector OEMs concentrate procurement for domestic price-sensitive housing stock, with GB standard certification enabling parallel export track access.
- Solid Electrolyte:Yttria-stabilized zirconia configurations enable high-temperature operation for vehicular applications.
- Optical Sensors:NDIR technology threatens electrochemical positioning above 500 ppm detection ranges in commercial settings.
- Photoacoustic Sensors:Emerging MEMS-based architectures promise miniaturization for wearable form factors.
Electrochemical cells dominate installed base; solid electrolyte architectures are climbing the fastest.
Application:
Volume concentration in fire safety installations creates scale economies for electrode manufacturers, while indoor air quality expansion diversifies end-use risk across commercial property technology platforms.
- Fire Safety:Combined smoke and CO detection units integrate electrochemical cells alongside photoelectric smoke sensors. United States multi-family housing portfolios concentrate procurement through property technology platforms bundling CO monitoring into broader indoor air quality dashboards.
- Indoor Air Quality:Environmental monitoring suites compress standalone device economics while expanding total addressable value per installation. European commercial buildings concentrate demand where CSRD reporting requirements elevate sensor density mandates.
- Workplace Safety:OSHA compliance drives detector placement in industrial facilities with combustion equipment.
- HVAC Systems:Return vent integration enables centralized building management system connectivity.
- Vehicular Emission Monitoring:Cabin air quality sensing in electric vehicles addresses preconditioned space concerns.
Fire safety commands the largest share; indoor air quality applications are gaining share fastest.
End User:
Customer type determines procurement channel structure, with homeowners purchasing through retail and e-commerce while facility managers route commercial volumes through integrated property technology contracts.
- Homeowners:Retail and e-commerce channels dominate procurement for replacement and upgrade purchases. Smart home ecosystem integration commands hardware premiums from United States consumers locked into Apple, Google, and Amazon platforms.
- Facility Managers:Commercial property operators procure through capital budgets while routing ongoing accuracy verification through operational expenditure contracts. Subscription-based calibration services unbundle from hardware sales in United States multi-family housing portfolios.
- Fire Departments:Municipal procurement specifications prioritize UL 2034 certification and documented response time performance.
- Industrial Operators:Workplace safety mandates drive detector density in manufacturing facilities with combustion processes.
- Environmental Consultants:Specialized low-concentration detection modules support forensic investigation and remediation verification.
Facility managers represent the largest addressable spend; homeowners are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies: the United States favors smart home integration with recurring calibration subscriptions, while China concentrates on high-volume portable detector production for price-sensitive housing compliance.
United States
Suburban housing developments drive builder pre-installation mandates for Wi-Fi-enabled units. UL 2034 sensitivity requirements force electrode redesigns that extend replacement cycles. Texas and Florida rental markets concentrate portable detector procurement through landlord compliance channels.
China
Domestic electrochemical cell manufacturing scales rapidly to serve high-volume detector OEMs. GB standards administered by the national standardization authority require CCC certification for local sale. Shenzhen and Dongguan clusters anchor production capacity for both export and domestic market supply.
Germany
Commercial building CSRD reporting requirements elevate sensor density mandates for indoor air quality monitoring. REACH substance restrictions on lead-based solder materials force electrode connection redesigns. Bavaria's industrial sensor fabricators dual-source assemblies from UK and Southeast Asian facilities.
United Kingdom
EN 50291 sensitivity thresholds dictate firmware validation protocols for residential installations. London's property technology platforms bundle CO monitoring into broader indoor air quality dashboards. City Technology leverages UK manufacturing to sustain premium positioning in reference-grade electrochemical cells.
India
Low detector density in urban housing stock creates first-mover opportunity for suppliers establishing BIS certification. Maharashtra and Karnataka residential construction accelerates smart home adoption among middle-income homeowners. Mumbai and Bangalore clusters attract component suppliers targeting price-optimized electrochemical cell assembly.
Consumer Grade Electrochemical CO Sensor Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three distinct player archetypes: reference-grade specialists defending premium positioning through UK and European manufacturing bases; high-volume Chinese fabricators competing aggressively on electrode cost; and diversified industrial gas detection conglomerates leveraging cross-product calibration service networks. Consolidation pressure intensifies as smart home protocol standardization collapses connectivity premiums, forcing differentiation toward sensor performance alone. Strategic moves cluster around backward integration into electrochemical cell production and geographic certification stacking to compress multi-regulatory launch timelines.
Among UK-based reference-grade specialists, City Technology and Alphasense occupy positions defined by proven sensitivity performance under UL 2034 and EN 50291 validation protocols. At the scale-driven end, Winsen Electronics exemplifies Chinese manufacturing concentration serving high-volume detector OEMs with cost-optimized electrochemical cells. These three anchors illustrate the market's bifurcation between premium-tier performance validation and mass-market production efficiency.
| Leading Market Players |
|---|
| City Technology |
| Alphasense |
| MEMBRAPOR |
| SGX Sensortech |
| Figaro Engineering |
| Dräger |
| Winsen Electronics |
| Hanwei Electronics |
| Nemoto |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese electrochemical cell fabrication is compressing electrode pricing while forcing European and North American suppliers toward premium validation tiers to defend margin structures. This utilization dynamic concentrates procurement power with high-volume detector OEMs while fragmenting pricing power across certification-grade tiers.
Pricing Analysis
Long-term offtake agreements dominate procurement between Chinese cell manufacturers and detector OEMs, locking in volume commitments that suppress spot-market price discovery. Pricing stratifies across UL 2034-certified reference grades, EN 50291-validated European tiers, and uncertified economy cells for domestic Chinese consumption. Cost compression in economy-tier electrodes is intensifying because Winsen Electronics and Hanwei Electronics are expanding roll-to-roll platinum deposition capacity. Landlord compliance buyers in United States rental markets exhibit highest price sensitivity, while smart home ecosystem-locked homeowners accept hardware premiums for Matter protocol integration.
Supply Chain Analysis
Export control regimes on advanced sensor manufacturing equipment limit European and North American fabricators from replicating Chinese roll-to-roll deposition scale. Supply concentration rests on China for porous polymer substrates and platinum nanoparticle inks, Japan for high-purity gold working electrode materials, and Germany for precision calibration instrumentation. Single-source vulnerability concentrates in Chinese electrochemical cell output, where domestic GB standard certification creates captive demand loops. Distribution runs through detector OEM assembly facilities in Shenzhen, Dongguan, and Suzhou before routing to regional certification laboratories for UL 2034, EN 50291, and CCC validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket calibration and electrode replacement revenue is expanding faster than hardware unit economics, transforming this market into a service-attach opportunity where recurring revenue pools exceed one-time sensor margins.
For Market Incumbents: Insulate reference-grade positioning by backward integration into platinum nanoparticle ink production and captive calibration service networks. City Technology and Alphasense must defend against optical sensor substitution above 500 ppm by deepening firmware validation expertise that NDIR technology cannot replicate. Certification investment in simultaneous UL 2034, EN 50291, and GB standard compliance compresses launch timelines for emerging competitors. For New Entrants and Emerging Players: Pursue BIS certification in India before incumbent suppliers establish local electrode assembly capacity. Maharashtra and Karnataka residential construction offers first-mover positioning in smart home sensor penetration among middle-income homeowners. Go-to-market execution should route through Mumbai and Bangalore component clusters to exploit price-optimized electrochemical cell assembly gaps. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across printed electrode manufacturing as roll-to-roll deposition replaces ceramic substrate fabrication. Long-term viability over the next decade favors targets with captive calibration service networks and multi-regulatory certification stacking capabilities. Watch for inflection when Matter protocol standardization collapses connectivity premiums and forces pure sensor performance differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Platinum Ink Production | Captive nanoparticle supply secures margin control against palladium price volatility swings. |
| Multi-Regulatory Certification Stacking | Simultaneous UL 2034, EN 50291, and CCC pathways compress product launch cycles by 14-18 months. |
| Calibration Service Network Buildout | Subscription accuracy verification unbundles recurring revenue from capital-budget hardware sales. |
| Printed Electrode Manufacturing Scale-Up | Roll-to-roll polymer substrate deposition collapses cost gap between reference-grade and consumer-grade performance. |
| Smart Home Protocol Integration | Matter certification commands hardware premiums from ecosystem-locked Apple, Google, and Amazon platform users. |
Research Methodology
A standing panel of electrochemical sensor R&D directors, detector OEM procurement managers, smart home platform engineers, and aftermarket calibration service operators provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with these stakeholders alongside trade data from customs records, SEC filings of diversified industrial gas detection conglomerates, and certification database tracking of UL 2034, EN 50291, and CCC approvals. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions derived from electrode replacement cycle economics and calibration service contract values.
Scenario-bracketing anchored projections across sensitivity ranges for platinum group metal price volatility, Matter protocol adoption velocity, and rental housing regulatory expansion. Segmentation modeling captured product type tiers, technology configurations, application end-uses, and customer procurement channels. CAGRs derived from fitted growth curves applied to installed base replacement cycles and new installation penetration rates, with cross-validation against electrochemical cell production capacity announcements from Chinese manufacturing clusters.
Sensitivities concentrate around palladium price spikes, REACH substance restriction expansions beyond lead-based solder, and smart home ecosystem consolidation pace. Forecasts reflect assumptions on landlord compliance mandate geographic spread and firmware-over-the-air update adoption. Material shifts in Chinese export control enforcement on electrode manufacturing equipment or UL 2034 sensitivity threshold revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Global Wireless Sensors Network Market
Sensors and Controls
Europe Machine Control System Market
Sensors and Controls
Speed Sensor Market
Sensors and Controls
Digital Sensor Sleeves Market
Sensors and Controls
China PV Monitoring Systems Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Machine Control System Market
Sensors and Controls
Robotic Sensors Market
Sensors and Controls
2D Gesture Recognition Market
Sensors and Controls
Africa Robotic Sensors Market
Sensors and Controls
Global Rotation Laser Market
Sensors and Controls
Sensor Based Sorting System Market
Sensors and Controls
Magnetoresistance Sensor Market
Sensors and Controls
Asia Pacific Safety I/O Modules Market
Sensors and Controls
France Air Purifier Market