
 Latin America Proximity Sensors Market | 2026-2036
Latin America Proximity Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Proximity Sensors Market Foresight
Silicon carbide is rebalancing cost-performance trade-offs in high-temperature proximity sensing modules across Latin American factories. OMRON Corporation leverages its Osaka-developed inductive platforms to anchor premium positioning in Mexican automotive tier-one supply chains. Pepperl+Fuchs GmbH sustains channel dominance through Brazilian distributor networks serving Petrobras-linked maintenance operations. SICK AG specializes in laser-based safety systems for Chilean copper concentrator belt lines.
Proximity sensors detect object presence or distance without physical contact, typically operating via electromagnetic fields, capacitive coupling, or optical beams across ranges from millimeters to several meters with response times under one millisecond. These devices automate position verification, collision avoidance, and inventory tracking in continuous-process environments. Inductive sensors dominate Latin American metalworking applications due to immunity to contamination, while photoelectric variants capture expanding share in packaging lines requiring longer detection ranges. Capacitive sensors serve level-measurement roles in Brazilian soybean oil storage tanks where material dielectric properties vary. Ultrasonic platforms remain niche but grow in Argentine grain silo monitoring for liquid-solid interface detection.
Brazil's INMETRO certification mandates electromagnetic compatibility testing for industrial sensors deployed in automotive plants, while Mexico's NOM-001-SEDE electrical standards shape voltage tolerance specifications for proximity devices in maquiladora automation. ANMAT in Argentina and COFEPRIS in Mexico enforce divergent material-contact protocols that complicate pan-regional product platforms. Stakeholders must monitor convergence between EU CE marking requirements and emerging Latin American technical regulations as European OEMs deepen local supply chain commitments.
Market Dynamics
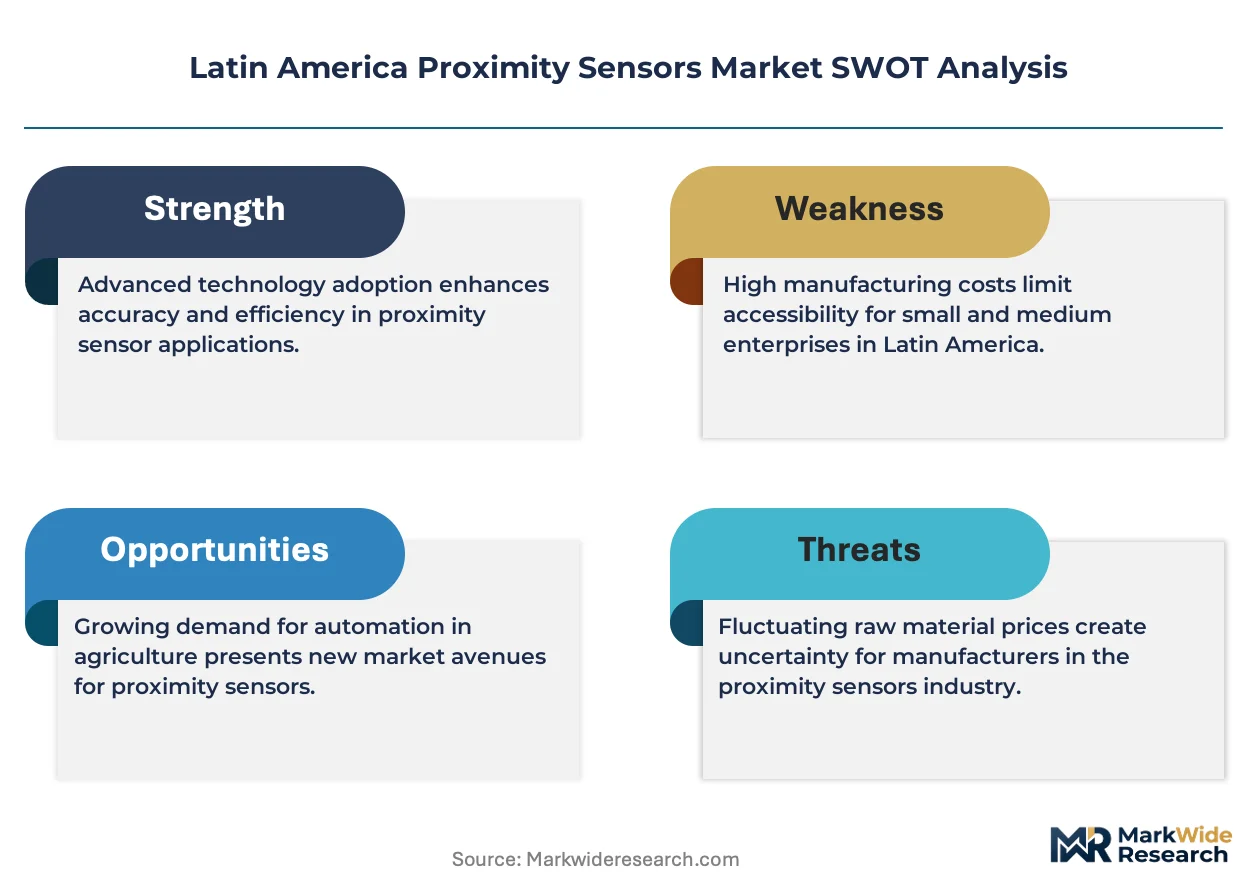
Silicon carbide substrate adoption is compressing thermal tolerance thresholds in Latin American proximity sensor modules, forcing incumbent suppliers to recalibrate material sourcing strategies across Mexican automotive and Brazilian heavy manufacturing clusters.
Growth Catalysts
- INMETRO electromagnetic compatibility mandates:Brazil's certification requirements for automotive plant sensors are accelerating replacement cycles in robotic welding infrastructure.
- Maquiladora automation intensity:Mexican export manufacturing zones are embedding capacitive sensors into NOM-compliant appliance production lines at accelerated rates.
- Photoelectric range extension:Packaging lines across Argentina's Rosario industrial corridor are adopting laser-based position sensing for longer-detection inventory tracking.
Market Restraints
- Copper price volatility:Inductive sensor coil manufacturing faces margin pressure from commodity input swings affecting Brazilian tier-two suppliers.
- Single-source magnet dependency:Rare earth sourcing concentration in Asian processing nodes creates supply vulnerability for Latin American inductive module assemblers.
- Dielectric calibration complexity:Capacitive sensor deployment in Brazilian soybean oil storage requires material-specific tuning that extends commissioning timelines.
Strategic Opportunities
- Chilean copper concentrator automation:Laser-based safety systems for conveyor belt monitoring represent underpenetrated demand in Andean mining operations.
- Argentine grain silo monitoring:Ultrasonic liquid-solid interface detection offers white space in agricultural storage infrastructure.
- NOM-001-SEDE voltage harmonization:Mexico's electrical standard convergence with North American frameworks reduces SKU complexity for cross-border suppliers.
Industry Challenges
- Field calibration technician scarcity:Capacitive sensor commissioning in variable dielectric environments requires specialized labor that outstrips supply in Brazilian interior states.
- ANMAT-COFEPRIS protocol divergence:Material-contact compliance requirements fragment product platforms between Argentine and Mexican medical-adjacent manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Proximity Sensors Market |
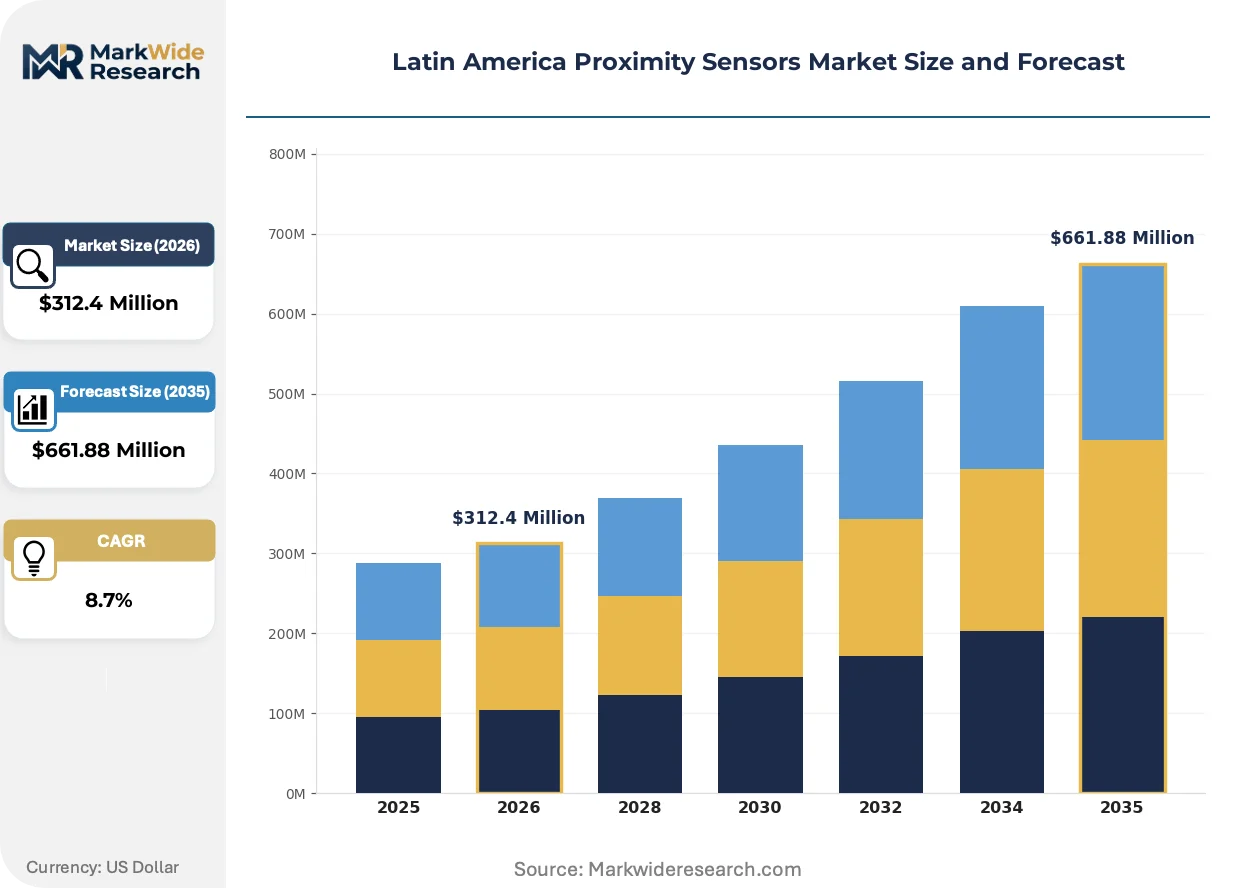
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inductive Sensors, Capacitive Sensors, Ultrasonic Sensors, Photoelectric Sensors Technology: Magnetic, Infrared, Laser, RFID End User: Automotive, Industrial Automation, Consumer Electronics, Home Appliances Application: Object Detection, Position Sensing, Level Measurement, Safety Systems |
| Companies Covered | Delta Electronics Inc., OMRON Corporation, Panasonic Corporation, Pepperl+Fuchs GmbH, Rockwell Automation Inc., SICK AG, Datalogic SpA, Honeywell International Inc., STMicroelectronics NV, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Proximity Sensors Market Shifts & Advancements
Edge-computing integration is redistributing signal processing loads from central controllers to sensor nodes, altering maintenance protocols and supplier value capture across Latin American industrial automation deployments.
Silicon carbide sensing elements are decentralizing thermal management architectures in high-temperature Latin American foundry applications. Brazilian steel mills operating above 400°C ambient conditions are adopting SiC-based inductive modules to eliminate external cooling hardware. This substrate transition is decentralizing supplier relationships away from traditional silicon-centric semiconductor distributors toward specialized wide-bandgap material channels.
Mexico's NOM energy-efficiency standards are compressing standby power allowances for industrial automation components. Appliance manufacturers in Querétaro and Tijuana must now source proximity sensors meeting sub-50mW idle consumption thresholds. Capacitive variants with integrated sleep-mode circuitry are capturing preference share in refrigerator and washing machine assembly lines subject to these electrical standards.
Maintenance contracting is unbundling sensor replacement from original equipment vendor agreements. Brazilian Petrobras-linked operations are sourcing proximity devices through independent distributors rather than integrated automation packages. This channel fragmentation concentrates price pressure on standard inductive models while creating margin refuge for certified specialists serving hazardous-area photoelectric applications in offshore platform environments.
Latin America Proximity Sensors Market Segmentation
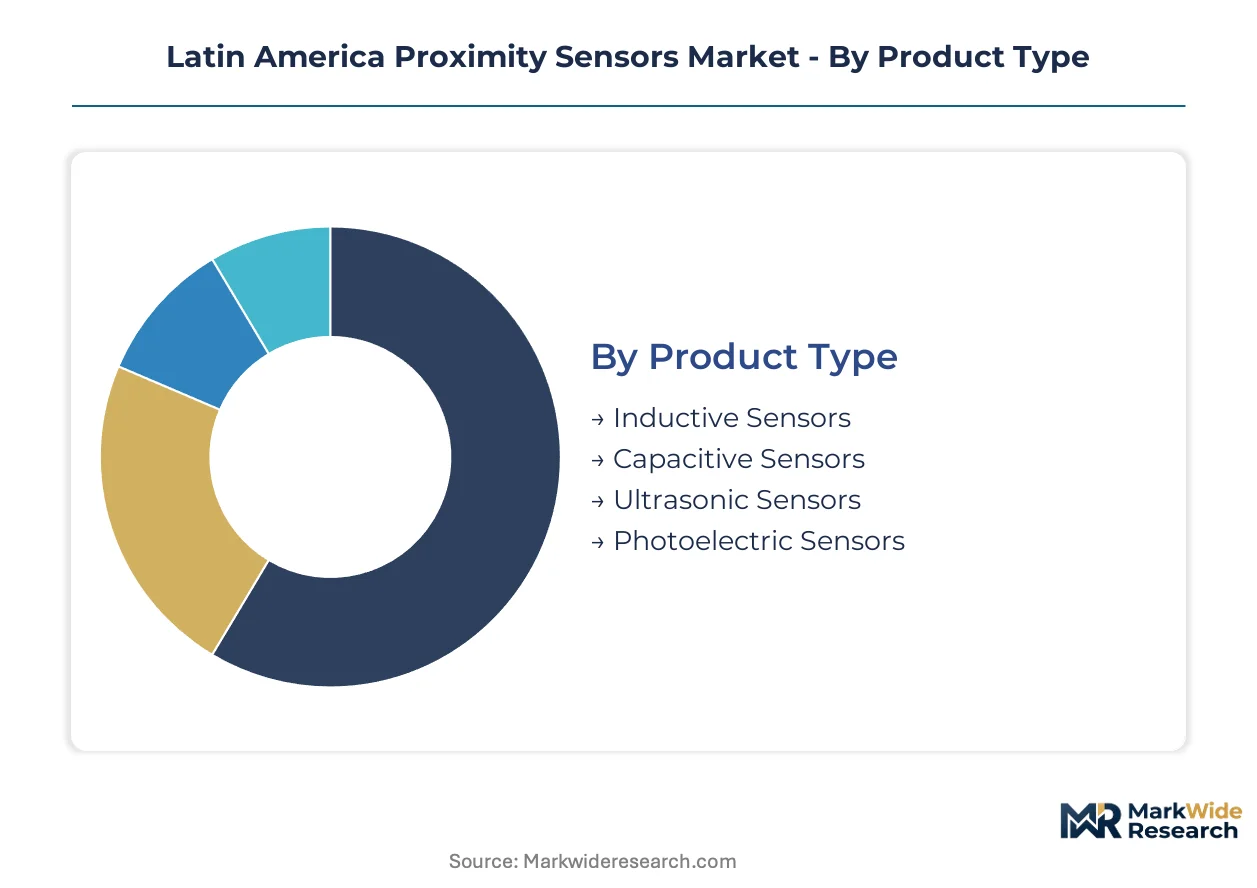
Proximity sensor segmentation in Latin America reflects divergent industrial maturity across the region. Product type splits reveal metalworking dominance in Brazil against packaging expansion in Argentina, while technology choices track thermal tolerance demands and detection range requirements.
Product Type:
Volume deployment clusters in standard inductive units for automotive welding lines, while premium pricing attaches to photoelectric variants with extended range capabilities.
- Inductive Sensors:Electromagnetic field detection operates without physical contact, immune to oil, dust, and moisture contamination. Brazilian automotive assembly plants in São Paulo state deploy these for robotic weld seam verification, driven by INMETRO electromagnetic compatibility mandates accelerating replacement cycles.
- Photoelectric Sensors:Light beam interruption or reflection enables detection across several meters with sub-millisecond response. Argentine packaging corridors near Rosario concentrate demand for laser-based position sensing, where longer detection ranges support high-speed inventory tracking on extended conveyor configurations.
- Capacitive Sensors:Dielectric property variation detection serves level measurement in Brazilian soybean oil storage tanks where material properties fluctuate.
- Ultrasonic Sensors:Time-of-flight acoustic ranging penetrates dust and vapor for liquid-solid interface detection in Argentine grain silo infrastructure.
Mature deployment sits with Inductive Sensors. Newer deployment is concentrated in Photoelectric Sensors.
Technology:
Application environment dictates technology selection, with thermal extremes favoring magnetic platforms and precision positioning driving laser adoption.
- Magnetic:Hall effect and reed switch technologies tolerate ambient temperatures exceeding standard silicon limits. Brazilian steel mills operating above 400°C conditions source magnetic inductive modules to eliminate external cooling hardware, compressing maintenance intervals.
- Laser:Coherent light emission delivers micrometer-scale precision over extended ranges. Chilean copper concentrator belt lines deploy laser photoelectric safety systems for personnel protection around high-speed material handling equipment.
- Infrared:Non-visible spectrum detection reduces ambient light interference in outdoor agricultural monitoring applications.
- RFID:Radio-frequency identification integration enables object tracking beyond simple presence detection in serialized component logistics.
Established process industries anchor Magnetic technology adoption. Steepest expansion trajectory belongs to Laser platforms in mining safety applications.
End User:
Customer scale separates high-volume appliance manufacturers from specialized industrial automation integrators serving hazardous environments.
- Automotive:Robotic welding, paint shop, and final assembly verification dominate sensor consumption. Mexican maquiladora operations embed capacitive devices into NOM-compliant production lines, with tier-one suppliers specifying OMRON inductive platforms for weld seam validation.
- Industrial Automation:General manufacturing and process control applications span metalworking, food processing, and material handling. Brazilian Petrobras-linked maintenance operations source proximity devices through independent distributors rather than integrated automation packages, fragmenting procurement channels.
- Consumer Electronics:Miniaturized touchless detection enables device proximity wake functions in regional assembly operations.
- Home Appliances:NOM energy-efficiency standards compress standby power allowances below 50mW, favoring capacitive variants with integrated sleep-mode circuitry in Querétaro and Tijuana refrigerator and washing machine assembly.
Automotive sector commands the largest installed base. Appliance manufacturing represents the fastest-climbing demand category on energy regulation compliance.
Application:
Functional requirements range from binary presence verification to continuous distance measurement, with safety-critical applications commanding certification premiums.
- Object Detection:Binary presence-absence determination automates sorting, counting, and quality verification. Brazilian soybean oil storage tank level monitoring employs capacitive detection where dielectric calibration complexity extends commissioning timelines in interior states with scarce field technician supply.
- Safety Systems:Personnel protection and collision avoidance mandate fail-safe operation with diagnostic feedback. Chilean copper concentrator operations represent underpenetrated demand for laser-based conveyor monitoring in Andean mining infrastructure.
- Position Sensing:Continuous distance measurement supports robotic arm coordination and alignment verification.
- Level Measurement:Liquid and bulk solid height determination serves process tank and silo inventory management.
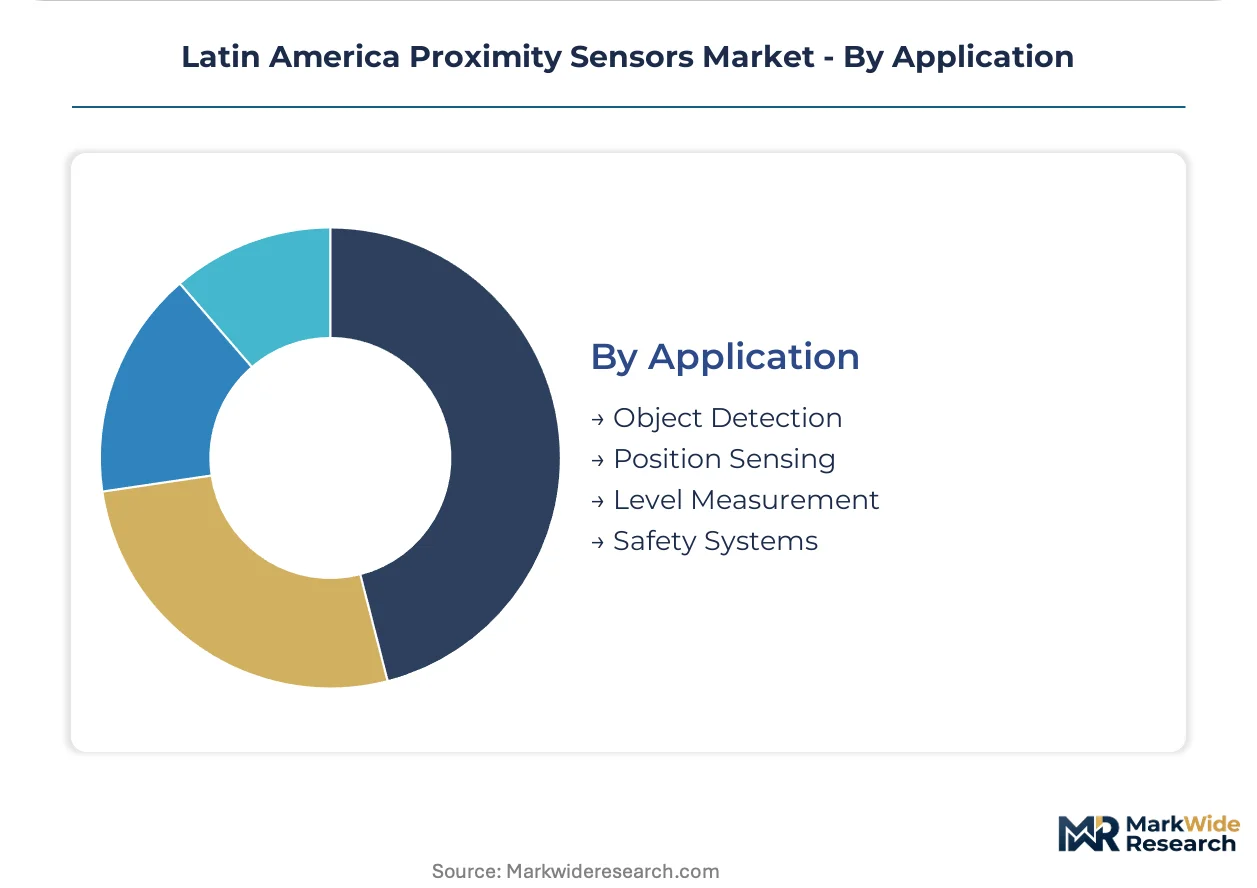
Object Detection carries the deepest installed base. Safety Systems deployment is expanding most quickly on mining automation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Brazil's automotive corridors and Mexico's export manufacturing zones, with Argentina's agro-industrial belt and Chile's mining infrastructure generating specialized sensor requirements. Regulatory divergence across national certification regimes fragments procurement strategies.
Brazil
Automotive assembly plants in São Paulo state deploy inductive sensors for robotic weld seam verification. INMETRO electromagnetic compatibility mandates accelerate replacement cycles in welding infrastructure. Petrobras-linked maintenance operations source proximity devices through independent distributors rather than integrated automation packages.
Mexico
Maquiladora operations in Querétaro and Tijuana embed capacitive devices into NOM-compliant appliance production lines. NOM-001-SEDE electrical standards shape voltage tolerance specifications for proximity devices in export manufacturing zones. Tier-one automotive suppliers specify OMRON inductive platforms for weld seam validation.
Argentina
Packaging corridors near Rosario concentrate demand for laser-based position sensing with extended detection ranges. ANMAT material-contact protocols complicate pan-regional product platforms for medical-adjacent manufacturing. Ultrasonic liquid-solid interface detection offers white space in grain silo infrastructure across the Pampas agricultural zone.
Chile
Copper concentrator belt lines in Andean mining operations deploy laser-based safety systems for personnel protection. Mining automation investment expands demand for safety-critical photoelectric applications. Maintenance contracting unbundles sensor replacement from original equipment vendor agreements in concentrator operations.
Latin America Proximity Sensors Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers navigate certification fragmentation across Brazilian, Mexican, and Argentine regulatory regimes. The vendor base organizes around three tiers: diversified automation conglomerates with full portfolio coverage, specialized sensor manufacturers with deep technical expertise, and regional distributors serving maintenance-intensive industries. Technology licensing agreements and geographic expansion constitute the primary competitive vectors as European and Asian OEMs deepen local supply chain commitments.
Among Japanese automation specialists, OMRON Corporation and Panasonic Corporation occupy premium positioning in Mexican automotive tier-one supply chains. German industrial sensor fabricators Pepperl+Fuchs GmbH and SICK AG exemplify the specialized manufacturer archetype, with the former sustaining channel dominance through Brazilian distributor networks and the latter anchoring mining safety applications in Chilean copper operations. Taiwanese electronics conglomerate Delta Electronics Inc. represents the diversified automation tier with scale-driven manufacturing capabilities.
| Leading Market Players |
|---|
| Delta Electronics Inc. |
| OMRON Corporation |
| Panasonic Corporation |
| Pepperl+Fuchs GmbH |
| Rockwell Automation Inc. |
| SICK AG |
| Datalogic SpA |
| Honeywell International Inc. |
| STMicroelectronics NV |
| Others |
Supply & Pricing Matrix
INMETRO electromagnetic compatibility mandates in Brazilian automotive plants are forcing sensor suppliers to absorb certification testing costs while maintaining competitive unit economics, compressing margins on standard inductive modules and widening spreads between certified premium tiers and uncertified economy alternatives.
Pricing Analysis
Volume deployment of standard inductive sensors for robotic welding lines operates on thin per-unit margins, while photoelectric variants with extended range capabilities and hazardous-area certifications capture substantial price premiums. Price differentiation hinges on INMETRO certification tier and after-sales service bundling, with certified modules commanding multiples over uncertified alternatives. Pricing pressure stems from Brazilian Petrobras-linked operations unbundling procurement from integrated automation packages and sourcing through independent distributors. Appliance manufacturers in Mexican maquiladora zones exhibit highest price sensitivity due to NOM energy-efficiency compliance costs, while Chilean mining safety applications show lowest sensitivity given personnel-protection imperatives.
Supply Chain Analysis
Brazilian local-content rules under BNDES financing guidelines are reshaping sourcing patterns for automotive plant deployments, pressuring foreign suppliers to establish domestic assembly or partner with certified local distributors. Manufacturing concentration centers on Germany, Japan, and Taiwan for core sensing elements, with Mexican maquiladora zones serving as regional final-assembly hubs. Rare earth magnet supply for inductive coils rests on Chinese processing nodes, while silicon carbide substrates draw from specialized wide-bandgap semiconductor channels. Single-source dependency on Asian rare earth processing creates structural vulnerability for Latin American module assemblers. Distribution runs through Brazilian distributor networks serving Petrobras-linked maintenance operations and Mexican tier-one automotive supplier channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive supply of silicon carbide substrates and rare earth magnet processing to escape commodity input volatility and certification cost compression.
For Market Incumbents: Acquire wide-bandgap semiconductor fabrication capabilities to secure silicon carbide substrate supply for high-temperature inductive modules serving Brazilian steel mills above 400°C ambient conditions. Consolidate Brazilian distributor relationships serving Petrobras-linked operations to defend against channel fragmentation from independent procurement. Threat of emerging Asian sensor manufacturers with cost-advantaged magnetic platforms necessitates certification investment in INMETRO electromagnetic compatibility testing infrastructure. For New Entrants and Emerging Players: The price-point gap between premium laser-based safety systems and economy photoelectric units in Chilean copper concentrator operations offers entry leverage for mid-tier alternatives with sufficient range precision. Target Argentine grain silo infrastructure across the Pampas agricultural zone, where ultrasonic liquid-solid interface detection remains underpenetrated relative to Brazilian and Mexican industrial automation intensity. Go-to-market angle should emphasize field calibration support partnerships to overcome technician scarcity in Brazilian interior states. For Investors and Strategic Acquirers: The window for entry favors specialized sensor manufacturers with deep technical expertise in hazardous-area certifications and mining safety applications over diversified automation conglomerates. Long-term viability hinges on regulatory convergence between EU CE marking and emerging Latin American technical regulations as European OEMs deepen local supply chain commitments. Watch for NOM-001-SEDE voltage harmonization completion as inflection signal for cross-border SKU consolidation and margin expansion in Mexican appliance manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrates | Eliminates external cooling hardware costs for Brazilian steel mill deployments above 400°C. |
| INMETRO Certification Infrastructure Investment | Accelerates replacement cycles in São Paulo automotive welding lines under electromagnetic compatibility mandates. |
| Argentine Grain Silo Channel Partnership | Captures white space in ultrasonic liquid-solid interface detection across Pampas agricultural infrastructure. |
| Chilean Mining Safety System Specialization | Addresses underpenetrated demand for laser-based conveyor monitoring in Andean copper concentrator operations. |
| Mexican Maquiladora Capacitive Platform Expansion | Aligns with NOM sub-50mW standby power thresholds in Querétaro and Tijuana appliance assembly. |
Research Methodology
Document review covered SEC filings of listed automation suppliers, INMETRO certification databases, and NOM regulatory gazettes, complemented by interviews with plant engineers at Brazilian automotive assembly operations, procurement leads at Mexican tier-one suppliers, maintenance directors at Petrobras-linked facilities, and channel managers at Brazilian industrial distributors. Secondary validation drew from customs records of sensor imports, ANMAT and COFEPRIS material-contact protocol documentation, and Chilean mining safety incident reports. Bottom-up demand modeling triangulated against top-down industrial automation capex forecasts.
Segmented outputs across product type, technology platform, end-use sector, and application function were generated through the projection horizon. The analytical framework modeled inductive, photoelectric, capacitive, and ultrasonic sensor demand separately, with technology splits further disaggregating magnetic, laser, infrared, and RFID platforms. CAGRs were derived from regression against industrial production indices and automotive assembly plant investment cycles. Industry-specific forecast inputs included INMETRO replacement cycle acceleration rates and NOM energy-efficiency compliance timelines for appliance manufacturing.
Inputs from primary stakeholder interviews and regulatory documentation were available through the study window; gaps in real-time Argentine grain silo deployment data and Chilean mining safety system procurement records introduce uncertainty bands around ultrasonic and laser platform adoption trajectories. Forecasts reflect assumptions regarding continued convergence between EU CE marking requirements and Latin American technical regulations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Machine Control System Market
Sensors and Controls
Body Worn Temperature Sensors Market
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
Air Pressure Sensor Market
Sensors and Controls
Europe Touch Sensor Market
Sensors and Controls
Condition Monitoring Equipment Market
Sensors and Controls
Pressure Sensor Market
Sensors and Controls
Industrial Sensors Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
Aton Management and Monitoring System Market
Sensors and Controls
APAC Acoustic Sensors Market
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
Marine Sensors Market
Sensors and Controls
Sensor Data Analytics Market
Sensors and Controls
CO Gas Sensors Market
Sensors and Controls
Level Measuring Equipment Market