
 Wired Occupancy Sensors Market | 2026-2036
Wired Occupancy Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Wired Occupancy Sensors Market Outlook
Aftermarket service revenue is fragmenting across hardware-software bundles as vendors compete for recurring platform income. Johnson Controls leverages its building automation installed base to capture long-term maintenance contracts. Schneider Electric anchors its position through EcoStruxure integration that extends sensor data into enterprise energy dashboards. Lutron Electronics specializes in premium lighting control ecosystems that dominate specification-driven commercial projects.
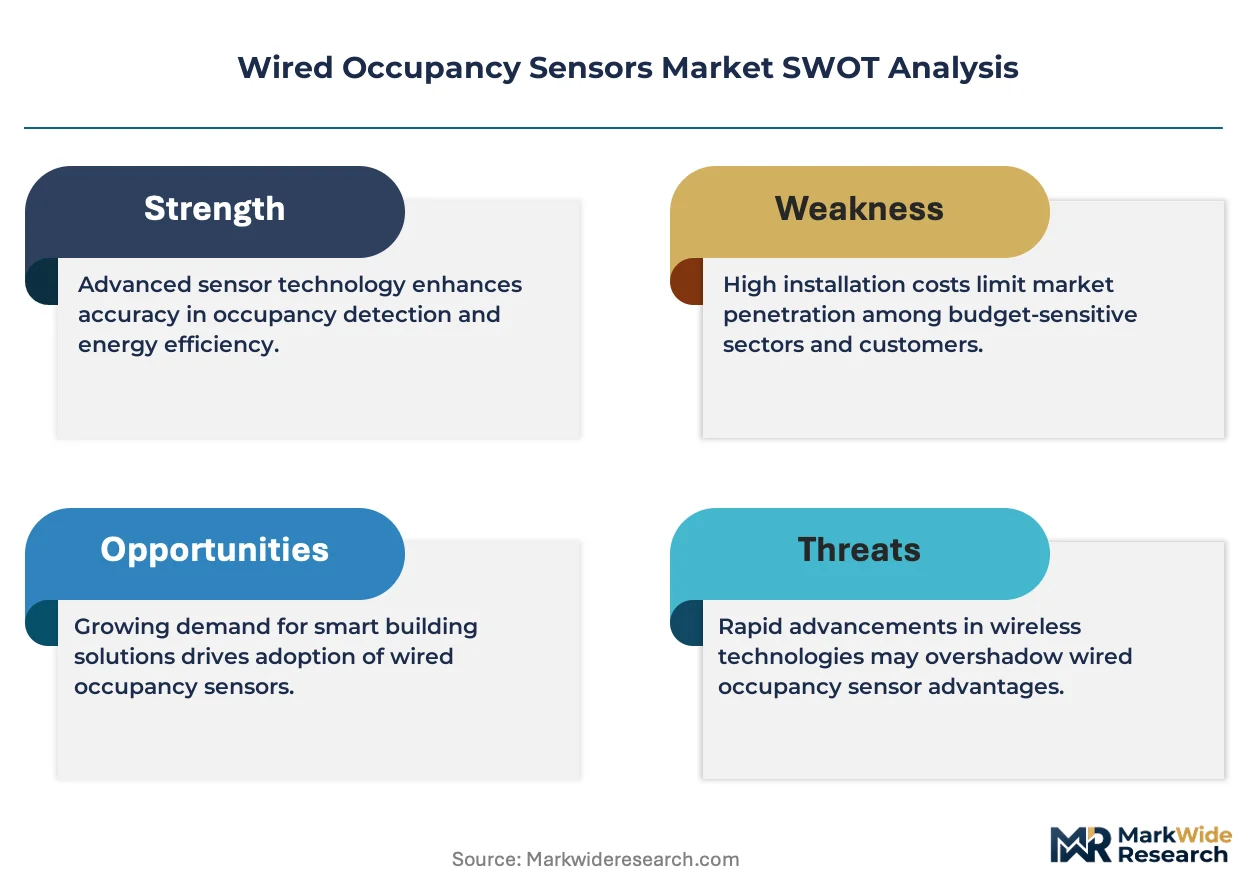
Wired occupancy sensors are hardwired detection devices that use passive infrared, ultrasonic, or dual-technology detection methods to identify human presence within a defined zone, typically operating on low-voltage DC power with hardwired signal transmission to building management systems for automated environmental control. Their primary commercial purpose is eliminating energy waste in unoccupied spaces by triggering lighting, HVAC, or security responses based on verified presence rather than schedules. Passive infrared sensors occupy the largest volume tier due to lower per-unit cost and simpler installation protocols in standard ceiling applications. Dual technology sensors represent the fastest-growing product category as facilities managers prioritize false-positive reduction in complex occupancy environments like open-plan offices and healthcare corridors. Energy management applications command the strongest margin pools where sensors feed into utility-grade metering and demand-response platforms rather than standalone lighting circuits.
The EU Green Deal and F-Gas Regulation shape European demand by mandating building efficiency upgrades that prioritize hardwired sensor networks over wireless alternatives in large commercial retrofits. In the United States, ASHRAE Standard 90.1 and utility-sponsored rebate programs administered by entities like FERC-aligned grid operators directly influence specification requirements for wired detection in new construction and major renovation projects. Stakeholders must monitor how evolving cybersecurity frameworks for building IoT devices affect hardwired sensor preference as a perceived lower-risk alternative to wireless connectivity in sensitive facilities.
Market Dynamics
Building efficiency mandates across the EU Green Deal and ASHRAE 90.1 standards are compressing installation timelines and forcing specification upgrades toward dual-technology wired sensors that reduce false positives in complex commercial environments.
Growth Catalysts
- EU Green Deal building retrofits:Germany's commercial building sector accelerates hardwired sensor deployment under efficiency mandates that prioritize verified occupancy detection over scheduled controls.
- Utility rebate programs:FERC-aligned grid operators in the United States administer direct incentives for wired PIR and dual-technology installations across Class A office portfolios.
- Dual-technology adoption:Facilities managers in healthcare corridors and open-plan offices specify ultrasonic-infrared hybrid units to eliminate false triggers from HVAC air movement.
Market Restraints
- Copper and semiconductor input volatility:Low-voltage DC wiring and sensor microcontrollers face price instability from concentrated East Asian foundry capacity.
- Wireless substitution threat:Battery-powered IoT sensors with decade-long lifespans compete for retrofit projects where hardwired infrastructure is absent.
- Installation labor intensity:Ceiling grid penetration and conduit runs require certified low-voltage electricians, extending project timelines versus wireless alternatives.
Strategic Opportunities
- Healthcare facility modernization:German hospital corridors and patient rooms present untapped demand for dual-technology sensors that distinguish staff movement from patient stillness.
- Enterprise energy dashboard integration:Convergence of wired occupancy data with utility-grade metering platforms creates subscription revenue streams for building automation vendors.
- Demand-response program enrollment:FERC Order 2222 implementation enables sensor-networked buildings to participate in wholesale electricity markets through automated load curtailment.
Industry Challenges
- Legacy building management system integration:BACnet and Modbus protocol fragmentation forces custom middleware development for unified sensor data streams.
- Cybersecurity certification timelines:NIST Cybersecurity Framework compliance for building IoT devices extends product launch cycles and increases documentation burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wired Occupancy Sensors Market |
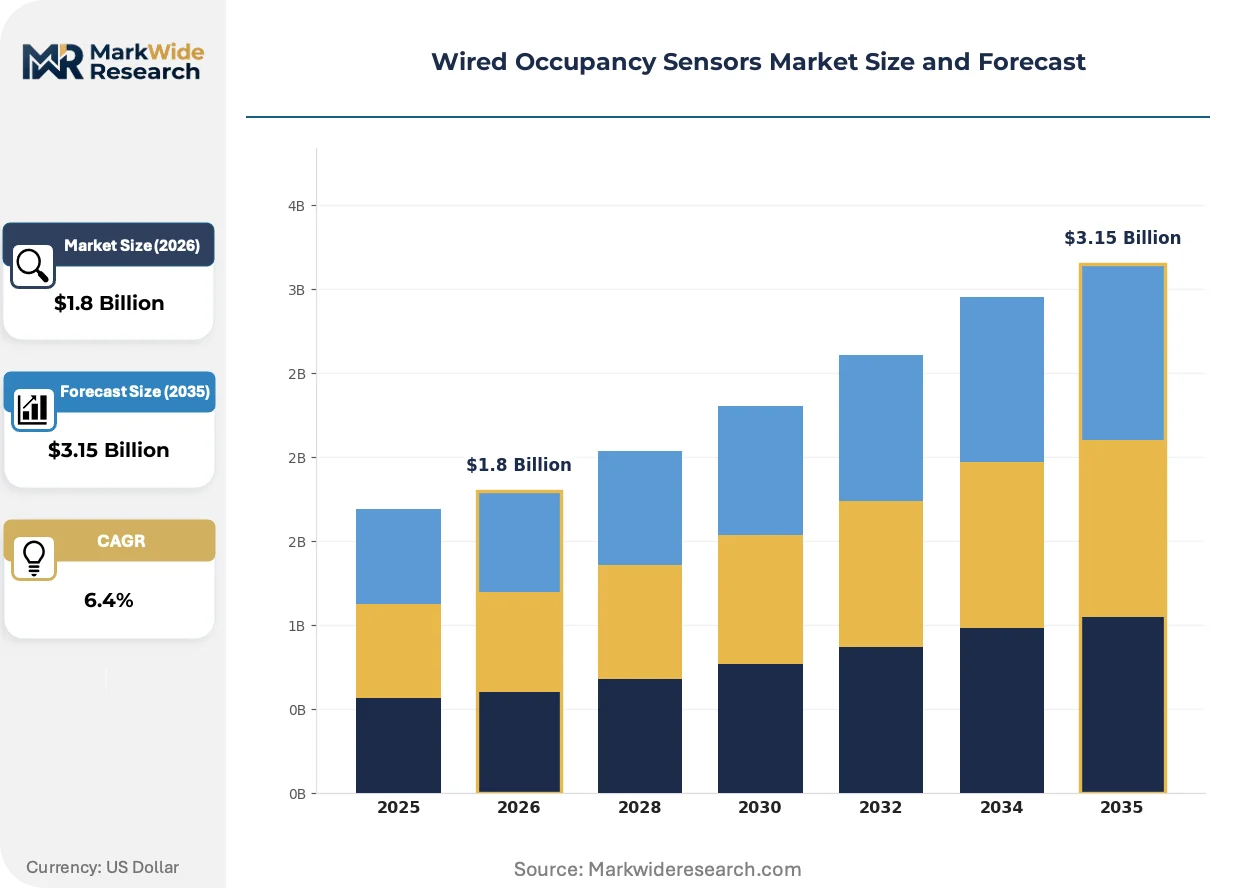
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Sensors, Passive Infrared Sensors, Ultrasonic Sensors, Dual Technology Sensors Application: Lighting Control, HVAC Control, Security Systems, Energy Management End User: Commercial Buildings, Industrial Facilities, Residential Homes, Educational Institutions Installation Type: Wall-Mounted, Ceiling-Mounted, Integration with Existing Systems, Standalone |
| Companies Covered | Johnson Controls, Honeywell International, Schneider Electric, Eaton Corporation, Legrand, Texas Instruments, Acuity Brands, Leviton, Lutron Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wired Occupancy Sensors Market Strategic Shifts
Sensor architectures are converging with building automation platforms while detection methods fuse multiple physical principles to reduce false occupancy signals in dynamic commercial environments.
Dual-technology detection is hybridizing passive infrared and ultrasonic sensing into single-housing units that cross-validate presence signals. Healthcare facilities and corporate campuses with open floor plans adopt these hybrid units fastest to eliminate lighting activation from thermal drafts and vibration. The technology is hybridizing market segmentation by collapsing the distinction between standard and premium product tiers.
The EU F-Gas Regulation and ASHRAE Standard 90.1 updates mandate automated controls in commercial retrofits exceeding specific floor areas. These policies compress decision timelines for facilities managers evaluating wired versus wireless infrastructure. Large commercial portfolios in Germany and the United States now specify hardwired networks as default to satisfy audit documentation requirements.
Facilities procurement teams now bundle sensor hardware with decade-long maintenance contracts rather than purchasing equipment outright. Johnson Controls and Schneider Electric capture this shift through platform subscriptions that monetize sensor data analytics. This unbundling of capital and service expenditures concentrates buying power among national account holders with multi-site portfolios.
Wired Occupancy Sensors Market Segmentation
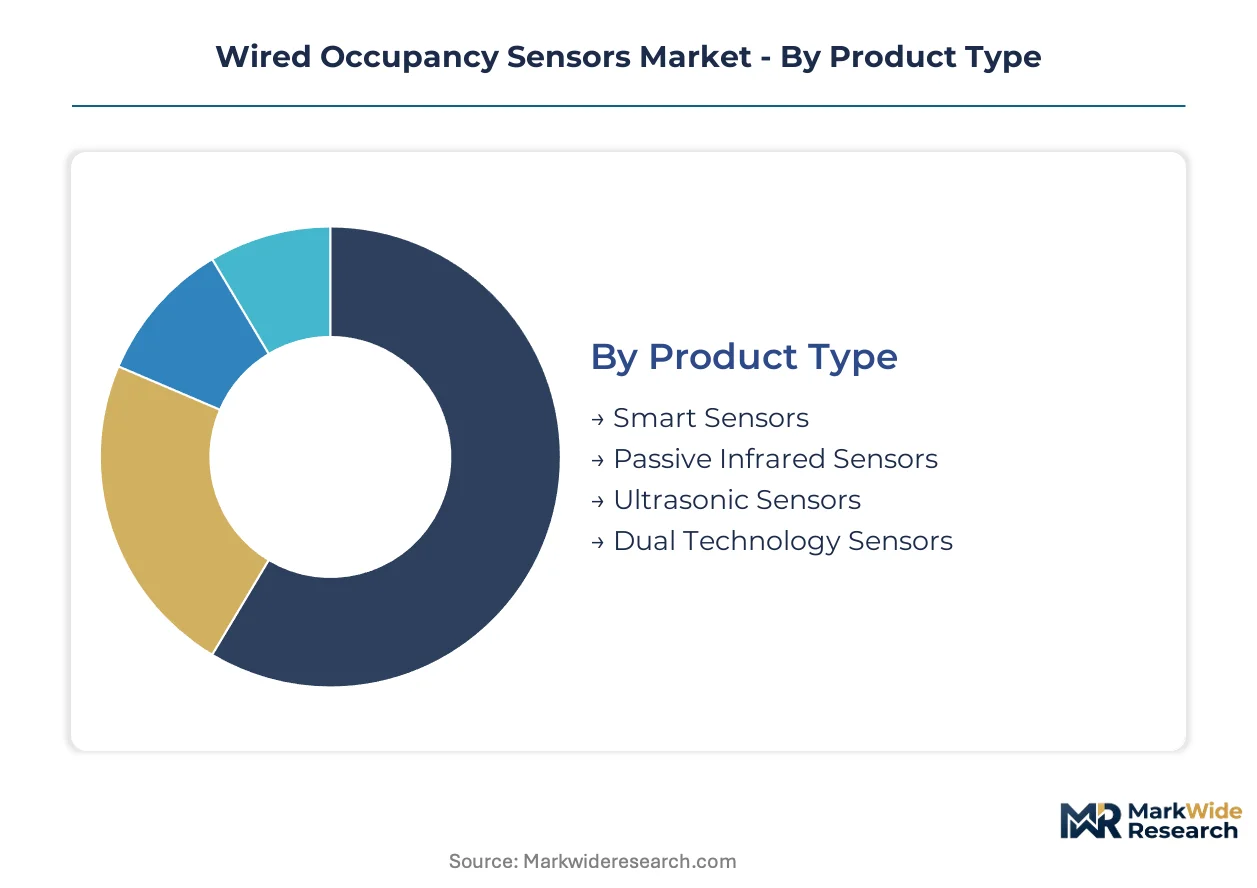
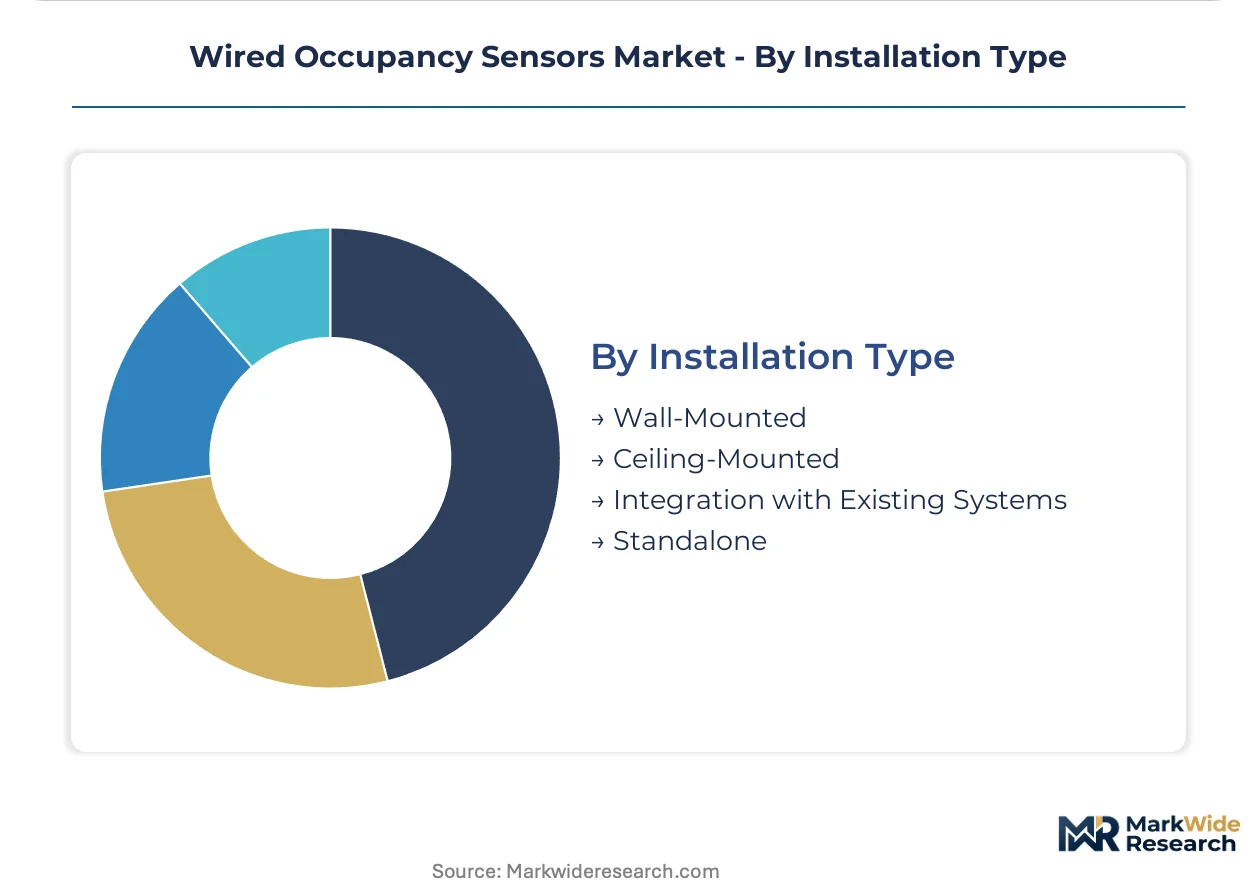
Product architecture, application intensity, and installation complexity fragment the wired occupancy sensor market into distinct commercial tiers. Vendors configure detection methods, mounting protocols, and system integration depth to match facility-specific energy compliance and operational requirements.
Product Type:
Mature infrared detection dominates volume shipments while emerging hybrid architectures reshape specification standards.
- Passive Infrared Sensors:Thermal motion detection operates through pyroelectric elements that sense body heat differentials against ambient background. Class A office portfolios in the United States specify these units under ASHRAE 90.1 compliance paths where utility rebates offset hardware costs.
- Dual Technology Sensors:Cross-validated infrared-ultrasonic detection eliminates false positives from HVAC air movement and vibration. German hospital corridors and open-plan corporate campuses specify these hybrid units fastest under EU Green Deal efficiency mandates that prioritize verified occupancy over scheduled controls.
- Smart Sensors:Microprocessor-embedded units with onboard analytics and network connectivity enable edge computing for occupancy pattern recognition.
- Ultrasonic Sensors:High-frequency sound wave detection excels in irregular room geometries where line-of-sight infrared coverage fails.
Passive Infrared Sensors handle the majority of throughput; Dual Technology Sensors is the fastest mover on share.
Application:
Energy compliance intensity varies sharply across building systems, concentrating margin in utility-integrated deployments.
- Energy Management:Sensor networks feed utility-grade metering and demand-response platforms with real-time occupancy data for automated load curtailment. FERC Order 2222 implementation enables wholesale electricity market participation through sensor-networked building enrollment.
- Lighting Control:Circuit-level automation triggers illumination based on verified presence rather than time schedules. Commercial retrofits in Germany accelerate deployment under EU Green Deal mandates that prioritize hardwired detection over wireless alternatives.
- HVAC Control:Zone-level climate adjustment reduces conditioning of unoccupied spaces in large floor plates.
- Security Systems:Presence verification integrates with access control and intrusion detection for facility protection.
Lighting Control absorbs the largest installation base; Energy Management captures the steepest expansion trajectory.
End User:
Building scale and regulatory exposure determine specification grade and contract structure.
- Commercial Buildings:Multi-tenant office towers and retail complexes deploy ceiling-mounted networks across Class A portfolios. United States utility rebate programs administered by FERC-aligned grid operators directly influence wired PIR and dual-technology specification requirements.
- Industrial Facilities:High-bay manufacturing and warehousing applications demand robust housings with extended detection ranges for motion in obstructed sightlines.
- Educational Institutions:Campus-wide retrofits bundle hardware with decade-long maintenance contracts rather than outright purchase.
- Residential Homes:Single-family and multi-family deployments concentrate in premium new construction with integrated home automation.
Commercial Buildings command the dominant share of specification volume; Industrial Facilities is gaining share fastest on automation intensity.
Installation Type:
Labor intensity and infrastructure compatibility shape retrofit versus new construction economics.
- Ceiling-Mounted:Grid penetration and conduit runs require certified low-voltage electricians for standard commercial applications. Installation labor intensity extends project timelines versus wireless alternatives but satisfies audit documentation requirements for EU Green Deal and ASHRAE 90.1 compliance.
- Integration with Existing Systems:BACnet and Modbus protocol middleware unifies sensor data streams with legacy building management systems. Johnson Controls and Schneider Electric capture this segment through platform subscriptions that monetize sensor data analytics.
- Wall-Mounted:Surface or recess mounting serves corridor and small-room applications where ceiling access is impractical.
- Standalone:Self-contained units with local relay control operate independently of network infrastructure.
Ceiling-Mounted handles the majority of commercial throughput; Integration with Existing Systems is expanding most quickly on platform convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German commercial retrofits deploy dual-technology sensors for EU Green Deal compliance, while United States Class A offices favor PIR units under utility rebate programs. This consumption-mix differential reflects tighter efficiency mandates in Europe versus incentive-driven adoption in North America.
United States
Class A office portfolios drive specification volume for wired PIR and dual-technology installations. ASHRAE Standard 90.1 and FERC-aligned utility rebate programs directly influence procurement requirements across new construction and major renovation projects. Manhattan and Chicago commercial towers concentrate deployment where audit documentation satisfies green building certification.
Germany
Hospital corridors and patient rooms generate accelerating demand for ultrasonic-infrared hybrid sensors that eliminate false triggers. EU Green Deal building efficiency mandates prioritize hardwired detection networks over wireless alternatives in large commercial retrofits. Munich and Frankfurt commercial districts anchor specification activity under national efficiency audit requirements.
China
Industrial facility automation and smart building initiatives in tier-one cities expand ceiling-mounted sensor deployment. GB standards and MIIT building efficiency guidelines shape procurement specifications for integrated energy management systems. Yangtze River Delta manufacturing clusters adopt dual-technology units for high-bay warehousing and production floor climate control.
Japan
Commercial building energy conservation drives METI-aligned specification of hardwired occupancy detection in Tokyo and Osaka office towers. JIS standards and national building efficiency codes mandate automated controls in retrofits exceeding defined floor areas. Nagoya automotive and electronics manufacturing campuses deploy hybrid sensors for zone-level HVAC optimization.
United Kingdom
London commercial retrofits and educational institution modernization projects accelerate wired sensor deployment under national net-zero building targets. The country's building efficiency regulations prioritize verified occupancy detection in public sector and multi-tenant office refurbishments. Southeast England commercial corridors concentrate specification activity for integrated lighting and climate control systems.
Wired Occupancy Sensors Market Competitive Environment
Capability concentration sits with building automation platform specialists; scale advantage sits with diversified electrical component conglomerates. The market structures around three tiers: integrated building management system vendors, standalone sensor specialists, and broad-line electrical manufacturers. Strategic archetypes include platform-anchored service bundlers, specification-driven premium specialists, and volume-oriented standard product suppliers. Dominant competitive moves encompass decade-long maintenance contract capture and middleware development for legacy system integration.
Within the platform-anchored tier, Johnson Controls and Schneider Electric represent the convergence of sensor hardware with enterprise energy dashboard subscriptions. Lutron Electronics occupies a position exemplifying specification-driven premium positioning in lighting control ecosystems. These three anchors illustrate how vendor strategy diverges between recurring platform revenue capture and upfront hardware specification dominance.
| Leading Market Players |
|---|
| Johnson Controls |
| Honeywell International |
| Schneider Electric |
| Eaton Corporation |
| Legrand |
| Texas Instruments |
| Acuity Brands |
| Leviton |
| Lutron Electronics |
| Others |
Value Chain & Pricing Dynamics
Yantian-to-Long Beach container freight corridors transmit East Asian foundry cost volatility into European and North American sensor pricing, compressing margins for ceiling-mounted PIR units while amplifying premium capture for dual-technology hybrids with certified cybersecurity documentation.
Pricing Analysis
Long-term offtake contracts dominate procurement for Class A office portfolios under FERC-aligned utility rebate programs, while spot purchasing persists in smaller commercial retrofits. Three-tier pricing structure across premium, standard, and economy levels separates dual-technology sensors with NIST Cybersecurity Framework certification from basic PIR units and unbranded commodity alternatives. Cost compression in standard PIR tiers is intensifying because semiconductor microcontroller shortages from concentrated Taiwanese foundry capacity. Educational institutions exhibit highest price sensitivity due to capital budget constraints, whereas healthcare facilities demonstrate lowest sensitivity given EU Green Deal compliance mandates and patient safety requirements.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for low-voltage DC wiring assemblies and pyroelectric sensor housings. Manufacturing concentrates in China, Taiwan, and South Korea for semiconductor microcontrollers, pyroelectric elements, and ultrasonic transducers. Raw material dependencies span copper for low-voltage cabling, rare earth elements for pyroelectric ceramics, and epoxy resins for sensor housing encapsulation. Single-source vulnerability persists for advanced MEMS ultrasonic transducers from specialized Japanese suppliers. Distribution runs through building automation system integrators and electrical wholesale distributors serving commercial construction channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as EU Green Deal and ASHRAE 90.1 mandates splinter procurement authority across facilities managers, energy consultants, and cybersecurity compliance officers, creating niche entry points for specialized vendors.
For Market Incumbents: Harden platform subscription revenue by embedding occupancy analytics into enterprise energy dashboards, countering wireless IoT substitution threats through BACnet middleware development. Backward integration into sensor microcontroller sourcing mitigates Taiwanese foundry concentration risk. Certification investment in NIST Cybersecurity Framework compliance extends product launch timelines but locks out unqualified competitors from federal and healthcare specifications. For New Entrants and Emerging Players: Build out healthcare corridor specialization in German hospital markets where dual-technology false-positive reduction commands specification premium. German commercial retrofits under EU Green Deal efficiency mandates represent the most penetrable geography given compressed decision timelines and audit documentation requirements. Go-to-market through energy consultant channel partnerships bypasses incumbent building automation vendor lock-in. For Investors and Strategic Acquirers: Building automation middleware specialists with legacy BACnet/Modbus protocol expertise anchor acquisition priority lists. Long-term viability frames around decade-long maintenance contract capture and recurring platform revenue conversion. Watch FERC Order 2222 demand-response program enrollment velocity as inflection indicator for sensor-networked building asset valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Schneider Electric's EcoStruxure convergence demonstrates enterprise dashboard subscription monetization. |
| Cybersecurity Certification | NIST Framework compliance extends product cycles but satisfies federal facility procurement requirements. |
| Long-term Service Contracting | Johnson Controls captures maintenance revenue through decade-long hardware-software bundled agreements. |
| Dual-Technology Product Launch | Ultrasonic-infrared hybrid units eliminate false positives in German hospital corridor specifications. |
| Backward Integration | Captive microcontroller sourcing insulates against Taiwanese foundry capacity volatility. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with facilities managers, building automation system integrators, electrical contractors, and energy consultants; and secondary validation through ASHRAE standards documentation, FERC regulatory filings, EU Green Deal mandate texts, and building automation vendor SEC disclosures. Bottom-up triangulation cross-checked sensor shipment estimates against utility rebate program enrollment data and commercial construction permit databases.
Forecast inputs span detection technology type, application intensity across lighting control and energy management, installation complexity tier, and regional regulatory framework clustering. Segmentation dimensions modeled include product architecture, end-use building type, and integration depth with legacy building management systems. CAGRs were derived from regression analysis against building efficiency mandate implementation timelines and utility incentive program budgets across the projection horizon. Industry-specific inputs incorporated copper price futures volatility and semiconductor foundry capacity utilization rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by wireless IoT sensor platforms or cybersecurity-first entrants would shift outcomes. Macroeconomic deviation in construction activity, regulatory acceleration of F-Gas phase-out schedules, or breakthrough battery longevity in wireless alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Environmental Noise Cancellation Microphones Market
Sensors and Controls
Motion Sensor Market
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
North America Sensor Market
Sensors and Controls
Capacitive Ceramic Pressure Sensors Market
Sensors and Controls
MEMS Microphones Market
Sensors and Controls
Piece-Level Inventory Tracking and Vision Systems Market
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Smart Temperature Management Market
Sensors and Controls
Air Quality Monitoring System Market
Sensors and Controls
Ambient Light Sensor Market
Sensors and Controls
In-Display Fingerprint Sensors Market
Sensors and Controls
Europe Human Machine Interface Market
Sensors and Controls
North America Fingerprint Sensor Market
Sensors and Controls
Ozone Meter Market