
 APAC Proximity Sensors Market | 2026-2036
APAC Proximity Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Proximity Sensors Market Outlook
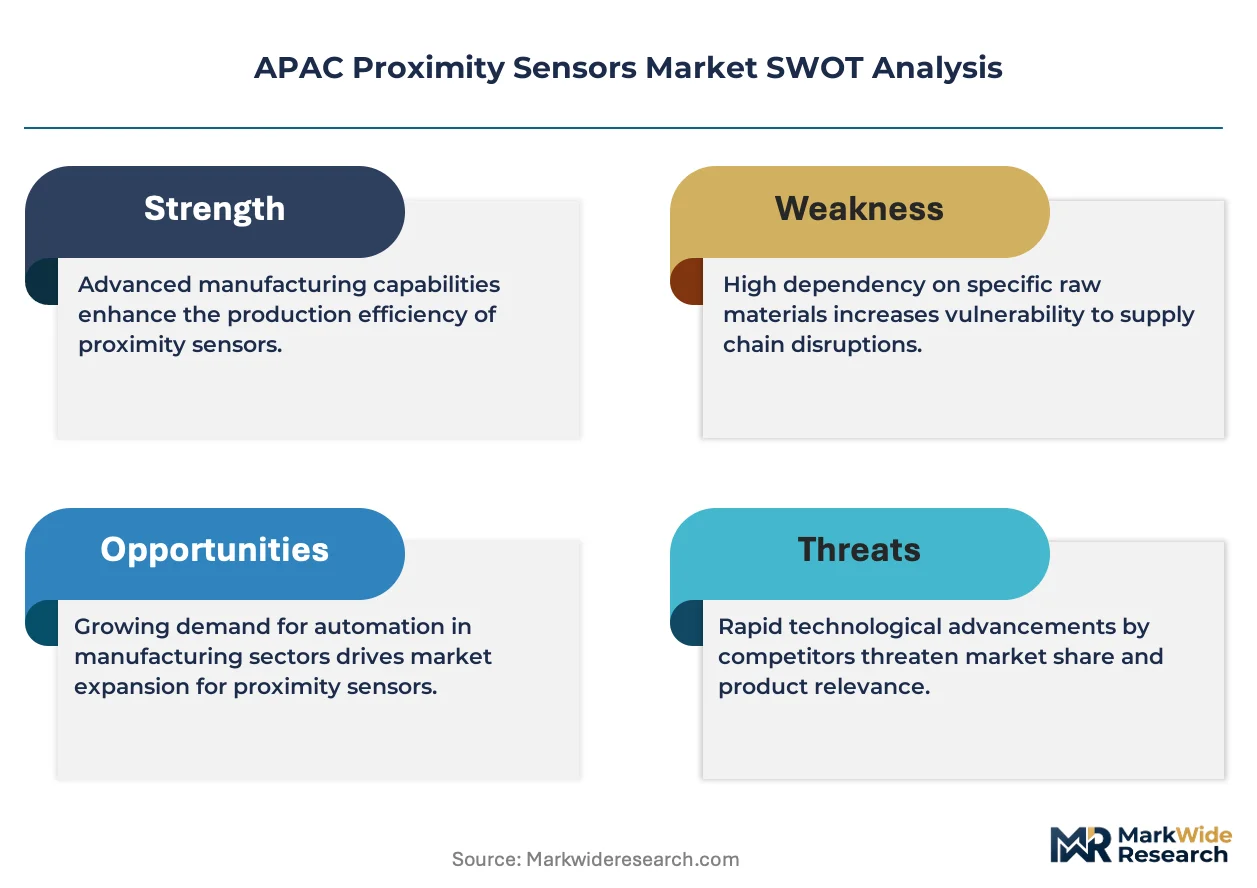
Asset-light leasing models for sensor testbeds is tilting competitive dynamics toward firms with flexible manufacturing footprints. Panasonic Corporation leverages captive semiconductor fabrication to control inductive sensor chip supply. Omron Corporation anchors its position through dense distribution networks across Japanese automotive tier-one suppliers. Keyence Corporation differentiates via high-margin direct sales channels that bypass traditional distributor markups.
Proximity sensors detect object presence without physical contact through electromagnetic fields, light beams, or ultrasonic pulses, typically operating at sensing distances from 0.2 mm to 60 mm depending on technology. Inductive variants dominate metal-detection tasks in machine tooling, while photoelectric types handle longer-range object recognition in packaging lines. Among end users, industrial automation commands the largest installed base, though robotics applications are expanding fastest as collaborative robot deployments multiply across South Korean and Chinese electronics factories. Embedded installation formats lead volume shipments, but surface-mount configurations are gaining share in miniaturized consumer electronics designs.
China's SAMR enforces GB standards that align proximity sensor electromagnetic compatibility with IEC benchmarks, while Japan's METI mandates industrial equipment energy-efficiency certifications that favor low-power digital sensor architectures. South Korea's MFDS and KOSHA frameworks govern workplace safety equipment incorporating proximity switches in heavy machinery guarding systems. Stakeholders must track how China's dual carbon goals reshape factory upgrade timelines and sensor replacement cycles across the region's manufacturing belt.
Market Dynamics
China's dual carbon goals are compressing factory upgrade timelines across the Yangtze River Delta manufacturing belt, forcing rapid sensor replacement cycles as industrial automation integrators retrofit legacy equipment with energy-efficient proximity detection systems.
Growth Catalysts
- GB Standard Harmonization:China's SAMR alignment of electromagnetic compatibility rules with IEC 60947-5-2 benchmarks is accelerating inductive sensor upgrades in automotive battery management systems.
- Electric Vehicle Production:Automotive OEMs in Japan and South Korea are expanding photoelectric sensor deployment for autonomous driving perception stacks and battery thermal monitoring.
- Smart Factory Retrofits:Industrial automation integrators in China's Jiangsu and Zhejiang provinces are sourcing embedded-format proximity sensors for legacy machining line modernization.
Market Restraints
- Semiconductor Supply Concentration:Captive fabrication capacity at Japanese and Korean chipmakers creates allocation bottlenecks for inductive sensor ASICs during demand spikes.
- Technical Distance Limitations:Inductive proximity sensors face hard physical caps near 60mm detection range, restricting deployment in large-format packaging and warehouse automation.
- Input Cost Volatility:Rare earth magnet price swings in Chinese processing hubs transmit directly to inductive coil production economics.
Strategic Opportunities
- Vietnam Manufacturing Migration:Electronics contract manufacturers relocating from China are creating greenfield demand for surface-mount proximity sensors in miniaturized consumer device assembly.
- Collaborative Robotics:South Korean electronics factories deploying cobots for precision assembly are driving ultrasonic proximity sensor adoption for human-machine safety zoning.
- Energy-Efficiency Mandates:Japan's METI low-power equipment certifications favor digital sensor architectures with sleep-mode functionality in machine tooling applications.
Industry Challenges
- Certification Timeline Compression:South Korea's KOSHA machinery safety approvals for proximity switches in heavy equipment guarding require extended validation cycles that delay product launches.
- Legacy System Integration:Japanese automotive tier-one suppliers face protocol translation complexity when mating IEC-standard digital sensors to existing analog PLC infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Proximity Sensors Market |
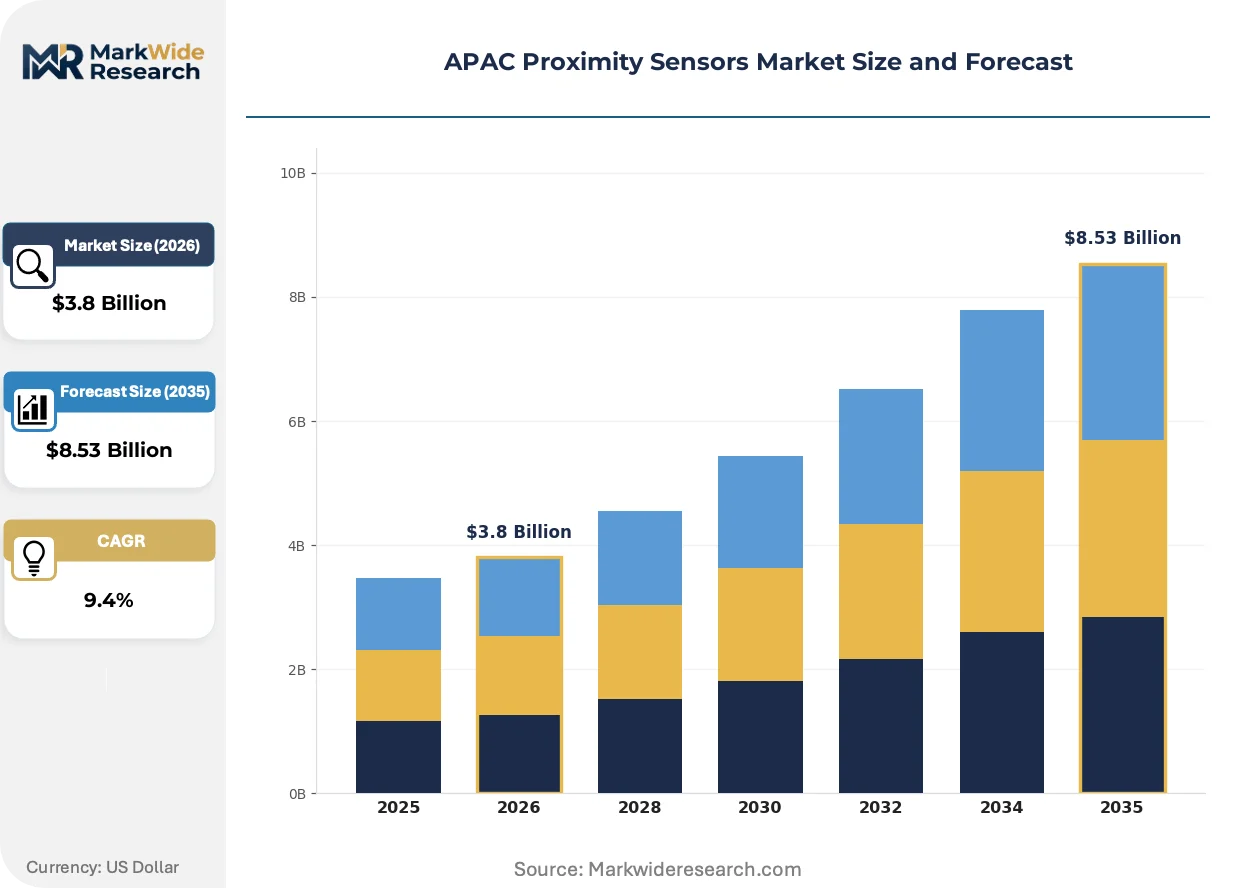
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic, Inductive, Capacitive, Photoelectric End User: Automotive OEMs, Consumer Electronics, Industrial Automation, Robotics Technology: Active, Passive, Analog, Digital Installation: Embedded, Surface-Mount, Through-Hole, Panel-Mount |
| Companies Covered | Panasonic Corporation, Omron Corporation, Keyence Corporation, Delta Electronics Inc, Autonics Corporation, Riko Opto-electronics Technology Co Ltd, Murata Manufacturing Co Ltd, TDK Corporation, SICK AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Proximity Sensors Market Strategic Shifts
Photoelectric sensing architectures are compressing form factors while extending operational ranges, altering how packaging and logistics operators specify detection equipment for high-speed line configurations.
Time-of-flight photoelectric sensors is collapsing the performance gap between short-range inductive and long-range ultrasonic alternatives in warehouse automation. Third-party logistics operators in South Korea are adopting these chips at accelerated pace for pallet detection. The technology is collapsing the traditional three-tier sensor specification hierarchy into a single-platform procurement model.
China's GB standard harmonization with IEC electromagnetic compatibility benchmarks is mandating shielding upgrades across inductive sensor product lines. Industrial equipment exporters must now dual-certify for domestic SAMR compliance and international IEC acceptance. Automotive battery pack manufacturers in the Yangtze River Delta are absorbing the compliance cost fastest to maintain OEM qualification status.
Direct manufacturer engagement is displacing traditional distributor relationships in high-volume sensor procurement. Japanese automotive tier-one suppliers are negotiating frame contracts that bypass regional wholesaler markups for proximity switch volumes. South Korean electronics factories exhibit the sharpest procurement pattern shift, consolidating annual sensor spend with single-source technical partnerships rather than spot-market purchasing.
APAC Proximity Sensors Market Segmentation
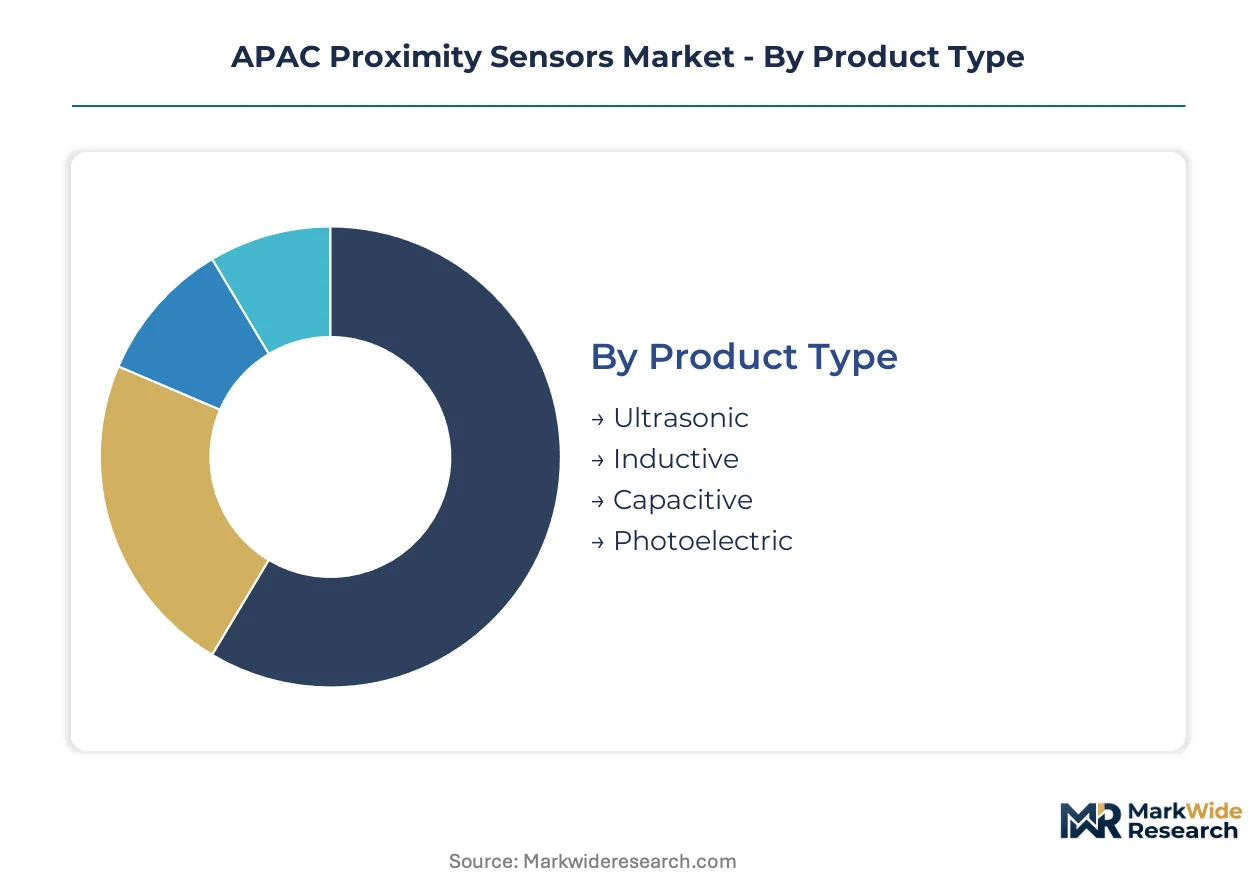
Proximity sensor procurement patterns across the APAC region diverge sharply by detection physics, end-use environment, and integration format. Understanding these segment boundaries clarifies why inductive variants dominate automotive battery management while photoelectric architectures capture logistics automation spend.
Product Type:
Cost tier positioning separates commodity metal-detection solutions from premium optical and ultrasonic platforms with extended range capabilities.
- Inductive:Electromagnetic coil assemblies detect ferrous and non-ferrous metals through eddy current induction, typically rated for 0.2 mm to 60 mm sensing distances. China's Yangtze River Delta machine tool builders source these in volume for CNC positioning feedback, though rare earth magnet price volatility in Chinese processing hubs compresses margin stability for coil manufacturers.
- Photoelectric:LED emitter and photodetector pairs modulate light beams for object recognition across 100 mm to 10 meter ranges. South Korean third-party logistics operators are adopting time-of-flight photoelectric chips at accelerated pace for pallet detection in high-bay warehouse configurations.
- Ultrasonic:Piezoelectric transducers emit high-frequency pulses for non-contact distance measurement through air or liquid media. Japanese automotive tier-one suppliers specify these for battery pack liquid cooling level monitoring.
- Capacitive:Electrode plates sense dielectric constant changes to detect metallic and non-metallic targets including plastics and liquids. Consumer electronics assemblers in Vietnam deploy surface-mount capacitive variants for smartphone proximity detection.
Inductive proximity sensors command the established base across the region's metalworking industries. The steepest expansion runs through photoelectric architectures as warehouse automation integrators consolidate on single-platform procurement models.
End User:
Application maturity varies from established factory automation deployments to emerging robotics safety zoning requirements.
- Industrial Automation:Machine tooling, packaging lines, and material handling systems constitute the largest installed base of proximity detection equipment. Jiangsu and Zhejiang province integrators are retrofitting legacy machining centers with embedded-format inductive sensors to meet China's dual carbon efficiency mandates.
- Automotive OEMs:Battery management systems and autonomous driving perception stacks drive specification complexity. Japanese and South Korean electric vehicle manufacturers are expanding photoelectric sensor deployment for thermal monitoring and LiDAR complementation.
- Robotics:Collaborative robot deployments multiply across South Korean and Chinese electronics factories. Ultrasonic proximity sensors enable human-machine safety zoning without physical guarding barriers.
- Consumer Electronics:Miniaturized assembly processes in Vietnam and Indonesia require surface-mount proximity detection for device assembly verification. Contract manufacturers relocating from China create greenfield demand for compact form factor sensors.
Industrial automation maintains the deepest penetration across the region's manufacturing belt. Robotics applications are climbing the fastest as cobot deployment accelerates in precision electronics assembly.
Technology:
Signal processing architecture determines power consumption, noise immunity, and protocol compatibility with legacy control systems.
- Digital:Microcontroller-based architectures with sleep-mode functionality reduce standby power draw. Japan's METI energy-efficiency certifications favor these low-power designs in machine tooling applications across Osaka and Nagoya industrial corridors.
- Analog:Continuous voltage or current output signals interface directly with legacy PLC infrastructures. Japanese automotive tier-one suppliers face protocol translation complexity when mating IEC-standard digital sensors to existing analog control networks.
- Active:Externally powered detection circuits with amplified output stages. These dominate high-reliability applications in South Korean heavy machinery guarding systems subject to KOSHA safety approvals.
- Passive:Self-powered magnetic or inductive switches requiring no external supply voltage. Mining and outdoor equipment manufacturers in Australia specify these for explosion-risk environments.
Analog technology retains substantial legacy infrastructure lock-in across Japanese manufacturing. Digital architectures are gaining share fastest where METI efficiency mandates drive control system modernization.
Installation:
Physical integration format dictates thermal management, electromagnetic shielding, and field service accessibility.
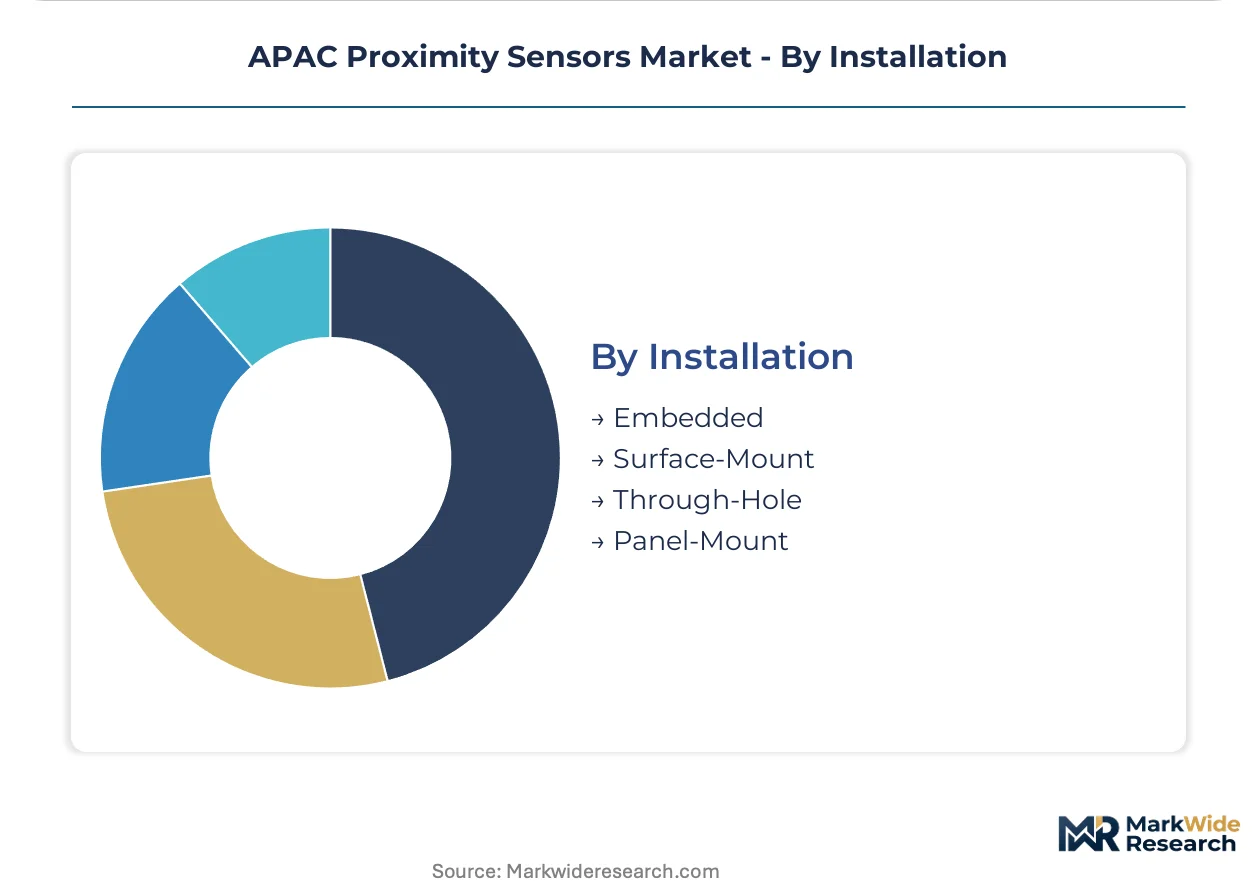
- Embedded:Cylindrical or rectangular housings mount flush within machine structures. These lead volume shipments for smart factory retrofits in China's manufacturing clusters where space constraints limit external sensor mounting.
- Surface-Mount:Low-profile packages solder directly to printed circuit boards. Vietnam electronics contract manufacturers specify these for miniaturized consumer device assembly where through-hole mounting consumes excessive board area.
- Through-Hole:Leaded packages pass through PCB vias for mechanical stability. Industrial control board manufacturers in Taiwan continue specifying these for high-vibration environments.
- Panel-Mount:Threaded or snap-in housings secure to equipment enclosures. South Korean heavy machinery builders source these for operator-accessible proximity switch replacement in guarding systems.
Embedded formats dominate current procurement volumes across the region's machining and packaging sectors. Surface-mount configurations are expanding most quickly as electronics manufacturing migrates to Vietnam and Indonesia greenfield facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing clusters across the region drive sensor demand asymmetries, with component-importing assembly hubs in Vietnam and Indonesia contrasting against chip-fabricating economies in Japan and South Korea. Trade flows concentrate precision sensing hardware in coastal industrial corridors while inland provinces absorb retrofit equipment for legacy automation upgrades.
China
Automotive battery management systems and smart factory retrofits absorb the bulk of inductive sensor volumes. SAMR's GB standard harmonization with IEC 60947-5-2 compels electromagnetic compatibility upgrades across product lines. The Yangtze River Delta manufacturing cluster hosts industrial automation integrators sourcing embedded-format proximity sensors for CNC machining line modernization.
Japan
Electric vehicle thermal monitoring and autonomous driving perception stacks expand photoelectric sensor procurement. METI energy-efficiency certifications favor low-power digital architectures with sleep-mode functionality in machine tooling. The Chubu industrial corridor around Nagoya anchors automotive tier-one supplier demand for protocol-compatible sensing solutions.
South Korea
Collaborative robot deployments in electronics factories accelerate ultrasonic proximity sensor adoption for human-machine safety zoning. KOSHA machinery safety approvals govern proximity switch integration in heavy equipment guarding systems. The Seoul Capital Area concentrates third-party logistics operators adopting time-of-flight photoelectric chips for high-bay warehouse pallet detection.
Vietnam
Electronics contract manufacturers relocating from China generate greenfield demand for surface-mount proximity sensors in miniaturized consumer device assembly. The country's national industrial standards regulator mandates electromagnetic compatibility testing for imported sensing equipment. Northern industrial provinces around Hanoi and Hai Phong host new assembly facilities specifying compact form factor sensors.
Australia
Mining and outdoor equipment manufacturers specify passive magnetic switches for explosion-risk environments where external power supplies pose safety hazards. The country's national workplace safety regulator enforces machinery guarding standards incorporating proximity detection. Western Australia's Pilbara region drives demand for ruggedized sensing hardware in autonomous haulage systems.
APAC Proximity Sensors Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying discrete sensing elements to automation OEMs. The vendor base stratifies across three tiers: captive semiconductor fabricators controlling inductive sensor ASIC supply, direct-sales specialists bypassing distributor markups, and regional distributors serving fragmented machine builder demand. Strategic archetypes include backward-integrated chipmakers, high-margin direct-channel operators, and asset-light leasing providers. Competitive moves center on frame contract negotiations with automotive tier-one suppliers and flexible manufacturing footprint expansion.
Among Japanese fabricators, Panasonic Corporation, Omron Corporation, and Keyence Corporation exemplify divergent channel strategies. Panasonic Corporation occupies a position anchored in captive semiconductor fabrication. Omron Corporation sits within the dense distribution network archetype serving domestic automotive suppliers. Keyence Corporation represents the direct-sales model eliminating intermediary markups. These three patterns illustrate how geographic concentration generates structural differentiation rather than price-based competition.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Omron Corporation |
| Keyence Corporation |
| Delta Electronics Inc |
| Autonics Corporation |
| Riko Opto-electronics Technology Co Ltd |
| Murata Manufacturing Co Ltd |
| TDK Corporation |
| SICK AG |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Nagoya container corridor's freight cost volatility transmits directly into sensor landed costs, amplifying pricing power for Japanese captive fabricators while compressing margins for distributors serving Vietnam's electronics assemblers. This logistics chokepoint concentrates cost differentiation between inductive coil manufacturers with backward-integrated magnet supply and photoelectric assemblers importing LED emitters from Taiwan.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on METI energy-efficiency certification grade and volume scale commitments from automotive tier-one suppliers. Cost compression in standard-tier inductive sensors is intensifying because Chinese rare earth processing hubs transmit magnet price swings directly to coil economics. Contract manufacturers in Vietnam exhibit the sharpest price sensitivity, while Japanese automotive OEMs absorb premium-tier markups for protocol-compatible digital architectures.
Supply Chain Analysis
Export controls on semiconductor manufacturing equipment limit ASIC fabrication capacity expansion outside Japan and South Korea, constraining inductive sensor chip supply elasticity. Geographic supply concentration centers on Japan, South Korea, and Taiwan for photodetector components and China for rare earth magnet processing. Raw material dependencies include neodymium-iron-boron magnets, gallium arsenide wafers, and epoxy molding compounds. Single-source vulnerability runs through Japanese captive fabricators controlling inductive sensor ASIC supply. Distribution runs through direct manufacturer engagement displacing regional wholesaler markups in high-volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GB standard harmonization with IEC electromagnetic compatibility benchmarks is compressing certification timelines and forcing rapid product line upgrades across the APAC manufacturing belt. This regulatory inflection creates asymmetric advantage for fabricators with captive testing infrastructure.
For Market Incumbents: Harden ASIC supply security through capacity reservations at Japanese and Korean foundries before allocation bottlenecks intensify during EV battery management system demand spikes. Deepen channel control by negotiating frame contracts with automotive tier-one suppliers that bypass distributor markups and lock in multi-year volumes. For New Entrants and Emerging Players: Vietnam's northern industrial provinces around Hanoi and Hai Phong represent the most penetrable entry point for surface-mount proximity sensors serving electronics contract manufacturers relocating from China. Target collaborative robotics safety zoning applications in South Korean electronics factories where ultrasonic proximity detection specifications remain fluid. Pursue technical partnership positioning with single-source procurement officers rather than spot-market distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized sensor divisions lacking direct sales infrastructure. Long-term viability favors specialists with captive semiconductor fabrication or dense METI certification pipelines. Watch for KOSHA approval timeline compression as an inflection signal indicating regulatory capacity constraints that favor incumbent scale advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Captive ASIC Fabrication Expansion | Panasonic's in-house chip production insulates inductive sensor supply from Taiwan foundry allocation bottlenecks. |
| Direct Sales Channel Buildout | Keyence's bypass of regional distributor markups captures margin premium from Japanese automotive tier-one suppliers. |
| GB-IEC Dual Certification Investment | SAMR electromagnetic compatibility alignment opens Yangtze River Delta battery management system qualification. |
| Vietnam Surface-Mount Capacity Addition | Greenfield electronics assembly facilities in Hai Phong province drive compact form factor sensor demand. |
| Time-of-Flight Photoelectric Platform Launch | South Korean third-party logistics operators adopt single-platform procurement collapsing three-tier sensor hierarchies. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with automation OEM procurement teams, industrial integrators, and semiconductor fabrication planners; and secondary validation through customs trade records, METI efficiency certification databases, and SAMR regulatory filings. Bottom-up sensor shipment estimates from Chinese machine tool builders triangulated against top-down automotive OEM content-per-vehicle assumptions.
Forecast inputs considered detection technology physics, installation format adoption curves, and end-use vertical expansion rates across the projection horizon. Segmentation dimensions modeled include product type, signal processing architecture, and regional regulatory cluster. CAGRs derived from install base replacement cycles, factory automation retrofit timelines, and EV production ramp assumptions. Industry-specific inputs incorporated rare earth magnet price elasticity and KOSHA approval queue lengths.
Practitioners should monitor SAMR enforcement intensity and dual carbon goal acceleration for early signals of demand inflection. Forecasts reflect assumptions on GB standard implementation pace and semiconductor fabrication capacity expansion. Material shifts in export control regimes or METI efficiency mandate scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Fingerprint Module Market
Sensors and Controls
Semiconductor Sensor Market
Sensors and Controls
Motion Sensor Market
Sensors and Controls
Optical Chemical Sensor Market
Sensors and Controls
Distributed Acoustic Sensing (DAS) Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Surface Vision and Inspection Market
Sensors and Controls
Sensor Hub Market
Sensors and Controls
APAC Chemical Sensors Market
Sensors and Controls
APAC Vibration Sensors Market
Sensors and Controls
Electromagnetic Tracking Systems Market
Sensors and Controls
Wireless IoT Sensors Market
Sensors and Controls
APAC Temperature Sensors Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Asia-Pacific Current Transducer Market
Sensors and Controls
Canada Digital Thermometer Market