
 GCC Oral Hygiene Market | 2026-2036
GCC Oral Hygiene Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Oral Hygiene Market Intelligence
Bundle configurations pairing toothpaste with mouthwash or whitening strips are shifting buyer choice toward value-oriented multi-product sets across GCC retail channels. Procter & Gamble leverages its shelf-space dominance in Saudi hypermarkets to anchor premium bundle placement. Colgate-Palmolive differentiates through specialized sensitivity formulations targeting the region's high incidence of dental erosion. Haleon plc competes via pharmacy channel control, where pharmacist recommendations drive therapeutic product selection.
Oral hygiene encompasses mechanical and chemical interventions for plaque removal, breath freshening, and enamel preservation, including formulations with fluoride concentrations between 1000-1500 ppm for caries prevention and hydrogen peroxide levels up to 6% for supervised whitening applications. Toothpaste occupies the largest margin pool due to daily-use frequency and premiumization potential, while whitening products represent the fastest-growing category as aesthetic dental concerns rise among younger Gulf consumers. Pharmacy distribution channels sustain higher per-unit economics than supermarkets because of professional endorsement requirements for therapeutic claims.
SFDA enforces ingredient disclosure and concentration limits for peroxide-based whitening products in Saudi Arabia, while MOHAP regulates therapeutic oral care claims across the UAE, with both agencies requiring Arabic-English bilingual labeling. These frameworks elevate compliance costs for new entrants but protect established players with dedicated regulatory affairs capacity. Stakeholders must monitor harmonization talks between Gulf standards bodies, as unified labeling and testing protocols would reshape market access requirements across the six member states.
Market Dynamics
Professional endorsement requirements across Saudi Arabia, the UAE, and Kuwait are concentrating purchase authority in pharmacist and dental clinician networks, compressing traditional retail influence and elevating compliance investment as the primary competitive barrier.
Growth Catalysts
- SFDA Registration Mandates:Saudi Arabia's tightening peroxide concentration limits for whitening agents force formulation upgrades that established players absorb faster than entrants, consolidating shelf access.
- Dental Clinic Channel Expansion:Professional care settings in Riyadh and Jeddah now recommend bundled preventive and aesthetic products, pulling volume from unaided supermarket selection.
- Urban Per-Capita Spending Concentration:The Riyadh-Jeddah corridor outpaces other Gulf states in oral care expenditure, rewarding distribution infrastructure investment in Saudi Arabia's dense metropolitan zones.
Market Restraints
- MOHAP Therapeutic Claim Friction:UAE regulators require clinical substantiation for sensitivity and gum health messaging, extending product launch timelines and legal review costs.
- Active Ingredient Import Dependence:Hydrogen peroxide and stabilized fluoride compounds concentrate in European and Asian chemical suppliers, exposing margins to currency and shipping volatility.
- Substitution from Professional Whitening:In-clinic laser and tray-based treatments in Dubai and Abu Dhabi capture aesthetic demand that over-the-counter strips cannot satisfy.
Strategic Opportunities
- Kuwait Pharmacy Network White Space:Independent and chain pharmacies in Kuwait City and Al Ahmadi remain underdeveloped for therapeutic oral care compared to Saudi and UAE counterparts.
- Smart Dispensing Convergence:IoT-enabled brushing monitors and app-connected rinse systems create data-capture platforms that dental insurers in the UAE are piloting for preventive coverage incentives.
- Arabic-English Bilingual Label Harmonization:Ongoing Gulf standards body discussions toward unified packaging requirements would reduce SKU complexity for manufacturers serving multiple member states.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Firms struggle to hire bilingual specialists capable of navigating simultaneous SFDA and MOHAP submission pathways.
- Cold Chain Integrity for Probiotic Formulations:Temperature-sensitive oral microbiome products require refrigerated transport infrastructure that Gulf logistics networks only partially cover.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Oral Hygiene Market |
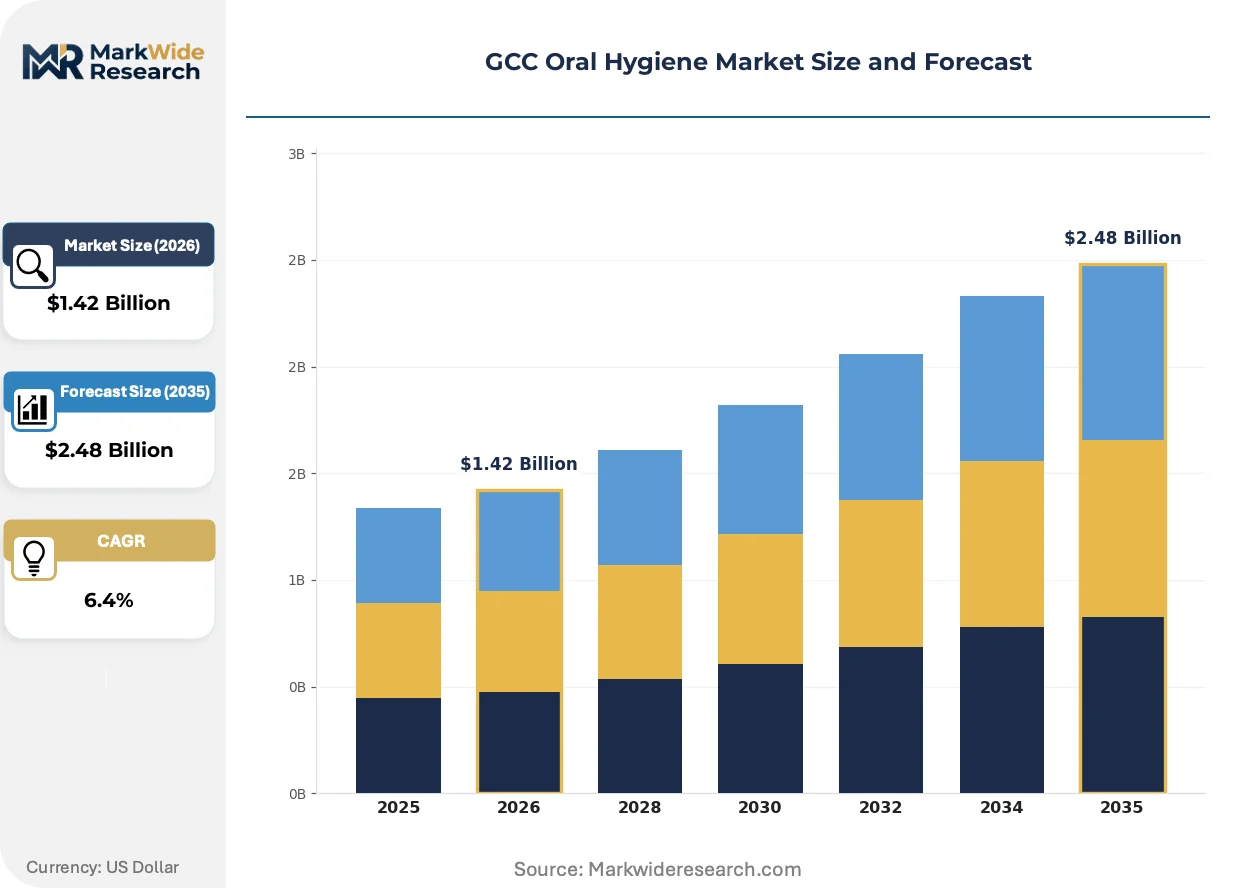
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Dental Floss, Whitening Products End User: Adults, Children, Seniors, Pregnant Women Distribution Channel: Online Retail, Supermarkets, Pharmacies, Convenience Stores Packaging Type: Tubes, Bottles, Sachets, Pumps |
| Companies Covered | GlaxoSmithKline PLC, Sunstar Suisse, Procter & Gamble, Haleon plc, Lion Corporation, Colgate-Palmolive Company, Johnson & Johnson, Church & Dwight Co., Inc., Unilever PLC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Oral Hygiene Market Strategic Shifts & Innovations
Formulation science and professional channel control are displacing mass-market brand loyalty across GCC oral hygiene, with technology-enabled personalization and regulatory compliance emerging as the twin axes of competitive differentiation.
Enamel remineralization systems incorporating bioactive glass and casein phosphopeptide-amorphous calcium phosphate are expanding into premium daily-use toothpaste positioned for the region's high dental erosion incidence. Younger consumers in Saudi Arabia's urban centers adopt these chemistries fastest, pulling manufacturers toward ingredient transparency claims that exceed baseline fluoride disclosure.
SFDA and MOHAP are synchronizing inspection protocols for manufacturing facilities supplying both markets, raising audit frequency and documentation standards for GMP compliance. Dual-registered production sites in Jeddah and Dubai now face unannounced verification visits that compress batch release timelines and elevate quality system investment.
Pharmacist recommendation networks in Abu Dhabi and Riyadh are displacing unassisted retail selection for therapeutic-segment purchases, with clinic-affiliated dispensaries capturing whitening and sensitivity categories. This channel consolidation rewards firms with dedicated medical affairs teams capable of clinical education and formulary negotiation.
GCC Oral Hygiene Market Segmentation
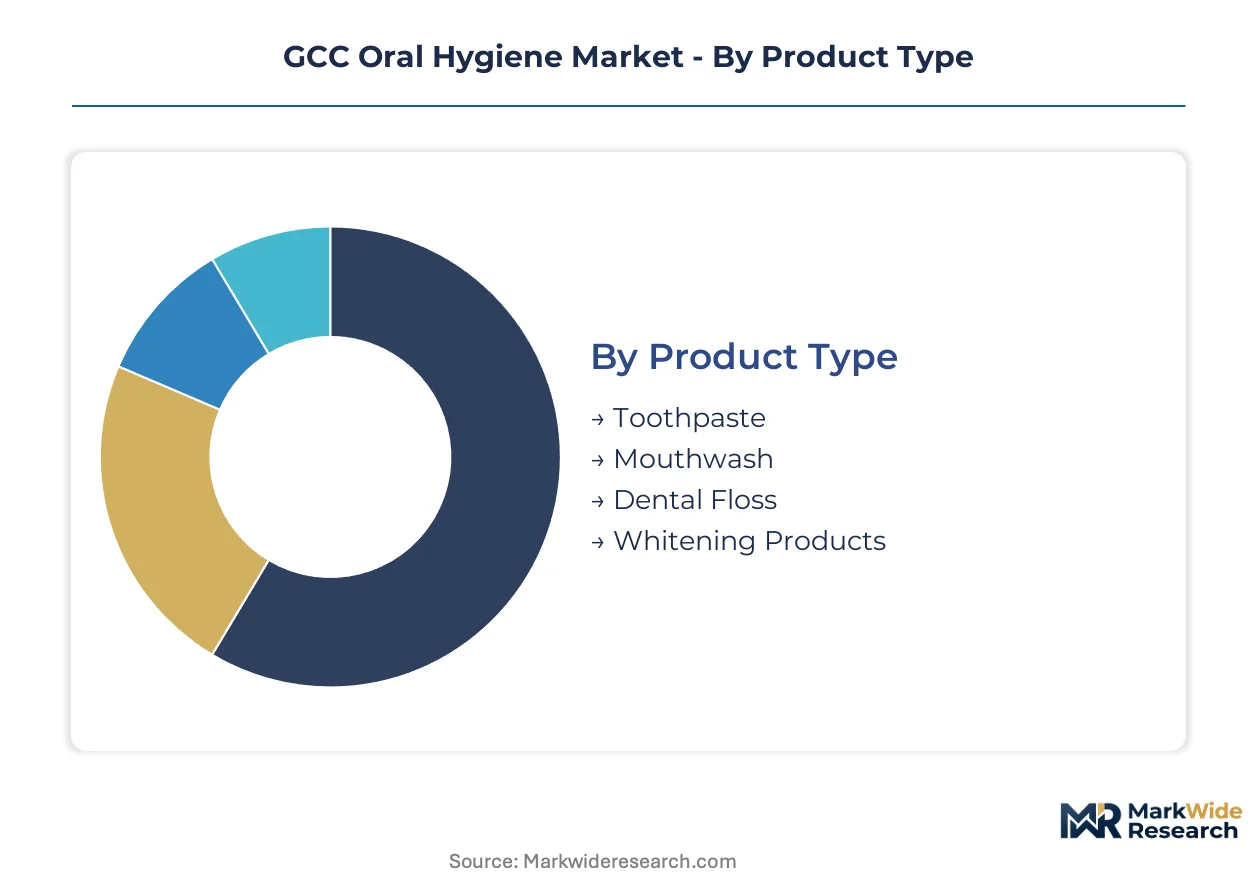
Oral hygiene purchasing patterns across Saudi Arabia, the UAE, and Kuwait fragment sharply across product form, user life stage, and channel access. Manufacturers must align formulation portfolios and distribution investments to these distinct demand clusters to capture margin.
Product Type:
Toothpaste functions as the standalone daily-use anchor, while adjunct products embed into broader preventive or aesthetic routines.
- Toothpaste:Fluoride concentrations between 1000-1500 ppm dominate formulations for caries prevention. Demand concentrates in Saudi Arabia's Riyadh-Jeddah corridor where per-capita spending outpaces other Gulf states, with premiumization pulling toward enamel remineralization variants containing bioactive glass.
- Whitening Products:Hydrogen peroxide levels up to 6% characterize supervised-use strips and trays. Younger consumers in Dubai and Abu Dhabi drive aesthetic demand fastest, though in-clinic laser treatments capture share that over-the-counter formulations cannot satisfy.
- Mouthwash:Therapeutic formulations with cetylpyridinium chloride or essential oils target breath freshening and gum health claims requiring MOHAP clinical substantiation in the UAE.
- Dental Floss:Waxed and unwaxed nylon or PTFE monofilament variants serve mechanical plaque removal needs with lower purchase frequency than paste or rinse categories.
Toothpaste leads volumes today; whitening products are gaining share fastest.
End User:
Life-stage segmentation determines formulation sensitivity, flavor profiles, and professional recommendation pathways.
- Adults:The largest addressable base across all GCC markets, spanning preventive maintenance through aesthetic enhancement needs with full access to therapeutic and cosmetic product ranges.
- Children:Lower fluoride concentrations and flavor-optimized formulations address safety and compliance concerns. Saudi Arabia's pediatric dental clinic networks in Riyadh and Jeddah increasingly recommend age-appropriate bundled sets.
- Seniors:Dry mouth and gum recession formulations concentrate demand in pharmacy channels where pharmacist endorsement substitutes for declining self-selection capacity.
- Pregnant Women:Gingivitis-prevention formulations without alcohol or harsh antimicrobials attract recommendation-driven purchasing in clinic-affiliated dispensaries across Abu Dhabi and Dubai.
Adults dominate absolute consumption; children's segments show the steepest expansion trajectory as pediatric dental awareness campaigns intensify across Saudi Arabia.
Distribution Channel:
Channel economics diverge sharply between professional-endorsed and self-service purchase environments.
- Pharmacies:Therapeutic claims and whitening products requiring professional guidance concentrate here. Pharmacist recommendation networks in Riyadh and Abu Dhabi displace unassisted selection, rewarding firms with dedicated medical affairs teams.
- Supermarkets:Bundle configurations pairing toothpaste with mouthwash or adjunct products shift volume toward value-oriented multi-product sets, with shelf-space dominance in Saudi hypermarkets anchoring premium placement.
- Online Retail:Subscription and replenishment models gain traction among urban Saudi and UAE consumers seeking convenience, though regulatory compliance for peroxide-based whitening limits direct-to-consumer expansion.
- Convenience Stores:Emergency and travel-size purchases dominate, with sachet and small-format packaging addressing immediate need states rather than planned replenishment.
Pharmacies capture the highest per-unit economics; online retail is climbing the fastest as digital payment infrastructure matures across the Gulf.
Packaging Type:
Format selection intersects with usage occasion, portability requirements, and shelf-life engineering.
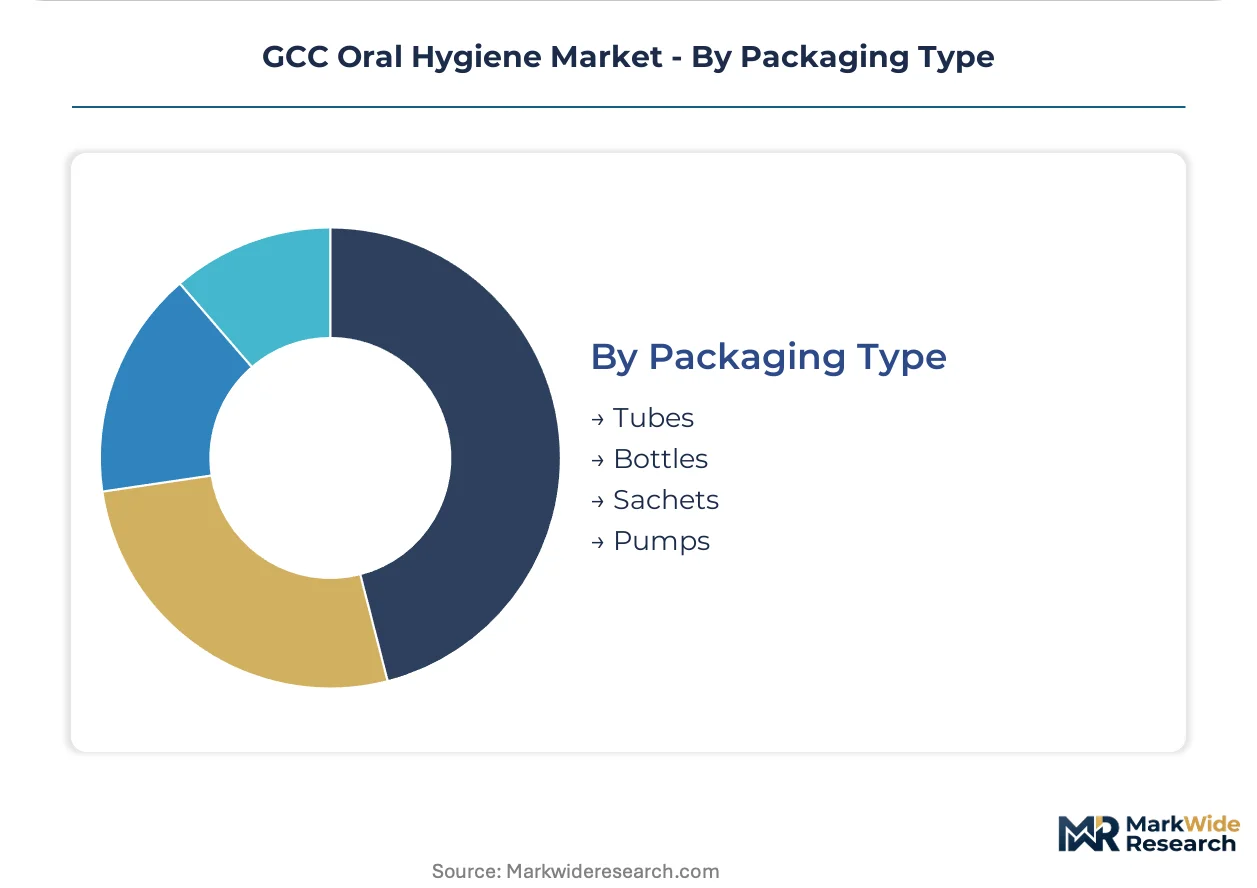
- Tubes:Laminated aluminum-plastic multilayer structures dominate toothpaste delivery, with Arabic-English bilingual labeling requirements elevating print complexity for SFDA and MOHAP compliance.
- Bottles:PET and HDPE containers serve mouthwash volumes, with child-resistant closures mandatory for therapeutic formulations containing higher active concentrations.
- Sachets:Single-use foil pouches address travel and trial occasions across Kuwait's pharmacy and convenience networks, with lower per-unit margins offset by penetration in underdeveloped therapeutic segments.
- Pumps:Metered-dose dispensing systems appear in premium mouthwash and specialized rinse formats, supporting dosage compliance claims that differentiate clinical-positioned products.
Tubes maintain volume leadership; pumps are expanding most quickly as premium positioning accelerates across UAE pharmacy channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oral hygiene distribution across the Gulf Cooperation Council traces its modern structure to the 1970s oil-boom era, when multinational consumer goods firms established beachheads in Jeddah and Dubai to serve expatriate and emerging local middle-class demand. Today the six member states present distinct regulatory and channel environments.
Saudi Arabia
SFDA registration mandates for whitening agents and therapeutic claims create compliance barriers that favor established players with dedicated regulatory affairs teams. The Riyadh-Jeddah corridor concentrates per-capita oral care spending above other Gulf states, with dental clinic networks in these cities now driving bundled product recommendations. Pediatric dental awareness campaigns in Riyadh are accelerating children's segment growth faster than adult categories.
United Arab Emirates
MOHAP requirements for clinical substantiation of sensitivity and gum health messaging extend product launch timelines, compressing margins for entrants lacking legal review capacity. Dubai and Abu Dhabi host the region's most developed in-clinic laser whitening services, capturing aesthetic demand that over-the-counter strips cannot satisfy. Pharmacist recommendation networks in these emirates displace unassisted retail selection for therapeutic purchases.
Kuwait
Independent and chain pharmacies in Kuwait City and Al Ahmadi remain underdeveloped for therapeutic oral care compared to Saudi and UAE counterparts, presenting white-space opportunity for firms with medical affairs capabilities. The country's smaller population base limits absolute volume but sustains higher per-unit economics through import-dependent supply chains. Sachet and travel-format packaging penetrates convenience networks more deeply than in larger neighbors.
Qatar
Doha's concentrated high-income demographic supports premium positioning for enamel remineralization and smart dispensing systems, with dental insurers piloting IoT-connected brushing monitors for preventive coverage incentives. Regulatory alignment with Saudi SFDA standards simplifies market access for dual-registered manufacturers. Clinic-affiliated dispensaries in West Bay and The Pearl capture whitening category volume ahead of traditional retail.
Bahrain
The kingdom's compact geography enables rapid pharmacy channel coverage, though absolute market size limits infrastructure investment returns compared to Saudi Arabia or the UAE. MOHAP-influenced therapeutic claim standards apply through Gulf harmonization discussions, elevating documentation requirements for sensitivity formulations. Manama's dental clinic density per capita exceeds regional averages, intensifying professional endorsement competition.
GCC Oral Hygiene Market Key Industry Players
Premium-margin players sit above commodity-margin players across pharmacy channel control and regulatory compliance capacity, with the GCC oral hygiene market consolidating around multinational consumer health conglomerates with established SFDA and MOHAP registration pathways. The competitive structure rewards firms possessing bilingual regulatory affairs specialists and medical education teams capable of formulary negotiation with clinic networks. Three archetypes dominate: diversified consumer health giants with shelf-space dominance, specialized oral care firms with therapeutic positioning, and regional distributors with pharmacy network relationships. Capacity expansion into Jeddah and Dubai production facilities and strategic partnerships with dental clinic chains constitute the dominant competitive moves.
Within the diversified consumer health tier, Procter & Gamble, Colgate-Palmolive Company, and Haleon plc exemplify scale-driven positioning. Procter & Gamble occupies shelf-space dominance in Saudi hypermarkets, anchoring premium bundle placement through established retail relationships. Colgate-Palmolive Company represents specialized sensitivity formulation capabilities targeting the region's high dental erosion incidence. Haleon plc sits within the pharmacy channel control archetype, where pharmacist recommendations drive therapeutic product selection across Abu Dhabi and Riyadh networks.
| Leading Market Players |
|---|
| GlaxoSmithKline PLC |
| Sunstar Suisse |
| Procter & Gamble |
| Haleon plc |
| Lion Corporation |
| Colgate-Palmolive Company |
| Johnson & Johnson |
| Church & Dwight Co., Inc. |
| Unilever PLC |
| Others |
Cost & Logistics Intelligence
Enamel remineralization chemistry incorporating bioactive glass and CPP-ACP compounds is elevating formulation costs while compressing margins for manufacturers lacking backward integration into specialty chemical supply. This production-method transition simultaneously concentrates pricing power among firms with captive sourcing relationships and forces tiered pricing stratification across premium therapeutic and standard fluoride categories.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the GCC oral hygiene market, with price differentiation anchored in therapeutic certification grade and pharmacist endorsement requirements. Premium enamel remineralization and whitening formulations command shelf-space premiums in Saudi and UAE pharmacy channels, while economy fluoride pastes face margin compression from private-label substitution in hypermarket bundles. Pricing pressure stems from MOHAP clinical substantiation costs extending UAE launch timelines, with price sensitivity highest among convenience-store emergency purchasers and lowest among clinic-affiliated dispensary buyers seeking therapeutic efficacy.
Supply Chain Analysis
SFDA and MOHAP local-content discussions are reshaping sourcing strategies, though active ingredient production for hydrogen peroxide and stabilized fluoride compounds remains concentrated in Germany, Japan, and South Korea. Raw material dependencies span European chemical suppliers for peroxide precursors, Asian manufacturers for fluoride stabilization compounds, and regional converters for Arabic-English bilingual packaging materials. Single-source vulnerability runs through hydrogen peroxide feedstock channels exposed to shipping volatility from European ports. Distribution runs through Jeddah and Dubai logistics hubs serving pharmacy networks and hypermarket retail chains across all six GCC member states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC oral hygiene market reads as a late-cycle quality story where enamel remineralization demand and professional channel control reward compliance-heavy incumbents over price competitors. Premium specification pull from younger Saudi urban consumers and dentist-affiliated dispensaries is displacing unaided retail selection.
For Market Incumbents: Hedge regulatory concentration risk by diversifying SFDA-MOHAP dual-registration capacity across Jeddah and Dubai production facilities, while building backward integration into fluoride compound stabilization to offset European supplier currency exposure. Channel control through medical affairs teams represents the priority defensive lever against pharmacy-network displacement by clinic-affiliated dispensaries. For New Entrants and Emerging Players: Begin with Kuwait's underdeveloped therapeutic pharmacy networks in Kuwait City and Al Ahmadi, where medical affairs capabilities face lighter incumbent saturation than Saudi or UAE markets. Sachet-format probiotic and travel-size oral care products offer the most penetrable white-space, with go-to-market execution anchored through independent pharmacy chain partnerships rather than hypermarket slotting battles. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors possessing pharmacy network relationships but lacking proprietary formulation portfolios, as multinational consumer health conglomerates consolidate around SFDA-MOHAP registration pathways. Long-term viability favors targets with bilingual regulatory affairs capacity and clinic-chain formulary access. The signal to watch is harmonization progress across Gulf standards bodies toward unified Arabic-English labeling protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Capacity Expansion | Dual SFDA-MOHAP registration teams compress product launch timelines against single-market competitors. |
| Clinic-Affiliated Dispensary Partnership | Professional endorsement networks in Riyadh and Abu Dhabi displace unassisted retail selection for therapeutic categories. |
| Enamel Remineralization Formulation Launch | Bioactive glass and CPP-ACP chemistry captures premium positioning among younger Saudi urban consumers. |
| Backward Integration into Active Ingredients | Captive sourcing of stabilized fluoride compounds insulates margins from European supplier currency volatility. |
| Smart Dispensing System Pilot | IoT-connected brushing monitors create data platforms for UAE dental insurer preventive coverage incentives. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs directors at multinational consumer health firms, pharmacy chain procurement managers across Saudi Arabia and the UAE, dental clinic dispensing coordinators in Riyadh and Dubai, and logistics operators at Jeddah and Dubai distribution hubs. Secondary validation drew from SFDA registration databases, MOHAP therapeutic claim filings, GCC customs trade records, and Nielsen retail audit data across pharmacy and hypermarket channels. Bottom-up SKU-level volume aggregation and top-down macroeconomic adjustment provided cross-check triangulation.
Segment-weighting approaches distributed value and volume across product type, end-user life stage, distribution channel, and packaging format dimensions throughout the projection horizon. CAGRs derived from fitted growth curves applied to historical registration and import data, with adjustment for SFDA peroxide concentration limit enforcement and MOHAP clinical substantiation timeline impacts. Industry-specific forecast inputs incorporated pediatric dental awareness campaign intensity indices and pharmacy network expansion rates across Kuwait and Qatar.
Several conditions sit outside the modeled scope, including potential Gulf standards body harmonization outcomes, cold chain infrastructure buildout timelines for probiotic formulations, and laser whitening technology cost curves affecting over-the-counter substitution dynamics. Forecasts reflect documented assumptions regarding regulatory stability and channel structure continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Us Oral Care Market
Oral Care
Herbal Toothpaste Market
Oral Care
Oral Thin Films Market
Oral Care
Oral Mucositis Market
Oral Care
Europe Oral Hygiene Market
Oral Care
North America Oral Care Market
Oral Care
Tongue Cleaner Market
Oral Care
Mouth Sore Medicine Market
Oral Care
Herbal Toothcare Market
Oral Care
Global Oral Care Products Market
Oral Care
Asia-Pacific Oral Care Market
Oral Care
South America Oral Care Market
Oral Care
Oral Irrigator Market
Oral Care
Dry Mouth Relief Market
Oral Care
Oral Health Ingredient Market
Oral Care
Oral Care Market