
 Endoscope Cleaning Products Market | 2026-2036
Endoscope Cleaning Products Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscope Cleaning Products Market Analytics
Trained reprocessing technicians is collapsing across North American and European healthcare systems, forcing facilities toward automated endoscope cleaning systems that reduce manual dependency and error rates. STERIS leverages its installed base of washer-disinfector platforms to sustain recurring consumable revenue streams. Ecolab anchors hospital supply contracts through integrated chemistry-and-service bundles that lock in multi-year relationships. Getinge competes on manufacturing scale, operating large-volume production lines that serve centralized sterile processing departments across multiple countries.
Endoscope cleaning products encompass enzymatic detergents, high-level disinfectants, automated washer-disinfectors, and drying storage cabinets engineered to achieve log-6 microbial reduction on flexible gastrointestinal and respiratory endoscopes while preserving delicate instrument channels and lens assemblies. These products serve the essential function of eliminating biofilm-forming organisms and protein residues between patient procedures to prevent healthcare-associated infections. Automated systems command the largest revenue share by product type due to capital replacement cycles and regulatory pressure for validated, repeatable cleaning protocols. Manual cleaning solutions retain steady demand in smaller clinics and resource-constrained settings where upfront equipment investment proves prohibitive. Disinfectants represent the fastest-growing margin pool by delivery mode, driven by single-use high-level disinfectant formulations that simplify compliance documentation and reduce cross-contamination risk in high-throughput endoscopy suites.
FDA enforcement of duodenoscope-related infection outbreaks has tightened 510(k) clearance requirements for cleaning accessories and automated reprocessors, directly shaping product development roadmaps and validation study budgets for manufacturers. AAMI ST91 and EN ISO 15883 standards in the United States and Europe respectively mandate periodic efficacy testing and water quality monitoring that expand aftermarket service revenue for equipment vendors. Stakeholders must monitor evolving EPA and state-level disinfectant chemistry restrictions, as quaternary ammonium and glutaraldehyde formulations face scrutiny that could force rapid formulation pivots and supply chain requalification.
Market Dynamics
Automated reprocessing systems are capturing procurement budgets as healthcare facilities confront technician shortages and FDA-mandated validation protocols for duodenoscope cleaning. This structural shift compresses manual chemistry volumes while elevating capital equipment and single-use consumable demand.
Growth Catalysts
- AAMI ST91 validation mandates:United States hospitals must demonstrate repeatable cleaning efficacy, forcing capital upgrades to automated washer-disinfector platforms with documented log-6 reduction.
- Ambulatory surgical center expansion:United States outpatient facilities are installing compact automated systems to handle elevated endoscopy volumes without centralized sterile processing infrastructure.
- Peracetic acid formulations:Single-use high-level disinfectant chemistry eliminates glutaraldehyde exposure risks and simplifies compliance documentation for high-throughput endoscopy suites.
Market Restraints
- Capital intensity of automated platforms:Washer-disinfector systems require substantial upfront investment and dedicated utility infrastructure, excluding small clinics and resource-constrained settings.
- Water quality dependency:EN ISO 15883 mandates for purified water supply create ongoing operational costs and facility engineering requirements that strain maintenance budgets.
- Glutaraldehyde regulatory pressure:EPA and state-level restrictions on quaternary ammonium and aldehyde chemistries force rapid formulation pivots and supply chain requalification costs.
Strategic Opportunities
- Centralized sterile processing consolidation:Health system mergers in the United States create demand for high-capacity automated lines serving multiple facilities from single hubs.
- Integrated chemistry-service bundles:Multi-year contracts combining disinfectant supply with validation testing and technician training lock in recurring revenue streams.
- AI-enabled cleaning verification:Machine vision systems for residual soil detection converge with automated reprocessors to close documentation gaps in compliance audits.
Industry Challenges
- Trained reprocessing technician scarcity:North American and European healthcare systems face collapsing pipeline of certified sterile processing professionals, forcing automation adoption before staff readiness.
- Legacy endoscope compatibility:Older flexible gastrointestinal and respiratory endoscope designs lack standardized channel geometries that automated systems assume, creating cleaning verification failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscope Cleaning Products Market |
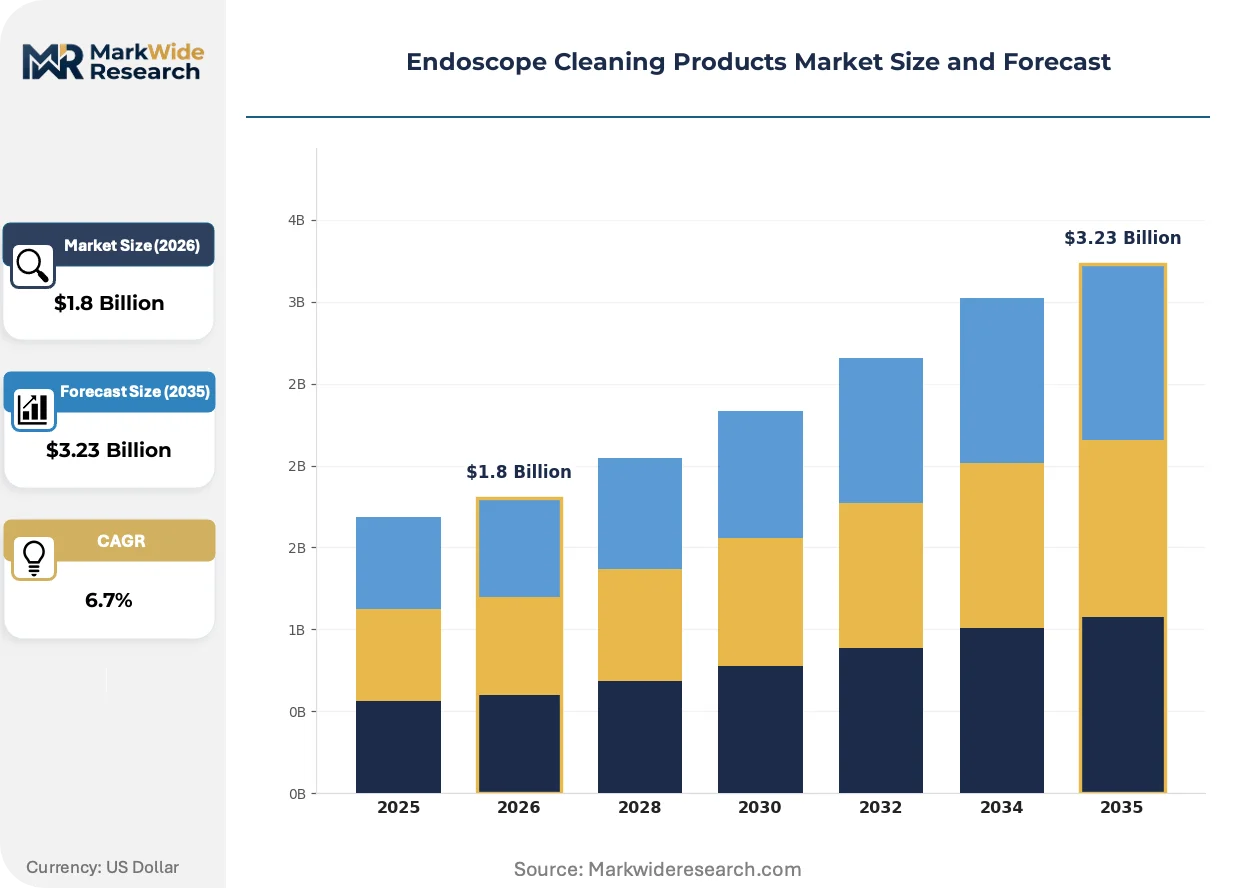
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Cleaning Solutions, Disinfectants, Wipes Delivery Mode: On-premise Solutions, Disposable Products, Reusable Equipment, Sterilization Services End User: Hospitals, Clinics, Diagnostic Centers, Ambulatory Surgical Centers Application: Gastroenterology, Pulmonology, Urology, ENT |
| Companies Covered | Ecolab, Schülke & Mayr, STERIS, Steelco, Wassenburg Medical, Advanced Sterilization Products, Olympus, Shinva Medical, Getinge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscope Cleaning Products Market Evolving Landscape
Single-use high-level disinfectant chemistry is compressing reusable disinfectant volumes as facilities prioritize compliance simplification and cross-contamination elimination. Three convergent forces are reshaping product development roadmaps and procurement patterns.
Peracetic acid-based single-use disinfectant systems is supplanting glutaraldehyde baths in United States ambulatory surgical centers. These closed-cartridge designs eliminate manual mixing, ventilation requirements, and exposure monitoring. Hospital sterile processing departments are adopting them fastest where liability exposure and Joint Commission scrutiny concentrate.
Europe's MDR and EN ISO 15883 standards are elevating validation documentation burdens for cleaning accessory manufacturers. Reprocessing equipment vendors must now submit periodic efficacy testing data and water quality monitoring records. Centralized sterile processing departments across Germany, France, and the United Kingdom are absorbing these compliance costs through extended service contracts.
After-sales service unbundling is disrupting traditional equipment procurement in United States health systems. Buyers are separating capital acquisition from validation testing, preventive maintenance, and consumable supply into distinct contract vehicles. This pattern is most visible in multi-hospital networks standardizing on single vendor platforms while negotiating chemistry supply competitively.
Endoscope Cleaning Products Market Segmentation
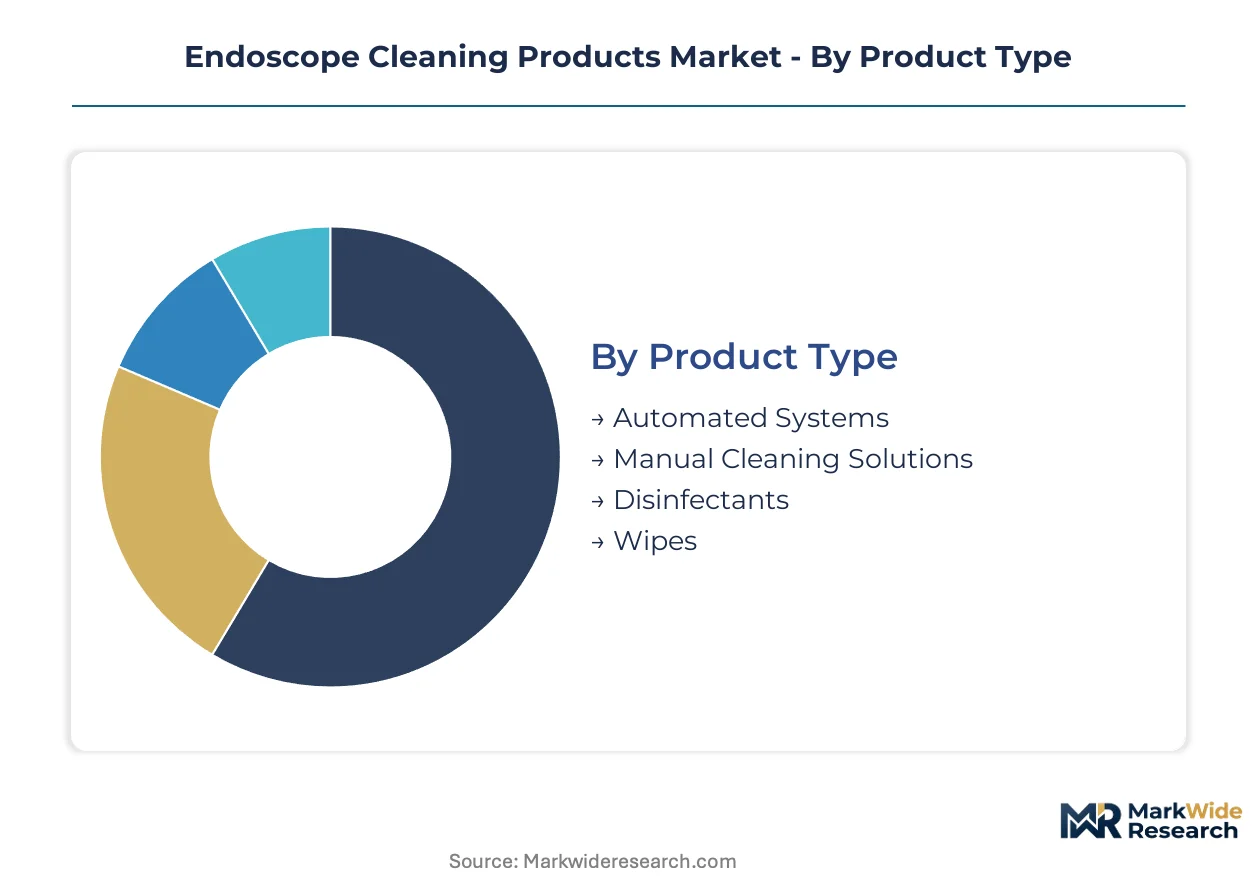
Endoscope cleaning products fragment across four distinct dimensions that shape procurement patterns and margin structures. Each category reflects divergent regulatory pressures, capital requirements, and clinical throughput needs that vendors must navigate simultaneously.
Product Type:
Automated systems dominate capital budgets in the United States and Germany where labor costs and liability exposure concentrate. Manual solutions retain footholds in price-sensitive clinics across India and Brazil.
- Automated Systems:Washer-disinfector platforms integrate ultrasonic cleaning, high-level disinfection, and drying cycles with documented log-6 microbial reduction. United States hospitals facing AAMI ST91 mandates are replacing legacy units on compressed 5-7 year cycles.
- Manual Cleaning Solutions:Enzymatic detergents and brush kits require trained technician labor but eliminate capital barriers. Clinics in Mexico and Southeast Asia rely on these for flexible gastrointestinal endoscope reprocessing where automated infrastructure remains uneconomical.
- Disinfectants:High-level chemistries achieve sporicidal efficacy on delicate instrument surfaces.
- Wipes:Surface disinfection products address environmental contamination in endoscopy suites.
Automated Systems commands the established base. The steepest expansion runs through Disinfectants.
Delivery Mode:
Capital ownership models prevail where health systems possess centralized sterile processing infrastructure. Service-based arrangements gain traction among ambulatory networks seeking to offload compliance burden.
- On-premise Solutions:Facilities purchase and operate reprocessing equipment directly, absorbing validation and maintenance responsibilities. German hospital networks favor this model to maintain internal quality control over duodenoscope reprocessing protocols.
- Disposable Products:Single-use disinfectant cartridges and brush kits eliminate cross-contamination risks and simplify documentation. United States ambulatory surgical centers are converting fastest where Joint Commission audits concentrate.
- Reusable Equipment:Durable washer-disinfector components and multi-cycle chemistries reduce per-procedure costs.
- Sterilization Services:Third-party reprocessing providers handle high-volume instrument fleets.
On-premise Solutions anchors procurement volumes. Disposable Products is climbing the fastest as compliance simplification drives conversion.
End User:
Hospital procurement concentrates purchasing power and demands integrated chemistry-service bundles. Outpatient facilities prioritize compact footprint and rapid cycle times over throughput capacity.
- Hospitals:Centralized sterile processing departments manage diverse endoscope inventories across multiple specialties. United States academic medical centers are consolidating reprocessing operations into single hubs serving satellite campuses.
- Ambulatory Surgical Centers:Limited physical space and high procedure turnover favor automated systems with sub-30 minute cycle times. These facilities in Texas and Florida are installing compact washer-disinfectors to handle elevated colonoscopy volumes.
- Clinics:Lower throughput settings rely on manual methods or outsourced sterilization services.
- Diagnostic Centers:Imaging-focused facilities require rapid endoscope turnaround for same-day patient flows.
Hospitals retain the dominant share. Ambulatory Surgical Centers is gaining share fastest as outpatient migration accelerates.
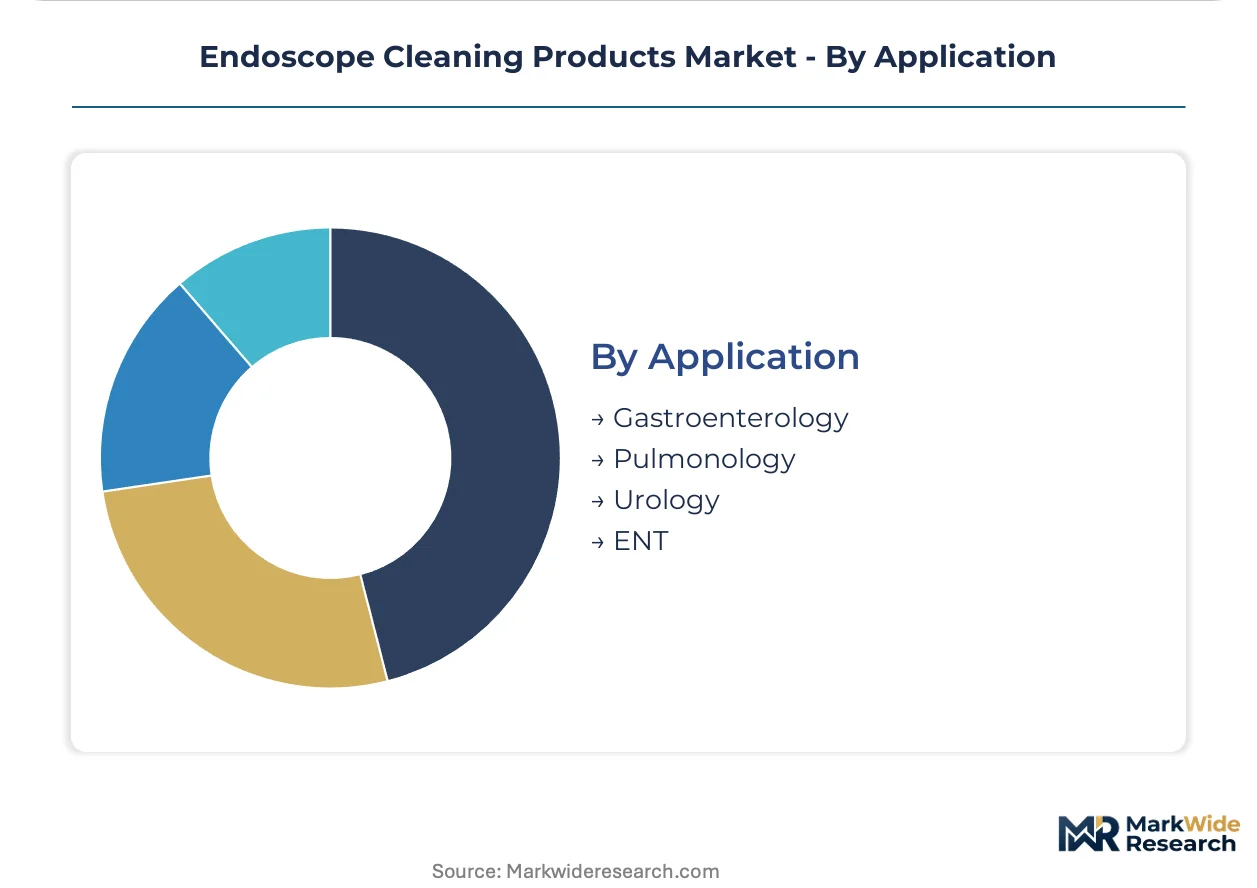
Application:
Gastrointestinal procedures generate the highest reprocessing volumes due to colonoscopy screening programs. Pulmonology applications face elevated scrutiny following duodenoscope-related infection outbreaks.
- Gastroenterology:Flexible colonoscopes and gastroscopes require channel brushing and high-level disinfection between patients. Screening program expansion in Japan and the United Kingdom sustains demand for validated reprocessing protocols.
- Pulmonology:Bronchoscopes present complex biofilm challenges in narrow working channels. FDA enforcement actions following multidrug-resistant organism transmissions have tightened cleaning verification requirements in United States hospitals.
- Urology:Cystoscopes and ureteroscopes demand compatibility with specific high-level disinfectant chemistries.
- ENT:Rigid and flexible endoscopes for otolaryngology procedures require gentler processing parameters.
Gastroenterology holds the volume base. Pulmonology is expanding most quickly as regulatory pressure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States facilities prioritize automated reprocessing platforms to satisfy FDA validation mandates, while German hospital networks emphasize water quality infrastructure under EN ISO 15883, and Indian clinics sustain manual chemistry volumes where capital investment remains constrained.
United States
Ambulatory surgical center expansion and liability exposure concentrate procurement of compact automated washer-disinfectors. FDA enforcement of duodenoscope-related infection outbreaks has tightened 510(k) clearance requirements for cleaning accessories. Texas and Florida ASC clusters are installing sub-30 minute cycle systems to handle elevated colonoscopy volumes.
Germany
Centralized sterile processing departments in academic medical centers absorb extended service contracts to manage MDR validation documentation burdens. EN ISO 15883 mandates for purified water supply create ongoing operational costs that strain maintenance budgets. The North Rhine-Westphalia hospital network is consolidating reprocessing operations into single hubs serving satellite campuses.
United Kingdom
Colonoscopy screening program expansion sustains demand for validated reprocessing protocols across NHS trusts. AAMI ST91-aligned procurement standards influence equipment replacement cycles even without direct regulatory application. London and Southeast England health systems are standardizing on single vendor platforms while negotiating chemistry supply competitively.
Japan
Gastroenterology procedure volumes drive premium disinfectant and automated system procurement in metropolitan hospital networks. METI guidelines on medical device reprocessing elevate product validation thresholds for domestic and imported equipment. The Kanto region around Tokyo anchors domestic manufacturing of washer-disinfector components.
India
Price-sensitive clinics across Maharashtra and Gujarat rely on enzymatic detergents and brush kits for flexible endoscope reprocessing. CDSCO medical device regulations are gradually elevating import standards for automated reprocessing equipment. Diagnostic chains in Delhi-NCR and Bengaluru are piloting compact automated systems for high-throughput endoscopy suites.
Endoscope Cleaning Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding hospital supply contracts through chemistry-and-service bundles and the specialist tier competing on manufacturing scale or regional proximity. Three archetypes dominate: chemistry-anchored integrators, equipment-focused platform vendors, and regional manufacturing specialists. Competitive moves concentrate on multi-year contract lock-ins and validation testing service unbundling.
Among chemistry-anchored integrators, Ecolab occupies a position exemplifying integrated bundle strategies, while STERIS represents the equipment-platform archetype with recurring consumable revenue models. Getinge sits within the manufacturing scale tier, serving centralized sterile processing departments across multiple countries.
| Leading Market Players |
|---|
| Ecolab |
| Schülke & Mayr |
| STERIS |
| Steelco |
| Wassenburg Medical |
| Advanced Sterilization Products |
| Olympus |
| Shinva Medical |
| Getinge |
| Others |
Value Network & Pricing Analysis
Forty-five to sixty days of safety stock for peracetic acid disinfectant cartridges now separates compliant ambulatory surgical centers from supply disruptions, concentrating pricing power with chemistry-anchored integrators who bundle validation services into multi-year contracts. This inventory buffer reflects both FDA-mandated validation documentation burdens and the geographic concentration of automated washer-disinfector manufacturing in Germany and the United States.
Pricing Analysis
Long-term offtake agreements dominate hospital procurement as health systems consolidate reprocessing operations into centralized sterile processing hubs. Three-tier pricing structure across premium automated platforms, standard washer-disinfector lines, and economy manual chemistry kits differentiates by validation documentation depth and technician training bundling. Cost compression in the economy tier is intensifying because Indian and Brazilian clinics resist capital equipment upgrades. Ambulatory surgical centers in Texas and Florida exhibit the highest price sensitivity due to thin procedure margins, while academic medical centers absorb premium pricing for integrated chemistry-service bundles.
Supply Chain Analysis
Sixty-day lead times for EN ISO 15883-compliant water purification modules now constrain German hospital network expansion timelines. Manufacturing concentrates in Germany, the United States, and Japan for automated reprocessing platforms, while China and India supply enzymatic detergent precursors and brush kit components. Raw material dependencies include medical-grade stainless steel for washer-disinfector chambers, peracetic acid precursors for single-use disinfectants, and specialized polymers for endoscope-compatible brush filaments. Single-source vulnerability runs through European-sourced high-level disinfectant chemistry subject to REACH regulatory revisions. Distribution runs through hospital GPO contracts in North America and direct manufacturer-service contracts in European hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
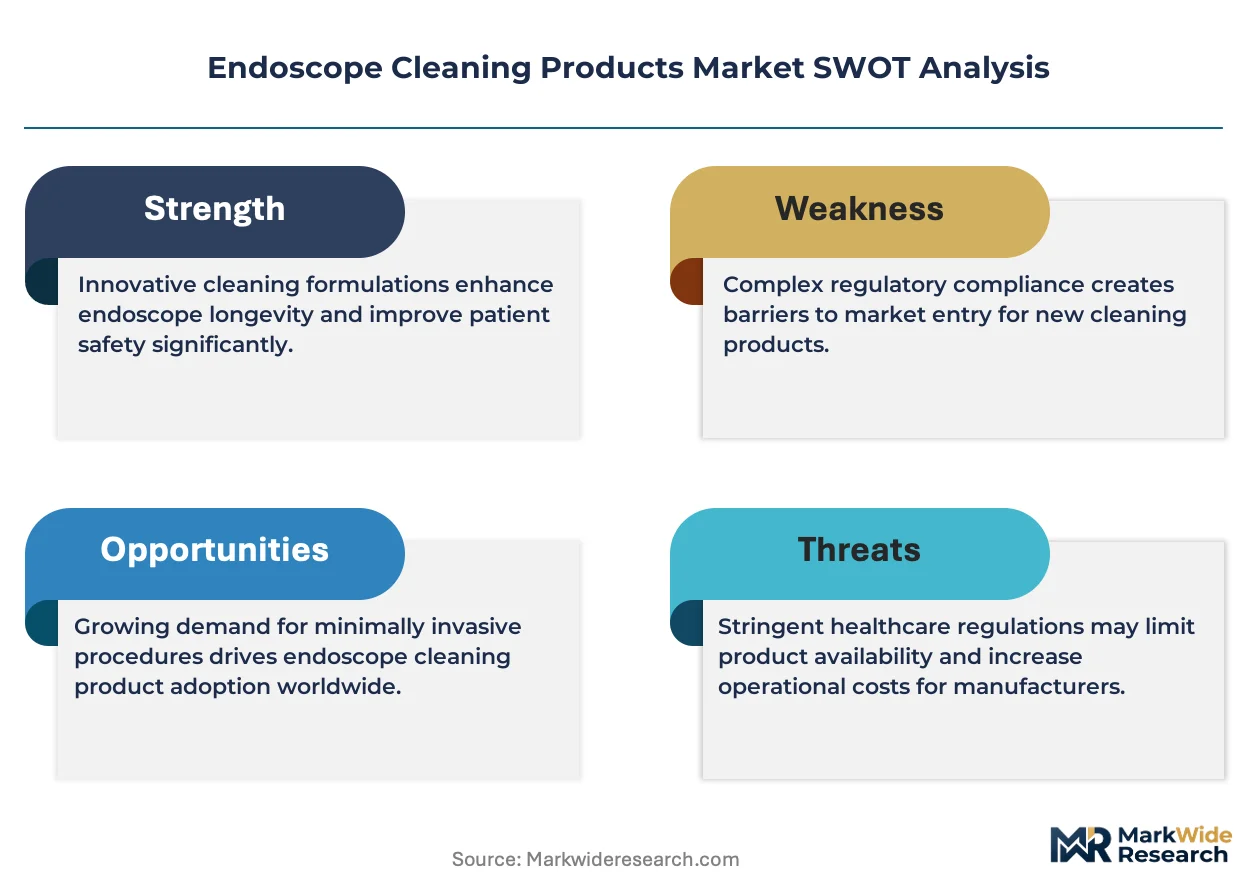
Fragmentation across manual chemistry, automated equipment, and validation service layers creates entry niches as ambulatory surgical center expansion outpaces incumbent capacity to serve mid-tier facilities with tailored bundles.
For Market Incumbents: Consolidate service contract portfolios around AI-enabled cleaning verification systems to offset technician scarcity pressure. Lock in multi-year chemistry supply agreements with emerging diagnostic chains in India before CDSCO regulatory elevation closes import pathways. Backward integration into peracetic acid precursor manufacturing defends margin position against REACH-driven supply requalification costs. For New Entrants and Emerging Players: FDA 510(k) fast-track for single-use disinfectant cartridges targeting United States ambulatory surgical centers offers the most penetrable entry point. White-space concentrates in compact automated systems for Mexican and Southeast Asian clinics where manual methods dominate due to capital barriers. A rental-plus-consumables model bypasses upfront equipment resistance while capturing recurring revenue. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because validation documentation burdens and regulatory tightening create sticky customer relationships resistant to switching. Acquisition targets should display installed base scale in automated platforms with underpenetrated consumable attach rates. Watch FDA enforcement action intensity against duodenoscope reprocessing failures as the inflection signal for accelerated capital replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Locks in multi-year chemistry supply and validation service revenue with United States academic medical centers. |
| FDA Submission | Accelerates clearance for AI-enabled cleaning verification accessories amid tightened 510(k) requirements. |
| CE Marking Pathway | Opens European ambulatory surgical center access under MDR and EN ISO 15883 compliance frameworks. |
| Backward Integration | Captures peracetic acid precursor supply to offset REACH regulatory pressure on European chemistry sourcing. |
| Software Companion Development | Closes documentation gaps in Joint Commission audits through machine vision residual soil detection. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, AAMI ST91 technical documentation, and EN ISO 15883 compliance records to validate market sizing and competitive positioning. Interviews with sterile processing department managers, biomedical engineers, GPO contracts managers, and reprocessing equipment procurement officers provided operational demand signals. Secondary sources included hospital procurement databases, CMS Medicare reimbursement data, and customs records for automated reprocessing equipment trade flows. Bottom-up facility-level equipment counts triangulated against top-down manufacturer revenue disclosures.
Segmentation dimensions modeled span product type, delivery mode, end user, and application across the projection horizon. The analytical framework applies procedure volume growth rates, regulatory compliance cost absorption curves, and capital replacement cycle timing to derive expansion trajectories. CAGRs were computed from installed base evolution and consumable attach rate assumptions. Industry-specific inputs incorporated duodenoscope-related infection outbreak frequencies and Joint Commission audit intensity variations by United States state.
Decision-makers should treat outputs as directional under assumptions of sustained FDA enforcement posture and stable REACH chemical regulation; material deviation in either would warrant model refresh. Specific risk factors include sudden EPA restrictions on quaternary ammonium compounds, accelerated health system merger activity disrupting vendor relationships, and breakthrough single-use endoscope adoption displacing reprocessing demand. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Dental Emergency Kit Market
Medical Supplies
Oral Syringes Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Disposable Hospital Supplies Market
Medical Supplies
Anti Venom Market
Medical Supplies
Global Surgical Masks Market
Medical Supplies
Skin Traction Kits Market
Medical Supplies
Medical Swabs Market
Medical Supplies
Absorbable Surgical Sutures Market
Medical Supplies
Asia-Pacific Medical Clothing Market
Medical Supplies
Children's Antipyretic Patch Market
Medical Supplies
Cryogenic Vials Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Elbow Splints Market
Medical Supplies
Global Povidone Iodine Market
Medical Supplies
Global Unna Boot Market