
 CBD Consumer Health Market | 2026-2036
CBD Consumer Health Market Size, Share, and Industry Trends Forecast 2026-2036
CBD Consumer Health Market Intelligence
Wellness-seeking millennials is unwinding the historical dominance of pain-management buyers in CBD consumer health. Charlotte's Web leverages its seed-to-shelf vertical integration to command premium shelf space in health stores and pharmacies. ENDOCA sustains European market presence through certified organic cultivation and third-party laboratory verification protocols.
CBD consumer health encompasses hemp-derived cannabidiol formulations manufactured for over-the-counter wellness applications, typically extracted through CO2 or ethanol methods to achieve standardized cannabinoid concentrations between 5 mg and 50 mg per serving unit. These products function primarily as non-prescription alternatives for stress modulation, dermatological conditioning, and sleep architecture support. Oils and tinctures anchor current revenue pools due to established bioavailability data and flexible dosing protocols, while gummies capture the fastest expansion trajectory among product formats driven by flavor-masked delivery and discrete consumption patterns. Online retail channels now dominate volume throughput as direct-to-consumer platforms bypass traditional pharmacy markups and capture recurring subscription revenue.
The FDA maintains evolving enforcement discretion on CBD ingestibles, while the 2018 Farm Bill removed hemp from Schedule I classification and delegated state-level retail oversight to agriculture departments. European markets operate under the EFSA novel food authorization pathway, with individual member states applying divergent tolerance thresholds for THC contamination in finished goods. Stakeholders must monitor pending FDA rulemaking on dietary supplement pathways versus over-the-counter drug monographs, as this classification fork will determine permissible health claims and distribution channel access for the next decade of commercial development.
Market Dynamics
The 2018 Farm Bill's descheduling of hemp and the FDA's evolving enforcement posture on ingestible CBD have created a bifurcated regulatory landscape where product classification—dietary supplement versus over-the-counter drug—determines permissible claims and channel access.
Growth Catalysts
- Wellness-seeking millennials:This demographic cohort now outnumbers pain-management buyers in CBD consumer health, driving demand for stress modulation and sleep architecture support applications.
- EFSA novel food authorization pathway:European markets are consolidating around this regulatory framework, enabling standardized THC contamination thresholds and cross-border retail expansion.
- CO2 extraction standardization:Advanced supercritical methods now achieve consistent 5-50 mg cannabinoid concentrations per serving, unlocking pharmacy-grade reproducibility for tincture and gummy formats.
Market Restraints
- THC contamination testing costs:Third-party laboratory verification for finished goods adds substantial per-batch overhead, compressing margins for small-batch operators.
- Supply concentration in Colorado and Kentucky:Domestic hemp cultivation clusters in these two states, creating weather-dependent input volatility and geographic risk exposure.
- Substitute botanicals:Ashwagandha and L-theanine formulations compete directly for stress and sleep positioning at lower price points with clearer regulatory status.
Strategic Opportunities
- Germany's pharmacy channel:Regulatory clarity under BfArM guidance positions this market for health insurance reimbursement pathways unavailable in other European jurisdictions.
- Nanotechnology emulsion:Convergence of lipid nanoparticle delivery with existing oil formats promises enhanced bioavailability and faster onset timing for competitive differentiation.
- Subscription direct-to-consumer platforms:Recurring revenue models bypass traditional retail markups and capture lifetime value through personalized dosing protocols.
Industry Challenges
- Analytical chemist shortage:Cannabinoid quantification and terpene profiling require specialized HPLC-MS expertise that outpaces current vocational training pipelines.
- OTC drug monograph compliance timeline:FDA pathway selection remains unresolved, forcing dual-track investment in supplement and drug-grade manufacturing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CBD Consumer Health Market |
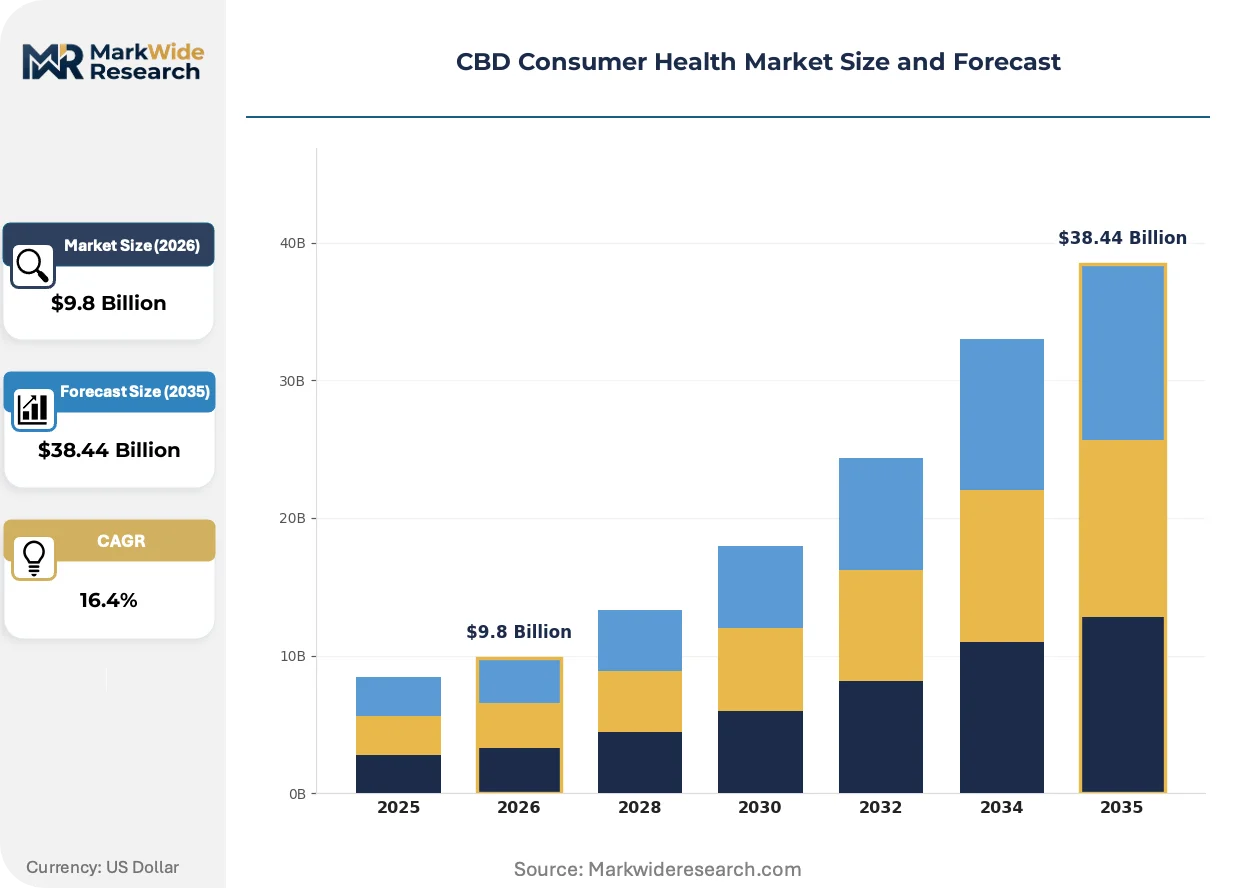
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $38.44 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Capsules, Gummies, Topicals Application: Pain Relief, Sleep Aid, Anxiety Management, Skin Care Distribution Channel: Online Retail, Pharmacies, Health Stores, Direct Sales Customer Type: Consumers, Healthcare Professionals, Retailers, Distributors |
| Companies Covered | Charlotte's Web, ENDOCA, CV Sciences, Medical Marijuana Inc., Joy Organics, Elixinol, NuLeaf Naturals, The Cronos Group, Isodiol International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CBD Consumer Health Market Strategic Shifts & Innovations
Formulation science and distribution architecture are undergoing parallel transformation as bioavailability optimization collides with channel disintermediation.
Nanoemulsion technology is decomposing the traditional oil-tincture dominance by enabling water-compatible CBD matrices with demonstrably faster absorption kinetics. Beverage manufacturers and functional food developers are integrating these lipid-dispersed systems at accelerating pace. The structural consequence is compression of the efficacy-per-dollar gap between premium oils and mass-market drinkables.
EFSA's cumulative toxicology assessments for CBD novel food applications are reshaping permissible daily intake thresholds across European member states. Industrial consequence includes mandatory 28-day repeated-dose studies that add six-figure certification costs per SKU. Germany and the Netherlands are responding fastest with pre-submission consultation frameworks, while southern European regulators lag in implementation consistency.
Millennial buyers now prioritize certificate-of-analysis accessibility over brand heritage when selecting products. Direct-to-consumer platforms with QR-linked batch testing are displacing pharmacy and health store intermediaries for this segment. The United Kingdom and United States exhibit the most pronounced channel migration, with subscription attach rates exceeding traditional retail repurchase frequency by substantial margins.
CBD Consumer Health Market Segmentation
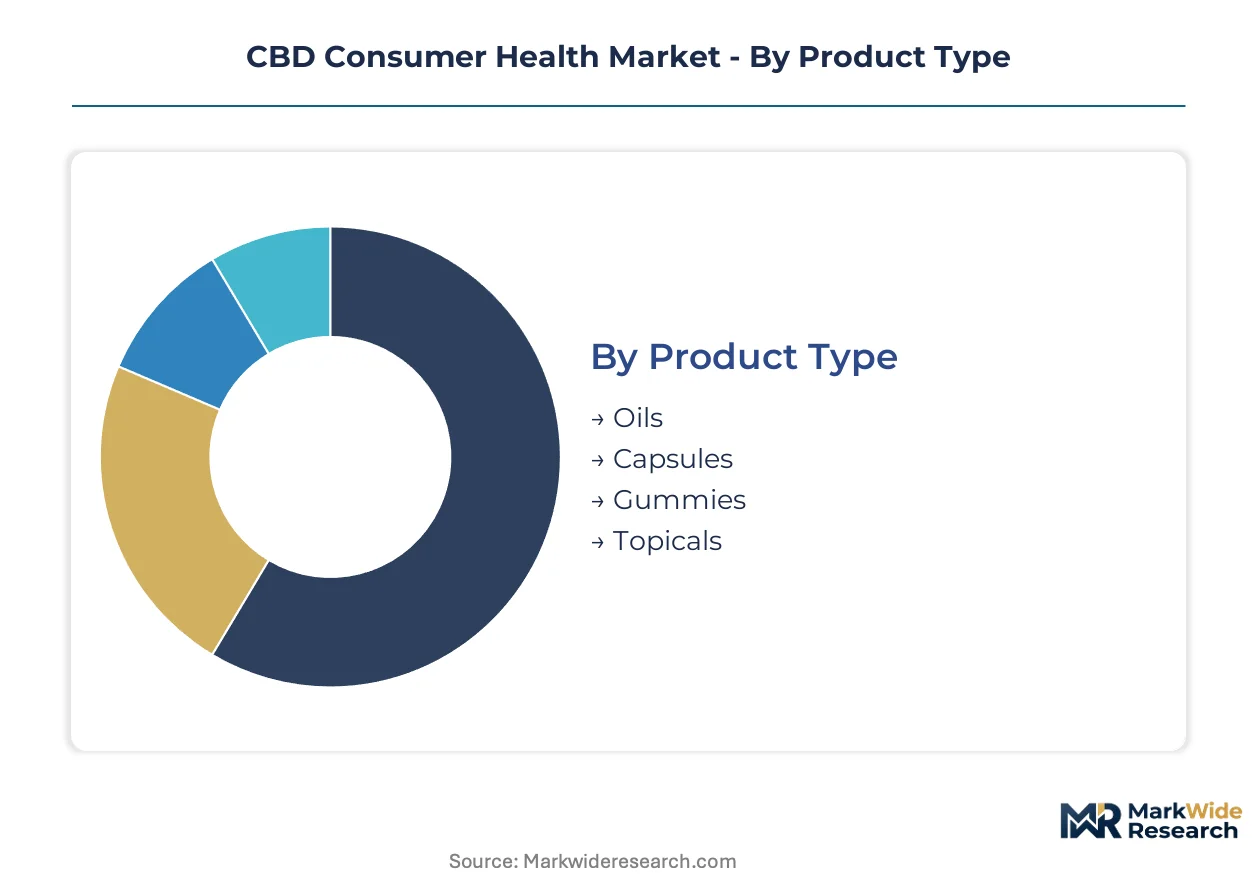
Segmentation in CBD consumer health determines regulatory pathway eligibility, manufacturing investment requirements, and permissible marketing claims. Product format classification dictates whether FDA dietary supplement or OTC drug monograph compliance applies, while distribution channel selection shapes margin structures and customer acquisition economics.
Product Type:
Regulatory differentiation between ingestible and non-ingestible formats determines permissible health claims and distribution access across jurisdictions. The FDA maintains divergent enforcement discretion for oils versus topicals, while EFSA novel food authorization applies exclusively to ingestible categories in Europe.
- Oils:CO2-extracted formulations standardized at 5-50 mg cannabinoid concentrations per serving anchor pharmacy and health store distribution. Established bioavailability data supports flexible dosing protocols that appeal to aging populations seeking non-pharmaceutical alternatives in Germany and the United States.
- Gummies:Flavor-masked delivery systems with discrete consumption patterns capture wellness-oriented millennials through direct-to-consumer subscription platforms. Nanotechnology emulsion integration promises enhanced absorption kinetics that could compress the efficacy-per-dollar gap with traditional oils.
- Capsules:Pre-measured unit dosing satisfies healthcare professional preferences for prescription-adjacent protocols in pharmacy channels.
- Topicals:Dermatological conditioning applications bypass novel food authorization requirements in European markets.
Oils handle the majority of throughput; gummies are the fastest mover on share.
Application:
Cost tier stratification separates premium clinical-positioned products from mass-market wellness offerings, with certification requirements and study investment driving pricing architecture.
- Pain Relief:Historically dominant positioning now yields share to wellness applications as millennial buyers prioritize stress modulation over analgesic claims. Third-party laboratory verification for THC contamination adds per-batch overhead that compresses margins for small-batch operators serving this segment.
- Sleep Aid:Melatonin-CBD combination formulations command premium shelf space as consumers substitute away from pharmaceutical sleep architecture interventions. Subscription direct-to-consumer platforms capture recurring revenue through personalized dosing protocols unavailable in traditional retail.
- Anxiety Management:Competes directly with ashwagandha and L-theanine formulations at lower price points with clearer regulatory status.
- Skin Care:Topical delivery avoids EFSA novel food authorization costs while targeting dermatological conditioning applications.
Pain Relief retains volume leadership; Sleep Aid is expanding most quickly on share.
Distribution Channel:
Volume concentration in online retail reflects channel disintermediation economics, while pharmacy access depends on unresolved FDA pathway classification.
- Online Retail:Direct-to-consumer platforms with QR-linked batch testing displace traditional intermediaries as millennial buyers prioritize certificate-of-analysis accessibility over brand heritage. Subscription attach rates exceed traditional retail repurchase frequency by substantial margins in the United Kingdom and United States.
- Pharmacies:Germany's BfArM guidance positions this channel for health insurance reimbursement pathways unavailable in other European jurisdictions. FDA OTC drug monograph compliance timeline remains unresolved, forcing dual-track infrastructure investment.
- Health Stores:Premium shelf space allocation favors vertically integrated operators with seed-to-shelf traceability.
- Direct Sales:Personalized consultation models serve healthcare professional customer segments with prescription-adjacent protocols.
Online Retail handles the majority of throughput; Pharmacies are climbing the fastest on share.
Customer Type:
Supply concentration in Colorado and Kentucky cultivation clusters creates geographic risk exposure that shapes procurement patterns across customer segments.
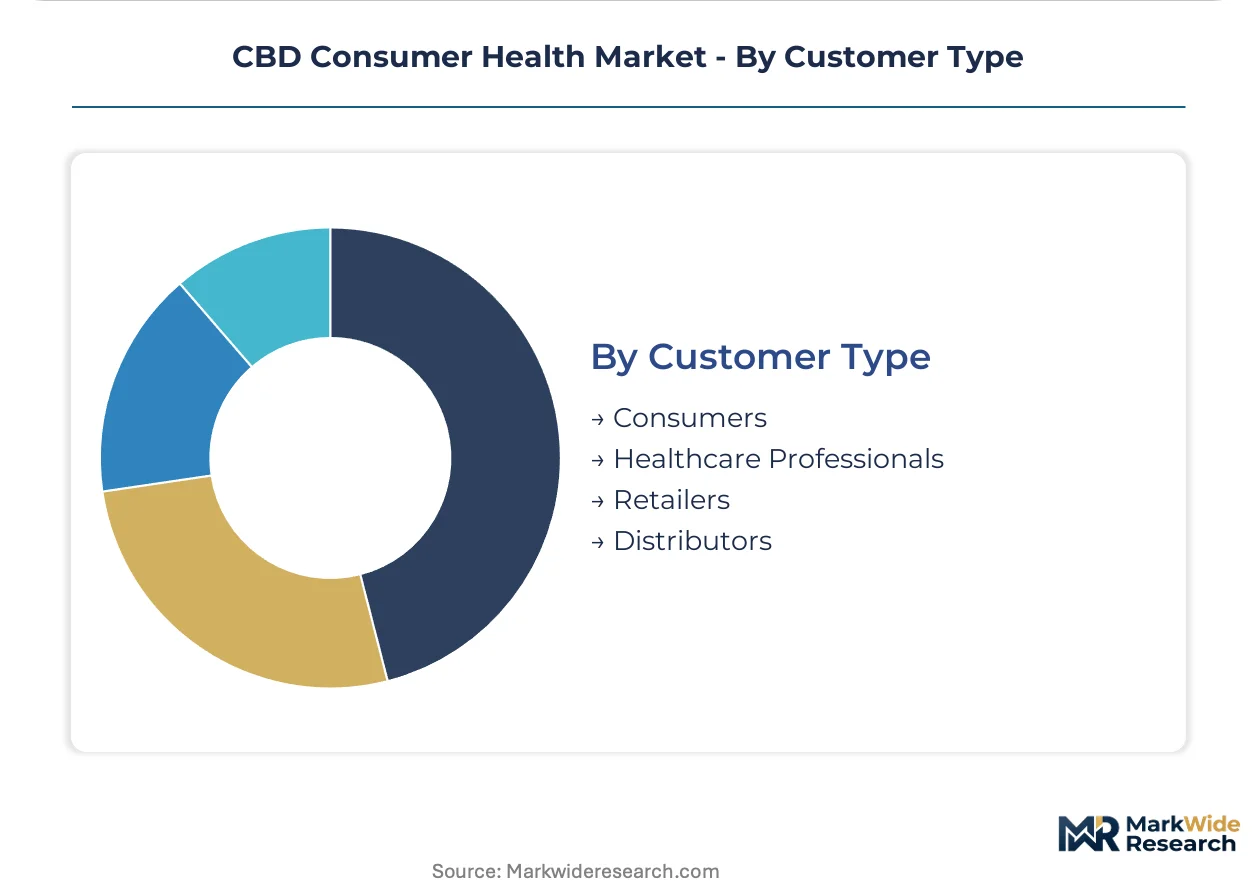
- Consumers:Wellness-seeking millennials drive category expansion through stress modulation and sleep architecture support demand, with certificate-of-analysis accessibility now prioritized over brand heritage.
- Healthcare Professionals:Require prescription-adjacent protocols with standardized dosing and third-party verification that pharmacy-grade manufacturing infrastructure satisfies.
- Retailers:Concentrate procurement in North American markets where regulatory clarity first emerged, with Germany and the United Kingdom representing the largest European opportunities.
- Distributors:Navigate divergent state-level retail oversight delegated to agriculture departments under the 2018 Farm Bill framework.
Consumers handle the majority of throughput; Healthcare Professionals are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites European CBD import velocity, while Denver International Airport's cargo throughput anchors North American distribution velocity for hemp-derived formulations.
United States
Wellness-seeking millennials in California and New York Metro drive subscription platform adoption for stress modulation applications. The FDA maintains evolving enforcement discretion on CBD ingestibles under the 2018 Farm Bill framework, with state agriculture departments exercising delegated retail oversight. Colorado's Front Range cultivation corridor concentrates supercritical CO2 extraction capacity serving pharmacy and direct-to-consumer channels.
Germany
Aging populations in Bavaria and North Rhine-Westphalia seek non-pharmaceutical alternatives for sleep architecture support through pharmacy distribution. BfArM guidance positions the pharmacy channel for health insurance reimbursement pathways unavailable elsewhere in Europe. Hamburg's logistics cluster handles EFSA novel food authorization documentation for cross-border retail expansion into Benelux markets.
United Kingdom
Millennial buyers in Greater London prioritize certificate-of-analysis accessibility over brand heritage when selecting products. The Food Standards Agency enforces novel food authorization requirements with divergent tolerance thresholds for THC contamination across England, Scotland, and Wales. Manchester's analytical laboratory cluster supports third-party verification protocols for direct-to-consumer platforms.
Canada
Healthcare professional segments in Ontario and British Columbia demand prescription-adjacent protocols with standardized dosing. Health Canada and PMRA regulate cannabis-derived products under the Cannabis Act, with hemp-derived CBD falling under separate natural health product pathways. Alberta's extraction infrastructure serves both domestic pharmacy channels and export markets requiring GMP certification.
Australia
Consumer demand in New South Wales and Victoria concentrates on dermatological conditioning applications bypassing novel food authorization costs. The TGA regulates low-dose CBD products under pharmacist-only medicine scheduling, creating pharmacy-centric distribution constraints. Melbourne's formulation science cluster develops nanotechnology emulsion systems for enhanced bioavailability in beverage applications.
CBD Consumer Health Market Key Industry Players
Concentration sits with vertically integrated seed-to-shelf operators and certified organic cultivators commanding premium shelf space in pharmacy and health store channels. The competitive terrain fragments between mass-market direct-to-consumer platforms and clinical-positioned manufacturers investing in dual-track FDA compliance infrastructure. Two strategic archetypes dominate: agricultural heritage brands leveraging cultivation traceability, and formulation science specialists patenting delivery technologies. M&A activity targets analytical laboratory capabilities, while geographic expansion concentrates on Germany's pharmacy reimbursement pathway and United Kingdom subscription platform migration.
Within the agricultural heritage tier, Charlotte's Web and ENDOCA exemplify divergent geographic anchoring strategies. Charlotte's Web occupies a position representing North American vertical integration archetypes with seed-to-shelf traceability systems. ENDOCA sits within the European certified organic cultivation segment, with Dutch-structured operations emphasizing third-party laboratory verification protocols. CV Sciences represents the compliance-forward archetype navigating unresolved FDA pathway classification through dual-track manufacturing investment.
| Leading Market Players |
|---|
| Charlotte's Web |
| ENDOCA |
| CV Sciences |
| Medical Marijuana Inc. |
| Joy Organics |
| Elixinol |
| NuLeaf Naturals |
| The Cronos Group |
| Isodiol International |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Colorado cultivators and extraction operators lock in biomass supply at fixed price points while insulating processors from weather-driven spot market volatility. These arrangements simultaneously secure input visibility for CO2 extraction facilities and stabilize unit economics across tincture and gummy production tiers.
Pricing Analysis
Volume-discount tiering separates pharmacy-grade certified organic SKUs from mass-market direct-to-consumer formats. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and third-party laboratory verification depth. Cost compression in the economy tier is intensifying because ashwagandha and L-theanine substitutes compete at lower price points. Healthcare professionals demonstrate lowest price sensitivity due to prescription-adjacent protocol requirements, while wellness-seeking millennials exhibit highest elasticity.
Supply Chain Analysis
Strategic stockpiling of hemp biomass dominates inventory strategy as cultivators buffer against Kentucky and Colorado weather volatility. Domestic supply concentrates in these two states, with European sourcing from Dutch and German certified organic operations. Raw material dependencies include hemp biomass, supercritical CO2 extraction solvents, and lipid nanoparticle emulsion carriers. Single-source vulnerability runs through Colorado's Front Range extraction corridor. Distribution runs through direct-to-consumer subscription platforms and pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cyclical recovery in CBD consumer health tracks the FDA's unresolved OTC drug monograph timeline, with pathway clarity poised to unlock pharmacy channel expansion and health insurance reimbursement analogs.
For Market Incumbents: Consolidate analytical laboratory capabilities through targeted acquisition to offset the cannabinoid quantification specialist shortage. Deepen backward integration into certified organic cultivation to defend margin position against THC contamination testing cost inflation. Prioritize dual-track manufacturing infrastructure investment as regulatory classification uncertainty persists. For New Entrants and Emerging Players: Lead with nanotechnology emulsion formulations targeting beverage manufacturer partnerships as the most penetrable white-space application. Germany's pharmacy channel represents the lowest competitive density geography for health insurance reimbursement pathway positioning. Deploy QR-linked certificate-of-analysis accessibility as the primary go-to-market differentiator for millennial buyer acquisition. For Investors and Strategic Acquirers: Formulation science specialists patenting lipid nanoparticle delivery systems represent the highest-conviction acquisition archetype for long-term viability across the 5-10 year window. Seed-to-shelf traceability infrastructure commands persistent premium shelf space allocation. Revision becomes warranted when FDA pathway selection crosses definitive thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Track Manufacturing Investment | Positions operators for either dietary supplement or OTC drug monograph compliance under FDA evolving enforcement. |
| Nanotechnology Emulsion Patenting | Secures competitive differentiation through enhanced bioavailability claims validated by pharmacokinetic studies. |
| Certified Organic Cultivation Expansion | Unlocks EFSA novel food authorization eligibility and German pharmacy channel premium positioning. |
| Subscription Platform Development | Captures recurring revenue with personalized dosing protocols that exceed traditional retail repurchase frequency. |
| Analytical Laboratory Acquisition | Addresses HPLC-MS expertise scarcity while internalizing THC contamination verification cost structures. |
Research Approach
Initial hypotheses were tested against primary input from extraction facility operators, pharmacy procurement managers, regulatory affairs specialists, and direct-to-consumer platform executives and refined through secondary validation against FDA enforcement discretion memoranda, EFSA novel food authorization submissions, state agriculture department hemp cultivation reports, and customs trade data. Bottom-up volume modeling triangulated with top-down category sizing across product format, application, and distribution channel dimensions.
Variance decomposition across the projection horizon isolates regulatory pathway uncertainty, substitution threat intensity, and channel migration velocity as primary forecast sensitivity drivers. Segmentation modeling incorporated product type, application use case, distribution channel, and customer archetype dimensions. CAGRs were derived from fitted growth curves anchored to historical adoption patterns and regulatory inflection points. Industry-specific inputs included EFSA toxicology assessment timelines and BfArM pharmacy reimbursement guidance evolution.
Forecasts assume regulatory continuity in FDA enforcement discretion and EFSA novel food authorization regimes; material policy shifts would require re-modeling. Revision becomes warranted when FDA pathway selection or THC contamination tolerance thresholds cross material adjustment boundaries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Mexico Medical Cannabis Market
Cannabis/Marijuana
Cannabis Edibles Market
Cannabis/Marijuana
North America Legal Marijuana Market
Cannabis/Marijuana
US Minor Cannabinoids Market
Cannabis/Marijuana
CBD Oil Market
Cannabis/Marijuana
North America Legal Cannabis Market
Cannabis/Marijuana
Cannabis Use Disorder Treatment Market
Cannabis/Marijuana
Legal Marijuana Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Asia-Pacific CBD Patch Market
Cannabis/Marijuana
Marijuana Sensors Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Market
Cannabis/Marijuana
Latin America and Caribbean Hemp-Derived Cannabidiol Market
Cannabis/Marijuana
Cannabis Capsules Market
Cannabis/Marijuana
CBD Hemp Oil Market
Cannabis/Marijuana
Cannabinoid Therapy Market