
 Chemical Peel Market | 2026-2036
Chemical Peel Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Peel Market Intelligence
North American dermatology device manufacturing is decoupling from European supply dependencies as domestic acid compound production scales. Glytone leverages its physician-dispensed channel heritage to sustain premium positioning in professional settings. Allergan Aesthetics anchors its portfolio through integrated training programs for clinic staff. Bausch Health Companies competes on cost-engineered formulations that navigate price-sensitive outpatient segments.
Chemical peels are acid-based exfoliating formulations, typically employing alpha-hydroxy acids, beta-hydroxy acids, or trichloroacetic acid at concentrations between 10% and 70%, designed to induce controlled epidermal or dermal injury for skin resurfacing and regeneration. AHA and trichloroacetic acid peels dominate professional revenue pools due to their tunable depth and established safety profiles, while enzyme peels represent the fastest-growing category among home users seeking gentler alternatives. Dermatology clinics and medical spas capture the highest-margin application segments, particularly anti-aging and hyperpigmentation protocols that require supervised post-peel management.
The FDA regulates chemical peels as cosmetic or medical devices depending on acid concentration and intended depth of action, creating tiered compliance burdens that favor established manufacturers with dedicated regulatory affairs teams. The EU MDR and REACH frameworks impose additional substance safety testing requirements on formulations entering European professional channels. Stakeholders must monitor evolving classification boundaries between cosmetic and medical-grade peels, as regulatory reclassification would reshape market access costs and competitive barriers.
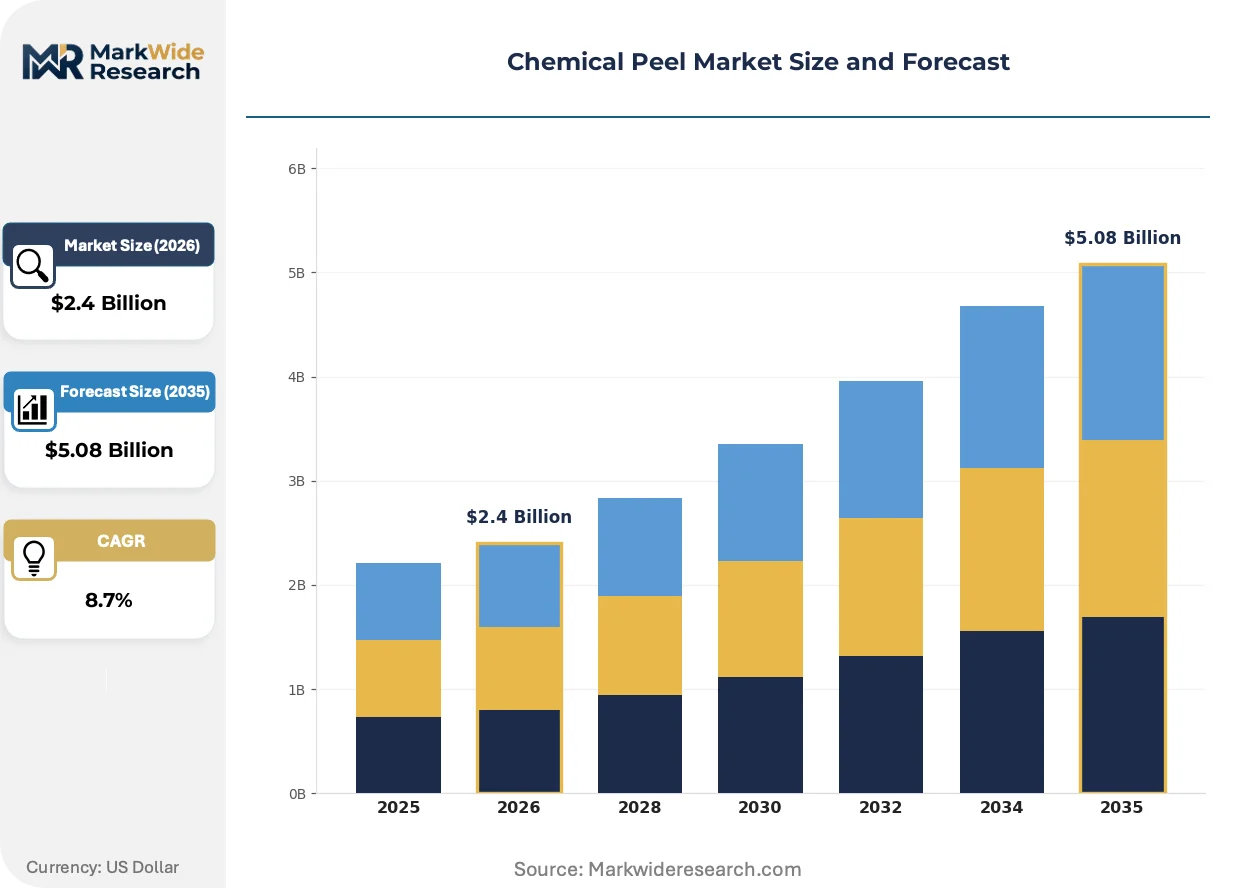
Market Dynamics
The chemical peel market is restructuring around acid concentration thresholds that trigger medical device classification, forcing manufacturers to maintain dual formulation pipelines and dedicated regulatory compliance infrastructure.
Growth Catalysts
- Superficial peel protocols:Dermatology clinics in the United States are expanding lunchtime peel services that require minimal downtime, driving volume through high-frequency, low-complication treatments.
- EU MDR substance safety pathways:REACH-compliant acid sourcing now serves as a competitive credential for European professional channel entry, accelerating investment in certified supply chains.
- Trichloroacetic acid compounding:Medical spas are adopting customizable TCA concentrations for medium-depth resurfacing, creating demand for tunable formulation platforms.
Market Restraints
- Raw acid import dependencies:Domestic glycolic acid production capacity in North America remains concentrated among three specialty chemical suppliers, exposing formulators to feedstock volatility.
- FDA medical device boundary uncertainty:Pending guidance on deep peel classification threatens to reclassify 35% TCA formulations as investigational devices, freezing R&D investment in higher-concentration pipelines.
- At-home device substitution:LED masks and microcurrent tools are capturing budget-conscious consumers seeking non-acid resurfacing alternatives with zero recovery protocols.
Strategic Opportunities
- Enzyme peel home kits:Papaya and pumpkin-derived formulations are penetrating direct-to-consumer channels in Germany and France, where natural cosmetic claims carry premium pricing power.
- Post-peel recovery cosmeceuticals:Ceramide and growth factor serums represent adjacent revenue pools that clinics can capture through bundled protocol pricing.
- Physician extender training modules:Standardized certification programs for nurse practitioners and physician assistants are expanding addressable provider bases beyond board-certified dermatologists.
Industry Challenges
- Compounding pharmacy compliance:State-level oversight variations for in-clinic acid mixing create liability exposure for multi-location medical spa operators.
- Post-inflammatory hyperpigmentation risk management:Fitzpatrick skin type IV-VI protocols require specialized formulation expertise that outpaces current training program availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Peel Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AHA, BHA, Enzyme Peels, Trichloroacetic Acid Application: Acne Treatment, Anti-Aging, Hyperpigmentation, Skin Rejuvenation End User: Dermatology Clinics, Beauty Salons, Home Users, Medical Spas Distribution Channel: Online, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Glytone, Bausch Health Companies, Allergan Aesthetics, L'Oréal, AbbVie, Merz Pharma, IMAGE Skincare, Johnson & Johnson Services, Galderma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Peel Market Strategic Shifts & Innovations
Formulation science is fragmenting the market into concentration-specific niches, while regulatory pressure on depth-of-action claims is compressing marketing flexibility for professional-grade products.
Buffered glycolic acid delivery systems are decentralizing peel administration from physician offices to supervised aesthetician environments. Medical spas in California and Texas are adopting these modified pH platforms for epidermal-only resurfacing. The technology is decentralizing service delivery economics by reducing malpractice insurance burdens and expanding addressable provider pools.
The EU MDR's substance safety notification requirements are forcing reformulation of phenol-based deep peels for European professional markets. Manufacturers must now submit clinical safety dossiers for concentrations exceeding 50% phenol, adding twelve to eighteen months to product launch timelines. German and Swiss dermatology device distributors are prioritizing TCA alternatives to circumvent phenol regulatory complexity.
Subscription-based peel protocols are replacing single-session purchases in United States medical spas. Patients commit to quarterly superficial peels with bundled home-care products, locking in predictable revenue streams for clinic operators. This model is most visible in Miami and Los Angeles aesthetic corridors, where patient lifetime value calculations now dominate acquisition strategy.
Chemical Peel Market Segmentation
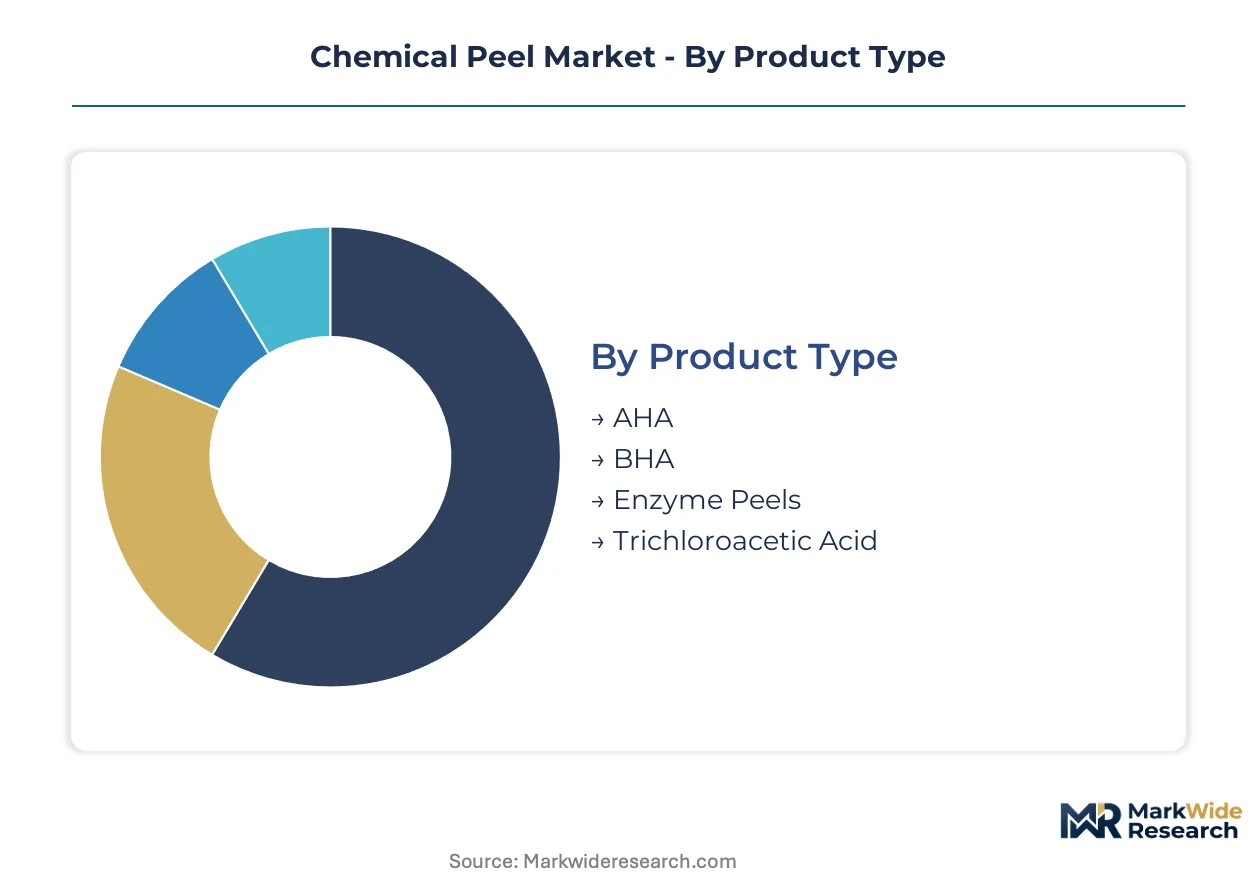
Chemical peel manufacturers design formulations around acid concentration thresholds that determine regulatory classification and clinical application depth. Segmentation choices directly dictate compliance burden, margin structure, and channel access for suppliers.
Product Type:
Clinics cycle patients between superficial and medium-depth protocols based on seasonal downtime availability and cumulative skin tolerance.
- AHA:Glycolic and lactic acid formulations dominate superficial resurfacing protocols in United States dermatology clinics. Miami and Los Angeles medical spas deploy these for high-frequency lunchtime treatments that minimize recovery disruption.
- Trichloroacetic Acid:Concentrations between 20% and 35% enable tunable medium-depth resurfacing for photodamage and fine lines. California and Texas medical spas favor TCA for customizable protocols that command premium pricing over fixed-concentration alternatives.
- BHA:Salicylic acid peels penetrate sebaceous follicles for acne-prone patients. United States clinics integrate these into combination protocols.
- Enzyme Peels:Papaya and pumpkin-derived formulations gain traction in German and French direct-to-consumer channels where natural cosmetic claims support price premiums.
Volume placements concentrate in AHA; the faster expansion belongs to enzyme peels.
Application:
Protocol bundling across multiple indication areas lifts per-patient revenue and extends treatment cycles beyond single-condition resolution.
- Anti-Aging:Collagen induction protocols using serial superficial peels target fine lines and texture irregularities. United States medical spas in aesthetic corridors capture recurring revenue through quarterly maintenance schedules.
- Hyperpigmentation:Melasma and post-inflammatory pigment alteration require carefully titrated acid exposure with strict photoprotection. Dermatology clinics in sun-intensive United States markets develop specialized Fitzpatrick skin type protocols.
- Acne Treatment:BHA and combination peels address comedonal and inflammatory lesions. Teenage and young adult demographics drive volume in outpatient dermatology settings.
- Skin Rejuvenation:General resurfacing for texture and luminosity attracts preventive maintenance patients. United States medical spas market these as entry-level aesthetic procedures.
Anti-Aging commands the largest revenue pool; hyperpigmentation protocols are climbing the fastest as pigmentation concerns rise across diverse skin types.
End User:
Provider credentialing requirements and malpractice exposure stratify service delivery economics across clinical settings.
- Dermatology Clinics:Board-certified supervision enables the deepest acid concentrations and highest complication management capacity. United States clinics capture premium pricing for phenol and high-concentration TCA protocols.
- Medical Spas:Physician oversight with nurse practitioner or physician assistant delivery expands addressable provider bases. California and Texas lead United States adoption of supervised aesthetician-administered buffered glycolic systems.
- Beauty Salons:Cosmetologist-permitted superficial peels operate under lighter regulatory burden in select United States jurisdictions. Service commoditization pressures margins.
- Home Users:Low-concentration enzyme and acid formulations bypass professional supervision entirely. German and French consumers drive premium natural positioning.
Dermatology clinics retain the highest-margin segment; medical spas are gaining share fastest through volume expansion.
Distribution Channel:
Channel selection determines regulatory compliance pathway and customer relationship depth for manufacturers.
- Direct Sales:Manufacturer-to-clinic relationships enable training program bundling and protocol co-development. Allergan Aesthetics and Glytone leverage this channel for premium professional positioning.
- Distributors:German and Swiss dermatology device distributors prioritize TCA alternatives to circumvent phenol regulatory complexity under EU MDR substance safety requirements.
- Online:Direct-to-consumer enzyme peel kits bypass professional gatekeepers entirely. German and French natural cosmetic channels show strongest traction.
- Offline Retail:Pharmacy and specialty beauty retail carry lower-concentration home-use formulations. United States retail placement requires careful concentration management to avoid medical device classification.
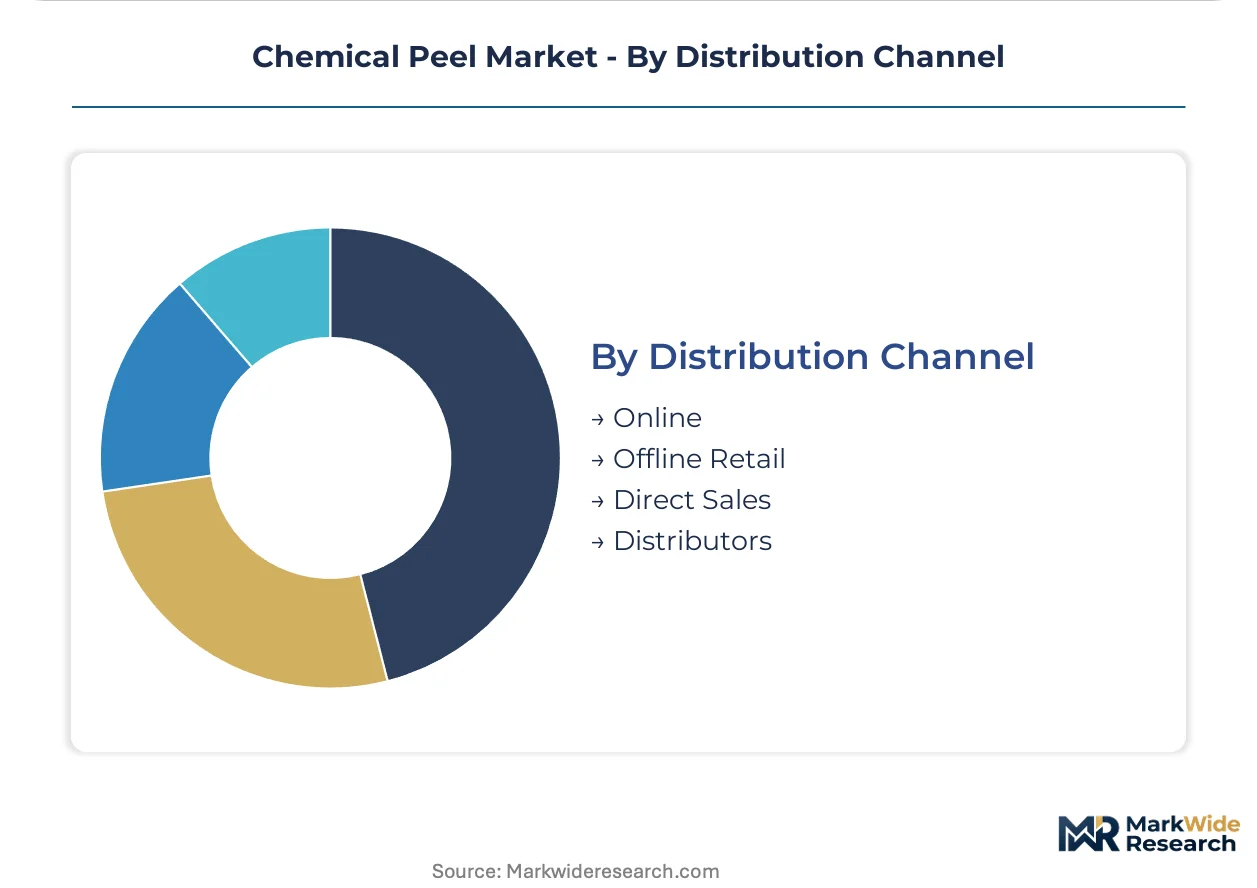
Direct sales capture the highest professional revenue; online channels are expanding most quickly as home-use enzyme formulations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glycolic acid feedstock production concentrates in Texas and Louisiana petrochemical corridors, anchoring North American formulation supply chains. European acid sourcing routes through Antwerp and Rotterdam chemical hubs face REACH compliance recertification cycles.
United States
Miami and Los Angeles medical spas drive superficial peel volume through quarterly subscription protocols. FDA medical device classification thresholds shape manufacturer formulation pipelines. California's supervised aesthetician regulations expand addressable provider bases beyond board-certified dermatologists.
Germany
Düsseldorf and Frankfurt dermatology distributors prioritize TCA alternatives to circumvent phenol regulatory complexity under EU MDR substance safety requirements. German consumers propel enzyme peel direct-to-consumer channels through natural cosmetic premium positioning. ECHA REACH compliance now serves as competitive credential for professional channel entry.
France
Paris aesthetic corridors bundle post-peel recovery cosmeceuticals into protocol pricing for patient lifetime value capture. ANSM oversees cosmetic-medical device boundary classifications for acid concentration thresholds. Lyon and Marseille clinics develop specialized Fitzpatrick skin type IV-VI protocols for pigmentation risk management.
United Kingdom
London Harley Street dermatology clusters command premium pricing for phenol and high-concentration TCA resurfacing. MHRA post-Brexit regulatory divergence creates parallel compliance tracks for EU-exporting manufacturers. Manchester and Birmingham medical spas adopt buffered glycolic systems for supervised aesthetician administration.
Switzerland
Zurich and Geneva dermatology device distributors source REACH-certified acid compounds for cross-border German and French professional markets. Swissmedic substance safety dossier requirements extend phenol-based deep peel launch timelines. Basel chemical formulation heritage supports domestic acid compounding expertise.
Chemical Peel Market Key Industry Players
Global majors compete with regional champions across regulatory compliance infrastructure and physician-dispensed channel access. Market structure tilts toward consolidated professional-grade supply, with fragmentation emerging in home-use enzyme formulations. Three archetypes dominate: pharmaceutical-backed aesthetic divisions, dedicated dermatology device specialists, and diversified consumer beauty conglomerates. M&A activity targets training program capabilities and formulation platform portfolios.
Within the pharmaceutical-backed tier, AbbVie and Galderma occupy positions leveraging existing physician relationships and regulatory affairs scale. Bausch Health Companies exemplifies cost-engineered formulation strategy for price-sensitive outpatient segments. These three anchors represent divergent competitive vectors: premium professional positioning, integrated training bundling, and volume-driven accessibility.
| Leading Market Players |
|---|
| Glytone |
| Bausch Health Companies |
| Allergan Aesthetics |
| L'Oréal |
| AbbVie |
| Merz Pharma |
| IMAGE Skincare |
| Johnson & Johnson Services |
| Galderma |
| Others |
Cost & Logistics Intelligence
Glycolic acid spot prices in Texas and Louisiana petrochemical corridors cascade through formulation tiers, compressing margins on commodity-grade superficial peels while insulating premium phenol-based protocols from feedstock volatility. This input-cost architecture stratifies manufacturer pricing power across concentration thresholds and regulatory classification boundaries.
Pricing Analysis
Service-bundling separates training-inclusive professional contracts from unbundled product-only transactions. Three-tier pricing structure across premium, standard, and economy levels tracks acid concentration, FDA device classification tier, and post-peel recovery protocol inclusion. Pricing pressure stems from at-home LED mask substitution in budget-conscious consumer segments. Medical spas exhibit highest price sensitivity due to subscription-model patient retention demands, while board-certified dermatology clinics absorb premium markups for complication management capacity.
Supply Chain Analysis
Freight costs from Antwerp and Rotterdam chemical hubs to German and Swiss distributors amplify REACH-certified acid premiums over domestic North American sourcing. Concentrated feedstock production in Texas, Louisiana, and Belgian petrochemical corridors feeds from three specialty glycolic acid suppliers. Single-source vulnerability concentrates in trichloroacetic acid compounding inputs. Distribution runs through direct manufacturer-to-clinic relationships for professional-grade formulations, with online channels bypassing gatekeepers for enzyme peel home kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
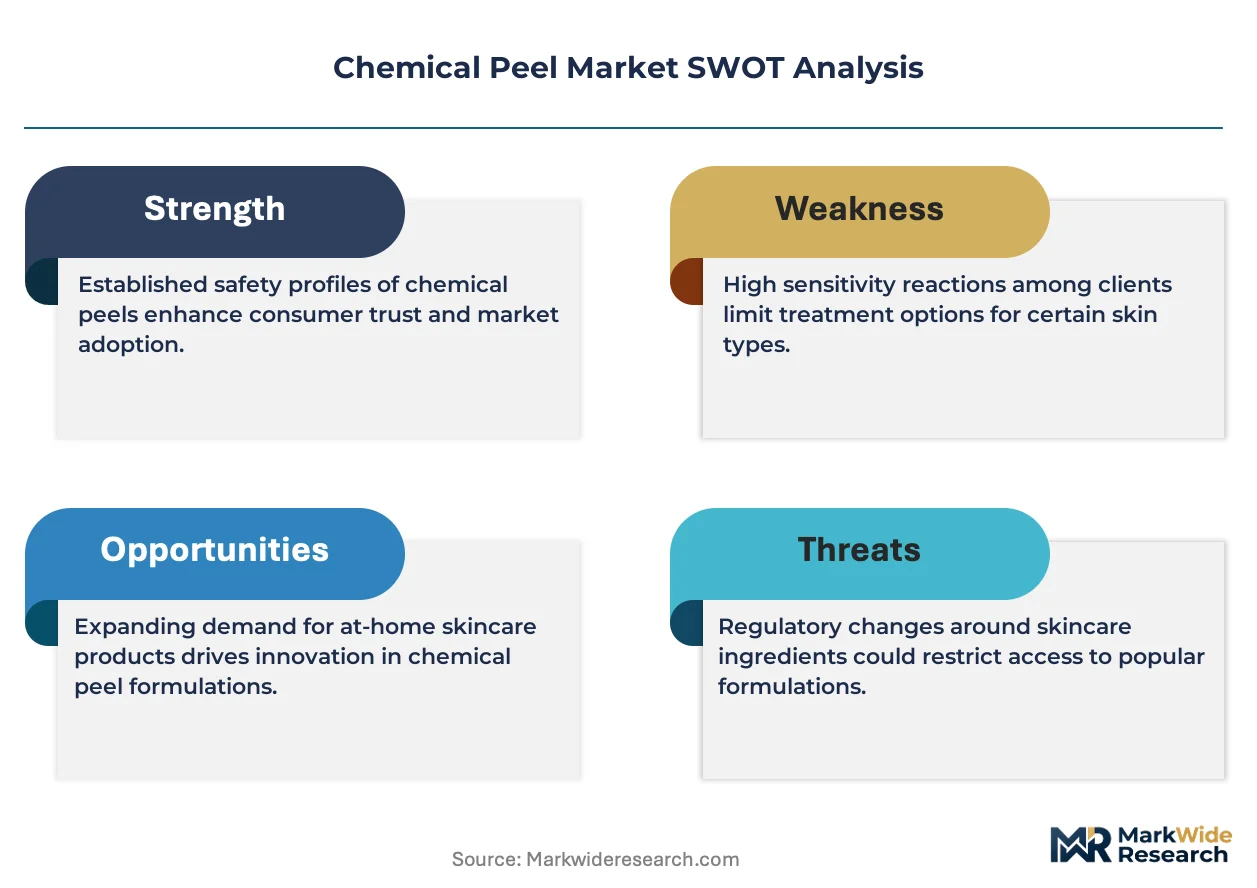
The chemical peel market operates as a cost-of-compliance story where FDA medical device classification thresholds and EU MDR substance safety dossier requirements erect formidable barrier-to-entry moats favoring established regulatory affairs infrastructure.
For Market Incumbents: Anchor premium positioning through proprietary physician extender training certification programs that lock in clinic switching costs. Deepen backward integration into REACH-certified acid sourcing to neutralize Antwerp-Rotterdam freight cost premiums. Defend against enzyme peel substitution by bundling post-peel recovery cosmeceuticals into protocol pricing.
For New Entrants and Emerging Players: Direct-to-consumer online channels in Germany and France offer the most penetrable white-space for papaya and pumpkin-derived enzyme formulations with natural cosmetic premium claims. Target supervised aesthetician-administered buffered glycolic systems in California and Texas where state regulations expand addressable provider pools beyond board-certified dermatologists. Pursue white-label supply partnerships with established compounding pharmacies to circumvent multi-year FDA device pathway timelines.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap formulation platform specialists with existing EU MDR dossier submissions in German-speaking markets over de novo regulatory investments. Long-term viability hinges on subscription-based patient lifetime value capture in Miami and Los Angeles aesthetic corridors. Watch FDA guidance finalization on 35% TCA classification boundaries as the critical inflection signal for pipeline asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Dossier Submission | Twelve-to-eighteen month phenol-based deep peel launch timelines in Germany and Switzerland demand early investment. |
| Physician Extender Certification Program | Standardized nurse practitioner training expands addressable provider bases in California and Texas medical spas. |
| REACH-Certified Acid Backward Integration | Captive glycolic acid supply from Texas-Louisiana corridors neutralizes Antwerp-Rotterdam freight cost premiums. |
| Subscription Protocol Platform Launch | Quarterly superficial peel commitments with bundled home-care products lock recurring revenue in Miami and Los Angeles. |
| Enzyme Peel Direct-to-Consumer Channel | Papaya-derived formulations bypass professional gatekeepers in German and French natural cosmetic premium channels. |
Research Approach
Document review covered FDA 510(k) device filings, EU MDR substance safety notifications, ECHA REACH compliance registrations, and dermatology clinic procurement databases, complemented by interviews with regulatory affairs directors at formulation manufacturers, medical spa operations managers, board-certified dermatologists, and German-Swiss device distributors. Secondary validation drew from customs trade data, SEC 10-K aesthetic division disclosures, and professional association training program records. Bottom-up patient volume modeling and top-down manufacturer revenue triangulation anchored segmentation outputs.
Segmentation outputs across acid type, application indication, end-user credential tier, and distribution channel structure populated the analytical framework over the projection horizon. CAGRs derived from patient visit trend extrapolation, clinic expansion pipeline tracking, and substitution elasticity estimates for at-home device alternatives. Formulation platform R&D pipelines and pending FDA guidance on concentration thresholds served as scenario-weighting inputs.
Inputs from FDA pre-submission meeting minutes and EU MDR notified body consultation records were available through the study window; gaps in state-level compounding pharmacy enforcement variation introduce uncertainty bands around medical spa liability exposure estimates. Forecasts reflect documented assumptions on regulatory classification stability and acid feedstock price continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Non-Invasive Fat Reduction Market
Aesthetic Medicine
Global Cellulite Treatment Market
Aesthetic Medicine
Europe Aesthetic Dermatology Market
Aesthetic Medicine
Facial Rejuvenation Market
Aesthetic Medicine
Middle East and Africa Aesthetic Dermatology Market
Aesthetic Medicine
Photorejuvenation Market
Aesthetic Medicine
Energy-Based Aesthetic Devices Market
Aesthetic Medicine
Global Facial Fat Transfer Market
Aesthetic Medicine
Carboxy Therapy Market
Aesthetic Medicine
North America Medical Aesthetic Devices Market
Aesthetic Medicine
Medical Aesthetic Dermal Filler Market
Aesthetic Medicine
Global Dermal Filler Market
Aesthetic Medicine
Alexandrite Laser Treatment Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
Japan Facial Aesthetics Market
Aesthetic Medicine
Aesthetics Combination Therapy Market