
 Fabricated Structural Steel Market | 2026-2036
Fabricated Structural Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Fabricated Structural Steel Market Analysis
Direct procurement from fabrication shops is tilting toward integrated service models that bundle detailing, cutting, and coating. Valmont Industries anchors its position through captive galvanizing capacity and utility-focused product lines. Schuff Steel Co. leverages coast-to-coast fabrication yards to sustain large-scale infrastructure contracts. O'Neal Manufacturing Services competes via multi-site operational networks serving heavy industrial end users.
Fabricated structural steel comprises hot-rolled or welded sections cut, drilled, welded, and surface-treated to engineering specifications for load-bearing frameworks in buildings and infrastructure. ASTM A992 and A572 grade specifications govern yield strength and weldability for structural members. Commercial buildings command the largest application share, while modular construction represents the fastest-expanding installation category as developers compress project schedules. H-beams and I-beams carry the dominant product volume, though bearing plates capture higher margin pools in seismic and heavy industrial specifications.
FEMA seismic provisions, AISC 360 standards, and OSHA steel erection regulations shape fabrication quality mandates and field installation protocols across the United States. These frameworks elevate compliance costs for smaller shops while rewarding certified producers with preferred contractor status. Stakeholders must monitor evolving building code adoptions at the state level and pre-qualification requirements from institutional project owners.
Market Dynamics
Lean fabrication workflows and AISC certification standards are compressing supplier qualification timelines while elevating technical barriers for uncertified shops across the United States.
Growth Catalysts
- Commercial Building Procurement:Developers in Texas and Louisiana are expanding engineered steel framing system orders for mixed-use towers and logistics facilities.
- OSHA Steel Erection Standards:Updated safety mandates are accelerating prefabrication intensity to reduce field welding hours and exposure risks.
- Modular Construction Methods:Off-site assembly of structural modules is compressing project schedules for healthcare and educational facilities.
Market Restraints
- Scrap Metal Price Volatility:Electric arc furnace operators face margin compression when shredded scrap fluctuates above sustainable input cost bands.
- Gulf Coast Supply Concentration:Petrochemical project clustering in Texas and Louisiana creates localized capacity bottlenecks during peak construction windows.
- Composite Material Substitution:Cross-laminated timber and fiber-reinforced polymers are capturing mid-rise residential framing specifications.
Strategic Opportunities
- Seismic Retrofit Mandates:California and Pacific Northwest jurisdictions are expanding mandatory upgrade programs for existing building stock.
- Integrated Service Bundles:Fabricators combining detailing, cutting, and hot-dip galvanizing under single contracts are capturing preferred vendor status.
- Data Center Construction:Hyperscale facility developers in Northern Virginia and Phoenix are specifying high-load bearing plates for equipment-heavy floors.
Industry Challenges
- Certified Welder Scarcity:AWS D1.1 structural welding qualification programs are failing to replenish retiring craftsperson cohorts at required rates.
- AISC Certification Timelines:New fabrication shops face 18-24 month audit and qualification periods before securing institutional project pre-approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabricated Structural Steel Market |
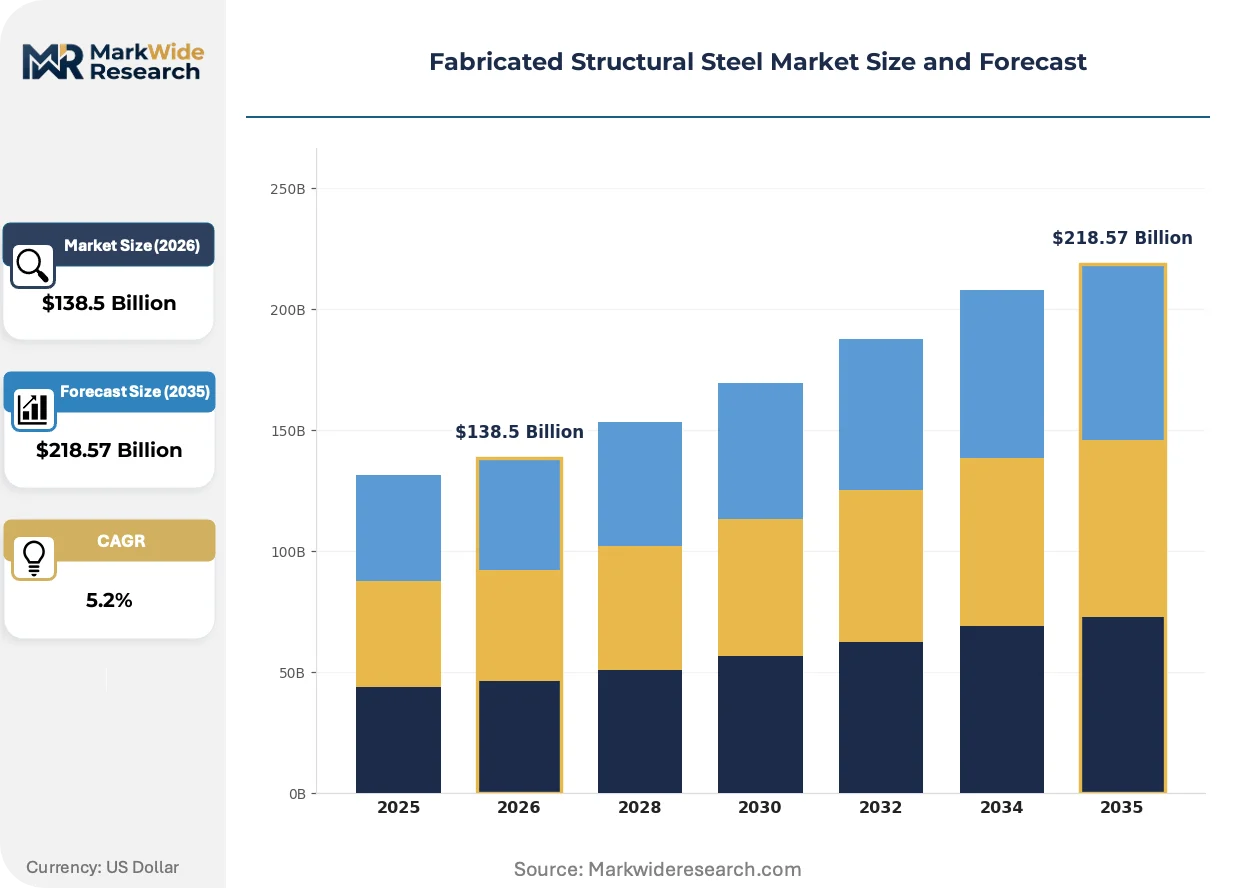
| Market Size in 2026 | $138.5 Billion |
| Market Size in 2035 | $218.57 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bearing Plates, I-Beams, H-Beams, Angle Sections Application: Commercial Buildings, Bridges, Industrial Facilities, Residential Construction Installation: On-site Assembly, Pre-fabrication, Modular Construction, Renovation End User: Contractors, Builders, Architects, Engineers |
| Companies Covered | O'Neal Manufacturing Services, Ironform Corp., Mayville Engineering Company, Inc., Valmont Industries Inc., Anchor Fabrication, Schuff Steel Co., Lexicon, Inc., Groupe Canam Inc., BTD Manufacturing Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabricated Structural Steel Market Emerging Trajectories
Digital fabrication tools and surface treatment advances are compressing production cycles while enabling precision tolerances previously unattainable in high-volume structural steel operations.
Building information modeling is hybridizing with automated plasma cutting systems to enable direct file-to-fabrication workflows. Bridge contractors in the Midwest are adopting these integrated platforms for complex curved girder production. The technology is hybridizing design and manufacturing stages into continuous digital threads that eliminate traditional shop drawing review cycles.
The Infrastructure Investment and Jobs Act is channeling federal funds toward domestic steel procurement preferences for transportation projects. State DOTs are rewriting material specification clauses to require melt-and-manufacture origin documentation. Heavy highway contractors in the Great Lakes region are restructuring supply chains to comply with Buy America domestic content thresholds.
Direct mill-to-fabricator contracting is displacing traditional distributor intermediaries for large-volume structural sections. Institutional project owners in the Southeast are establishing multi-year offtake agreements with specific rolling mills. This channel consolidation is most pronounced in energy corridor developments where schedule certainty outweighs spot market price flexibility.
Fabricated Structural Steel Market Segmentation
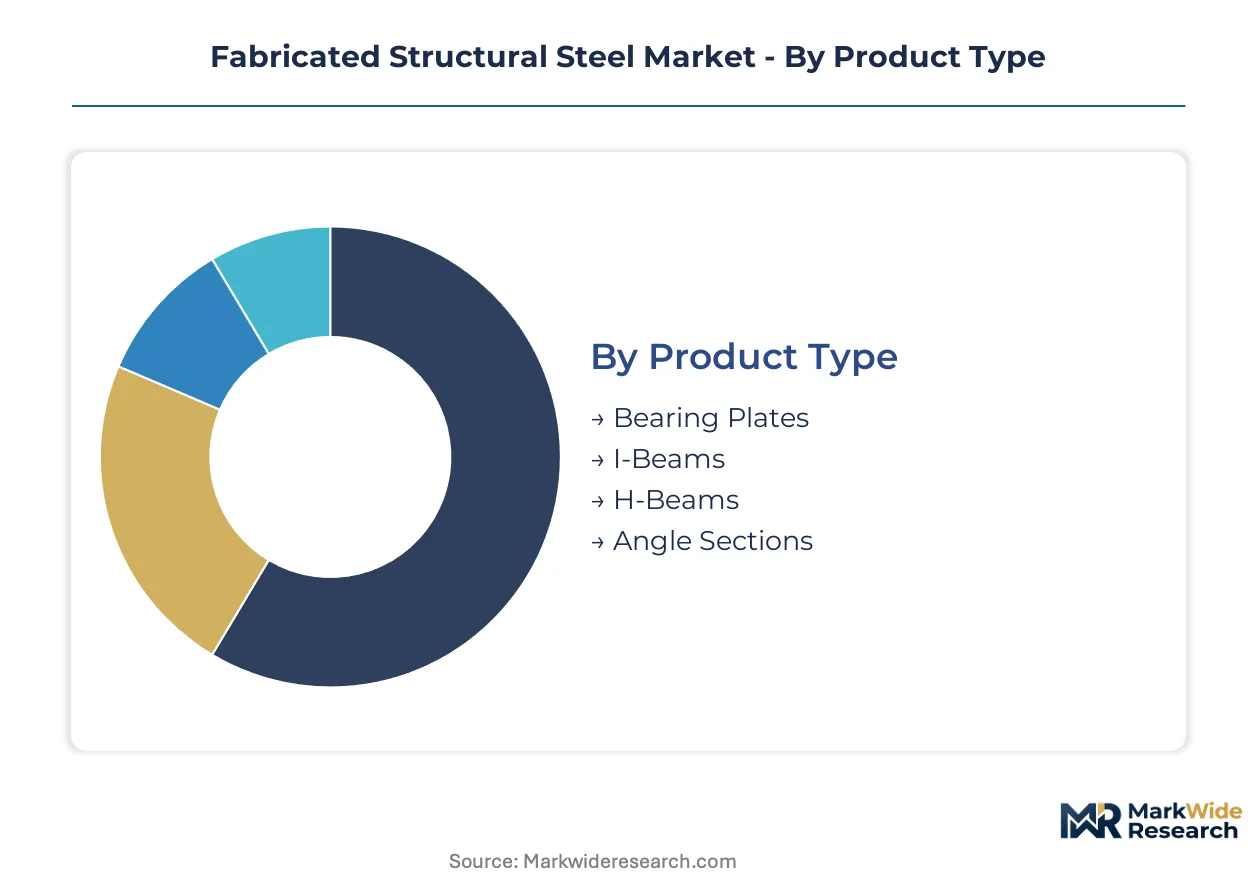
Structural steel fabrication serves divergent technical requirements across load-bearing applications. Segmentation reveals how specification intensity, installation methodology, and procurement authority reshape margin structures and supplier qualification barriers.
Product Type:
Volume concentration and margin capture diverge sharply across structural section geometries and performance grades.
- H-Beams:Wide-flange sections dominate tonnage throughput in multi-story commercial frames. Texas and Louisiana petrochemical corridors absorb substantial H-beam volumes for process structures and pipe racks.
- Bearing Plates:Thick steel plates machined to precise tolerances anchor equipment and transfer concentrated loads. Data center developers in Northern Virginia specify high-yield bearing plates for raised-floor systems supporting dense server arrays.
- I-Beams:Narrow-flange sections retain cost advantages in residential and light commercial framing where span requirements remain modest.
- Angle Sections:L-shaped profiles function as bracing members and connection plates in truss assemblies and secondary framing.
H-beams hold installed capacity. Bearing plates are rotating up the share rankings.
Application:
End-use sectors impose distinct certification, coating, and erection protocols that filter the qualified supplier base.
- Commercial Buildings:Mixed-use towers and logistics facilities command the largest application share. Developers in Texas and Louisiana are expanding engineered steel framing system orders for mixed-use towers and logistics facilities.
- Modular Construction:Off-site assembly of structural modules is compressing project schedules for healthcare and educational facilities. This installation category is climbing the fastest among all application segments.
- Bridges:Curved girder production for highway infrastructure demands AISC Complex Steel Building Structures certification and automated plasma cutting capabilities.
- Industrial Facilities:Petrochemical and energy infrastructure projects in the Gulf Coast corridor require seismic-resistant moment frames and fireproofing integration.
Commercial buildings anchor current volume. Modular construction is gaining share fastest.
Installation:
Field labor intensity and schedule risk distribute differently across assembly methodologies.
- Pre-fabrication:Shop welding of sub-assemblies reduces field exposure hours and accelerates erection timelines. OSHA steel erection standards are accelerating prefabrication intensity to reduce field welding hours and exposure risks.
- Modular Construction:Complete structural modules arrive weather-tight, compressing site duration for schedule-sensitive healthcare and educational clients.
- On-site Assembly:Traditional stick-built erection persists where transport constraints or design fluidity favor field-fabricated connections.
- Renovation:Seismic retrofit mandates in California and Pacific Northwest jurisdictions are expanding mandatory upgrade programs for existing building stock.
Pre-fabrication holds installed capacity. Modular construction is rotating up the share rankings.
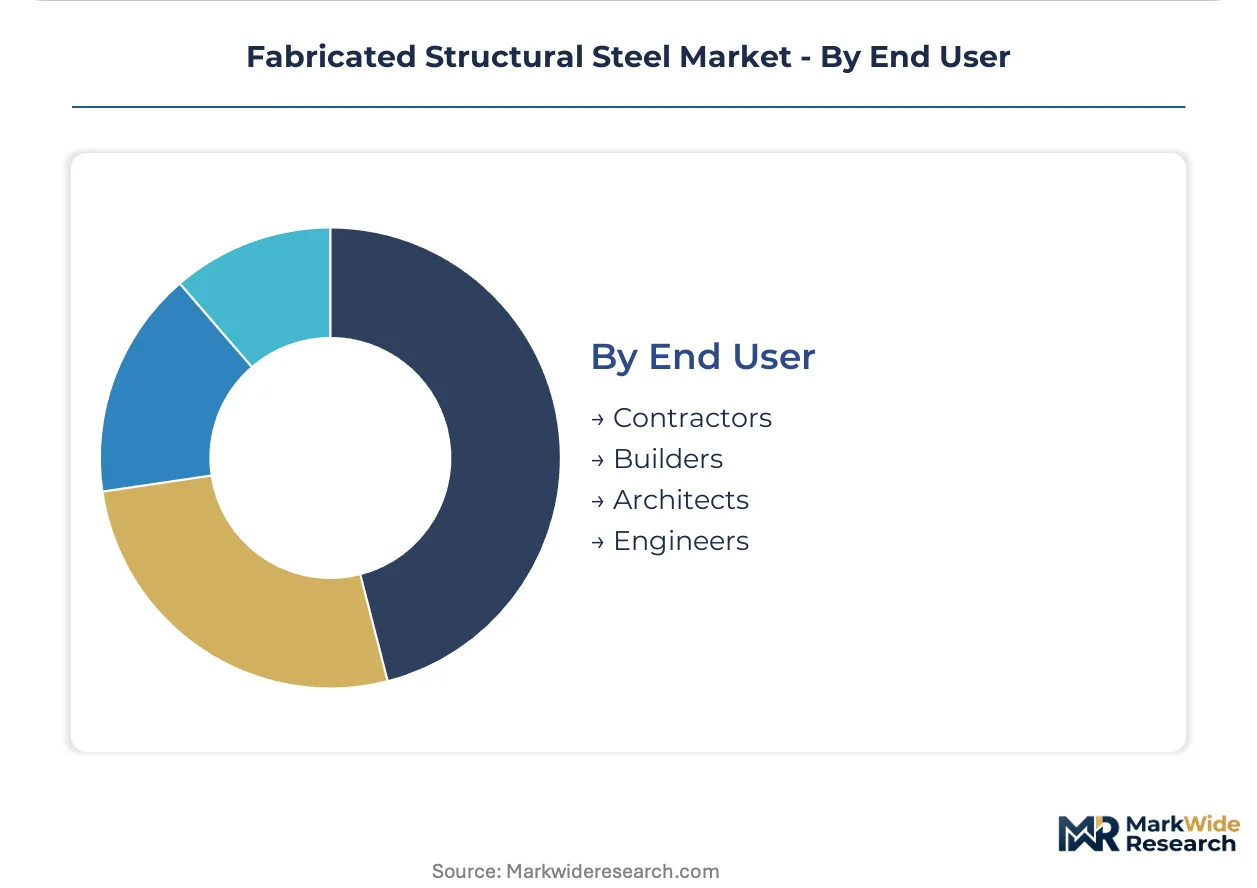
End User:
Procurement authority and technical specification control vary across the project delivery chain.
- Contractors:General and steel erection contractors dominate volume procurement, leveraging AISC certification requirements to filter vendor pools.
- Builders:Design-build entities increasingly bundle detailing, fabrication, and erection under single-contract accountability.
- Architects:Exposed structural steel specifications in civic and institutional projects elevate aesthetic and tolerance requirements.
- Engineers:Structural engineers control connection design and seismic detailing that dictates fabrication complexity.
Contractors hold installed capacity. Builders are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Houston's petrochemical export capacity underwrites Texas's dominance in fabricated structural steel demand. Gulf Coast energy corridors channel federal infrastructure dollars toward specialized fabrication yards. Seismic retrofit mandates and data center construction are redistributing procurement authority across sub-regional clusters.
United States
Commercial building developers in Texas and Louisiana are expanding engineered steel framing system orders for mixed-use towers and logistics facilities. OSHA steel erection standards and FEMA seismic provisions reshape fabrication quality mandates and field installation protocols. The Gulf Coast corridor spanning Houston and Lake Charles concentrates petrochemical and energy infrastructure projects requiring seismic-resistant moment frames.
Canada
Bridge contractors in Ontario and Quebec are adopting automated plasma cutting systems for complex curved girder production. Provincial DOTs are rewriting material specification clauses to require melt-and-manufacture origin documentation under federal infrastructure funding rules. The Great Lakes region hosts heavy highway contractors restructuring supply chains to comply with domestic content thresholds.
Germany
Industrial machinery OEMs in Bavaria and Baden-Württemberg specify precision bearing plates for automated manufacturing lines. CE marking requirements and EU Green Deal carbon intensity benchmarks filter qualified supplier pools for institutional projects. The Rhine-Ruhr industrial belt concentrates fabrication capacity serving automotive and chemical plant construction.
China
State-owned developers in the Yangtze River Delta are specifying high-load structural modules for compressed-schedule hospital expansions. GB standards and MIIT industrial policy directives mandate domestic steel procurement for transportation infrastructure. The Pearl River Delta hosts integrated service providers bundling detailing, cutting, and surface treatment under single-contract accountability.
India
Design-build entities in Maharashtra and Gujarat are expanding modular construction contracts for educational and healthcare facilities. BIS certification requirements and CEA building codes elevate technical barriers for uncertified fabrication shops. The Delhi-NCR corridor concentrates pre-fabrication capacity serving institutional project owners with multi-year offtake agreements.
Fabricated Structural Steel Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in fabrication-only relationships. The vendor base organizes around three strategic archetypes: multi-site operational networks serving heavy industrial end users, coast-to-coast fabrication yards sustaining large-scale infrastructure contracts, and integrated service providers bundling detailing with captive surface treatment capacity. Consolidation pressures favor certified producers with preferred contractor status, while AISC qualification timelines compress new entrant opportunities. Dominant competitive moves include direct mill-to-fabricator contracting displacing distributor intermediaries, and geographic expansion into Gulf Coast petrochemical corridors.
Within the multi-site operational tier, O'Neal Manufacturing Services and Schuff Steel Co. exemplify scale-driven positioning across dispersed fabrication yards. Valmont Industries occupies a position among integrated service providers, representing the archetype that combines captive galvanizing capacity with utility-focused product lines. These three US-based fabricators anchor the competitive structure, with certification status and geographic footprint serving as the primary differentiation vectors for institutional procurement authority.
| Leading Market Players |
|---|
| O'Neal Manufacturing Services |
| Ironform Corp. |
| Mayville Engineering Company, Inc. |
| Valmont Industries Inc. |
| Anchor Fabrication |
| Schuff Steel Co. |
| Lexicon, Inc. |
| Groupe Canam Inc. |
| BTD Manufacturing Inc. |
| Others |
Supply Flow & Price Mechanics
Scrap metal price volatility determines both pricing tier spreads and supply chain shape in fabricated structural steel. Electric arc furnace operators face margin compression when shredded scrap fluctuates above sustainable bands, forcing project-based contract structures that pass input cost risk to institutional buyers while smaller shops absorb spot market exposure.
Pricing Analysis
Volume-discount tiering structures dominate procurement relationships for fabricated structural steel. Three-tier pricing stratifies across AISC Complex Structures certified fabricators, standard AISC certified shops, and uncertified regional operators. Price differentiation hinges on certification grade and geographic delivery cost, with Gulf Coast petrochemical projects commanding premium tiers for seismic-resistant moment frames. Cost compression in the uncertified tier is intensifying because cross-laminated timber captures mid-rise residential specifications. General contractors with multi-year offtake agreements demonstrate least price sensitivity, while speculative commercial developers in secondary markets remain most exposed to spot fluctuations.
Supply Chain Analysis
Extended payment terms from institutional project owners now stretch 90-120 days, forcing fabricators to utilize supply-chain finance facilities anchored by receivables from state DOTs and energy majors. Geographic supply concentration centers on the United States, China, and India, with integrated mills in the Great Lakes region and electric arc furnace operators in the Southeast feeding domestic fabrication yards. Raw material dependencies rest on shredded scrap, hot-rolled wide-flange sections, and zinc for galvanizing operations. Tariff exposure on imported plate steel from traditional trading partners constitutes the primary structural risk. Distribution runs through direct mill-to-fabricator contracting that displaces traditional steel service centers for large-volume structural sections.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fabricated structural steel incumbents must defend against cross-laminated timber and fiber-reinforced polymer substitution in mid-rise framing applications. The threat intensifies as building codes in Pacific Northwest jurisdictions grant equivalent structural ratings to mass timber assemblies.
For Market Incumbents: Build certification moats around AISC Complex Steel Building Structures and Sophisticated Paint Endorsement qualifications. Acquire distressed fabrication capacity in the Gulf Coast corridor to capture petrochemical project clustering. Anchor backward integration into captive galvanizing to offset coating subcontractor margin leakage and secure preferred vendor status with utility-focused developers. For New Entrants and Emerging Players: Data center bearing plate specifications in Northern Virginia and Phoenix represent the most penetrable entry point for non-incumbent fabricators. Seismic retrofit mandates in California secondary cities offer white-space demand with lower incumbent saturation. Pursue design-build partnerships with regional contractors lacking in-house detailing capabilities to bypass traditional AISC certification timeline barriers. For Investors and Strategic Acquirers: Infrastructure Investment and Jobs Act domestic content thresholds reshape the acquisition landscape toward certified fabricators with melt-and-manufacture documentation capabilities. Five-to-ten year viability favors multi-site operational networks with coast-to-coast fabrication yard footprints. Monitor state DOT specification rewrites as the signal for accelerated consolidation among uncertified regional shops.| Strategic Initiative | Industry Significance |
|---|---|
| AISC Complex Structures Certification | Unlocks bridge and petrochemical procurement pools requiring seismic-resistant moment frame expertise. |
| Captive Hot-Dip Galvanizing Capacity | Eliminates coating subcontractor dependency for utility infrastructure and coastal corrosion specifications. |
| Direct Mill Offtake Agreements | Secures H-beam and wide-flange section supply certainty for institutional project owners prioritizing schedule over spot price. |
| Automated Plasma Cutting Integration | Enables curved girder production for bridge contractors adopting BIM-to-fabrication digital workflows. |
| Gulf Coast Corridor Expansion | Positions fabrication yards within logistics radius of Texas and Louisiana petrochemical construction clustering. |
Methodological Framework
Initial hypotheses were tested against primary input from fabrication shop operations directors, steel erection contractor procurement leads, structural engineer specification writers, and state DOT materials engineers, then refined through secondary validation. Primary fieldwork drew from AISC audit documentation, OSHA compliance incident databases, and project owner pre-qualification questionnaires. Secondary sources included customs trade data for steel section imports, SEC 10-K filings from publicly traded fabricators, and Infrastructure Investment and Jobs Act procurement disclosures. Bottom-up project pipeline aggregation was triangulated against top-down capacity utilization surveys from regional fabrication associations.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled included product type geometry, application sector, installation methodology, and end-user procurement authority, with AISC certification tier serving as the industry-specific stratification variable. CAGRs were derived from regression analysis against construction spending indices and industrial production indicators. Forecast inputs incorporated electric arc furnace operating rates, shredded scrap price bands, and petrochemical capital expenditure announcements from Gulf Coast project developers.
Macroeconomic conditions sit as an overlay; deviation in commercial construction lending rates, federal infrastructure appropriation timing, or steel import tariff schedules would shift the trajectory. Forecasts reflect documented assumptions regarding certification adoption curves and modular construction penetration rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Global Structural Health Monitoring Market
Structural Engineering
Global Concrete Restoration Market
Structural Engineering
Europe Facade Market
Structural Engineering
Offshore Structural Analysis Software Market
Structural Engineering
Metal Structural Insulation Panels Market
Structural Engineering
Asia-Pacific Structural Health Monitoring Market
Structural Engineering
FRP Bridge Market
Structural Engineering
Structural Steel Market
Structural Engineering
Translucent Concrete Market
Structural Engineering
Prestressed High Strength Concrete Pipe Pile Market
Structural Engineering
Steel Structure Anchor Bolt Market
Structural Engineering
Americas Structural Insulated Panel Market
Structural Engineering
Self-Healing Concrete Market
Structural Engineering
Europe Insulated Concrete Form (ICF) Market
Structural Engineering
Southeast Asia Anchors and Grouts Market
Structural Engineering
Philippines Roofing Market