
 Europe Facade Market | 2026-2036
Europe Facade Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Facade Market Foresight
The gap between premium engineered facade systems and commodity cladding is rebalancing as energy-code stringency splits procurement criteria. Lindner Group leverages its vertical manufacturing depth to dominate Germany's high-specification commercial segment. Reynaers Aluminium NV anchors Benelux demand through specialized thermal-break systems. Saint-Gobain S.A. competes across glass and composite lines with sustained R&D intensity in solar-control coatings.
Europe facade denotes the external envelope system of a building, comprising curtain walls, cladding panels, and integrated insulation layers engineered to manage thermal transmittance below 0.25 W/m²K in high-performance specifications, serving primarily to regulate energy consumption and occupant comfort. Glass facades lead value pools in commercial towers where solar-gain management commands specification premiums, while composite facades represent the fastest-growing category as architects seek weight reduction paired with insulation performance. Renovation installation types are expanding faster than new construction as the EU building stock renewal mandate redirects capital toward existing structures.
EU Green Deal carbon-reduction targets, ECHA REACH chemical-compliance protocols, and national transpositions of the Energy Performance of Buildings Directive are reshaping material certification requirements and procurement standards across member states. The European Commission's proposed Building Renovation Passport framework will further tighten documentation obligations for facade retrofits. Stakeholders must monitor how the EU AI Act's emerging conformity-assessment rules intersect with automated facade-inspection technologies before committing capital to sensor-integrated envelope platforms.
Market Dynamics
EU Green Deal carbon-reduction mandates are compressing renovation timelines across member states, forcing commercial building owners to accelerate envelope upgrades ahead of tightening Energy Performance of Buildings Directive transpositions. This regulatory pressure is restructuring procurement priorities toward thermal-transmittance performance thresholds below 0.25 W/m²K.
Growth Catalysts
- Energy Performance of Buildings Directive:National transpositions across Germany, France, and the Netherlands mandate deep retrofits of existing commercial stock, redirecting capital toward high-performance facade systems.
- Curtain wall specification:Commercial towers in metropolitan construction corridors prioritize solar-gain management, creating sustained demand for advanced glazing and integrated ventilation layers.
- Aluminum composite panels:Architects specify weight-reduction paired with insulation performance, expanding specification of composite systems in mid-rise commercial and mixed-use developments.
Market Restraints
- Aluminum price volatility:Primary aluminum input costs fluctuate with energy-intensive smelting economics, compressing margin stability for extrusion-dependent system suppliers.
- Glass supply concentration:Float-glass capacity concentrates among limited European producers, creating bottleneck risk for large-scale commercial projects requiring coordinated delivery.
- REACH chemical compliance:ECHA protocols restrict certain coating chemistries and flame-retardant additives, forcing reformulation cycles that extend product certification timelines.
Strategic Opportunities
- Poland and Eastern Europe:Building stock renewal lags Western European penetration rates, creating whitespace for renovation-focused facade contractors and system importers.
- Building Renovation Passport framework:The European Commission's proposed documentation obligations will tighten audit trails for retrofit projects, favoring suppliers with integrated digital specification tools.
- Sensor-integrated envelopes:Convergence of automated inspection technologies with envelope performance monitoring creates new service revenue streams, though stakeholders must navigate emerging EU AI Act conformity-assessment rules.
Industry Challenges
- Façade-engineering talent scarcity:Specialized thermal-bridge calculation and hygrothermal modeling expertise concentrates among aging practitioners, constraining project execution capacity.
- Multi-system integration complexity:Coordinating insulation, ventilation, and solar-control layers with legacy structural frames demands cross-trade coordination that extends installation timelines and warranty risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Facade Market |
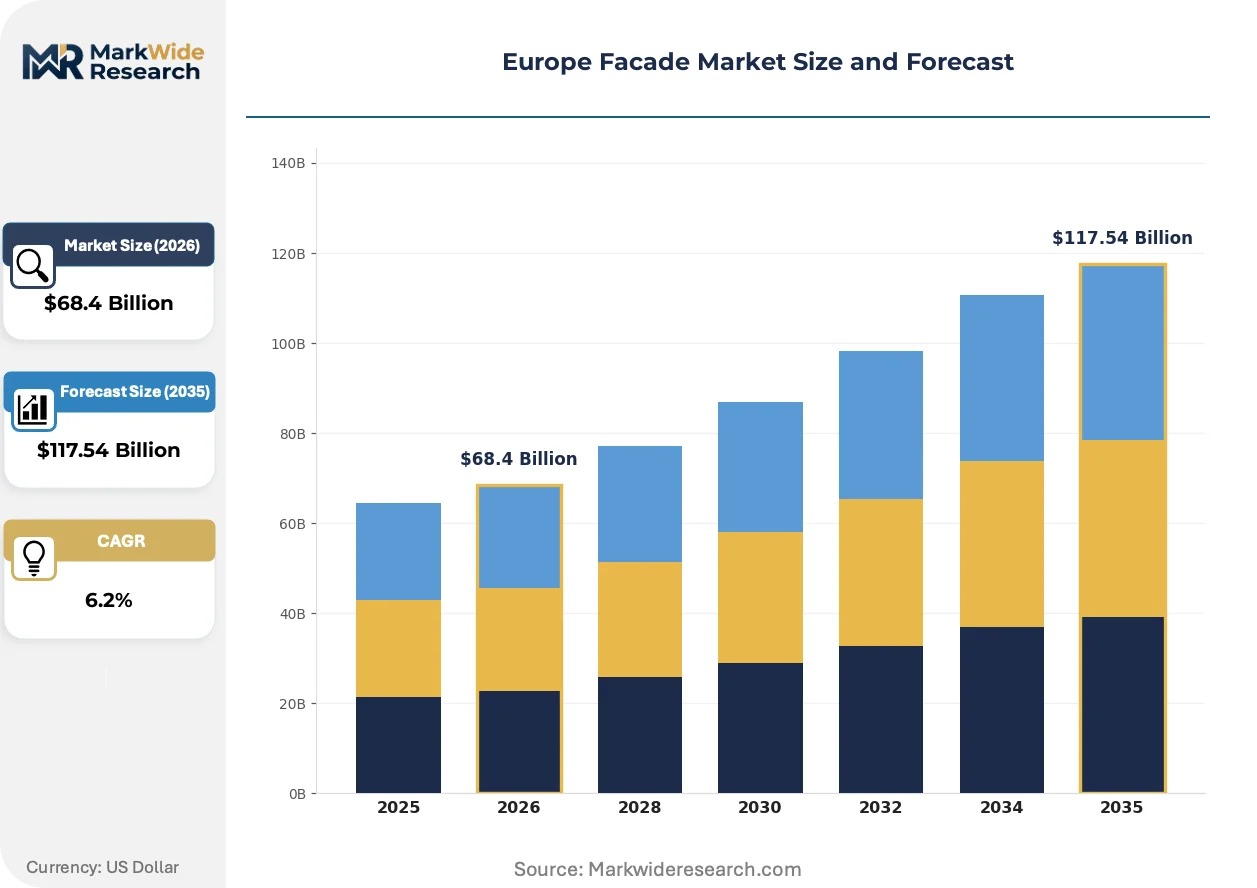
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $117.54 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Facades, Metal Facades, Wood Facades, Composite Facades Installation Type: New Construction, Renovation, Cladding, Retrofitting End User: Residential Buildings, Commercial Buildings, Institutional Buildings, Industrial Structures Material: Aluminum, Steel, Concrete, Fiberglass |
| Companies Covered | Lindner Group, Reynaers Aluminium NV, Saint-Gobain S.A., STO SE & Co. KGaA, Hydro Building Systems, Permasteelisa Group, Kingspan Group, Etex Group, Schüco International KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Facade Market Shifts & Advancements
Active materials and digital specification tools are compressing traditional design-to-installation cycles. Three developments dominate current market evolution.
Electrochromic glazing is absorbing specification share in premium commercial towers. Property developers in Frankfurt and Amsterdam specify dynamic solar-control glass to eliminate external shading hardware. This technology is absorbing capital that previously flowed to static low-emissivity coatings and motorized blind systems.
EU Green Deal implementation timelines are tightening material certification requirements. ECHA REACH protocols now govern flame-retardant content in composite core materials, forcing reformulation of established panel products. German and Dutch facade contractors report extended lead times as suppliers recertify modified chemistries.
Specification authority is migrating from general contractors to specialist facade consultants. Large commercial developments in Paris and Munich now engage independent envelope engineers before main contractor selection, unbundling design liability from construction risk. This shift concentrates influence among technical-specification firms with thermal-modeling capabilities.
Europe Facade Market Segmentation
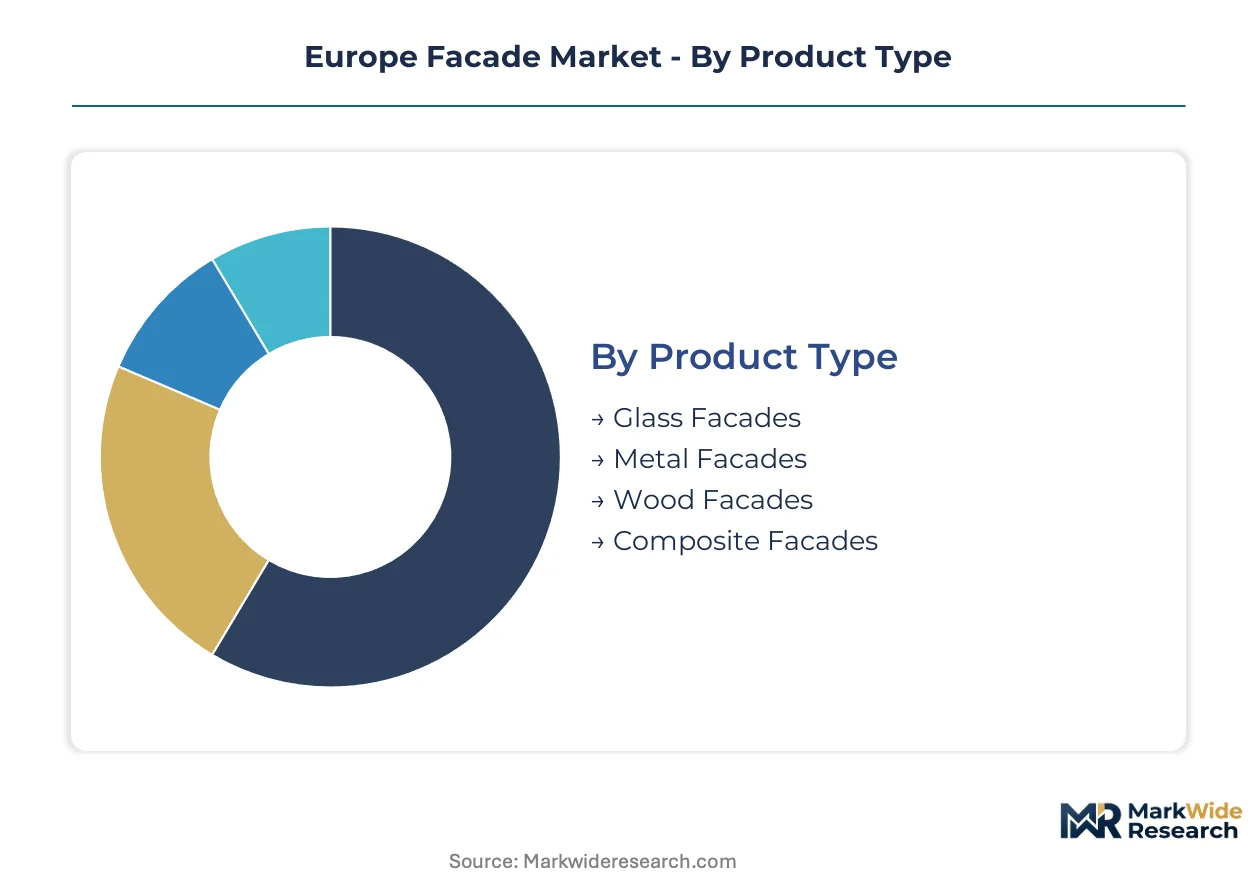
Facade procurement decisions in Europe diverge sharply between premium performance specifications driven by EU Green Deal compliance and cost-optimized solutions serving price-sensitive renovation segments. Understanding where volume concentrates versus where margins expand enables suppliers to align R&D portfolios with regulatory trajectories across Germany, France, and the Netherlands.
Product Type:
Glass facades command premium specification in commercial towers, while composite systems capture volume growth from weight-conscious mid-rise development.
- Glass Facades:Advanced glazing assemblies integrate solar-control coatings and thermal-break framing to achieve U-values below 0.25 W/m²K. Frankfurt and Amsterdam developers specify these systems to eliminate external shading hardware while meeting Energy Performance of Buildings Directive transpositions.
- Composite Facades:Aluminum-honeycomb or mineral-core panels deliver insulation performance at 40% lower weight than traditional masonry. Architects in Dutch mixed-use corridors specify these for mid-rise commercial where structural load limits constrain alternatives.
- Metal Facades:Steel and aluminum rainscreen systems dominate industrial and logistics facilities across Poland and Eastern Europe where capital constraints limit envelope investment.
- Wood Facades:Cross-laminated timber cladding serves Nordic residential markets and German low-carbon building certifications, though fire-rating restrictions limit commercial adoption.
Today's leader: Glass facades. Tomorrow's challenger: Composite facades.
Installation Type:
New construction concentrates in metropolitan corridors, yet renovation volumes are accelerating as building stock renewal mandates redirect capital.
- Renovation:Deep envelope retrofits of existing commercial stock in Germany, France, and the Netherlands now absorb the majority of high-performance system demand. EU Green Deal carbon-reduction timelines compress project execution windows, favoring contractors with digital specification tools.
- Retrofitting:Overcladding of legacy concrete and masonry structures with insulated rainscreen systems addresses thermal-bridge remediation without full demolition. Paris and Munich contractors report extended lead times as facade-engineering talent scarcity constrains project capacity.
- New Construction:Curtain wall specification in commercial towers concentrates solar-gain management demand, though pipeline volumes lag renovation growth rates.
- Cladding:Panelized systems serve mid-rise residential and mixed-use where speed of enclosure drives procurement criteria over thermal performance optimization.
Renovation dominates current procurement volumes; retrofitting shows the steepest expansion trajectory as Building Renovation Passport documentation obligations tighten.
End User:
Commercial building owners face the most acute regulatory pressure, while residential and institutional segments follow divergent compliance timelines.
- Commercial Buildings:Office towers and retail complexes in German metropolitan construction corridors drive specification of integrated ventilation and solar-control layers. ECHA REACH protocols on flame-retardant content force reformulation cycles that extend product certification timelines.
- Institutional Buildings:Healthcare and education facilities across the Netherlands prioritize hygrothermal performance and indoor air quality, engaging specialist facade consultants before main contractor selection.
- Residential Buildings:Multi-family housing in France and Benelux concentrates demand for cost-optimized composite systems, though energy-code stringency is narrowing the performance gap with commercial specifications.
- Industrial Structures:Logistics and manufacturing facilities in Eastern Europe prioritize weatherproofing and speed of installation over thermal transmittance thresholds.
Commercial buildings anchor specification premiums; institutional buildings are gaining share fastest as public procurement tightens performance documentation requirements.
Material:
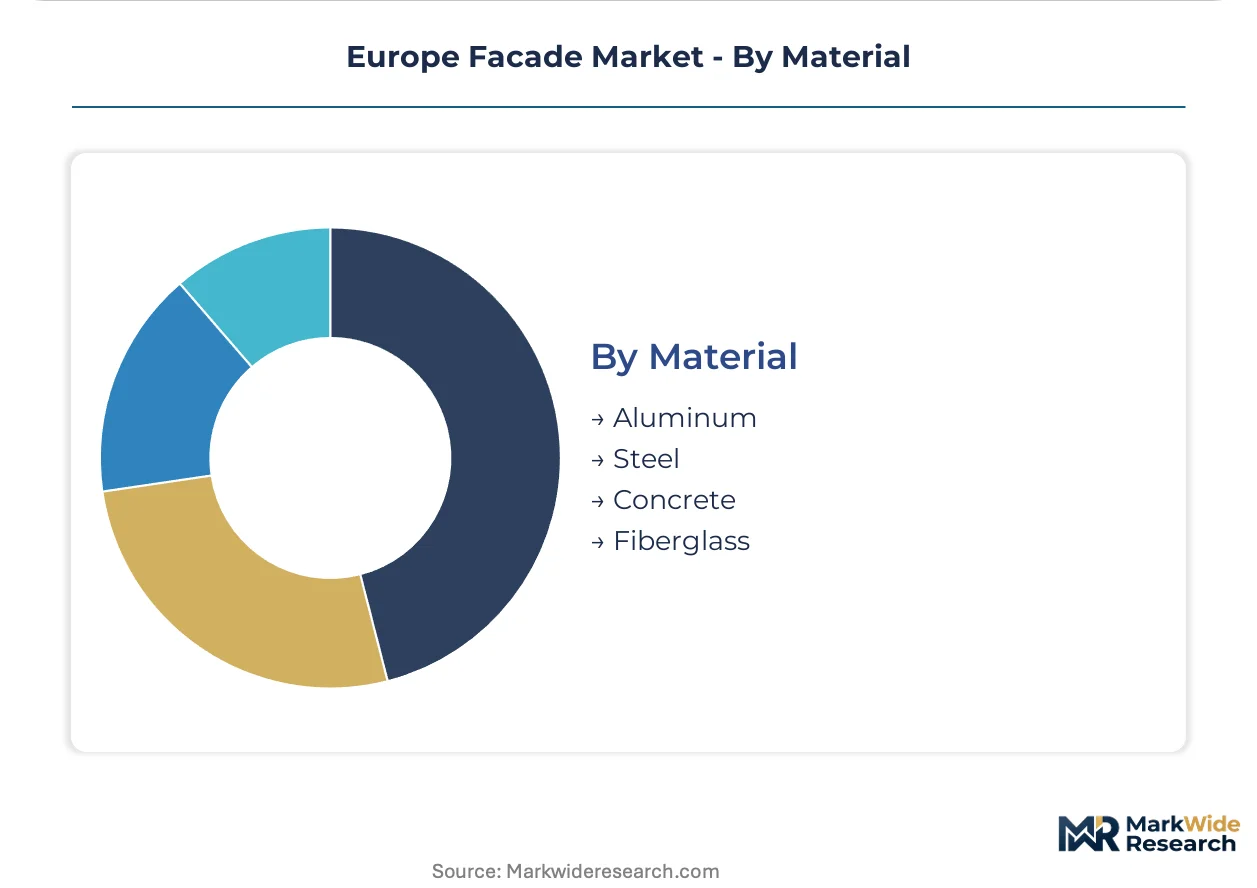
Aluminum and steel dominate structural framing, yet fiberglass is penetrating niche applications where thermal bridging must be eliminated.
- Aluminum:Extruded profiles with polyamide thermal breaks form the structural backbone of curtain wall and window-wall systems. Primary aluminum price volatility tied to energy-intensive smelting economics compresses margin stability for system suppliers.
- Steel:Cold-formed profiles and sheet metal dominate industrial facades and rainscreen substructures across Poland and Eastern Europe where first-cost sensitivity limits aluminum specification.
- Concrete:Precast sandwich panels with integrated insulation serve large-scale residential and institutional projects in France and Germany where fire resistance and acoustic performance dominate criteria.
- Fiberglass:Pultruded profiles penetrate window and door framing in Nordic markets where thermal-bridge-free construction is mandated, though supply concentration limits scale.
Aluminum retains structural dominance; fiberglass is climbing the fastest as zero-thermal-bridge specifications spread beyond Nordic markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facade-engineering talent concentrates in German metropolitan corridors, anchoring high-performance specification authority across the continent. This expertise distribution shapes where advanced envelope systems achieve market penetration first.
Germany
Commercial towers in Frankfurt and Munich drive specification of integrated ventilation and solar-control layers. The Energy Performance of Buildings Directive transposition mandates deep retrofits of existing office stock by 2030. Bavarian and North Rhine-Westphalian construction corridors absorb the majority of high-performance curtain wall demand as local codes tighten thermal-transmittance thresholds.
France
Parisian developers engage specialist facade consultants before main contractor selection, unbundling design liability from construction risk. The EU Green Deal's carbon-reduction timeline compresses renovation execution windows for commercial buildings in Île-de-France. Auvergne-Rhône-Alpes and Hauts-de-France industrial zones supply precast concrete sandwich panels with integrated insulation for large-scale institutional projects.
Netherlands
Amsterdam architects specify electrochromic glazing to eliminate external shading hardware while meeting stringent solar-gain management requirements. ECHA REACH protocols govern flame-retardant content in composite core materials, forcing reformulation of established panel products. Randstad metropolitan construction corridors concentrate demand for weight-reduced composite systems in mid-rise mixed-use developments.
Poland
Building stock renewal lags Western European penetration rates, creating whitespace for renovation-focused facade contractors. National transpositions of EU energy-performance standards are accelerating compliance timelines for existing commercial structures. Warsaw and Kraków logistics facilities prioritize steel rainscreen systems where capital constraints limit aluminum specification.
United Kingdom
London commercial towers sustain demand for advanced glazing assemblies despite post-Brexit regulatory divergence from EU certification frameworks. The Building Safety Regulator's documentation obligations tighten audit trails for retrofit projects. Southeast England and Midlands construction clusters concentrate specification of aluminum composite panels where speed of enclosure drives procurement criteria.
Europe Facade Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the European facade market. Integrated system manufacturers with captive aluminum extrusion and glass processing capabilities command premium positioning in high-specification commercial segments. Three archetypes dominate: vertically integrated envelope specialists, component-focused material suppliers, and project-execution contractors. Competitive moves concentrate on backward integration into primary aluminum supply and geographic expansion into Eastern European renovation whitespace.
Among Germany-based fabricators, Lindner Group and Schüco International KG exemplify vertically integrated envelope specialists with manufacturing depth across multiple material lines. Reynaers Aluminium NV represents the component-focused tier, anchoring thermal-break system supply across Benelux markets. Saint-Gobain S.A. occupies a position spanning glass and composite material platforms, reflecting sustained investment in solar-control coating capabilities.
| Leading Market Players |
|---|
| Lindner Group |
| Reynaers Aluminium NV |
| Saint-Gobain S.A. |
| STO SE & Co. KGaA |
| Hydro Building Systems |
| Permasteelisa Group |
| Kingspan Group |
| Etex Group |
| Schüco International KG |
| Others |
Supply & Pricing Matrix
Commercial building owners in German metropolitan corridors anchor procurement volumes, compressing supplier margins through project-scale aggregation and bundled performance contracting that ties envelope installation to long-term energy guarantees. This buyer concentration forces tiered pricing stratification across premium engineered systems, mid-range composite assemblies, and economy metal rainscreens.
Pricing Analysis
Project-based bundled service contracts dominate facade procurement, unbundling design engineering from installation labor only in high-specification commercial towers. Price differentiation hinges on thermal-transmittance certification tiers and geographic delivery distance from manufacturing clusters in Bavaria and North Rhine-Westphalia. Cost compression in economy metal segments intensifies as Polish contractors import standardized steel rainscreen systems, while premium electrochromic glazing commands specification premiums in Amsterdam and Frankfurt developments. Residential multi-family developers in France and Benelux exhibit highest price sensitivity, whereas institutional healthcare facilities prioritize hygrothermal performance over capital cost.
Supply Chain Analysis
Reverse-logistics flows for aluminum composite panel refurbishment remain underdeveloped, constraining circular material recovery as ECHA REACH reformulation cycles extend product lifecycles. Primary aluminum supply concentrates in Norway, Iceland, and Germany, drawing from energy-intensive smelting economics that tether input costs to regional power pricing. Float-glass capacity clusters in France, Germany, and Belgium, creating single-source vulnerability for large-scale commercial developments requiring coordinated delivery. Distribution runs through specialized facade contractors with captive installation crews rather than merchant distributors, concentrating channel control among vertically integrated envelope specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the Europe facade market rests on aluminum input cost stabilization and premium-tier shift toward sensor-integrated envelope platforms that capture recurring service revenue.
For Market Incumbents: Anchor high-specification positioning through captive aluminum extrusion capacity and thermal-break system certification investments that ECHA REACH protocols now mandate. Consolidate project-execution capacity by acquiring specialist facade consultants in Paris and Munich, where design liability unbundling threatens traditional general-contractor relationships. Defend against Polish import competition through digital specification tools that accelerate Building Renovation Passport documentation. For New Entrants and Emerging Players: Begin with renovation-focused service models in Poland and Eastern Europe, where building stock renewal lags Western penetration rates and local facade-engineering talent scarcity constrains incumbent response capacity. Target overcladding retrofit projects in Warsaw and Kraków commercial structures, where capital constraints favor speed-optimized panelized systems over full curtain-wall replacement. Partner with established aluminum system suppliers for thermal-break technology licensing rather than greenfield R&D investment. For Investors and Strategic Acquirers: Building materials conglomerates with captive glass and aluminum platforms represent the most active acquirer category in this space, seeking envelope-system capabilities to complete vertical integration. Long-term viability favors targets with digital specification tools and sensor-integration R&D pipelines. Monitor EU AI Act conformity-assessment rule finalization as inflection indicator for automated facade-inspection technology deployment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Aluminum | Norwegian smelter partnerships secure energy-cost advantage for German system suppliers. |
| Digital Specification Tool Development | Building Renovation Passport compliance accelerates software adoption among Dutch contractors. |
| Sensor-Integrated Envelope Platform Launch | EU AI Act conformity rules will determine automated inspection technology deployment pace. |
| Eastern European Renovation Expansion | Polish building stock renewal mandates create whitespace for facade contractor capacity buildout. |
| Thermal-Break System Certification Investment | ECHA REACH flame-retardant reformulation extends product recertification timelines for composite panel suppliers. |
Research Methodology
Coverage spans Germany, France, the Netherlands, Poland, and the United Kingdom, with primary inputs from each market derived through structured interviews with facade engineering consultants, commercial building procurement directors, aluminum system manufacturer technical leads, and specialist envelope contractors. Secondary validation draws from EU Energy Performance of Buildings Directive national transposition documents, ECHA REACH substance restriction updates, national construction statistics bureaus, and trade customs data for aluminum and glass imports. Bottom-up project pipeline analysis triangulates with top-down building stock renewal mandate quantification.
Granularity-level modeling disaggregates volume and value across product type, installation category, end-use sector, and material composition, with thermal-transmittance performance tier as an additional industry-specific dimension. CAGRs derive from regression analysis of historical renovation permit issuance correlated with regulatory compliance timeline acceleration. Forecast inputs incorporate aluminum price volatility scenarios and ECHA chemical restriction implementation schedules.
Several conditions sit outside the modeled scope, including potential Brexit regulatory divergence effects on UK certification mutual recognition and unforeseen EU AI Act enforcement severity on sensor-integrated systems. Forecasts reflect assumptions regarding Energy Performance of Buildings Directive transposition uniformity across member states. Practitioners should monitor ECHA substance restriction expansion proposals and primary aluminum smelter energy cost shocks for early signals warranting forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Civil Engineering Market
Structural Engineering
Fabricated Structural Steel Market
Structural Engineering
UK Facade Market
Structural Engineering
Bridge Expansion Joint Market
Structural Engineering
Asia-Pacific Structural Health Monitoring Market
Structural Engineering
High Strength Concrete Market
Structural Engineering
Cold-Formed Steel Market
Structural Engineering
Self-Healing Concrete Market
Structural Engineering
Self-Compacting Concrete Market
Structural Engineering
Steel Structure Anchor Bolt Market
Structural Engineering
Global Structural Health Monitoring Market
Structural Engineering
Structural Lightweight Concrete Market
Structural Engineering
Global Concrete Restoration Market
Structural Engineering
Prestressed Concrete Market
Structural Engineering
Americas Structural Insulated Panel Market
Structural Engineering
Philippines Structural Insulated Panels Market