
 Wear Plates Market | 2026-2036
Wear Plates Market Size, Share, and Industry Trends Forecast 2026-2036
Wear Plates Market Analytics
Composite ceramic overlays are expanding their addressable market as quarry operators substitute polymer-lined chutes with higher-hardness alternatives that survive silica-rich feed streams. SSAB dominates premium quenched-and-tempered plate supply through captive steelmaking in Sweden and the United States. JFE Steel Corporation anchors Asian project logistics with mill-direct delivery to Japanese shipyards and Southeast Asian mining contractors. Thyssenkrupp differentiates via integrated heat-treatment capacity that compresses lead times for German automotive tool-and-die customers.
Wear plates are hardened steel, ceramic, polymer, or composite flat products engineered to resist abrasion, impact, and erosion in material-handling equipment, typically specified by Brinell hardness ratings from 400 to 700 BHN and installed as bolt-on or weld-on liners. Metallic grades still occupy the largest volume share due to established welding protocols and scrap-value recovery at end of life, though composite segments are gaining fastest as Brazilian iron ore processors and Australian coal operators validate ceramic-metal hybrid architectures against pure steel baselines. Pre-fabricated installation formats command margin premiums by reducing field welding hours, while on-site custom fitting remains the default for aging infrastructure retrofits where dimensional tolerances have degraded.
ASTM International governs hardness testing and material characterization for North American-specified plates, while ISO 9001 certification shapes supplier qualification for European mining OEMs and Chinese state-owned construction conglomerates. REACH compliance pressures European producers to document chromium and nickel content in high-alloy formulations, adding traceability costs that favor integrated mills over traders. Stakeholders must monitor how China's GB standards evolution and the EU Green Deal embodied-carbon tracking reshape sourcing decisions for cross-border mining equipment contracts.
Market Dynamics
Composite ceramic-metal hybrid architectures are displacing conventional quenched-and-tempered steel in high-abrasion mining applications, forcing suppliers to recalibrate heat-treatment investments and certification protocols across their production networks.
Growth Catalysts
- Iron ore processing intensity:Australian and Brazilian mining operators are expanding procurement of composite wear plates to extend equipment lifecycles in silica-rich feed streams.
- REACH compliance documentation:European producers must now trace chromium and nickel content in high-alloy formulations, favoring integrated mills with captive metallurgical control over trading intermediaries.
- GB standards evolution:China's tightening quality management protocols for heavy manufacturing corridors are accelerating bulk replacement cycles in steel mills and cement plants.
Market Restraints
- Alloy input volatility:Nickel and chromium price swings compress margin predictability for high-hardness plate producers dependent on specialty scrap streams.
- Supply concentration in Nordic steelmaking:Premium quenched-and-tempered capacity clusters in Sweden and Finland, exposing buyers to single-source logistics risk during Baltic shipping disruptions.
- Polymer substitution in low-abrasion zones:Quarry operators retain polymer-lined chutes for non-silica applications, capping metallic plate penetration in secondary processing stages.
Strategic Opportunities
- Pre-fabricated installation formats:Bolt-on liner systems command margin premiums by eliminating field welding hours for German automotive tool-and-die customers.
- Southeast Asian mining contractor expansion:Mill-direct delivery protocols from Japanese producers are opening project logistics channels in Indonesian and Vietnamese coal operations.
- EU Green Deal embodied-carbon tracking:Cross-border mining equipment contracts now require documented carbon intensity, creating qualification barriers for non-European suppliers without EPD certification.
Industry Challenges
- Welding technician scarcity:Field installation of weld-on liners demands certified alloy welders, a skill cohort aging out in Australian and South African mining regions.
- Dimensional tolerance degradation:Aging infrastructure retrofits require on-site custom fitting where original equipment drawings have been lost, extending project timelines.
- ISO 9001 certification timeline compression:European mining OEMs now demand 12-month requalification cycles, straining quality management resources at mid-cap plate processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wear Plates Market |
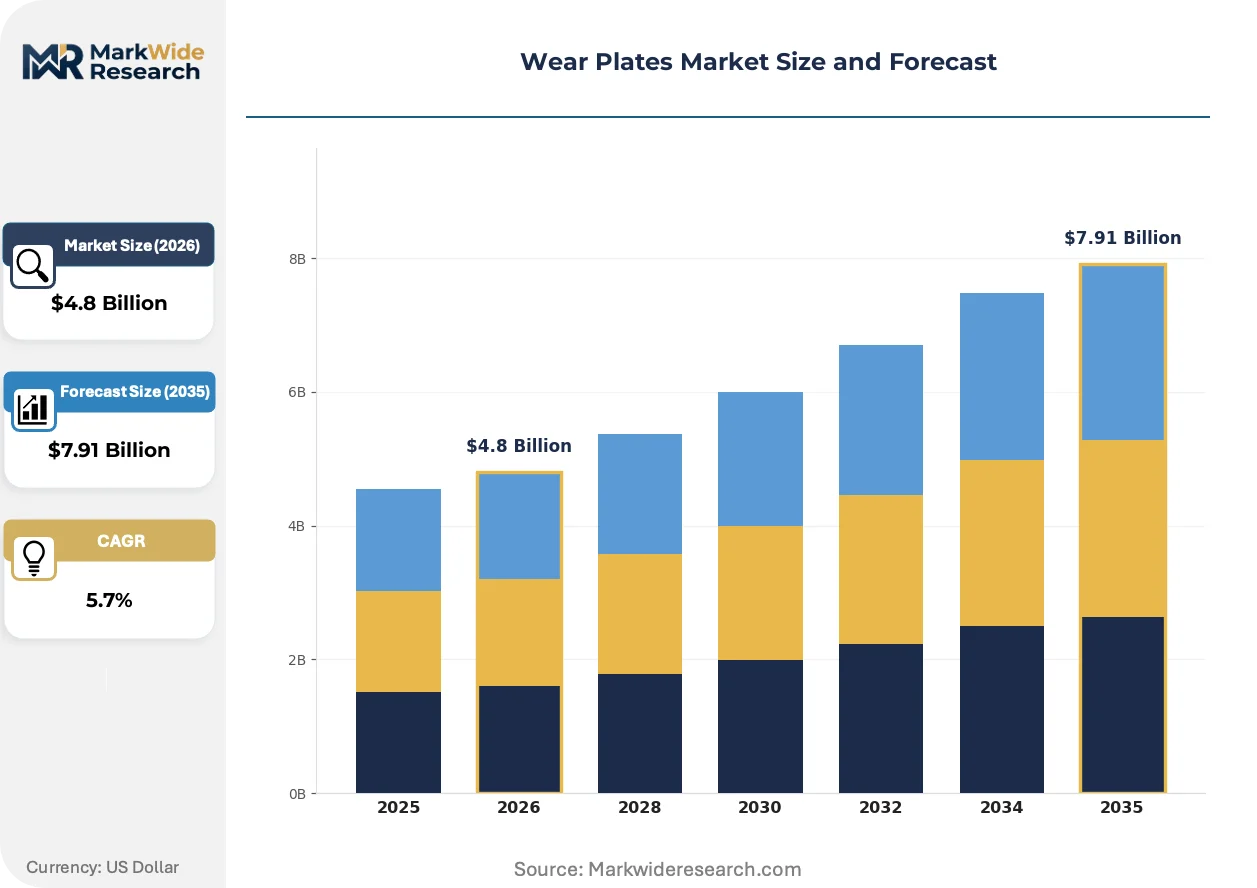
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic, Polymeric, Composite, Ceramic End User: Mining, Construction, Agriculture, Manufacturing Installation Type: On-Site, Pre-Fabricated, Custom Fit, Standard Fit Application: Cutting, Grinding, Crushing, Abrasion Control |
| Companies Covered | SSAB, JFE Steel Corporation, Thyssenkrupp, ArcelorMittal, Dillinger, Nippon Steel Corporation, Bisalloy Steel Group, Voestalpine, NLMK Clabecq, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wear Plates Market Evolving Landscape
Material science advances and regulatory traceability mandates are converging to reshape specification protocols, installation methods, and supplier qualification criteria across mining and heavy manufacturing verticals.
Ceramic overlay deposition via plasma-transferred arc welding is electrifying wear surface engineering by fusing tungsten carbide particulates into ductile steel substrates. Brazilian iron ore processors are validating these hybrid architectures against pure steel baselines in primary crusher feed chutes. The technology is electrifying competitive positioning by enabling 3x service-life extension without full component replacement.
REACH substance-of-very-high-concern listings are tightening disclosure thresholds for hexavalent chromium in welding consumables. European fabricators must now substitute low-chromium filler metals or install extraction systems for field repairs. German automotive tool-and-die customers are responding by consolidating procurement with suppliers holding ECHA-registered chemical safety dossiers.
After-sales service unbundling is fragmenting traditional supply relationships in Chinese state-owned construction conglomerates. These buyers now separate plate procurement from installation contracting, pitting domestic traders against mill-direct channels. The shift is most visible in cement plant expansion projects along the Yangtze River manufacturing belt, where logistics cost optimization overrides single-source loyalty.
Wear Plates Market Segmentation
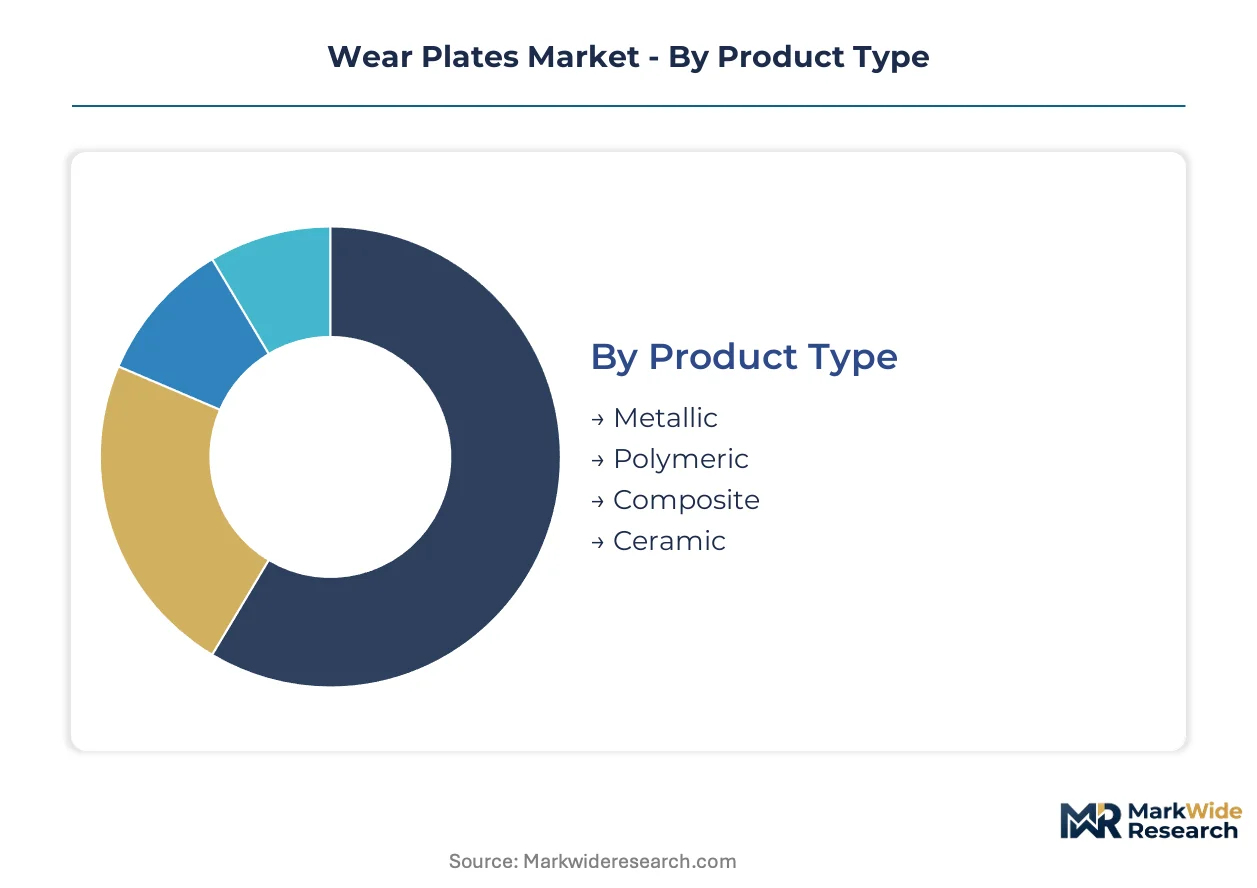
Wear plate specification protocols diverge sharply across material classes and installation contexts. Procurement decisions hinge on hardness ratings, welding compatibility, and lifecycle cost modeling rather than upfront unit pricing alone.
Product Type:
Material composition dictates thermal processing requirements and end-of-life recovery value.
- Metallic:Quenched-and-tempered steel grades from 400 to 700 BHN dominate volume through established welding protocols and scrap-value recovery. Australian iron ore processors specify these for primary crusher feed chutes where field repairability outweighs absolute hardness.
- Composite:Ceramic-metal hybrid architectures fuse tungsten carbide particulates into ductile substrates via plasma-transferred arc welding. Brazilian mining operators validate these against pure steel baselines in silica-rich streams demanding 3x service-life extension.
- Polymeric:UHMWPE and polyurethane formulations serve low-abrasion secondary processing where impact absorption matters more than hardness.
- Ceramic:Monolithic alumina and silicon carbide plates occupy niche high-temperature applications in cement kiln feed systems.
Mature deployment sits with Metallic grades. Newer deployment is concentrated in Composite architectures.
End User:
Operational intensity and feedstock abrasiveness shape specification tiers across verticals.
- Mining:Iron ore and coal operators drive premium composite adoption in primary material handling. Procurement concentrates in Australian and Brazilian corridors where silica content accelerates wear rates.
- Construction:Cement plants along China's Yangtze River belt execute bulk replacement cycles under tightening GB standards protocols.
- Agriculture:Grain handling and soil-engaging equipment specify lower-hardness metallic grades with corrosion-resistant coatings.
- Manufacturing:German automotive tool-and-die customers demand pre-fabricated bolt-on formats to eliminate field welding hours.
Volume concentration rests with Mining. Steepest specification upgrading is occurring in Construction.
Installation Type:
Format selection trades logistics efficiency against dimensional tolerance accommodation.
- Pre-Fabricated:Bolt-on liner systems command margin premiums by compressing site installation schedules. German automotive customers specify these for new equipment builds with tight production ramp timelines.
- On-Site:Weld-on formats remain default for aging infrastructure where original drawings have degraded, demanding certified alloy welders increasingly scarce in Australian and South African mining regions.
- Custom Fit:Dimensional survey and plasma-cutting services address retrofits with tolerance degradation exceeding standard liner geometries.
- Standard Fit:Catalog dimensions serve OEM original equipment builds with controlled tolerances and predictable replacement cycles.
Margin capture favors Pre-Fabricated. Project delay risk concentrates in Custom Fit.
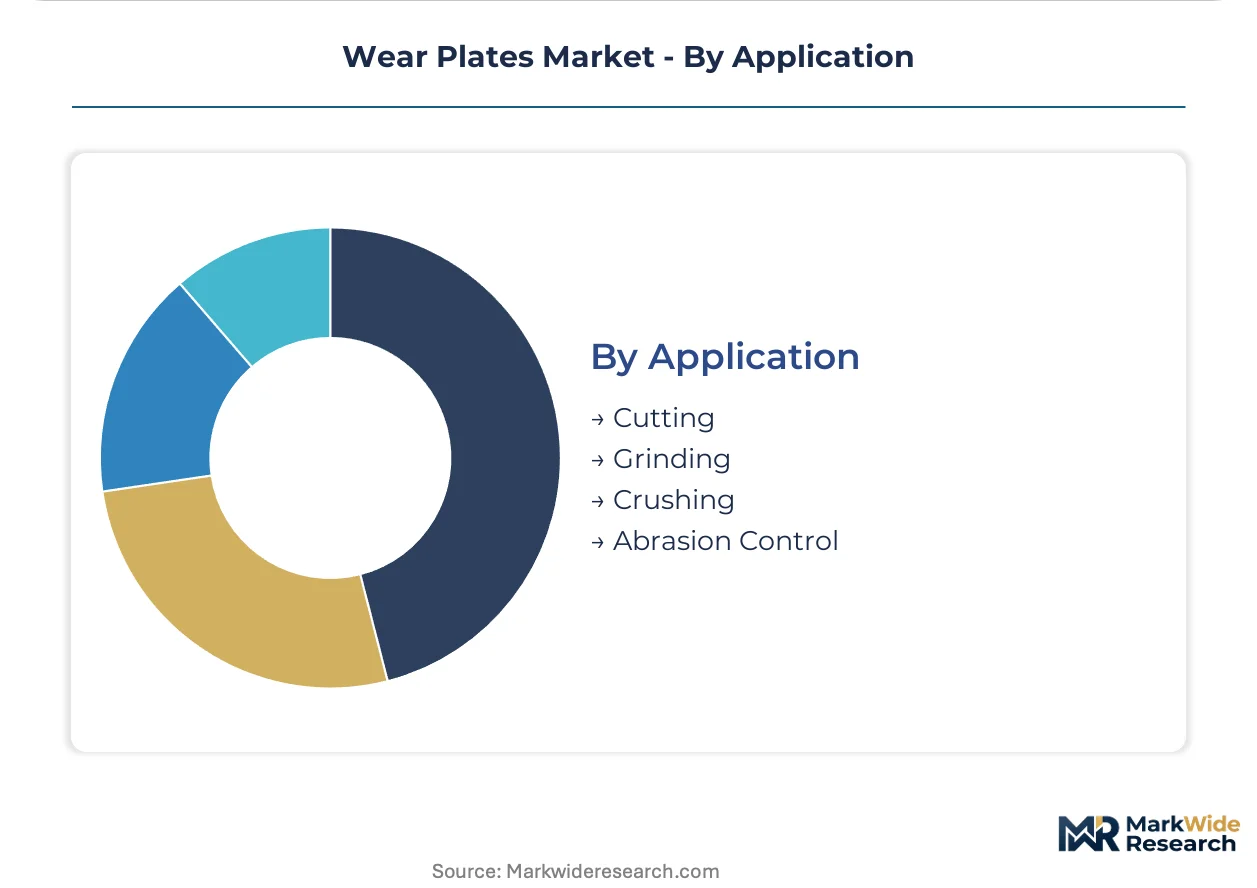
Application:
Mechanical stress modes determine hardness-ductility balancing in specification.
- Abrasion Control:Chute and hopper linings in silica-rich feed streams specify 600+ BHN metallic grades or ceramic overlays. Brazilian iron ore processors validate composite architectures here against pure steel baselines.
- Crushing:Jaw and gyratory crusher liners balance hardness against impact resistance, favoring through-hardened steels with controlled carbon equivalent for weldability.
- Grinding:SAG and ball mill shell plates require bolt-on formats with wear monitoring integration for scheduled replacement.
- Cutting:Shear blade and shredder applications specify high-alloy formulations with nickel and chromium content now requiring REACH documentation for European supply.
Specification complexity peaks in Abrasion Control. Fastest material substitution is underway in Crushing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Economic Belt special zones concentrate heavy manufacturing procurement, while Australian mining corridors and German automotive clusters anchor premium specification demand across three continents.
Australia
Iron ore processors in the Pilbara region drive composite wear plate validation against silica-rich baselines. The country's Work Health and Safety Act mandates documented material traceability for mining equipment certification. Perth-based contractors now source mill-direct from Japanese producers to compress project logistics for Indonesian coal expansion projects.
Brazil
Minas Gerais iron ore operators specify ceramic-metal hybrid architectures for primary crusher feed chutes demanding triple service-life extension. ANVISA chemical safety protocols align with REACH disclosure thresholds for hexavalent chromium in welding consumables. São Paulo fabricators consolidate procurement with ECHA-registered suppliers to satisfy European OEM export requirements.
China
Steel mills and cement plants along the Yangtze River execute bulk replacement cycles under tightening GB standards quality protocols. The MIIT dual carbon goals pressure state-owned construction conglomerates to document embodied carbon in cross-border equipment contracts. Shanghai-Ningbo corridor traders now compete against mill-direct channels as procurement unbundles installation from plate supply.
Germany
Automotive tool-and-die customers in Baden-Württemberg demand pre-fabricated bolt-on formats to eliminate field welding hours. The EU Green Deal carbon tracking requirements create qualification barriers for non-European suppliers without EPD certification. Ruhr Valley heat-treatment specialists compress lead times through integrated capacity that captive steelmaking supports.
United States
Quarry operators in the Appalachian mining belt substitute polymer-lined chutes with ceramic overlays for silica applications. OSHA welding fume exposure limits drive certified alloy welder scarcity that extends project timelines for aging infrastructure retrofits. Great Lakes steelmaking clusters face Baltic shipping disruption exposure from Nordic premium plate concentration.
Wear Plates Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated steelmakers commanding premium quenched-and-tempered supply while regional fabricators capture installation-adjacent value. The vendor base concentrates around three strategic archetypes: captive steelmaking specialists with heat-treatment integration, mill-direct logistics operators serving Asian project corridors, and trading intermediaries facing margin compression from certification documentation requirements. Competitive moves center on pre-fabricated format development and REACH-compliant supply chain restructuring.
Among Nordic-integrated producers, SSAB exemplifies the captive steelmaking archetype through Swedish and United States production bases. JFE Steel Corporation anchors the mill-direct logistics tier with Japanese and Southeast Asian delivery protocols. Thyssenkrupp occupies the heat-treatment integration position serving German automotive specification demand.
| Leading Market Players |
|---|
| SSAB |
| JFE Steel Corporation |
| Thyssenkrupp |
| ArcelorMittal |
| Dillinger |
| Nippon Steel Corporation |
| Bisalloy Steel Group |
| Voestalpine |
| NLMK Clabecq |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between REACH-compliant integrated mills and trading intermediaries manifests in 40-60% unit price spreads, with premium quenched-and-tempered capacity commanding captive metallurgical control while commodity traders absorb documentation cost compression. This bifurcation concentrates margin capture among Nordic and Japanese producers with in-house heat-treatment, forcing mid-cap processors into custom fabrication services to escape pure commodity pricing.
Pricing Analysis
Volume-mass metallic grades trade on scrap-value recovery and established welding protocols, while composite ceramic-metal hybrids capture margin premiums through triple service-life validation in Brazilian iron ore corridors. Price differentiation rests on ISO 9001 certification tier and plasma-transferred arc welding capability, with German automotive tool-and-die buyers least sensitive due to production ramp timeline pressures. Cost compression in standard metallic grades intensifies as Chinese state-owned construction conglomerates unbundle installation from plate supply, pitting domestic traders against mill-direct channels.
Supply Chain Analysis
Dual-sourcing mandates from Australian Pilbara operators and German automotive OEMs require qualification across Swedish, Japanese, and Finnish mill bases to mitigate Baltic shipping disruption exposure. Raw material flows draw from chromium and nickel specialty scrap streams, tungsten carbide particulate suppliers, and ductile steel substrate producers. Single-source vulnerability concentrates in premium quenched-and-tempered capacity clustering around SSAB's Swedish and United States production bases. Distribution runs through mill-direct logistics for Southeast Asian mining contractors and regional fabricator networks for aging infrastructure retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Premium quenched-and-tempered capacity scarcity props pricing power for integrated producers, with heat-treatment bottleneck intensity accelerating as composite adoption forces recalibration across certification networks.
For Market Incumbents: Deepen captive metallurgical control through Swedish and Finnish heat-treatment capacity expansion to defend against ceramic-metal hybrid substitution threatening conventional steel baselines. Prioritize EPD certification investment to capture EU Green Deal embodied-carbon tracking requirements that disqualify non-European suppliers from cross-border mining equipment contracts. For New Entrants and Emerging Players: Launch via pre-fabricated bolt-on liner systems targeting German automotive tool-and-die customers desperate to eliminate field welding hours from scarce certified alloy welder pools. Penetrate Indonesian and Vietnamese coal expansion corridors through mill-direct logistics partnerships with Japanese producers already anchoring Asian project channels. For Investors and Strategic Acquirers: Re-rating potential sits with heat-treatment-integrated mid-cap specialists given EU carbon tracking mandates and REACH documentation barriers favoring integrated mills over trading intermediaries. Long-term viability across the analysis window hinges on plasma-transferred arc welding capability and ECHA-registered chemical safety dossiers. Monitor Brazilian iron ore processor validation rates for composite architectures against pure steel baselines as inflection indicator for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Treatment Capacity Expansion | Swedish and Finnish integrated mills compress lead times for German automotive specification demand. |
| EPD Certification Investment | European producers secure qualification for EU Green Deal cross-border mining equipment contracts. |
| Plasma-Transferred Arc Welding Scale-Up | Brazilian iron ore processors validate tungsten carbide overlay deposition for triple service-life extension. |
| Pre-Fabricated Bolt-On Format Development | German tool-and-die customers eliminate field welding hours from aging certified welder pools. |
| Mill-Direct Logistics Partnership | Japanese producers anchor Indonesian and Vietnamese coal expansion project channels. |
Research Methodology
Document review covered ASTM International hardness testing protocols, ISO 9001 certification databases, and REACH substance-of-very-high-concern listings, complemented by interviews with mining maintenance directors, cement plant procurement leads, automotive tool-and-die engineers, and steel mill technical R&D directors. Secondary validation drew from customs trade data, SEC filings of listed steel producers, and ECHA chemical safety dossiers. Bottom-up equipment lifecycle modeling and top-down regional demand aggregation provided cross-reference triangulation.
Historical shipment volumes were cross-referenced against panel input from plant engineers and OEM procurement teams across the projection horizon. Segmentation modeling captured material composition tiers, installation format categories, and end-use vertical intensity levels. CAGRs were derived from replacement cycle timing, specification upgrade trajectories, and regional infrastructure investment pipelines. Nickel and chromium price volatility indices, welding technician demographic data, and GB standards evolution timelines informed scenario boundaries.
Alloy input price swings, Baltic shipping disruption frequency, and certification timeline compression are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding composite validation rates in silica-rich feed streams and European carbon tracking enforcement intensity. A model refresh is warranted upon material change in Brazilian or Australian mining operator procurement specifications for ceramic-metal hybrid architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Hooklifts Market
Material Handling Equipment
Electric Stacker Market
Material Handling Equipment
Roll Slitting Machines Market
Material Handling Equipment
Bale Clamp Intensive Market
Material Handling Equipment
Global Industrial Lifting Equipment Market
Material Handling Equipment
Latin America Conveyors Market
Material Handling Equipment
Fork Lift Attachments Market
Material Handling Equipment
Port Material Handling Equipment Vehicle Market
Material Handling Equipment
Canada Forklift Market
Material Handling Equipment
Pneumatic Conveying Systems Market
Material Handling Equipment
Asia-Pacific Forklift Truck Market
Material Handling Equipment
Clinching Machines Market
Material Handling Equipment
Forklift Truck Market
Material Handling Equipment
Conveyors and Belt Loaders Market
Material Handling Equipment
Truck Loader Crane Market
Material Handling Equipment
Decoiler Machine Market