
 Steel Structure Anchor Bolt Market | 2026-2036
Steel Structure Anchor Bolt Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Structure Anchor Bolt Market Insights
The gap between premium-grade seismic-rated anchor bolts and commodity threaded rods is broadening as infrastructure specifications tighten across major economies. Hilti Group leverages its captive testing infrastructure to certify performance under cyclic loading conditions for bridge applications. Simpson Strong-Tie anchors its portfolio in North American residential and light commercial construction through proprietary wedge anchor designs. Würth Group competes through dense distribution networks that supply construction firms with same-day availability of headed anchor bolts.
Steel structure anchor bolts are mechanical fasteners designed to secure structural steel columns, frames, and equipment to concrete foundations, typically manufactured from carbon or alloy steel with specified minimum yield strengths and thread profiles per engineering standards. Hot dip galvanization dominates the technology segment for outdoor and corrosive environments due to superior coating thickness and sacrificial protection, while powder coating gains share in sports complexes where aesthetic finish requirements intersect with durability needs. Cast-in anchor bolts retain primacy in heavy industrial plants where precise embedment depth and load transfer govern foundation design, though machine anchor bolts expand in retrofit bridge construction where drilling into existing concrete limits traditional placement options.
OSHA fall-protection standards and AISC seismic provisions in the United States shape product certification requirements for structural steel connections, while China's GB 50011 code for building seismic resistance mandates anchor bolt performance testing that foreign suppliers must navigate for market access. India's BIS certification for steel fasteners creates compliance thresholds that filter import competition. Stakeholders must monitor evolving national building codes that increasingly specify performance-based anchor bolt testing over prescriptive material grades.
Market Dynamics
Seismic code convergence across multiple jurisdictions is forcing anchor bolt manufacturers to maintain parallel certification streams, elevating fixed compliance costs while compressing product development cycles for infrastructure-grade fastening systems.
Growth Catalysts
- India's industrial corridor buildout:Transmission tower foundations across Gujarat and Maharashtra specify hot dip galvanized anchor bolts, creating sustained procurement volume from state electricity boards.
- GB 50011 seismic provisions:China's tightened material certification requirements for seismic-resistant steel structures filter import competition and elevate domestic testing infrastructure investment.
- Bridge retrofit mandates:Machine anchor bolt adoption accelerates in Southeast Asian bridge construction where drilling into existing concrete foundations displaces cast-in placement methods.
Market Restraints
- Alloy steel price volatility:Chromium and molybdenum input cost swings compress margin predictability for forged high-strength anchor bolt producers.
- Testing infrastructure concentration:Cyclic load certification capacity clusters in Germany, Japan, and the United States, creating geographic bottlenecks for suppliers seeking seismic-rated product validation.
- Wedge anchor substitution:Mechanical expansion anchors capture light commercial applications where load requirements fall below structural steel thresholds.
Strategic Opportunities
- Vietnam infrastructure pipeline:North-South Expressway phases and port expansion projects specify corrosion-resistant fastening systems for marine exposure conditions.
- Powder coating aesthetic convergence:Sports complex developers specify color-matched anchor bolt finishes that satisfy durability and visual integration requirements.
- Direct contractor distribution:Construction firms in India's private industrial sector bypass traditional distributor tiers through project-specific procurement platforms.
Industry Challenges
- Multijurisdictional certification timelines:Parallel OSHA fall-protection validation, AISC seismic provisions compliance, and BIS marking create 18-24 month product launch cycles.
- Embedment precision engineering:Heavy industrial plant foundations demand millimeter-accurate cast-in placement coordination between structural engineers and concrete contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Structure Anchor Bolt Market |
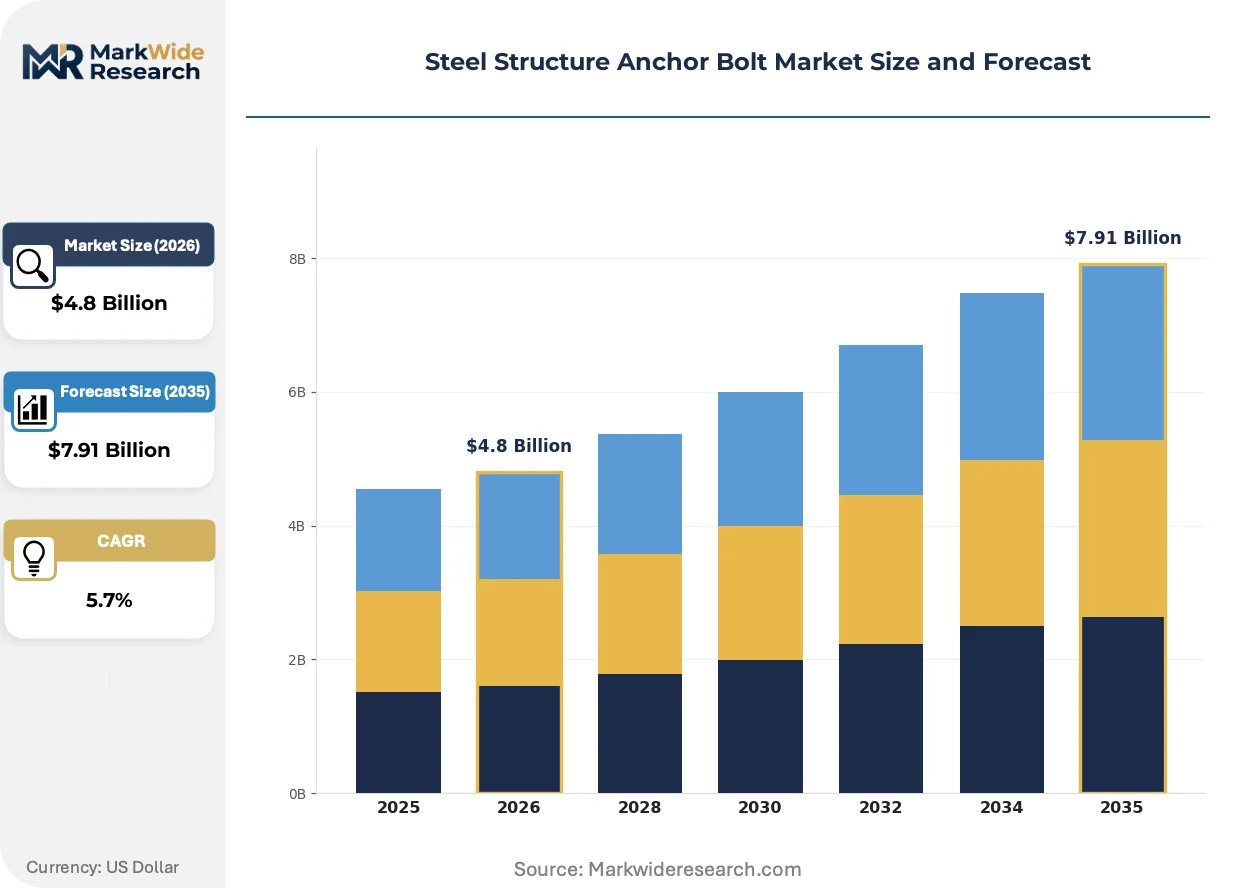
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast-in Anchor Bolts, Machine Anchor Bolts, Headed Anchor Bolts, Threaded Rods Technology: Hot Dip Galvanization, Electroplating, Mechanical Coating, Powder Coating Application: Bridge Construction, Transmission Towers, Industrial Plants, Sports Complexes End User: Construction Firms, Heavy Equipment Manufacturers, Infrastructure Developers, Engineering Consultants |
| Companies Covered | Hilti Group, Stanley Black & Decker, Illinois Tool Works, Würth Group, Simpson Strong-Tie, Fischer Group, SFS Group, Fastenal, Bossard Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Structure Anchor Bolt Market Trends and Innovations
Digital thread integration from finite element analysis through field installation is compressing design-validation loops while elevating performance accountability across structural fastening supply chains.
Automated ultrasonic testing equipment is automating quality assurance for hot dip galvanized coating thickness verification. Bridge contractors in Thailand and Indonesia deploy these systems to accelerate foundation acceptance protocols. The technology is automating inspection documentation that previously required manual caliper measurement and photographic logging.
REACH substance restrictions on hexavalent chromium conversion coatings are forcing European anchor bolt suppliers to shift toward trivalent chromium and zinc-nickel alternatives. Surface treatment lines require capital reconfiguration to maintain CE marking compliance. Manufacturers serving German automotive plant construction report 12-18 month formulation validation cycles for replacement coatings.
Specification-driven procurement consolidation is compressing supplier rosters for industrial developers. India's National High Speed Rail Corporation maintains approved vendor lists for seismic-rated anchor bolts, requiring pre-qualification testing that smaller forging operations cannot finance. Tier-one contractors leverage these pre-approvals to streamline project bidding and reduce foundation subcontractor qualification overhead.
Steel Structure Anchor Bolt Market Segmentation
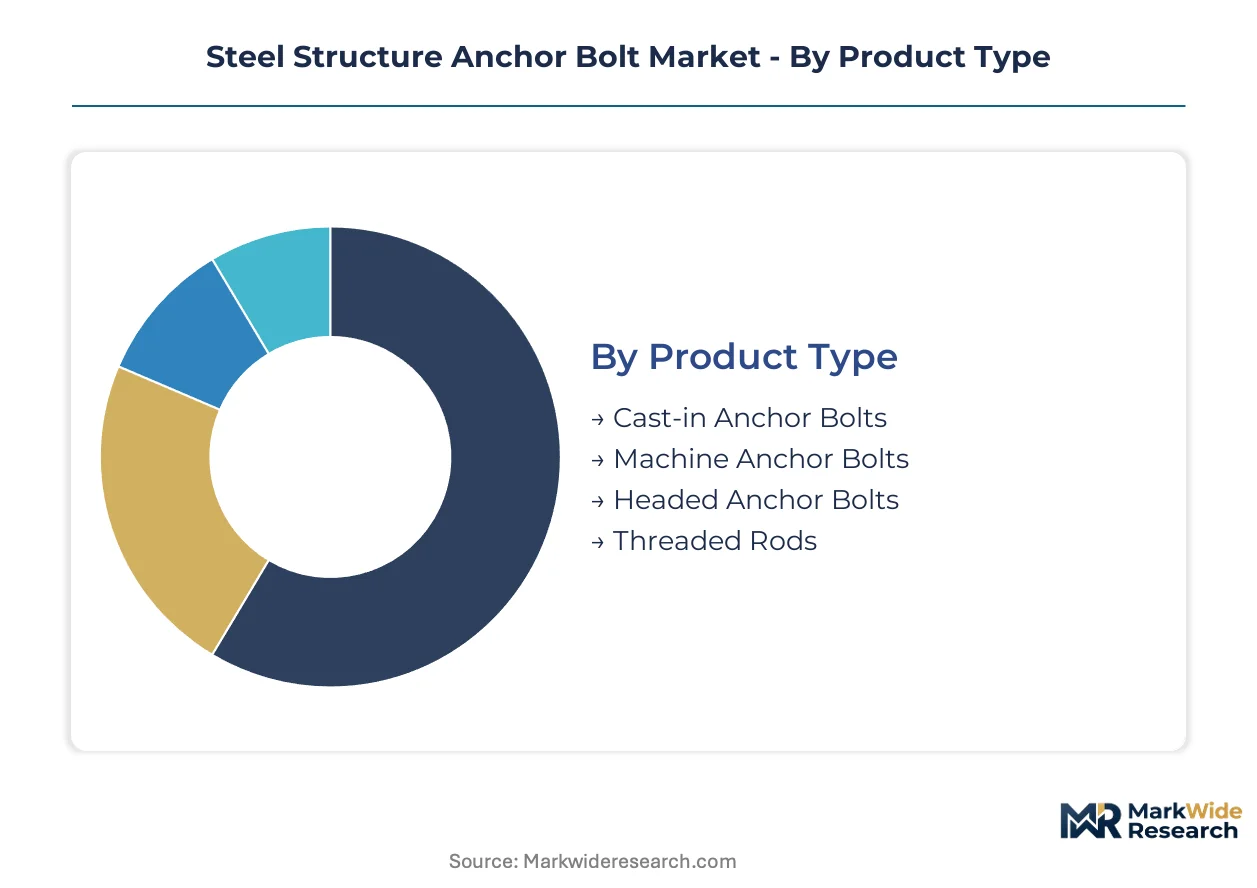
Steel structure anchor bolt procurement splits along engineering specifications, environmental exposure requirements, and project delivery methods. Specification engineers select segments based on load transfer mechanisms, corrosion protection needs, and installation sequencing constraints.
Product Type:
Capital intensity varies sharply across forging and machining requirements, with cast-in anchor bolts demanding the heaviest upfront tooling investment for embedment precision.
- Cast-in Anchor Bolts:These fasteners integrate directly into wet concrete pours with specified embedment depths and plate washers for load distribution. Heavy industrial plants in India's Gujarat corridor specify these for turbine foundations where millimeter-accurate placement governs structural integrity.
- Machine Anchor Bolts:Post-installed systems drill into cured concrete with expansion or adhesive anchoring mechanisms. Bridge retrofit contractors across Thailand and Indonesia deploy these where cast-in placement is impossible.
- Headed Anchor Bolts:Forged heads provide bearing surfaces for column base plates without nut assemblies. Infrastructure developers specify these for transmission tower foundations requiring simplified field installation.
- Threaded Rods:Continuous-thread carbon steel rods offer commodity fastening for light commercial applications with lower load requirements.
Cast-in anchor bolts absorb the bulk of installed capacity in heavy industrial foundations; machine anchor bolts are expanding most quickly in bridge retrofit applications.
Technology:
Surface treatment selection tracks environmental exposure severity, with marine and industrial atmospheres driving specification toward thicker sacrificial coatings.
- Hot Dip Galvanization:Immersion in molten zinc delivers coating thicknesses exceeding mechanical alternatives. Transmission tower foundations across Maharashtra and Gujarat mandate this specification for decades-long corrosion protection in monsoon-exposed conditions.
- Electroplating:Thin zinc deposits suit indoor applications with controlled atmospheres and aesthetic requirements.
- Mechanical Coating:Impact-applied zinc layers bridge the thickness gap between electroplating and hot dip processes for mid-range corrosion protection.
- Powder Coating:Thermoset polymer finishes address sports complex specifications where color matching and visual integration matter alongside durability.
Hot dip galvanization commands the largest share of outdoor infrastructure procurement; powder coating is climbing the fastest as sports facility investment accelerates.
Application:
Project scale and engineering complexity determine specification tier, with bridge and industrial applications demanding certified seismic performance.
- Bridge Construction:Cyclic load resistance and fatigue performance govern anchor bolt selection for structural steel connections. Southeast Asian expressway projects specify corrosion-resistant systems for marine exposure conditions spanning foundation piers to expansion joints.
- Transmission Towers:High-tensile specifications with hot dip galvanization dominate state electricity board procurement across India's industrial corridors.
- Industrial Plants:Precision-embedded cast-in systems anchor heavy machinery and process equipment to foundations.
- Sports Complexes:Aesthetic finish requirements intersect with structural performance for stadium and arena construction.
Bridge construction anchors the highest-value procurement segment; sports complexes are gaining share fastest as entertainment infrastructure investment rises.
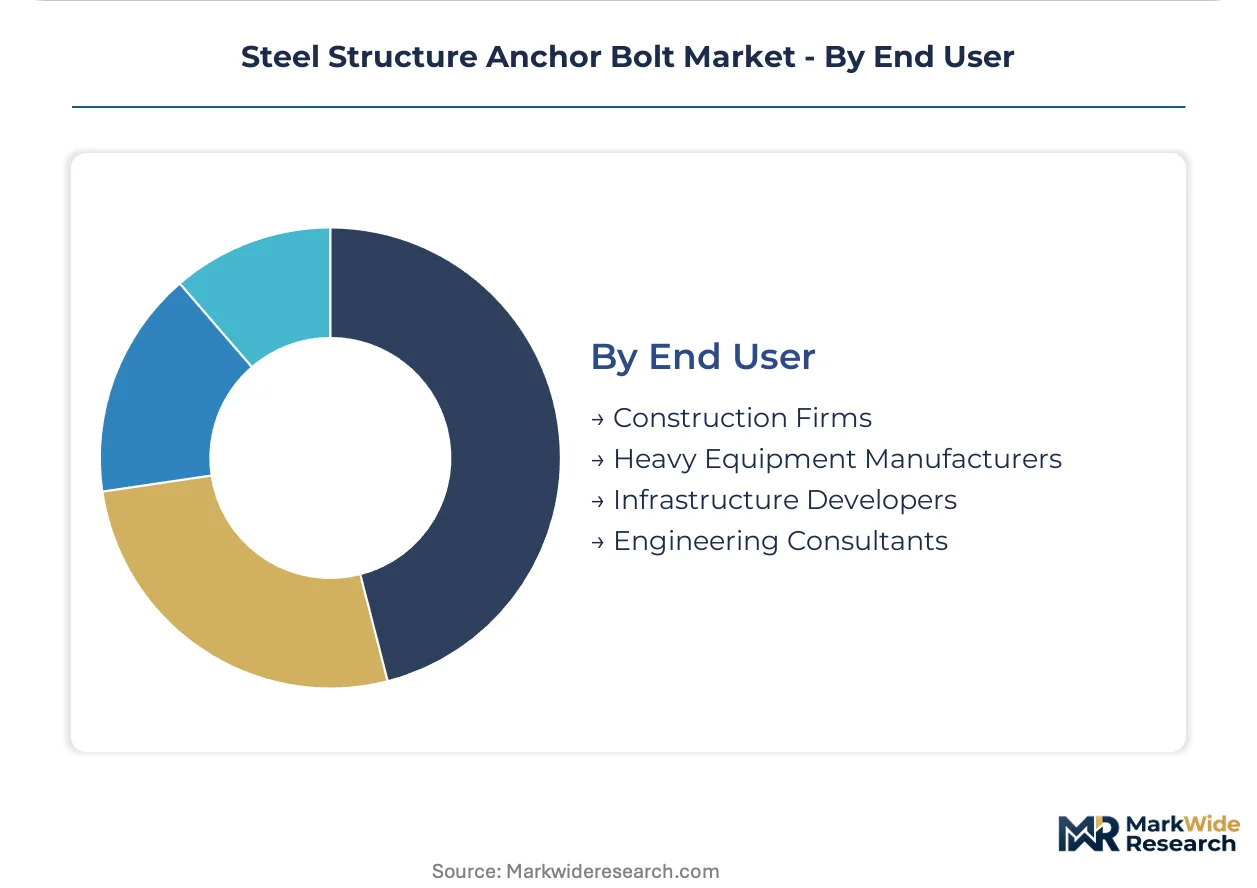
End User:
Procurement authority and technical specification capability vary across the construction value chain, filtering supplier access.
- Construction Firms:General contractors and steel erectors source anchor bolts through project-specific procurement platforms, increasingly bypassing distributor tiers for direct mill relationships.
- Heavy Equipment Manufacturers:Original equipment suppliers specify anchor systems for machinery installation, integrating fastening into equipment delivery packages.
- Infrastructure Developers:State-owned enterprises and private developers maintain approved vendor lists with pre-qualification testing requirements that filter supplier participation.
- Engineering Consultants:Design firms specify anchor bolt performance criteria in construction documents, influencing procurement without direct purchasing authority.
Infrastructure developers concentrate the largest procurement volumes; construction firms are expanding direct sourcing fastest through digital procurement platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mumbai-Pune industrial corridor anchors anchor bolt procurement volume as transmission tower foundations and heavy manufacturing plants drive specification demand across India's western seaboard.
China
Seismic-resistant steel construction in Chengdu and Xi'an accelerates demand for GB 50011-certified anchor systems. The Ministry of Housing and Urban-Rural Development tightened material testing protocols for high-rise structural connections in seismic zones. Yangtze River Delta fabricators invest in captive cyclic load testing infrastructure to satisfy domestic certification requirements.
United States
Bridge retrofit programs across California and Texas specify corrosion-resistant machine anchor bolts for seismic upgrades. OSHA fall-protection standards and AISC seismic provisions govern structural steel connection certification. Gulf Coast petrochemical expansions in Houston and Corpus Christi drive hot dip galvanized procurement for marine atmospheric exposure.
India
State electricity boards in Gujarat and Maharashtra specify hot dip galvanized anchor bolts for transmission tower foundations across the Delhi-Mumbai Industrial Corridor. BIS certification requirements for steel fasteners filter import competition and elevate domestic testing investment. Surat and Vadodara forging clusters expand capacity to serve National High Speed Rail Corporation vendor list pre-qualification.
Germany
Automotive plant construction in Bavaria and Baden-Württemberg drives specification of REACH-compliant surface treatments as hexavalent chromium conversion coatings phase out. ECHA substance restrictions force coating line reconfiguration for CE marking maintenance. Stuttgart and Munich engineering consultancies specify performance-based anchor testing over prescriptive material grades.
Vietnam
North-South Expressway phases and Hai Phong port expansion specify corrosion-resistant fastening systems for marine exposure conditions. Ministry of Transport infrastructure tenders prioritize suppliers with seismic-rated product validation. Ho Chi Minh City construction firms accelerate direct procurement platform adoption to bypass traditional distributor tiers.
Steel Structure Anchor Bolt Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification infrastructure and testing capability. The market structures around three tiers: multinational fastening systems houses with captive seismic testing labs, regional forging specialists serving approved vendor lists, and commodity threaded rod distributors competing on logistics density. Consolidation pressure concentrates among mid-scale European and Asian fabricators seeking AISC and GB standard parallel certification. Strategic moves center on testing infrastructure acquisition and direct contractor distribution platform deployment.
Among Swiss- and Liechtenstein-based fastening systems houses, Hilti Group and Fischer Group occupy positions emphasizing captive testing infrastructure for cyclic load certification. Würth Group anchors the German distribution-centric archetype with dense logistics networks supplying same-day headed anchor bolt availability. Simpson Strong-Tie exemplifies the North American residential-commercial specialist model through proprietary mechanical anchor design positioning.
| Leading Market Players |
|---|
| Hilti Group |
| Stanley Black & Decker |
| Illinois Tool Works |
| Würth Group |
| Simpson Strong-Tie |
| Fischer Group |
| SFS Group |
| Fastenal |
| Bossard Group |
| Others |
Pricing and Supply Chain Analysis
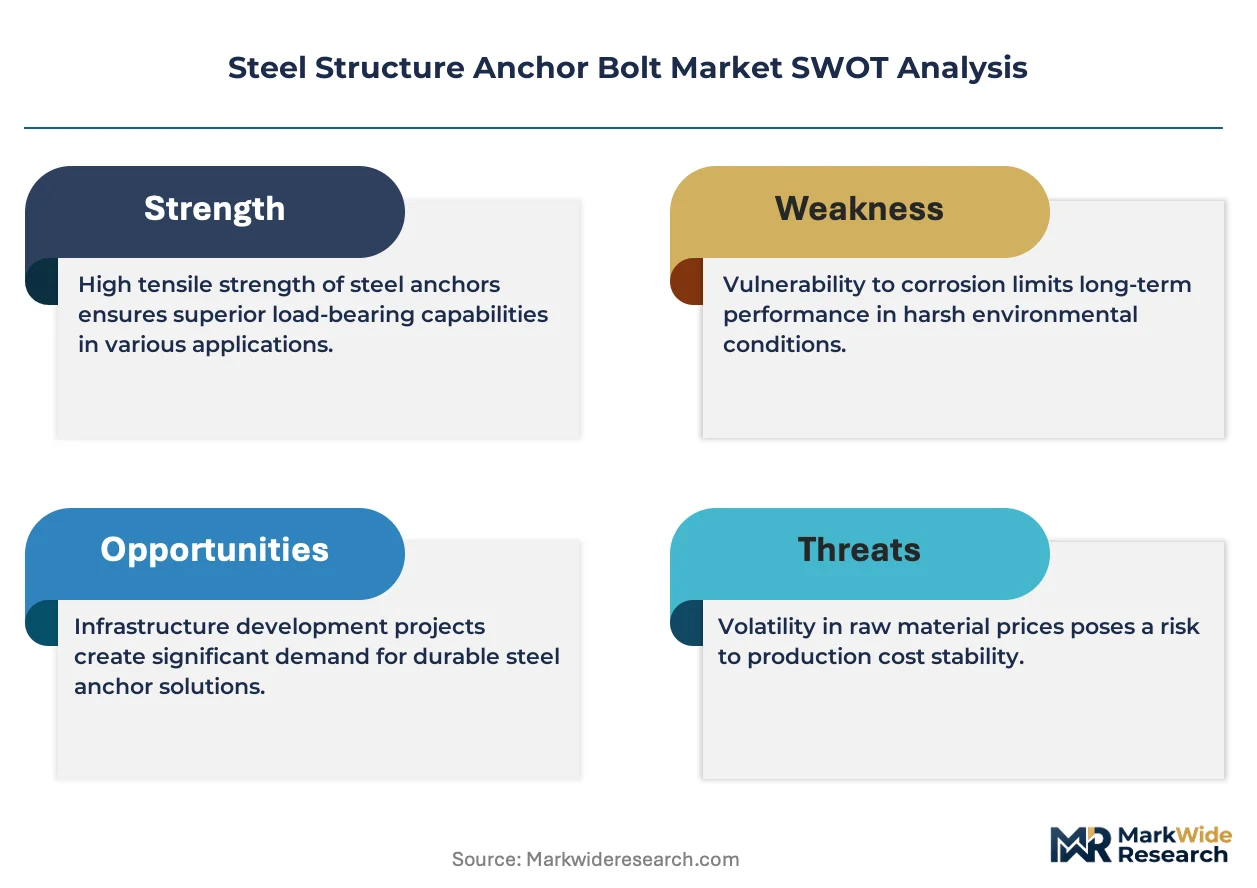
India's BIS certification mandate for steel fasteners filters import competition and elevates domestic testing infrastructure investment, forcing suppliers to absorb fixed compliance costs that compress margin flexibility across forged high-strength anchor bolt tiers.
Pricing Analysis
Certified seismic performance anchors value-based pricing across bridge and industrial applications, with cyclic load validation creating measurable differentiation from commodity threaded rods. Pricing stratifies across seismic-rated, corrosion-protected, and standard specification tiers, with hot dip galvanization and powder coating commanding premiums based on environmental exposure severity. Cost compression in alloy steel inputs intensifies margin pressure for forged high-strength producers exposed to chromium and molybdenum volatility. State electricity boards and infrastructure developers exhibit lowest price sensitivity, while light commercial contractors sourcing through distributor networks face highest sensitivity to per-unit transactional pricing.
Supply Chain Analysis
Scrap steel recovery and coating reprocessing flows remain underdeveloped in anchor bolt manufacturing, though European REACH compliance is forcing surface treatment line reconfiguration toward trivalent chromium alternatives. Production concentrates in China, India, and Germany, with Surat and Vadodara forging clusters expanding capacity to serve domestic certification requirements. Supply chains draw from alloy steel bar stock, zinc ingots for galvanization, and polymer powders for aesthetic finishes. Single-source vulnerability clusters in cyclic load testing infrastructure, with certification capacity concentrated in Germany, Japan, and the United States. Distribution runs through approved vendor lists maintained by infrastructure developers and direct procurement platforms serving construction firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story, with China's GB 50011 seismic provisions and India's BIS certification creating barrier-to-entry moats that reward pre-qualified domestic suppliers and captive testing infrastructure owners.
For Market Incumbents: Lock in approved vendor list positions with India's National High Speed Rail Corporation and state electricity boards through accelerated pre-qualification testing investment. Defend against machine anchor bolt substitution in bridge retrofit applications by embedding certified cast-in systems in heavy industrial plant specifications. Prioritize captive cyclic load testing infrastructure in Yangtze River Delta or western India to compress multijurisdictional certification timelines. For New Entrants and Emerging Players: The price-point gap between premium seismic-rated anchor bolts and commodity threaded rods creates white-space opportunity in mid-tier corrosion-protected specifications for Vietnam's North-South Expressway phases. Target sports complex powder coating applications where aesthetic finish requirements intersect with durability specifications and incumbent penetration remains limited. Pursue direct contractor distribution platform partnerships in Ho Chi Minh City and Surat to bypass traditional distributor markups. For Investors and Strategic Acquirers: The window for entry favors regional forging specialists with latent GB 50011 or AISC seismic certification capability and established relationships with state-owned infrastructure developers. Long-term viability hinges on consolidation of mid-scale European and Asian fabricators seeking parallel certification across multiple jurisdictions. Monitor ECHA substance restriction enforcement and BIS certification timeline acceleration as inflection indicators for coating technology substitution and import competition filtering.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclic Load Testing Infrastructure Acquisition | Captive certification capacity in Chengdu or Xi'an satisfies GB 50011 mandates and compresses product launch cycles. |
| Direct Contractor Distribution Platform Deployment | Digital procurement integration with Mumbai-Pune industrial corridor construction firms bypasses traditional distributor tiers. |
| REACH-Compliant Surface Treatment Line Reconfiguration | Trivalent chromium and zinc-nickel alternatives maintain CE marking access as hexavalent chromium phases out. |
| Approved Vendor List Pre-Qualification Investment | Pre-approval with India's National High Speed Rail Corporation secures transmission tower foundation procurement volume. |
| Backward Integration into Alloy Steel Forging | In-house production of high-tensile bar stock mitigates chromium and molybdenum input cost volatility exposure. |
Research Methodology
Multi-period observation of BIS certification timeline acceleration, GB 50011 enforcement patterns, and approved vendor list expansion anchored the trend analysis, supplemented by interviews with foundation subcontractor procurement managers, structural engineering consultants specifying anchor bolt performance criteria, hot dip galvanization plant operators, and state electricity board technical evaluators. Secondary validation drew from customs trade data for steel fastener imports, Ministry of Housing and Urban-Rural Development regulatory filings, ECHA substance restriction updates, and AISC seismic provision documentation. Bottom-up project pipeline assessment across India's industrial corridors and Vietnam's expressway phases was triangulated against top-down market sizing.
Segment-weighting across product type, surface treatment technology, application, and end user governed the analytical framework across the analysis window. CAGRs were derived from installed capacity expansion in Surat and Vadodara forging clusters, bridge retrofit procurement volumes in Thailand and Indonesia, and sports complex investment pipelines. Forecast inputs incorporated alloy steel price trajectory assumptions and multijurisdictional certification timeline compression scenarios.
Inputs from foundation subcontractor procurement managers and state electricity board technical evaluators were available through the study window; gaps in real-time cyclic load testing capacity utilization data introduce uncertainty bands around seismic-rated product volume assumptions. Forecasts reflect documented assumptions regarding BIS certification timeline acceleration and ECHA enforcement consistency. Practitioners should monitor GB 50011 testing protocol amendments and REACH substance restriction expansion for early signals of compliance cost escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
UK Facade Market
Structural Engineering
Structural Steel Market
Structural Engineering
Bridge Bearing Pad Market
Structural Engineering
Civil Engineering Market
Structural Engineering
Global Concrete Restoration Market
Structural Engineering
Cold-Formed Steel Market
Structural Engineering
Europe Structural Health Monitoring Market
Structural Engineering
Structural Lightweight Concrete Market
Structural Engineering
FRP Bridge Market
Structural Engineering
Concrete Slabs Market
Structural Engineering
Metal Structural Insulation Panels Market
Structural Engineering
Bridge Expansion Joint Market
Structural Engineering
Philippines Roofing Market
Structural Engineering
Americas Structural Insulated Panel Market
Structural Engineering
North America Facade Market