
 Asia-Pacific Structural Health Monitoring Market | 2026-2036
Asia-Pacific Structural Health Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Structural Health Monitoring Market Outlook
Bridge authorities and railway operators is collapsing the legacy dominance of building developers as the primary procurement channel for structural health monitoring systems across Asia-Pacific. Campbell Scientific, Inc. leverages its datalogger manufacturing scale to anchor supply contracts for Australian dam surveillance networks. GEOKON competes through specialized geotechnical instrumentation that dominates tunnel and slope stability applications in mountainous Southeast Asian terrain. Nova Ventures Group Corp. differentiates by sustaining deep channel relationships with Japanese prefectural governments responsible for expressway maintenance.
Structural health monitoring encompasses the deployment of sensor networks, data acquisition hardware, and analytical software to detect anomalies in load-bearing infrastructure before catastrophic failure occurs. Fiber optic sensors achieve microstrain resolution through Bragg grating interferometry, enabling continuous assessment of concrete curing stress and steel fatigue in environments with high electromagnetic interference. Wireless sensor networks capture the largest installed base across bridge applications due to elimination of cabling costs in expansive span structures, while IoT-based monitoring represents the fastest-expanding technology category as edge computing architectures reduce latency for real-time alerts. Non-Destructive Testing retains mature margins in periodic inspection regimes but faces displacement by permanently embedded smart sensor arrays.
Japan's Ministry of Land, Infrastructure, Transport and Tourism mandates periodic structural audits under the Building Standard Law, directly expanding demand for automated monitoring substitutes to manual inspection. China's Ministry of Ecology and Environment enforces dual carbon goals that require energy-intensive industries to verify structural integrity of emissions control infrastructure, creating compliance-driven procurement in steel and cement plants. India's Central Electricity Authority stipulates dam safety instrumentation for hydropower facilities exceeding defined height thresholds. Stakeholders must decide whether to build captive data analytics capabilities or partner with platform providers as monitoring data volumes exceed traditional engineering firm processing capacities.
Market Dynamics
The Asia-Pacific Structural Health Monitoring Market is undergoing a fundamental channel shift as bridge authorities and railway operators displace building developers as the dominant procurement force, driven by aging infrastructure portfolios exceeding original design life across Japan, South Korea, and China's Yangtze River Delta megacity cluster.
Growth Catalysts
- Japan's Building Standard Law:Mandated periodic structural audits by the Ministry of Land, Infrastructure, Transport and Tourism are accelerating substitution of manual inspection with automated sensor networks on aging expressways and high-rise portfolios.
- Wireless sensor networks:Elimination of cabling costs in expansive bridge spans is capturing the largest installed base across civil infrastructure applications, with fiber optic Bragg grating systems penetrating electromagnetic interference-heavy industrial environments.
- China's dual carbon enforcement:The Ministry of Ecology and Environment's emissions verification mandates for steel and cement plants are creating compliance-driven procurement for continuous structural integrity monitoring of emissions control infrastructure.
Market Restraints
- Specialized geotechnical instrumentation supply concentration:Dominant suppliers for tunnel and slope stability applications in mountainous Southeast Asian terrain create single-source vulnerability for critical infrastructure projects.
- Data processing capacity constraints:Monitoring data volumes from dense sensor arrays exceed traditional engineering firm analytical capabilities, forcing stakeholders into expensive platform partnerships or captive capability builds.
- Non-Destructive Testing substitution resistance:Mature margins in periodic manual inspection regimes slow displacement by permanently embedded smart sensor arrays despite superior predictive performance.
Strategic Opportunities
- India's Central Electricity Authority dam safety mandates:Instrumentation requirements for hydropower facilities exceeding height thresholds create unmet demand in Himalayan and Western Ghats catchment zones.
- Edge computing convergence with IoT architectures:Latency reduction for real-time structural alerts is opening new service models combining hardware supply with predictive analytics subscriptions.
- Seismic zone IV and V construction:India's Bureau of Indian Standards tightened monitoring mandates for high-rise construction are generating first-mover advantage for integrated vibration and strain assessment platforms.
Industry Challenges
- Interoperability with legacy SCADA systems:Integration complexity delays deployment timelines for brownfield infrastructure upgrades across Australian dam surveillance networks and Japanese prefectural expressway maintenance programs.
- Embedded sensor calibration expertise:Shortage of field engineers capable of fiber optic Bragg grating installation and microstrain resolution validation constrains deployment velocity in high electromagnetic interference environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Structural Health Monitoring Market |
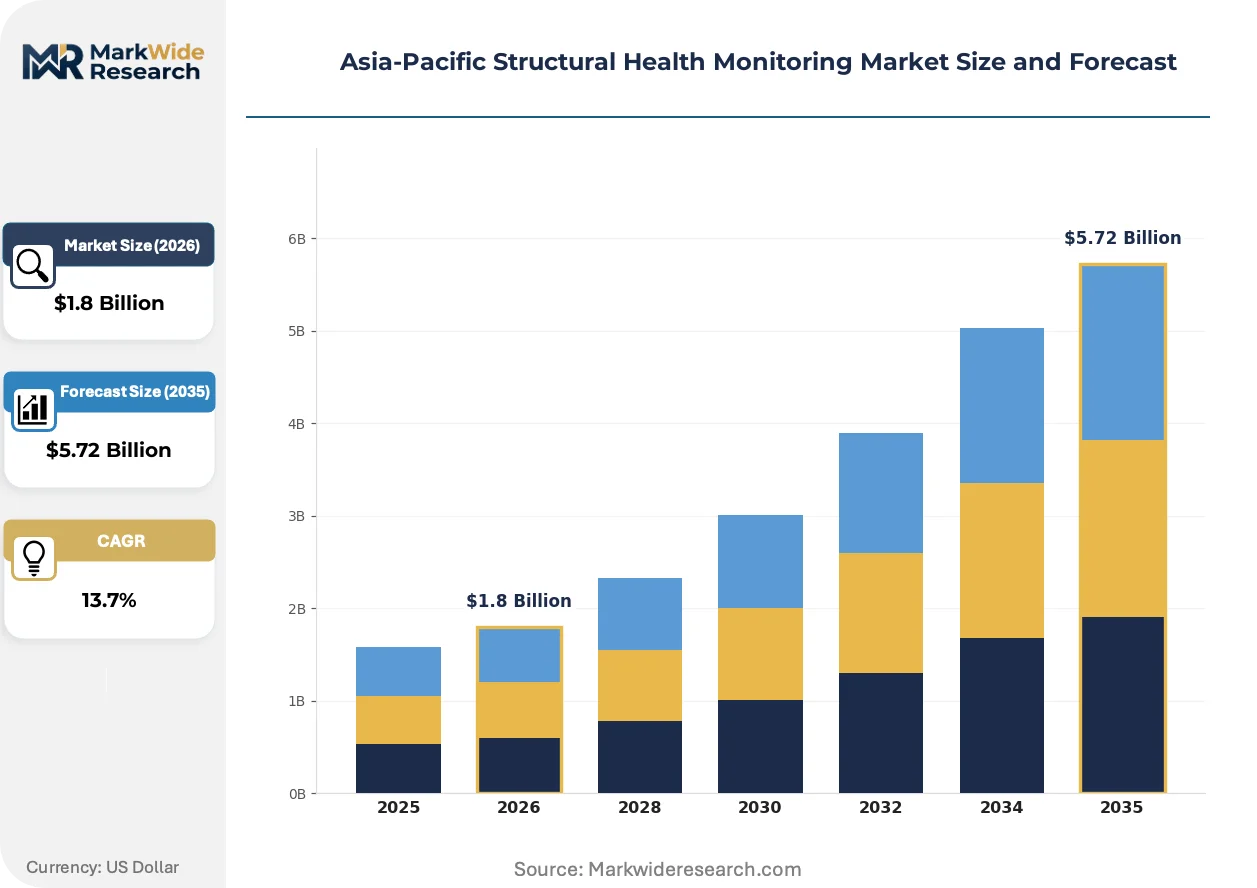
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Sensor Networks, Acoustic Emission Sensors, Fiber Optic Sensors, Temperature Sensors Technology: Non-Destructive Testing, Data Acquisition Systems, IoT-based Monitoring, Smart Sensors End User: Construction, Transportation, Oil & Gas, Energy Sector Application: Bridges, Dams, Buildings, Railways |
| Companies Covered | Acellent Technologies, Inc., Sixense, Nova Ventures Group Corp., Structural Monitoring Systems, Digitexx Data Systems, Inc., Campbell Scientific, Inc., COWI A/S, GEOKON, Geocomp Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Structural Health Monitoring Market Strategic Shifts
Active reshaping of the Asia-Pacific Structural Health Monitoring Market centers on three vectors: decomposition of traditional hardware-software bundles, regulatory acceleration of automated compliance verification, and buyer consolidation around integrated service platforms.
Edge computing architectures are decomposing the legacy separation between data acquisition hardware and centralized analytics platforms. Railway operators across China's high-speed rail viaduct network are deploying latency-optimized processing nodes that enable millisecond-level structural anomaly alerts without cloud dependency. This decomposition is compressing vendor margins on standalone datalogger sales while expanding recurring revenue from embedded software services.
India's Bureau of Indian Standards seismic monitoring mandates for high-rise construction in zones IV and V are forcing design-phase integration of continuous vibration assessment. Developers in Mumbai and Delhi NCR are specifying fiber optic strain monitoring as a condition for structural engineer sign-off. The mandate is most acute in residential towers exceeding 35 stories, where manual inspection intervals cannot capture dynamic load responses.
Japanese prefectural governments are consolidating expressway maintenance procurement through multi-year integrated service contracts. Channel relationships with maintenance divisions are displacing transactional hardware sales as the primary competitive battleground. Kanto and Kansai regional authorities are piloting performance-based contracts where sensor network uptime guarantees determine payment schedules.
Asia-Pacific Structural Health Monitoring Market Segmentation
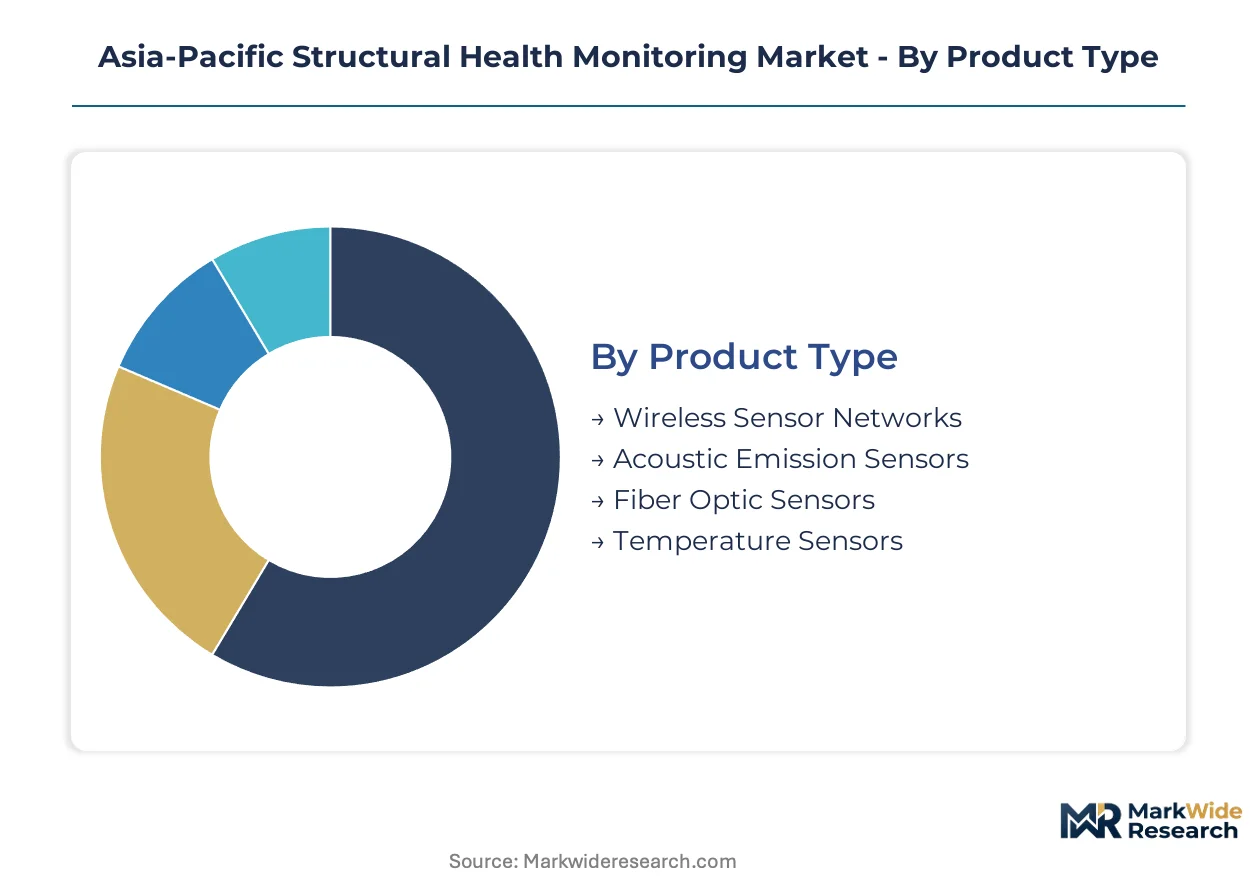
Structural health monitoring procurement flows through distinct channel configurations depending on product complexity and installation permanence. Understanding segment-channel alignment reveals where margin pools concentrate and which technology categories face commoditization pressure from integrated service contracts.
Product Type:
Wireless sensor networks reach bridge authorities through systems integrators, while fiber optic sensors flow directly to industrial end-users requiring electromagnetic immunity.
- Wireless Sensor Networks:Battery-powered mesh architectures eliminate cabling across expansive bridge spans and railway viaducts. Demand concentrates in China's Yangtze River Delta high-speed rail network, where installation cost reduction outweighs battery replacement logistics.
- Fiber Optic Sensors:Bragg grating interferometry achieves microstrain resolution in high electromagnetic interference environments. Steel plants and cement facilities under China's Ministry of Ecology and Environment dual carbon enforcement specify these for emissions control infrastructure monitoring.
- Acoustic Emission Sensors:Piezoelectric transducers detect crack propagation in concrete and steel through stress wave analysis.
- Temperature Sensors:Thermocouple and resistance-based units track thermal expansion effects in dam concrete curing and seasonal bridge deck movement.
By volume, wireless sensor networks lead. By growth pace, fiber optic sensors are expanding most quickly.
Technology:
Technology selection follows inspection regime transformation — periodic manual methods yield to continuous automated systems with diverging margin structures.
- IoT-based Monitoring:Edge computing architectures reduce alert latency through localized processing nodes. Railway operators across Japan's Shinkansen network deploy these for millisecond-level anomaly detection without cloud dependency.
- Smart Sensors:Embedded arrays with onboard diagnostics and self-calibration capabilities displace traditional datalogger-dependent configurations. India's Bureau of Indian Standards seismic mandates for high-rise construction in zones IV and V accelerate specification.
- Non-Destructive Testing:Ultrasonic, radiographic, and magnetic particle inspection methods retain mature margins in regulatory-mandated periodic assessment regimes.
- Data Acquisition Systems:Multi-channel hardware platforms aggregate inputs from heterogeneous sensor types into unified processing streams.
By installed base, non-destructive testing leads. By expansion trajectory, IoT-based monitoring climbs the fastest.
End User:
End-user concentration determines procurement sophistication — public infrastructure authorities consolidate through multi-year service contracts while industrial buyers retain transactional purchasing patterns.
- Transportation:Bridge authorities and railway operators displace building developers as dominant procurement channel. Japanese prefectural governments consolidate expressway maintenance through performance-based contracts where sensor uptime guarantees determine payment schedules.
- Construction:Developers in seismic zones face design-phase monitoring integration requirements. Mumbai and Delhi NCR residential towers exceeding 35 stories specify continuous vibration assessment as structural engineer sign-off condition.
- Energy Sector:Hydropower operators respond to India's Central Electricity Authority dam safety instrumentation mandates for facilities exceeding height thresholds.
- Oil & Gas:Pipeline integrity monitoring and offshore platform structural assessment drive specification of corrosion-resistant sensor housings.
By contract value, transportation leads. By mandate-driven expansion pace, construction is gaining share fastest.
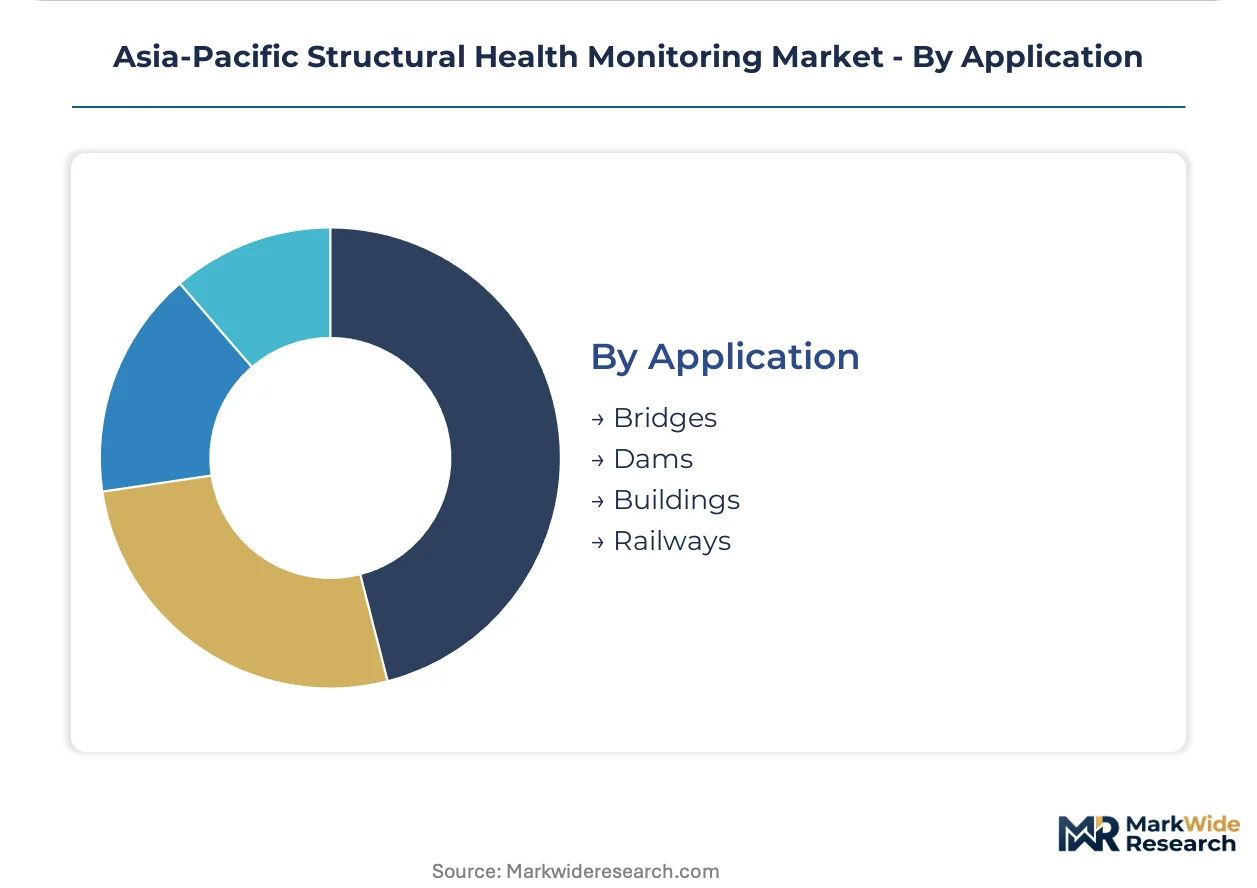
Application:
Application focus shifts with infrastructure age — aging assets exceed original design life and require continuous assessment where periodic inspection once sufficed.
- Bridges:Cable-stayed and suspension structures demand distributed sensing across expansive spans. South Korean and Japanese bridge operators accelerate embedded sensor array procurement as civil infrastructure ages beyond original design specifications.
- Buildings:Super-tall structures in seismic zones require dynamic load response capture. Manual inspection intervals cannot characterize wind-induced oscillation and occupancy-driven vibration patterns.
- Dams:Concrete gravity and embankment structures need seepage monitoring and foundation settlement tracking.
- Railways:High-speed rail viaducts face continuous dynamic loading from train passage frequencies.
By deployment count, bridges lead. By regulatory urgency, buildings show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese sensor manufacturers supply embedded monitoring arrays to South Korean bridge authorities and Australian dam operators, establishing a north-south trade corridor across the Asia-Pacific rim.
China
Steel plants and cement facilities under the Ministry of Ecology and Environment's dual carbon enforcement drive compliance-driven procurement for emissions control infrastructure monitoring. The Yangtze River Delta megacity cluster concentrates demand where high-speed rail viaducts require continuous vibration assessment. Shanghai and Suzhou developers specify fiber optic strain monitoring for super-tall residential towers.
Japan
Aging expressways and high-rise portfolios exceeding original design life accelerate substitution of manual inspection with automated sensor networks. The Ministry of Land, Infrastructure, Transport and Tourism mandates periodic structural audits under the Building Standard Law. Kanto and Kansai prefectural governments consolidate expressway maintenance through multi-year integrated service contracts with uptime guarantees.
India
Hydropower operators respond to Central Electricity Authority dam safety instrumentation mandates for facilities exceeding defined height thresholds. The Bureau of Indian Standards tightened seismic monitoring requirements for high-rise construction in zones IV and V. Mumbai and Delhi NCR residential towers exceeding 35 stories now specify continuous vibration assessment as structural engineer sign-off condition.
South Korea
Bridge operators accelerate procurement of embedded sensor arrays as civil infrastructure ages beyond original design specifications. National highway authorities specify wireless mesh architectures for cable-stayed spans to eliminate cabling costs. The Seoul Capital Area concentrates demand for smart sensor integration in new transportation infrastructure.
Australia
Dam surveillance networks require distributed sensing for concrete gravity and embankment structures across New South Wales and Queensland catchments. Campbell Scientific anchors supply contracts through datalogger manufacturing scale. Interoperability challenges with legacy SCADA systems delay deployment timelines for brownfield infrastructure upgrades.
Asia-Pacific Structural Health Monitoring Market Competitive Environment
Player mix skews toward specialized instrumentation manufacturers with deep channel relationships in public infrastructure procurement. The market exhibits moderate concentration, with dominant positions in geotechnical applications creating single-source vulnerability for tunnel and slope stability projects. Two strategic archetypes define competitive positioning: datalogger-scale manufacturers leveraging manufacturing volume for dam and bridge surveillance contracts, and geotechnical specialists commanding premium positioning in mountainous terrain applications. Capacity expansion and strategic partnerships represent the dominant competitive moves, as vendors build captive data analytics capabilities or align with platform providers to address processing constraints.
Within the instrumentation tier, Campbell Scientific, Inc. and GEOKON occupy positions representing scale-driven and specialization-focused archetypes respectively. Nova Ventures Group Corp. exemplifies the channel-relationship model through sustained engagement with Japanese prefectural governments. These three companies represent the competitive spectrum from manufacturing-scale supply to geotechnical specialization to public-sector channel depth.
| Leading Market Players |
|---|
| Acellent Technologies, Inc. |
| Sixense |
| Nova Ventures Group Corp. |
| Structural Monitoring Systems |
| Digitexx Data Systems, Inc. |
| Campbell Scientific, Inc. |
| COWI A/S |
| GEOKON |
| Geocomp Corporation |
| Others |
Value Chain & Pricing Dynamics
Ninety-day lead times for fiber optic Bragg grating interrogators concentrate pricing power with Japanese and German component suppliers, while bridge authorities in South Korea and Australia absorb inventory carrying costs to secure allocation priority. This supply-chain rigidity translates into project-based contracting premiums for embedded sensor arrays, compressing margins for systems integrators unable to pre-position hardware.
Pricing Analysis
Current-generation IoT edge nodes command 40-60% premiums over prior-generation datalogger-dependent configurations, while next-generation AI-embedded smart sensors remain pre-commercial. Project-based pricing dominates public infrastructure procurement, with fiber optic systems stratifying across premium, standard, and economy tiers based on microstrain resolution certification. Cost compression in wireless sensor mesh hardware stems from Chinese manufacturing scale, though field calibration service bundles retain pricing power. Railway operators in Japan show lowest price sensitivity due to uptime guarantee requirements, while Indian hydropower developers face acute budget constraints under Central Electricity Authority mandates.
Supply Chain Analysis
Strait of Malacca transit vulnerability underwrites inventory pre-positioning strategies for Australian dam surveillance networks. Component sourcing concentrates in Japan for fiber optic interrogators, China for wireless sensor assembly, and Germany for precision geotechnical instrumentation. Raw material dependencies span lithium for battery-powered mesh nodes, rare-earth dopants for fiber Bragg gratings, and corrosion-resistant alloys for embedded housings. Single-source vulnerability persists in specialized geotechnical sensors for mountainous Southeast Asian tunnel projects. Distribution runs through systems integrators for bridge and railway applications, while industrial end-users in steel and cement sectors procure directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
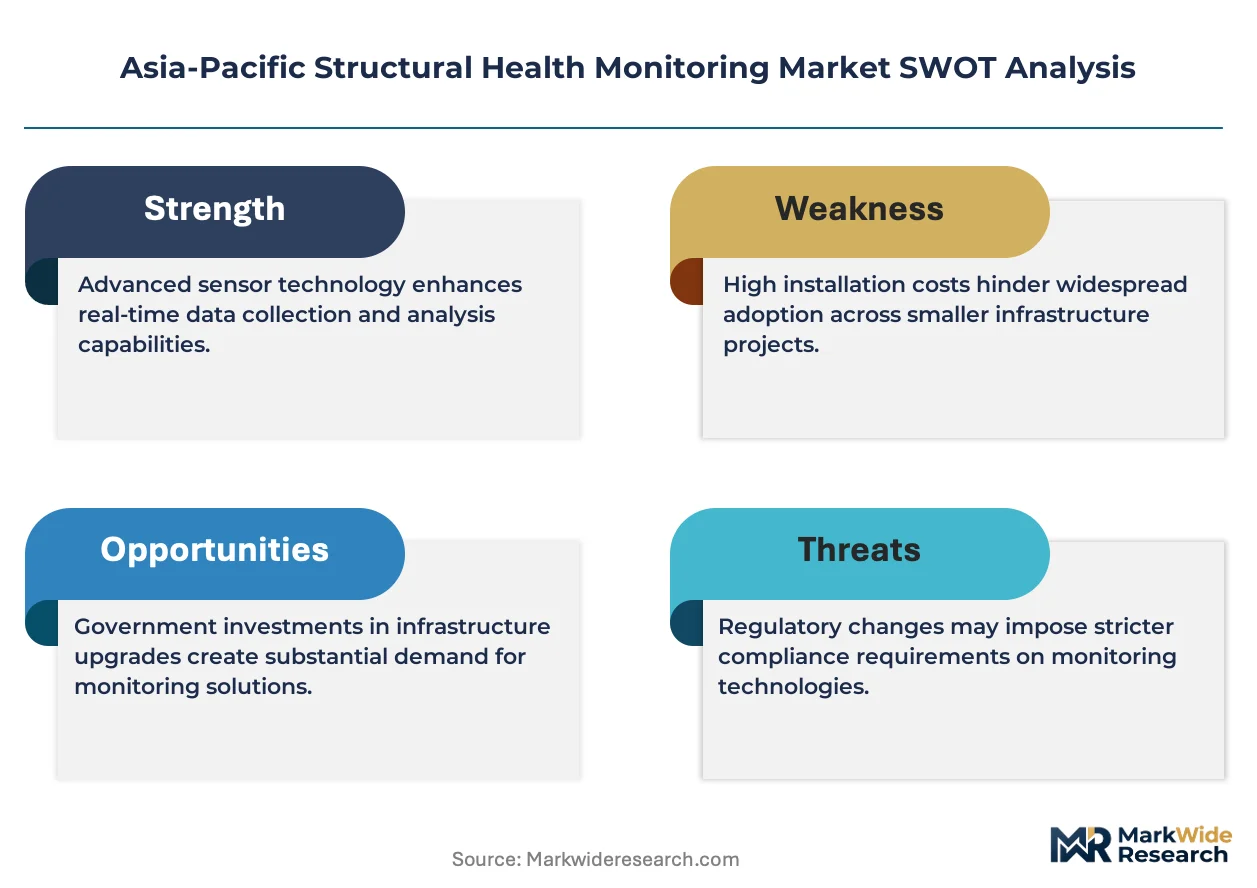
Field engineers capable of fiber optic Bragg grating installation and microstrain validation represent the scarcest capability layer, constraining deployment velocity across high electromagnetic interference environments and creating bottlenecks for project completion timelines.
For Market Incumbents: Shield embedded sensor calibration expertise through captive training academies and certification lock-in with Japanese prefectural maintenance divisions. Capacity addition in India for dam safety instrumentation addresses Central Electricity Authority mandate timing, while backward integration into fiber Bragg grating manufacturing reduces exposure to German component supply volatility. For New Entrants and Emerging Players: Predictive analytics service layers remain under-developed by hardware-centric incumbents, creating white-space for subscription-based anomaly detection platforms targeting South Korean bridge authorities. India's seismic zone IV and V high-rise construction offers the most penetrable entry point, with design-phase specification influence as the critical go-to-market angle through structural engineering consultancies. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because infrastructure age and environmental enforcement tighten monitoring mandates across irreversible time horizons. Acquisition targets should display vertical integration into edge computing software or channel depth with Australian state water authorities. The signal to watch is Japanese prefectural contract consolidation velocity, indicating whether integrated service models achieve sustainable margin capture.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Platform Integration | Reduces alert latency for Japan's Shinkansen operators below millisecond thresholds. |
| Backward Integration into Fiber Bragg Grating Manufacturing | Captures margin pool currently held by German precision optics suppliers. |
| Performance-Based Service Contracting | Aligns payment schedules with uptime guarantees demanded by Kanto regional authorities. |
| Seismic Zone Certification Investment | Unlocks specification priority under India's Bureau of Indian Standards mandates. |
| Joint Venture with Australian State Water Agencies | Secures anchor position for dam surveillance network upgrades across New South Wales. |
Study Parameters
Desk research of customs trade databases, national infrastructure procurement registries, and regulatory filing archives preceded structured interviews with bridge maintenance engineers, railway operations directors, dam safety officers, and geotechnical instrumentation procurement leads. Primary fieldwork across Japan's Kanto and Kansai prefectures, India's Himalayan hydropower catchments, and Australia's eastern seaboard dam networks validated secondary estimates. Bottom-up sensor shipment tracking and top-down infrastructure investment flow analysis enabled triangulation across independent estimation approaches.
Variance decomposition across technology generation, end-user procurement sophistication, and application permanence requirements shaped the analytical framework. Modeled segmentation spans product type complexity, installation regime, and regional regulatory enforcement intensity. CAGRs derived from unit economics trajectories and replacement cycle dynamics, with fiber optic sensor penetration curves and wireless mesh deployment rates serving as industry-specific forecast inputs across the projection horizon.
Underlying assumptions cover regulatory mandate enforcement continuity, component supply chain stability, and infrastructure age distribution profiles, with deviation risk concentrated in India's state-level implementation variance for seismic monitoring and China's dual carbon policy pacing. Practitioners should keep alternative scenarios live as electromagnetic interference environment certification standards and edge computing architecture roadmaps evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Philippines Structural Insulated Panels Market
Structural Engineering
Europe Bridge Bearings Market
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
Europe Structural Health Monitoring Market
Structural Engineering
Self-Levelling Concrete Market
Structural Engineering
Philippines Roofing Market
Structural Engineering
Fluid Viscous Dampers Market
Structural Engineering
India Structural Steel Fabrication Market
Structural Engineering
Prestressed Concrete Market
Structural Engineering
Global Structural Health Monitoring Market
Structural Engineering
Concrete Slabs Market
Structural Engineering
North America Anchors and Grouts Market
Structural Engineering
Global Concrete Restoration Market
Structural Engineering
Steel Structure Anchor Bolt Market
Structural Engineering
High Strength Concrete Market
Structural Engineering
Bridge Expansion Joint Market