
 Asia Pacific Expanded Polyethylene (EPE) Foam Market | 2026-2036
Asia Pacific Expanded Polyethylene (EPE) Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Expanded Polyethylene (EPE) Foam Market Analysis
Automotive component packaging is shifting toward higher-density EPE grades as EV battery shipments expand across Thailand and Vietnam. Supreme Industries Limited leverages its Indian manufacturing footprint to supply tier-1 auto suppliers with customized foam profiles. Sekisui Chemical anchors Japanese demand through precision-calibrated thermal insulation grades for electronics OEMs. Kaneka competes on cross-linked foam formulations that withstand repeated sterilization cycles for medical device clients.
Asia Pacific Expanded Polyethylene (EPE) Foam comprises closed-cell polyethylene beads expanded through physical or chemical blowing agents, typically achieving densities between 20-100 kg/m³ with thermal conductivity near 0.035 W/m·K, serving primarily as impact-dissipating and thermally insulating material across manufacturing supply chains. Non-cross-linked grades dominate volume flows in consumer goods protective packaging where cost sensitivity drives procurement decisions, while cross-linked variants command premium positioning in medical device and precision electronics segments where dimensional stability under thermal cycling determines specification adherence. Laminated configurations represent the fastest-growing product configuration as multi-layer bonding with aluminum films or barrier substrates opens insulation applications in cold-chain logistics across Southeast Asian temperature corridors.
China's SAMR enforces GB standards for polymer recyclability that restrict virgin content thresholds in packaging applications, while India's BIS mandates product certification for polyethylene foam used in consumer contact applications, creating compliance cost tiers that favor scaled manufacturers over regional converters. Japan's METI circular economy guidelines for plastic resource efficiency incentivize closed-loop collection partnerships between EPE processors and electronics OEMs. Stakeholders must monitor divergence between national recycling infrastructure maturity and harmonized cross-border material passport requirements affecting intra-Asia Pacific trade flows.
Market Dynamics
Automotive electrification across Thailand and Vietnam is compressing specification cycles for battery protective packaging, forcing converters to qualify higher-density EPE grades within 18-month windows rather than traditional 36-month automotive approval timelines.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Subsidies for mobile phone and component production in Uttar Pradesh and Tamil Nadu are pulling EPE foam converters toward dedicated cleanroom lamination capacity.
- Cross-linked foam sterilization compatibility:Medical device manufacturers in Japan's Kansai corridor specify gamma-stable EPE grades for single-use surgical instrument trays, creating specification premiums.
- Southeast Asian cold-chain buildout:Temperature-controlled pharmaceutical distribution from Singapore and Bangkok is absorbing aluminum-laminated EPE panels for insulated shipping containers.
Market Restraints
- Ethylene feedstock volatility:Naphtha-linked polyethylene resin costs in Northeast Asia swing 15-25% quarterly, compressing converter margins on fixed-price packaging contracts.
- China's virgin content thresholds:SAMR-enforced GB standards for polymer recyclability restrict non-recycled material shares in consumer packaging, forcing reformulation investments.
- Expanded polypropylene substitution:Higher-temperature automotive applications near EV battery packs are specifying EPP foam where EPE thermal limits fail.
Strategic Opportunities
- Indonesia's underpenetrated automotive tier-2 supply base:Component clusters around Karawang lack localized EPE slitting and die-cutting capacity, creating logistics arbitrage for integrated converters.
- Digital printing integration:Direct-to-foam branding systems enable electronics OEMs to eliminate secondary label application, collapsing packaging line steps.
- Australia's medical device export growth:TGA-registered sterilizable foam demand from Sydney and Melbourne manufacturers outpaces domestic extrusion capacity.
Industry Challenges
- Multi-jurisdiction certification timelines:BIS approval for India, GB marking for China, and JIS compliance for Japan require parallel testing streams that extend product launch cycles 8-14 months.
- Lamination adhesive qualification:Bonding EPE to aluminum films for cold-chain applications demands solvent-free polyurethane systems with 180-day shelf stability that few regional suppliers reliably produce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Expanded Polyethylene (EPE) Foam Market |
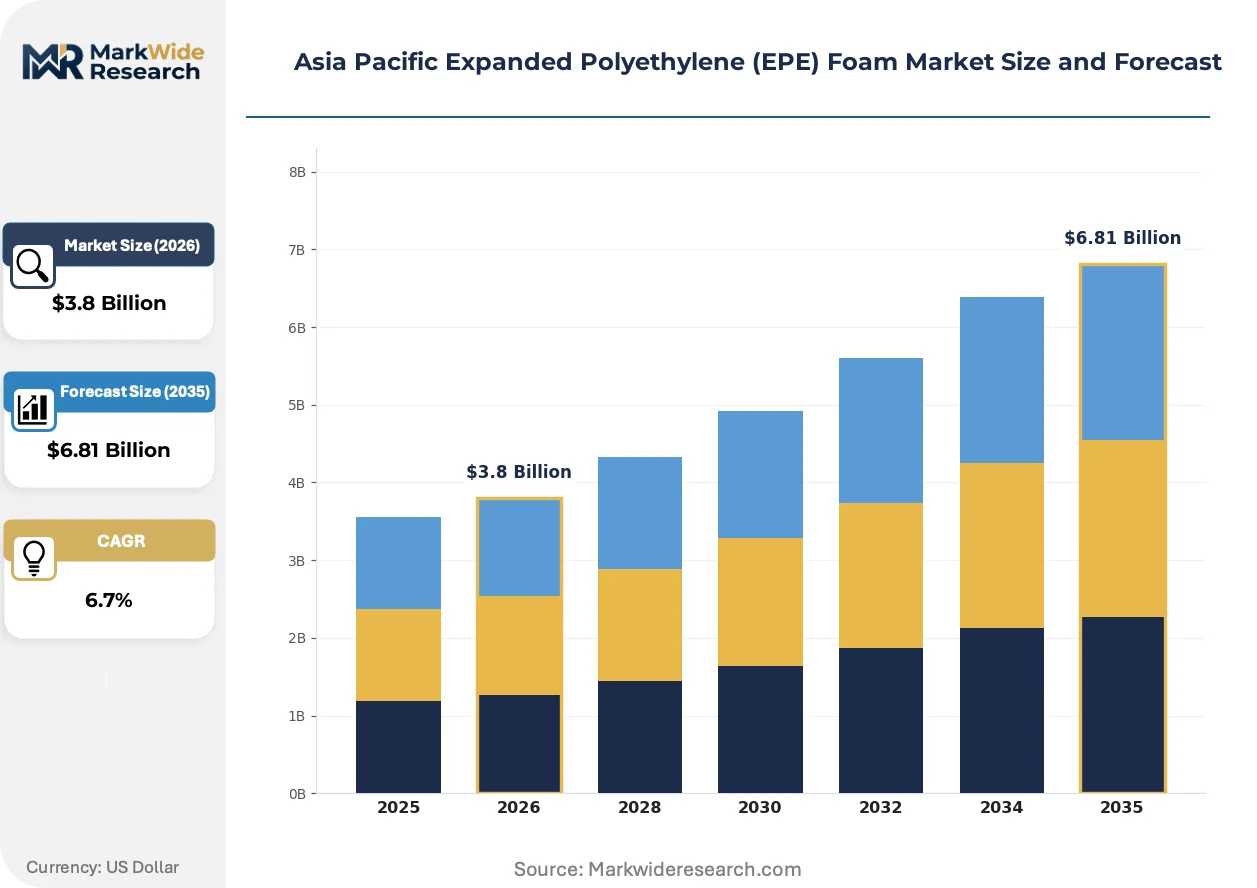
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cross-Linked, Non-Cross-Linked, Coated, Laminated Application: Packaging, Insulation, Automotive, Sports Equipment End User: Consumer Goods, Electronics, Packaging Industry, Medical Devices Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Supreme Industries Limited, Kunshan Yucel Packaging Co. Ltd., Sekisui Chemical, Kaneka, Mitsui Chemicals, Toyobo, Armacell, Pregis Corporation, NMC Products (M) Sdn. Bhd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Expanded Polyethylene (EPE) Foam Market Emerging Trajectories
Physical foaming process refinements and barrier-layer bonding technologies are compressing the performance gap between commodity packaging grades and engineered thermal insulation products across Asia Pacific manufacturing supply chains.
Multi-layer coextrusion with nucleating agent optimization is expanding into precision electronics packaging where void-size uniformity below 0.5mm protects semiconductor wafers during inter-facility transfer. Korean memory module manufacturers in Pyeongtaek and Chinese display panel fabs in Suzhou specify these grades for automated handling compatibility. The technology is expanding into medical device cleanroom logistics where particulate shedding limits disqualify conventional foam.
China's GB standards for polymer recyclability and Japan's METI circular economy guidelines are converging on closed-loop collection mandates that require EPE processors to document post-industrial scrap recovery rates. Electronics OEMs in Shenzhen and Osaka now audit converter partners on material passport traceability. India's BIS certification requirements for consumer-contact polyethylene foam are tightening testing protocols for heavy metal content and volatile organic compound emissions.
Consolidated procurement by multinational electronics contract manufacturers is displacing fragmented regional converter relationships across Southeast Asia. Foxconn and Pegatron operations in Vietnam and Thailand now specify pan-Asia Pacific EPE suppliers with ISO 13485 medical-grade capability alongside consumer electronics capacity. This concentration is most visible in Ho Chi Minh City's industrial zones where tier-2 foam fabricators without automotive or medical certifications are losing specification access.
Asia Pacific Expanded Polyethylene (EPE) Foam Market Segmentation
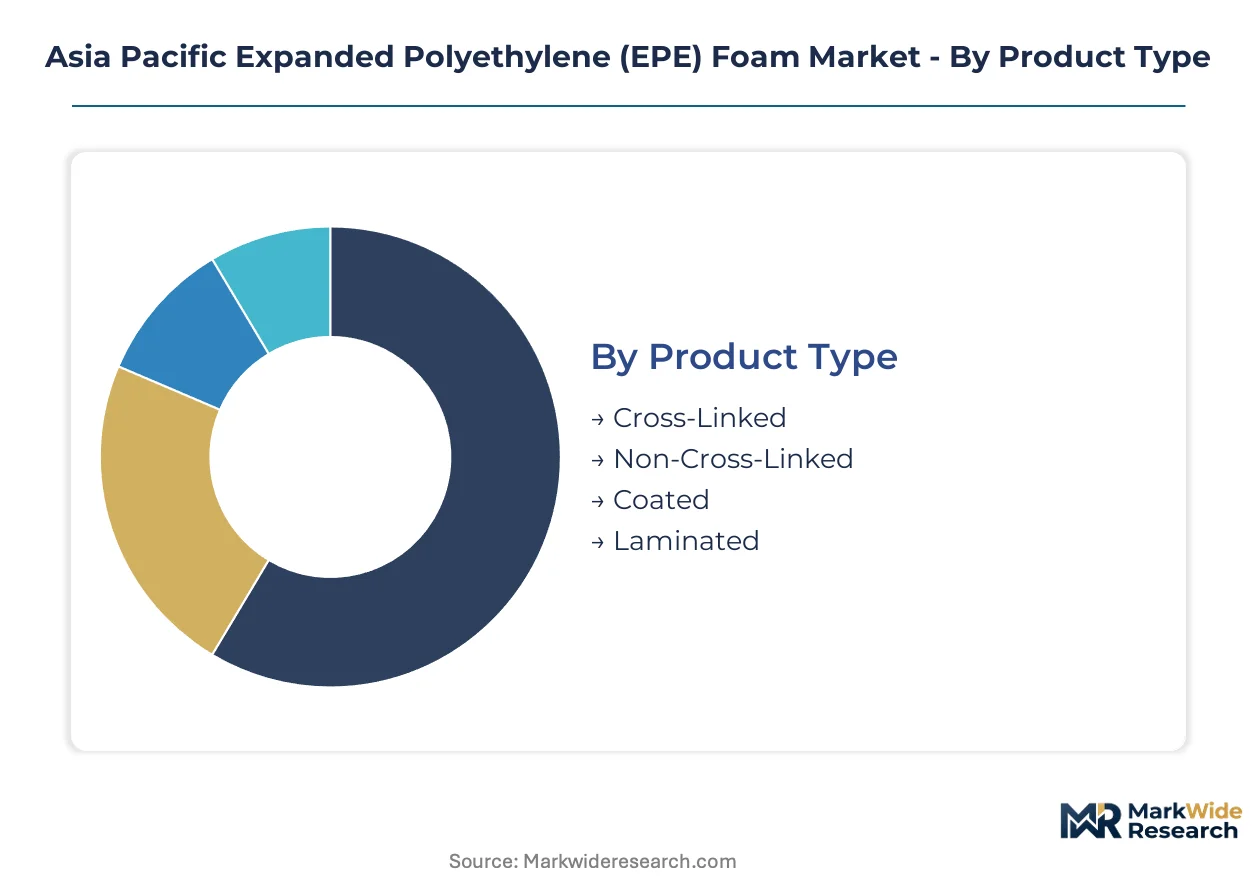
EPE foam specification tiers separate commodity protective packaging from engineered thermal and medical-grade applications. Technical differentiation across molecular structure, surface treatment, and bonding configuration determines pricing power and customer lock-in across Asia Pacific manufacturing supply chains.
Product Type:
Cross-linking density and surface modification define performance ceilings for temperature resistance, dimensional stability, and sterilization compatibility.
- Non-Cross-Linked:Linear polyethylene chains without chemical bonding deliver cost-optimized cushioning for consumer electronics and appliance packaging. Procurement concentrates in Vietnam and Thailand contract manufacturing zones where Foxconn and Pegatron operations specify virgin-content grades meeting China's GB recyclability thresholds.
- Cross-Linked:Peroxide or radiation-induced molecular bonding creates closed-cell structures withstanding repeated autoclave and gamma sterilization cycles. Japan's Kansai medical device corridor specifies these grades for single-use surgical instrument trays, commanding specification premiums over standard packaging variants.
- Coated:Surface-applied anti-static or barrier films modify triboelectric properties for semiconductor wafer handling.
- Laminated:Multi-layer bonding with aluminum films or vapor barrier substrates opens cold-chain pharmaceutical applications across Singapore and Bangkok distribution hubs.
Non-Cross-Linked leads on scale; Laminated leads on momentum.
Application:
End-use thermal and mechanical requirements drive density specification, with automotive electrification compressing qualification timelines.
- Packaging:Impact-dissipating inserts and corner protectors for consumer electronics and appliances dominate volume flows. India's Maharashtra and Gujarat industrial corridors source localized foam supply to reduce logistics costs for automotive component clusters.
- Insulation:Thermal conductivity near 0.035 W/m·K enables cold-chain logistics panels for temperature-controlled pharmaceutical distribution. Southeast Asian temperature corridors from Singapore to Bangkok absorb aluminum-laminated configurations for insulated shipping containers.
- Automotive:Higher-density grades protect EV battery packs during inter-facility transfer across Thailand and Vietnam assembly plants.
- Sports Equipment:Lightweight cushioning for protective gear and matting applications serves recreational and professional markets.
Packaging leads on scale; Insulation leads on momentum.
End User:
Certification requirements and cleanroom protocols segment procurement behavior across regulated and non-regulated industries.
- Electronics:Memory module manufacturers in Pyeongtaek and display panel fabs in Suzhou specify void-size uniformity below 0.5mm for automated wafer handling. India's PLI scheme for electronics manufacturing in Uttar Pradesh and Tamil Nadu pulls converters toward dedicated cleanroom lamination capacity.
- Medical Devices:Gamma-stable grades for single-use surgical trays require ISO 13485 certification that tier-2 fabricators without medical qualifications cannot access. TGA-registered demand from Sydney and Melbourne manufacturers outpaces Australian domestic extrusion capacity.
- Consumer Goods:Cost-sensitive protective packaging for appliances and furniture drives high-volume, low-margin procurement.
- Packaging Industry:Converter and fabricator intermediaries supply customized die-cut profiles to downstream OEMs.
Electronics leads on scale; Medical Devices leads on momentum.
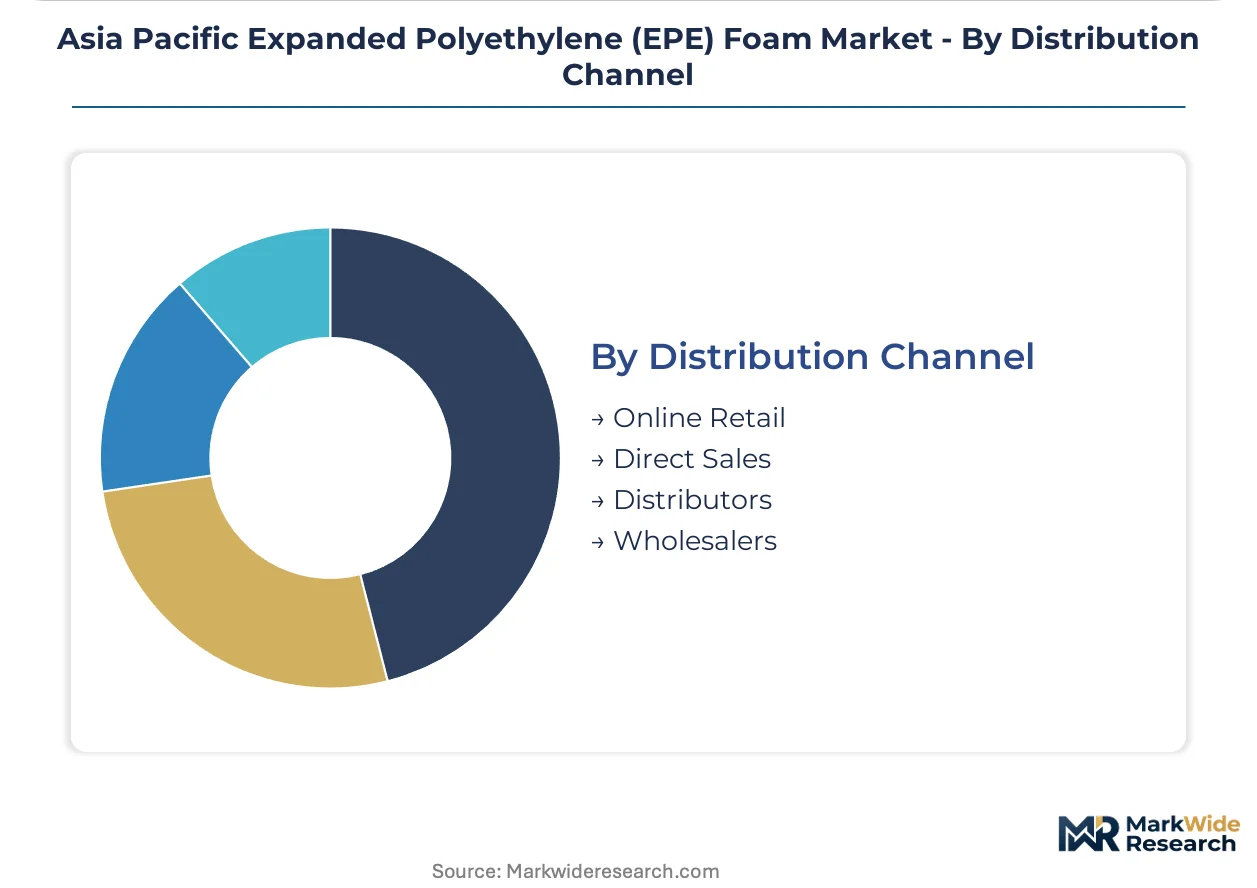
Distribution Channel:
Customer scale and specification complexity determine channel selection, with integrated converters bypassing intermediaries for multinational accounts.
- Direct Sales:Pan-Asia Pacific electronics contract manufacturers consolidate procurement through direct converter relationships. Foxconn and Pegatron operations in Vietnam and Thailand specify suppliers with simultaneous ISO 13485 medical-grade and consumer electronics capability.
- Distributors:Regional inventory positioning serves fragmented tier-2 automotive and appliance manufacturers requiring just-in-time slitting and die-cutting.
- Online Retail:E-commerce platforms enable small-batch procurement for prototyping and specialty applications.
- Wholesalers:Bulk commodity grades flow through traditional trade networks serving local packaging converters.
Direct Sales leads on scale; Distributors leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
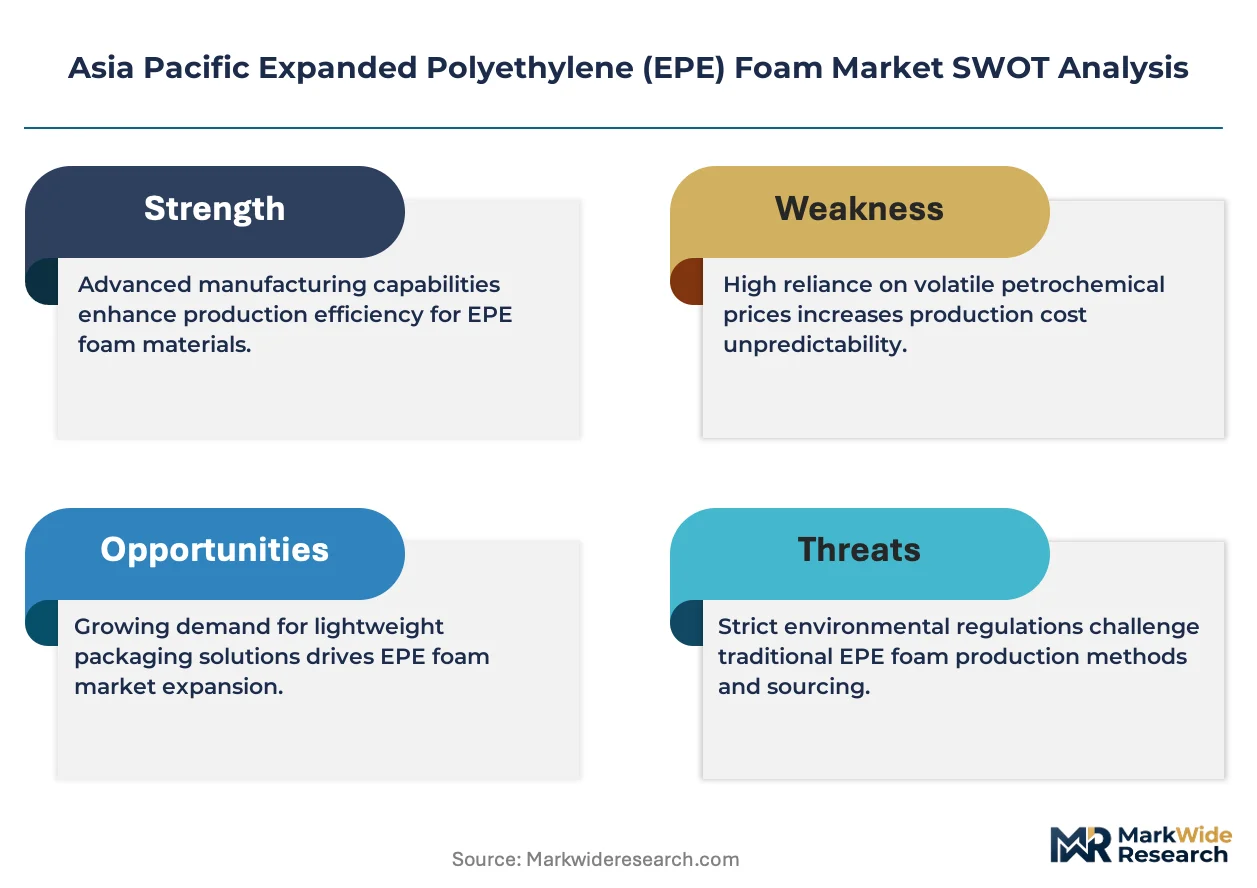
Regulatory-arbitrage dynamics are reshaping production geography as converters migrate toward jurisdictions with lower compliance-cost burdens while maintaining access to high-specification export markets. China's tightening GB standards for recyclability and India's BIS certification requirements create tiered cost structures that favor scaled operators with parallel qualification capabilities across multiple national regimes.
China
SAMR-enforced GB standards for polymer recyclability restrict virgin-content thresholds in consumer packaging applications, forcing reformulation investments among extrusion operators. The Yangtze River Delta and Pearl River Delta industrial corridors concentrate electronics OEM demand from memory module manufacturers in Suzhou and display panel fabricators requiring void-size uniformity below 0.5mm. Shenzhen-based electronics contract manufacturers now audit converter partners on material passport traceability under METI-aligned circular economy guidelines.
India
BIS mandates product certification for polyethylene foam used in consumer-contact applications, creating compliance cost tiers that favor scaled manufacturers over regional converters. The PLI scheme for electronics manufacturing subsidizes mobile phone and component production in Uttar Pradesh and Tamil Nadu, pulling EPE foam converters toward dedicated cleanroom lamination capacity. Maharashtra and Gujarat industrial corridors source localized foam supply to reduce logistics costs for automotive component clusters serving tier-1 auto suppliers.
Japan
METI circular economy guidelines for plastic resource efficiency incentivize closed-loop collection partnerships between EPE processors and electronics OEMs in Osaka and Tokyo. The Kansai medical device corridor specifies gamma-stable cross-linked grades for single-use surgical instrument trays, commanding specification premiums over standard packaging variants. Precision-calibrated thermal insulation grades anchor domestic demand from electronics OEMs requiring dimensional stability under thermal cycling.
Vietnam
Foxconn and Pegatron operations in Ho Chi Minh City's industrial zones specify pan-Asia Pacific EPE suppliers with simultaneous ISO 13485 medical-grade and consumer electronics capability. Tier-2 foam fabricators without automotive or medical certifications are losing specification access as consolidated procurement displaces fragmented regional converter relationships. Electronics manufacturers are expanding protective packaging procurement while higher-density grades protect EV battery packs during inter-facility transfer across assembly plants.
Thailand
Automotive electrification is compressing specification cycles for battery protective packaging, forcing converters to qualify higher-density EPE grades within 18-month windows rather than traditional 36-month automotive approval timelines. Bangkok distribution hubs absorb aluminum-laminated EPE panels for temperature-controlled pharmaceutical distribution across Southeast Asian temperature corridors. Contract manufacturing zones serving electronics OEMs drive cost-optimized cushioning procurement for consumer goods protective packaging where virgin-content grades meet China's GB recyclability thresholds.
Asia Pacific Expanded Polyethylene (EPE) Foam Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated procurement by multinational electronics contract manufacturers displacing fragmented regional converter relationships across Southeast Asia. The vendor base organizes around three strategic archetypes: diversified chemical conglomerates with integrated resin-to-foam capabilities, specialized foam fabricators with die-cutting and lamination expertise, and regional packaging converters serving tier-2 automotive and appliance manufacturers. Dominant competitive moves include geographic expansion through dedicated cleanroom capacity in India's PLI-subsidized electronics corridors and portfolio diversification into medical-grade sterilization-compatible formulations.
Among Asia-Pacific-based chemical conglomerates, Sekisui Chemical and Kaneka occupy positions exemplifying the premium-tier specialization archetype, while Mitsui Chemicals and Toyobo represent diversified resin producers with downstream foam integration. Supreme Industries Limited anchors the India-focused integrated converter segment. These named entities serve as reference points for market structure analysis rather than definitive competitive positioning claims.
| Leading Market Players |
|---|
| Supreme Industries Limited |
| Kunshan Yucel Packaging Co. Ltd. |
| Sekisui Chemical |
| Kaneka |
| Mitsui Chemicals |
| Toyobo |
| Armacell |
| Pregis Corporation |
| NMC Products (M) Sdn. Bhd. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between medical-grade cross-linked foam and commodity non-cross-linked packaging creates a bifurcated pricing architecture that concentrates margin capture in Japan's Kansai corridor while compressing returns across Vietnam's contract manufacturing zones. This tier split manifests in supply chain configurations where ISO 13485-certified processors command direct OEM relationships, while uncertified converters remain tethered to distributor intermediaries serving price-sensitive appliance manufacturers.
Pricing Analysis
Distributor margin layers absorb 12-18 percentage points between extrusion gate and tier-2 automotive fabricators in Indonesia, whereas direct-to-OEM contracts for Foxconn and Pegatron operations in Vietnam eliminate intermediaries entirely. Pricing stratifies across medical sterilization grades, automotive density specifications, and consumer electronics commodity tiers, with gamma-stable cross-linked formulations commanding sustained premiums over standard variants. Cost compression in non-cross-linked segments is intensifying because naphtha-linked polyethylene resin costs in Northeast Asia swing unpredictably, squeezing converter margins on fixed-price packaging agreements. Electronics contract manufacturers exhibit lowest price sensitivity due to specification lock-in, while furniture and appliance OEMs drive aggressive procurement negotiations on virgin-content grades.
Supply Chain Analysis
Closed-loop collection partnerships between Osaka-based processors and electronics OEMs are reshaping reverse-logistics flows under Japan's METI circular economy guidelines, with post-industrial scrap recovery rates now audited as contract conditions. Primary extrusion capacity concentrates in China, Japan, and South Korea, with downstream slitting and die-cutting operations distributed across Vietnam, Thailand, and India's Maharashtra corridor. Raw material dependencies draw from naphtha crackers in Northeast Asia, peroxide cross-linking agents from European chemical specialists, and nucleating agents for precision void-size control. Single-source vulnerability in medical-grade adhesive bonding systems for aluminum-laminated cold-chain panels creates qualification bottlenecks. Distribution runs through direct converter relationships for multinational electronics manufacturers and regional distributor networks for fragmented tier-2 automotive suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where India's BIS certification mandates and China's GB recyclability thresholds are accelerating demand for qualified converters capable of parallel multi-jurisdiction compliance. The convergence of automotive electrification and medical device sterilization requirements is expanding the addressable premium tier faster than commodity packaging volumes.
For Market Incumbents: Hedge against expanded polypropylene substitution in high-temperature automotive applications by qualifying hybrid foam formulations that bridge thermal performance gaps. Secure backward integration into peroxide cross-linking agent supply through captive sourcing agreements with European chemical specialists, insulating margin structures from input volatility. Defensive consolidation through acquisition of Indonesia's tier-2 slitting and die-cutting capacity addresses the Karawang supply gap before competitors establish localized fabrication.
For New Entrants and Emerging Players: Enter via Australia's TGA-registered sterilizable foam segment where Sydney and Melbourne medical device manufacturers outpace domestic extrusion capacity, creating immediate offtake visibility. Target Indonesia's underpenetrated automotive tier-2 supply base around Karawang with integrated slitting and logistics arbitrage capabilities. Deploy direct-to-foam digital printing systems as the go-to-market angle, collapsing packaging line steps for electronics OEMs seeking brand differentiation without secondary label application.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap converters possessing simultaneous ISO 13485 medical-grade capability and consumer electronics scale across the Vietnam-Thailand corridor. Long-term viability hinges on material passport traceability infrastructure that satisfies both Japan's METI circular economy guidelines and Shenzhen-based electronics OEM audit requirements. Acquisition targets should demonstrate validated closed-loop collection partnerships with quantifiable post-industrial scrap recovery rates. Monitor BIS approval timeline compression in India as the inflection indicator for scaled manufacturers displacing regional converters.
| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Lamination Capacity Expansion | India's PLI-subsidized electronics corridors in Uttar Pradesh and Tamil Nadu demand qualified supply. |
| Backward Integration into Cross-Linking Agents | Peroxide supply security insulates margin structures from European chemical specialist pricing volatility. |
| Digital Printing System Integration | Foxconn and Pegatron operations seek packaging line step reduction through direct-to-foam branding. |
| Multi-Jurisdiction Certification Investment | Parallel BIS, GB marking, and JIS compliance accelerates product launch cycles for pan-Asia Pacific suppliers. |
| Closed-Loop Collection Partnerships | Osaka and Shenzhen OEMs now audit material passport traceability under METI-aligned circular economy mandates. |
Methodological Framework
Multiple input streams — primary interviews with foam extrusion plant managers, procurement leads at tier-1 automotive suppliers, and medical device regulatory affairs directors; secondary validation through customs and trade data, BIS certification registries, and SEC filings of listed chemical conglomerates; plus technical literature on nucleating agent optimization — were reconciled through bottom-up and top-down triangulation. Conversations with distribution channel partners in Ho Chi Minh City and Bangkok provided downstream pricing visibility, while engagement with cleanroom lamination specialists in India's PLI corridors illuminated capacity expansion timelines.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include cross-linking density tiers, end-use applications spanning electronics packaging through medical sterilization, regional production hub configurations, and certification-grade stratification. CAGRs were derived through trend extrapolation adjusted for regulatory milestone impacts and feedstock cost volatility assumptions. Industry-specific forecast inputs incorporated naphtha price sensitivity coefficients and automotive electrification penetration curves for battery protective packaging specifications.
Inputs from BIS certification databases and METI circular economy partnership registries were available through the study window; gaps in real-time converter margin data introduce uncertainty bands around pricing trajectory assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and resin cost normalization patterns. Practitioners should monitor SAMR GB standard enforcement intensity and Indonesia's automotive cluster development pace for early signals of supply chain reconfiguration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global Plastic Fasteners Market
Industrial Materials
Global Jet Mill Market
Industrial Materials
Grouting Materials Market
Industrial Materials
Global Thermally Modified Wood Market
Industrial Materials
Industrial Silica Sand Market
Industrial Materials
Polymer Bearing Market
Industrial Materials
Wire Hoods Market
Industrial Materials
Silica Fume Market
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
Polyurethane Insulation Board Market
Industrial Materials
Crimped Wire Brushes Market
Industrial Materials
UHP Graphite Electrode Market
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
Industrial Anti-Fatigue Mat Market
Industrial Materials
Hardfacing Rods Market
Industrial Materials
Global High Temperature Gaskets Market