
 Heat-Insulation Boards for Industrial Equipment Market | 2026-2036
Heat-Insulation Boards for Industrial Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Heat-Insulation Boards for Industrial Equipment Market Insights
Multi-source procurement among energy-intensive manufacturers is consolidating toward preferred technical partnerships with fewer insulation suppliers. Owens Corning leverages its fiberglass mat technology leadership to anchor long-term utility contracts. Rockwool International competes on basalt mineral wool formulations rated above 700°C operating temperatures. BASF SE differentiates through polyurethane systems tailored for cryogenic chemical processing environments.
Heat-insulation boards for industrial equipment are engineered panels designed to reduce thermal bridging, maintain process temperatures, and protect structural substrates from heat stress in continuous-operation settings. These assemblies typically incorporate mineral wool, ceramic fiber, or aerogel cores bonded to metal or composite facings, with performance graded by ASTM C518 thermal conductivity testing and ISO 8301 declared R-values. Mineral wool products dominate installed base across power generation and petrochemical plants where fire resistance ratings govern specification. Aerogel segments command premium positioning in space-constrained retrofit applications where thinner profiles justify higher material costs. Calcium silicate technology sustains share in high-temperature steam systems where compressive strength requirements exclude lighter alternatives.
EPA New Source Performance Standards, OSHA 1910.147 thermal hazard protocols, and ISO 23993 energy management frameworks shape product certification pathways and facility compliance timelines. REACH restrictions on formaldehyde-based binders in Europe and China's GB 50264 industrial thermal design code further narrow acceptable material formulations. Buyers must weigh total lifecycle thermal performance against evolving cross-border chemical content rules when qualifying suppliers.
Market Dynamics
Energy-intensive manufacturers are consolidating procurement around fewer technical partners capable of delivering certified thermal performance packages, compressing vendor counts while elevating engineering service expectations.
Growth Catalysts
- EPA New Source Performance Standards:Tighter emissions thresholds compel facility retrofits across US chemical processing and power generation sites, accelerating specification of high-temperature insulation systems.
- China's GB 50264 industrial thermal design code:State-mandated efficiency targets drive replacement cycles across steel complexes and petrochemical clusters, concentrating demand for mineral wool and ceramic fiber boards.
- Aerogel core technology:Thinner thermal profiles enable space-constrained retrofits in aging European refineries where structural clearance limits exclude conventional insulation thicknesses.
Market Restraints
- Alumina-silica raw material concentration:Supply of high-purity ceramic fiber feedstock concentrates among limited specialty chemical producers, exposing board manufacturers to input volatility and qualification delays.
- REACH formaldehyde binder restrictions:ECHA limitations on traditional binding agents force European suppliers to reformulate mineral wool products, extending R&D timelines and compressing margin structures during transition.
- Technical performance ceiling:Calcium silicate boards face compressive strength constraints above 650°C operating temperatures, excluding them from ultra-high-temperature steam systems where denser alternatives dominate.
Strategic Opportunities
- Cryogenic chemical processing:Polyurethane-based systems tailored for sub-zero LNG handling and cold-chain infrastructure remain underpenetrated relative to high-temperature segments, offering white-space expansion.
- India's PLI scheme for manufacturing:Production-linked incentives for domestic industrial equipment buildout create localized demand for certified insulation suppliers establishing technical partnerships with EPC contractors.
- Digital thermal monitoring integration:Convergence of IoT sensor networks with insulation specification enables predictive maintenance contracts, shifting vendor relationships from material supply to performance-guaranteed service models.
Industry Challenges
- ASTM C518 and ISO 8301 certification complexity:Multi-jurisdictional testing requirements extend product qualification timelines, delaying market entry for reformulated binders and novel core materials.
- Installation skill specialization:Proper deployment of aerogel and multi-layer composite systems demands trained applicator networks that remain thinner than conventional mineral wool contractor bases.
- Legacy equipment compatibility:Retrofit projects require thermal bridging calculations and substrate adhesion verification that complicate specification engineering for aging industrial infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat-Insulation Boards for Industrial Equipment Market |
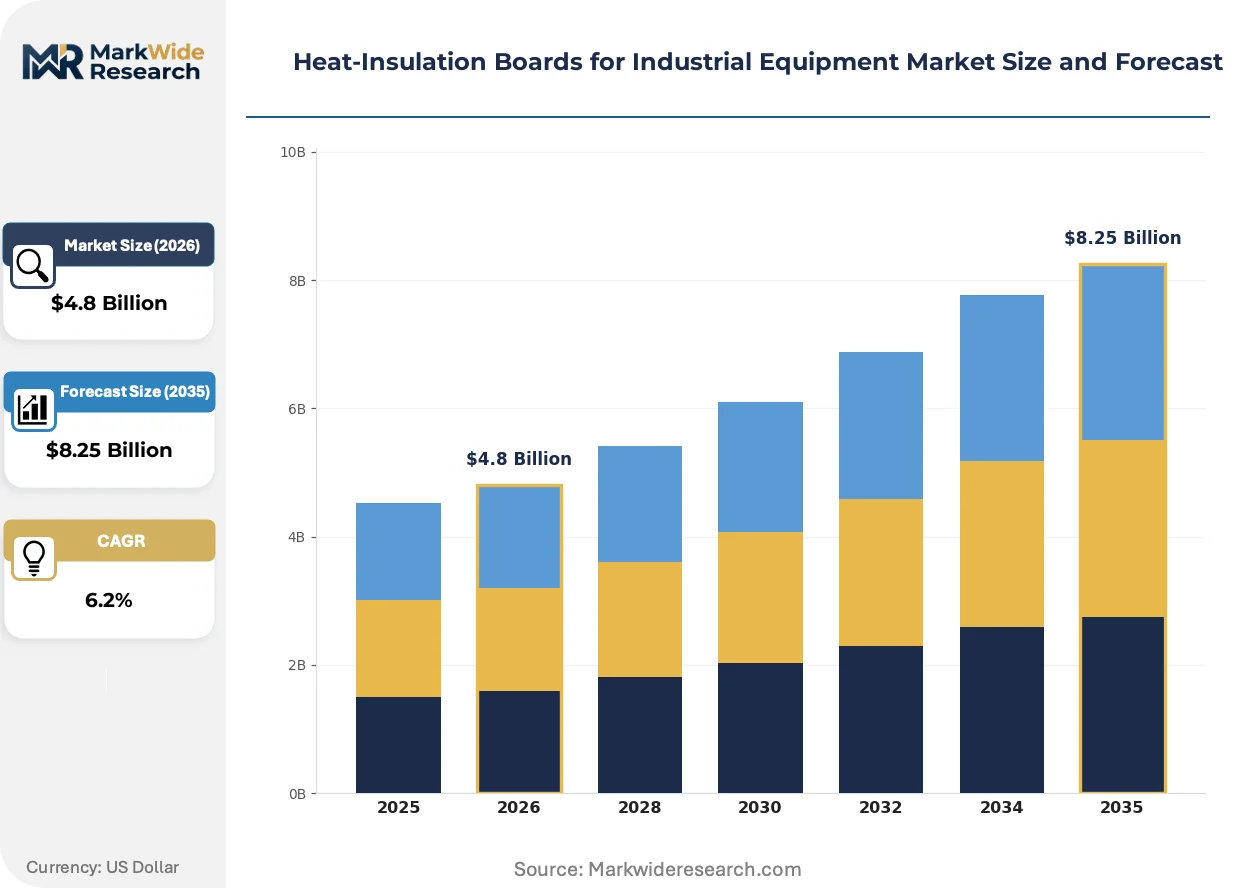
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Wool, Polystyrene, Polyurethane, Phenolic Foam, Aerogel Technology: Vacuum Insulation Panels, Reflective Coatings, Fiberglass Mats, Ceramic Fiber Boards, Calcium Silicate Application: Power Generation, Chemical Processing, Food Processing, HVAC Systems, Petrochemical Plants End User: Manufacturing Plants, Refineries, Cold Storage Facilities, Waste Treatment Units, Metal Fabrication Yards |
| Companies Covered | Owens Corning, Kingspan Group, Rockwool International, BASF SE, Saint-Gobain, Johns Manville, Armacell International, Knauf Insulation, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat-Insulation Boards for Industrial Equipment Market Trends and Innovations
Thermal performance engineering is pivoting from passive material supply toward integrated system solutions, with specification decisions increasingly contingent on lifecycle energy modeling and predictive service capabilities rather than upfront unit costs.
Aerogel-impregnated fiberglass composites are expanding into refinery maintenance schedules where turnaround windows compress installation hours. Major petrochemical operators in the US Gulf Coast and Rotterdam-Antwerp corridor specify these systems for vessel and pipeline retrofits, accepting material premiums to minimize production downtime. The technology is expanding into conventional mineral wool strongholds by redefining total project economics around speed of deployment rather than square-meter material pricing.
OSHA 1910.147 thermal hazard protocols now mandate documented surface temperature limits on accessible industrial equipment, compelling facility-wide insulation audits across US manufacturing sites. The regulation forces replacement of degraded legacy systems and disqualifies partial repairs that fail to meet documented safe-touch thresholds. Food processing and pharmaceutical packaging lines face the steepest compliance timelines due to frequent worker proximity to heated equipment.
Long-term utility contracting is displacing transactional material purchasing among power generators and chemical processors seeking to transfer thermal performance risk. Engineering-procurement-construction firms now bundle insulation specification with 10-year energy guarantee clauses, shifting vendor selection criteria toward balance-sheet capacity and installation track record. This restructuring concentrates procurement authority with integrated service providers and marginalizes standalone board distributors in North American and Western European markets.
Heat-Insulation Boards for Industrial Equipment Market Segmentation
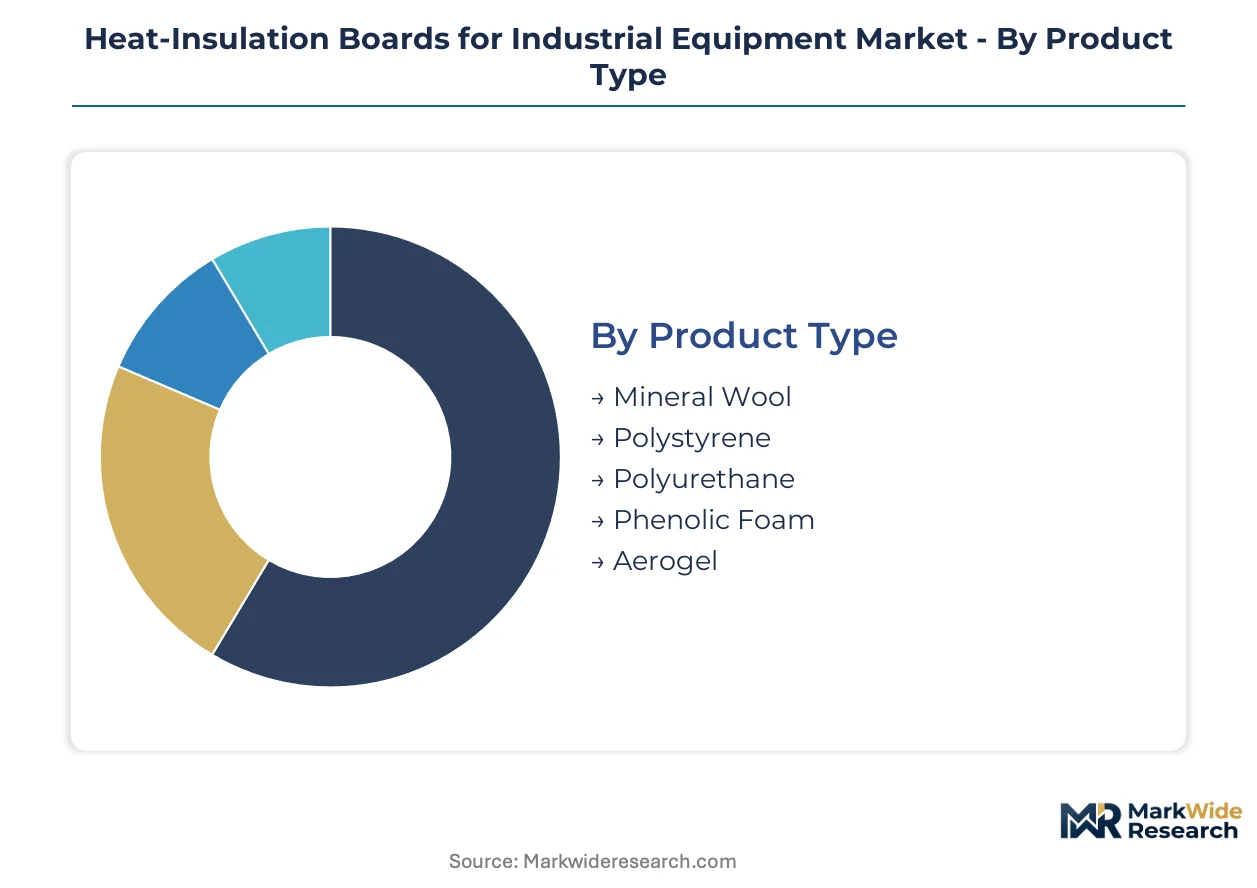
Material selection in industrial thermal insulation hinges on operating temperature thresholds, space constraints, and fire resistance ratings. Specification engineers weigh compressive strength against thermal conductivity coefficients when matching board types to equipment duty cycles.
Product Type:
Cost tier separates specification-grade mineral wool from premium aerogel systems in buyer decision matrices.
- Mineral Wool:Basalt or slag-based fibers bonded with phenolic resins deliver fire resistance ratings above 750°C. Steel complexes in China specify mineral wool boards under GB 50264 efficiency mandates to cut heat losses in furnace linings and ductwork.
- Aerogel:Silica-based nanoporous structures achieve thermal conductivity below 0.020 W/m·K in profiles one-third the thickness of conventional insulation. European refineries in Rotterdam-Antwerp corridor accept material premiums to solve space-constrained retrofits where structural clearances exclude thicker alternatives.
- Polystyrene:Expanded and extruded variants serve moderate-temperature HVAC and cold storage applications where moisture resistance governs specification.
- Polyurethane:Rigid foam systems dominate cryogenic chemical processing and LNG handling infrastructure with sub-zero thermal performance.
- Phenolic Foam:Low-smoke emission characteristics meet stringent fire safety codes in enclosed industrial facilities.
Volume sits with mineral wool; growth tilts toward aerogel.
Technology:
Application temperature range determines whether vacuum panels or ceramic fiber boards enter final specification packages.
- Ceramic Fiber Boards:Alumina-silica compositions withstand continuous exposure above 1000°C in gas turbine exhaust systems and reformer vessels. Petrochemical clusters along the US Gulf Coast specify these boards for cracking furnace linings where thermal cycling resistance extends maintenance intervals.
- Vacuum Insulation Panels:Core materials evacuated to sub-atmospheric pressure achieve R-values five times conventional insulation in equivalent thickness. Cold storage facilities in Germany and Netherlands deploy VIPs for perimeter insulation where floor space constraints limit conventional board thicknesses.
- Reflective Coatings:Aluminum-faced laminates reduce radiant heat transfer in high-temperature ductwork and vessel exteriors.
- Fiberglass Mats:Owens Corning's proprietary formulations anchor utility-scale power generation contracts through standardized mat dimensions and installation protocols.
- Calcium Silicate:Hydrous calcium silicate structures provide compressive strength for high-pressure steam piping where load-bearing requirements exclude lighter alternatives.
Ceramic fiber commands the installed base; vacuum panels are climbing the fastest.
Application:
Process intensity and thermal hazard exposure separate chemical processing specifications from food processing requirements.
- Chemical Processing:Reactor vessels, distillation columns, and heat exchanger networks demand multi-layer insulation systems rated for thermal shock and chemical exposure. EPA New Source Performance Standards compel facility-wide upgrades across US chemical complexes, accelerating procurement of certified high-temperature boards.
- Power Generation:Boiler casings, steam turbines, and flue gas desulfurization units require insulation packages combining thermal performance with structural integrity. Coal and combined-cycle plants in India specify calcium silicate and mineral wool systems under production-linked incentive schemes for domestic equipment buildout.
- Petrochemical Plants:Ethylene crackers and catalytic reformers operate at temperature extremes that exclude all but ceramic fiber and advanced composite systems.
- Food Processing:OSHA 1910.147 safe-touch mandates drive replacement of degraded insulation on ovens, fryers, and pasteurization equipment with frequent worker proximity.
- HVAC Systems:Chilled water piping and air handling units specify closed-cell foams where condensation control parallels thermal performance.
Chemical processing absorbs the largest share; power generation offers the steepest expansion trajectory.
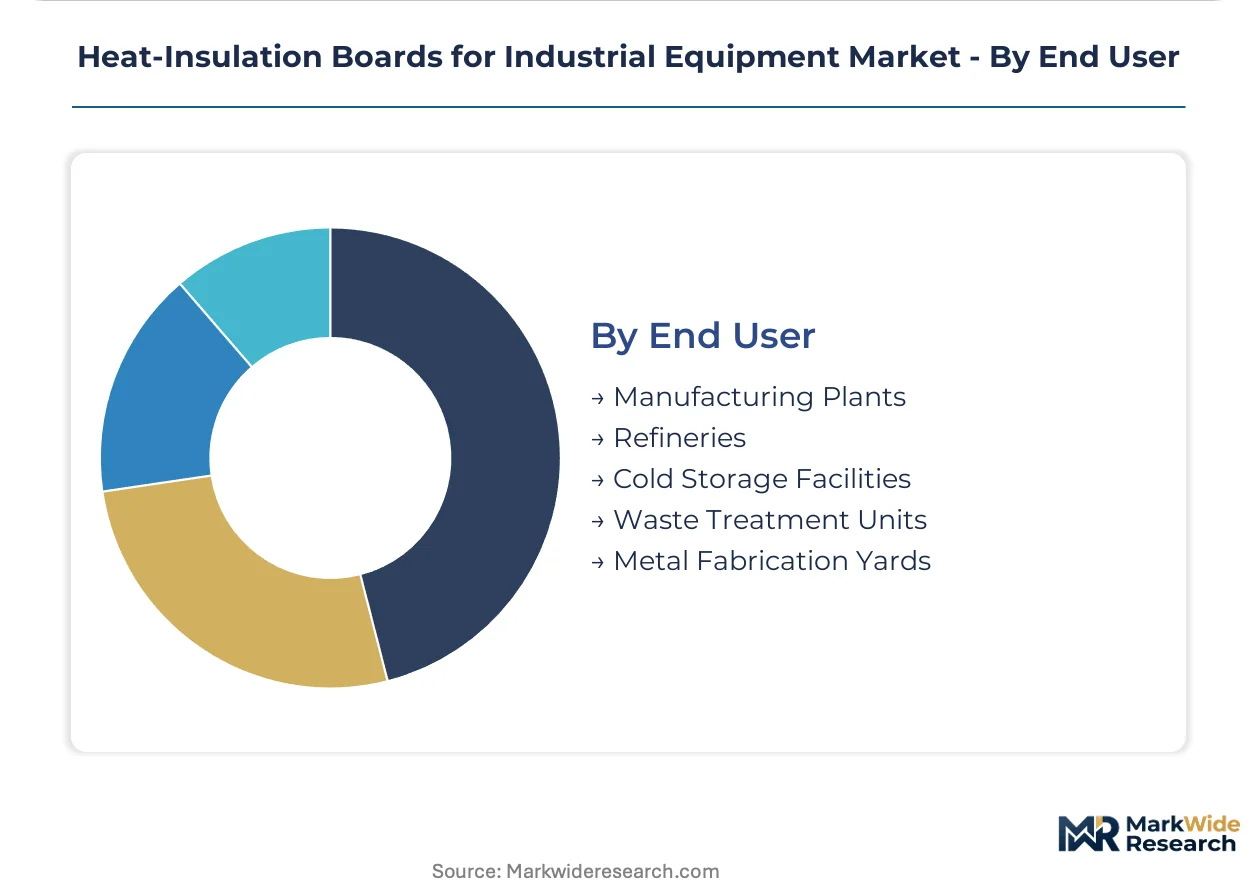
End User:
Capital expenditure cycles and regulatory compliance timelines differentiate procurement patterns across facility types.
- Refineries:Turnaround schedules compress installation windows to 30-60 day outages, favoring pre-fabricated insulation modules and aerogel composites that minimize labor hours. Major operators in Saudi Arabia and Singapore specify integrated thermal performance contracts with decade-long energy guarantees.
- Manufacturing Plants:Discrete production equipment—extruders, presses, and heat treatment furnaces—requires customized insulation geometries that fragment procurement into project-specific orders.
- Cold Storage Facilities:Continuous refrigeration loads prioritize thermal bridge elimination in panel joints and penetration seals.
- Waste Treatment Units:Incinerator linings and flue gas handling systems demand acid-resistant insulation formulations.
- Metal Fabrication Yards:Heat treatment furnaces and welding stations specify mid-temperature mineral wool systems with rapid replacement protocols.
Refineries dominate contract value; manufacturing plants represent the broadest addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alumina-silica feedstock availability in Shandong Province anchors Asia-Pacific supply chains for ceramic fiber board production. European manufacturers source high-purity raw materials from limited specialty chemical producers in Germany and Belgium. North American demand concentrates along Gulf Coast petrochemical corridors where EPA compliance timelines accelerate procurement cycles.
United States
Gulf Coast petrochemical clusters in Texas and Louisiana drive specification of high-temperature insulation systems for ethylene crackers and catalytic reformers. EPA New Source Performance Standards compel facility-wide retrofits across chemical processing sites. Houston-area engineering-procurement-construction firms bundle decade-long thermal performance contracts with insulation specification.
China
State-mandated efficiency targets under GB 50264 industrial thermal design code accelerate replacement cycles across steel complexes and petrochemical facilities. Shandong and Jiangsu provinces concentrate mineral wool and ceramic fiber board manufacturing capacity. Baosteel facilities in Shanghai specify certified insulation packages to meet dual carbon goals and industrial efficiency benchmarks.
Germany
REACH restrictions on formaldehyde-based binders force mineral wool suppliers to reformulate products, extending R&D timelines for European market entry. BASF SE anchors polyurethane system development for cryogenic chemical processing applications. Industrial clusters in North Rhine-Westphalia specify vacuum insulation panels for cold storage facilities where floor space constraints limit conventional board thicknesses.
India
Production-linked incentive schemes for domestic industrial equipment buildout create localized demand for certified insulation suppliers. Reliance Industries and Indian Oil Corporation expand petrochemical capacity in Gujarat and Maharashtra, specifying calcium silicate and mineral wool systems. Mumbai-based EPC contractors establish technical partnerships with insulation vendors for refinery and power generation projects.
Saudi Arabia
SABIC and Saudi Aramco turnaround schedules compress installation windows to 30-60 day outages, favoring pre-fabricated insulation modules. Integrated thermal performance contracts with decade-long energy guarantees restructure procurement authority toward service providers. Jubail Industrial City and Yanbu complexes concentrate demand for ceramic fiber boards in gas turbine exhaust and reformer vessel applications.
Heat-Insulation Boards for Industrial Equipment Market Competitive Landscape
Long-term utility contracting dominates the current landscape as power generators and chemical processors transfer thermal performance risk to integrated service providers. The vendor base organizes around three strategic tiers: multinational material science conglomerates with balance-sheet capacity for performance guarantees, regional specialists in high-temperature formulation, and application-focused contractors with installation track records. Competitive positioning hinges on ASTM C518 and ISO 8301 certification breadth, alongside predictive maintenance service capabilities.
Within the multinational tier, Owens Corning, Rockwool International, and BASF SE exemplify divergent technical anchoring strategies. Owens Corning represents fiberglass mat standardization approaches that secure utility-scale power generation contracts through installation protocol uniformity. Rockwool International occupies the basalt mineral wool specialization position rated for continuous exposure above 700°C operating thresholds. BASF SE anchors polyurethane system development for sub-zero chemical processing environments where cryogenic performance requirements exclude fiber-based alternatives. Each archetype faces pressure to bundle material supply with IoT-enabled thermal monitoring and predictive maintenance clauses.
| Leading Market Players |
|---|
| Owens Corning |
| Kingspan Group |
| Rockwool International |
| BASF SE |
| Saint-Gobain |
| Johns Manville |
| Armacell International |
| Knauf Insulation |
| Dow Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term utility contracting among power generators and chemical processors is compressing procurement cycles and forcing suppliers to bundle installation services with material supply, elevating working capital requirements and reshaping margin structures across the insulation board value chain.
Pricing Analysis
Warranty-backed thermal performance guarantees now separate premium suppliers from commodity competitors, with decade-long energy contracts bundling material, installation, and predictive maintenance into single-price packages. Three-tier pricing structure across premium, standard, and economy levels reflects ASTM C518 certification grade, ISO 8301 declared R-value precision, and geographic delivery complexity. Cost compression in mineral wool segments is intensifying because REACH-mandated binder reformulations extend R&D timelines without immediate price recovery mechanisms. Refinery operators demonstrate lowest price sensitivity due to turnaround-driven urgency, while metal fabrication yards exhibit highest elasticity given rapid replacement protocols and fragmented procurement authority.
Supply Chain Analysis
Refurbishment flows for degraded ceramic fiber linings from Saudi and Singapore refineries are creating secondary material streams that compete with virgin board production in price-sensitive segments. Alumina-silica feedstock concentrates in China, Germany, and Belgium, with high-purity ceramic fiber precursors drawing from limited specialty chemical producers in Shandong Province and the Rhine-Ruhr corridor. Single-source vulnerability in phenolic resin binders exposes mineral wool manufacturers to ECHA restriction cascades. Distribution runs through engineering-procurement-construction firms that bundle specification with installation, marginalizing standalone board distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EPA New Source Performance Standards and OSHA 1910.147 thermal hazard protocols erect certification barriers that favor incumbents with established testing relationships and documented installation track records.
For Market Incumbents: Deepen backward integration into alumina-silica feedstock to secure ceramic fiber supply against specialty chemical producer concentration, while expanding predictive maintenance service capabilities to capture long-term utility contract renewals. Aerogel core technology substitutes threaten mineral wool dominance in space-constrained retrofits; defend position by accelerating IoT-enabled thermal monitoring integration that shifts vendor relationships from material supply to performance-guaranteed service models. For New Entrants and Emerging Players: Direct-to-EPC digital platforms offer lower-friction entry paths than established distributor networks, enabling specification influence before procurement formalization. Cryogenic chemical processing remains underpenetrated relative to high-temperature segments; target polyurethane system development for LNG handling infrastructure where BASF SE's technical anchoring has not yet saturated demand. India's PLI scheme for manufacturing creates localized partnership opportunities with Mumbai-based contractors seeking certified insulation suppliers for refinery and power generation projects. For Investors and Strategic Acquirers: The window for entry favors application-focused contractors with installation track records and existing OSHA 1910.147 compliance documentation, as long-term thermal performance contracting displaces transactional material purchasing. Five-to-ten year viability hinges on balance-sheet capacity for decade-long energy guarantee clauses. Monitor EPA enforcement intensity and GB 50264 implementation pace in China as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina-Silica Feedstock | Ceramic fiber board manufacturers secure supply against Shandong Province concentration and qualification delays. |
| IoT-Enabled Thermal Monitoring Integration | Insulation suppliers shift from material provision to predictive maintenance contracts with power generators. |
| REACH-Compliant Binder Reformulation | European mineral wool producers extend R&D timelines to meet ECHA restrictions on formaldehyde-based agents. |
| Prefabricated Insulation Module Development | Suppliers capture Saudi Aramco and SABIC turnaround schedules compressing installation windows to 30-60 days. |
| Cryogenic Polyurethane System Expansion | BASF SE anchors technical differentiation for LNG handling infrastructure with sub-zero thermal performance requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads at industrial facilities across chemical processing, power generation, and petrochemical verticals. EPA New Source Performance Standards documentation, OSHA 1910.147 enforcement records, GB 50264 implementation reports, and REACH restriction notices provided regulatory validation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators and energy intensity benchmarks.
Data-stream reconciliation across material consumption volumes, installation project pipelines, and long-term utility contract disclosures informed the analytical framework. Segmentation dimensions modeled include material type, technology category, application intensity, and end-user capital expenditure cycle across the projection horizon. CAGRs derived from replacement cycle analysis, regulatory compliance timeline mapping, and efficiency mandate implementation schedules. Industry-specific forecast inputs incorporated alumina-silica feedstock availability indices and EPC contractor backlog data.
The model holds under steady regulatory enforcement and continued state-backed efficiency targets; deviation in EPA rulemaking intensity or Chinese industrial policy shifts would alter replacement cycle assumptions. Practitioners should monitor OSHA audit frequency and Shandong Province environmental compliance actions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Isotropic Graphite Market
Industrial Materials
Global Industrial Chain Market
Industrial Materials
Twin Screw Extruders Market
Industrial Materials
Industrial Couplings Market
Industrial Materials
Industrial Wax Market
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
Colored Hard PU Foam Market
Industrial Materials
UHP Graphite Electrode Market
Industrial Materials
Foam Insulation Market
Industrial Materials
Expanded PTFE (Eptfe) Market
Industrial Materials
Global Cenospheres Market
Industrial Materials
Thermal Spray Guns Market
Industrial Materials
Global Graphite Electrode Rod Market
Industrial Materials
Portable Magnetizer Market
Industrial Materials
Polycarbonate Panels Market
Industrial Materials
Tension Spring Market