
 Europe Wood-Plastic Composite (WPC) Market | 2026-2036
Europe Wood-Plastic Composite (WPC) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wood-Plastic Composite (WPC) Market Foresight
Market Context
German compounders and extrusion specialists is realigning capacity toward bio-based feedstocks to serve specification-grade construction projects. Deceuninck leverages its profile systems expertise to dominate facade and decking channels across Benelux and France. FKuR Kunststoff GmbH specializes in custom biopolymer compounds that anchor its position in premium architectural specifications. Silvadec competes through integrated sawmill-to-extrusion operations that control fiber sourcing quality.
Technical Definition and Segment Structure
Europe Wood-Plastic Composite (WPC) denotes extruded or molded thermoplastic matrices—typically polyethylene, polypropylene, or PVC—reinforced with wood flour or natural fibers at loadings of 50-70% by weight, yielding moisture-resistant dimensional stability for exterior building products. Decking occupies the dominant volume position, though margin pools concentrate in siding and railing systems where surface finishing complexity creates differentiation. Residential applications lead absolute consumption, while commercial landscaping represents the fastest-expanding specification channel as municipal projects mandate recycled-content thresholds.
Regulatory Framework and Outlook
REACH registration requirements and the EU Green Deal's embodied carbon benchmarks are reshaping material certification protocols, with ECHA scrutiny on plastic additive migration tightening formulation disclosure. CE marking under Construction Products Regulation (CPR) governs structural deployment in load-bearing exterior applications. France's RE2020 environmental regulation and Germany's federal building codes add national layers to performance verification. Stakeholders must monitor evolving EPD requirements and recyclability audits as procurement criteria harden across public infrastructure tenders.
Market Dynamics
The EU Green Deal's embodied carbon benchmarks are forcing compounders to reformulate feedstocks, while REACH compliance requirements tighten additive disclosure protocols across extrusion operations.
Growth Catalysts
- RE2020 environmental regulation:France's building code mandates lower carbon intensity in construction materials, accelerating specification of recycled-content WPC in residential facades.
- Rhine-Ruhr corridor demand cluster:German builders concentrate procurement of certified decking systems, creating volume anchors for compounders serving specification-grade projects.
- Natural fiber loading optimization:Extrusion specialists advance processing techniques to push wood flour content toward 70% by weight, improving moisture resistance and dimensional stability.
Market Restraints
- Polypropylene price volatility:Crude-linked resin costs swing formulation economics, compressing margins for producers locked into fixed-price construction contracts.
- ECHA additive scrutiny:REACH registration requirements intensify disclosure burdens for plasticizers and stabilizers, extending compliance timelines and raising testing expenditures.
- Aluminum composite panel substitution:Metal facade systems compete on fire rating performance in high-rise applications where WPC faces height restrictions.
Strategic Opportunities
- Benelux facade channel expansion:Profile system integrators seek WPC alternatives to PVC for commercial cladding, opening specification pathways in Belgium and Netherlands.
- Municipal landscaping mandates:Italian and Spanish public infrastructure tenders increasingly require recycled-content thresholds for boardwalks and park furniture.
- Bio-based polymer convergence:Compounders blending PLA with conventional thermoplastics capture premium positioning in architectural specifications targeting carbon neutrality.
Industry Challenges
- CPR certification timeline compression:CE marking under Construction Products Regulation demands extended fire performance testing, delaying product launches by 8-12 months.
- Extrusion technician scarcity:Specialized knowledge in fiber dispersion and die design concentrates among aging workforces in Germany and Austria.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wood-Plastic Composite (WPC) Market |
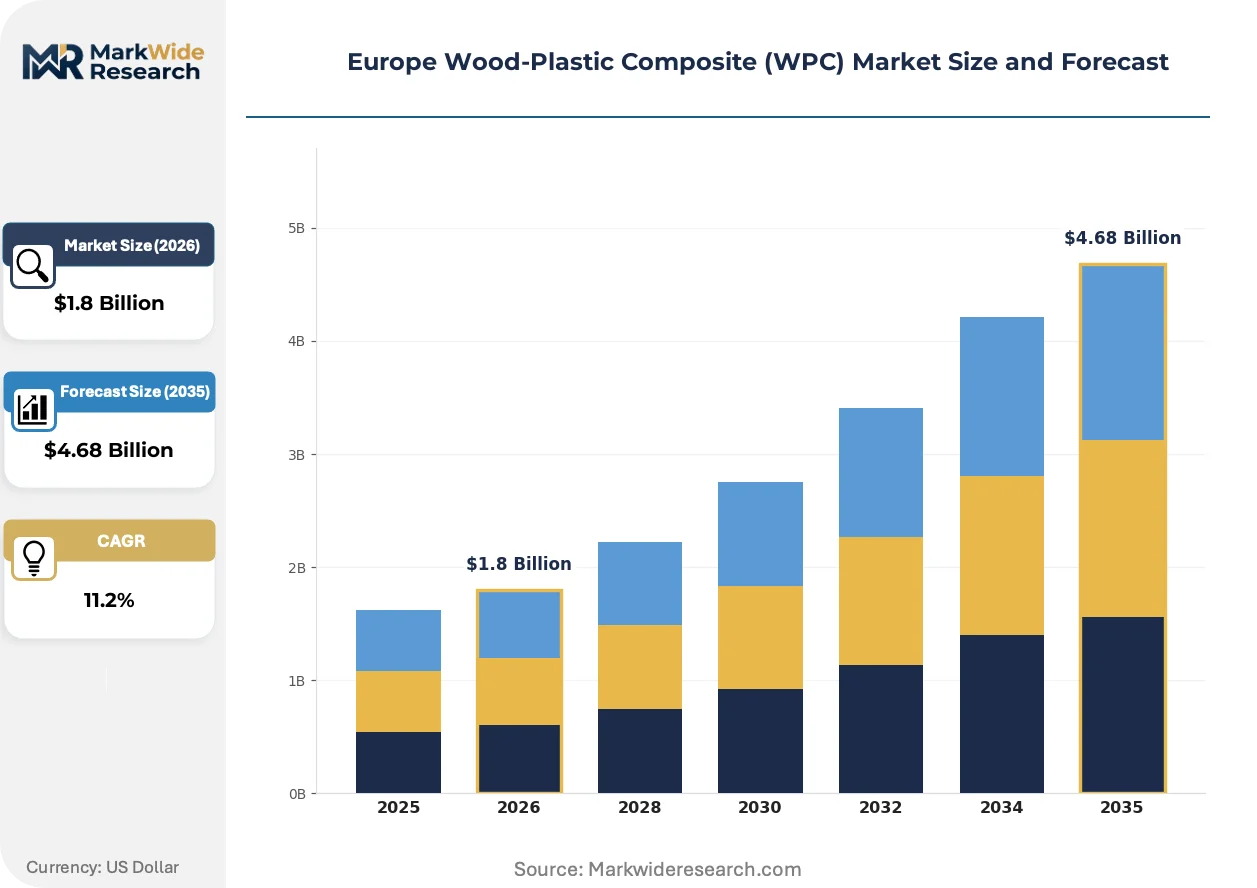
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.68 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decking, Fencing, Railings, Siding Application: Residential, Commercial, Industrial, Landscaping End User: Builders, Contractors, Distributors, Homeowners Material: Recycled Wood, Virgin Plastic, Natural Fibers, Additives |
| Companies Covered | Deceuninck, FKuR Kunststoff GmbH, Trex Company, Inc., NOVO-TECH GmbH & Co. KG, Silvadec, The AZEK Company Inc. (TimberTech), UPM, Beologic, Fortune Brands Innovations, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wood-Plastic Composite (WPC) Market Shifts & Advancements
Formulation chemistry and certification protocols are diverging competitive positioning, with premium architectural specifications separating from commodity decking on traceability and carbon accounting dimensions.
Co-extrusion capstock technology is integrating advanced UV stabilizers and colorfast pigments into outer layers, protecting recycled-core formulations from photodegradation. Italian facade specialists adopt these systems for south-facing commercial installations. The technology is integrating moisture management and thermal expansion control into specification-grade products that command pricing premiums over monolayer alternatives.
REACH registration requirements are tightening disclosure protocols for plastic additive migration, forcing compounders to reformulate stabilizer packages. ECHA scrutiny extends to legacy phthalate replacements, accelerating shifts toward bio-based plasticizers. German extruders face the steepest compliance burdens, with documentation demands compressing R&D cycles for new color and texture introductions.
Specification-driven procurement now dominates premium residential and commercial channels, with architects and developers demanding Environmental Product Declarations before tender submission. Distributors respond by building certification libraries and technical support capabilities that commodity resellers cannot replicate. This pattern concentrates most visibly in France and Germany, where RE2020 and federal building codes harden procurement criteria.
Europe Wood-Plastic Composite (WPC) Market Segmentation
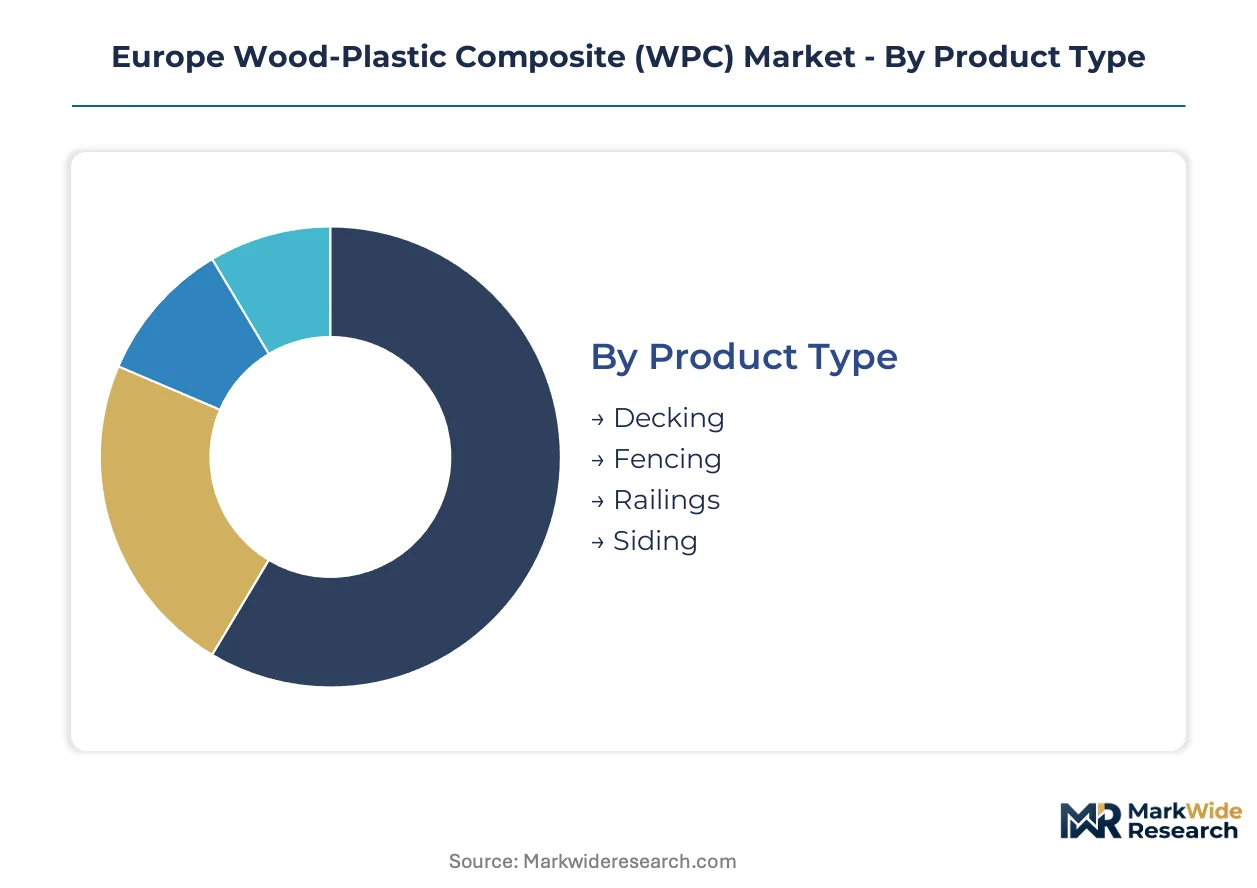
Certification requirements under REACH and the Construction Products Regulation fragment demand across product tiers, with CE-marked structural applications commanding specification premiums over decorative alternatives. Material composition and end-user procurement authority determine which segments absorb compliance costs versus passing them downstream.
Product Type:
CE marking under CPR creates a two-tier compliance landscape: load-bearing decking and railing systems require extended fire performance testing, while fencing and decorative siding operate under lighter disclosure protocols.
- Decking:Extruded boards bearing 50-70% wood flour loading serve exterior residential platforms and municipal boardwalks. German builders in the Rhine-Ruhr corridor concentrate procurement of certified systems, with RE2020 regulations in France accelerating substitution of tropical hardwoods.
- Railings:Structural balustrade systems demand reinforced polymer matrices and impact-resistant formulations for height-coded installations. ECHA scrutiny of plasticizer migration forces reformulation of stabilizer packages, extending R&D cycles for color and texture introductions.
- Fencing:Privacy and perimeter systems utilize lower fiber loadings with decorative surface treatments. Italian agricultural and residential estates drive Mediterranean demand for moisture-resistant profiles.
- Siding:Facade cladding competes against aluminum composite panels on fire rating performance, with Benelux commercial projects opening specification pathways for WPC alternatives to PVC.
Decking sits at the top of the volume ranking, with siding climbing the fastest.
Application:
Cost tier stratification separates specification-grade commercial installations from price-sensitive residential retrofit projects, with municipal landscaping occupying a middle tier on recycled-content mandates.
- Residential:Single-family and multi-unit housing drive absolute consumption through decking and railing replacement cycles. French RE2020 environmental regulation mandates lower carbon intensity in construction materials, accelerating specification of recycled-content formulations.
- Commercial:Office parks, retail facades, and hospitality installations demand co-extruded capstock technology with advanced UV stabilizers. Italian facade specialists adopt these systems for south-facing installations, commanding pricing premiums over monolayer alternatives.
- Industrial:Warehousing and logistics facilities utilize heavy-duty decking for elevated platforms and walkways. REACH registration requirements tighten additive disclosure protocols for stabilizers in high-traffic load-bearing applications.
- Landscaping:Public parks, boardwalks, and recreational infrastructure represent the fastest-expanding specification channel. Italian and Spanish municipal tenders increasingly require recycled-content thresholds, opening volume anchors for compounders with certified supply chains.
Residential captures the dominant revenue share, with landscaping expanding most quickly on public procurement mandates.
End User:
Procurement authority concentrates among professional intermediaries, with homeowners relegated to distributor-sourced retrofit projects lacking specification-grade certification requirements.
- Builders:Large-scale residential developers in Germany and France consolidate demand for CE-marked decking systems. Federal building codes and RE2020 harden procurement criteria, requiring Environmental Product Declarations before tender submission.
- Contractors:Installation specialists bridge specification and execution, with extrusion technician scarcity in Germany and Austria limiting service capacity for complex facade projects.
- Distributors:Building material merchants respond to architect-driven certification demands by building technical support capabilities that commodity resellers cannot replicate.
- Homeowners:Retail-channel consumers prioritize aesthetics and immediate availability over traceability documentation, purchasing through DIY networks for garden decking and fencing.
Builders command the specification pipeline, with distributors gaining share fastest on certification library investments.
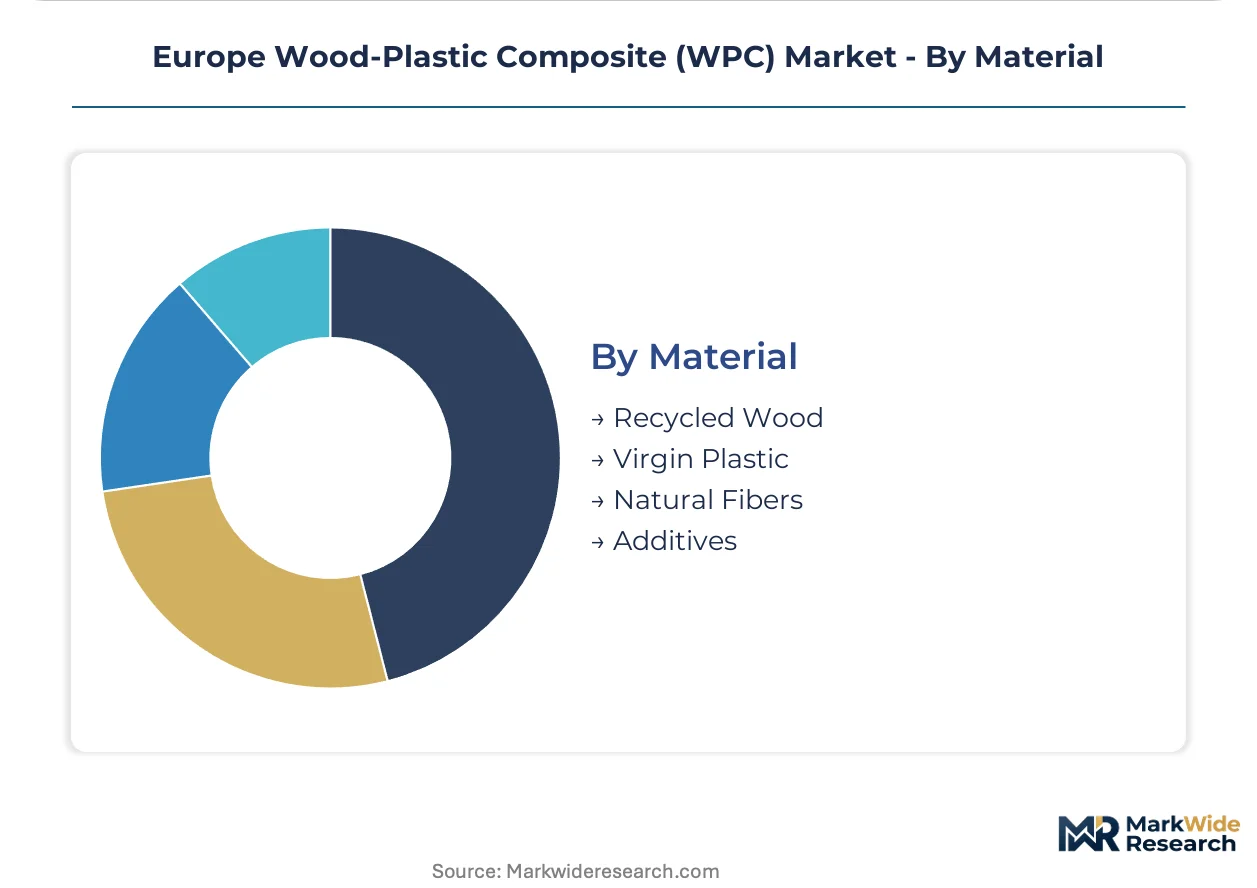
Material:
Margin pools concentrate upstream in feedstock control, with virgin polymer pricing volatility compressing compounder economics while recycled-content formulations capture premium positioning on carbon accounting dimensions.
- Recycled Wood:Sawmill residues and post-industrial fiber streams anchor sustainability claims for specification-grade products. Silvadec's integrated sawmill-to-extrusion operations demonstrate quality control advantages in fiber sourcing.
- Virgin Plastic:Polyethylene and polypropylene matrices provide consistent processing characteristics for high-volume decking production. Crude-linked resin cost swings compress margins for producers locked into fixed-price construction contracts.
- Natural Fibers:Hemp, flax, and rice husk alternatives to wood flour enable bio-based positioning in architectural specifications targeting carbon neutrality.
- Additives:UV stabilizers, colorants, and coupling agents determine surface durability and moisture resistance. ECHA scrutiny of legacy phthalate replacements accelerates shifts toward bio-based plasticizers.
Recycled wood leads volume consumption, with natural fibers gaining share fastest on bio-based polymer convergence trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints across Europe, with compounders migrating capacity toward jurisdictions offering streamlined REACH compliance pathways and proximity to certified fiber supply chains. The EU Green Deal's embodied carbon benchmarks create compliance-cost gaps that favor integrated operations in Benelux and German federal states with established recycling infrastructure.
Germany
Rhine-Ruhr corridor builders concentrate procurement of CE-marked decking systems for specification-grade residential developments. Federal building codes under the Construction Products Regulation mandate extended fire performance testing, compressing certification timelines for structural applications. Bavarian extrusion specialists advance natural fiber loading optimization techniques, pushing wood flour content toward upper technical limits.
France
RE2020 environmental regulation mandates lower carbon intensity in construction materials, accelerating substitution of tropical hardwoods with recycled-content WPC in residential facades. Île-de-France architects demand Environmental Product Declarations before tender submission, hardening procurement criteria for commercial landscaping projects. Auvergne-Rhône-Alpes compounders serve specification channels through co-extruded capstock technology with advanced UV stabilizers.
Italy
Municipal landscaping tenders increasingly require recycled-content thresholds for boardwalks and park furniture across Lombardy and Veneto. Italian facade specialists adopt co-extrusion systems for south-facing commercial installations, commanding pricing premiums over monolayer alternatives. Emilia-Romagna distributors build certification libraries to serve architect-driven procurement in premium residential channels.
Netherlands
Profile system integrators in the Randstad region seek WPC alternatives to PVC for commercial cladding applications. Benelux facade channel expansion opens specification pathways where REACH registration requirements have already streamlined additive disclosure protocols. Eindhoven-area compounders leverage proximity to German fiber suppliers for just-in-time extrusion operations.
Spain
Andalusian and Catalan public infrastructure tenders incorporate recycled-content mandates for recreational decking and perimeter fencing. Spanish municipal projects absorb volume from compounders with certified supply chains extending into Portuguese fiber markets. Madrid-based distributors respond to specification demands by building technical support capabilities for commercial landscaping installations.
Europe Wood-Plastic Composite (WPC) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based polymer convergence and architectural specification channels. The vendor base stratifies across integrated sawmill-to-extrusion operators, profile system specialists, and custom biopolymer compounders serving premium segments. Three archetypes dominate: fiber-integrated manufacturers controlling upstream sourcing, formulation specialists advancing loading optimization, and distribution-anchored integrators capturing specification pipelines. Capacity expansion and certification library investments represent the dominant competitive moves, with players building EPD documentation capabilities to secure tender participation.
Among Belgian and German fabricators, Deceuninck and FKuR Kunststoff GmbH occupy positions within the profile systems and custom biopolymer tiers respectively. Silvadec exemplifies the integrated sawmill-to-extrusion archetype through its captive fiber sourcing model. These three anchors represent divergent strategic pathways: distribution-led specification capture, formulation-led premium positioning, and backward integration into raw material control.
| Leading Market Players |
|---|
| Deceuninck |
| FKuR Kunststoff GmbH |
| Trex Company, Inc. |
| NOVO-TECH GmbH & Co. KG |
| Silvadec |
| The AZEK Company Inc. (TimberTech) |
| UPM |
| Beologic |
| Fortune Brands Innovations, Inc. |
| Others |
Supply & Pricing Matrix
Co-extrusion capstock adoption across Benelux and French facade channels simultaneously elevates production cost structures and concentrates supply among compounders with in-house compounding capabilities. REACH additive disclosure burdens and ECHA scrutiny on stabilizer packages compound this dynamic, forcing smaller extruders toward toll-manufacturing arrangements that cede margin to integrated operators.
Pricing Analysis
Distributor margin capture in specification-grade channels runs 18-25 points above DIY retail, reflecting certification library investments and technical support capabilities that commodity resellers cannot replicate. Three-tier pricing structure across premium architectural, standard residential, and economy fencing levels separates products on CE marking status and EPD documentation completeness. Cost compression in standard-grade decking intensifies as polypropylene price volatility squeezes compounders locked into fixed-price construction contracts. Homeowners purchasing through retail channels exhibit highest price sensitivity, while Rhine-Ruhr corridor builders accept specification premiums for CPR-certified structural systems.
Supply Chain Analysis
CE marking and REACH registration requirements gate supply participation, filtering compounders without documentation capabilities toward decorative segments with lighter compliance burdens. Manufacturing gravity centers on Germany, France, and Belgium, with Bavarian extrusion specialists and Auvergne-Rhône-Alpes compounders anchoring premium output. Raw material sourcing draws from Nordic sawmill residues for fiber streams and Rotterdam-Antwerp petrochemical corridors for polymer matrices. Single-source vulnerability concentrates in specialized coupling agents and UV stabilizer packages subject to ECHA additive scrutiny. Distribution runs through building material merchants in specification channels and DIY networks for retail-grade products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory-arbitrage dynamics position Benelux compounders advantageously against German counterparts facing steeper REACH compliance timelines, creating cost-structure differentials that reshape competitive positioning across the region.
For Market Incumbents: Extend certification library investments to capture municipal landscaping mandates in Italy and Spain before specification requirements harden. Backward integration into sawmill operations, following Silvadec's captive fiber model, defends margin position against polypropylene price volatility. Capacity expansion in Netherlands and Belgium exploits streamlined REACH pathways while German facilities absorb technical R&D for next-generation bio-based formulations.
For New Entrants and Emerging Players: The premium-to-economy price gap in facade cladding offers entry traction for compounders with co-extrusion capabilities targeting Benelux commercial projects. Municipal boardwalk tenders across Lombardy and Veneto represent the most penetrable specification channel, with recycled-content thresholds still below full EPD requirements. Direct architect engagement through distributor partnerships bypasses incumbent builder relationships that dominate residential decking procurement.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier extruders lacking CE marking capabilities but holding established fiber supply relationships. Long-term viability hinges on regulatory compliance infrastructure rather than scale alone, favoring targets with documented REACH registration histories. The signal to watch is ECHA expansion of additive scrutiny to bio-based plasticizer categories, which would compress R&D cycles and favor acquirers with existing formulation expertise.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Supply | Captive sawmill operations in France and Germany insulate Silvadec and peers from Nordic fiber price volatility. |
| Co-Extrusion Capacity Expansion | Auvergne-Rhône-Alpes and Benelux facilities capture premium facade specifications requiring advanced UV stabilizer integration. |
| REACH Registration Acceleration | Early ECHA compliance for bio-based plasticizers positions FKuR and German compounders ahead of disclosure deadline compression. |
| EPD Documentation Investment | Certification libraries enable Deceuninck and distributors to meet RE2020 tender requirements in French commercial channels. |
| Municipal Tender Pre-Qualification | Italian and Spanish landscaping mandates create volume anchors for compounders with verified recycled-content supply chains. |
Research Methodology
Multiple input streams — extrusion plant manager interviews, downstream builder procurement surveys, customs and trade flow databases, and ECHA regulatory filings — were reconciled to construct demand and supply estimates. Primary fieldwork engaged compounder technical directors, distributor category managers, architect specification consultants, and municipal tender officers across Germany, France, Italy, Netherlands, and Spain. Secondary validation drew from Construction Products Regulation implementation reports, EU Green Deal embodied carbon benchmarking studies, REACH registration databases, and national building code amendments. Bottom-up volume modeling by product type and application was cross-checked against top-down macroeconomic indicators and construction sector forecasts.
Historical shipment data was cross-referenced against expert panel inputs from industry associations and regulatory affairs specialists to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated product type, application channel, material composition, and national regulatory cluster dimensions. CAGRs were derived from trend extrapolation adjusted for policy inflection points including RE2020 enforcement phases and anticipated ECHA additive disclosure expansions. Industry-specific forecast inputs included wood flour loading optimization curves, co-extrusion adoption rates in commercial facade channels, and municipal recycled-content mandate implementation timelines.
The model assumes a particular technology adoption path for co-extrusion capstock systems; alternative pathways favoring monolayer formulations with surface treatment alternatives would alter the outlook for premium pricing capture. Forecasts reflect assumptions regarding REACH compliance timeline adherence and EU Green Deal carbon accounting standardization that may shift with regulatory enforcement intensity. A model refresh is warranted upon material change in ECHA additive scrutiny scope or federal building code amendments in Germany and France.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Lignin-Based Graphene Market
Composite Materials
Molded Underfill Material Market
Composite Materials
Asia-Pacific Molded FRP Grating Market
Composite Materials
Composite Adhesives Market
Composite Materials
Composites Distributor Market
Composite Materials
Fiber Reinforced Plastic (FRP) Panels and Sheets Market
Composite Materials
Global Wind Turbine Composites Material Market
Composite Materials
Polypropylene and Polypropylene Composites Market
Composite Materials
Transportation Composites Market
Composite Materials
Composite Preforms Market
Composite Materials
Global Thermoplastic Composites Market
Composite Materials
Carbon Fiber Composites Market
Composite Materials
Organosheet and Semi-Finished Thermoplastic UD-Tape Laminate Market
Composite Materials
Synthetic Rope Market
Composite Materials
Global Carbon Fiber Reinforced Plastic Market
Composite Materials
Global Sports Composites Market