
 Compression Gas Spring Market | 2026-2036
Compression Gas Spring Market Size, Share, and Industry Trends Forecast 2026-2036
Compression Gas Spring Market Outlook
The compression gas spring market is recalibrating around a widening performance gap between precision-engineered premium units and standardized commodity springs. Stabilus leverages its vertical integration across nitrogen charging and seal manufacturing to command premium positioning in automotive seating. Suspa GmbH anchors its competitiveness through specialized heavy-duty spring portfolios for industrial automation, while Hahn Gasfedern GmbH dominates niche medical equipment applications with validated cleanroom-compatible production.
A compression gas spring is a self-contained hydro-pneumatic cylinder that stores energy via compressed nitrogen gas and transmits force through a piston rod, typically operating at pressures between 20 and 300 bar depending on load requirements. Its primary purpose is to provide controlled, damped motion for lifting, lowering, or positioning applications across industrial and consumer equipment. Dynamic springs lead product type demand due to their integration into adjustable automotive seating and hospital beds where repeated cycling is required. Aerospace components represent the fastest-growing application segment as airframers specify lighter titanium-alloy variants to reduce mass in cabin interiors. OEMs capture the dominant end-user value pool through long-term supply agreements with tier-one seating suppliers.
Regulatory frameworks including ECE R14 for automotive seat anchorage strength, FDA 21 CFR Part 820 for medical device quality systems, and ISO 9001 for manufacturing consistency collectively shape product certification requirements and market access barriers. REACH compliance in Europe and RoHS substance restrictions further constrain seal material selection and surface coating chemistry for export-bound manufacturers. Stakeholders must monitor evolving fatigue-test protocols from NHTSA and EMA as these agencies tighten lifecycle validation standards for safety-critical spring applications.
Market Dynamics
OEM fatigue-life mandates under ECE R14 and GB/T 25751 are forcing tier-one suppliers to source dynamic gas springs with validated nitrogen-charging protocols, compressing supplier qualification timelines from eighteen to six months. This regulatory compression is redrawing competitive boundaries between vertically integrated nitrogen processors and seal specialists.
Growth Catalysts
- Automotive seating fatigue standards:ECE R14 and GB/T 25751 enforcement in Germany and China is accelerating replacement cycles for legacy mechanical springs in adjustable seat mechanisms.
- Medical device quality systems:FDA 21 CFR Part 820 compliance requirements for patient positioning equipment are pulling validated cleanroom-compatible nitrogen springs into hospital procurement specifications.
- Titanium-alloy lightweighting:Aerospace cabin interior mass reduction targets are expanding specification of titanium piston rod variants for overhead bin and galley applications.
Market Restraints
- Seal material input volatility:Fluorocarbon elastomer prices fluctuate with perfluorinated chemical feedstock availability, compressing margin predictability for mid-tier assemblers.
- Specialized charging equipment concentration:High-pressure nitrogen charging infrastructure clusters in Germany, Japan, and the US, creating geographic supply bottlenecks for emerging market manufacturers.
- Electromechanical actuator substitution:Linear motor systems with position feedback are displacing gas springs in precision industrial automation where programmability outweighs passive damping benefits.
Strategic Opportunities
- Underpenetrated Indian medical equipment:CDSCO regulatory alignment with ISO 13485 is opening procurement pathways for validated gas springs in domestic diagnostic imaging table manufacturing.
- EU F-Gas Regulation compliance services:Seal material reformulation to eliminate HFC-based processing aids creates advisory revenue streams for technical compliance support.
- Sensor-integrated smart springs:Convergence of pressure transducers with gas spring bodies enables predictive maintenance contracts in automated warehouse racking systems.
Industry Challenges
- High-pressure welding certification scarcity:Qualified orbital TIG welders for 300-bar cylinder construction command premium wages, constraining capacity expansion at specialty manufacturers.
- Multi-agency approval timelines:Simultaneous FDA 510(k) and CE MDR submissions for medical gas springs extend time-to-revenue by fourteen to twenty-two months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compression Gas Spring Market |
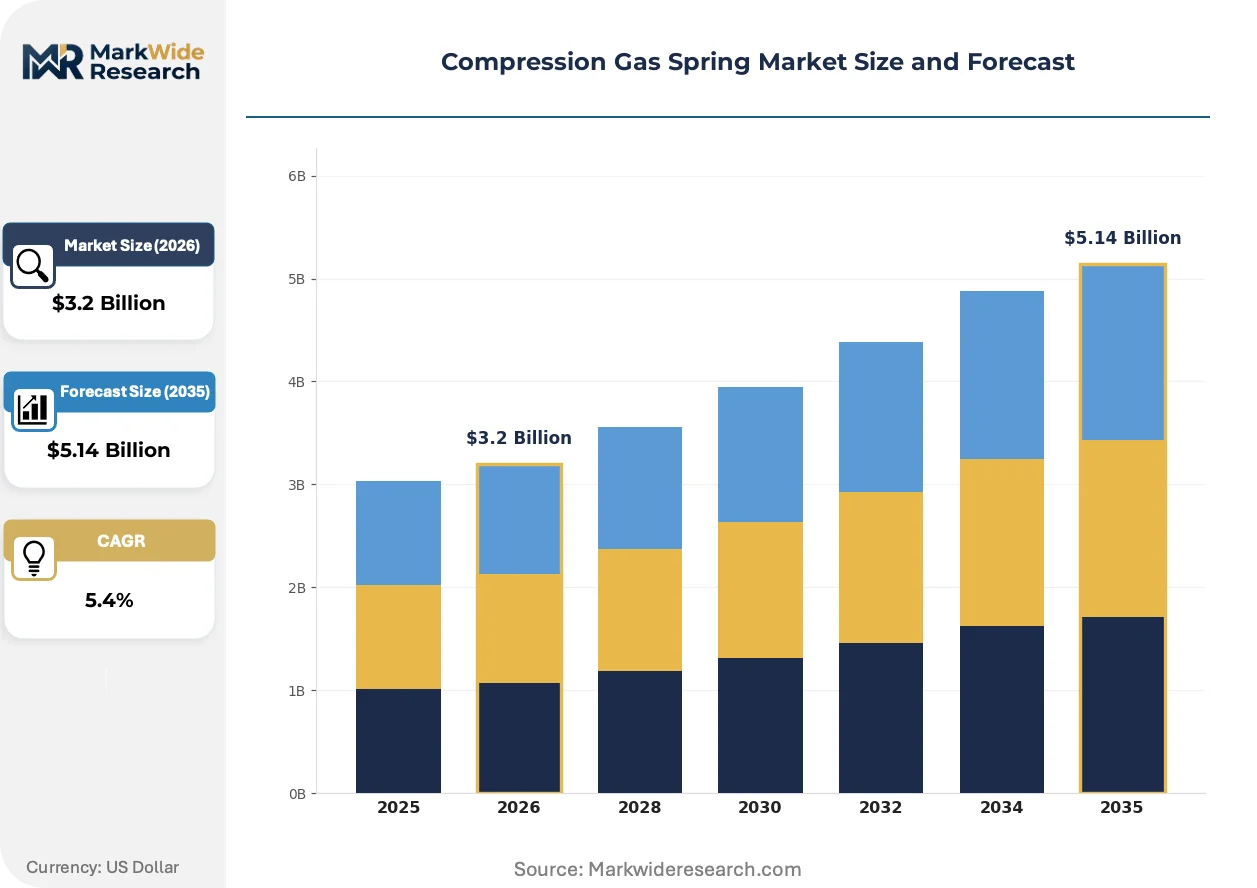
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.14 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dynamic Springs, Static Springs, Heavy-Duty Springs, Light-Duty Springs Application: Automotive Seating, Medical Equipment, Furniture, Aerospace Components End User: OEMs, Aftermarket Suppliers, Manufacturers, Distributors Installation Type: Integral, Modular, Removable, Fixed |
| Companies Covered | Stabilus, ACE Controls Inc., Suspa GmbH, Bansbach Easylift, Hahn Gasfedern GmbH, Weforma Dämpfungstechnik GmbH, Dictator Technik GmbH, AVM Industries, LANTAN gas spring Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compression Gas Spring Market Strategic Shifts
Active materials substitution and embedded sensing capabilities are redefining performance benchmarks across automotive, aerospace, and medical verticals. Suppliers now compete on validated cycle counts and traceable nitrogen purity rather than unit cost alone.
Titanium-alloy piston rod fabrication is expanding into aerospace cabin interiors where mass reduction targets exceed ten percent per seating row. Airframers at Boeing and Airbus specification committees are qualifying these variants for overhead bin lift mechanisms and crew rest compartment doors. This materials shift is compressing the addressable market for standard steel-rod springs in premium aerospace applications.
REACH substance restrictions on perfluorinated compounds are forcing seal compound reformulation across European supply chains. ECHA enforcement of updated candidate list entries is disqualifying legacy fluoroelastomer grades from export-bound medical equipment. German and Swiss manufacturers are responding with hydrogenated nitrile alternatives validated to ten million cycles.
Hospital procurement departments are consolidating vendor lists around FDA-cleared suppliers with ISO 13485 quality system documentation. Group purchasing organizations are displacing fragmented distributor networks with direct manufacturer contracts tied to validated batch records. This concentration is most visible in US academic medical centers where patient positioning system standardization reduces clinical engineering overhead.
Compression Gas Spring Market Segmentation
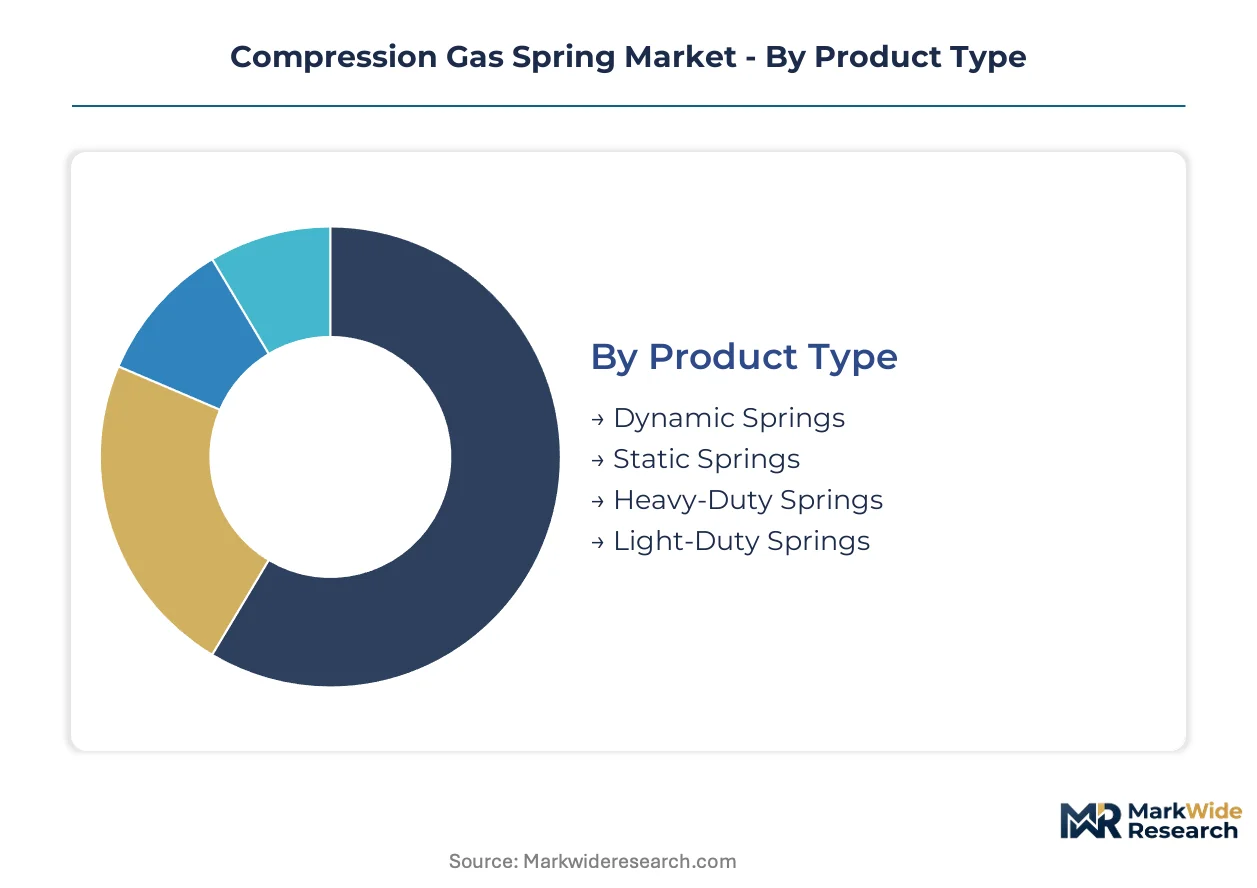
Compression gas spring procurement decisions hinge on validated cycle counts and regulatory certification tiers rather than unit economics alone. Buyers segment suppliers by nitrogen-charging protocol precision and fatigue-test documentation depth.
Product Type:
Buyers prioritize cycle-life validation and pressure stability when selecting spring configurations for safety-critical installations.
- Dynamic Springs:Self-contained hydro-pneumatic cylinders engineered for repeated actuation cycles between 20 and 300 bar. Automotive seating manufacturers in Germany and China specify these for adjustable seat mechanisms under ECE R14 and GB/T 25751 fatigue mandates.
- Heavy-Duty Springs:Reinforced cylinder constructions rated for sustained high-load industrial environments. Suspa GmbH anchors its portfolio in this tier for factory automation where 10-million-cycle validation is standard procurement specification.
- Static Springs:Fixed-position nitrogen-charged units for non-cyclic load support. Furniture OEMs specify these for cabinet lift mechanisms where cost sensitivity outweighs fatigue documentation requirements.
- Light-Duty Springs:Compact variants for consumer-grade positioning tasks. Office furniture assemblers source these through distributor networks with minimal certification overhead.
Volume sits with Dynamic Springs; growth tilts toward Heavy-Duty Springs.
Application:
Regulatory stringency varies sharply across end-use environments, creating tiered certification barriers that reshape supplier qualification.
- Automotive Seating:Precision-engineered seat adjustment mechanisms requiring validated nitrogen purity and traceable batch records. Tier-one suppliers face compressed qualification timelines from eighteen to six months under OEM mandate enforcement.
- Medical Equipment:FDA-cleared patient positioning systems demanding cleanroom-compatible production and ISO 13485 quality system documentation. Hahn Gasfedern GmbH dominates this niche with validated cycle-count transparency.
- Furniture:Consumer and commercial fixture applications with lower certification thresholds. Mass-market producers source through fragmented distributor channels with price-primary selection criteria.
- Aerospace Components:Titanium-alloy piston rod variants for cabin interior mass reduction. Boeing and Airbus specification committees are qualifying these for overhead bin and galley lift mechanisms.
Revenue concentrates in Automotive Seating; Aerospace Components are climbing the fastest.
End User:
Contract structure and technical specification authority determine supplier relationship depth across the value chain.
- OEMs:Original equipment manufacturers with direct engineering specification authority and long-term supply agreement frameworks. These buyers capture the dominant value pool through tier-one seating supplier partnerships.
- Manufacturers:Mid-tier production assemblers with delegated procurement authority. Hospital procurement departments in US academic medical centers are consolidating vendor lists around this buyer type with ISO 13485 requirements.
- Aftermarket Suppliers:Replacement part distributors serving repair and refurbishment channels. These buyers prioritize inventory velocity over cycle-count documentation.
- Distributors:Intermediary networks with limited technical specification influence. Furniture and light industrial segments rely on these channels for transactional procurement.
Specification authority rests with OEMs; procurement consolidation favors Manufacturers.
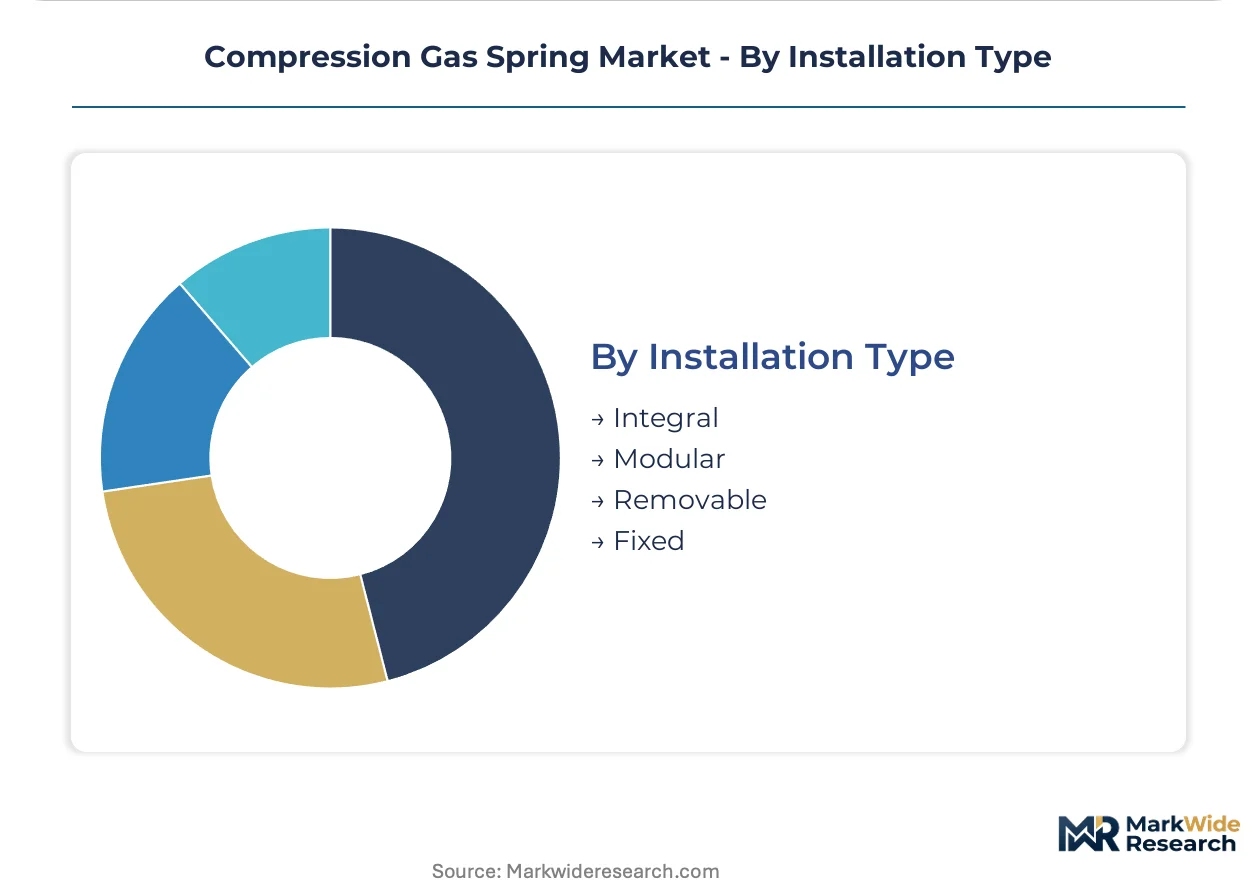
Installation Type:
System architecture decisions determine field serviceability requirements and total cost of ownership calculations.
- Integral:Permanently embedded spring assemblies with no field replacement capability. Aerospace cabin interiors specify these for galley applications where weight minimization overrides maintenance access.
- Modular:Standardized interface designs enabling rapid component swap without system disassembly. Automated warehouse racking systems favor this architecture for predictive maintenance integration.
- Removable:Tool-free detachment mechanisms for scheduled replacement cycles. Medical equipment manufacturers specify these for patient positioning tables under FDA 21 CFR Part 820 serviceability requirements.
- Fixed:Permanent mounting configurations with replacement requiring complete unit decommissioning. Legacy industrial automation retains this architecture where retrofit economics are unfavorable.
Deployment volume favors Modular; specification momentum shifts toward Removable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors global production gravity for precision gas spring manufacturing, with the Neckar-Alb region hosting clustered nitrogen-charging facilities and seal compound specialists that supply tier-one automotive seating programs across three continents.
Germany
Automotive OEMs in Stuttgart and Munich enforce ECE R14 fatigue mandates that compress supplier qualification timelines from eighteen to six months. KBA oversight of seat anchorage certification creates compliance barriers for non-integrated manufacturers. The Neckar-Alb industrial corridor concentrates orbital TIG welding capacity for 300-bar cylinder construction.
China
Domestic medical equipment manufacturers in Shanghai and Suzhou source validated nitrogen springs under GB/T 25751 alignment with international fatigue protocols. NMPA device quality system inspections accelerate procurement consolidation around ISO 13485-certified suppliers. The Yangtze River Delta hosts clustered high-pressure charging infrastructure serving both automotive and hospital bed producers.
United States
FDA 510(k) clearance requirements for patient positioning systems pull validated cleanroom-compatible springs into academic medical center procurement specifications. NHTSA lifecycle validation protocols for safety-critical applications tighten documentation standards. The Great Lakes manufacturing belt retains heavy-duty spring fabrication for automated warehouse racking systems.
Japan
PMDA quality system inspections for diagnostic imaging tables create procurement pathways for cycle-validated nitrogen springs. METI industrial automation standards favor modular spring architectures with predictive maintenance integration. The Nagoya industrial zone concentrates titanium-alloy piston rod machining for aerospace cabin interior applications.
India
CDSCO regulatory alignment with ISO 13485 opens domestic manufacturing for diagnostic imaging table gas springs. BIS certification requirements for automotive components accelerate local sourcing mandates from multinational seating suppliers. The Pune-Aurangabad industrial corridor attracts nitrogen-charging equipment investments to reduce import dependence.
Compression Gas Spring Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and cycle-count validation tiers. The vendor base organizes around three strategic archetypes: vertically integrated nitrogen processors capturing automotive seating contracts, specialized heavy-duty fabricators serving industrial automation, and cleanroom-certified specialists anchoring medical equipment supply chains. Dominant competitive moves include backward integration into seal compound manufacturing and geographic expansion of high-pressure charging infrastructure into underpenetrated Asian markets.
Among German-based fabricators, Stabilus GmbH and Suspa GmbH occupy positions at opposite ends of the specialization spectrum, with the former exemplifying scale-driven nitrogen integration and the latter representing heavy-duty cycle-validation expertise. Hahn Gasfedern GmbH anchors the cleanroom-certified medical tier. ACE Controls Inc. sits within the North American automation-focused archetype alongside Dictator Technik GmbH, which represents European precision-engineering lineage. Chinese manufacturers including LANTAN gas spring Co., Ltd. and AVM Industries exemplify cost-optimized production capacity serving furniture and light industrial segments.
| Leading Market Players |
|---|
| Stabilus |
| ACE Controls Inc. |
| Suspa GmbH |
| Bansbach Easylift |
| Hahn Gasfedern GmbH |
| Weforma Dämpfungstechnik GmbH |
| Dictator Technik GmbH |
| AVM Industries |
| LANTAN gas spring Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Fluorocarbon elastomer feedstock volatility cascades through three distinct pricing tiers, with perfluorinated compound costs compressing margins at mid-tier assemblers while vertically integrated nitrogen processors in Germany and Japan capture premium positioning through captive seal manufacturing.
Pricing Analysis
Validated cycle-count guarantees anchor value-based pricing for safety-critical applications, with FDA-cleared medical springs commanding substantial premiums over furniture-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels separates ECE R14-certified automotive seating springs from GB/T 25751-aligned Chinese variants and uncertified commodity units. Cost compression in mid-tier industrial segments is intensifying because fluorocarbon elastomer prices fluctuate with feedstock availability. Furniture OEMs exhibit the highest price sensitivity, while hospital procurement departments prioritize validated batch records over unit economics.
Supply Chain Analysis
BIS certification requirements for automotive components and CDSCO alignment with ISO 13485 are reshaping sourcing patterns toward domestic nitrogen-charging infrastructure in India and China. Geographic supply concentration centers on Germany, Japan, and the United States, where high-pressure charging equipment clusters around Stuttgart, Nagoya, and the Great Lakes manufacturing belt. Raw material dependencies draw from titanium-alloy rod stock, fluorocarbon and hydrogenated nitrile seal compounds, and high-purity nitrogen feedstock. Single-source vulnerability persists in orbital TIG welding certification for 300-bar cylinder construction. Distribution runs through tier-one seating suppliers for automotive, direct manufacturer contracts for medical equipment, and fragmented distributor networks for furniture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where ECE R14 and FDA 21 CFR Part 820 certification requirements create formidable barrier-to-entry moats for validated players, permanently excluding commodity assemblers from safety-critical value pools.
For Market Incumbents: Extend backward integration into seal compound manufacturing to secure fluorocarbon elastomer supply against REACH substance restrictions. Anchor capacity expansion in the Pune-Aurangabad corridor to capture BIS-mandated local content requirements from multinational seating suppliers. Electromechanical actuator substitution in precision automation represents the primary displacement threat requiring sensor-integrated smart spring development as counterpositioning. For New Entrants and Emerging Players: Enter via CDSCO-aligned diagnostic imaging table manufacturing in India, where ISO 13485 certification gaps among domestic producers create procurement openings for validated nitrogen springs. Target modular installation architectures for automated warehouse racking systems, where predictive maintenance integration contracts remain underpenetrated. Lead with EU F-Gas Regulation compliance advisory services to establish technical credibility before spring fabrication investments. For Investors and Strategic Acquirers: FDA 510(k) clearance timelines stretching fourteen to twenty-two months is the leading indicator that cleanroom-certified medical specialists with validated cycle-count transparency command durable premium multiples. The five-to-ten year viability window favors acquisition targets with captive nitrogen-charging infrastructure and orbital TIG welding certification depth. Monitor NHTSA fatigue-test protocol tightening as the signal for accelerated replacement cycles in automotive seating.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Manufacturing | Captive fluorocarbon compound production insulates margins from ECHA REACH enforcement volatility. |
| High-Pressure Charging Infrastructure Expansion | Geographic diversification into Pune-Aurangabad reduces dependence on German and Japanese equipment clusters. |
| Sensor-Integrated Smart Spring Development | Pressure transducer convergence enables predictive maintenance contracts in METI-aligned automated warehouse systems. |
| Cleanroom Certification Investment | ISO 13485 quality system documentation opens hospital procurement consolidation at US academic medical centers. |
| Titanium-Alloy Piston Rod Qualification | Boeing and Airbus specification committee approval captures aerospace cabin interior lightweighting mandates. |
Study Parameters
Independent corroboration across tier-one seating supplier procurement directors, hospital biomedical engineering managers, aerospace specification committee members, and nitrogen-charging equipment manufacturers underwrites the qualitative findings. Primary interviews with FDA regulatory affairs consultants, ECHA compliance specialists, and automated warehouse maintenance directors combined with secondary validation from ECE R14 test documentation, FDA 510(k) clearance databases, GB/T 25751 certification records, and ISO 13485 audit reports. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Comparable-period anchoring to historical automotive production cycles, medical device capital expenditure patterns, and aerospace delivery backlogs structured the projection horizon across the analysis window. Segmentation dimensions modeled include product type tier, application regulatory stringency, end-user contract structure, and installation architecture serviceability. CAGRs derived from regression analysis of validated cycle-count demand curves and titanium-alloy adoption slopes in cabin interiors. Industry-specific forecast inputs incorporated NHTSA fatigue-test protocol evolution and CDSCO inspection schedule acceleration.
Forecast precision tightens around the base case; tail outcomes carry wider variance under fluorocarbon feedstock disruption, orbital TIG welder wage inflation, or electromechanical actuator substitution acceleration in precision automation. Forecasts reflect documented assumptions regarding ECE R14 enforcement consistency, FDA 510(k) timeline stability, and REACH substance restriction implementation pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Gaskets and Seals Market
Industrial Materials
Industrial Seals Market
Industrial Materials
Encapsulated Gaskets/Seals Market
Industrial Materials
Powder Processing Service Market
Industrial Materials
Asia-Pacific Wood Based Panel Market
Industrial Materials
Petrochemical Fasteners Market
Industrial Materials
Lip Seals Market
Industrial Materials
Industrial Continuous Furnaces Market
Industrial Materials
Global Melamine Market
Industrial Materials
Wood Protein Market
Industrial Materials
Heat Shrink Tubing and Sleeves Market
Industrial Materials
Isostatic Pressing Market
Industrial Materials
Magnet Rings Market
Industrial Materials
Industrial Brushes Market
Industrial Materials
Global Machined Seals Market
Industrial Materials
Tooling Board Market