
 High Speed Dispersers (HSD) Market | 2026-2036
High Speed Dispersers (HSD) Market Size, Share, and Industry Trends Forecast 2026-2036
High Speed Dispersers (HSD) Market Insights
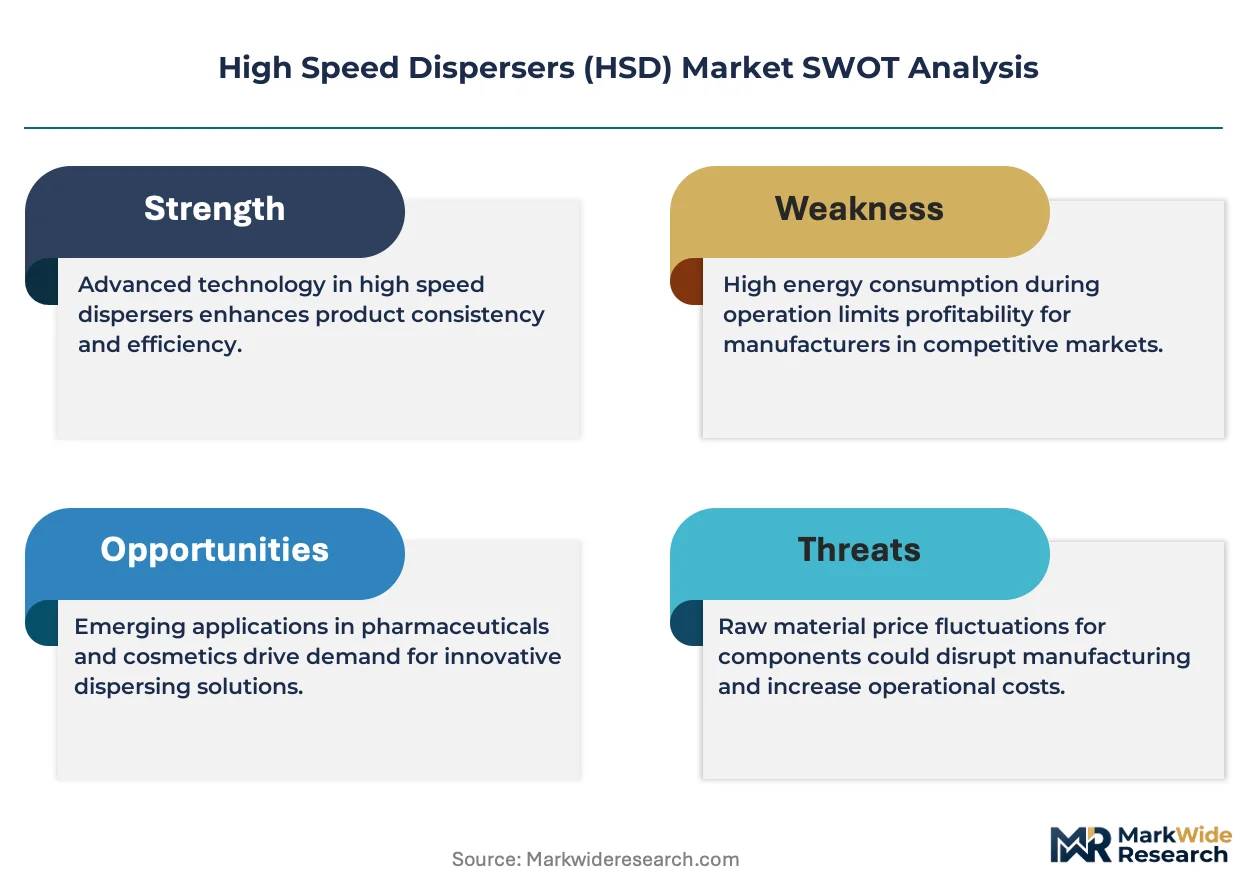
Project finance and equipment leasing is tilting competitive dynamics toward asset-light operators that can scale without heavy balance sheets. SPX FLOW leverages its global service network to sustain recurring revenue from aftermarket parts. Hockmeyer Equipment anchors its position through deep specialization in immersion mill technology for high-viscosity formulations. IKA competes across laboratory and production scales, extending its reach into pharmaceutical validation protocols.
High speed dispersers are rotary mixing systems operating at tip speeds typically exceeding 5,000 feet per minute, employing saw-tooth or slotted impellers to generate intense shear forces that break agglomerates and achieve particle size reduction in liquid matrices. Their primary purpose centers on producing homogeneous dispersions, emulsions, and suspensions for coatings, adhesives, and specialty chemicals where consistency directly determines end-product performance. Industrial dispersers dominate installed capacity due to established demand from batch chemical production, while inline dispersers represent the fastest-expanding category as continuous processing architectures replace traditional tank-based workflows. Electromagnetic technology occupies a narrower but higher-margin niche where precise energy delivery and reduced mechanical wear justify premium positioning against conventional mechanical systems.
EPA emissions standards and OSHA process safety management requirements in the United States shape equipment specifications for hazardous chemical handling, while REACH compliance in Europe restricts certain lubricant and sealant chemistries used in disperser construction. China's GB standards and MIIT energy efficiency directives are raising barriers for imported equipment while creating openings for local manufacturers that certify to domestic protocols. Stakeholders must weigh regulatory divergence against standardization economies when configuring product portfolios for multi-regional deployment.
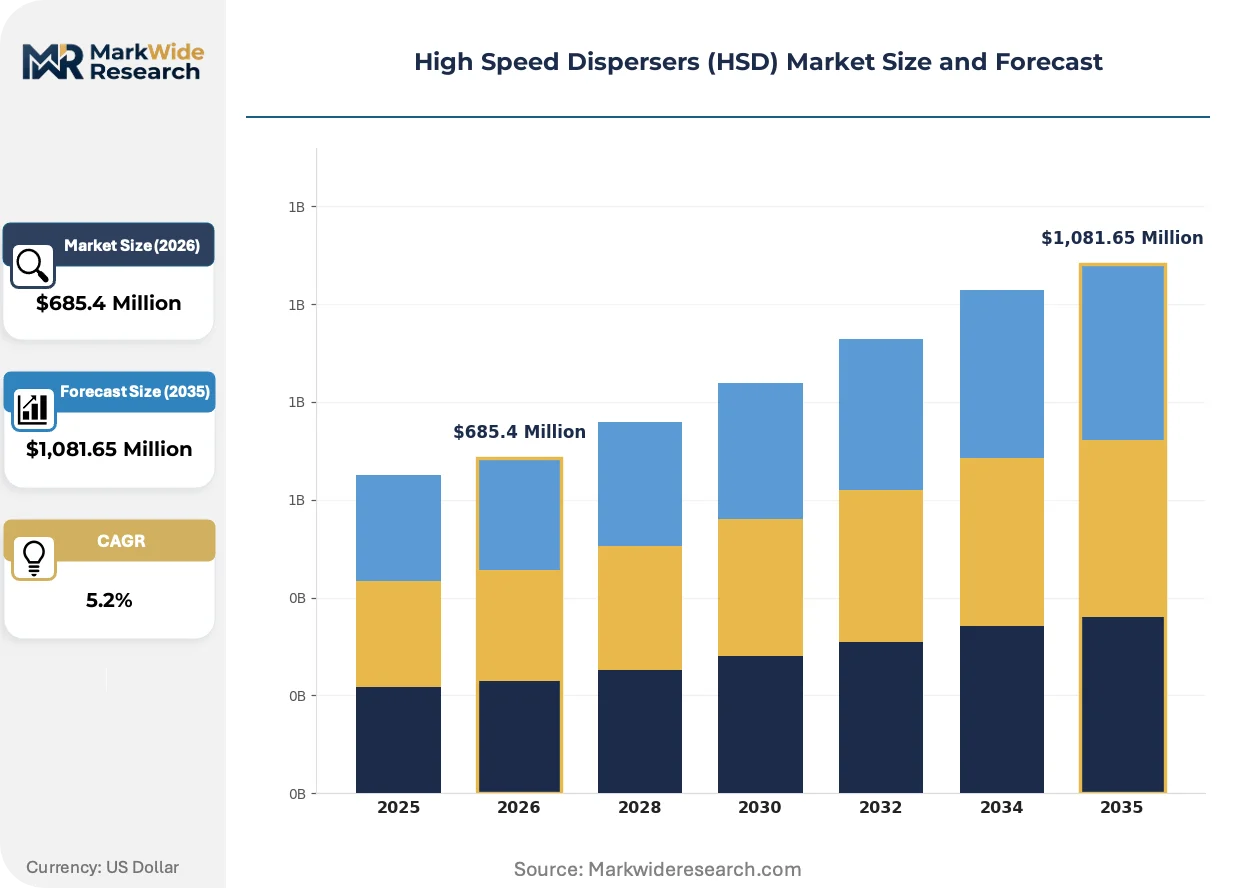
Market Dynamics
Continuous processing architectures are displacing batch tank workflows across chemical manufacturing, compressing equipment footprints while demanding inline disperser configurations that integrate with automated process control systems.
Growth Catalysts
- REACH Phase-Out Restrictions:European coatings manufacturers are retrofitting production lines with closed-system HSD configurations to eliminate solvent emissions and comply with ECHA substance restrictions on volatile organic compounds.
- China's MIIT Energy Efficiency Directives:Domestic chemical processors face mandatory equipment upgrades, creating replacement demand for electromagnetic dispersion systems that reduce power consumption in high-viscosity mixing operations.
- Automotive Electrification:Battery electrode slurry production requires precisely controlled particle dispersion, pulling HSD installations into gigafactory construction pipelines across multiple manufacturing clusters.
Market Restraints
- Specialized Alloy Input Volatility:Hastelloy and duplex stainless steel price swings directly impact vessel and impeller fabrication costs, constraining margin flexibility for equipment fabricators.
- Regional Certification Fragmentation:China's GB standards for explosion-proof electrical components diverge from ATEX and UL classifications, forcing redundant engineering cycles for multinational suppliers.
- Mechanical Seal Degradation:High-solids abrasive formulations accelerate wear in conventional packed-gland designs, elevating maintenance frequency and total cost of ownership for end-users.
Strategic Opportunities
- India's PLI Scheme for Chemicals:Production-linked incentives for specialty chemical manufacturing are stimulating greenfield plant investments that specify imported disperser technology for quality-critical applications.
- Pharmaceutical Continuous Manufacturing:FDA guidance on real-time release testing is collapsing regulatory barriers for inline dispersion in oral solid dosage production, opening validation-intensive segments.
- Service Contract Unbundling:Predictive maintenance platforms using vibration analytics enable aftermarket revenue streams independent of initial equipment sales, restructuring vendor-customer relationships.
Industry Challenges
- Cross-Disciplinary Engineering Shortage:Equipment specification requires simultaneous expertise in fluid mechanics, explosion protection, and process control automation, limiting qualified sales engineering capacity.
- Legacy DCS Integration Complexity:Brownfield installations must bridge proprietary communication protocols between modern disperser variable frequency drives and aging distributed control system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Speed Dispersers (HSD) Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laboratory Dispersers, Industrial Dispersers, Portable Dispersers, Inline Dispersers Technology: Mechanical, Hydraulic, Ultrasonic, Electromagnetic Application: Coatings, Pharmaceuticals, Food Processing, Chemicals End User: Manufacturers, Research Institutions, Food Producers, Cosmetic Companies |
| Companies Covered | Admix, Hockmeyer Equipment, Silverson Machines Ltd., SPX FLOW, Charles Ross & Son Company, ROSS Mixers, GEA Group, Ystral, IKA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Speed Dispersers (HSD) Market Trends and Innovations
Digital twin modeling and electromagnetic actuation are converging to redefine how shear energy is delivered and optimized in dispersion processes, shifting competitive advantage toward system integrators with software capabilities.
Electromagnetic dispersion technology is collapsing the traditional trade-off between energy precision and mechanical durability. Coil-based impeller drive systems eliminate gearbox wear and enable real-time torque modulation. Specialty chemical producers in Germany and Japan are piloting these configurations for temperature-sensitive nanomaterial synthesis. The technology is collapsing maintenance intervals from quarterly to annual cycles while enabling sub-micron particle size targets previously requiring multiple pass operations.
EPA New Source Performance Standards for coating manufacturing facilities are mandating maximum achievable control technology for VOC emissions. This regulatory pressure is accelerating enclosure and vapor recovery retrofits on existing HSD installations. Automotive OEM paint shops in Michigan and Alabama are prioritizing sealed-tank disperser designs to preempt enforcement actions and avoid production line shutdowns.
Equipment-as-a-service contracting is displacing capital purchase models among mid-size adhesive compounders. Monthly payments tied to throughput volume transfer operational risk to vendors while preserving buyer liquidity. This pattern is most visible in Ohio and Pennsylvania manufacturing corridors where private equity consolidation has compressed balance sheet capacity for standalone chemical processors.
High Speed Dispersers (HSD) Market Segmentation
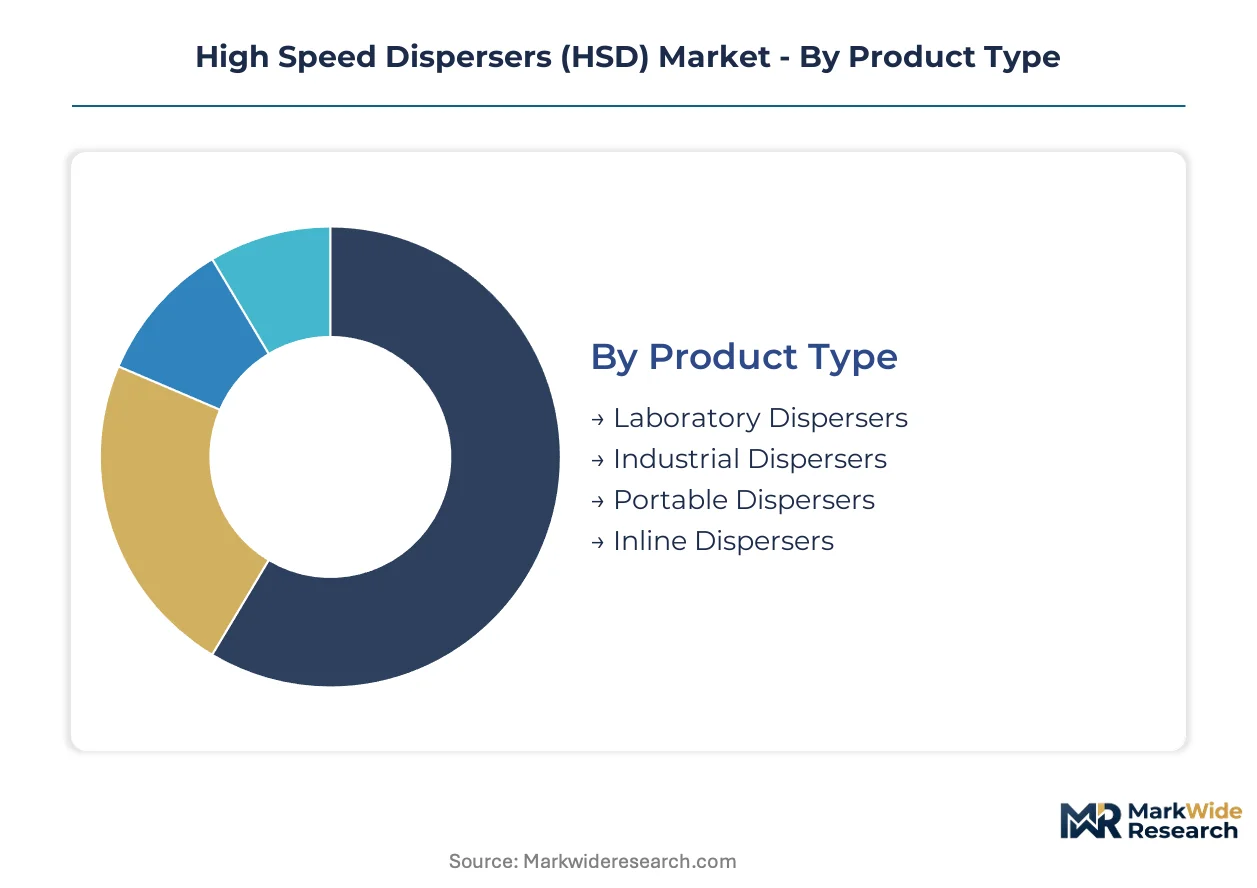
Segmentation in the High Speed Dispersers market reveals how equipment specifications diverge across operational scales, energy delivery methods, and regulatory environments. Understanding these divides helps suppliers align R&D investments with the highest-velocity demand corridors.
Product Type:
Laboratory formulations and continuous production lines sit at opposite ends of the use-case spectrum, with equipment footprints and power requirements scaling accordingly.
- Industrial Dispersers:Fixed-base systems rated for batch volumes exceeding 1,000 gallons dominate installed capacity across chemical processing facilities. Demand concentrates in Germany's automotive coatings sector, where EPA-aligned VOC containment retrofits are forcing sealed-tank upgrades at existing plants.
- Inline Dispersers:Continuous-flow configurations integrate directly into pipeline architectures, eliminating tank transfer steps. China's expanding specialty chemical capacity is pulling these installations into greenfield projects seeking MIIT energy efficiency certification.
- Laboratory Dispersers:Benchtop units with variable speed controls serve formulation development and quality validation protocols.
- Portable Dispersers:Mobile cart-mounted systems enable multi-vessel processing in contract manufacturing environments.
The dominant share belongs to Industrial Dispersers, while Inline Dispersers is closing the gap fastest.
Technology:
Energy delivery mechanisms range from conventional mechanical torque transfer to precision electromagnetic modulation, with capital intensity and maintenance profiles diverging sharply.
- Mechanical:Gearbox-driven impeller systems represent the established installed base, with saw-tooth designs optimized for mid-viscosity coatings. China's tightening GB standards for explosion-proof electrical enclosures are accelerating replacement cycles in aging mechanical fleets.
- Electromagnetic:Coil-based drives eliminate physical wear components while enabling real-time torque adjustment. German nanomaterial producers are piloting these systems for temperature-sensitive synthesis where energy precision directly yields particle size targets.
- Hydraulic:Fluid power transmission suits high-torque applications in abrasive slurry processing.
- Ultrasonic:Cavitation-based dispersion addresses fragile particle structures in pharmaceutical liposomal formulations.
Mechanical systems retain the largest installed footprint, though Electromagnetic configurations are climbing the fastest as energy efficiency mandates tighten across European and Asian manufacturing jurisdictions.
Application:
End-use requirements span from aesthetic finish consistency to pharmaceutical bioavailability, with validation protocols and contamination thresholds defining equipment selection.
- Coatings:Automotive OEM paint operations in Michigan and Alabama specify sealed-tank HSD configurations to satisfy EPA New Source Performance Standards for VOC capture. Electrification trends are pulling additional demand from battery electrode slurry production lines.
- Pharmaceuticals:Oral solid dosage manufacturing under FDA real-time release testing guidance is collapsing barriers for inline dispersion adoption, with validation documentation becoming a competitive differentiator.
- Chemicals:Specialty and commodity chemical production accounts for substantial batch processing volume across multiple geographies.
- Food Processing:Sanitary design requirements and allergen control protocols shape equipment specifications for emulsion and suspension production.
Coatings commands the dominant revenue position, while Pharmaceuticals is gaining share fastest on continuous manufacturing regulatory momentum.
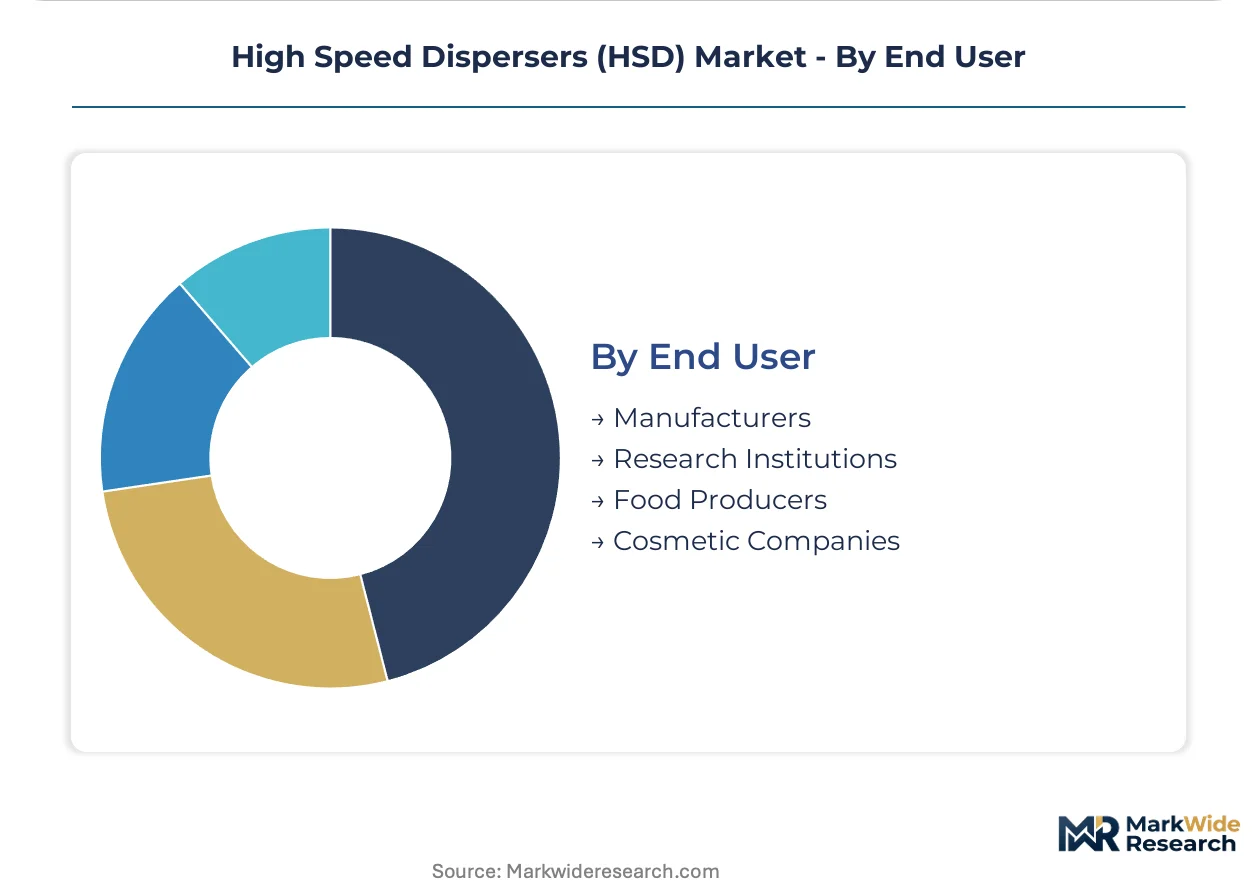
End User:
Procurement authority varies from centralized engineering teams at multinational manufacturers to specialized equipment committees at research institutions.
- Manufacturers:Integrated chemical and coatings producers with in-house process engineering capabilities specify custom-configured systems. India's PLI scheme for specialty chemicals is stimulating greenfield investments specifying imported disperser technology.
- Research Institutions:University and national laboratory procurement prioritizes flexibility and multi-application compatibility over throughput optimization.
- Food Producers:Commercial-scale bakeries and dairy operations deploy sanitary-grade dispersers for emulsion stability.
- Cosmetic Companies:Personal care formulators require equipment handling both aqueous and anhydrous phases with rapid changeover capability.
Manufacturers hold the dominant procurement volume, while Research Institutions are expanding fastest on government-funded materials science initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment trade flows reveal a net import dependency across emerging chemical processing hubs, while established manufacturing clusters defend positions through technology export licensing. Germany, China, the United States, India, and Japan concentrate both production capacity and regulatory innovation that shapes cross-border equipment specifications.
United States
Automotive OEM paint operations in Michigan and Alabama drive sealed-tank HSD retrofits to satisfy EPA New Source Performance Standards for VOC containment. OSHA process safety management requirements mandate explosion-proof electrical configurations for hazardous chemical handling. Battery gigafactory construction across the Midwest and Southeast pulls inline disperser installations into electrode slurry production lines.
Germany
Specialty chemical producers pilot electromagnetic dispersion systems for temperature-sensitive nanomaterial synthesis where energy precision yields particle size targets. ECHA REACH Phase-Out restrictions on volatile organic compounds force closed-system configurations across coatings manufacturing. The industrial corridor spanning North Rhine-Westphalia and Bavaria concentrates both automotive coatings demand and equipment R&D activity.
China
Domestic chemical processing expansion creates replacement demand as MIIT energy efficiency directives mandate equipment upgrades. GB standards for explosion-proof electrical components diverge from ATEX classifications, raising barriers for imported systems. The Yangtze River Delta and Shandong Peninsula clusters anchor greenfield specialty chemical investments specifying inline disperser architectures.
India
Production-linked incentives under the PLI scheme for specialty chemicals stimulate greenfield plant investments specifying imported disperser technology. CDSCO pharmaceutical validation protocols create documentation-intensive procurement requirements for oral solid dosage manufacturing. The Gujarat and Maharashtra industrial corridors concentrate contract manufacturing capacity driving portable disperser demand.
Japan
METI industrial efficiency guidelines accelerate electromagnetic technology adoption in high-viscosity mixing operations. Pharmaceutical continuous manufacturing under PMDA oversight collapses barriers for inline dispersion in real-time release testing environments. The Kansai region around Osaka anchors precision chemical equipment production serving both domestic and export markets.
High Speed Dispersers (HSD) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in impeller and seal fabrication. The vendor base organizes around three archetypes: diversified process equipment conglomerates with global service networks, specialized dispersion technology houses with deep application expertise, and regional fabricators competing on customization velocity. Consolidation pressure concentrates among mid-scale operators lacking aftermarket service infrastructure. Strategic moves center on predictive maintenance platform development and electromagnetic drive technology licensing.
Within the diversified equipment tier, SPX FLOW and GEA Group represent platform integrators with recurring revenue architectures. Among specialized dispersion houses, Hockmeyer Equipment and Silverson Machines Ltd. exemplify deep application focus. IKA occupies a position spanning laboratory and production scales. These named entities anchor competitive dynamics without exhausting the participant set.
| Leading Market Players |
|---|
| Admix |
| Hockmeyer Equipment |
| Silverson Machines Ltd. |
| SPX FLOW |
| Charles Ross & Son Company |
| ROSS Mixers |
| GEA Group |
| Ystral |
| IKA |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp chemical corridor's freight cost volatility transmits directly into HSD landed pricing, amplifying margin compression for European fabricators while enabling Chinese producers to exploit proximity premiums in Asia-Pacific procurement.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium electromagnetic, standard mechanical, and economy hydraulic configurations. Price differentiation stems from MIIT energy efficiency certification tier and aftermarket service bundling intensity. Cost compression in economy mechanical tiers is intensifying because Chinese GB standard compliance costs are eroding export competitiveness. Mid-size adhesive compounders in Ohio and Pennsylvania manufacturing corridors exhibit highest price sensitivity, while German nanomaterial specialists tolerate premium positioning for temperature-sensitive synthesis applications.
Supply Chain Analysis
Dual-use technology export controls on precision electromagnetic coil assemblies limit flows from Germany and Japan into Chinese battery gigafactory projects. Fabrication capacity concentrates in Germany, China, and the United States, with vessel welding and impeller machining drawing from Hastelloy and duplex stainless steel feedstock anchored in Swedish and Finnish metallurgical output. Single-source vulnerability in specialized alloy procurement elevates risk exposure for European fabricators. Distribution runs through authorized distributor networks serving regional chemical processing clusters, with direct OEM relationships dominating large-volume coatings and pharmaceutical installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service contracting is collapsing traditional capital-sales economics, creating platform-arbitrage opportunities for vendors that integrate predictive maintenance software with hardware deployments.
For Market Incumbents: Harden aftermarket service infrastructure against specialized engineering talent scarcity by building predictive maintenance platforms using vibration analytics. Deepen backward integration into explosion-proof electrical component fabrication to circumvent China's divergent GB certification requirements. Anchor capacity in the Yangtze River Delta to capture MIIT-mandated replacement cycles.
For New Entrants and Emerging Players: India's Gujarat and Maharashtra industrial corridors offer underpenetrated contract manufacturing demand for portable disperser configurations. Target pharmaceutical continuous manufacturing validation services as the most penetrable white-space segment, where FDA real-time release testing guidance has collapsed regulatory barriers. Pursue equipment-leasing partnerships with private equity-consolidated adhesive compounders lacking balance sheet capacity for capital purchases.
For Investors and Strategic Acquirers: EPA New Source Performance Standards for VOC containment reshape the acquisition landscape toward sealed-tank system specialists with automotive OEM relationships. Long-term viability favors platform-integrated vendors with recurring revenue architectures over pure-play fabricators. Monitor electromagnetic drive technology licensing velocity as the signal indicating technology-transition inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Electromagnetic Drive Licensing | German nanomaterial producers pilot coil-based systems for sub-micron particle targets. |
| Predictive Maintenance Platform Development | Vibration analytics transfer operational risk to vendors under equipment-as-a-service contracts. |
| Backward Integration into Specialized Alloys | Captive Hastelloy supply insulates margin from Swedish metallurgical price swings. |
| Sealed-Tank Configuration Retrofit Services | EPA VOC mandates force automotive paint shop upgrades across Michigan and Alabama. |
| Pharmaceutical Validation Documentation Investment | FDA real-time release testing collapses barriers for inline dispersion in oral solid dosage. |
Research Methodology
A spread of perspectives from plant engineers at coatings manufacturers, procurement leads at battery gigafactory developers, aftermarket service heads at diversified equipment conglomerates, and technical R&D directors at specialty chemical producers converged on the working assumptions. These primary insights were cross-checked against customs trade data for disperser equipment flows, SEC filings from publicly traded process equipment vendors, MIIT energy efficiency directive documentation, and ECHA REACH substance restriction updates. Bottom-up volume estimates from individual facility installations were reconciled with top-down market sizing derived from chemical processing capacity expansion announcements.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by operational scale, technology segmentation by energy delivery mechanism, application segmentation by end-use validation intensity, and geographic segmentation by regulatory framework cluster. CAGRs were derived from trend extrapolation of replacement cycle timing, greenfield investment pipelines, and technology substitution elasticities. Forecast inputs included battery electrode slurry production line deployment schedules, pharmaceutical continuous manufacturing regulatory adoption curves, and specialty chemical capacity expansion under India's PLI scheme.
Practitioners should monitor alloy price volatility, electromagnetic technology pilot conversion rates, and regional certification divergence for early signals of forecast deviation. Material shifts in EPA enforcement intensity, REACH substance restriction scope, or MIIT energy efficiency compliance deadlines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Plastic Molds Market
Industrial Materials
Elastomeric Couplings Market
Industrial Materials
Tooling Board Market
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
Wire Mesh Market
Industrial Materials
Industrial Drum Market
Industrial Materials
Wire Drawing Dies Market
Industrial Materials
High Shear Mixer Market
Industrial Materials
Injection Molding Market
Industrial Materials
Steel Cord Market
Industrial Materials
Middle-East and Africa Engineering Plastics Market
Industrial Materials
Asia-Pacific Wood Based Panel Market
Industrial Materials
North America Activated Carbon Market
Industrial Materials
Atomizing Metal Powder Market
Industrial Materials
Heat-Insulation Boards for Industrial Equipment Market
Industrial Materials
Industrial Pails and Drums Market