
 Shock Mat Market | 2026-2036
Shock Mat Market Size, Share, and Industry Trends Forecast 2026-2036
Shock Mat Market Analytics
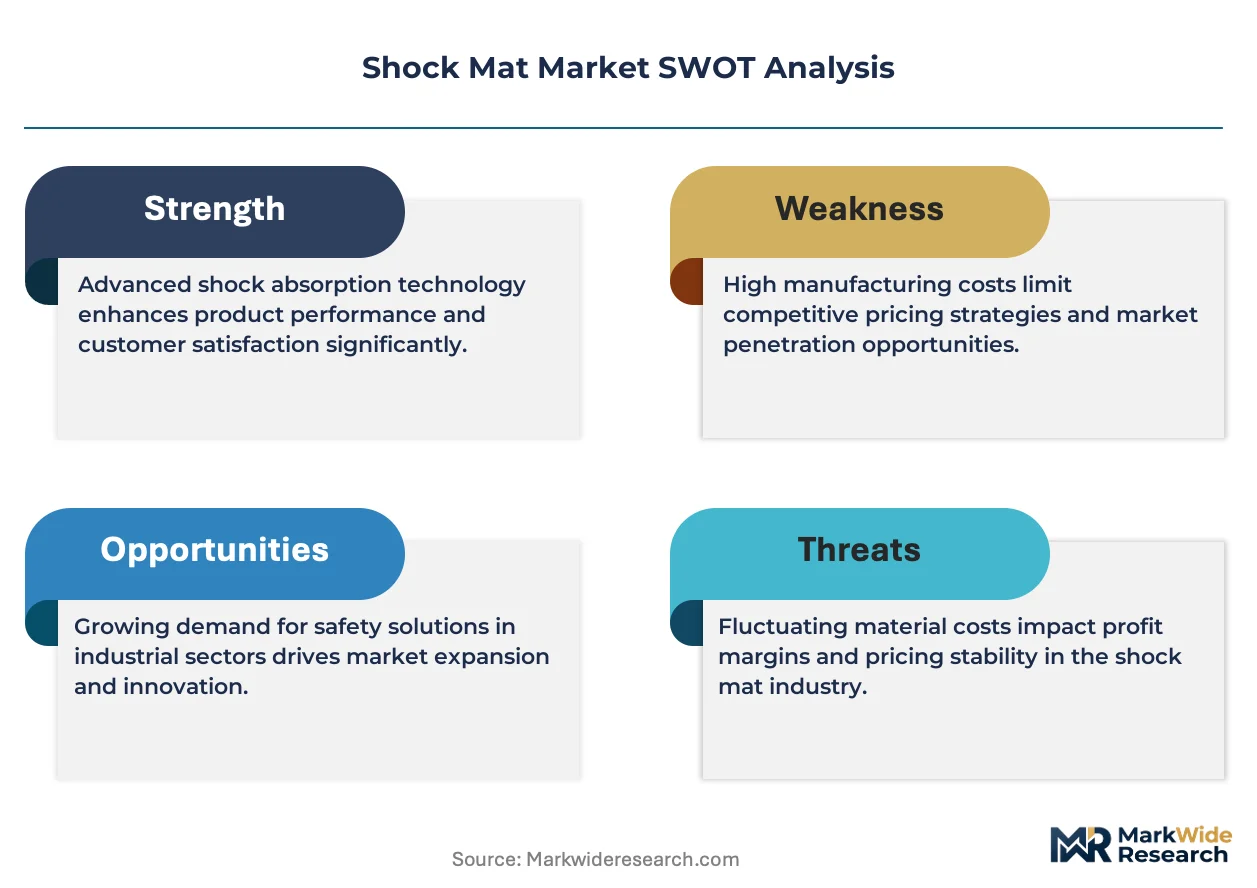
The EU Green Deal is rebalancing procurement criteria across European industrial flooring contracts. Mondo S.p.A. leverages its Italian manufacturing base to dominate sports training installations. Tarkett S.A. anchors its position through extensive R&D on recycled vinyl compounds. Regupol BSW GmbH specializes in rubber formulations for German automotive OEMs.
Shock mats are engineered flooring surfaces, typically 10-50mm thick, composed of vulcanized rubber granules, cross-linked polyethylene foam, or PVC composites bonded under heat and pressure, designed to attenuate impact forces and reduce worker fatigue in standing environments. Rubber shock mats sustain the largest revenue share due to durability requirements in heavy manufacturing, while foam shock mats represent the fastest-expanding category as gym operators prioritize lightweight installability. Synthetic shock mats command premium pricing in automotive paint booths where chemical resistance dictates specification.
OSHA workplace safety standards, REACH substance restrictions, and EPA industrial emissions frameworks collectively tighten material compliance burdens across supply chains. The EU F-Gas Regulation and California Air Resources Board protocols further constrain polymer processing chemistries in domestic production. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that threaten conventional waterproofing treatments.
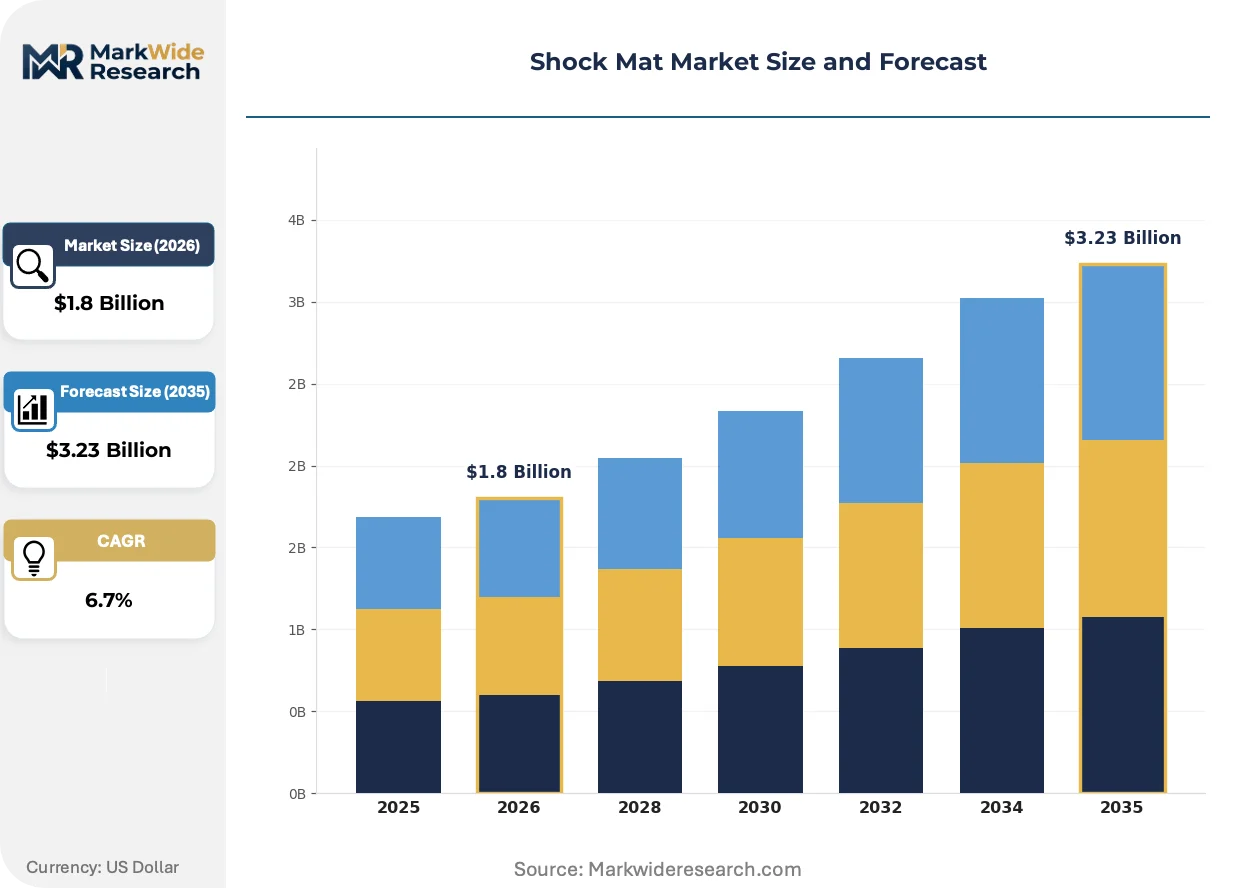
Market Dynamics
Automotive OEMs in Germany, China, and the US Southeast are consolidating shock mat specifications around recycled rubber formulations, compressing supplier margins while elevating compliance documentation burdens across tier-1 flooring contractors.
Growth Catalysts
- REACH substance restrictions:European chemical safety mandates are redirecting procurement toward verified recycled rubber streams in German automotive assembly plants.
- Lightweight foam formulations:Cross-linked polyethylene shock mats are displacing traditional rubber in gym and fitness center installations due to reduced freight costs and faster deployment.
- China's manufacturing belt expansion:Industrial safety flooring demand concentrates in Guangdong and Jiangsu provinces where electronics assembly lines require anti-fatigue surfaces.
Market Restraints
- Natural rubber price volatility:Input cost swings in Southeast Asian latex markets compress margins for vulcanized rubber mat producers.
- Supply concentration in German chemical processors:Limited domestic sources for REACH-compliant bonding agents create single-source vulnerability.
- Per- and polyfluoroalkyl substance restrictions:California Air Resources Board protocols threaten conventional waterproofing treatments in US West Coast distribution.
Strategic Opportunities
- EU Green Deal procurement incentives:Public infrastructure contracts in Italy and Spain now prioritize recycled-content flooring with verified carbon footprints.
- Modular interlocking systems:Tool-free installation formats are opening commercial kitchen and food processing applications previously served by epoxy flooring.
- Automotive paint booth chemical resistance:Synthetic PVC shock mat specifications command premium positioning in German and US Southeast OEM facilities.
Industry Challenges
- Vulcanization technician shortage:Specialized rubber curing expertise is aging out of European and North American manufacturing bases.
- Multi-jurisdiction certification timelines:Simultaneous OSHA, REACH, and EPA compliance documentation extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shock Mat Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Shock Mats, Foam Shock Mats, Vinyl Shock Mats, Synthetic Shock Mats Application: Industrial Safety, Sports Training, Home Use, Automotive Feature: Shock Absorption, Anti-Slip Surface, Waterproof, Fire-Resistant End User: Manufacturing Plants, Gyms, Residential Homes, Vehicle Repair Shops |
| Companies Covered | Mondo S.p.A., Tarkett S.A., Regupol BSW GmbH, Ecore, The Dow Chemical Company, 3M, Trelleborg AB, Nitto Denko Corporation, LINTEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shock Mat Market Evolving Landscape
Digital specification tools and predictive wear analytics are compressing buyer decision cycles while elevating performance transparency requirements across industrial flooring procurement.
Cross-linked polyethylene foam shock mat technology is decentralizing installation authority from specialized contractors to facility maintenance teams. Warehouse operators in the US Southeast and China's logistics hubs are adopting 15-25mm interlocking tile formats for rapid reconfiguration. This shift is decentralizing the traditional specification gatekeeper role of architectural flooring consultants.
California Air Resources Board protocols on industrial emissions are constraining solvent-based adhesive chemistries in domestic production. Manufacturers serving US West Coast automotive and electronics assembly plants are reformulating bonding agents to water-based alternatives. German automotive OEMs are extending these specifications to their US Southeast transplant facilities, creating transatlantic regulatory harmonization pressure.
Buyer specification behavior is rotating from catalog-based purchasing toward performance-guaranteed service agreements. Industrial facility managers in Germany's automotive corridor are unbundling shock mat procurement from installation and maintenance contracts. This pattern is most visible in multi-site manufacturing networks where standardized flooring performance metrics enable centralized supplier consolidation.
Shock Mat Market Segmentation
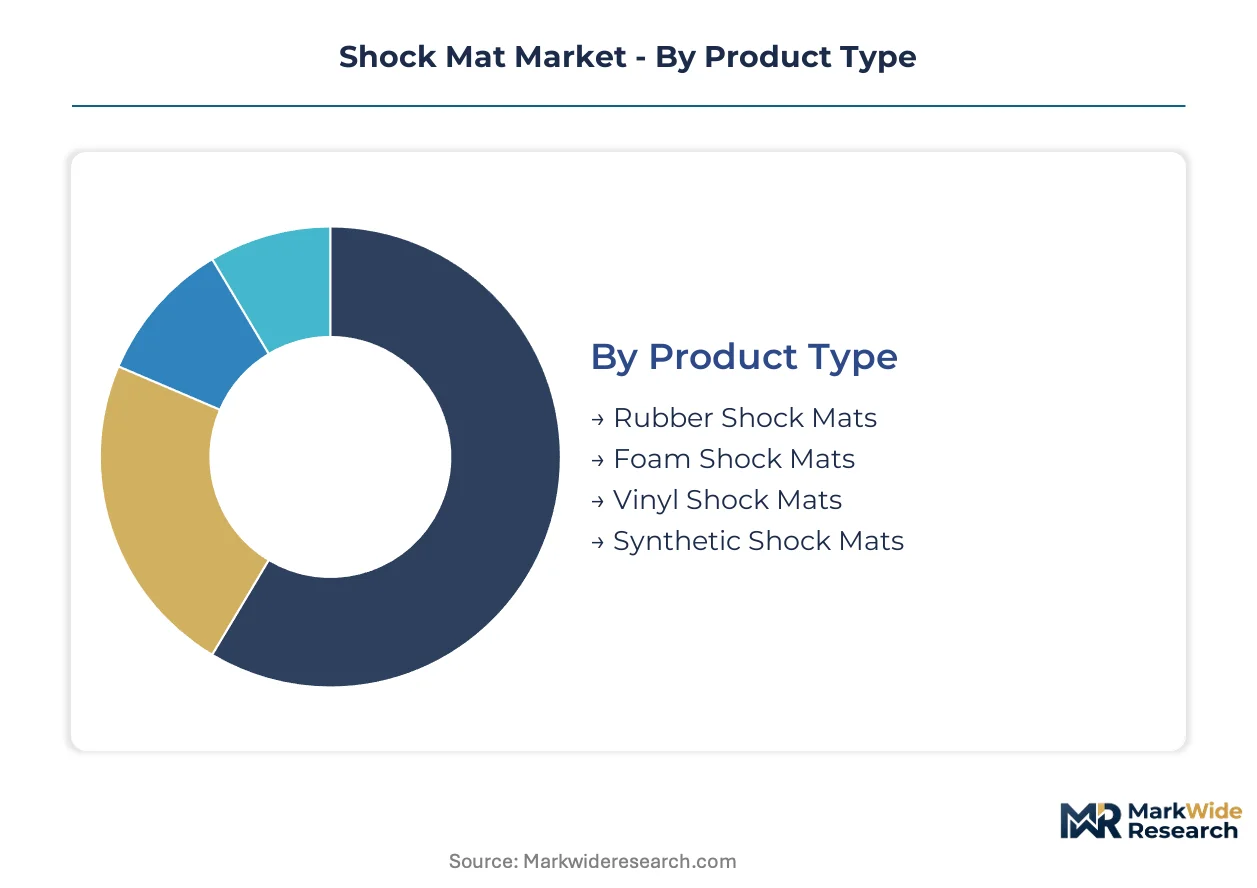
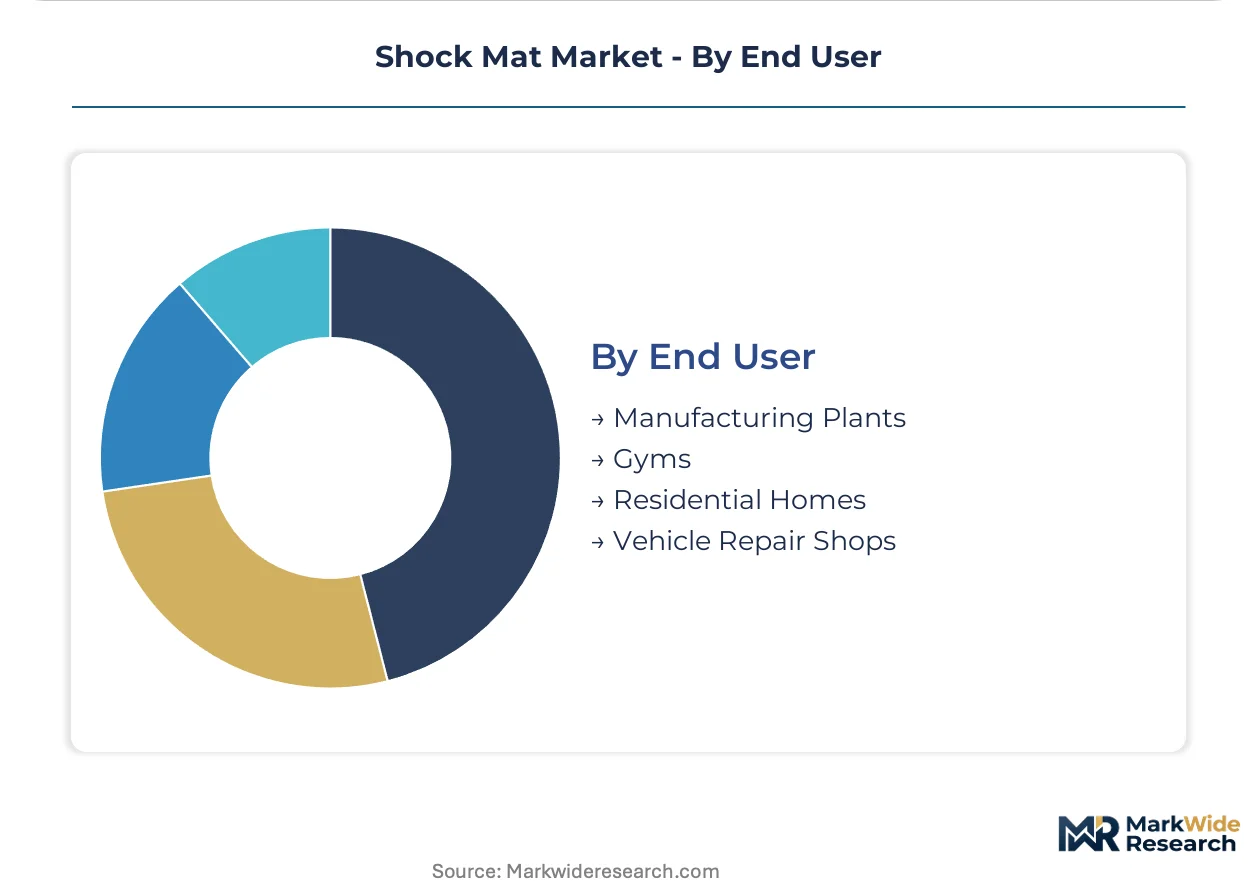
Shock mat procurement diverges sharply across buyer profiles, with industrial safety officers prioritizing durability certifications while fitness operators trade longevity for installability. Specification authority fragments between facility engineers, procurement teams, and maintenance departments depending on end-use context.
Product Type:
Buyer differentiation hinges on load-bearing requirements versus deployment speed, with heavy manufacturing tolerating no substitution for density while temporary installations sacrifice permanence.
- Rubber Shock Mats:Vulcanized rubber granules bonded under heat and pressure deliver 10-50mm thickness ratings for sustained impact attenuation. Demand concentrates in Germany's automotive corridor where BMW and Volkswagen assembly plants specify REACH-compliant recycled formulations for welding bay flooring.
- Foam Shock Mats:Cross-linked polyethylene foam structures achieve 60-70% weight reduction versus rubber equivalents, enabling single-person installation. Guangdong electronics assembly plants and US Southeast logistics hubs are displacing traditional rubber in temporary workstation configurations where reconfiguration frequency exceeds durability concerns.
- Vinyl Shock Mats:PVC composite layers provide chemical resistance for solvent-exposed environments. German paint booth contractors specify these for overspray protection.
- Synthetic Shock Mats:Engineered polymer blends balance density with modularity. China's manufacturing belt adopts these for hybrid industrial-gym facilities.
Volume sits with rubber formulations; growth tilts toward foam variants.
Application:
Specification cycles compress where regulatory inspection regimes enforce replacement schedules, elongating where buyer education lags.
- Industrial Safety:Anti-fatigue surfaces for standing workstations in automotive, electronics, and logistics operations. Jiangsu province electronics assemblers and US Southeast Amazon fulfillment centers drive specification for 12-hour shift endurance ratings.
- Sports Training:Weightlifting platforms and functional training zones prioritize impact attenuation for dropped equipment. Boutique gym operators in Italy and Spain specify recycled-content products under EU Green Deal procurement incentives.
- Home Use:Garage workshops and basement gyms represent price-sensitive demand with minimal compliance documentation.
- Automotive:OEM assembly lines and vehicle repair facilities require oil-resistant formulations. German KBA inspection protocols influence specification durability testing.
Industrial safety commands procurement volume; sports training exhibits the steepest expansion trajectory.
Feature:
Performance claims face escalating verification burdens as multi-jurisdiction certification timelines extend product launch cycles.
- Shock Absorption:Engineered density gradients attenuate impact forces through controlled deformation. German automotive OEMs mandate EN 1177-equivalent testing for assembly line installations.
- Anti-Slip Surface:Textured top layers maintain traction under oil, coolant, and perspiration exposure. California OSHA consultation records document slip-fall reduction claims.
- Waterproof:Closed-cell structures prevent moisture ingress for food processing and outdoor applications. EPA industrial emissions frameworks constrain solvent-based waterproofing chemistries.
- Fire-Resistant:Halogen-free flame retardant additives meet EU F-Gas Regulation constraints on polymer processing. German chemical processors supply REACH-compliant bonding agents for this specification tier.
Shock absorption remains the baseline specification; fire-resistant formulations gain share fastest in automotive paint booth applications.
End User:
Procurement authority centralizes in multi-site manufacturing networks while fragmenting across independent fitness operators.
- Manufacturing Plants:Centralized engineering specifications govern flooring decisions across distributed production networks. Volkswagen Group standardizes shock mat performance metrics across Wolfsburg, Chattanooga, and Shanghai facilities.
- Gyms:Franchise operators balance brand consistency against local installer relationships. Equinox and Planet Fitness specify differently despite shared end-use.
- Residential Homes:E-commerce channel dominance compresses specification to price-point and review velocity.
- Vehicle Repair Shops:Independent operators prioritize immediate availability from automotive parts distributors over performance optimization.
Manufacturing plants anchor volume concentration; gyms represent the most rapidly diversifying demand profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wolfsburg anchors European shock mat procurement through Volkswagen Group's centralized flooring specifications that cascade across assembly plants in three continents. German automotive OEMs extend these standards to transplant facilities, creating regulatory harmonization pressure that reshapes supplier qualification timelines.
United States
Amazon fulfillment centers in Tennessee and Georgia drive specification for 12-hour shift endurance ratings in anti-fatigue flooring. OSHA workplace safety standards mandate slip-fall documentation that compresses replacement cycles. Chattanooga's Volkswagen assembly plant imports German KBA inspection protocols for welding bay installations.
Germany
BMW and Volkswagen assembly plants in Bavaria and Lower Saxony specify REACH-compliant recycled rubber formulations for welding bay flooring. The EU F-Gas Regulation constrains polymer processing chemistries in domestic production. Stuttgart's automotive corridor concentrates tier-1 flooring contractor activity around compliance documentation services.
China
Electronics assemblers in Guangdong and Jiangsu provinces displace traditional rubber with cross-linked polyethylene foam for temporary workstation reconfiguration. The country's national environmental regulator enforces industrial emissions frameworks that constrain solvent-based adhesive chemistries. Shenzhen's manufacturing belt prioritizes lightweight installability over density specifications.
Italy
Boutique gym operators in Milan and Rome specify recycled-content products under EU Green Deal procurement incentives for public infrastructure contracts. ECHA substance restrictions redirect material sourcing toward verified recycled rubber streams. Turin's sports training installation sector leverages domestic manufacturing for carbon footprint verification.
Japan
Automotive suppliers in Aichi Prefecture adopt synthetic PVC shock mat specifications for paint booth chemical resistance. METI industrial standards influence durability testing protocols that extend to Southeast Asian component plants. Nagoya's manufacturing base concentrates demand for halogen-free flame retardant formulations.
Shock Mat Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance documentation capabilities and recycled-content verification systems. The vendor base stratifies into three tiers: integrated polymer processors with captive raw material streams, specialized flooring fabricators with regional installation networks, and commodity converters competing on freight-adjusted pricing. Two dominant competitive moves are reshaping positioning: automotive OEMs are unbundling procurement from installation contracts to enable centralized supplier consolidation, and cross-linked polyethylene specialists are licensing tool-free interlocking formats to facility maintenance teams.
Among European specialists, Mondo S.p.A., Tarkett S.A., and Regupol BSW GmbH occupy positions that exemplify distinct archetype strategies. Mondo S.p.A. represents the sports-training-focused fabricator with Italian manufacturing heritage. Tarkett S.A. anchors the R&D-intensive polymer processor tier through recycled vinyl compound development. Regupol BSW GmbH sits within the automotive-tied rubber formulation specialist category, with geographic naming indicating German operational roots. These three entities collectively illustrate how regional manufacturing concentration aligns with end-use specialization.
| Leading Market Players |
|---|
| Mondo S.p.A. |
| Tarkett S.A. |
| Regupol BSW GmbH |
| Ecore |
| The Dow Chemical Company |
| 3M |
| Trelleborg AB |
| Nitto Denko Corporation |
| LINTEC Corporation |
| Others |
Value Network & Pricing Analysis
Vulcanization technician shortages in Germany and the US Southeast amplify labor-cost differentials between premium REACH-compliant formulations and economy-grade imports. This workforce concentration compresses margins at the mid-tier while widening price spreads across certification levels.
Pricing Analysis
Value-based pricing anchors on guaranteed uptime performance in automotive assembly environments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in the economy tier is intensifying because Guangdong foam producers are displacing traditional rubber in temporary installations. Boutique gym operators in Italy exhibit the highest price sensitivity, while German automotive OEMs prioritize compliance documentation over unit cost.
Supply Chain Analysis
Warehouse-distribution layer concentration in Rotterdam and Hamburg shapes European availability timelines for REACH-compliant bonding agents. Raw material supply draws from Southeast Asian latex processors, German chemical formulators, and Chinese polyethylene foam extruders. Single-source vulnerability sits with limited domestic sources for EU F-Gas Regulation-compliant polymer processing chemistries. Distribution runs through tier-1 flooring contractors who maintain regional installation networks and compliance documentation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is forcing out commodity converters lacking recycled-content verification systems. REACH compliance documentation burdens favor scaled polymer processors with captive technical resources.
For Market Incumbents: Hedge against foam displacement by securing cross-linked polyethylene licensing agreements with Guangdong equipment manufacturers. Backward integration into verified recycled rubber streams defends margin position against REACH-compliant import competition. German automotive OEM unbundling of procurement from installation contracts demands centralized supplier consolidation capabilities.
For New Entrants and Emerging Players: Capture modular interlocking format opportunities in US Southeast logistics hubs where facility maintenance teams seek tool-free reconfiguration authority. The most penetrable segment sits with warehouse operators prioritizing deployment speed over density specifications. A direct-to-facility-maintenance go-to-market angle bypasses traditional architectural flooring consultant gatekeepers.
For Investors and Strategic Acquirers: Re-rating potential sits with REACH-compliant rubber formulation specialists given EU Green Deal procurement incentive expansion across Italian and Spanish public infrastructure contracts. Long-term viability favors integrated polymer processors with verified carbon footprint documentation and multi-site manufacturing network relationships. Watch for California Air Resources Board protocol harmonization with German KBA inspection standards as an inflection indicator for transatlantic specification consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Bonding Agent Investment | Secures qualification for BMW and Volkswagen welding bay specifications in Wolfsburg and Chattanooga. |
| Cross-Linked Polyethylene Licensing | Enables single-person installation formats that displace traditional rubber in Guangdong electronics assembly. |
| Recycled-Content Verification System | Unlocks EU Green Deal procurement incentives for Italian boutique gym and public infrastructure contracts. |
| Modular Interlocking Format Development | Opens commercial kitchen applications previously served by epoxy flooring through tool-free deployment. |
| Water-Based Adhesive Reformulation | Aligns with California Air Resources Board protocols constraining solvent-based chemistries in US West Coast distribution. |
Research Methodology
Trade association filings, customs import records, and EU ECHA substance restriction databases formed the secondary backbone for this analysis. Primary interviews with automotive safety officers, industrial flooring procurement leads, gym franchise operators, polymer processing plant managers, and REACH compliance consultants validated demand patterns. Bottom-up triangulation across product-type shipment data and top-down reconciliation against end-use industry capital expenditure disclosures anchored volume estimates.
Historical trendline analysis of automotive assembly plant flooring replacement cycles and gym equipment procurement patterns informed projection assumptions across the analysis window. Segmentation modeling incorporated product type, application context, certification tier, and regional regulatory cluster dimensions. CAGRs derived from elasticity-adjusted demand curves reflected input cost volatility in natural rubber markets and foam formulation technology diffusion rates.
The model holds under stable REACH enforcement intensity and continued EU Green Deal procurement incentive continuity; deviation in per- and polyfluoroalkyl substance restriction timelines or automotive OEM specification consolidation pace would shift trajectory. Forecasts reflect documented assumptions regarding technician workforce availability and bonding agent supply concentration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global Polycarbonate Sheets Market
Industrial Materials
Cork Material Market
Industrial Materials
Global Machined Seals Market
Industrial Materials
Industrial Strainers Market
Industrial Materials
Warehouse Drums and Barrels Market
Industrial Materials
Soil Stabilization Materials Market
Industrial Materials
Global Industrial Chain Market
Industrial Materials
Steel Bar Magnet Market
Industrial Materials
HV Glass Insulator Market
Industrial Materials
Anode Carbon Block Market
Industrial Materials
Felt Gasket Market
Industrial Materials
Natural Industrial Absorbents Market
Industrial Materials
Elastomeric Couplings Market
Industrial Materials
Powder Processing Service Market
Industrial Materials
Continuous Mesh Belt Furnaces Market
Industrial Materials
Global Jet Mill Market