
 EV Battery Thermal Insulation Materials Market | 2026-2036
EV Battery Thermal Insulation Materials Market Size, Share, and Industry Trends Forecast 2026-2036
EV Battery Thermal Insulation Materials Market Insights
UN ECE R100 certification is unwinding the competitive landscape, forcing suppliers to prove cell-to-pack thermal runaway containment before securing OEM contracts. Aspen Aerogels leverages its aerogel manufacturing scale to dominate premium electric vehicle programs. Morgan Advanced Materials anchors European supply through its ceramic fiber expertise and existing relationships with German automakers. DuPont sustains technology leadership by controlling high-performance polymer formulations that meet flammability benchmarks.
EV battery thermal insulation materials are engineered barriers—typically silica aerogels, ceramic fibers, or intumescent coatings with thermal conductivity below 0.020 W/m·K—that prevent thermal propagation between lithium-ion cells during fault conditions. Their primary purpose is maintaining cell isolation integrity across temperature cycles while minimizing pack weight and volume. Aerogel formulations command the highest margin pools due to OEM preference for ultralow thermal conductivity in premium battery architectures. Fiberglass and thermoplastic segments compete on cost efficiency for standard-range vehicles where pack energy density requirements are less severe.
The US NHTSA and EPA enforce vehicle-level fire safety and environmental compliance that directly shapes insulation material selection and testing protocols. China's MIIT mandates GB standards for battery system safety that require domestic and foreign suppliers to certify thermal barrier performance under nail penetration and overcharge scenarios. EMA's alignment with EU Battery Regulation sustainability requirements is forcing manufacturers to document recyclability and carbon footprint across insulation supply chains. Stakeholders must monitor how qualification timelines and regional certification divergence affect supplier switching costs and contract lock-in periods.
Market Dynamics
Cell-level fire safety mandates under UN ECE R100 and China's GB standards are compressing supplier qualification timelines and concentrating procurement among certified thermal barrier manufacturers. OEMs now require documented thermal runaway containment performance before contract award, reshaping competitive entry barriers.
Growth Catalysts
- UN ECE R100 Phase 2:European OEMs must demonstrate 5-minute cell-to-cell propagation resistance, forcing battery pack redesigns that expand aerogel and ceramic fiber volumes.
- Solid-state battery commercialization:Next-generation cell architectures with higher energy density require more sophisticated thermal isolation layers between cells and modules.
- Germany:BMW, Volkswagen, and Mercedes-Benz are localizing battery assembly and mandating qualification-certified insulation suppliers for domestic production programs.
Market Restraints
- Silica precursor cost volatility:Aerogel manufacturing depends on petrochemical-derived alkoxides subject to feedstock price swings that compress margin pools.
- Single-source ceramic fiber supply:High-purity alumina-silica fiber production concentrates in limited geographic clusters, creating concentration risk for European automakers.
- Intumescent coating cure time:Extended drying cycles limit throughput in high-volume battery pack assembly lines, constraining adoption for mass-market EV platforms.
Strategic Opportunities
- India:Domestic battery manufacturing incentives under the PLI scheme create first-mover advantage for insulation suppliers establishing local qualification laboratories.
- Recyclable thermal barriers:EU Battery Regulation sustainability documentation requirements favor suppliers with closed-loop material recovery systems.
- Module-to-chassis integration:Structural battery pack designs require conformable insulation materials that bond directly to vehicle floor pans, opening new specification categories.
Industry Challenges
- UN ECE R100 certification timelines:Full cell-to-pack thermal runaway testing requires 12-18 months, locking suppliers into extended development cycles before revenue recognition.
- Multiphysics simulation talent:Battery thermal modeling requires combined expertise in CFD, FEA, and electrochemistry that commands premium compensation and extends hiring cycles.
- Legacy pack retrofit compatibility:First-generation EV platforms lack standardized cell interfaces, forcing custom insulation engineering for aftermarket thermal upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Battery Thermal Insulation Materials Market |
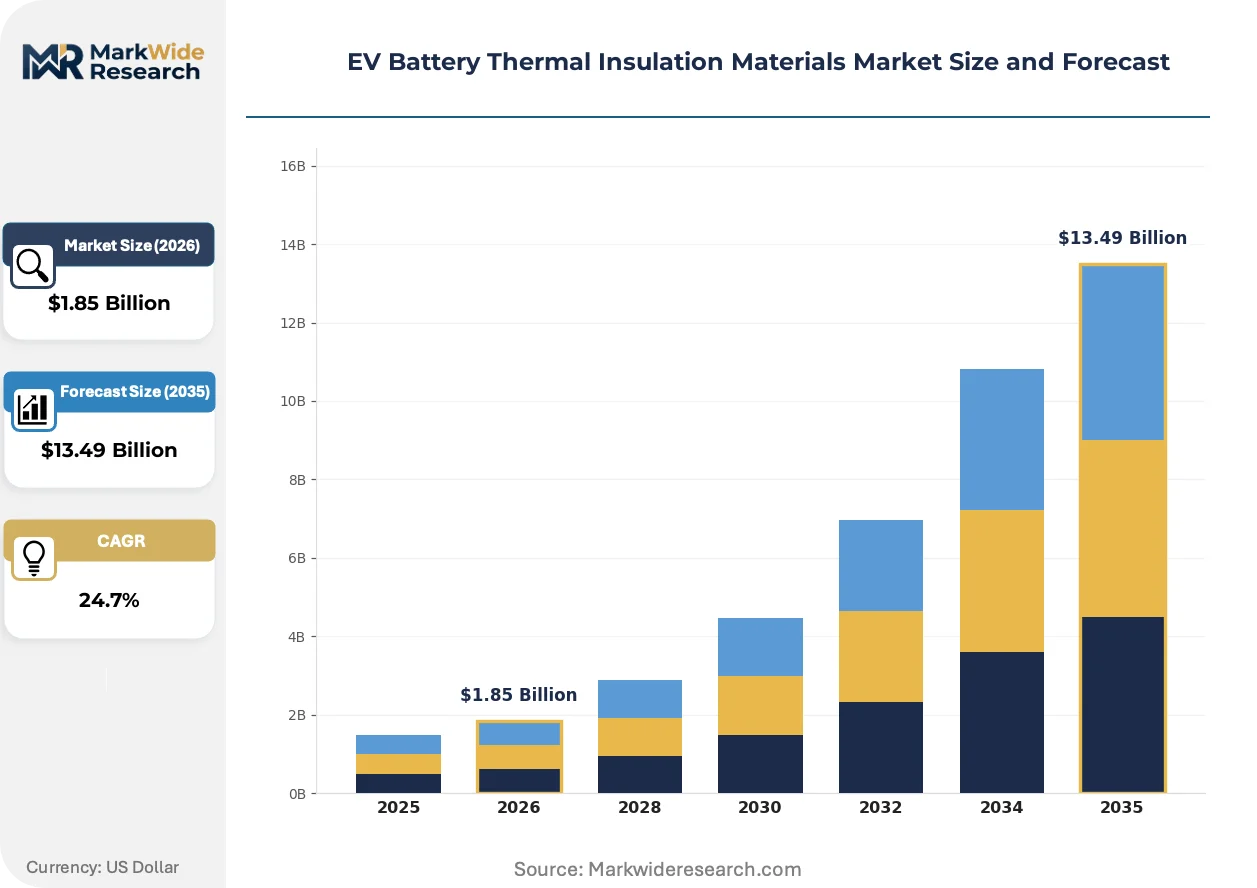
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $13.49 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fiberglass, Foam, Aerogel, Thermoplastic Application: Electric Vehicles, Energy Storage Systems, Charging Infrastructure, Consumer Electronics Manufacturing Process: Injection Molding, Extrusion, Casting, Coating Performance Criteria: Thermal Conductivity, Flammability Rating, Mechanical Strength, Durability |
| Companies Covered | 3M Company, DuPont, Aspen Aerogels, Morgan Advanced Materials, Elkem ASA, Saint-Gobain, BASF SE, Parker Hannifin, Henkel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Battery Thermal Insulation Materials Market Trends and Innovations
Active materials engineering is compressing thermal conductivity thresholds while manufacturing scale-up reduces unit costs for premium insulation formats. Three developments are restructuring supplier capabilities and buyer specifications.
Aerogel composite blankets with fiber-reinforced facing layers are displacing traditional fiberglass mats in premium battery architectures. German and South Korean OEMs specify these materials for 800-volt platforms where cell-to-cell isolation distances shrink. The technology is displacing multi-layer insulation stacks by combining thermal, electrical, and mechanical functions in single-component designs that reduce pack assembly complexity.
China's MIIT has tightened GB 38031 enforcement for nail penetration and overcharge thermal propagation resistance. Domestic battery manufacturers must submit third-party test reports for every new cell chemistry and pack configuration. Suppliers serving BYD, CATL, and CALB are accelerating development of thin-profile ceramic papers that satisfy the standard's temperature-rise limits without sacrificing energy density.
Cell manufacturers are consolidating thermal barrier procurement under long-term framework agreements with volume-commitment clauses. Direct supplier-OEM relationships are replacing tiered sourcing through module integrators in Germany and the United States. This concentration is most visible in Michigan and Stuttgart, where battery gigafactories negotiate multi-year insulation supply contracts with penalty structures for qualification delays.
EV Battery Thermal Insulation Materials Market Segmentation
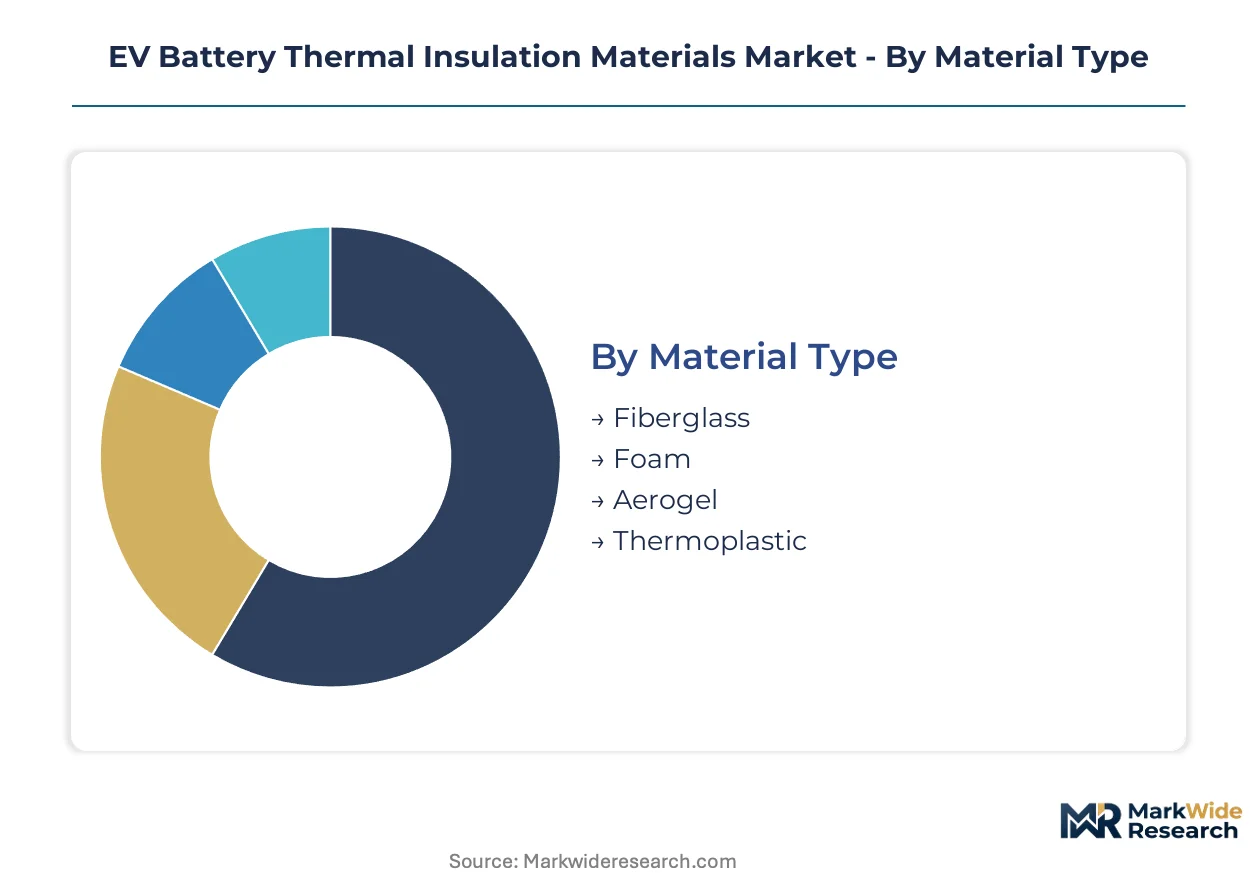
Material selection in EV battery thermal insulation directly determines qualification timelines and contract value. OEM procurement teams segment suppliers by thermal conductivity thresholds and flammability certification tiers rather than commodity chemistry alone.
Material Type:
Aerogel formulations command the steepest margin pools due to ultralow thermal conductivity specifications in premium 800-volt architectures. Fiberglass and thermoplastic alternatives compete on unit economics for standard-range platforms where pack energy density requirements relax.
- Aerogel:Silica-based nanoporous structures with thermal conductivity below 0.020 W/m·K. German OEMs specify fiber-reinforced composite blankets for cell-to-cell isolation in localized battery assembly programs. UN ECE R100 Phase 2 compliance timelines compress supplier qualification windows, locking in incumbents with certified manufacturing scale.
- Fiberglass:Alumina-silica fiber mats providing intermediate thermal protection at lower unit cost. Demand concentrates in mass-market EV platforms from Detroit and Shanghai where pack redesigns prioritize cost efficiency over extreme performance. Single-source supply concentration for high-purity precursor fibers creates procurement risk for European automakers.
- Foam:Polymeric cellular structures with tunable density for module-level thermal management. China's MIIT GB 38031 enforcement is accelerating thin-profile foam adoption for nail penetration test compliance.
- Thermoplastic:Injection-moldable barriers enabling complex geometries for structural battery pack integration. Michigan-based battery gigafactories specify these materials for module-to-chassis bonding applications.
Aerogel holds installed capacity. Thermoplastic is rotating up the share rankings.
Application:
Volume concentration follows battery production geography rather than end-use dispersion. Electric vehicle programs absorb the majority of qualified supplier capacity, while adjacent applications compete for residual manufacturing slots.
- Electric Vehicles:Cell-level and module-level thermal barriers preventing propagation during thermal runaway events. BMW, Volkswagen, and Mercedes-Benz mandate qualification-certified suppliers for domestic German battery assembly, compressing vendor lists to pre-approved manufacturers. Solid-state battery commercialization is expanding isolation layer complexity for next-generation cell architectures.
- Energy Storage Systems:Grid-scale battery installations requiring fire containment between rack-mounted modules. California and Texas utility procurement specifications are aligning with automotive flammability benchmarks, opening crossover qualification pathways.
- Charging Infrastructure:Thermal management for high-power connector housings and cable insulation. South Korean charging network operators specify materials matching automotive GB standard performance.
- Consumer Electronics:Compact device batteries requiring thin-profile isolation. This segment competes for supplier attention against higher-volume automotive contracts.
Electric Vehicles captures dominant volume share. Energy Storage Systems is climbing the fastest.
Manufacturing Process:
Process selection locks suppliers into specific equipment investments and cycle time economics. Extrusion and coating methods dominate high-throughput applications, while injection molding enables geometric complexity for structural integration.
- Extrusion:Continuous sheet production for blanket and mat formats. Stuttgart battery gigafactories specify extruded aerogel composites for conformable layer applications in pack floor pans.
- Coating:Intumescent and ceramic layer deposition onto carrier substrates. Extended cure cycles constrain throughput for mass-market EV platforms, limiting adoption to premium programs with flexible assembly schedules.
- Injection Molding:High-pressure forming of thermoplastic barriers with integrated mounting features. Michigan OEMs favor this process for module-to-chassis structural integration designs.
- Casting:Low-pressure molding for prototype and low-volume specialty geometries. Tooling costs restrict this process to qualification samples and aftermarket retrofit applications.
Extrusion holds installed capacity. Injection Molding is gaining share fastest.
Performance Criteria:
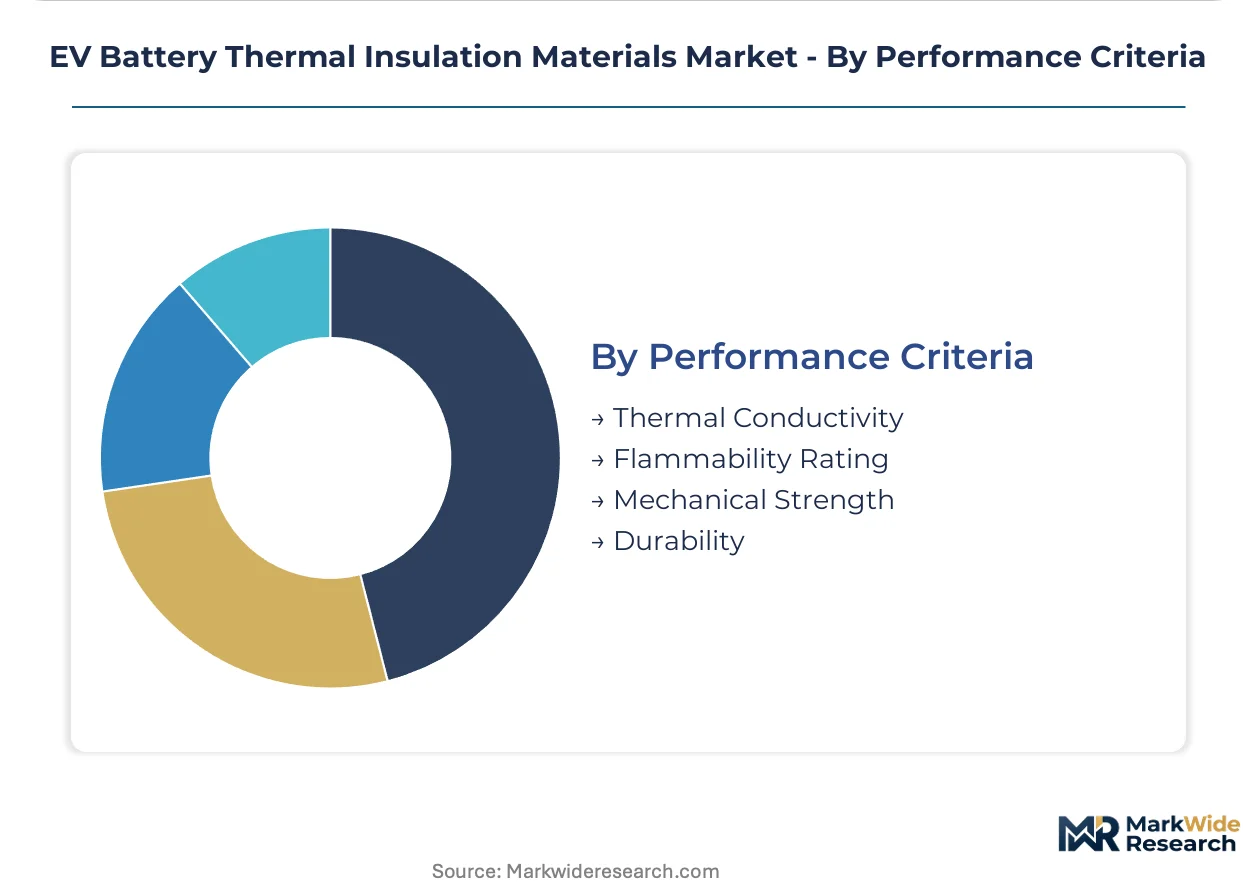
Procurement specifications cascade from regulatory test protocols rather than abstract material properties. UN ECE R100 and China's GB standards define measurable thresholds that determine supplier eligibility.
- Thermal Conductivity:Primary specification metric with hard ceilings for cell-to-cell isolation designs. Aerogel formulations achieve sub-0.020 W/m·K performance required for 800-volt platform cell spacing reduction.
- Flammability Rating:UL 94 V-0 and equivalent certifications mandatory for OEM contract eligibility. German automakers require third-party test documentation before supplier qualification.
- Mechanical Strength:Compression and tensile properties for structural load-bearing insulation layers. Module-to-chassis integration designs specify minimum values for floor pan bonding applications.
- Durability:Thermal cycling and aging performance across 15-year vehicle life targets. EMA alignment with EU Battery Regulation is forcing documentation of degradation curves for sustainability certification.
Thermal Conductivity holds specification priority. Flammability Rating is rotating up the procurement checklist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UN ECE R100 Phase 2 implementation is redirecting procurement flows toward jurisdictions with established qualification infrastructure. Battery gigafactories concentrate where regulatory clarity intersects with automotive manufacturing heritage.
Germany
BMW, Volkswagen, and Mercedes-Benz are localizing battery assembly and mandating qualification-certified insulation suppliers. KBA enforces UN ECE R100 cell-to-pack containment documentation before production approval. Stuttgart anchors aerogel composite demand for 800-volt platform cell isolation.
China
CATL, BYD, and CALB are scaling domestic thermal barrier production for export-qualified battery packs. MIIT's tightened GB 38031 enforcement requires third-party nail penetration test reports for every new cell chemistry. Yangtze River Delta battery clusters are accelerating thin-profile ceramic paper development.
United States
Michigan and Tennessee battery gigafactories are negotiating multi-year insulation supply contracts with penalty structures for qualification delays. NHTSA vehicle-level fire safety protocols shape material selection and testing requirements. Detroit module-to-chassis integration programs specify injection-moldable thermoplastic barriers.
South Korea
LG Energy Solution and Samsung SDI are qualifying suppliers for next-generation solid-state battery architectures. MFDS alignment with automotive flammability benchmarks opens crossover pathways from consumer electronics. Seoul Capital Area charging network operators specify materials matching automotive GB standard performance.
India
Domestic battery manufacturing incentives under the PLI scheme create first-mover advantage for insulation suppliers establishing local qualification laboratories. BIS is developing aligned thermal barrier standards for emerging EV production hubs. Tamil Nadu and Gujarat automotive clusters are attracting tier-one material suppliers.
EV Battery Thermal Insulation Materials Market Competitive Landscape
Listed leaders compete with private specialists across certification timelines and manufacturing scale. The supplier base concentrates around three qualification tiers: incumbents with UN ECE R100 test documentation, mid-scale regional fabricators serving single OEMs, and emerging entrants targeting cost-efficient segments. Aerogel specialists, ceramic fiber houses, and polymer formulators represent the dominant strategic archetypes. Capacity expansion and backward integration into silica precursor supply are the primary competitive moves reshaping margin structures.
Within the aerogel tier, Aspen Aerogels exemplifies scale-driven positioning through its manufacturing footprint. Among diversified material houses, DuPont and 3M Company occupy positions anchored in high-performance polymer formulation expertise. Morgan Advanced Materials represents the ceramic fiber archetype with European supply relationships.
| Leading Market Players |
|---|
| 3M Company |
| DuPont |
| Aspen Aerogels |
| Morgan Advanced Materials |
| Elkem ASA |
| Saint-Gobain |
| BASF SE |
| Parker Hannifin |
| Henkel |
| Others |
Pricing and Supply Chain Analysis
UN ECE R100 Phase 2 certification gates both supplier qualification and price differentiation simultaneously, compressing vendor lists to pre-approved manufacturers while creating steep premiums for aerogel formulations that demonstrate validated cell-to-cell propagation resistance. OEM procurement teams now weight documented thermal runaway containment performance above unit economics, fragmenting the supplier base into certification-haves and have-nots with corresponding margin spreads.
Pricing Analysis
Certification level under UN ECE R100 and China's GB 38031 standards creates the primary spread between aerogel premium tiers and fiberglass commodity alternatives. Contract-based long-term offtake agreements dominate, with volume-commitment clauses locking in multi-year supply relationships at German battery gigafactories. Price differentiation rests on thermal conductivity thresholds and third-party test documentation, with standard-range EV platforms showing highest price sensitivity against 800-volt premium architectures. Cost compression in fiberglass and thermoplastic segments is intensifying because Chinese domestic manufacturers are scaling thin-profile ceramic paper production for export-qualified battery packs.
Supply Chain Analysis
Silica precursor feedstock concentration in Germany, China, and the United States anchors raw material access for aerogel manufacturing at scale. High-purity alumina-silica fiber production draws from limited geographic clusters, creating single-source vulnerability for European automakers dependent on Morgan Advanced Materials and Saint-Gobain ceramic fiber supply. Distribution runs through direct supplier-OEM framework agreements that displace tiered sourcing through module integrators, particularly visible in Michigan and Stuttgart battery gigafactories negotiating penalty structures for qualification delays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state battery commercialization represents a technological inflection that will expand thermal isolation layer complexity and qualification timelines, favoring incumbents with certified manufacturing scale and testing infrastructure already deployed.
For Market Incumbents: Compound certification advantages by accelerating backward integration into silica precursor supply and expanding fiber-reinforced aerogel composite capacity in Stuttgart and Michigan production corridors. Aerogel manufacturing scale is the priority lever against emerging ceramic fiber specialists threatening margin pools in mass-market EV platforms.
For New Entrants and Emerging Players: Anchor in India's PLI scheme battery manufacturing incentives before domestic qualification laboratories achieve full BIS alignment, targeting Tamil Nadu and Gujarat automotive clusters with thin-profile ceramic paper formulations. White-space opportunity concentrates in recyclable thermal barriers satisfying EU Battery Regulation sustainability documentation requirements.
For Investors and Strategic Acquirers: UN ECE R100 Phase 2 implementation reshapes the acquisition landscape toward suppliers with existing third-party test documentation and OEM framework agreements. Target acquisition archetype: mid-scale regional fabricators with certified manufacturing scale but limited geographic diversification. The signal to watch is BIS standard finalization in India, which will trigger qualification laboratory buildout and first-mover consolidation windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Precursor Supply | Aspen Aerogels and DuPont are securing captive alkoxide feedstock to compress margin volatility from petrochemical price swings. |
| Qualification Laboratory Expansion | Suppliers establishing BIS-aligned testing infrastructure in Tamil Nadu capture first-mover advantage under India's PLI scheme. |
| Long-term Framework Agreement Restructuring | BMW and Volkswagen are consolidating thermal barrier procurement under direct supplier contracts with volume-commitment penalty clauses. |
| Recyclable Thermal Barrier Development | EU Battery Regulation sustainability documentation favors closed-loop material recovery systems for carbon footprint certification. |
| Module-to-Chassis Integration Partnership | Michigan battery gigafactories specify injection-moldable thermoplastic barriers bonding directly to vehicle floor pans. |
Research Methodology
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, thermal barrier manufacturing plant managers, and automotive regulatory affairs directors anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from UN ECE R100 test documentation databases, KBA production approval filings, MIIT GB 38031 enforcement records, and SEC 10-K disclosures from listed material suppliers. Bottom-up cell-level demand modeling and top-down battery pack production forecasts were triangulated to cross-verify volume estimates.
Sensitivity analysis across thermal conductivity specification thresholds, flammability certification tiers, and regional regulatory divergence shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include material type, application category, manufacturing process, and performance criteria against vehicle class and propulsion architecture. CAGRs were derived from installed capacity buildout schedules and OEM contract award timelines, with specific inputs from solid-state battery commercialization roadmaps and 800-volt platform rollout densities.
Underlying assumptions cover sustained UN ECE R100 Phase 2 enforcement stringency, continued silica precursor petrochemical feedstock availability, and stable OEM localization commitments in Germany and the United States, with deviation risk concentrated in regulatory timeline delays and ceramic fiber supply concentration disruptions. Practitioners should keep alternative scenarios live as BIS standard development and India PLI scheme implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Phenolic Insulation Market
Insulation Materials
Pipe Insulation Products Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Acoustic Materials Market
Insulation Materials
Industrial Insulation Market
Insulation Materials
Global High-Performance Insulation Market
Insulation Materials
Carbon Foam Market
Insulation Materials
Roofing Underlying Materials Market
Insulation Materials
Multi-Layer Cryogenic Insulation Market
Insulation Materials
Hot Insulation Materials Market
Insulation Materials
Flexible Insulation Market
Insulation Materials
Insulation Boards Market
Insulation Materials
Global Industrial Foam Market
Insulation Materials
Polyisocyanurate Insulation Market
Insulation Materials
Global Tank Insulation Market
Insulation Materials
Global EMI Shielding Materials Market