
 Middle East and Africa Snack Food Market | 2026-2036
Middle East and Africa Snack Food Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Snack Food Market Foresight
Modern trade expansion across Gulf cities is reshaping how snack brands reach consumers. PepsiCo Inc leverages its beverage-and-snack bundled distribution to secure shelf space in hypermarkets from Dubai to Riyadh. Almarai Company anchors dairy-adjacent snacking through its chilled supply chain dominance in Saudi Arabia. Mondelez International competes on impulse placement, controlling checkout-aisle merchandising in Carrefour and Lulu networks.
Middle East and Africa snack food comprises processed, ready-to-eat items typically manufactured through extrusion, baking, or frying, with shelf stability achieved via controlled moisture content and modified atmosphere packaging; these products serve immediate consumption needs across retail, hospitality, and travel channels. Chips and nuts sustain the largest revenue pools, driven by habitual purchase frequency in hot climates where salted formats address electrolyte preferences. Single-serve flexible packs represent the fastest-growing packaging type, as convenience stores and petrol station retail expand across secondary cities. Sweet flavor profiles still trail savory penetration but show structural momentum where multinational brands localize formulations with date, honey, and cardamom variants.
Saudi Arabia's SFDA, South Africa's Department of Health, and the UAE's Ministry of Climate Change and Environment enforce divergent sodium caps, trans-fat limits, and front-of-pack labeling rules that fragment formulation requirements across markets. Egypt's food safety authority and Nigeria's NAFDAC add further compliance layers for imported and locally manufactured snacks. Stakeholders must monitor regulatory divergence between Gulf harmonization efforts and sub-Saharan national standards when allocating R&D and production capacity.
Market Dynamics
Regulatory fragmentation between Gulf harmonization efforts and sub-Saharan national standards is forcing manufacturers to maintain parallel formulation and packaging configurations across markets. Saudi Arabia's SFDA labeling mandates diverge materially from South Africa's sodium caps and Nigeria's NAFDAC import protocols.
Growth Catalysts
- Tourism recovery in GCC cities:Hotel and airline catering channels in Dubai, Riyadh, and Doha are restocking premium single-serve formats. Duty-free retail at these hubs drives impulse purchase velocity for international brands.
- SFDA front-of-pack labeling enforcement:Saudi Arabia's mandatory nutrient disclosure rules are accelerating manufacturer investment in reformulation R&D. Cleaner-label products command shelf space in modern trade channels.
- Extrusion technology advancement:Local processors in Egypt and Morocco are adopting twin-screw extrusion for pulse-based snacks. This equipment migration reduces dependency on imported potato flake supply.
Market Restraints
- Palm oil price volatility:Frying oil input costs fluctuate with Malaysian and Indonesian export duty policies. Margins compress when currency depreciation in Egypt and Nigeria coincides with commodity spikes.
- Import dependency for modified atmosphere packaging films:Gulf manufacturers source barrier laminates primarily from European and Asian converters. Lead times extend to 12-16 weeks, constraining new product launch cadence.
- Solar thermal drying limitations:Date and fruit snack processors in Tunisia and Algeria face seasonal moisture control inconsistency. Batch rejection rates rise during humid coastal periods.
Strategic Opportunities
- Ethiopia's underpenetrated modern trade:Supermarket format expansion in Addis Ababa creates first-mover positioning for packaged snack entrants. Local distribution partnerships bypass fragmented traditional retail.
- E-commerce fulfillment integration:Jumia and Noon platforms are building chilled last-mile capability for dairy-adjacent snacking. Direct-to-consumer subscription models capture urban household pantry share.
- UAE Ministry of Climate Change and Environment green packaging incentives:Biodegradable flexible film adoption qualifies manufacturers for preferential shelf fees in Emirates retail networks.
Industry Challenges
- Food safety auditor scarcity:BRC and FSSC 22000 certification bodies have limited accredited personnel across East Africa. Factory audit backlogs delay export qualification timelines by 4-6 months.
- Legacy ERP integration with track-and-trace mandates:Nigerian and Kenyan manufacturers face capital outlays to retrofit batch serialization systems for NAFDAC and KEBS compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Snack Food Market |
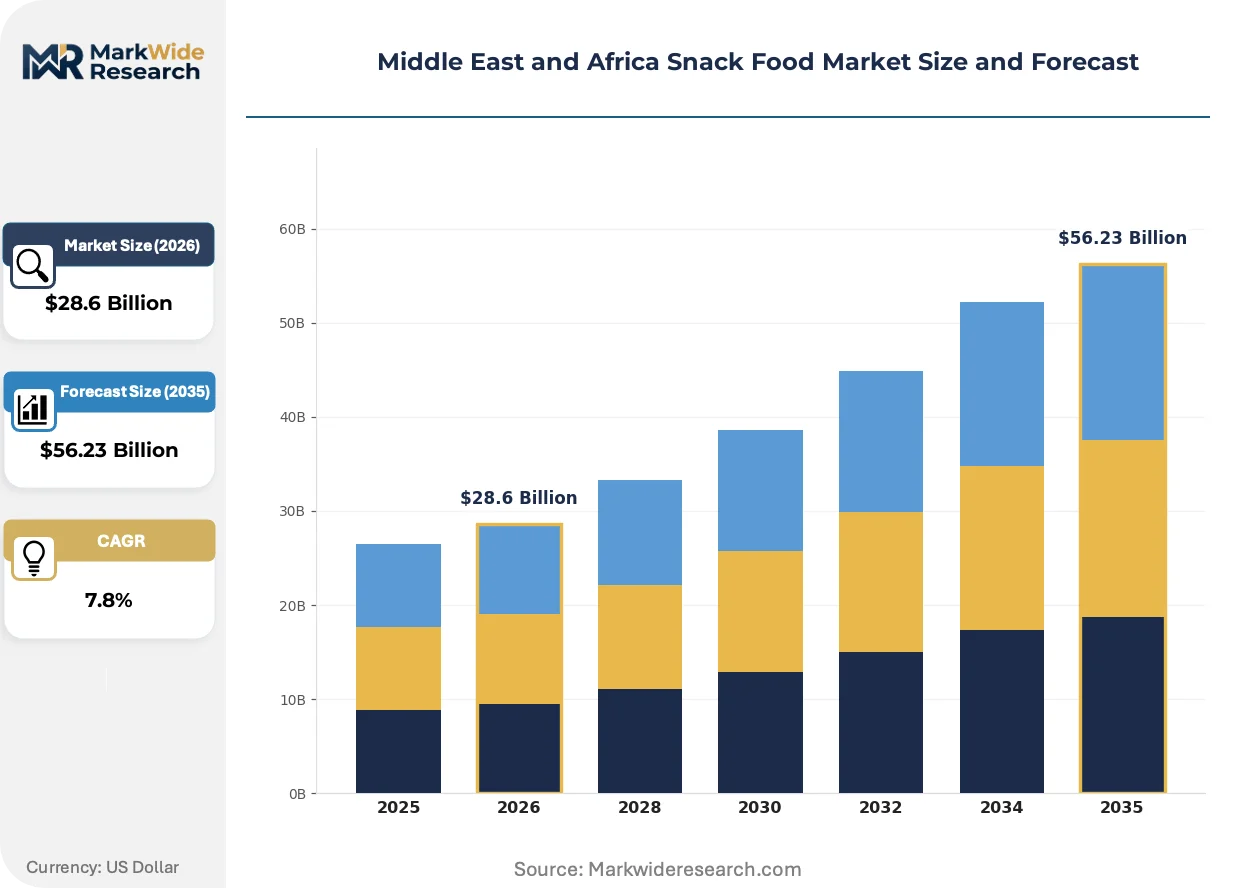
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $56.23 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Popcorn, Nuts, Trail Mix Customer Type: Retail Consumers, Foodservice Operators, Online Shoppers, Supermarkets Flavor Profile: Sweet, Savory, Spicy, Sour Packaging Type: Flexible Packs, Rigid Containers, Bulk, Single-Serve |
| Companies Covered | Unilever PLC, Almarai Company, PepsiCo Inc, Frito-Lay, General Mills Inc, Nestlé S.A., Kellogg's Company, ITC, Mondelez International, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Snack Food Market Shifts & Advancements
Digital twin technology is virtualizing production line optimization across Middle East and Africa snack manufacturing. Virtual commissioning reduces physical trial runs and accelerates new product scale-up timelines.
Modified atmosphere packaging simulation software is virtualizing shelf-life prediction for regional climate conditions. PepsiCo and Almarai operations teams in Jeddah and Riyadh deploy these tools to compress formulation testing from months to weeks. The technology is virtualizing traditional accelerated aging studies, enabling faster regional flavor localization.
South Africa's Department of Health trans-fat regulations are eliminating partially hydrogenated oils from savory snack formulations. Manufacturers reformulate with high-oleic sunflower and canola blends at 15-20% cost premiums. Chips and extruded segments absorb these input shifts through gradual retail price adjustments rather than sudden pack-size reductions.
Convenience store format proliferation is fragmenting traditional wholesale-dependent distribution in secondary Nigerian and Kenyan cities. Petrol station retail and pharmacy chains stock grab-and-go snacking adjacent to beverage and personal care. Lagos, Nairobi, and Accra witness the fastest channel shift velocity as urban commute patterns lengthen.
Middle East and Africa Snack Food Market Segmentation
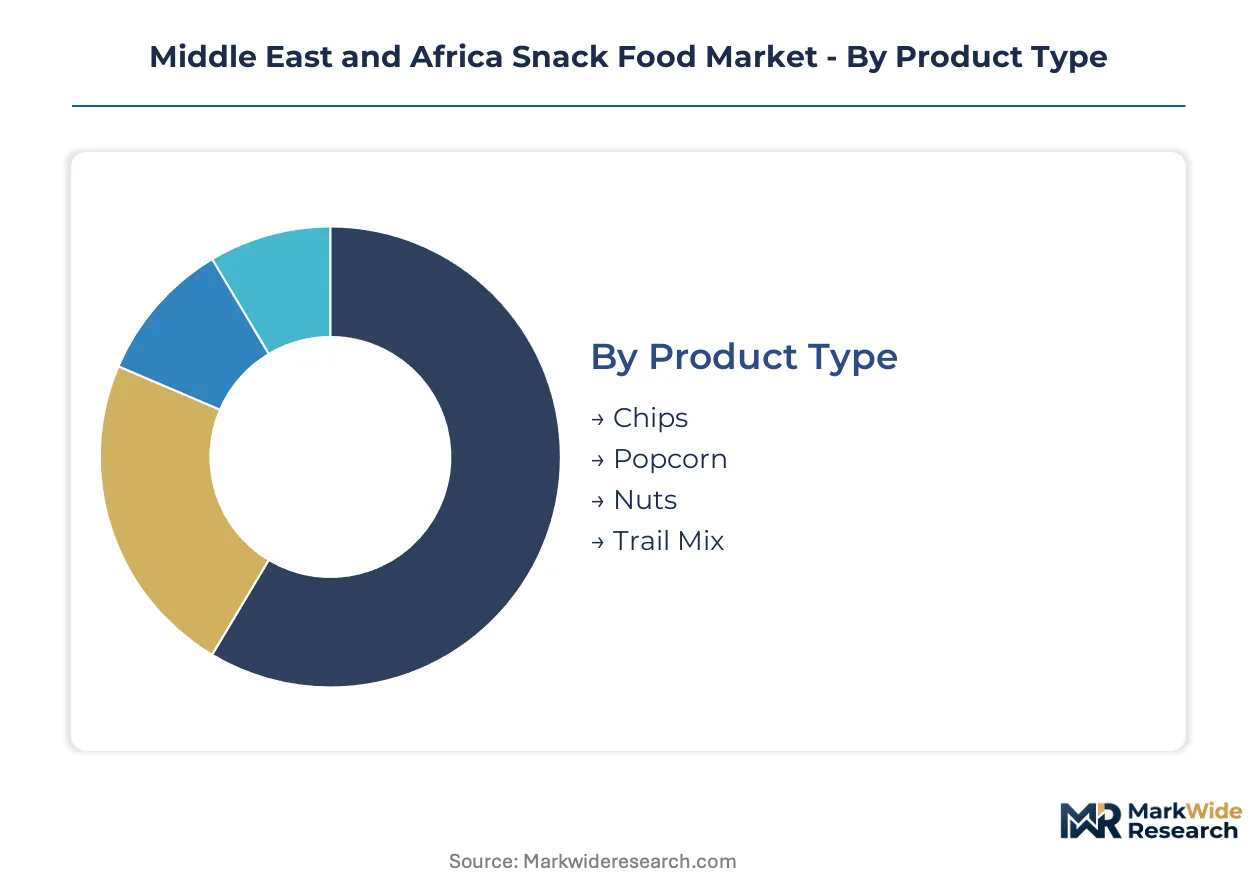
Segmentation in Middle East and Africa snack food reveals divergent growth mechanics across product maturity, channel evolution, and consumer occasion targeting. Manufacturers allocate formulation and packaging resources based on where urbanization and retail modernization are reshaping purchase behavior.
Product Type:
Mature categories dominate shelf space while emerging formats capture shifting dietary preferences in Gulf and sub-Saharan cities.
- Chips:Thin-sliced potato and cassava-based products fried in palm or sunflower oil dominate manufacturing capacity across Egypt and South Africa. Saudi Arabia's SFDA sodium caps are forcing reformulation of legacy salted variants in Jeddah and Riyadh hypermarkets.
- Popcorn:Air-popped and kettle-corn variants serve cinema and home-entertainment occasions in Dubai and Lagos. Microwaveable bag formats are displacing loose-kernel retail in Nairobi supermarket chains.
- Nuts:Roasted and flavored almond, cashew, and pistachio SKUs anchor premium positioning in UAE duty-free and airline catering channels.
- Trail Mix:Dried fruit and nut combinations target health-positioned convenience stores in Accra and Addis Ababa with protein-forward labeling.
Chips retain volume leadership; trail mix holds the steepest expansion curve.
Customer Type:
Channel fragmentation is redistributing margin capture between traditional wholesale and emerging direct-to-consumer pathways.
- Retail Consumers:Individual households purchasing through modern trade and traditional souks generate baseline volume in Cairo, Casablanca, and Johannesburg. Impulse placement at checkout drives unplanned trial of new flavor launches.
- Foodservice Operators:Hotels, airlines, and cinema chains in Doha and Dubai procure single-serve formats through institutional distributors. Tourism recovery is restocking minibars and in-flight meal carts with premium savory options.
- Online Shoppers:Jumia and Noon platform users in Lagos and Nairobi subscribe to bulk snack bundles with free-delivery thresholds. Chilled last-mile infrastructure is expanding dairy-adjacent snacking penetration.
- Supermarkets:Carrefour and Lulu hypermarkets in Gulf cities command slotting fees and exclusive pack sizes from multinational suppliers. Private-label expansion in Shoprite and Pick n Pay networks pressures branded pricing in South Africa.
Supermarkets retain volume leadership; online shoppers are climbing the fastest.
Flavor Profile:
Palate localization separates multinational adaptation from regional challenger strategies.
- Savory:Salted, cheese, and barbecue variants formulated with reduced sodium meet Saudi SFDA disclosure requirements while maintaining habitual purchase frequency in hot climates.
- Sweet:Date, honey, and cardamom infusions localize Western confectionery formats for Ramadan and Eid gifting occasions in UAE and Qatar.
- Spicy:Chili and peri-peri heat levels calibrated for Nigerian and Ghanaian preferences differentiate regional brands from imported mild variants.
- Sour:Tamarind and citrus-acidulated products target East African and North African taste traditions with limited multinational competition.
Savory retains volume leadership; sweet holds the steepest expansion curve.
Packaging Type:
Format economics and shelf-life engineering determine regional manufacturing investment priorities.
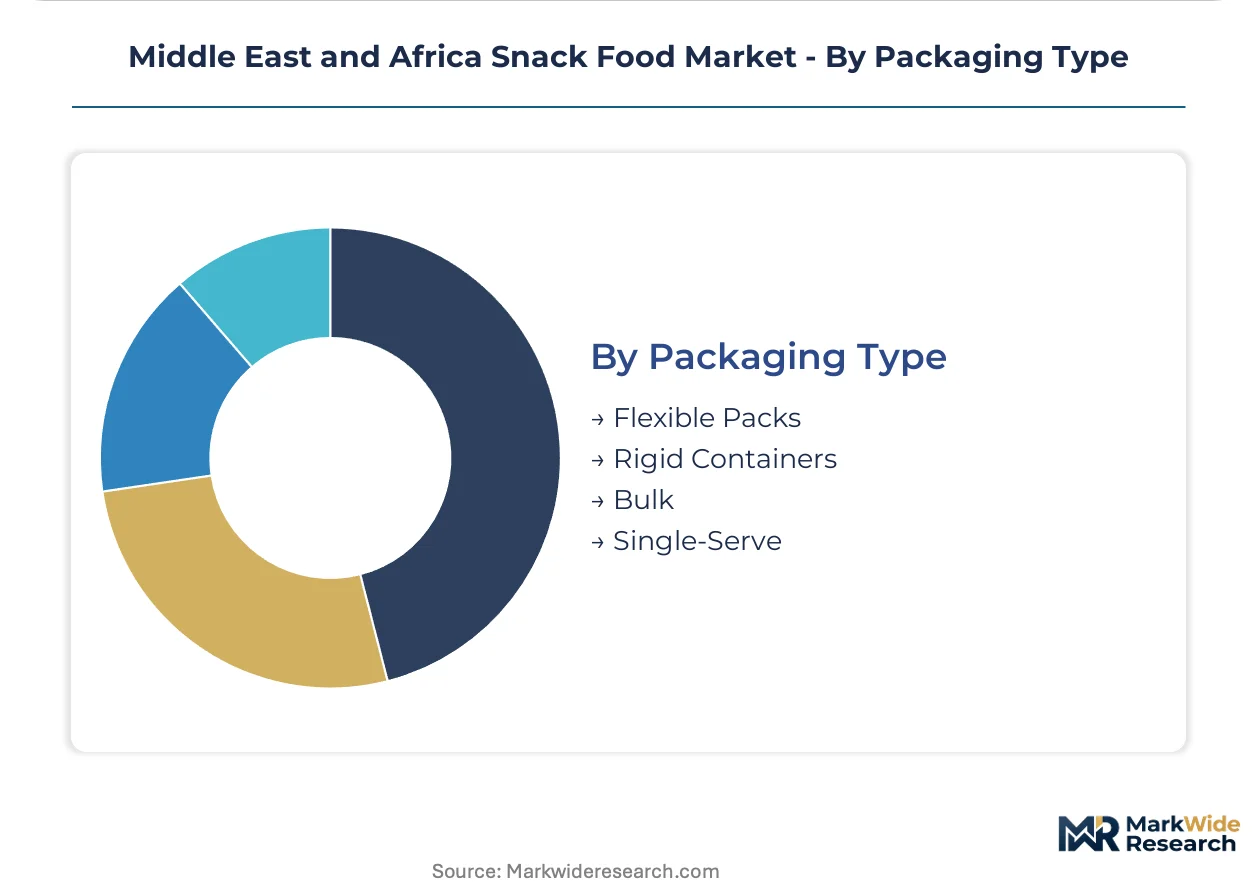
- Flexible Packs:Metallized polyester and polyethylene laminates with modified atmosphere sealing dominate chips and nut distribution across humidity-variable climates. Import dependency for barrier films constrains new product launch velocity in Gulf markets.
- Single-Serve:20-40 gram portion packs serve petrol station retail and convenience store expansion in secondary Nigerian and Kenyan cities. Price-point accessibility drives trial among young urban commuters.
- Rigid Containers:Polypropylene tubs and tins preserve crispness for premium gifting assortments in UAE and Saudi Arabia during holiday periods.
- Bulk:Institutional formats for foodservice and traditional wholesale channels in Egypt and Morocco minimize per-unit packaging cost for price-sensitive volume.
Flexible packs retain volume leadership; single-serve is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA enforcement in Saudi Arabia is anchoring regulatory momentum across the Middle East and Africa snack food market. Divergent sodium caps and labeling mandates between Gulf Cooperation Council harmonization efforts and sub-Saharan national standards are fragmenting compliance requirements. Urban retail expansion and tourism recovery are redistributing demand concentration across key metropolitan clusters.
Saudi Arabia
Modern trade penetration in Riyadh and Jeddah is accelerating premium single-serve format adoption. SFDA front-of-pack labeling mandates are compelling manufacturers to reformulate legacy salted variants and redesign packaging disclosures. The Eastern Province industrial corridor hosts extrusion and frying capacity serving Gulf export markets.
United Arab Emirates
Dubai's duty-free retail and airline catering channels are restocking international brands as tourism flows recover. The Ministry of Climate Change and Environment green packaging incentives are driving biodegradable flexible film adoption among Emirates-based manufacturers. Abu Dhabi's hypermarket networks command exclusive pack sizes and slotting fees from multinational suppliers.
Nigeria
Young urban consumers in Lagos are driving retail demand for convenient, portable snack options through convenience store and petrol station expansion. NAFDAC import protocols and batch serialization mandates are adding compliance layers for both imported and locally manufactured products. Secondary cities including Abuja and Port Harcourt witness rapid channel shift velocity as traditional wholesale dependence fragments.
South Africa
The Department of Health trans-fat regulations are eliminating partially hydrogenated oils from savory snack formulations. Shoprite and Pick n Pay private-label expansion pressures branded pricing across Johannesburg and Cape Town retail networks. The country's food safety auditor scarcity delays BRC and FSSC 22000 certification timelines for regional exporters.
Egypt
Local processors in Cairo and Alexandria are adopting twin-screw extrusion technology for pulse-based snacks to reduce potato flake import dependency. The national food safety authority maintains additional compliance layers for imported snack products. Currency depreciation pressures margins when palm oil input costs spike concurrently with commodity fluctuations.
Middle East and Africa Snack Food Market Competitive Landscape
Multinational conglomerates and regional dairy specialists split the market between scale-driven distribution leverage and chilled supply chain dominance. The vendor base concentrates around beverage-snack bundling capabilities and hypermarket slotting fee negotiations. Three archetypes define competitive positioning: global FMCG giants with integrated distribution, regional dairy-adjacent players with cold chain control, and impulse-merchandising specialists commanding checkout-aisle placement. Dominant competitive moves include portfolio diversification into cleaner-label variants and strategic partnerships with e-commerce platforms for last-mile chilled fulfillment.
Among the multinational tier, PepsiCo Inc and Mondelez International exemplify divergent route-to-market strategies. PepsiCo leverages beverage-and-snack bundled distribution to secure shelf space across Gulf hypermarkets. Mondelez International occupies a position anchored on impulse placement and checkout-aisle merchandising control in modern trade networks. Almarai Company represents the regional specialist archetype, with dairy-adjacent snacking penetration enabled by chilled supply chain dominance in Saudi Arabia.
| Leading Market Players |
|---|
| Unilever PLC |
| Almarai Company |
| PepsiCo Inc |
| Frito-Lay |
| General Mills Inc |
| Nestlé S.A. |
| Kellogg's Company |
| ITC |
| Mondelez International |
| Others |
Supply & Pricing Matrix
Malaysian and Indonesian palm oil export duty policies concentrate frying oil input costs for snack manufacturers across Egypt and Nigeria. Margin pools shift downstream toward brands with reformulation agility when currency depreciation coincides with commodity spikes.
Pricing Analysis
Price spreads between Gulf hypermarkets and sub-Saharan traditional retail exceed fifty percent for identical chip and nut SKUs. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by sodium compliance tier and chilled last-mile capability. Pricing pressure stems from South Africa's trans-fat reformulation mandates absorbing fifteen to twenty percent input cost premiums. Traditional wholesale buyers in Cairo and Casablanca exhibit highest price sensitivity; duty-free and airline catering channels in Dubai show lowest.
Supply Chain Analysis
European and Asian export controls on modified atmosphere packaging barrier technology constrain Gulf manufacturers' access to metallized polyester laminates. Supply concentrates in Germany, China, and Japan for barrier film conversion, while palm oil sourcing feeds from Malaysia and Indonesia. Single-source vulnerability runs through twelve-to-sixteen-week lead times for imported packaging films. Distribution runs through hypermarket slotting fee negotiations in Riyadh and Dubai, with traditional wholesale fragmentation persisting in Lagos and Nairobi secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat. SFDA compliance investments create switching costs that lock in modern trade shelf space.
For Market Incumbents: Harden formulation R&D capabilities against Saudi sodium cap divergence from sub-Saharan standards. Secure backward integration into pulse-based extrusion capacity in Egypt to reduce potato flake import exposure. Channel control through beverage-snack bundling defends against private-label expansion in South African retail.
For New Entrants and Emerging Players: Pursue Ethiopia's underpenetrated supermarket format expansion in Addis Ababa before multinational slotting fee escalation. Target trail mix and protein-forward positioning in Accra convenience stores where health-positioned snacking shows structural momentum. Direct-to-consumer subscription models through Jumia and Noon platforms offer lowest customer acquisition cost entry.
For Investors and Strategic Acquirers: Capital is best deployed toward regional dairy-adjacent specialists with chilled supply chain dominance and SFDA pre-approval status. Long-term viability across the analysis window hinges on reformulation agility under divergent Gulf and sub-Saharan regulatory regimes. Watch for NAFDAC batch serialization mandate acceleration as inflection indicator for compliance cost barriers.
| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation R&D Investment | SFDA sodium cap compliance secures modern trade shelf access in Saudi hypermarkets. |
| Backward Integration into Extrusion | Local pulse-based snack production reduces Egyptian import dependency and currency exposure. |
| E-commerce Fulfillment Partnership | Noon and Jumia chilled last-mile capability expands dairy-adjacent snacking penetration. |
| Biodegradable Packaging Adoption | UAE Ministry of Climate Change incentives qualify manufacturers for preferential retail fees. |
| Regional Certification Acquisition | BRC and FSSC 22000 credentials overcome East African food safety auditor scarcity delays. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with snack brand managers, hypermarket category buyers, extrusion equipment suppliers, and NAFDAC regulatory affairs specialists. Secondary validation drew from SFDA labeling guidance documents, South Africa Department of Health trans-fat regulations, Nielsen retail audit data for Gulf Cooperation Council cities, and customs records for Malaysian palm oil shipments. Bottom-up volume modeling triangulated against top-down category spending estimates.
Calibration anchored volume and value outputs across the projection horizon against historical modern trade expansion rates and tourism recovery trajectories. Segmentation dimensions modeled include product type, flavor profile, packaging format, customer channel, and regulatory compliance tier. CAGRs were derived from slope analysis of category penetration curves. Forecast inputs incorporated extrusion technology adoption rates and e-commerce fulfillment infrastructure buildout timelines.
Sensitivities concentrate around palm oil price volatility, SFDA enforcement acceleration, and NAFDAC serialization mandate timing. Forecasts reflect assumptions on urban retail format expansion and regulatory harmonization progress. Material shifts in Gulf tourism recovery velocity or sub-Saharan currency stability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Kids Snacks Market
Snacks
Low Calorie Cookies Market
Snacks
Organic Chips Market
Snacks
Legume-Based Snacks Market
Snacks
Refrigerated Snacks Market
Snacks
India Snack Bar Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
UAE Cereal Bar Market
Snacks
North America Baked Chips Market
Snacks
Roasted Snacks Market
Snacks
Snack Food Packaging Market
Snacks
Trail Mix Market
Snacks
Snack Products Market
Snacks
Organic Snack Food Market
Snacks
Savoury Biscuits Market
Snacks
Southeast Asia Savory Snacks Market