
 High Viscosity Bone Cement Market | 2026-2036
High Viscosity Bone Cement Market Size, Share, and Industry Trends Forecast 2026-2036
High Viscosity Bone Cement Market Insights
Germany is reshaping European supply dynamics through expanded PMMA cement production capacity serving central European orthopedic networks. Stryker leverages its integrated hospital contracting infrastructure to secure long-term cement supply agreements across North American health systems. Zimmer Biomet anchors its position through specialized high-viscosity formulations optimized for revision arthroplasty procedures. Heraeus Medical competes via deep manufacturing expertise in acrylic bone cement chemistry accumulated over decades of European market presence.
High viscosity bone cement denotes polymethyl methacrylate (PMMA) or alternative polymer-based formulations with elevated dough-phase viscosity exceeding 1,000 Pa·s, designed to resist phase separation and enable controlled delivery into prepared bone voids under pressurized injection. The material functions primarily to mechanically interlock prosthetic implants with cancellous bone structure, transferring load while maintaining positional stability. PMMA-based cement dominates current revenue pools due to decades of clinical validation and established reimbursement pathways, while calcium phosphate cement represents the fastest-growing category as surgeons seek osteoconductive alternatives for younger patient cohorts. Joint replacement applications sustain the largest absolute volume, though spinal procedures are gaining share as minimally invasive vertebral augmentation techniques proliferate.
FDA 510(k) clearance pathways govern U.S. market entry for bone cement devices, while the EU MDR imposes enhanced clinical evidence requirements for implantable cement products sold in European markets. ISO 5833 standards define mechanical performance benchmarks including compressive strength and setting time parameters that manufacturers must satisfy for commercial access. Stakeholders should monitor evolving MDR notified body capacity constraints and FDA orthopedic panel guidance revisions that could alter approval timelines and competitive positioning.
Market Dynamics
Hospital consolidation across the United States is compressing formulary diversity and forcing cement manufacturers into exclusive supply contracts with integrated delivery networks. This structural concentration is reshaping pricing power and distribution economics throughout the orthopedic supply chain.
Growth Catalysts
- EU MDR compliance deadlines:Biocompatibility testing mandates are filtering out smaller cement suppliers and expanding market share for validated manufacturers with established notified body relationships.
- Outpatient joint migration:Ambulatory surgery centers in Germany are expanding cement procurement volumes as knee and hip procedures shift from inpatient settings.
- Calcium phosphate chemistry:Osteoconductive alternatives are capturing surgeon preference in younger patient cohorts seeking bone-integrating fixation solutions.
Market Restraints
- Methyl methacrylate monomer volatility:Petrochemical feedstock fluctuations compress margin stability for PMMA-based cement producers without backward integration into monomer supply.
- Notified body bottleneck:EU MDR implementation has reduced certification capacity across European conformity assessment organizations, extending product approval timelines.
- Antibiotic-loaded substitution:Systemic infection prophylaxis protocols in some health systems are displacing antimicrobial-impregnated cement demand in primary arthroplasty.
Strategic Opportunities
- Spinal augmentation expansion:Vertebroplasty and kyphoplasty procedures are creating cement volume growth outside traditional joint replacement applications.
- Indian orthopedic infrastructure:Government hospital modernization programs under the country's national health mission are expanding cement-accessible surgical capacity.
- Digital surgical planning integration:Preoperative templating software is enabling patient-specific cement dosing and delivery system configurations.
Industry Challenges
- Polymerization control expertise:Cement mixing technicians with calibrated viscosity management skills remain scarce in expanding ambulatory settings.
- Legacy sterilization validation:Gamma and electron beam sterilization protocol transitions require extensive biocompatibility requalification under ISO 10993 standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Viscosity Bone Cement Market |
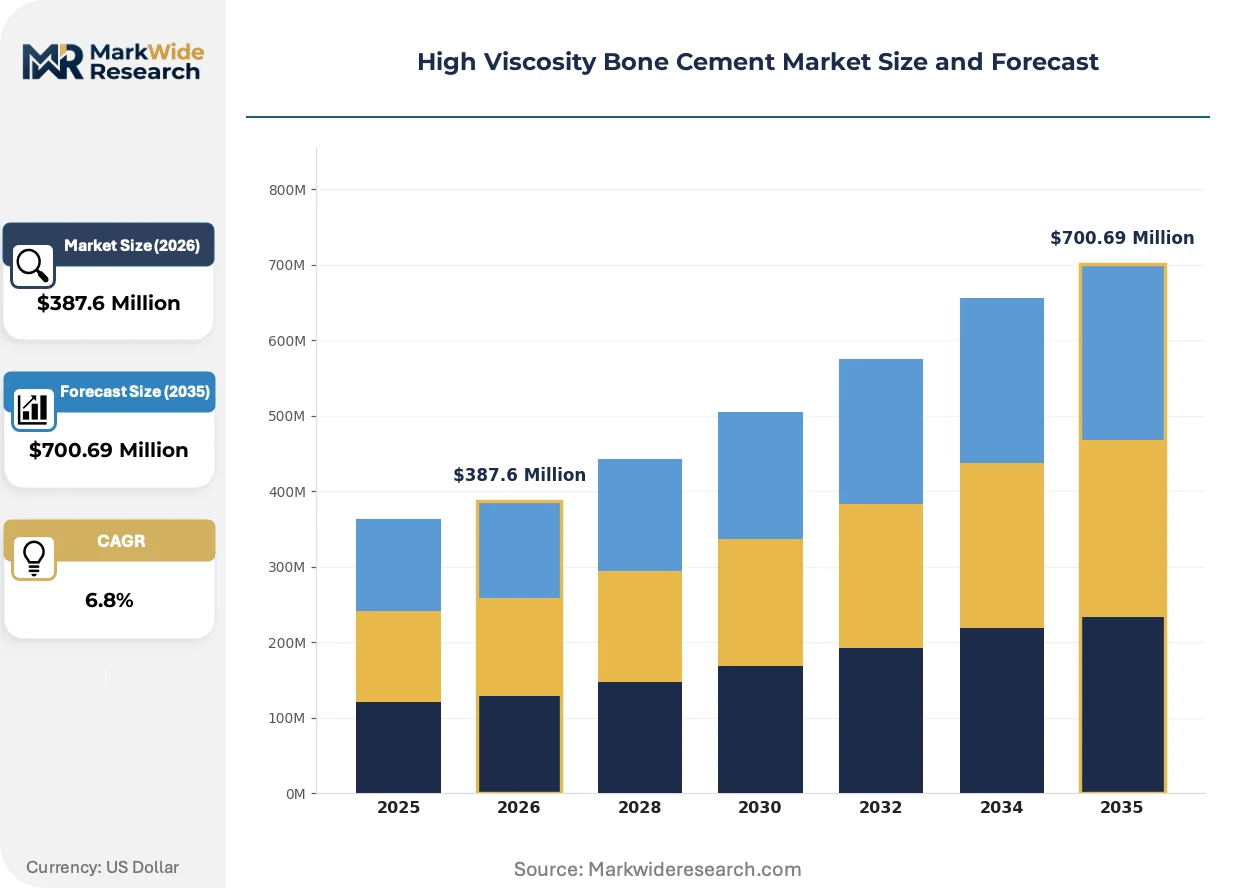
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PMMA-based Cement, Calcium Phosphate Cement, Glass Ionomer Cement, Polyethylene Glycol-based Cement Application: Osteoporosis Treatment, Joint Replacement, Spinal Procedures, Trauma Surgery End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Rehabilitation Facilities Distribution Channel: Direct Sales, Medical Distributors, Online Platforms, Wholesalers |
| Companies Covered | Stryker, Zimmer Biomet, Heraeus Medical, DePuy Synthes, Smith & Nephew, DJO Global, Tecres, G21, Teknimed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Viscosity Bone Cement Market Trends and Innovations
Material science convergence with digital surgical workflows is redefining cement application precision and postoperative outcome predictability. Three developments are restructuring competitive advantage.
Antibiotic-eluting PMMA formulations are hybridizing with local carrier technologies to extend antimicrobial release profiles beyond traditional gentamicin-loaded cements. Revision arthroplasty specialists in tertiary referral centers are adopting these hybrid systems at accelerating rates. The technology is hybridizing infection prophylaxis economics and opening premium pricing tiers for validated extended-release formulations.
FDA 510(k) orthopedic panel guidance revisions are tightening predicate device equivalence standards for high-viscosity cement submissions. Manufacturers now face expanded mechanical testing requirements and clinical data expectations for modified formulations. North American market entrants are responding by front-loading biocompatibility studies and predicate selection strategies.
Direct-to-facility distribution models are displacing traditional distributor intermediaries in consolidated health system procurement. Integrated delivery networks in the United States are negotiating master service agreements that bundle cement supply with instrumentation and implant provision. This channel compression is most visible in multi-hospital systems spanning Texas, Florida, and Ohio markets.
High Viscosity Bone Cement Market Segmentation
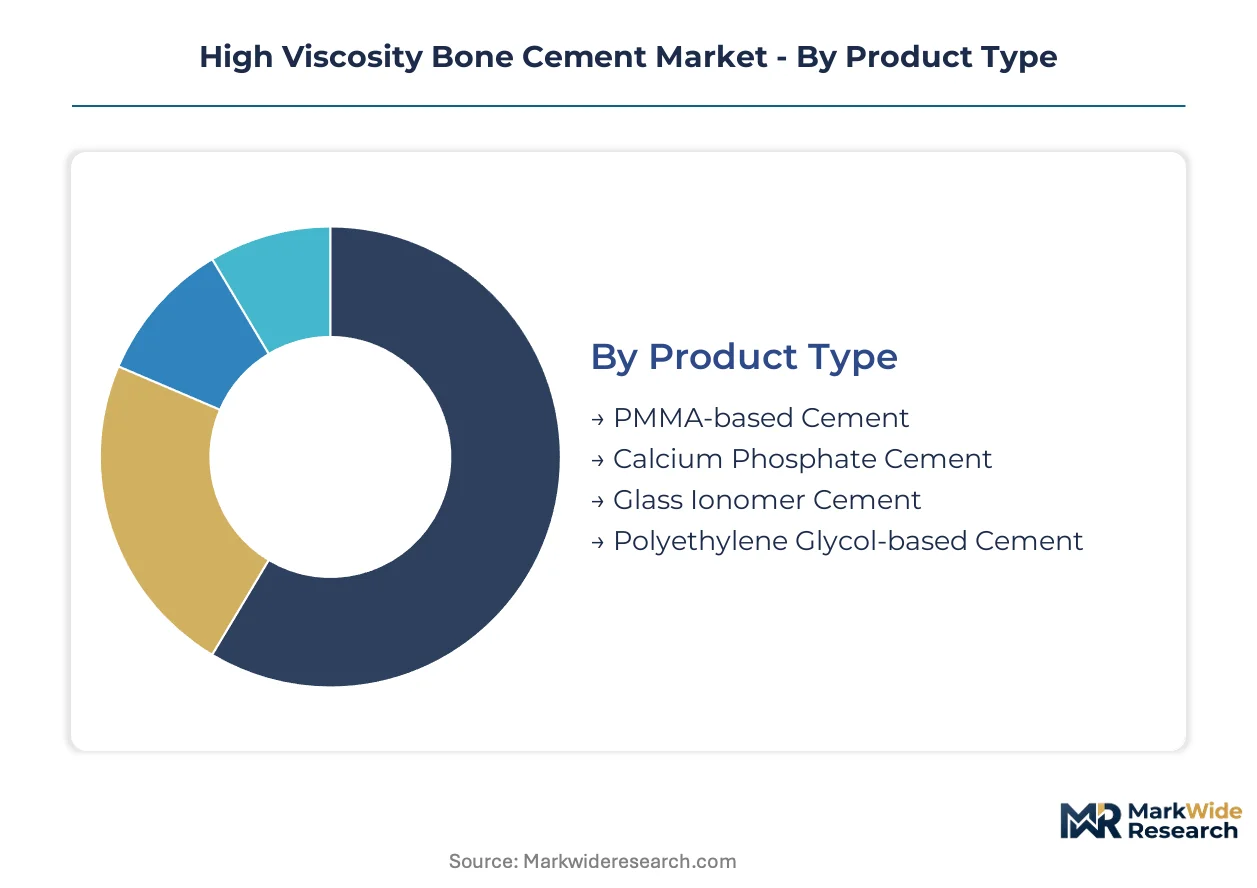
High viscosity bone cement segmentation reveals divergent service intensity requirements across product chemistries and clinical settings. PMMA formulations demand intensive technical support for mixing calibration, while calcium phosphate systems require sustained surgeon training programs. Distribution channel selection directly shapes aftermarket service economics and inventory carrying costs.
Product Type:
After-sales service intensity varies sharply across cement chemistries, with polymerization-controlled formulations requiring dedicated field engineering support.
- PMMA-based Cement:Polymethyl methacrylate formulations with dough-phase viscosity exceeding 1,000 Pa·s dominate current surgical volume through decades of mechanical validation. Demand concentrates in United States hospital systems where Stryker and Zimmer Biomet maintain captive service teams for mixing protocol training. FDA 510(k) predicate pathways reinforce incumbent positioning through established biocompatibility dossiers.
- Calcium Phosphate Cement:Osteoconductive alternatives enable direct bone bonding without fibrous encapsulation, appealing to revision specialists seeking biological fixation. German orthopedic clinics in Berlin and Munich are expanding procurement for younger patient cohorts requiring load-sharing implant integration. Extended setting times demand precision mixing support that strains traditional distributor service models.
- Glass Ionomer Cement:Fluoroaluminosilicate formulations serve niche dental-orthopedic crossover applications with limited high-viscosity adaptation.
- Polyethylene Glycol-based Cement:Hydrogel-integrated systems target experimental drug-eluting applications with unproven commercial scale.
PMMA-based Cement holds the largest share; momentum sits with Calcium Phosphate Cement.
Application:
Procedure volume distribution determines cement consumption patterns, with arthroplasty sustaining absolute demand while spinal intervention expands fastest.
- Joint Replacement:Hip and knee arthroplasty procedures consume the majority of high-viscosity cement volume through mechanical interlock requirements for load-bearing implants. United States ambulatory surgery centers in Texas and Florida are migrating primary joint cases from inpatient settings, compressing delivery logistics into same-day discharge protocols. Hospital consolidation is standardizing cement formulary choices across integrated delivery networks.
- Spinal Procedures:Vertebroplasty and kyphoplasty techniques for osteoporotic compression fractures are expanding cement addressable market beyond traditional joint applications. German spinal surgeons in Stuttgart and Hamburg are adopting minimally invasive vertebral augmentation with specialized high-viscosity injection systems. EU MDR biocompatibility testing mandates are filtering out suppliers without established notified body relationships.
- Osteoporosis Treatment:Prophylactic vertebral augmentation remains limited to high-risk patient stratification protocols.
- Trauma Surgery:Fracture fixation applications favor alternative fixation methods with limited cement penetration.
Joint Replacement captures dominant volume; Spinal Procedures are climbing the fastest.
End User:
Facility type dictates procurement sophistication, with hospital systems leveraging scale against ambulatory centers prioritizing flexibility.
- Hospitals:Tertiary medical centers perform complex revision arthroplasty requiring validated cement formulations with extended mechanical testing documentation. United States health systems spanning Ohio and Illinois are negotiating master service agreements bundling cement supply with instrumentation provision. FDA orthopedic panel guidance revisions are tightening predicate equivalence standards for new hospital formulary entrants.
- Ambulatory Surgical Centers:Outpatient joint facilities in Germany are expanding cement procurement volumes as knee and hip procedures shift from inpatient reimbursement categories. Lean staffing models demand pre-mixed or simplified delivery systems that reduce polymerization control expertise requirements.
- Orthopedic Clinics:Specialist practices in Berlin and Munich are integrating cement procurement for outpatient joint procedures.
- Rehabilitation Facilities:Post-acute settings maintain minimal direct cement consumption through procedural referral patterns.
Hospitals retain dominant procurement scale; Ambulatory Surgical Centers are gaining share fastest.
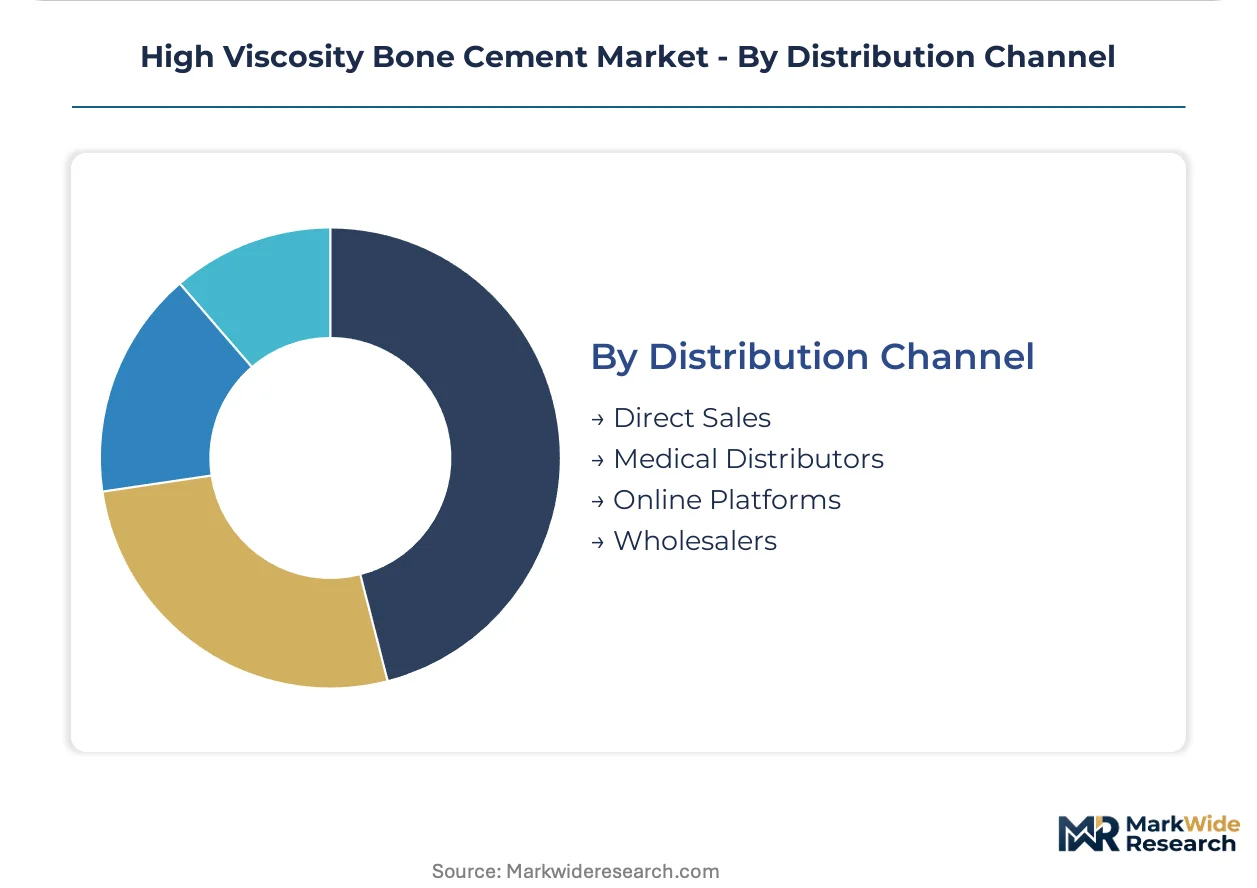
Distribution Channel:
Channel structure determines margin capture, with direct models displacing intermediaries in consolidated health system procurement.
- Direct Sales:Manufacturer-to-facility relationships eliminate distributor markups and enable customized delivery system configurations. Stryker leverages integrated hospital contracting infrastructure across North American health systems for exclusive supply agreements. Field service teams provide mixing protocol training that substitutes for traditional clinical engineering support.
- Medical Distributors:Regional intermediaries maintain relevance in fragmented clinic networks lacking procurement scale for direct manufacturer negotiation. German orthopedic supply chains rely on specialized distributors for central European hospital network coverage.
- Online Platforms:Digital procurement channels serve small-volume purchasers with limited formulary standardization requirements.
- Wholesalers:Bulk distribution models concentrate in commodity cement categories with minimal technical service differentiation.
Direct Sales commands premium positioning; Medical Distributors retain structural role in fragmented geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PMMA monomer production clusters in Germany and the United States concentrate upstream supply for orthopedic cement manufacturing. Hospital procurement consolidation in North America and EU MDR compliance deadlines in Europe are reshaping competitive access across major markets.
United States
Ambulatory surgery centers in Texas and Florida are expanding cement volumes as knee and hip procedures migrate to outpatient settings. FDA orthopedic panel guidance revisions are tightening predicate equivalence standards for new cement submissions. Integrated delivery networks spanning Ohio and Illinois are negotiating master service agreements that bundle cement supply with instrumentation provision.
Germany
Orthopedic clinics in Berlin and Munich are accelerating procurement for outpatient joint procedures as reimbursement shifts favor same-day discharge. EU MDR biocompatibility testing mandates are filtering out smaller cement suppliers without established notified body relationships. Stuttgart and Hamburg spinal surgery centers are adopting minimally invasive vertebral augmentation with specialized high-viscosity injection systems.
China
Hospital modernization programs under the national health mission are expanding cement-accessible surgical capacity in tertiary medical centers. NMPA regulatory pathways for implantable cements are converging toward ISO 5833 mechanical performance benchmarks. Yangtze River Delta manufacturing clusters are developing domestic PMMA monomer capacity to reduce import dependency.
India
Government hospital modernization initiatives are creating cement demand in public sector orthopedic units across Maharashtra and Karnataka. CDSCO medical device registration requirements are formalizing quality standards for imported and domestically manufactured cements. Delhi-NCR private hospital chains are standardizing cement formulary choices through centralized procurement committees.
Japan
Aging demographics are sustaining arthroplasty procedure volumes in Kanto and Kansai metropolitan hospitals. PMDA regulatory reviews emphasize extended mechanical testing documentation for revision arthroplasty cement formulations. Nagoya-based medical device distributors are consolidating regional coverage for orthopedic supply chains.
High Viscosity Bone Cement Market Competitive Landscape
Integrated orthopedic conglomerates and specialized cement chemists split the market between formulary dominance and manufacturing expertise. Consolidated health system procurement in the United States favors vendors with captive service infrastructure, while European market access hinges on notified body relationships. Three archetypes prevail: diversified orthopedic majors with hospital contracting scale, European chemical specialists with acrylic polymer heritage, and regional distributors with fragmented clinic network coverage. Competitive moves center on exclusive supply agreements with integrated delivery networks and backward integration into monomer production.
Among diversified orthopedic majors, Stryker and Zimmer Biomet exemplify the integrated contracting archetype through North American health system penetration. Heraeus Medical occupies a position within the European chemical specialist tier, leveraging decades of acrylic bone cement manufacturing presence. These three anchors represent distinct strategic positions: formulary bundling, revision procedure specialization, and polymer chemistry depth.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| Heraeus Medical |
| DePuy Synthes |
| Smith & Nephew |
| DJO Global |
| Tecres |
| G21 |
| Teknimed |
| Others |
Pricing and Supply Chain Analysis
Ruhr Valley PMMA monomer production clusters anchor European cement manufacturing capacity, concentrating upstream supply leverage among German chemical producers who translate feedstock control into formulary pricing power across central European orthopedic networks.
Pricing Analysis
EU MDR dictates the pricing tier structure across the European high viscosity bone cement market, separating validated manufacturers with established notified body relationships from filtered competitors lacking certification depth. Three-tier pricing structure across premium antibiotic-eluting formulations, standard mechanical-grade cements, and economy unmodified PMMA bases reflects after-sales service bundling and biocompatibility dossier completeness. Cost compression in standard-tier PMMA cements is intensifying because hospital consolidation in the United States is compressing formulary diversity and forcing exclusive supply negotiations. Ambulatory surgical centers exhibit highest price sensitivity due to lean staffing models and same-day discharge economics, while tertiary revision centers prioritize mechanical validation documentation over unit cost.
Supply Chain Analysis
Methyl methacrylate monomer feedstock draws from petrochemical complexes in Germany, the United States, and China, with Yangtze River Delta manufacturing clusters developing domestic capacity to reduce import dependency for Asian cement producers. Acrylic polymer resins, radiopaque additives, and antibiotic powders constitute critical input categories with specialized handling requirements. Single-source vulnerability concentrates in gamma sterilization services following ISO 10993 protocol transitions requiring extensive biocompatibility requalification. Distribution runs through direct-to-facility models displacing traditional intermediaries in consolidated North American health systems, while specialized regional distributors retain structural relevance in fragmented European clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists in this market as outpatient joint migration creates service intensity niches that incumbent formulary bundlers struggle to address with standardized hospital contracting infrastructure.
For Market Incumbents: Harden exclusive supply agreement structures through integrated instrumentation bundling that raises switching costs for consolidated United States health systems. Deepen backward integration into PMMA monomer production to buffer margin compression from petrochemical feedstock volatility. Prioritize notified body relationship investment ahead of EU MDR compliance deadlines to filter regional competition. For New Entrants and Emerging Players: Indian government hospital modernization programs under the national health mission offer the most penetrable entry corridor for cement manufacturers lacking established North American or European formulary presence. Target ambulatory spinal augmentation applications in German orthopedic clinics where specialized high-viscosity injection system expertise remains scarce and distributor service models strain. Pursue digital surgical planning integration partnerships as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among European chemical specialists with decades of acrylic bone cement manufacturing heritage and captive notified body certification infrastructure. Long-term viability across the analysis window favors acquisition targets with demonstrated polymerization control expertise and established surgeon training program economics. Watch FDA orthopedic panel guidance revisions as inflection indicator for predicate equivalence standard tightening that would advantage incumbents with front-loaded biocompatibility studies.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Filters smaller suppliers without notified body relationships, consolidating share among validated manufacturers. |
| Backward Integration into Monomer Supply | Buffers German and United States producers from methyl methacrylate feedstock price volatility compressing margins. |
| Direct-to-Facility Distribution Buildout | Eliminates distributor markups in Texas and Ohio integrated delivery networks negotiating master service agreements. |
| Antibiotic-Eluting Formulation Development | Captures revision arthroplasty premium pricing tiers through extended antimicrobial release profile validation. |
| Digital Surgical Planning Integration | Enables patient-specific cement dosing configurations that differentiate against standardized delivery competitors. |
Research Methodology
A standing panel of orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and ISO 5833 mechanical testing standards. Bottom-up cement volume estimates by procedure type triangulated with top-down manufacturer revenue analysis across product chemistry segments.
Scenario-bracketing anchored projections across conservative, baseline, and accelerated adoption trajectories for calcium phosphate cement penetration and ambulatory surgery center joint migration. Segmentation modeling incorporated product chemistry, application procedure type, end-user facility category, and distribution channel structure. CAGRs derived from procedure volume growth rates, pricing trend assumptions, and mix-shift dynamics between PMMA and osteoconductive alternatives. Forecast inputs included EU MDR implementation timelines, FDA orthopedic panel guidance revision schedules, and hospital consolidation transaction velocity.
Practitioners should monitor notified body capacity constraints, methyl methacrylate monomer price volatility, and antibiotic-loaded cement substitution protocols for early signals requiring forecast reassessment. Material shifts in EU MDR enforcement intensity or United States ambulatory reimbursement policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Unilateral Biportal Endoscopy Market
Medical Devices
Muscle Stimulator Market
Medical Devices
Temperature Sensing Foley Catheter Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
Contraceptive Rings Market
Medical Devices
Public Access Automated External Defibrillators (Aeds) Market
Medical Devices
India Spinal Fusion Devices Market
Medical Devices
Membrane Oxygenators Market
Medical Devices
Rectal Catheters Market
Medical Devices
Global Craniomaxillofacial Fixation Devices Market
Medical Devices
IV Fluid Transfer Drugs Devices Market
Medical Devices
Oxygen Concentrators Market
Medical Devices
Japan Drug Delivery Devices Market
Medical Devices
Global Automatic Stair Climbing Wheelchair Market
Medical Devices
Genitourinary Prosthetics Market