
 Automotive Solar Sunroof Market | 2026-2036
Automotive Solar Sunroof Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Solar Sunroof Market Analysis
The EU Green Deal is recalibrating European OEM procurement priorities toward embedded renewable energy systems. Webasto leverages its deep integration with German premium automakers to sustain factory-installed solar roof programs across multiple vehicle platforms. Aisin Corporation anchors Asian supply chains through its specialized glass encapsulation capabilities and Toyota group relationships. Magna International competes on manufacturing scale with vertically integrated module assembly lines serving North American and European customers simultaneously.
An automotive solar sunroof integrates photovoltaic cells—typically monocrystalline silicon or thin-film CIGS deposited on tempered glass—into a vehicle roof aperture to generate auxiliary electrical power for cabin preconditioning or battery trickle-charging. Factory-installed systems dominate current revenue flows due to OEM warranty integration and aerodynamic optimization during vehicle design, while retrofitted systems occupy a smaller but expanding niche among aftermarket specialists serving existing EV fleets. High power output configurations (300W-600W) lead unit economics as they deliver measurable range extension benefits that justify premium pricing, whereas low power segments remain concentrated in hybrid auxiliary applications with thinner margin profiles.
The EPA's vehicle efficiency standards and California Air Resources Board zero-emission mandates shape North American product specifications and testing protocols, while REACH compliance governs material substitutions in European photovoltaic encapsulants. China's MIIT new energy vehicle catalog inclusion criteria create market access conditions for imported solar roof systems. Stakeholders must monitor evolving certification requirements across multiple jurisdictions and assess whether backward integration into cell manufacturing or partnership with established photovoltaic suppliers offers superior capital efficiency for scaling production.
Market Dynamics
The EU Green Deal's vehicle emission targets are compressing OEM design cycles and forcing integration of auxiliary renewable energy systems into premium vehicle architectures before 2030 model year lock-ins.
Growth Catalysts
- EU Green Deal mandates:Binding vehicle emission reduction targets are compelling German and French automakers to factory-install solar roof systems as standard equipment on luxury EV platforms.
- Monocrystalline silicon efficiency gains:Cell conversion improvements above 22% are extending auxiliary charging capacity to support cabin preconditioning without main battery draw.
- South Korea's K-EV initiative:Government subsidies for zero-emission vehicle components are accelerating domestic OEM adoption of integrated photovoltaic roof assemblies.
Market Restraints
- Tempered glass supply concentration:Specialty automotive-grade glass fabrication capacity clusters in Germany and Japan, creating input bottlenecks during demand surges.
- REACH compliance costs:European photovoltaic encapsulant material substitutions require expensive requalification testing, compressing margin on lower-power configurations.
- Thin-film CIGS durability limitations:Moisture ingress susceptibility in humid climates restricts deployment geography and warranty terms.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic manufacturing incentives are opening factory-installed solar roof localization for export-oriented OEMs serving ASEAN markets.
- Commercial fleet auxiliary power:Refrigerated transport and last-mile delivery vehicles represent untapped demand for 300W-600W roof systems to power auxiliary equipment.
- California Air Resources Board zero-emission mandates:ZEV credit generation potential is incentivizing US premium EV manufacturers to specify high-output solar configurations.
Industry Challenges
- Photovoltaic-electronics integration expertise:Shortage of engineers capable of optimizing power electronics for automotive thermal cycling and vibration environments extends development timelines.
- Multi-jurisdiction certification sequencing:Simultaneous EPA efficiency validation, ECE R43 safety compliance, and MIIT catalog inclusion creates parallel testing cost burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Solar Sunroof Market |
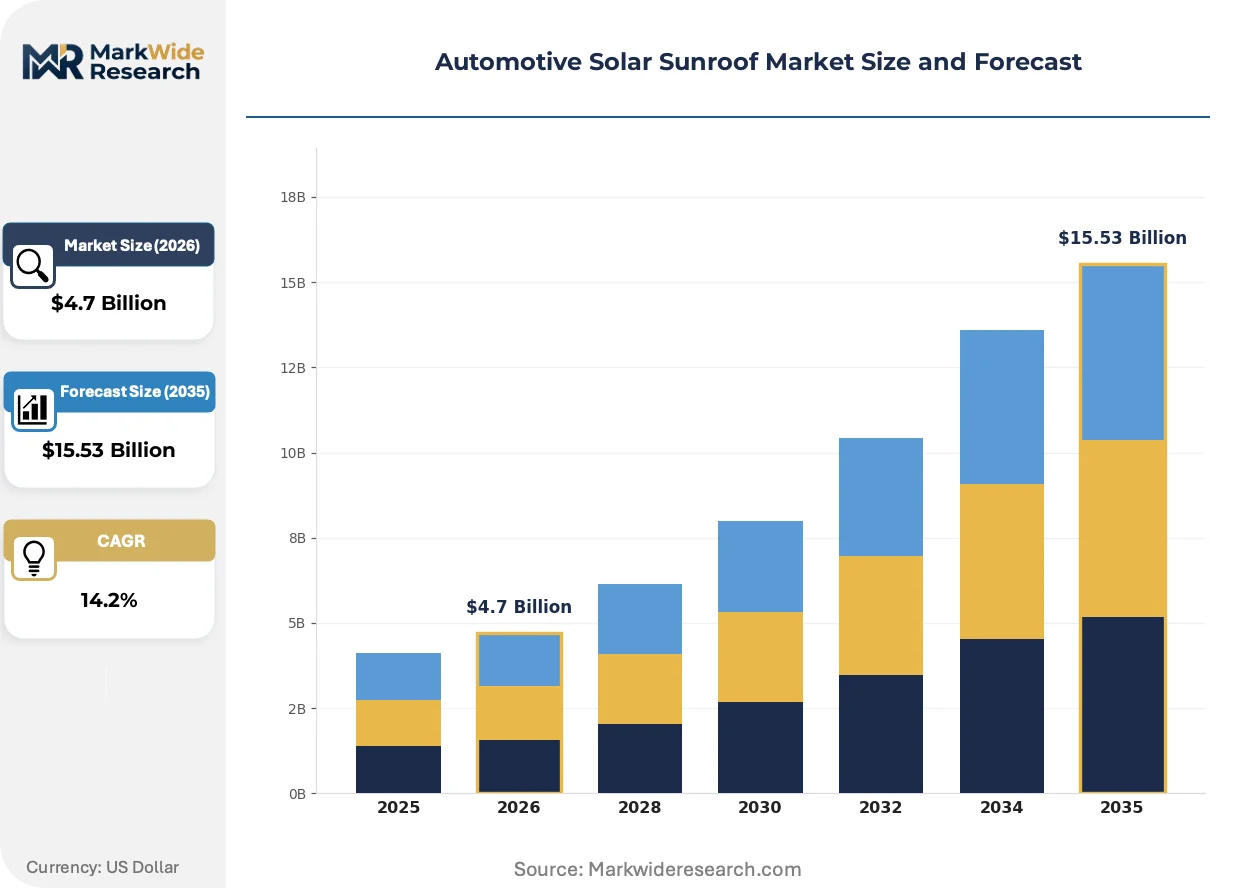
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Solar Panels, Rigid Solar Panels, Hybrid Solar Systems, Standard Sunroofs End User: OEMs, Aftermarket Providers, Luxury Vehicle Manufacturers, Environmental Organizations Installation Type: Factory-Installed, Retrofitted Systems, Custom Installations, Integrated Solutions Power Output: Low Power (up to 100W), Medium Power (100W-300W), High Power (300W-600W), Ultra High Power (600W+) |
| Companies Covered | Yachiyo Industry, Aisin Corporation, Webasto, Magna International, CIE Automotive, Inalfa Roof Systems, Mobitech, Motiontec, AGC Automotive Europe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Solar Sunroof Market Emerging Trajectories
Photovoltaic cell technology, regulatory pressure on vehicle efficiency, and shifting OEM procurement models are restructuring competitive advantage around integrated system design rather than component supply.
Perovskite-silicon tandem cells are absorbing incremental research investment from automotive glass suppliers seeking higher conversion efficiency without aperture area expansion. German premium OEMs are piloting these configurations on 2028 model year prototypes. The technology is absorbing development resources that previously flowed to incremental crystalline silicon improvements, compressing the viable window for thin-film alternatives in high-output segments.
REACH Annex XVII restrictions on hazardous substances in photovoltaic encapsulants are forcing material reformulations across European supply chains. ECHA substance evaluation timelines are extending qualification periods for new chemistries by 12-18 months. Factory-installed system manufacturers serving EU markets are responding by dual-sourcing encapsulant formulations and accelerating in-house materials testing capabilities.
Fleet procurement departments are consolidating supplier relationships around vertically integrated solar roof system providers capable of delivering warranty-aligned lifecycle service. Direct OEM-fleet agreements are displacing traditional tiered distribution networks for commercial vehicle configurations. This concentration is most visible in Germany's corporate fleet sector, where sustainability reporting requirements under CSRD are mandating documented renewable energy contribution from vehicle assets.
Automotive Solar Sunroof Market Segmentation
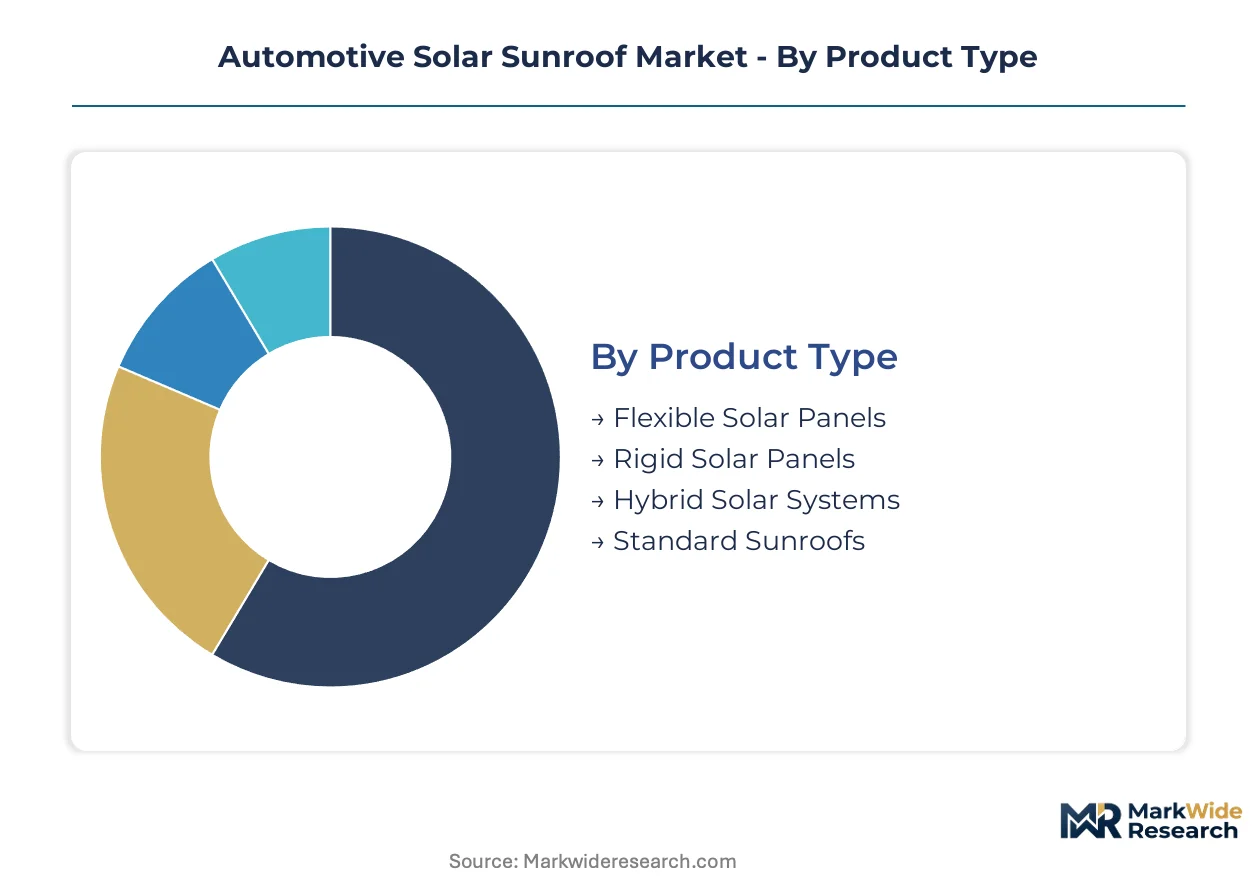
Photovoltaic integration architectures diverge sharply across vehicle platforms, with power output thresholds and installation timing determining warranty alignment, thermal management complexity, and OEM procurement patterns. Segment boundaries reflect competing pressures between aerodynamic optimization at the design stage versus retrofit accessibility for existing fleets.
Product Type:
Buyers differentiate primarily by curvature tolerance, weight penalty tolerance, and integration depth with existing roof structures.
- Flexible Solar Panels:Polymer-substrate photovoltaic films conform to curved roof geometries without structural reinforcement. Demand concentrates among retrofit specialists serving European commercial van fleets where roof curvature varies by chassis manufacturer and aerodynamic modification is prohibited by lease terms.
- Rigid Solar Panels:Tempered glass-encapsulated crystalline silicon cells deliver maximum power density per aperture area. German premium OEMs specify these configurations for factory-installed programs on luxury sedans, prioritizing conversion efficiency over weight savings to maximize ZEV credit generation under EU Green Deal frameworks.
- Hybrid Solar Systems:Dual-layer architectures combining rigid cell arrays with flexible edge segments.
- Standard Sunroofs:Non-photovoltaic glass panels retaining structural compatibility with solar-ready mounting systems.
Volume sits with Rigid Solar Panels; growth tilts toward Flexible Solar Panels.
End User:
Procurement authority varies by warranty liability exposure and design-cycle integration depth.
- OEMs:Vehicle manufacturers with full design control specify solar roofs during platform development, locking aerodynamic profiles and electrical architectures years before production. Toyota group relationships with Aisin Corporation demonstrate how captive supplier networks secure capacity allocation during supply constraints.
- Luxury Vehicle Manufacturers:Premium brands command price premiums for factory-installed solar configurations that support cabin preconditioning without main battery depletion. South Korean OEMs leverage K-EV initiative subsidies to absorb incremental system costs on flagship EV platforms.
- Aftermarket Providers:Independent installers serving existing vehicle owners.
- Environmental Organizations:Non-commercial buyers prioritizing demonstration fleets and research applications.
Procurement volume clusters with OEMs; margin expansion favors Luxury Vehicle Manufacturers.
Installation Type:
Timing relative to vehicle lifecycle determines electrical system compatibility and regulatory certification pathways.
- Factory-Installed:Systems integrated during vehicle assembly carry full OEM warranty coverage and undergo aerodynamic optimization during wind tunnel validation. Webasto's deep integration with German automakers sustains multi-platform programs where roof stampings accommodate photovoltaic wiring harnesses from the design phase.
- Integrated Solutions:Module-and-controller packages engineered for specific vehicle platforms but installed at regional assembly points. Magna International operates vertically integrated assembly lines serving North American and European customers simultaneously, optimizing logistics against tariff exposure.
- Retrofitted Systems:Post-manufacture installations on existing vehicles.
- Custom Installations:Bespoke configurations for specialized commercial applications.
Factory-Installed systems dominate revenue capture; Integrated Solutions are climbing the fastest as OEMs regionalize assembly.
Power Output:
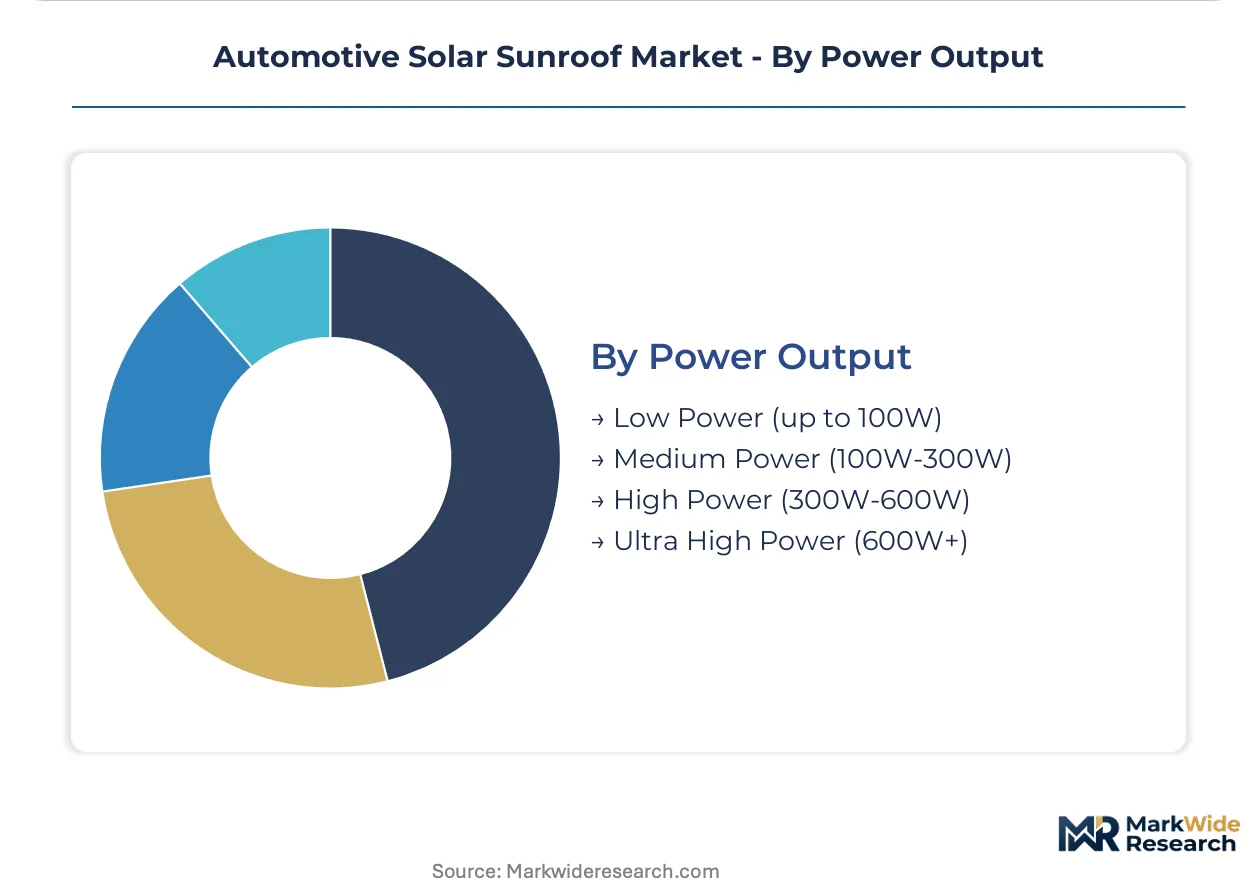
Output thresholds segment applications by electrical load requirements and economic justification for premium pricing.
- High Power (300W-600W):Configurations delivering measurable EV range extension through auxiliary battery charging justify substantial price premiums. California Air Resources Board ZEV credit generation incentivizes US premium manufacturers to specify these outputs, with EPA efficiency validation protocols governing certification timelines.
- Medium Power (100W-300W):Systems supporting cabin preconditioning and auxiliary electronics without main battery draw. Japanese OEMs concentrate procurement here for hybrid platforms where electrical architecture constraints limit rooftop power handling.
- Low Power (up to 100W):Trickle-charging applications with thinner margin profiles.
- Ultra High Power (600W+):Emerging configurations for commercial fleet auxiliary equipment.
High Power (300W-600W) commands the steepest expansion trajectory; Low Power (up to 100W) retains volume concentration in hybrid auxiliary segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors factory-installed solar roof engineering through Webasto's deep integration with German premium automakers. The city's wind tunnel facilities and photovoltaic wiring harness expertise concentrate OEM design-cycle activity for luxury EV platforms.
Germany
The EU Green Deal's binding emission targets compel BMW and Mercedes-Benz to factory-install solar configurations as standard equipment. KBA certification protocols govern aerodynamic validation and electrical safety compliance. Stuttgart and Munich host concentrated engineering centers where roof stampings accommodate photovoltaic integration from the design phase.
Japan
Toyota group relationships with Aisin Corporation secure capacity allocation for hybrid auxiliary applications. METI energy efficiency standards shape power electronics specifications for cabin preconditioning systems. Nagoya and Toyota City concentrate glass encapsulation expertise and specialized manufacturing for medium-power configurations.
South Korea
The K-EV initiative subsidizes zero-emission vehicle components, accelerating Hyundai and Kia adoption of integrated photovoltaic roof assemblies. MFDS automotive component certification aligns with MIIT requirements for export-oriented production. Seoul and Ulsan host vertically integrated module assembly serving domestic OEMs and ASEAN markets.
United States
EPA vehicle efficiency standards and California Air Resources Board zero-emission mandates shape product specifications for premium EV manufacturers. ZEV credit generation incentivizes high-output solar configurations. Detroit and Los Angeles concentrate validation testing and regional assembly operations for North American customers.
China
MIIT new energy vehicle catalog inclusion criteria create market access conditions for imported solar roof systems. Domestic OEMs accelerate localization partnerships to meet dual carbon goals. Shanghai and Beijing concentrate certification sequencing and joint venture engineering for photovoltaic-electronics integration.
Automotive Solar Sunroof Market Vendor Landscape
Premium-margin players sit above commodity-margin players across factory-installed versus retrofitted system categories. Factory-installed specialists command warranty-aligned pricing through OEM design-cycle integration, while aftermarket providers compete on installation speed and fleet retrofit accessibility. Three archetypes dominate: captive automotive suppliers with OEM parent relationships, independent glass-encapsulation specialists, and vertically integrated module assemblers. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure tempered glass supply and photovoltaic cell sourcing.
Within the captive supplier tier, Aisin Corporation and Yachiyo Industry exemplify automotive-group-affiliated positioning. Webasto and Magna International occupy positions as independent specialists with multi-OEM reach. CIE Automotive represents European-based diversification across automotive component segments. These anchors demonstrate how geographic clustering around German, Japanese, and North American OEM engineering centers shapes competitive access to design-cycle integration opportunities.
| Leading Market Players |
|---|
| Yachiyo Industry |
| Aisin Corporation |
| Webasto |
| Magna International |
| CIE Automotive |
| Inalfa Roof Systems |
| Mobitech |
| Motiontec |
| AGC Automotive Europe |
| Others |
Supply Flow & Price Mechanics
Perovskite-silicon tandem cell development is absorbing R&D budgets that previously targeted incremental crystalline silicon gains, simultaneously elevating factory-installed system costs and concentrating procurement power among glass-encapsulation specialists with automotive validation capabilities. This technology transition compresses margin windows for thin-film alternatives while rewarding suppliers with in-house materials testing and dual-qualification pathways for REACH-compliant encapsulants.
Pricing Analysis
Range-extension value anchors pricing for high-output configurations, with California Air Resources Board ZEV credit generation justifying substantial premiums over auxiliary-only systems. Three-tier pricing structure across premium, standard, and economy levels separates factory-installed OEM programs from integrated solutions and aftermarket retrofits, with certification grade and volume scale as primary differentiation drivers. Cost compression in low-power hybrid auxiliary segments is intensifying because REACH requalification expenses concentrate in thinner-margin configurations. Fleet procurement departments exhibit lowest price sensitivity due to CSRD-mandated sustainability reporting requirements, while independent retrofit specialists face acute margin pressure.
Supply Chain Analysis
Dual-sourcing mandates from German and Japanese OEMs require qualified suppliers for tempered glass substrates and photovoltaic cell wafers simultaneously, extending qualification timelines but reducing single-source vulnerability. Manufacturing concentration clusters in Germany, Japan, and South Korea for specialty automotive-grade glass fabrication, with South Korea expanding capacity under K-EV initiative subsidies. Input dependencies rest on monocrystalline silicon wafer supply, CIGS thin-film deposition materials, and REACH-compliant encapsulant chemistries. Tariff exposure on Chinese-sourced photovoltaic components creates supply chain risk as OEMs regionalize assembly. Distribution runs through vertically integrated module assemblers serving OEM platform engineering centers directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive solar sunroof technology sits in a crystalline-to-tandem cell transition phase, with perovskite-silicon configurations displacing legacy monocrystalline architectures in premium OEM programs.
For Market Incumbents: Cement factory-installed program relationships through captive supply of glass-encapsulation capacity and accelerated in-house REACH testing capabilities. Prioritize backward integration into photovoltaic cell sourcing to secure allocation during wafer supply constraints, while defending against thin-film CIGS moisture-ingress limitations that restrict warranty terms in humid markets. For New Entrants and Emerging Players: Enter via refrigerated transport and last-mile delivery fleet auxiliary power applications, where 300W-600W configurations for equipment power generation remain underpenetrated relative to passenger EV cabin preconditioning. Target India's PLI scheme for auto component manufacturing localization, leveraging domestic incentives to serve ASEAN export markets with integrated module assembly. For Investors and Strategic Acquirers: Exit pathways concentrate in captive automotive supplier acquisitions by OEM parent groups seeking design-cycle integration control. Five-to-ten year viability hinges on perovskite-silicon tandem cell commercialization timelines and REACH encapsulant requalification completion rates. Watch ECHA substance evaluation acceleration as the inflection signal for margin recovery in European-facing supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite-Silicon Tandem Cell Commercialization | German OEM pilot programs on 2028 prototypes validate conversion efficiency gains without aperture expansion. |
| REACH-Compliant Encapsulant Dual-Qualification | ECHA evaluation timeline compression reduces 12-18 month qualification windows for European market access. |
| India PLI Scheme Manufacturing Localization | Domestic capacity buildout serves export-oriented OEMs targeting ASEAN fleet auxiliary power demand. |
| Commercial Fleet Direct Procurement Agreements | CSRD sustainability reporting mandates consolidate supplier relationships around lifecycle warranty service. |
| Photovoltaic-Electronics Integration Talent Acquisition | Power electronics optimization for automotive thermal cycling addresses engineering shortage extending development timelines. |
Methodological Framework
Independent corroboration across OEM platform engineering directors, Tier 1 supplier procurement leads, glass-encapsulation R&D heads, and aftermarket fleet retrofit specialists underwrites the qualitative findings. Primary interviews with KBA certification officials and ECHA regulatory affairs consultants combined with secondary validation from vehicle production databases, IHS Markit registration data, MIIT new energy vehicle catalog filings, and EPA efficiency standard dockets. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across power output tiers and installation types.
Comparable historical periods anchored the forecast window to pre-pandemic OEM design-cycle timelines and post-EU Green Deal announcement procurement shifts. The analytical framework models vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions throughout the forecast period. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs include ZEV credit valuation trajectories under California Air Resources Board frameworks and K-EV initiative subsidy renewal assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under perovskite-silicon tandem cell durability failures or ECHA encapsulant restriction acceleration. Forecasts reflect documented assumptions regarding OEM platform electrification timelines and tempered glass capacity expansion completion. Deviation in EU Green Deal vehicle emission target stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive in-Cabin Air Quality Improvement Solutions Market
Automotive Interior & Exterior
Automotive Glove Compartment Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Automotive Heat Shield Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Automotive Fridge Market
Automotive Interior & Exterior
India Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Trunk Lid Panel Market
Automotive Interior & Exterior
Heated Steering Wheel Market
Automotive Interior & Exterior
Weatherstrip Market
Automotive Interior & Exterior
Automotive Grill Guard Market
Automotive Interior & Exterior
Auto Ventilated Seats Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Automotive Grab Handle Market
Automotive Interior & Exterior
Door Panel Market
Automotive Interior & Exterior
Automotive Steering Wheel Covers Market