
 Extended Warranty Agreement Market | 2026-2036
Extended Warranty Agreement Market Size, Share, and Industry Trends Forecast 2026-2036
Extended Warranty Agreement Market Insights
Aftermarket service revenue is fragmenting across warranty administrators, repair networks, and data analytics platforms as margin pools migrate from pure underwriting to embedded service ecosystems. Assurant leverages its automotive dealer relationships to control distribution channels for vehicle service contracts. Allstate anchors its position through backward integration into claims administration technology. Asurion specializes in consumer electronics protection, sustaining premium pricing through same-day device replacement capabilities.
An extended warranty agreement constitutes a contractual service promise that extends manufacturer defect coverage beyond standard terms, typically specifying labor rates, parts categories, and claims adjudication protocols. These instruments transfer residual product risk from consumers or retailers to specialized underwriters, with pricing calibrated against actuarial failure curves and repair cost indices. Mechanical breakdown coverage commands the largest premium pool across product categories, while accidental damage protection for consumer electronics captures the fastest expansion as smartphone and laptop repair costs escalate. Online platforms represent the most rapidly growing sales channel, compressing traditional retail partner commissions and enabling direct-to-consumer subscription models.
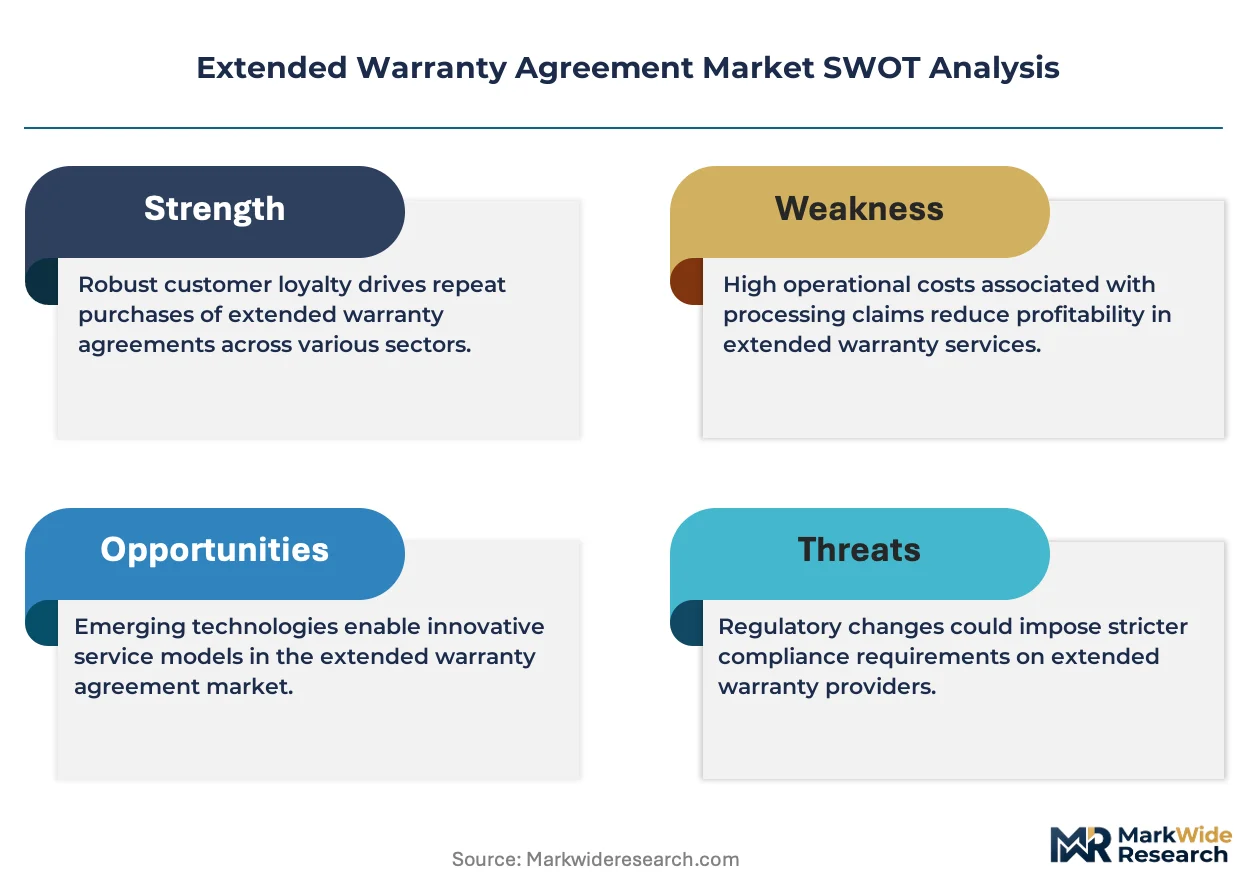
The Federal Trade Commission enforces warranty disclosure requirements under the Magnuson-Moss Act, shaping how providers structure contract transparency and cancellation terms. State insurance regulators in New York and California impose capital reserve requirements on vehicle service contract writers, creating barriers to unlicensed market entry. The Consumer Financial Protection Bureau monitors add-on warranty financing practices, particularly in automotive retail. Stakeholders must monitor regulatory divergence between state-level insurance classifications and federal consumer protection mandates to anticipate compliance cost trajectories and distribution model viability.
Market Dynamics
Automotive fleet electrification is accelerating component complexity, forcing underwriters to recalibrate actuarial models around battery degradation curves and power electronics failure modes rather than traditional mechanical wear patterns.
Growth Catalysts
- EU Digital Services Act:Mandatory transparency requirements for warranty terms are standardizing contract disclosure, reducing consumer friction in cross-border purchases and expanding addressable market for digital-first warranty platforms.
- Consumer electronics repair cost escalation:Smartphone and laptop component density increases are pushing accidental damage protection attach rates higher in retail channels.
- United States automotive retail concentration:Dealer group consolidation is creating captive distribution networks for vehicle service contracts at point-of-sale.
Market Restraints
- Semiconductor supply volatility:Extended lead times for automotive microcontrollers are compressing repair network throughput and inflating claims severity for electronics-heavy vehicles.
- State-level capital reserve fragmentation:New York and California impose divergent solvency requirements on vehicle service contract writers, raising compliance overhead for multi-state operators.
- Third-party administrator concentration:Claims processing capabilities cluster with a handful of technology platforms, creating single-point-of-failure risk in adjudication infrastructure.
Strategic Opportunities
- India automotive aftermarket:Passenger vehicle parc expansion and OEM warranty expiration waves are creating whitespace for independent extended warranty penetration in tier-2 and tier-3 cities.
- Embedded insurance APIs:Point-of-sale integration with e-commerce checkout flows enables subscription-based warranty models outside traditional retail partnerships.
- Connected vehicle telematics:Real-time diagnostic data streams allow usage-based pricing differentiation and predictive intervention before component failure.
Industry Challenges
- Actuarial talent scarcity:Product-specific failure data science expertise sits concentrated with legacy automotive underwriters, constraining new market entrants.
- Legacy claims system integration:Repair network management platforms require costly API development to interface with incumbent dealer management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extended Warranty Agreement Market |
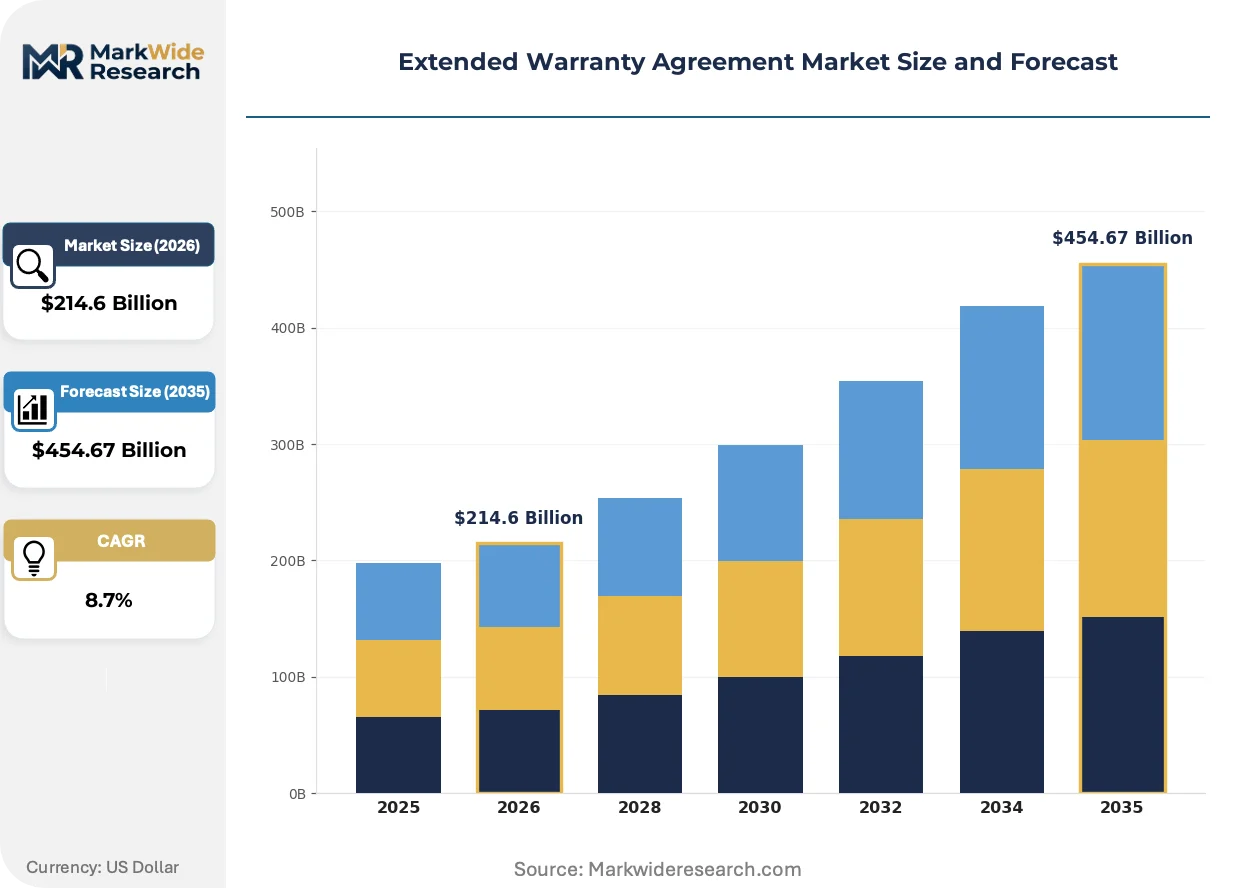
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $454.67 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Mechanical Breakdown, Accidental Damage, Wear and Tear, Replacement Costs Product Type: Consumer Electronics, Home Appliances, Furniture, Automotive Duration: 1 Year, 2 Years, 3 Years, 5 Years Sales Channel: Direct Sales, Retail Partners, Online Platforms, Third-Party Providers |
| Companies Covered | Assurant, Allstate, Asurion, American International Group, Allianz Partners, SquareTrade, AmTrust Financial, CarShield, Endurance Warranty Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extended Warranty Agreement Market Trends and Innovations
Artificial intelligence is penetrating warranty operations through predictive analytics and automated claims adjudication, compressing cost structures while raising data governance requirements.
Machine learning models trained on vehicle telematics streams are rendering obsolete traditional mileage-based pricing for automotive service contracts. Fleet operators with connected vehicle deployments are adopting these models fastest, shifting from fixed-term contracts to dynamic premium adjustments based on actual driving behavior and component stress indicators.
The EU's Digital Services Act mandates machine-readable warranty terms and standardized cancellation procedures for online sales. This regulatory framework is forcing contract restructuring across European electronics retail, with marketplace operators now required to surface warranty conditions at checkout rather than burying terms in post-purchase documentation.
Direct-to-consumer subscription models are displacing retail-embedded warranty sales in consumer electronics. Amazon and dedicated insurtech platforms capture this shift most visibly in the United States, where younger buyers prefer post-purchase activation via mobile apps over point-of-sale attachment.
Extended Warranty Agreement Market Segmentation
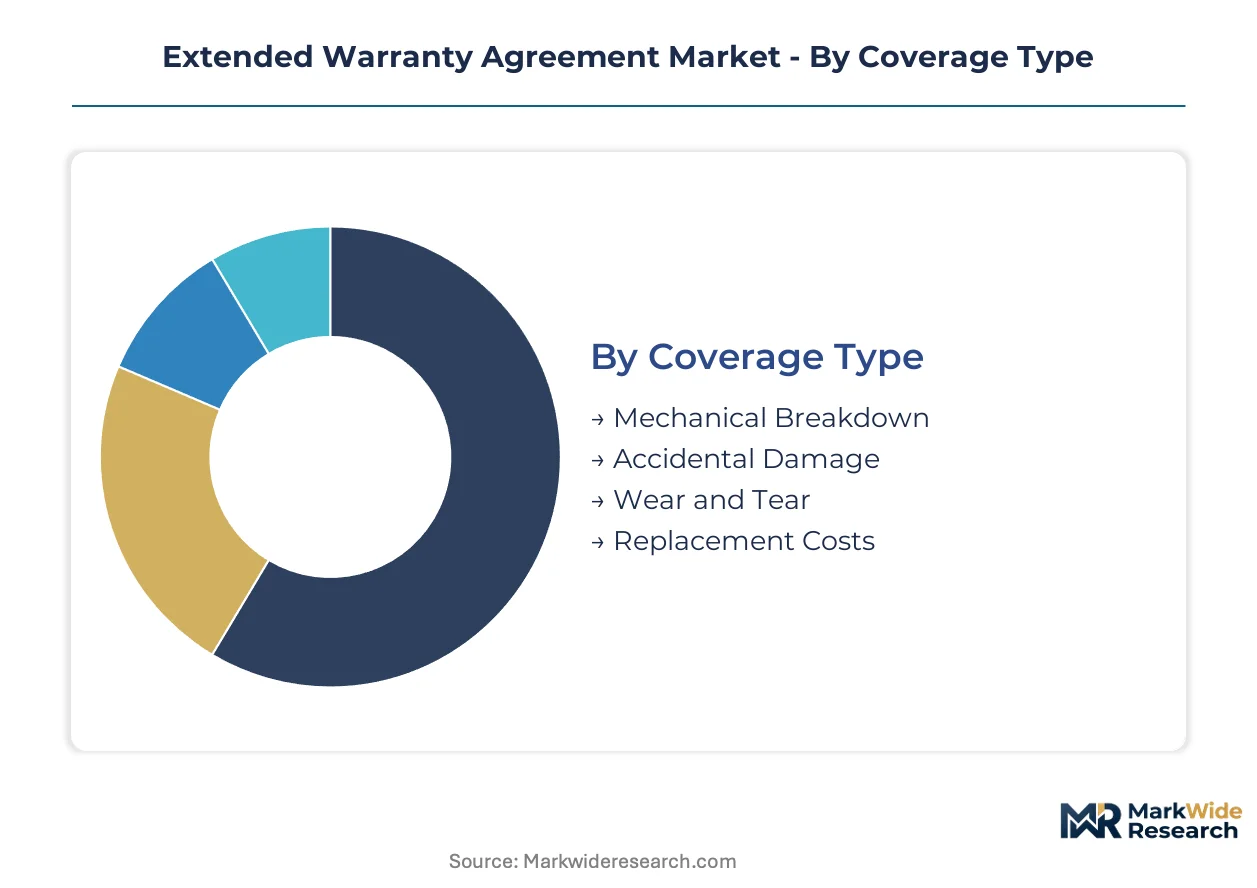
Warranty providers calibrate pricing and risk models against distinct segment profiles. Coverage type determines actuarial complexity, while sales channel dynamics govern margin capture and customer acquisition economics.
Coverage Type:
Mature mechanical coverage dominates premium pools, while emerging protection categories reshape risk transfer structures.
- Mechanical Breakdown:Traditional coverage for component failure due to manufacturing defects or material fatigue. Automotive powertrain and home appliance compressor failures concentrate demand in the United States, where dealer networks embed these contracts at point-of-sale.
- Accidental Damage:Protection against drops, spills, and physical trauma rather than internal component failure. Smartphone and laptop repair cost escalation in consumer electronics retail drives attach rate expansion, particularly for high-density OLED displays and sealed-battery designs.
- Wear and Tear:Coverage extending to degradation from normal use beyond manufacturer defect terms. Furniture and appliance segments leverage this for upholstery, mechanisms, and moving parts.
- Replacement Costs:Full product replacement rather than repair, common in low-value electronics and small appliances where labor economics favor swap-out over refurbishment.
Mechanical Breakdown handles the majority of throughput; Accidental Damage is the fastest mover on share.
Product Type:
Cost tier stratification separates high-premium automotive contracts from mass-market electronics attachments.
- Automotive:Vehicle service contracts covering powertrain, electrical, and increasingly battery-electric components. Fleet electrification in the United States forces recalibration of actuarial models around battery degradation curves.
- Consumer Electronics:Protection for smartphones, laptops, tablets, and wearables. Same-day replacement capabilities sustain premium pricing in this segment.
- Home Appliances:Coverage for refrigerators, washing machines, HVAC systems, and kitchen equipment. Extended terms align with product replacement cycles.
- Furniture:Structural, mechanical, and fabric protection for residential and commercial furnishings. Lower premium per unit but higher volume attachment in big-box retail.
Automotive commands the highest premium per contract; Consumer Electronics shows the steepest expansion trajectory.
Duration:
Customer type and product lifecycle stage dictate term selection patterns across retail and direct channels.
- 1 Year:Short-term coverage for seasonal electronics and promotional retail attachments. Low absolute premium but high conversion rates at checkout.
- 2 Years:Standard term matching typical manufacturer warranty gaps in mid-tier electronics. Balances affordability with meaningful protection extension.
- 3 Years:Preferred term for major appliances and automotive service contracts. Aligns with expected ownership duration before trade-in or upgrade.
- 5 Years:Long-term coverage for high-value automotive and luxury goods. Requires capital reserve discipline from underwriters.
3 Year terms handle the majority of throughput; 5 Year contracts are climbing the fastest on share.
Sales Channel:
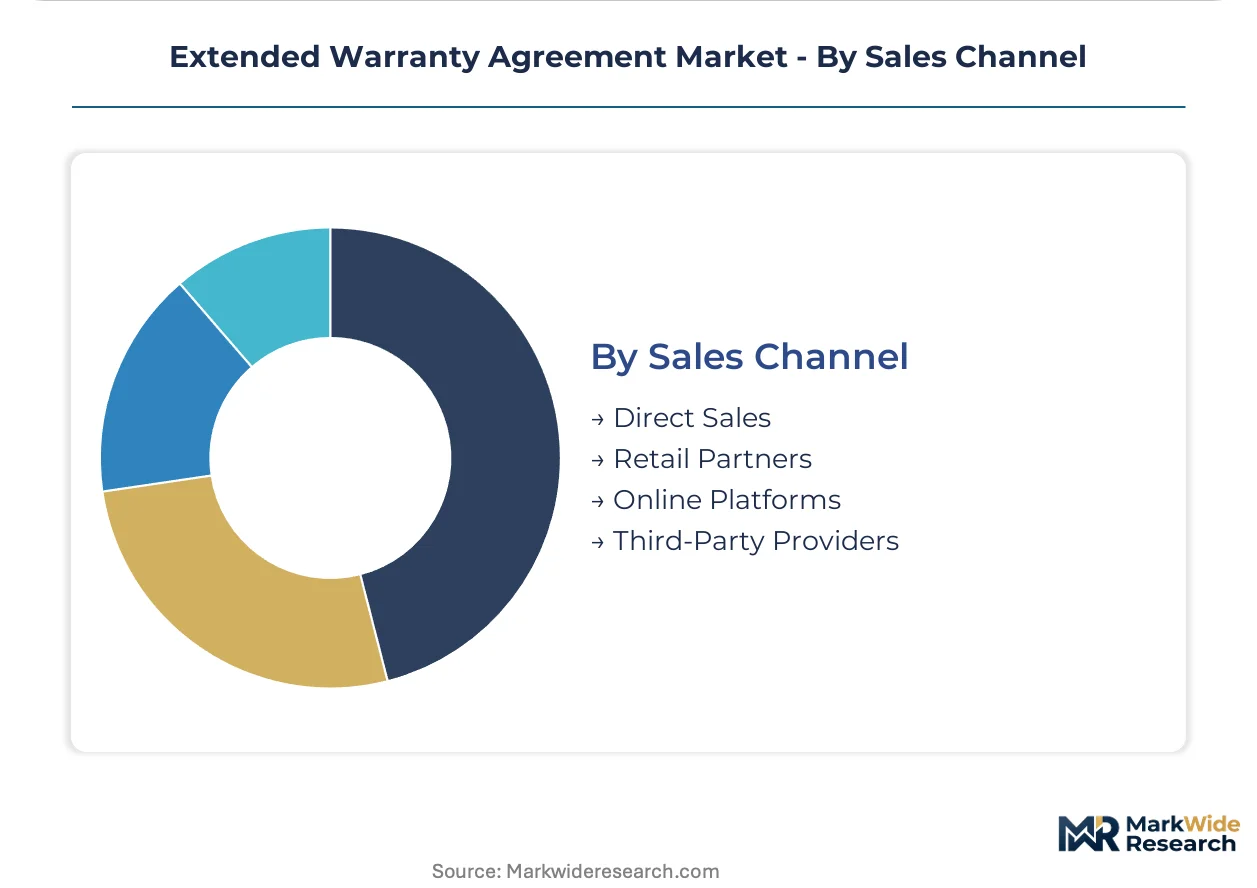
Volume concentration in retail partnerships contrasts with margin migration toward embedded digital platforms.
- Retail Partners:Point-of-sale attachment through automotive dealers, electronics retailers, and appliance stores. Commission structures compress underwriter margins but deliver scale.
- Online Platforms:Direct-to-consumer and marketplace-integrated warranty sales. Mobile app activation and subscription models gain traction with younger demographics in the United States.
- Third-Party Providers:Independent administrators and insurtech platforms selling outside manufacturer and retail ecosystems. Specialize in competitive pricing for informed comparison shoppers.
- Direct Sales:Manufacturer-backed extended warranty programs sold through owned channels. OEMs leverage brand trust to capture attachment revenue directly.
Retail Partners handle the majority of throughput; Online Platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia demonstrate the highest price elasticity, squeezing underwriter margins in emerging markets. United States consumers absorb premium pricing with minimal attach-rate sensitivity. European purchasers occupy the middle ground, demanding transparency but accepting moderate cost premiums for standardized contract terms.
United States
Fleet electrification and dealer group consolidation drive vehicle service contract penetration. The FTC enforces Magnuson-Moss Act disclosure requirements, mandating clear contract transparency. Detroit's automotive corridor anchors underwriting concentration, with actuarial talent clustering around legacy motor city infrastructure.
Germany
Automotive OEM warranty expiration waves and industrial machinery protection demand expand premium pools. The KBA oversees vehicle service contract solvency alongside federal consumer protection frameworks. Stuttgart's manufacturing belt hosts underwriter operations calibrated to precision-engineering failure curves.
China
Passenger vehicle parc growth and smartphone replacement cycles accelerate electronics protection adoption. SAMR implements standardized warranty disclosure under consumer protection directives. Shanghai's Yangtze River Delta concentration draws warranty administrators serving domestic EV manufacturers.
India
Two-wheeler and entry-level automotive segments drive volume expansion despite compressed premiums per contract. BIS certification requirements shape aftermarket service quality standards. Pune and Chennai automotive clusters attract third-party administrators targeting tier-2 city penetration.
United Kingdom
Used vehicle warranty penetration and home appliance protection sustain mid-market growth. FCA regulations govern insurance-warranty boundary classifications for consumer contracts. London's financial services concentration supports warranty-linked financing products and captive underwriter operations.
Extended Warranty Agreement Market Competitive Landscape
Capability concentration sits with legacy automotive underwriters possessing decades of actuarial data; scale advantage sits with diversified insurance conglomerates with captive distribution networks. The market structures around three tiers: integrated insurers with backward claims technology control, specialized warranty administrators with repair network relationships, and insurtech platforms with direct-to-consumer subscription models. Dominant competitive moves include strategic partnerships with automotive dealer groups and embedded API integrations with e-commerce checkout flows.
Within the integrated insurer tier, Assurant and Allstate exemplify divergent capability accumulation strategies. Assurant occupies a position anchored in automotive dealer channel relationships. Allstate represents the backward technology integration archetype through claims administration platform control. Asurion sits within the specialized administrator tier, exemplifying premium positioning through consumer electronics replacement logistics.
| Leading Market Players |
|---|
| Assurant |
| Allstate |
| Asurion |
| American International Group |
| Allianz Partners |
| SquareTrade |
| AmTrust Financial |
| CarShield |
| Endurance Warranty Services |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-to-Los Angeles maritime corridor's freight cost volatility feeds directly into extended warranty pricing power, as underwriters serving electronics protection programs absorb logistics-driven repair part inflation while calibrating premium tiers against dealer network concentration in the United States and direct-to-consumer platform expansion in Europe.
Pricing Analysis
Extended warranty contracts drive lifetime value for automotive dealer groups and electronics retailers. Three-tier pricing structure across premium, standard, and economy levels segments buyers by coverage depth and claims adjudication speed. Cost compression in the economy tier is intensifying because insurtech platforms bypass traditional retail commissions. Fleet operators show the least price sensitivity; individual consumer electronics buyers in India and Southeast Asia demonstrate the highest.
Supply Chain Analysis
Actuarial data feeds from Germany, the United States, and China anchor underwriting model development. Semiconductor components, lithium-ion battery cells, and replacement display panels constitute critical input dependencies. Single-source vulnerability concentrates in third-party claims administration platforms serving multiple underwriters. Distribution runs through captive automotive dealer networks and embedded e-commerce APIs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated automotive dealer groups and platform-embedded e-commerce operators, fragmenting traditional warranty distribution economics and forcing underwriters to renegotiate commission structures or build direct channels.
For Market Incumbents: Harden actuarial data moats by acquiring telematics analytics capabilities before connected vehicle platforms disintermediate failure prediction. Deepen backward integration into claims administration technology to reduce third-party platform dependency. Prioritize API development for dealer management system integration.
For New Entrants and Emerging Players: Build out embedded insurance API partnerships with e-commerce marketplaces in India and Southeast Asia where warranty penetration remains underdeveloped. Target tier-2 and tier-3 Indian cities experiencing passenger vehicle parc expansion. Launch subscription-based mobile activation models bypassing retail point-of-sale friction.
For Investors and Strategic Acquirers: Specialized warranty administrators with repair network relationships and proprietary claims adjudication platforms represent the most defensible acquisition archetype. Long-term viability hinges on data network effects in failure prediction rather than underwriting balance sheet scale. Monitor connected vehicle telematics adoption curves as the inflection signal for usage-based pricing model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Data Partnership | Enables usage-based pricing differentiation for fleet electrification contracts. |
| Embedded API Integration | Captures subscription revenue via e-commerce checkout flow embedding. |
| Claims Platform Acquisition | Secures adjudication infrastructure control against third-party concentration risk. |
| India Market Expansion | Addresses whitespace in tier-2 automotive aftermarket warranty penetration. |
| Battery Degradation Modeling | Recalibrates actuarial frameworks for electric vehicle powertrain coverage. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of warranty administrator regulatory filings, automotive dealer group financial disclosures, and consumer protection agency enforcement actions. Underwriting executives, claims operations directors, automotive dealership F&I managers, and insurtech platform engineers provided structured input. Secondary sources include FTC Magnuson-Moss enforcement records, state insurance regulator solvency reports, and EU Digital Services Act implementation guidance. Bottom-up policy volume estimates triangulate against top-down premium pool calculations.
Forecast inputs span coverage type evolution, sales channel migration, and product electrification trends across the analysis window. Segmentation dimensions include coverage category, product type, contract duration, and distribution channel. CAGRs derive from actuarial loss ratio trajectories and attach rate elasticity modeling. Battery degradation curve data and connected vehicle penetration assumptions inform automotive segment projections.
Stress conditions across semiconductor supply volatility, state regulatory divergence, and telematics adoption speed were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding repair cost inflation and dealer network consolidation. Cross-checking against vehicle registration databases and warranty attachment rate surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Japan Property and Casualty Insurance Market
Insurance
Cybersecurity Insurance Market
Insurance
Europe Bancassurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
UK Cyber (Liability) Insurance Market
Insurance
Cyber Insurance Market
Insurance
Telecommunication Insurance Market
Insurance
Asia-Pacific Surety Market
Insurance
Commercial Insurance Market
Insurance
Entertainment Insurance Market
Insurance
Employee Benefit Broker Market
Insurance
Global AI in Auto-Insurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
Engineering Insurance Market
Insurance
Event Insurance Market
Insurance
Embedded Insurance Market