
 Embedded Insurance Market | 2026-2036
Embedded Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Insurance Market Insights
E-commerce platform integration is broadening as the dominant distribution vector for embedded insurance products. AXA SA leverages its multinational licensing infrastructure to embed coverage across European digital retail networks. Cover Genius specializes in API-first architecture that enables real-time policy issuance at checkout points. Bolttech sustains a multi-continent partnership model linking insurers with non-insurance distribution platforms.
Embedded insurance denotes the integration of risk-transfer products directly into the purchase flow of primary goods or services, typically via application programming interfaces that trigger policy generation upon transaction confirmation. The mechanism relies on parametric data triggers—vehicle VINs, flight itineraries, or property addresses—to automate underwriting decisions without separate customer enrollment. Motor insurance occupies the largest current premium pool due to mandatory coverage requirements in most jurisdictions, while health insurance represents the fastest-expanding segment as telehealth platforms and wearable data streams enable dynamic risk pricing. Distribution through mobile applications captures disproportionate growth velocity among gig economy workers who transact primarily through smartphone interfaces.
The National Association of Insurance Commissioners in the United States maintains producer licensing requirements that complicate embedded distribution models, while the EU's Digital Operational Resilience Act imposes cybersecurity standards on insurance API infrastructures. China's National Financial Regulatory Administration oversees embedded product disclosures under consumer protection mandates. Stakeholders must monitor evolving sandbox approvals and partnership capitalization rules as regulators balance innovation facilitation with policyholder safeguard obligations.
Market Dynamics
API standardization across open banking frameworks is compressing integration timelines between insurers and digital distribution platforms, fundamentally altering how risk products attach to non-insurance transactions.
Growth Catalysts
- Real-time data infrastructure:Parametric triggers using vehicle identification numbers, flight itineraries, and property addresses automate underwriting without separate enrollment workflows. Motor coverage leverages this for instant policy generation at point of sale.
- EU Digital Operational Resilience Act:This framework mandates cybersecurity standards for insurance API infrastructures, creating compliant architecture that accelerates insurer-platform partnerships across European digital retail networks.
- Gig economy transaction volumes:Smartphone-dependent workers in delivery, ride-hailing, and freelance services generate embedded demand through mobile-first purchasing behaviors.
Market Restraints
- Producer licensing fragmentation:The National Association of Insurance Commissioners maintains state-by-state licensing requirements that complicate embedded distribution models requiring multi-jurisdictional compliance.
- Legacy system integration costs:Insurers face substantial capital expenditure to retrofit decades-old policy administration systems for real-time API connectivity with external platforms.
- Data privacy jurisdictional conflicts:China's National Financial Regulatory Administration disclosure mandates clash with GDPR data minimization principles, forcing product architecture divergence across markets.
Strategic Opportunities
- Telehealth platform convergence:Wearable data streams enable dynamic health risk pricing, creating embedded products that adjust premiums based on real-time biometric inputs from fitness trackers and medical devices.
- India's digital public infrastructure:The country's unified payments interface and account aggregator framework provide standardized rails for insurance embedding without proprietary platform development.
- Commercial property parametric coverage:Climate risk sensors and IoT monitoring systems enable automatic claims triggers based on flood depth, wind speed, or seismic readings, reducing loss adjustment expenses.
Industry Challenges
- Actuarial talent scarcity:The intersection of traditional underwriting expertise with API architecture and real-time data engineering creates recruitment bottlenecks for product development teams.
- Partnership capitalization requirements:Regulators in multiple jurisdictions impose balance sheet minimums on embedded distribution arrangements, constraining smaller insurtech platform economics.
- Disclosure standardization delays:Absence of uniform consumer transparency protocols across markets forces redundant compliance engineering for multi-territory product rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Insurance Market |
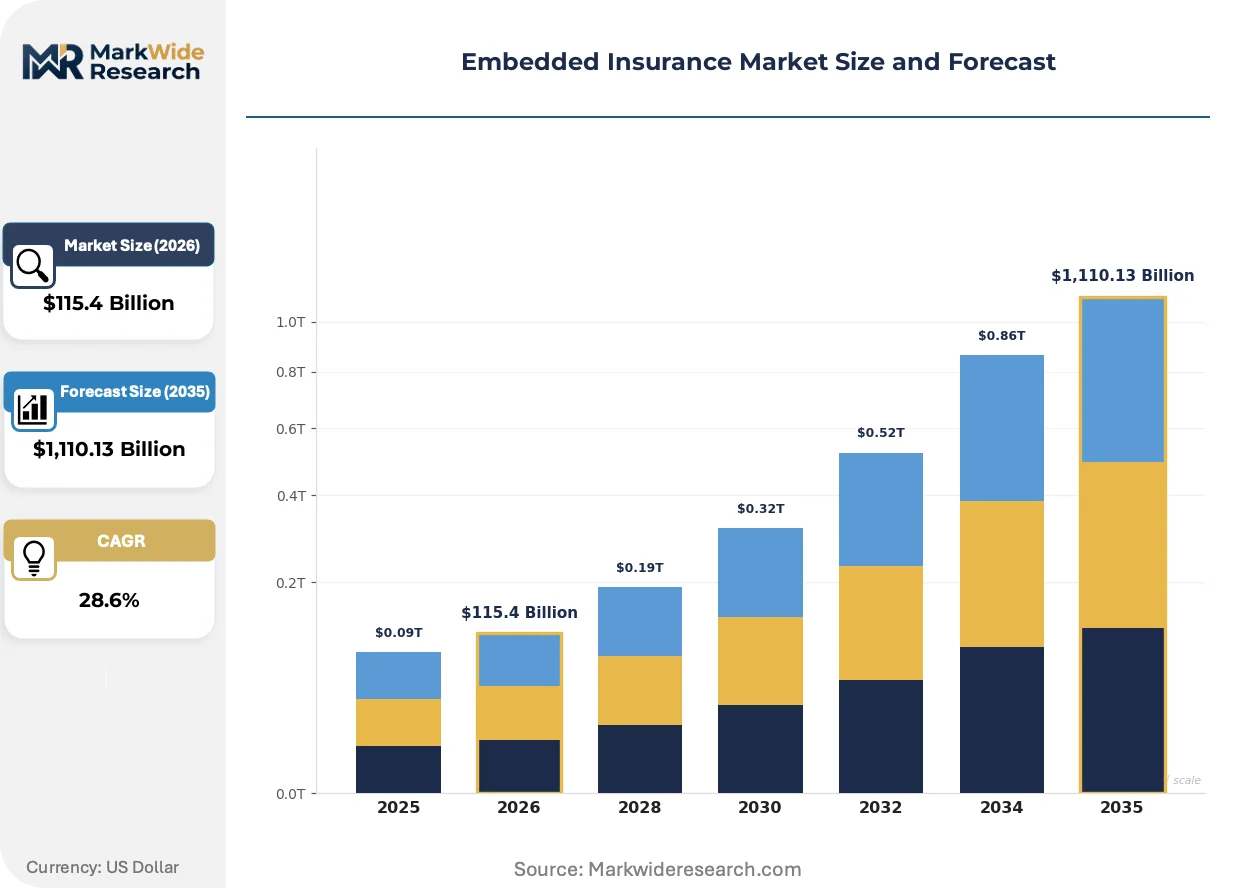
| Market Size in 2026 | $115.4 Billion |
| Market Size in 2035 | $1,110.13 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motor Insurance, Travel Insurance, Health Insurance, Property Insurance, Liability Insurance Distribution Channel: E-commerce Platforms, Financial Services, Automobile Dealerships, Travel Agencies, Mobile Applications Application: Online Retail, Vehicle Purchase, Trip Booking, Healthcare Services, Real Estate Transactions Customer Type: Individual Consumers, Small Enterprises, Gig Economy Workers, Freelancers, Startups |
| Companies Covered | Qover, AXA SA, Bolttech, Zurich Insurance Group, Chubb Limited, Cover Genius, Allianz SE, Igloo, Lemonade Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Insurance Market Trends and Innovations
Embedded insurance architecture is migrating from simple checkout integrations toward contextual risk assessment engines that anticipate coverage needs before transaction completion.
Parametric underwriting engines are overtaking traditional indemnity structures in high-frequency, low-severity product categories. These systems calculate payouts using objective data triggers rather than loss verification processes. E-commerce platforms and travel booking sites are adopting this architecture for shipping protection and trip cancellation coverage. The compression of claims settlement from weeks to minutes is overtaking customer retention metrics as the primary competitive differentiator in digital insurance distribution.
The EU's Digital Operational Resilience Act imposes mandatory cybersecurity standards on insurance API infrastructures that handle policyholder data. Insurers must implement encryption protocols, incident reporting mechanisms, and third-party risk management frameworks to maintain distribution partnerships. European digital retail networks are responding by consolidating vendor relationships toward DORA-compliant technology providers, raising barriers for non-compliant platform entrants.
Subscription-based coverage models are displacing single-transaction policy attachments in recurring purchase categories. Software-as-a-service procurement teams now expect embedded cyber liability and errors-and-omissions coverage bundled into license agreements rather than sourced separately. This pattern is most visible in North American and United Kingdom B2B software markets, where procurement departments prioritize vendor consolidation over insurance shopping.
Embedded Insurance Market Segmentation
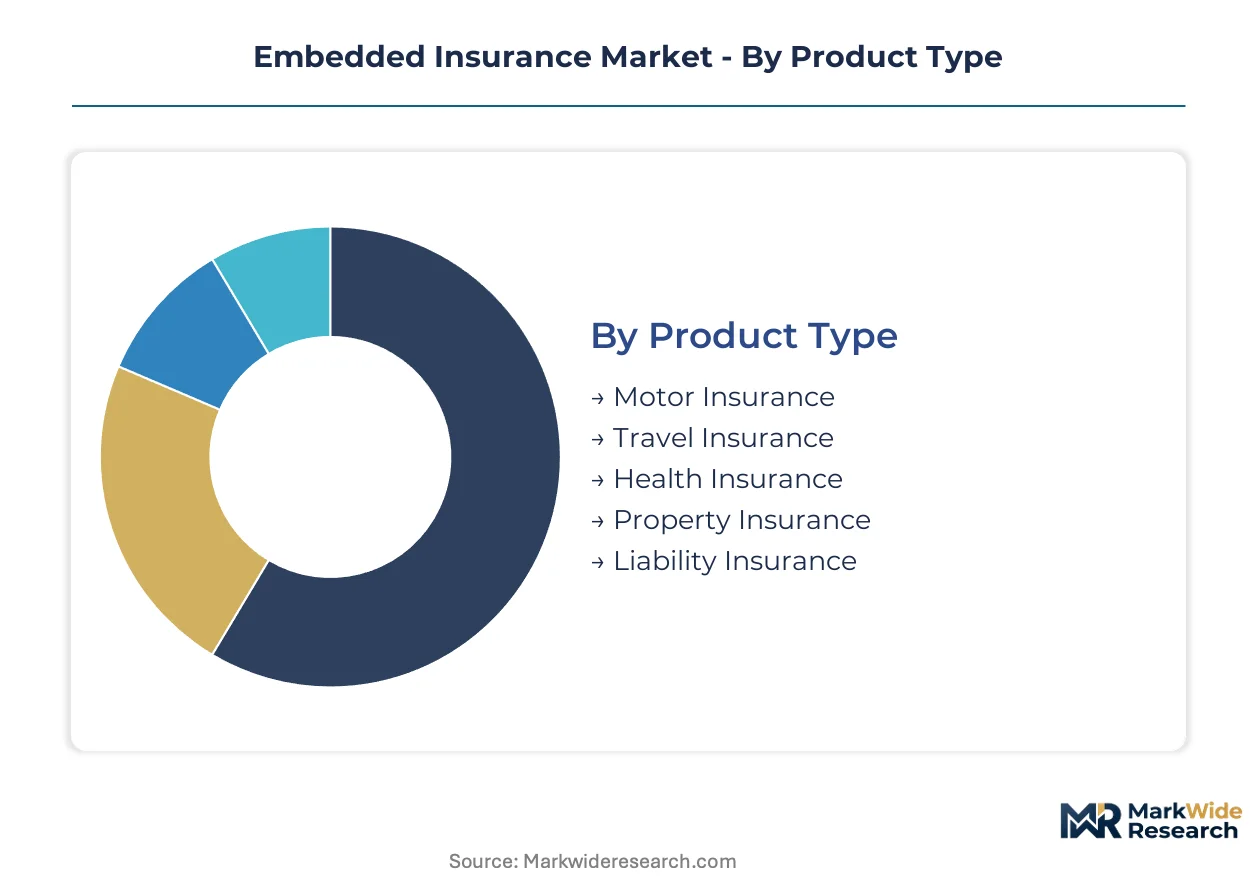
Embedded insurance products attach to diverse transaction types, each demanding distinct underwriting logic and API integration depth. Segmentation reveals how risk-transfer mechanisms align with specific purchase workflows and customer risk profiles.
Product Type:
Upgrade cycles in embedded insurance track regulatory mandates and digital platform capabilities rather than physical depreciation.
- Motor Insurance:Mandatory coverage requirements in most jurisdictions create automatic policy triggers at vehicle point-of-sale. United States dealerships and European digital retail networks concentrate demand through VIN-based instant underwriting.
- Health Insurance:Telehealth platforms and wearable data streams enable dynamic risk pricing with real-time biometric inputs. China's digital health ecosystem and United Kingdom NHS-integrated apps are climbing fastest as regulatory sandboxes permit algorithmic premium adjustment.
- Travel Insurance:Flight itinerary APIs trigger cancellation and medical evacuation coverage at booking confirmation.
- Property Insurance:Address verification systems automate homeowner and renter policy generation during lease execution.
- Liability Insurance:Commercial coverage embeds into B2B software procurement workflows for cyber and professional risk.
Motor Insurance sits at the top of the volume ranking, with Health Insurance climbing the fastest.
Distribution Channel:
Cost tier differentiation separates high-integration API partnerships from lightweight affiliate arrangements.
- E-commerce Platforms:Checkout-integrated shipping protection and device warranty products leverage cart data for parametric pricing. United States Amazon Marketplace and Alibaba's Tmall anchor transaction volume through embedded seller coverage.
- Mobile Applications:Gig economy workers transact primarily through smartphone interfaces, creating disproportionate growth velocity for delivery and ride-hailing coverage. India's Unified Payments Interface infrastructure accelerates adoption without proprietary platform development.
- Financial Services:Banking apps embed credit life and payment protection alongside loan origination.
- Automobile Dealerships:Physical retail maintains dominance in jurisdictions with complex inspection requirements.
- Travel Agencies:Online booking engines consolidate trip cancellation and medical coverage at reservation.
E-commerce Platforms capture the largest transaction flow, while Mobile Applications gain share fastest among smartphone-dependent workforce segments.
Application:
Customer type concentration varies sharply across transaction contexts, from impulse retail to deliberative major purchases.
- Vehicle Purchase:Financing arrangements bundle GAP and extended warranty coverage through lender API connections. China's automotive finance regulators mandate disclosure standards that shape product architecture.
- Online Retail:Shipping protection and device coverage attach to high-frequency, low-consideration transactions. United Kingdom consumer credit regulations influence refund-substitution product design.
- Trip Booking:Cross-border medical and cancellation products respond to itinerary complexity.
- Healthcare Services:Telehealth subscriptions integrate supplemental coverage for prescription and specialist access.
- Real Estate Transactions:Title and mortgage insurance embed through property closing workflows.
Vehicle Purchase generates the highest average premium per transaction, with Online Retail expanding most quickly through checkout friction reduction.
Customer Type:
Margin profiles diverge between standardized individual products and customized enterprise arrangements.
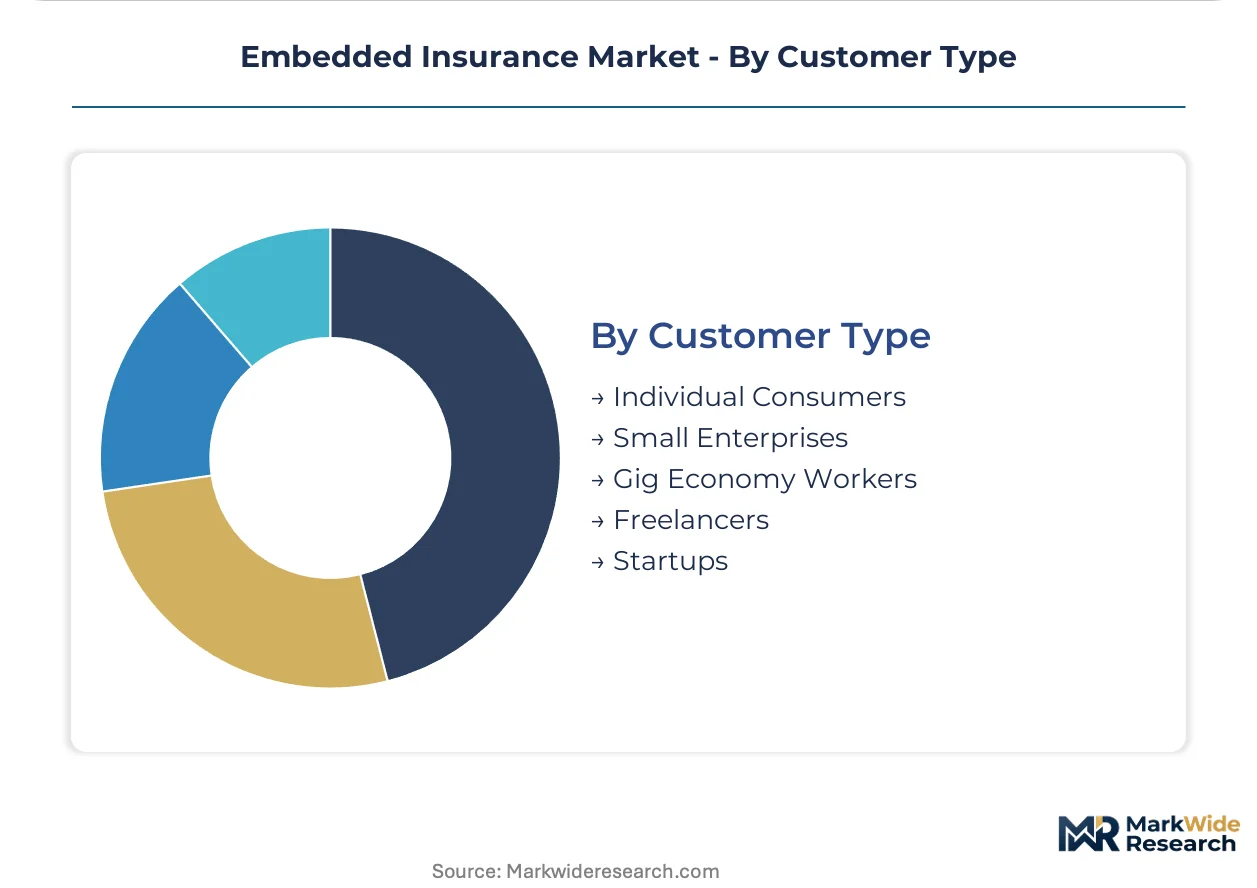
- Gig Economy Workers:Smartphone-first income patterns demand on-demand, per-transaction coverage for delivery and freelance platforms. India's account aggregator framework enables portable insurance records across gig employers.
- Small Enterprises:Cyber liability and errors-and-omissions coverage bundles into SaaS procurement agreements. United States B2B software markets show vendor consolidation prioritizing embedded over separately sourced protection.
- Individual Consumers:Mass-market products dominate volume through retail and travel channels.
- Freelancers:Professional indemnity attaches to creative platform memberships and project marketplaces.
- Startups:Venture-backed companies access director and officer coverage through cap table management platforms.
Individual Consumers represent the largest addressable base, with Gig Economy Workers showing the steepest expansion trajectory as platform employment scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's Square Mile anchors the embedded insurance ecosystem through its concentration of Lloyd's syndicates and fintech API infrastructure. United States regulatory complexity and China's digital payment scale generate divergent growth trajectories across major markets.
United States
E-commerce platform integrations drive embedded motor and device coverage through dealer networks and checkout flows. The National Association of Insurance Commissioners maintains state-by-state producer licensing requirements that fragment distribution compliance. Silicon Valley insurtech clusters and New York financial services corridors concentrate API development talent and carrier partnerships.
China
Digital health ecosystems and automotive finance platforms generate parametric policy triggers at massive transaction scale. The National Financial Regulatory Administration mandates embedded product disclosures under consumer protection frameworks. Shenzhen and Hangzhou technology hubs host platform partnerships linking insurers with e-commerce and ride-hailing applications.
United Kingdom
Open banking infrastructure and telehealth platform convergence accelerate health insurance embedding through NHS-integrated applications. The Financial Conduct Authority oversees sandbox approvals for algorithmic premium adjustment products. London's insurtech corridor and Manchester digital clusters sustain API-first carrier-platform partnerships.
Germany
Automotive manufacturing supply chains embed warranty and GAP coverage through lender API connections at point of sale. The Federal Financial Supervisory Authority implements EU Digital Operational Resilience Act cybersecurity standards on insurance infrastructures. Munich and Frankfurt insurance clusters develop compliant architecture for European digital retail network integration.
India
Gig economy platform employment and unified payments interface infrastructure enable portable insurance records across delivery and freelance applications. The Insurance Regulatory and Development Authority of India oversees sandbox frameworks for embedded product experimentation. Bangalore and Mumbai technology corridors host account aggregator partnerships linking insurers with digital transaction ecosystems.
Embedded Insurance Market Competitive Landscape
Strategic partnerships dominate the current landscape as carriers and technology platforms consolidate API integration capabilities. The market structure concentrates around multinational insurers with established licensing infrastructure, specialized insurtech API architects, and technology-agnostic distribution intermediaries. Three archetypes define competitive positioning: carrier-led embedding programs, platform-native insurance architects, and partnership orchestrators linking multiple underwriters with non-insurance distribution channels. M&A activity and technology licensing agreements represent the primary competitive vectors as players seek rapid geographic and capability expansion.
Within the multinational carrier tier, AXA SA and Allianz SE occupy positions exemplifying established licensing infrastructure across European digital retail networks. Among API-first specialists, Cover Genius represents the architecture-centric archetype enabling real-time policy issuance. Bolttech anchors the partnership orchestration model through its multi-continent platform linking insurers with non-insurance distribution channels.
| Leading Market Players |
|---|
| Qover |
| AXA SA |
| Bolttech |
| Zurich Insurance Group |
| Chubb Limited |
| Cover Genius |
| Allianz SE |
| Igloo |
| Lemonade Inc. |
| Others |
Pricing and Supply Chain Analysis
Horizontal API integration partnerships anchor supply positioning and pricing power for embedded insurance distributors, with carriers that control proprietary platform connections commanding premium placement fees while outsourced technology stacks face margin compression from licensing costs.
Pricing Analysis
Input-cost pass-through from cloud infrastructure and cybersecurity compliance investments shapes embedded insurance economics, with carriers bearing EU Digital Operational Resilience Act certification expenses passing these through as platform access fees. Price differentiation rests on API response latency and real-time underwriting capability, with sub-100-millisecond policy issuance commanding tier-one rates. Pricing pressure stems from gig economy platform volume consolidation, which squeezes per-transaction margins. Individual consumers show highest price sensitivity, while small enterprises purchasing bundled SaaS coverage demonstrate lowest sensitivity due to procurement efficiency priorities.
Supply Chain Analysis
Logistics and freight cost exposure remains minimal in embedded insurance, where digital API delivery eliminates physical distribution entirely. Technology development concentrates in the United States, United Kingdom, and Germany, with cloud infrastructure sourcing from Amazon Web Services, Microsoft Azure, and Google Cloud Platform. Supply chain risk centers on single-source vulnerability for core banking API providers, where concentrated platform dependence creates systemic failure exposure. Distribution runs through direct carrier-platform partnerships, bypassing traditional intermediary layers entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded insurance functions as a geographic-arbitrage play, with EU regulatory compliance costs running substantially higher than India's sandbox framework, creating divergent capital efficiency profiles for identical product architectures.
For Market Incumbents: To counter insurtech API-first specialists, legacy carriers should deepen captive control over core banking partnerships and accelerate certification investment under the EU Digital Operational Resilience Act. Channel control through exclusive e-commerce platform agreements represents the critical defensive lever against margin erosion. For New Entrants and Emerging Players: Launch via India's account aggregator infrastructure, where unified payments interface rails enable zero-proprietary-platform market entry. Telehealth platform convergence offers the most penetrable white-space target, with algorithmic premium adjustment products still awaiting regulatory sandbox approval in multiple jurisdictions. For Investors and Strategic Acquirers: Roll-up economics work for regional API-first specialists because fragmented licensing requirements prevent single-carrier global coverage, creating acquisition currency for multi-territory platform assemblers. Long-term viability over the medium-term horizon favors targets with established insurer partnerships rather than technology-only plays. Watch sandbox approval velocity as the key inflection signal for algorithmic health product expansion.| Strategic Initiative | Industry Significance |
|---|---|
| API Architecture Standardization | Enables real-time policy issuance through checkout-integrated parametric triggers at e-commerce platforms. |
| Regulatory Sandbox Entry | Accelerates algorithmic premium products through India's IRDAI and UK FCA experimental frameworks. |
| Insurer Partnership Consolidation | Strengthens distribution economics by pooling balance sheet capacity for embedded arrangement capitalization. |
| Telehealth Platform Integration | Captures dynamic health risk pricing through wearable data streams and NHS-integrated application layers. |
| Cybersecurity Certification Investment | Secures EU Digital Operational Resilience Act compliance for continued European digital retail access. |
Research Methodology
Coverage spans the United States, United Kingdom, China, Germany, and India, with primary inputs from each market's regulatory and technology clusters. Primary interviews with insurance API architects, platform partnership directors, regulatory sandbox administrators, and carrier embedded product executives combined with secondary validation from National Association of Insurance Commissioners guidance documents, EU Digital Operational Resilience Act implementation texts, China National Financial Regulatory Administration disclosure mandates, and IRDAI sandbox approvals. Bottom-up transaction volume estimates triangulated against top-down carrier premium disclosures.
Rate-of-change decomposition across the analysis window separates baseline API adoption velocity from regulatory enablement effects and platform partnership expansion. Segmentation dimensions modeled include product type, distribution channel depth, application context, and customer employment archetype. CAGRs derived from logistic diffusion curves fitted to digital transaction growth patterns, with parametric underwriting penetration and open banking API standardization serving as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory restriction scenarios or platform partnership consolidation waves. Forecasts reflect assumptions about sandbox approval timelines and carrier-platform negotiation leverage that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Financial Guarantee Market
Insurance
Europe Liability Insurance Market
Insurance
Aerial Imaging in Insurance Service Market
Insurance
India Dental Insurance Market
Insurance
Business Travel Insurance Market
Insurance
Germany Reinsurance Market
Insurance
Global Flood Insurance Market
Insurance
Spain Parametric Insurance Market
Insurance
Single Trip Travel Insurance Market
Insurance
Parametric Insurance Market
Insurance
Canada Cyber (Liability) Insurance Market
Insurance
Medical Claims Processing Services Market
Insurance
Asia-Pacific Travel Insurance Market
Insurance
Djibouti Insurance Market
Insurance
US Extended Warranty Market
Insurance
Business Insurance Market